
 India Condominium and Apartments Market | 2026-2036
India Condominium and Apartments Market Size, Share, and Industry Trends Forecast 2026-2036
India Condominium and Apartments Market Foresight
A widening capital-intensity gap between balance-sheet-heavy developers and asset-light operators is rotating competitive advantage toward firms with captive land banks and construction capabilities. DLF Limited leverages its extensive land reserves across Delhi-NCR to sustain project pipelines at scale. Godrej Properties anchors its reputation through green-certified developments that command pricing premiums in Mumbai and Bengaluru. Sobha Limited differentiates via backward integration into manufacturing, controlling quality through in-house production of concrete and interiors.
India Condominium and Apartments denote multi-unit residential structures with individual ownership of units and shared common areas, typically constructed through reinforced concrete frame systems with specifications ranging from bare-shell deliveries to fully fitted interiors with HVAC and smart-home infrastructure, serving the primary purpose of urban densification and asset ownership for households. The 2 BHK and 3 BHK configurations dominate volume absorption among nuclear families, while the luxury price tier captures disproportionate margin pools in Mumbai and Delhi-NCR. Affordable and mid-range segments face compressed margins due to input cost volatility, though first-time buyers sustain liquidity velocity in under-construction inventory across Pune and Hyderabad.
The Ministry of Housing and Urban Affairs, BIS structural codes, and state-level RERA authorities collectively shape developer compliance burdens, with RERA-mandated escrow requirements tightening working capital cycles and BIS seismic standards elevating foundation costs for high-rise construction. The CEA's energy-efficiency directives for common-area lighting and pumping systems add recurring operational obligations for condominium associations. Stakeholders must monitor how state-level affordable-housing subsidy schemes and municipal floor-area-ratio relaxations alter project feasibility mathematics in emerging corridors.
Market Dynamics
RERA-mandated escrow requirements are compressing developer working capital cycles while simultaneously elevating buyer confidence in under-construction inventory across Maharashtra and Karnataka. This structural tension between liquidity constraints and demand activation is forcing balance-sheet-heavy developers to reconfigure project financing structures.
Growth Catalysts
- PLI scheme for construction materials:Domestic manufacturing incentives for cement and steel are stabilizing input cost volatility for developers with captive supply chains.
- Nuclear family formation:Young households in Mumbai-Pune and Bengaluru corridors are driving 2 BHK and 3 BHK absorption at velocity levels sustaining pre-launch funding.
- BIS structural codes:Mandatory seismic certification for high-rise construction is filtering out undercapitalized developers, concentrating market share among compliant operators.
Market Restraints
- Reinforcement steel price volatility:Input cost swings of 15-20% quarterly are compressing margins in affordable and mid-range segments where pricing power remains constrained.
- CEA energy-efficiency mandates:Common-area lighting and pumping system upgrades impose recurring operational obligations on condominium associations, elevating maintenance cost projections.
- Floor-area-ratio limitations:Municipal density caps in core Mumbai and Delhi-NCR restrict developable square footage on premium land parcels.
Strategic Opportunities
- Hyderabad and Pune peripheral corridors:Municipal infrastructure expansion and metro connectivity extensions are unlocking greenfield development zones with favorable land acquisition costs.
- Green building certification premiums:CEA-compliant energy-efficient designs command 8-12% pricing premiums in Mumbai and Bengaluru luxury segments.
- Smart-home infrastructure integration:IoT-enabled HVAC and security systems are emerging as differentiation vectors in premium configurations.
Industry Challenges
- Structural engineering talent scarcity:Qualified seismic design specialists are concentrated among a handful of consulting firms, extending project timelines.
- RERA compliance documentation:State-level registration requirements and quarterly escrow reporting impose administrative burdens that scale with project portfolio size.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Condominium and Apartments Market |
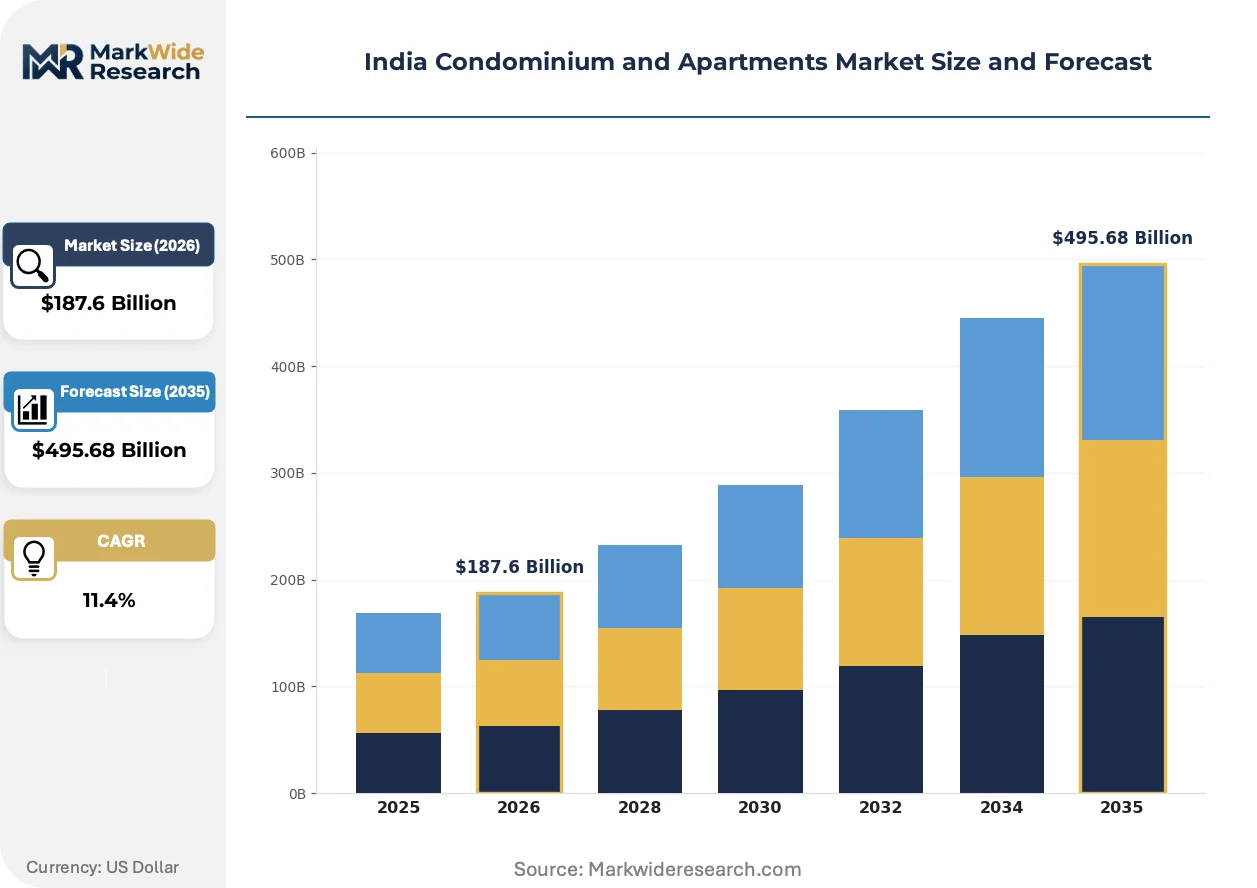
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $495.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Studio, 1 BHK, 2 BHK, 3 BHK Price Tier: Luxury, Mid-Range, Affordable, Budget Development Type: New Construction, Resale, Pre-Approved, Under Construction Customer Type: Investors, First-Time Buyers, Retirees, Families |
| Companies Covered | Godrej Properties, Tata Realty and Infrastructure, Prestige Group, Embassy Group, Brigade Group, Sobha Limited, DLF Limited, L&T Realty, Lodha Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Condominium and Apartments Market Shifts & Advancements
Construction methodology and buyer engagement models are undergoing parallel transformation. Developers are integrating manufacturing-grade precision into residential delivery while digital platforms compress discovery-to-purchase cycles.
Prefabricated concrete component systems are miniaturizing foundation-to-superstructure timelines for mid-rise developments. Tier-2 developers in Pune and Hyderabad are adopting modular wall and slab systems to offset skilled labor scarcity. This technology is compressing project delivery schedules from 36 to 24 months, enabling faster capital rotation.
BIS seismic standards for Zone IV and Zone V classifications are mandating deep pile foundations and shear wall configurations for structures exceeding fifteen stories. Foundation costs have elevated 18-25% for high-rise projects in Mumbai's coastal belt. Developers are responding by concentrating premium inventory in certified seismic zones to justify structural cost premiums.
Digital property discovery platforms are displacing traditional broker networks for first-time buyer segments. Virtual walkthroughs and drone-captured construction progress feeds now dominate pre-launch marketing in Bengaluru and Delhi-NCR. This channel shift is most visible among nuclear families aged 28-35, where 60% of initial shortlisting occurs through mobile-first interfaces before physical site visits.
India Condominium and Apartments Market Segmentation
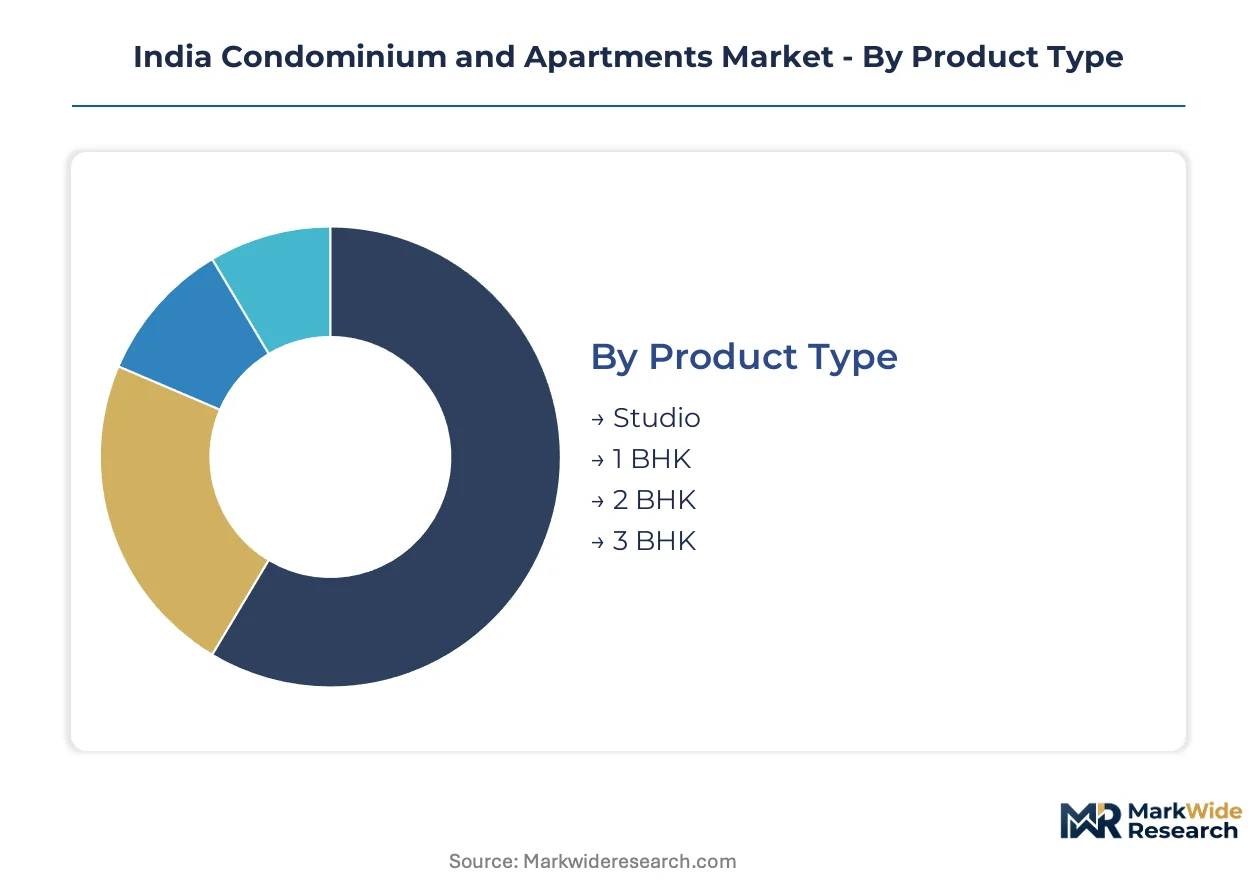
Segmentation in the India condominium and apartments market reveals how developer resources allocate across divergent margin structures. Configuration choices and price positioning determine capital intensity, absorption velocity, and compliance burden for projects across Maharashtra, Karnataka, and Telangana corridors.
Product Type:
Margin pools concentrate in configurations serving nuclear family formation, where square footage efficiency meets premium per-square-foot realization.
- 2 BHK:Two-bedroom units with integrated living-dining configurations and modular kitchen provisions dominate volume absorption. Mumbai-Pune and Bengaluru corridors absorb these units at velocity sustaining pre-launch funding for developers with RERA-compliant escrow structures.
- 3 BHK:Three-bedroom configurations with servant quarters and dual-bathroom specifications capture disproportionate margin pools in Delhi-NCR luxury clusters. BIS seismic compliance costs for high-rise delivery are offset through pricing power in certified developments.
- Studio:Compact single-room units with kitchenettes target investor segments and young professionals in Bengaluru's IT corridors.
- 1 BHK:One-bedroom configurations serve entry-level ownership in Hyderabad and Pune peripheral zones with favorable land acquisition costs.
2 BHK holds installed capacity. 3 BHK is rotating up the share rankings.
Price Tier:
Cost tier stratification determines working capital cycle length and buyer financing structure across developer portfolios.
- Luxury:Developments exceeding premium per-square-foot thresholds with imported fittings, smart-home infrastructure, and concierge services. Mumbai's coastal belt and Delhi-NCR concentrate absorption where CEA energy-efficiency certifications command 8-12% pricing premiums.
- Mid-Range:Specifications balancing branded fittings with standardized construction deliverables. Input cost volatility in reinforcement steel compresses margins where pricing power remains constrained.
- Affordable:Units qualifying for state-level subsidy schemes with standardized specifications and compressed amenity packages. First-time buyers sustain liquidity velocity in under-construction inventory across Pune and Hyderabad.
- Budget:Entry-tier configurations with bare-shell deliveries and minimal common-area obligations. Municipal floor-area-ratio limitations restrict developable square footage on premium land parcels in core Mumbai.
Luxury commands margin concentration. Affordable is expanding most quickly through subsidy scheme penetration.
Development Type:
Supply maturity determines buyer risk perception and financing availability across transaction structures.
- New Construction:Greenfield developments on fresh land parcels with full design flexibility. RERA-mandated escrow requirements compress developer working capital cycles while elevating buyer confidence.
- Under Construction:Projects between foundation completion and occupancy certificate stages. Digital property discovery platforms with drone-captured progress feeds dominate marketing for nuclear families aged 28-35.
- Resale:Secondary market transactions in completed inventory with immediate occupancy availability. Established condominium associations absorb CEA energy-efficiency upgrade obligations.
- Pre-Approved:Projects with sanctioned building plans awaiting construction commencement. Municipal infrastructure timelines determine absorption velocity in Hyderabad and Pune peripheral corridors.
New Construction dominates developer pipelines. Under Construction is gaining share fastest through RERA confidence effects.
Customer Type:
Buyer profile determines unit configuration preference, financing structure, and sensitivity to maintenance cost projections.
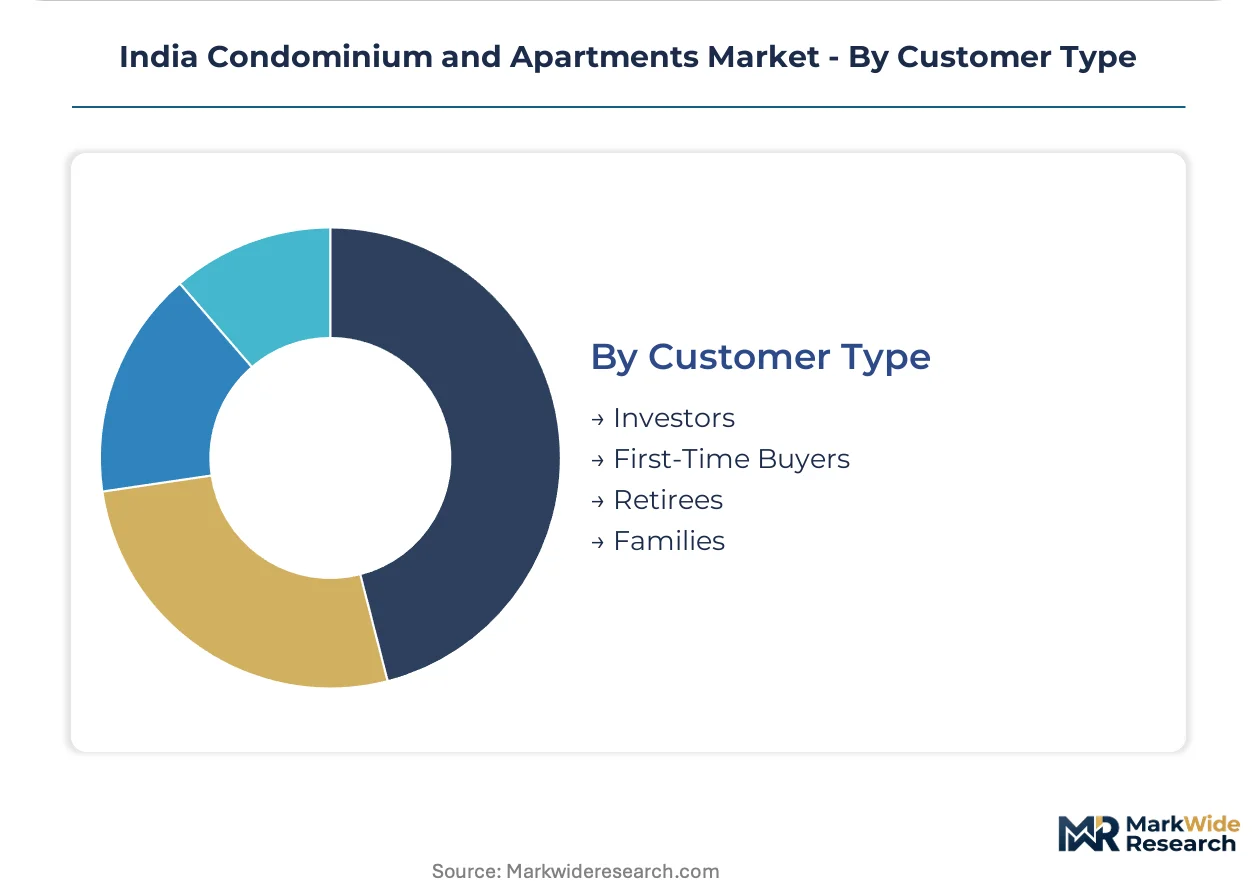
- Families:Nuclear households prioritizing 2 BHK and 3 BHK configurations with proximity to employment clusters and school infrastructure. Young households in Mumbai-Pune and Bengaluru corridors drive absorption velocity.
- Investors:Capital deployment seeking rental yield and appreciation in completed inventory. Resale and pre-approved segments concentrate this buyer type.
- First-Time Buyers:Entry-level ownership seeking affordable and budget tiers with subsidy scheme eligibility. State-level affordable-housing programs alter project feasibility mathematics.
- Retirees:Downsizing households prioritizing single-level living and reduced maintenance obligations. Limited specialized inventory concentration in current supply.
Families anchor volume absorption. First-Time Buyers is climbing the fastest through demographic transition effects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across Indian states. Maharashtra and Karnataka absorb premium inventory with nuclear-family-driven configurations, while southern and western corridors prioritize mid-range units with subsidy eligibility. Compliance thresholds and land availability shape divergent developer strategies.
Maharashtra
Mumbai-Pune corridor anchors luxury absorption with 2 BHK and 3 BHK configurations dominating pre-launch velocity. RERA-mandated escrow requirements compress working capital cycles for developers with balance-sheet depth. Municipal floor-area-ratio limitations in core Mumbai restrict developable square footage, pushing supply toward Thane and Pune peripheral zones.
Karnataka
Bengaluru cluster concentrates IT corridor demand with young professionals driving studio and 1 BHK absorption in Whitefield and Electronic City. BIS seismic standards for Zone II classification elevate foundation costs for high-rise construction. Godrej Properties and Embassy Group anchor green-certified developments commanding pricing premiums in Koramangala and Indiranagar.
Telangana
Hyderabad peripheral corridors unlock greenfield development with favorable land acquisition costs in Gachibowli and Financial District expansion zones. State-level affordable-housing subsidy schemes alter project feasibility mathematics for mid-range segments. Metro connectivity extensions activate absorption velocity in under-construction inventory.
Tamil Nadu
Chennai coastal belt faces elevated BIS seismic compliance costs for Zone III high-rise construction. DLF Limited and L&T Realty concentrate premium inventory in certified seismic zones to justify structural cost premiums. Peripheral corridors toward Sriperumbudur absorb industrial workforce housing demand with compressed amenity packages.
Delhi-NCR
Gurgaon and Noida corridors capture disproportionate margin pools in luxury segments with 3 BHK configurations and servant quarters. CEA energy-efficiency directives for common-area systems impose recurring operational obligations on condominium associations. Sobha Limited leverages backward integration into manufacturing to control quality through in-house concrete production.
India Condominium and Apartments Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with balance-sheet-heavy developers commanding project pipelines at scale while asset-light operators concentrate on niche positioning. Market structure rotates competitive advantage toward firms with captive land banks and construction capabilities. Strategic archetypes include land-bank aggregators, green-certified premium developers, and backward-integrated manufacturers. Dominant competitive moves encompass portfolio diversification across price tiers and geographic corridor expansion into peripheral municipalities.
Within the land-bank aggregator tier, DLF Limited exemplifies scale-driven positioning through extensive Delhi-NCR reserves. Godrej Properties and Sobha Limited anchor the premium-green-manufacturing nexus, representing divergent pathways to pricing power. Brigade Group and Prestige Group occupy positions in southern corridor consolidation. These developers illustrate how compliance capabilities and captive supply chains separate sustainable operators from undercapitalized competitors.
| Leading Market Players |
|---|
| Godrej Properties |
| Tata Realty and Infrastructure |
| Prestige Group |
| Embassy Group |
| Brigade Group |
| Sobha Limited |
| DLF Limited |
| L&T Realty |
| Lodha Group |
| Others |
Supply & Pricing Matrix
Thirty-six-month foundation-to-superstructure timelines compress to twenty-four months through prefabricated concrete adoption, concentrating pricing power with developers who control captive manufacturing while squeezing margins for balance-sheet-light operators dependent on spot procurement.
Pricing Analysis
Project-based contracting dominates luxury and mid-range segments, with pre-launch pricing commitments locking in buyer obligations before construction commencement. Price differentiation rests on BIS seismic certification tier and CEA energy-efficiency compliance grade, with certified developments in Mumbai and Bengaluru commanding substantial premiums. Cost compression in affordable segments intensifies due to reinforcement steel volatility, while first-time buyers in Hyderabad and Pune peripheral zones exhibit highest price sensitivity. Luxury nuclear families in Delhi-NCR demonstrate lowest sensitivity, prioritizing servant quarters and smart-home specifications over per-square-foot economics.
Supply Chain Analysis
Strategic stockpiling of cement and steel inventories dominates developer behavior, with RERA-mandated escrow requirements forcing working capital discipline that discourages just-in-time procurement for critical structural inputs. Domestic manufacturing draws from cement clusters in Rajasthan and Andhra Pradesh, steel from Odisha and Jharkhand integrated mills, and finishing materials from Gujarat ceramics hubs. Single-source vulnerability concentrates in qualified seismic design consulting, where certified structural engineers extend project timelines. Distribution runs through project-specific batching plants and direct-to-site logistics networks controlled by balance-sheet-heavy developers.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Condominium maintenance and energy-efficiency upgrade services are expanding faster than hardware delivery, creating recurring revenue layers that decouple developer economics from pure construction margins.
For Market Incumbents: Shield margin pools by accelerating backward integration into concrete manufacturing and interior component production, countering input cost volatility that threatens affordable-segment viability. Deepen captive land bank conversion in Hyderabad and Pune peripheral corridors where municipal infrastructure expansion unlocks favorable acquisition costs. Certification investment in BIS seismic and CEA compliance separates sustainable operators from undercapitalized competitors facing working capital compression. For New Entrants and Emerging Players: Post-occupancy property management services represent a service-layer gap where incumbents under-serve, with condominium associations absorbing CEA-mandated common-area upgrade obligations without integrated vendor relationships. Target resale and pre-approved segments in Bengaluru and Chennai where investor buyers prioritize immediate rental yield over developer brand equity. Deploy digital-first discovery platforms with drone-captured progress feeds to compress customer acquisition costs among mobile-first nuclear families. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across high-rise construction segments, favoring asset-heavy operators with integrated manufacturing and land reserves over pure development plays. Viable acquisition targets combine RERA-compliant escrow structures with green-certified project pipelines in Maharashtra and Karnataka growth corridors. Watch BIS structural code enforcement intensity as the signal indicating regulatory filtering that concentrates market share among compliant operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Manufacturing | In-house concrete and interior production insulates margins from reinforcement steel volatility. |
| Green Building Certification Program | CEA-compliant developments command pricing premiums in Mumbai and Bengaluru luxury clusters. |
| Peripheral Corridor Land Acquisition | Hyderabad and Pune greenfield zones offer favorable feasibility mathematics for mid-range pipelines. |
| Digital Property Discovery Platform | Virtual walkthroughs displace broker networks for nuclear family segments aged 28-35. |
| Post-Occupancy Service Layer Expansion | Maintenance and energy-upgrade contracts generate recurring revenue beyond construction completion. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of RERA registration databases, BIS structural code filings, and municipal development authority records. Primary interviews engaged project development heads at integrated developers, procurement leads at cement and steel suppliers, RERA compliance officers, and condominium association managers across Maharashtra, Karnataka, Telangana, and Delhi-NCR. Secondary validation drew from Ministry of Housing and Urban Affairs policy circulars, state-level affordable-housing scheme documentation, and CEA energy-efficiency directive archives. Bottom-up project pipeline enumeration triangulates against top-down state-level absorption estimates.
Segmentation dimensions modeled encompass product configuration, price tier stratification, development maturity stage, and buyer archetype across the analysis window. The analytical framework projects value expansion through unit absorption velocity and per-square-foot realization trends, with CAGRs derived from corridor-specific supply-demand balances. Industry-specific forecast inputs include municipal floor-area-ratio relaxation timelines and metro connectivity extension schedules that activate peripheral zone feasibility.
Forecasts assume regulatory continuity in BIS structural certification and RERA escrow regimes; material policy shifts would require re-modeling. Structural steel price volatility and state-level subsidy scheme modification represent primary revision triggers. Revision becomes warranted when input cost swings exceed quarterly tolerance bands or when municipal infrastructure delays alter absorption velocity assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condominium and Apartments
Asia-Pacific Condominiums and Apartments Market
Condominium and Apartments
Europe Condominiums and Apartments Market
Condominium and Apartments
Egypt Condominiums and Apartments Market
Condominium and Apartments
UAE Condominiums and Apartments Market
Condominium and Apartments
Italy Condominiums and Apartments Market
Condominium and Apartments
Germany Condominiums and Apartments Market
Condominium and Apartments
Japan Condominiums and Apartments Market
Condominium and Apartments
Saudi Arabia Condominiums and Apartments Market
Condominium and Apartments
Global Condominiums and Apartments Market
Condominium and Apartments
Spain Condominiums and Apartments Market
Condominium and Apartments
Qatar Condominium and Apartment Market
Condominium and Apartments
ASEAN Condominiums and Apartments Market
Condominium and Apartments
Latin America Condominiums and Apartments Market
Condominium and Apartments
Condom Market
Condominium and Apartments
Canada Condominiums and Apartments Market