
 Spain Condominiums and Apartments Market | 2026-2036
Spain Condominiums and Apartments Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Condominiums and Apartments Market Analytics
Young professional demand for studio apartments in Madrid and Barcelona is broadening the buyer base beyond traditional family purchasers. Metrovacesa leverages its land bank dominance across Madrid's periphery to control prime development sites. Neinor Homes anchors its position through industrialized construction methods that compress delivery timelines. AEDAS Homes differentiates via build-to-rent pipelines targeting institutional investors seeking yield stability.
Spain condominiums and apartments constitute multi-unit residential structures where individual units carry private title while common areas remain collectively owned, typically constructed with reinforced concrete frames, thermal insulation meeting CTE standards, and centralized HVAC distribution. Their primary purpose is densified urban housing that optimizes land use efficiency and infrastructure cost per capita. Luxury condominiums command premium pricing in Barcelona's Eixample and Madrid's Salamanca district, while duplexes attract family upgraders in suburban corridors. Mixed-use developments integrate retail and office below residential towers, capturing margin pools from diversified revenue streams and reduced tenant turnover risk.
Spain's Ministerio de Transportes y Movilidad Sostenible enforces CTE compliance for energy performance certificates, tightening envelope standards and heating efficiency thresholds. Banco de España macroprudential rules cap loan-to-value ratios for investment properties, directly constraining speculative condominium purchases. Local ayuntamientos in Valencia and Málaga impose height restrictions and green-space ratios that shape permissible density and unit mix. Stakeholders must monitor ECB interest rate trajectories and regional zoning liberalization proposals to time land acquisition and presale launches effectively.
Market Dynamics
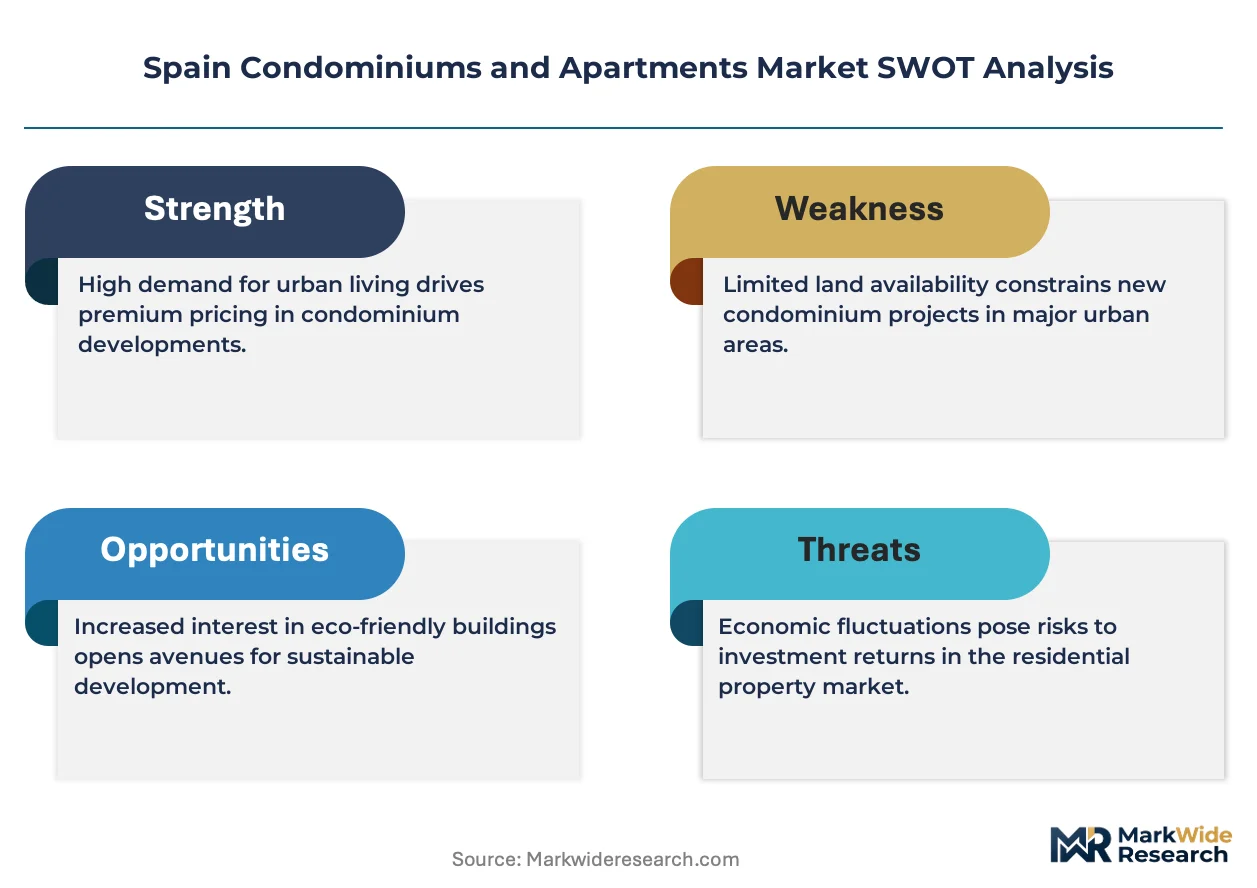
Spain's Código Técnico de la Edificación energy efficiency mandates are forcing developers to redesign building envelopes and HVAC systems, compressing margins on legacy project pipelines while accelerating capital deployment into certified green construction.
Growth Catalysts
- Young professional cohorts:Madrid and Barcelona studio apartment absorption is broadening the buyer base beyond traditional family purchasers, creating new density corridors in peripheral districts.
- CTE thermal insulation standards:Stricter envelope performance mandates are accelerating retrofit demand in Andalusia's aging coastal stock, unlocking renovation financing channels.
- Institutional capital deployment:Build-to-rent pipelines are attracting yield-focused investors seeking inflation-linked income streams from regulated tenancy frameworks.
Market Restraints
- Input cost volatility:Reinforced concrete and steel price fluctuations are squeezing developer margins on fixed-price presale contracts.
- Banco de España macroprudential caps:Loan-to-value limits on investment properties are constraining speculative condominium purchases in prime districts.
- Substitution pressure:Single-family detached housing in Madrid's exurban corridors is diverting family upgraders from duplex condominiums.
Strategic Opportunities
- Underpenetrated Andalusian secondary coast:Almería and Huelva vacation condominium stock remains below foreign retiree demand saturation levels.
- Industrialized construction convergence:Prefabricated facade systems and modular bathroom pods are compressing delivery timelines by 30-40 percent.
- Digital direct-to-buyer channels:Virtual staging and blockchain-enabled title transfers are disintermediating traditional broker networks.
Industry Challenges
- Certified energy auditor scarcity:CTE compliance documentation bottlenecks are delaying occupancy permits and presale closings.
- Legacy HVAC integration:Centralized distribution retrofits in 1970s concrete-frame buildings face spatial constraints and resident association approval friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Condominiums and Apartments Market |
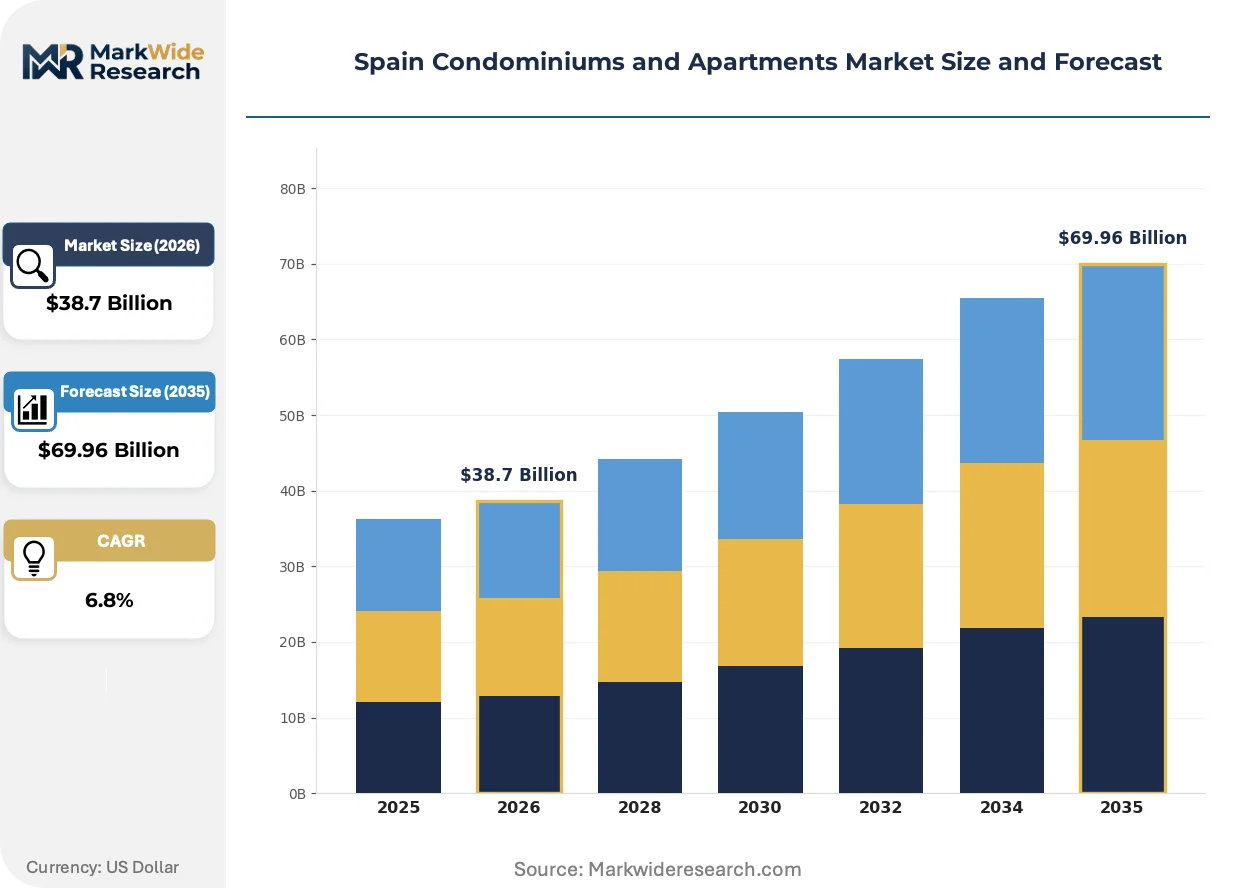
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luxury Condominiums, Studio Apartments, Penthouse Units, Duplexes Customer Type: First-Time Buyers, Investors, Vacation Home Buyers, Retirees Building Type: High-Rise Buildings, Low-Rise Buildings, Gated Communities, Mixed-Use Developments Sales Channel: Real Estate Agents, Online Platforms, Direct Sales, Open Houses |
| Companies Covered | Dragados Sociedad Anonima, Ferrovial Construccion SA, Constructora San Jose SA, Acsa Obras E Infraestructuras SAU, Ortiz Construcciones Y Proyectos SA, Metrovacesa, Neinor Homes, AEDAS Homes, Vía Célere, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Condominiums and Apartments Market Evolving Landscape
Active innovation in Spain's residential construction sector centers on material substitution, regulatory compliance automation, and buyer journey digitization. These forces are compressing traditional development cycles while raising capital efficiency thresholds.
Cross-laminated timber structural systems are overtaking conventional reinforced concrete frames in mid-rise Barcelona developments. Boutique developers targeting Eixample district eco-conscious buyers are specifying mass timber for its carbon sequestration credentials and faster assembly. This material transition is enabling tighter construction schedules and reduced foundation loads on constrained urban sites.
Spain's updated CTE energy certification framework is mandating near-zero energy building standards for all new permits from 2026. Developers must integrate photovoltaic generation and heat pump distribution or face permit rejection. The Valencia and Málaga municipal planning departments are already rejecting submissions lacking passive house pre-certification documentation.
Institutional investors are consolidating fragmented rental stock through portfolio acquisitions rather than greenfield development. Pension funds and REITs are deploying capital directly into stabilized income-producing assets, bypassing traditional developer intermediaries. This capital rotation is most visible in Madrid's Chamartín and Barcelona's Sant Martí districts where yield compression is accelerating.
Spain Condominiums and Apartments Market Segmentation
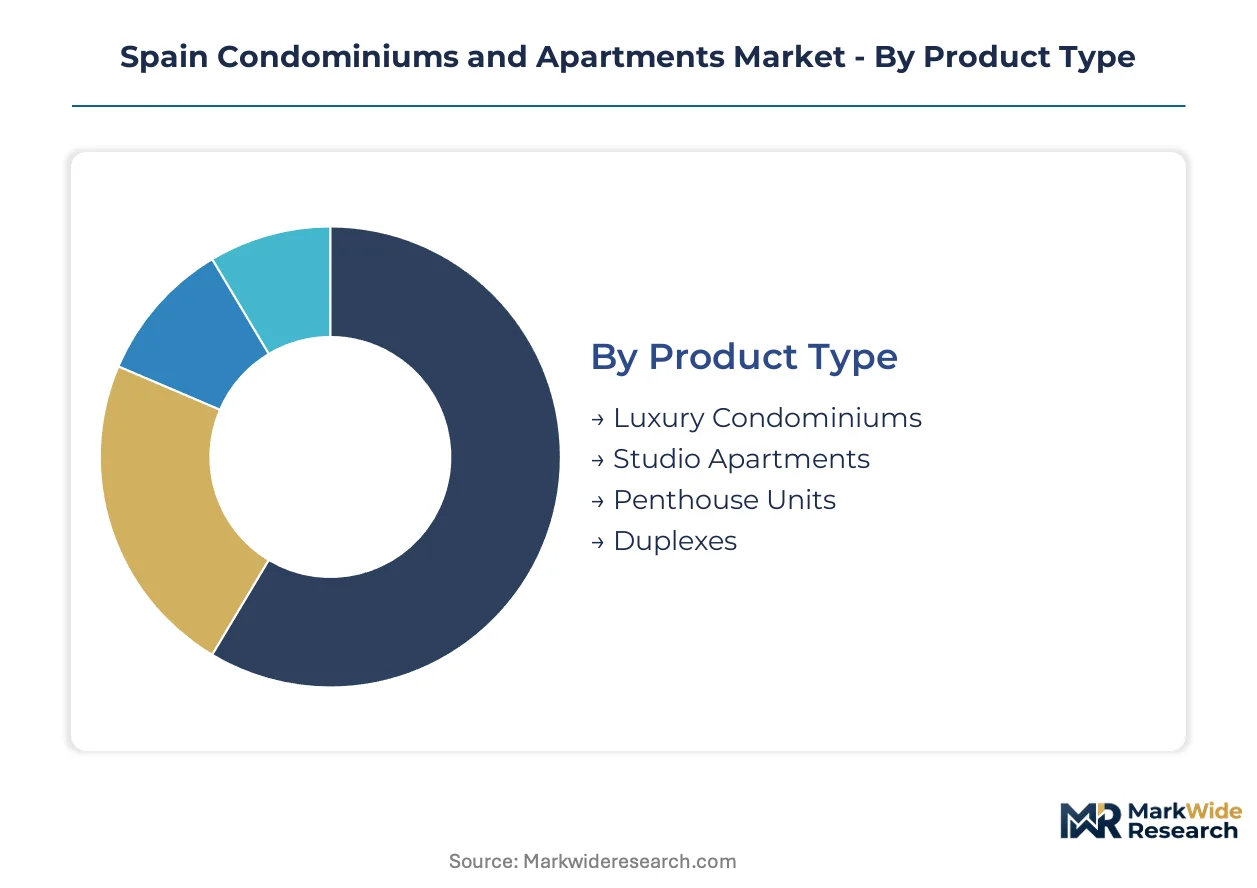
Segmentation in Spain's condominium and apartment market reveals how distinct buyer motivations, building specifications, and transaction pathways create differentiated competitive arenas. Developers and investors who align product configuration with channel strategy capture disproportionate margin pools in this maturing market.
Product Type:
Supply concentration in Madrid and Barcelona studio developments is reshaping developer priorities across Spain's urban periphery.
- Luxury Condominiums:Premium finishes, concierge services, and smart home integration define these units, typically exceeding 150 square meters in Barcelona's Eixample and Madrid's Salamanca district. Foreign capital from Northern European retirees drives absorption in coastal Andalusian nodes, though CTE energy certification delays constrain new supply pipelines.
- Studio Apartments:Compact 25-45 square meter units optimized for single occupancy, featuring modular furniture systems and shared amenity floors. Young professionals in Madrid's Chamberí and Barcelona's Gràcia are absorbing inventory faster than replacement rates, forcing developers to accelerate peripheral land acquisition.
- Penthouse Units:Top-floor configurations with private terraces and double-height living spaces command scarcity premiums in Valencia's Ciudad de las Artes corridor.
- Duplexes:Two-level family-oriented units in suburban Madrid municipalities attract upgraders seeking space without exurban commute penalties.
Today's leader: Studio Apartments. Tomorrow's challenger: Luxury Condominiums.
Customer Type:
Cost tier stratification across buyer profiles determines financing structure and holding period expectations for Spanish developers.
- First-Time Buyers:Young Spanish nationals aged 25-35 accessing subsidized VPO (Vivienda de Protección Oficial) schemes and family co-signatures for mortgage approval. Madrid's periphery and Barcelona's L'Hospitalet de Llobregat concentrate this demand, with Banco de España LTV caps constraining leverage ratios.
- Investors:Yield-focused purchasers targeting build-to-rent exposure or short-term tourist rental conversion in Málaga and Alicante coastal zones. Institutional capital from pension funds and REITs is displacing individual landlords in Madrid's Chamartín district.
- Vacation Home Buyers:Seasonal-use purchasers from Germany, UK, and Scandinavia seeking Andalusian and Balearic exposure with EU residency pathway benefits.
- Retirees:Fixed-income European nationals prioritizing ground-floor accessibility, healthcare proximity, and community amenities in Valencia's Alboraya and Málaga's Benalmádena.
First-Time Buyers anchor volume. Investors are gaining share fastest.
Building Type:
Application-driven design differentiation separates urban densification plays from lifestyle-oriented community developments.
- High-Rise Buildings:Reinforced concrete towers exceeding 12 stories with centralized HVAC and elevator banks, concentrated in Madrid's AZCA financial district and Barcelona's Diagonal Mar. CTE envelope standards are forcing facade retrofit investments in 1970s vintage stock.
- Low-Rise Buildings:Four-to-six story walk-up or elevator-served structures dominating Barcelona's Eixample grid and Valencia's historic center. Heritage preservation restrictions in these districts limit demolition-replacement economics.
- Gated Communities:Perimeter-secured developments with shared pools and landscaped commons attracting family purchasers in Madrid's Pozuelo de Alarcón and Barcelona's Sant Cugat del Vallès.
- Mixed-Use Developments:Vertical integration of retail, office, and residential in single structures, reducing tenant turnover risk through diversified revenue streams in Bilbao's Abandoibarra and Seville's Torre Sevilla zone.
High-Rise Buildings dominate urban supply. Mixed-Use Developments are climbing the fastest.
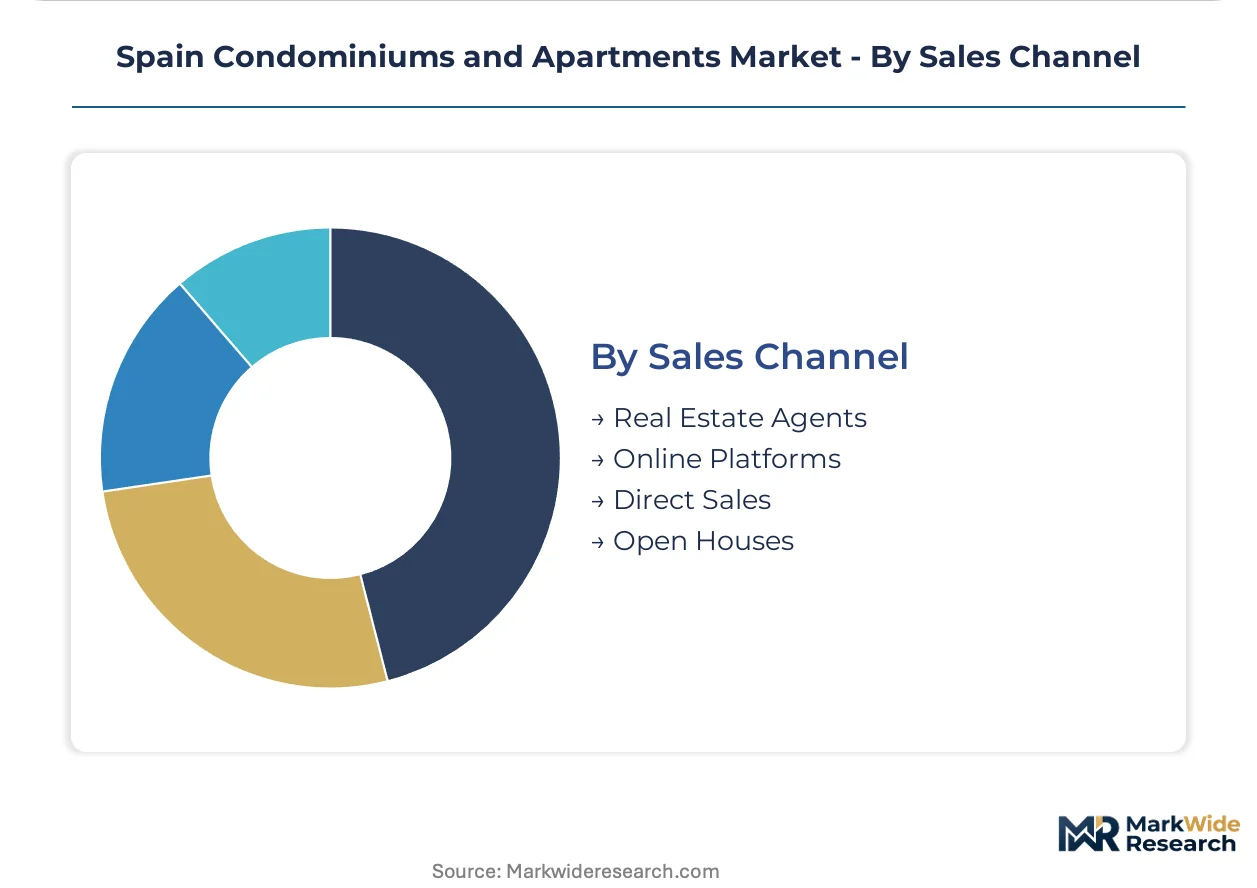
Sales Channel:
Volume concentration in traditional broker networks is fragmenting as digital platforms capture younger buyer cohorts.
- Real Estate Agents:Traditional commission-based intermediaries controlling prime district inventory access, particularly in Barcelona's Sarrià-Sant Gervasi and Madrid's Retiro. Established agencies maintain exclusivity relationships with Metrovacesa and Neinor Homes for new-build allocations.
- Online Platforms:Digital listing aggregators and virtual tour technologies disintermediating search behavior, with blockchain-enabled title transfers emerging in Valencia pilot programs.
- Direct Sales:Developer-owned showrooms and appointment-only preview events capturing margin otherwise paid to external brokers.
- Open Houses:Weekend viewing events generating competitive bidding dynamics in supply-constrained Madrid submarkets.
Real Estate Agents retain transaction volume leadership. Online Platforms represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's condominium market exhibits pronounced regional divergence as developers arbitrage regulatory cost differentials between autonomous communities. Madrid and Catalonia enforce stricter CTE energy compliance timelines than Andalusia or Valencia, redirecting speculative capital toward southern corridors where permitting cycles compress.
Madrid
Young professional absorption of studio units in Chamberí and Tetuán is outpacing replacement rates. The Comunidad de Madrid's updated VPO subsidy thresholds are tightening eligibility for first-time buyers. Metrovacesa's land bank dominance across Madrid's periphery is controlling prime development sites for future pipeline releases.
Catalonia
Barcelona's Eixample district commands scarcity premiums for luxury condominiums with heritage facade preservation. The Generalitat de Catalunya's urban density bonuses reward developers exceeding passive house standards in new permits. Cross-laminated timber adoption is accelerating in Gràcia and Sant Martí mid-rise projects.
Andalusia
Foreign retiree demand for Málaga and Alicante coastal vacation condominiums is absorbing inventory faster than regional construction permits allow. Andalusia's regional government maintains lighter CTE enforcement timelines than northern autonomous communities. Benalmádena and Estepona are witnessing institutional capital deployment into stabilized rental portfolios.
Valencia
The Valencia municipal planning department is rejecting submissions lacking passive house pre-certification documentation ahead of 2026 federal deadlines. Local ayuntamientos impose height restrictions that constrain high-rise density in the historic center. Alboraya's ground-floor accessible units are attracting fixed-income European retirees prioritizing healthcare proximity.
Basque Country
Bilbao's Abandoibarra mixed-use zone is integrating retail and office below residential towers to diversify revenue streams. The Eusko Jaurlaritza maintains distinct building code amendments that exceed federal CTE baselines for thermal envelope performance. San Sebastián's constrained topography is limiting greenfield expansion and elevating land values.
Spain Condominiums and Apartments Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated developers controlling prime urban land banks while regional contractors execute peripheral projects. Market structure tilts toward consolidation in Madrid and Barcelona, where three players dominate land acquisition, while Andalusian and Valencian markets retain fragmented contractor pools. Two archetypes define competitive positioning: land-bank aggregators monetizing scarcity premiums in prime districts, and industrialized builders compressing delivery timelines through prefabrication. Dominant competitive moves include portfolio diversification into build-to-rent pipelines and geographic expansion through regional contractor acquisitions.
Within the land-bank aggregator tier, Metrovacesa and AEDAS Homes exemplify capital deployment strategies targeting institutional yield-seekers. Among industrialized specialists, Neinor Homes occupies a position representing prefabricated construction convergence. These three developers anchor the competitive landscape by demonstrating divergent pathways to margin defense—scarcity control versus velocity optimization—without relying on overlapping geographic or product positioning.
| Leading Market Players |
|---|
| Dragados Sociedad Anonima |
| Ferrovial Construccion SA |
| Constructora San Jose SA |
| Acsa Obras E Infraestructuras SAU |
| Ortiz Construcciones Y Proyectos SA |
| Metrovacesa |
| Neinor Homes |
| AEDAS Homes |
| Vía Célere |
| Others |
Value Network & Pricing Analysis
Spain's Código Técnico de la Edificación near-zero energy building standards gate qualified supply access and premium-tier pricing power, as developers lacking certified green construction capabilities face permit rejection while CTE-compliant projects command 15-20 percent absorption premiums in Madrid and Barcelona submarkets.
Pricing Analysis
Direct-to-buyer sales channels capture margin otherwise paid to traditional broker networks, compressing external commission layers. Pricing stratifies across luxury condominiums, studio apartments, and economy-tier VPO units based on CTE certification grade and geographic delivery cost to coastal versus interior markets. Pricing pressure stems from reinforced concrete and steel input cost volatility squeezing fixed-price presale contract margins. First-time buyers accessing subsidized VPO schemes exhibit highest price sensitivity, while foreign retiree vacation home purchasers in Andalusia show lowest elasticity.
Supply Chain Analysis
Dual-sourcing mandates from institutional investors and large developers require multi-supplier qualification for reinforced concrete, steel rebar, and HVAC equipment to mitigate construction delay risk. Spain's supply chain draws from domestic cement producers, German and Italian HVAC system manufacturers, and Chinese photovoltaic panel suppliers for CTE-mandated building-integrated generation. Single-source vulnerability concentrates in certified energy auditor services, where qualified assessor scarcity delays occupancy permits. Distribution runs through developer-direct procurement for major projects and regional building material distributors serving fragmented Andalusian contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's condominium market represents a late-cycle quality story as young professional demand for CTE-certified studio apartments in Madrid and Barcelona shifts absorption toward premium energy-efficient specifications, compressing margins for legacy non-compliant stock.
For Market Incumbents: Deploy land-bank monetization acceleration to capture scarcity premiums before CTE enforcement timelines tighten. Metrovacesa and AEDAS Homes should consolidate peripheral Madrid development sites against emerging industrialized builders threatening delivery timeline advantages. Neinor Homes must defend prefabrication velocity leadership through modular bathroom pod capacity expansion as cross-laminated timber specialists enter Barcelona mid-rise segments.
For New Entrants and Emerging Players: Spain's updated Código Técnico de la Edificación energy certification framework opens a window for certified energy auditor service platforms addressing documentation bottlenecks delaying occupancy permits. Target Almería and Huelva vacation condominium construction where foreign retiree demand exceeds regional permit issuance capacity. Pursue direct-to-buyer digital channels disintermediating traditional broker networks through virtual staging and blockchain-enabled title transfer pilots.
For Investors and Strategic Acquirers: Roll-up economics work for stabilized rental portfolio aggregators because institutional capital deployment into build-to-rent pipelines is displacing individual landlords in Madrid's Chamartín and Barcelona's Sant Martí districts. Focus acquisition screening on Andalusian coastal assets with CTE retrofit pathways and regulated tenancy framework exposure. Monitor ECB interest rate trajectories as the inflection signal for presale launch timing and leveraged yield compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Industrialized Construction Scale-Up | Prefabricated facade systems compress delivery timelines by 30-40 percent for Neinor Homes and Vía Célere pipelines. |
| Build-to-Rent Portfolio Acquisition | Pension funds and REITs deploy capital directly into stabilized Chamartín and Sant Martí income-producing assets. |
| CTE Compliance Technology Investment | Automated energy certification documentation reduces occupancy permit delays and presale closing friction. |
| Cross-Laminated Timber Adoption | Mass timber structural systems enable faster Barcelona Eixample assembly and carbon sequestration positioning. |
| Digital Direct-to-Buyer Channel Development | Virtual staging and blockchain title transfers disintermediate traditional broker networks in Valencia pilot programs. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Spanish developer project directors, Banco de España macroprudential policy officers, Andalusian municipal planning regulators, institutional investor real estate allocation heads, and certified energy auditor practitioners with secondary validation against Ministerio de Transportes y Movilidad Sostenible CTE filings, Banco de España financial stability reports, autonomous community housing ministry statistics, and ECB monetary policy communications. Bottom-up project pipeline enumeration and top-down autonomous community absorption estimates were triangulated to anchor market sizing.
Segment-weighting approaches distributed value and volume across product type, customer type, building type, and sales channel dimensions, with additional stratification by CTE compliance tier and geographic regulatory cluster. CAGRs were derived from fitted trend extrapolation adjusted for policy inflection points and capital cycle timing. Forecast inputs incorporated ECB rate trajectory assumptions, regional zoning liberalization proposals, and industrialized construction penetration curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated CTE enforcement or prolonged monetary tightening conditions. Deviation in Banco de España loan-to-value cap adjustments or Andalusian permitting velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condominium and Apartments
Latin America Condominiums and Apartments Market
Condominium and Apartments
India Condominium and Apartments Market
Condominium and Apartments
Japan Condominiums and Apartments Market
Condominium and Apartments
Egypt Condominiums and Apartments Market
Condominium and Apartments
Global Condominiums and Apartments Market
Condominium and Apartments
Qatar Condominium and Apartment Market
Condominium and Apartments
Italy Condominiums and Apartments Market
Condominium and Apartments
Europe Condominiums and Apartments Market
Condominium and Apartments
ASEAN Condominiums and Apartments Market
Condominium and Apartments
Canada Condominiums and Apartments Market
Condominium and Apartments
Asia-Pacific Condominiums and Apartments Market
Condominium and Apartments
Saudi Arabia Condominiums and Apartments Market
Condominium and Apartments
Condom Market
Condominium and Apartments
UAE Condominiums and Apartments Market
Condominium and Apartments
Germany Condominiums and Apartments Market