
 Germany Condominiums and Apartments Market | 2026-2036
Germany Condominiums and Apartments Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Condominiums and Apartments Market Foresight
The German Building Energy Act (GEG) is consolidating cost-of-entry calculus for developers across Germany's residential construction sector. Hochtief Solutions AG leverages its engineering scale to navigate complex energy-efficiency compliance in multi-unit projects. LEG Immobilien SE anchors its portfolio strategy around rental and condominium ownership models in supply-constrained cities. Deutsche Wohnen SE differentiates through integrated property management platforms that sustain tenant retention across its Berlin and Rhine-Ruhr holdings.
Germany condominiums and apartments comprise individually owned residential units within multi-dwelling structures, typically constructed with reinforced concrete frameworks, thermal insulation composite systems, and centralized heating distribution networks designed for permanent urban habitation. The property type dimension spans studio through penthouse configurations, with two-bedroom units commanding the deepest buyer pool among first-time purchasers and small families. Building age segmentation reveals new construction and contemporary stock capturing premium pricing, while renovated historic properties in city centers attract investor capital seeking depreciation advantages and cultural amenity proximity.
KfW promotional bank standards and federal BauNVO zoning regulations shape permissible density and financing access across German states, directly influencing developer site selection and unit mix decisions. The country's national building regulator enforces GEG thermal performance thresholds that elevate material specifications and mechanical system costs for permitted projects. Stakeholders must monitor evolving federal rent control legislation and municipal expropriation debates that could recalibrate ownership model attractiveness and capital deployment timelines.
Market Dynamics
The German Building Energy Act (GEG) is compressing developer margins while mandating heat pump compatibility and photovoltaic integration in new residential construction, forcing a wholesale recalibration of project feasibility models across Berlin, Munich, and Hamburg metropolitan zones.
Growth Catalysts
- Urbanization pressure:Young professionals migrating into Berlin and Stuttgart are expanding the first-time purchaser segment for compact two-bedroom units. Municipal housing shortage declarations in Frankfurt and Cologne are accelerating permit timelines for qualifying projects.
- KfW promotional financing:Subsidized loan programs for energy-efficient construction are improving developer access to below-market capital. Efficiency House Plus standards unlock additional federal grants that offset GEG compliance costs.
- Renovation wave mechanics:Historic building stock in Leipzig and Dresden city centers offers depreciation advantages and cultural amenity proximity that attracts yield-focused investor capital.
Market Restraints
- Construction input volatility:Reinforced concrete and thermal insulation composite systems face price instability from energy-intensive manufacturing processes. Supply bottlenecks in cross-laminated timber imports constrain alternative material substitution.
- Zoning density limits:Federal BauNVO regulations cap permissible floor-area ratios in established neighborhoods. Municipal preservation designations in Hamburg and Munich restrict demolition-replacement economics.
- Interest rate transmission:European Central Bank policy rates have compressed mortgage affordability for leveraged purchasers. Financing cost spikes disproportionately affect entry-level buyer segments in secondary cities.
Strategic Opportunities
- Heat pump infrastructure retrofit:District heating conversion programs in eastern German cities create bundled service revenue streams. Integrated mechanical system providers can capture lifecycle value beyond initial equipment sales.
- Modular prefabrication:Factory-built wall and facade elements reduce on-site labor dependency and compress construction schedules. Bavarian and Baden-Württemberg manufacturing clusters offer logistics advantages for southern German projects.
- Build-to-rent-to-own conversion:Institutional rental platforms can structure equity-participation mechanisms that bridge tenant savings gaps. Rhine-Ruhr metropolitan employment density supports sustained occupancy through transition periods.
Industry Challenges
- Skilled trades scarcity:Electrical and HVAC technician shortages in northern German construction markets are extending commissioning timelines. Vocational pipeline gaps in heat pump installation certification compound GEG implementation delays.
- GEG compliance complexity:Thermal bridge calculation methodologies and primary energy demand documentation require specialized energy consulting. Project teams face penalty exposure from regulator interpretation variance across federal states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Condominiums and Apartments Market |
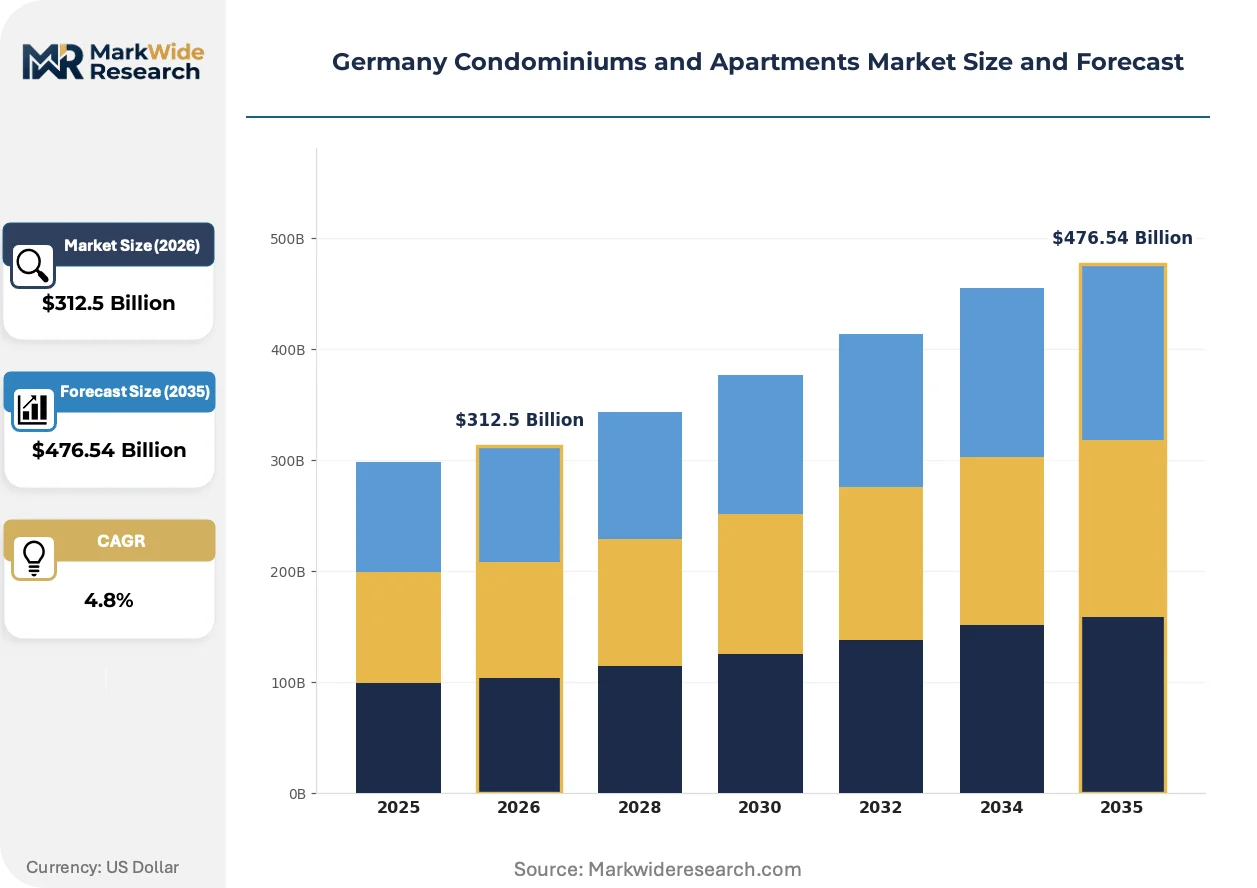
| Market Size in 2026 | $312.5 Billion |
| Market Size in 2035 | $476.54 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Studio, One-Bedroom, Two-Bedroom, Penthouse, Loft Building Age: New Construction, Renovated, Historic, Pre-War, Contemporary Ownership Model: Freehold, Leasehold, Cooperative, Rental, Condominium Ownership Buyer Profile: First-Time Purchasers, Real Estate Investors, Relocators, Downsizers, Vacation Home Buyers |
| Companies Covered | Vivawest GmbH, Strabag AG, Hochtief Solutions AG, Koster GmbH, Bremer AG, GAG Immobilien AG, ZECH Hochbau AG, LEG Immobilien SE, Deutsche Wohnen SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Condominiums and Apartments Market Shifts & Advancements
Residential construction across German metropolitan zones is undergoing a technology and policy recalibration centered on electrification mandates, prefabrication advances, and ownership-model experimentation that redefines how units are delivered and financed.
Heat pump systems paired with rooftop photovoltaic arrays and battery storage are electrifying the mechanical infrastructure of new multi-unit developments. Developers in Berlin and Munich are specifying these packages as standard to preempt GEG enforcement thresholds. The technology stack is compressing traditional gas-boiler supply chains while creating captive electricity demand that reshapes utility contracting structures.
The German Building Energy Act enforcement timeline is tightening thermal performance verification requirements for building permits. Project developers must now submit primary energy demand calculations and thermal bridge assessments before construction authorization. New construction segments in Hamburg and Frankfurt are responding by front-loading energy consulting contracts and locking in equipment specifications earlier in design phases.
Institutional rental platforms are unbundling property management, maintenance, and energy services into separate contractual relationships. Tenants in Rhine-Ruhr and Stuttgart markets are selecting service tiers à la carte rather than accepting bundled landlord provisions. This fragmentation is most visible among young professional households who prioritize flexibility over traditional ownership equity accumulation.
Germany Condominiums and Apartments Market Segmentation
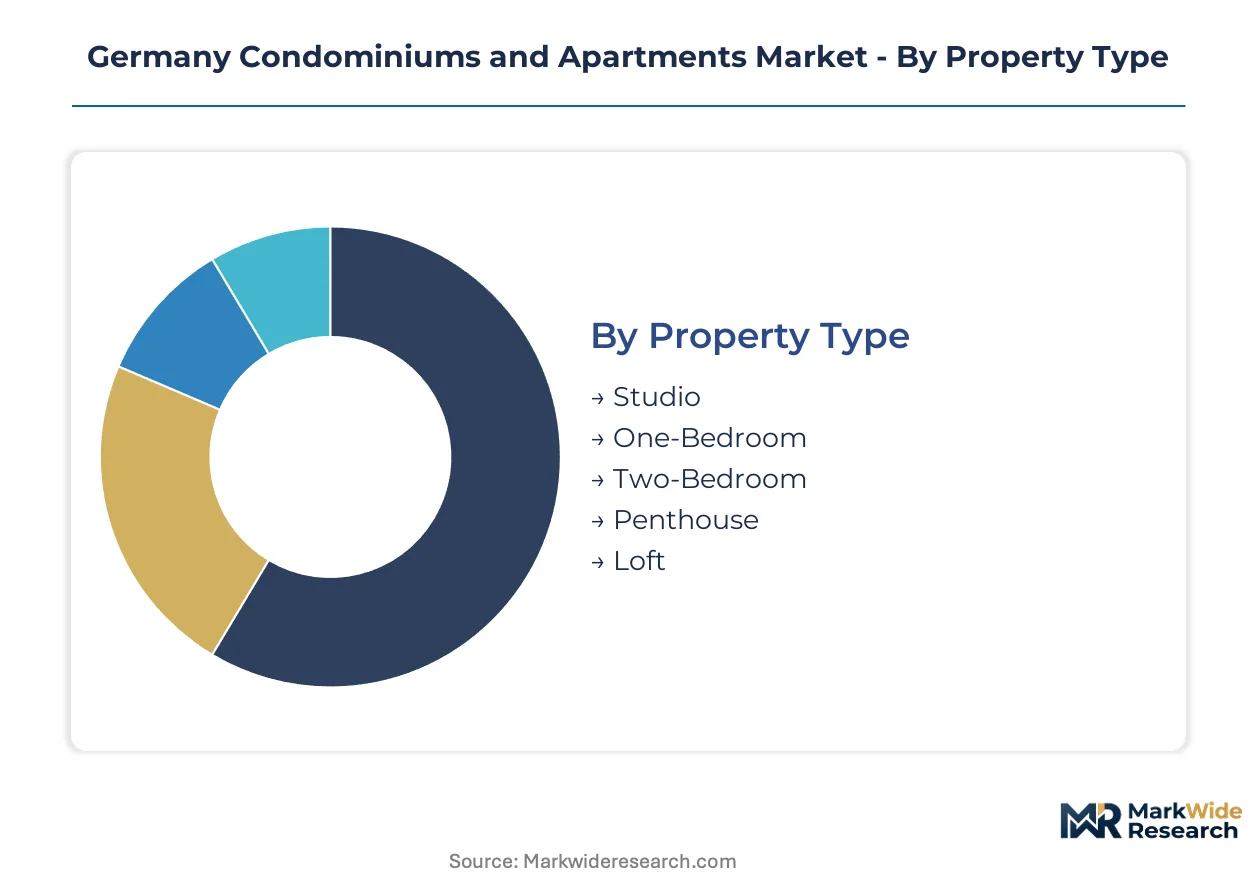
Unit configurations and buyer demographics in Germany's residential market determine financing structures, energy compliance pathways, and pricing elasticity across Berlin, Munich, and Hamburg metropolitan zones. Developers calibrate floor plans and ownership mechanisms to match municipal density regulations and KfW promotional bank eligibility criteria.
Property Type:
Standalone units dominate developer pipelines, while embedded multi-bedroom configurations serve integrated household formation needs in supply-constrained cities.
- Studio:Compact single-room layouts with integrated kitchenettes and minimal square footage target young professionals entering Berlin and Munich labor markets. Demand concentrates in university-adjacent districts and inner-ring neighborhoods with transit proximity; affordability constraints and first-time buyer mortgage limits sustain this segment's velocity.
- Two-Bedroom:Dual-chamber configurations with separate living and sleeping zones accommodate small families and dual-income households. This format captures the deepest buyer pool across Frankfurt and Stuttgart metropolitan areas; municipal housing shortage declarations accelerate permit timelines for qualifying projects in this category.
- One-Bedroom:Distinct sleeping and living quarters serve solo professionals and couples without children in Cologne and Düsseldorf.
- Penthouse:Top-floor units with terrace access and panoramic positioning command premium positioning in Hamburg harbor districts.
- Loft:Converted industrial spaces with open floor plans attract creative-sector professionals in Leipzig and Dresden.
Volume placements concentrate in Two-Bedroom units; the faster expansion belongs to Studio configurations.
Building Age:
Cost tiers separate premium new construction from value-positioned existing stock, with renovation bridging the efficiency-performance gap.
- New Construction:GEG-compliant structures with heat pump infrastructure and photovoltaic integration command pricing premiums across Bavarian and Baden-Württemberg developments. These units satisfy Efficiency House Plus standards for KfW promotional financing; thermal performance verification requirements front-load energy consulting contracts earlier in design phases.
- Historic:Pre-1945 structures with preservation designations offer depreciation advantages and cultural amenity proximity in Hamburg and Munich city centers. Investor capital targets these assets for yield-focused portfolios; municipal preservation restrictions constrain demolition-replacement economics.
- Renovated:Modernized existing stock with updated mechanical systems occupies mid-market positioning in Rhine-Ruhr cities.
- Pre-War:Early 20th-century construction with period details attracts heritage-conscious purchasers in Berlin.
- Contemporary:Post-2000 builds with standardized energy profiles serve family formation needs in Stuttgart suburbs.
Investor capital concentrates in Historic stock; the steepest expansion trajectory belongs to New Construction as GEG enforcement tightens.
Ownership Model:
Application context determines whether purchasers seek equity accumulation, flexibility, or income-generating structures.
- Freehold:Absolute ownership of unit and land interest provides maximum control for long-term household stability. This model dominates family-oriented purchases in suburban Munich and Frankfurt; federal rent control legislation debates recalibrate attractiveness relative to rental alternatives.
- Condominium Ownership:Individual unit title with shared common element responsibility structures urban multi-dwelling investment. Berlin and Hamburg professional households favor this format; homeowners association governance creates ongoing cost obligations that influence resale liquidity.
- Leasehold:Building ownership with ground lease obligations reduces entry costs in high-land-value districts.
- Cooperative:Share-based collective ownership with occupancy rights attracts community-oriented purchasers in progressive urban neighborhoods.
- Rental:Pure tenancy without equity participation serves transient professional segments and affordability-constrained households.
First-time placements concentrate in Condominium Ownership; the fastest share gains belong to Freehold as interest rate volatility shifts preferences toward fixed-cost structures.
Buyer Profile:
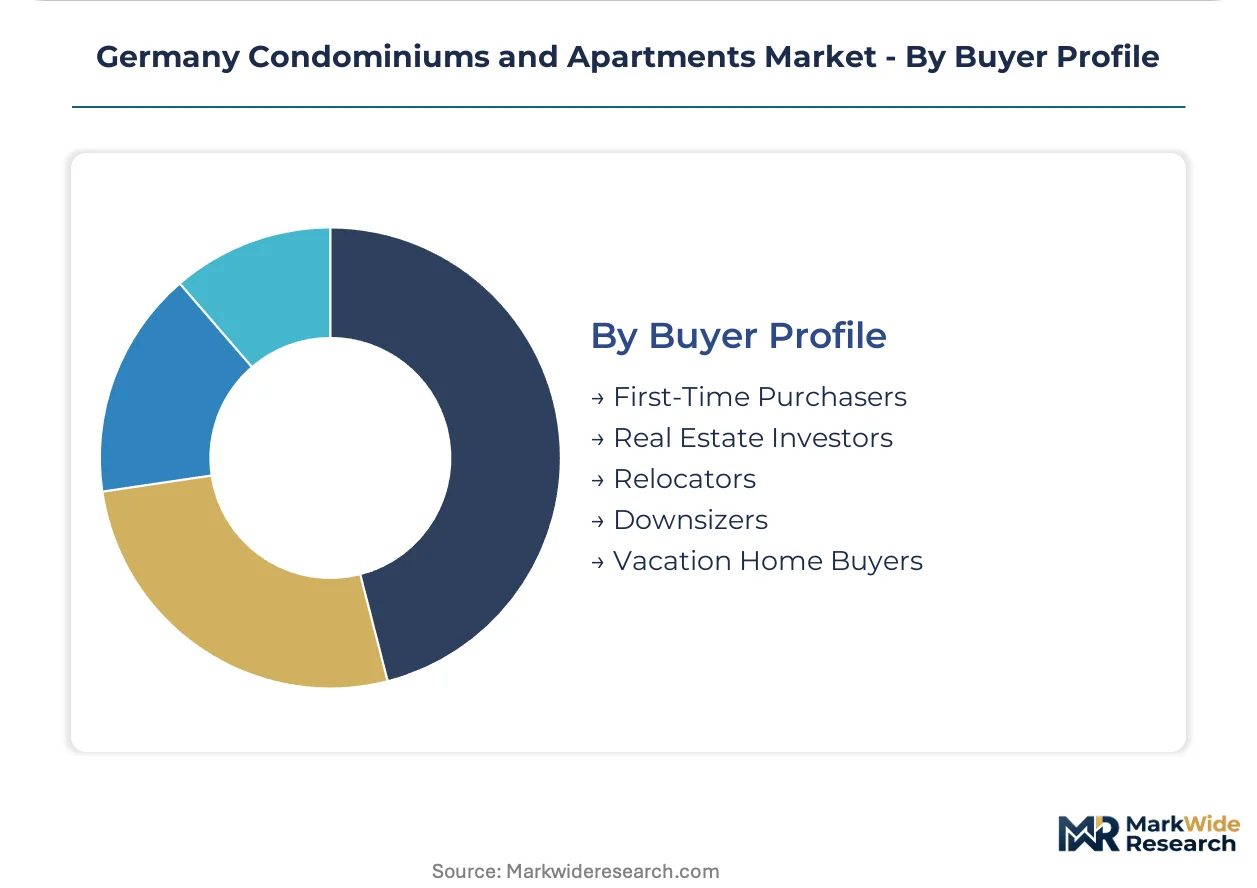
Customer type segmentation aligns marketing channels, financing products, and unit feature prioritization across German metropolitan markets.
- First-Time Purchasers:Entry-level households accumulating initial equity through leveraged acquisition dominate volume in Berlin and Stuttgart. Young professionals migrating into these cities expand this segment; European Central Bank policy rate transmission compresses mortgage affordability and extends savings timelines.
- Real Estate Investors:Yield-focused capital deploys across rental and appreciation strategies in supply-constrained markets. Institutional platforms structure build-to-rent-to-own mechanisms in Rhine-Ruhr metropolitan zones; depreciation advantages from historic building stock attract this buyer category to Leipzig and Dresden centers.
- Relocators:Inter-city and international transferees seek immediate occupancy solutions in Frankfurt and Munich.
- Downsizers:Empty-nest households trading square footage for location convenience concentrate in Hamburg and Cologne.
- Vacation Home Buyers:Secondary residence purchasers target recreational proximity in Bavarian lake districts and North Sea coastal zones.
Mortgage origination volumes concentrate in First-Time Purchasers; the most rapid buyer category expansion belongs to Real Estate Investors as rental yield spreads widen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan zones in Germany's western and southern states concentrate condominium and apartment demand, while eastern cities attract yield-focused investment capital seeking renovation opportunities.
North Rhine-Westphalia
Rhine-Ruhr employment density sustains rental occupancy across Düsseldorf, Cologne, and Essen. The state's municipal housing shortage declarations accelerate permit timelines for qualifying multi-unit projects. Dortmund and Bochum industrial conversion zones supply build-to-rent platforms with brownfield development sites.
Bavaria
Munich's technology sector expansion draws young professionals into compact studio and two-bedroom configurations. Bavarian manufacturing clusters around Nuremberg and Augsburg offer logistics advantages for modular prefabrication suppliers. Ingolstadt's automotive employment base stabilizes family-oriented suburban demand in Contemporary building stock.
Baden-Württemberg
Stuttgart's engineering concentration generates dual-income household formation in mid-market segments. The state's vocational training pipeline addresses heat pump installation certification gaps that delay GEG compliance. Karlsruhe and Mannheim riverfront zones attract penthouse development targeting executive relocators.
Berlin-Brandenburg
Capital region migration flows expand first-time purchaser volumes in Condominium Ownership structures. Federal rent control legislation debates and municipal expropriation discussions recalibrate investor capital deployment timelines. Potsdam's proximity to Berlin labor markets supports satellite city development in supply-constrained conditions.
Hamburg
Harbor district regeneration commands premium positioning for penthouse and loft configurations. Municipal preservation designations in Altona and Eimsbüttel restrict demolition-replacement economics for historic stock. Lübeck and Kiel secondary markets absorb affordability-constrained buyers from the metropolitan core.
Germany Condominiums and Apartments Market Competitive Landscape
German engineering-scale developers anchor one tier; regional construction specialists hold project-specific positioning in municipal markets. The vendor base clusters around integrated property management platforms and energy-compliance engineering capabilities. Three archetypes dominate: nationwide residential platforms with rental-to-ownership conversion mechanisms, engineering-led construction conglomerates navigating GEG thermal performance thresholds, and municipal-focused developers exploiting local zoning familiarity. Competitive moves concentrate on portfolio diversification across ownership models and strategic partnerships with KfW promotional financing channels.
Within the engineering-scale tier, Hochtief Solutions AG and ZECH Hochbau AG exemplify construction conglomerates leveraging technical capabilities for complex multi-unit compliance. LEG Immobilien SE and Deutsche Wohnen SE occupy positions in integrated property management, anchoring rental and condominium ownership models in supply-constrained metropolitan zones. Vivawest GmbH represents regional specialists concentrating on North Rhine-Westphalia municipal relationships and localized zoning navigation.
| Leading Market Players |
|---|
| Vivawest GmbH |
| Strabag AG |
| Hochtief Solutions AG |
| Koster GmbH |
| Bremer AG |
| GAG Immobilien AG |
| ZECH Hochbau AG |
| LEG Immobilien SE |
| Deutsche Wohnen SE |
| Others |
Supply & Pricing Matrix
GEG thermal performance mandates gate both qualified supply and premium-tier pricing access for German residential developers. Compliance-certified contractors and energy-efficient material suppliers command pricing premiums that stratify project economics across Berlin, Munich, and Hamburg metropolitan zones.
Pricing Analysis
Lead-time-driven pricing separates expedited GEG-compliant builds from standard-permit timelines, with heat pump-ready units commanding premiums over gas-boiler legacy stock. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and geographic delivery cost. Cost compression in entry-level segments is intensifying because ECB rate transmission extends first-time buyer savings timelines. First-time purchasers in secondary cities exhibit highest price sensitivity; institutional investors in historic Berlin and Leipzig stock show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Chinese photovoltaic module suppliers and Nordic cross-laminated timber producers serving German prefabrication demand. Manufacturing concentrates in Germany, Poland, and Austria for structural components; mechanical systems draw from Italy and Netherlands. Supply chain risk centers on energy-intensive cement and insulation manufacturing exposure to carbon border adjustments. Distribution runs through regional builder merchant networks and direct-to-developer factory contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
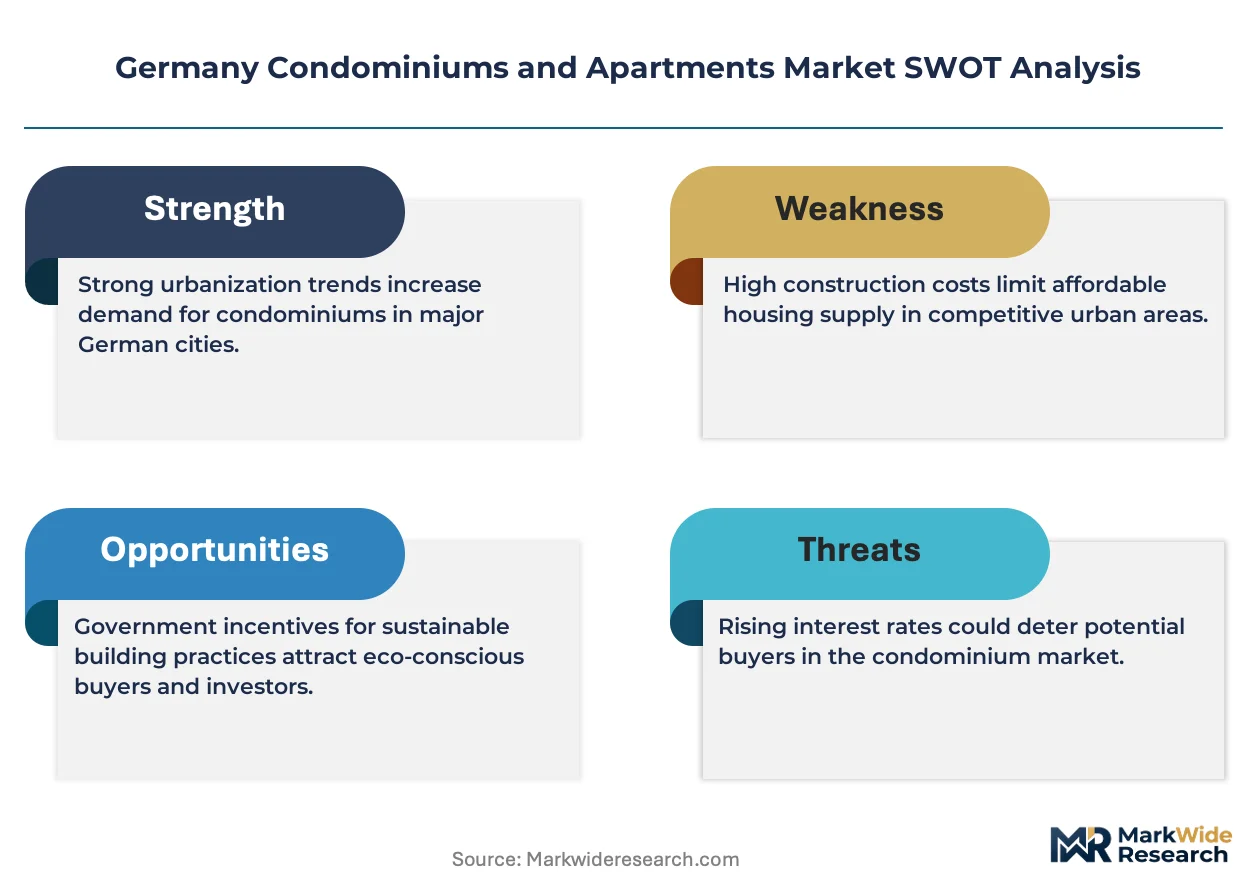
German Building Energy Act enforcement erects a barrier-to-entry moat that rewards compliant incumbents with preferred KfW financing access and accelerated permitting. This cost-of-compliance dynamic concentrates competitive advantage among engineering-scale developers.
For Market Incumbents: Deploy heat pump installation certification pipelines to capture scarce technician capacity before GEG deadlines tighten. Anchor portfolio strategy around Efficiency House Plus standards that unlock federal grant offsets. Consolidate regional construction specialists in North Rhine-Westphalia and Bavaria to defend municipal zoning relationships against modular prefabrication entrants. For New Entrants and Emerging Players: Capture brownfield industrial conversion opportunities in Dortmund and Bochum where municipal shortage declarations accelerate timelines. Target build-to-rent-to-own mechanisms in Rhine-Ruhr employment corridors where tenant equity-participation bridges affordability gaps. Partner with Bavarian manufacturing clusters for logistics-advantaged modular wall and facade supply. For Investors and Strategic Acquirers: KfW promotional bank lending volume shifts is the leading indicator that capital allocation toward GEG-compliant development is accelerating. Long-term viability favors integrated property management platforms with captive maintenance and energy service revenue streams. Monitor municipal expropriation debate resolutions in Berlin as inflection signal for ownership model attractiveness recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Pump Infrastructure Retrofit | District heating conversion in eastern German cities creates bundled lifecycle revenue beyond equipment sales. |
| Modular Prefabrication Scale-Up | Factory-built elements reduce on-site labor dependency and compress construction schedules in southern German projects. |
| Build-to-Rent-to-Own Conversion | Equity-participation mechanisms bridge tenant savings gaps in Rhine-Ruhr metropolitan employment corridors. |
| Energy Consulting Front-Loading | Early thermal bridge assessment contracts preempt GEG penalty exposure from regulator interpretation variance. |
| Historic Renovation Specialization | Depreciation advantages and cultural amenity proximity attract yield-focused capital to Leipzig and Dresden centers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Germany residential construction analysis. Primary interviews with project developers, energy consultants, municipal planning officers, and KfW promotional bank relationship managers combined with bottom-up permit database triangulation. Secondary sources included Federal Statistical Office construction reports, Bundesbank mortgage origination data, and state-level BauNVO zoning filings.
Data-stream reconciliation across unit configuration segmentation, buyer profile cohorts, building age tiers, and ownership model structures shaped the analytical framework throughout the forecast period. CAGRs derived from construction permit velocity, demographic migration patterns, and financing origination trends. Modeled inputs incorporated GEG enforcement phase-ins, heat pump installation capacity constraints, and municipal housing shortage declaration coverage.
The model holds under steady GEG regulatory interpretation and KfW promotional financing continuity; deviation in ECB policy trajectory or federal rent control legislation would shift first-time purchaser segment elasticity. Forecasts reflect assumptions on skilled trades pipeline recovery and cross-laminated timber import stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condominium and Apartments
Global Condominiums and Apartments Market
Condominium and Apartments
India Condominium and Apartments Market
Condominium and Apartments
Italy Condominiums and Apartments Market
Condominium and Apartments
Japan Condominiums and Apartments Market
Condominium and Apartments
ASEAN Condominiums and Apartments Market
Condominium and Apartments
Europe Condominiums and Apartments Market
Condominium and Apartments
Condom Market
Condominium and Apartments
Latin America Condominiums and Apartments Market
Condominium and Apartments
Saudi Arabia Condominiums and Apartments Market
Condominium and Apartments
Asia-Pacific Condominiums and Apartments Market
Condominium and Apartments
Canada Condominiums and Apartments Market
Condominium and Apartments
Qatar Condominium and Apartment Market
Condominium and Apartments
UAE Condominiums and Apartments Market
Condominium and Apartments
Spain Condominiums and Apartments Market
Condominium and Apartments
Egypt Condominiums and Apartments Market