
 Asia-Pacific Condominiums and Apartments Market | 2026-2036
Asia-Pacific Condominiums and Apartments Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Condominiums and Apartments Market Outlook
Vietnam's southern economic corridor is tilting toward high-density residential construction as manufacturing relocations from China swell the middle-income workforce. Ayala Land leverages its integrated township model across Philippine secondary cities to sustain premium pricing power. Sansiri anchors Bangkok's mid-market segment through design-forward studios targeting domestic upgraders. Frasers Property competes across Singapore and Australia with leasehold structures that reduce entry barriers for younger buyers.
Asia-Pacific condominiums and apartments comprise multi-unit residential structures where individual ownership attaches to defined airspace within a strata-titled building, typically constructed with reinforced concrete frames, curtain-wall glazing, and shared mechanical systems for HVAC and water distribution. The primary commercial purpose centers on capital-efficient land use in dense metropolitan zones where single-family development proves economically unviable. High-rise product dominates transaction volume across core Southeast Asian markets, though low-rise stock captures outsized margins in suburban Tokyo and Sydney where height restrictions preserve neighborhood character. First-time homebuyers represent the deepest demand pool, while investor financing through mortgage structures faces tightening scrutiny as central banks adjust risk weights on speculative lending.
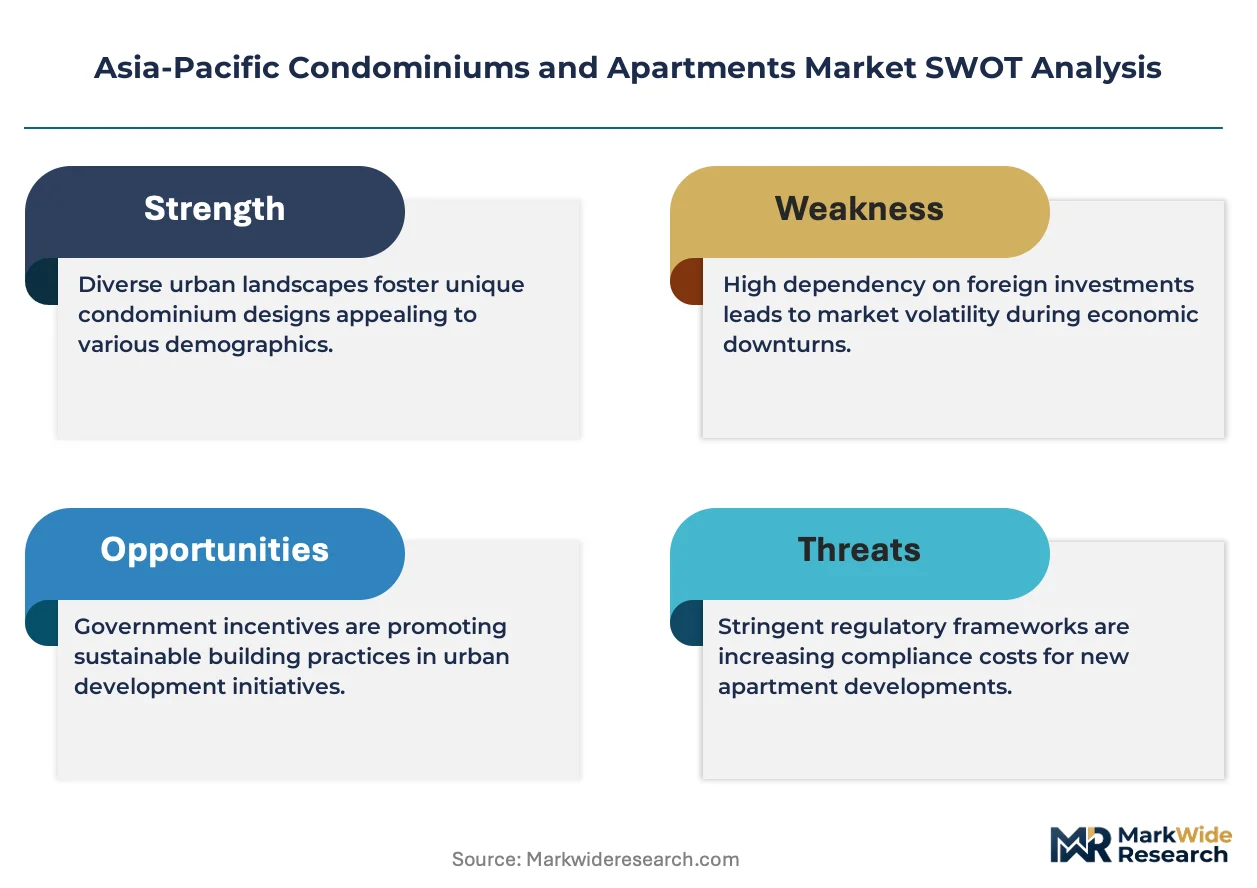
Japan's METI enforces progressive energy efficiency standards that mandate thermal performance upgrades in new condominium envelopes, directly elevating construction costs and filtering developer margins. Australia's National Construction Code, administered by the Australian Building Codes Board, imposes waterproofing and fire safety protocols that extend project timelines and reshape procurement patterns for cladding materials. Thailand's Condominium Act, overseen by the Land Department, restricts foreign ownership quotas and dictates common-area governance structures that influence project feasibility calculations. Stakeholders must monitor how divergent energy transition timelines across ASEAN member states recalibrate capital allocation between speculative development and build-to-rent platforms.
Market Dynamics
Urban densification mandates across Southeast Asian capitals are compressing allowable floor area ratios while elevating land premiums, forcing developers toward vertical construction models that maximize revenue per square meter of footprint. Japan's METI energy codes add compliance layers that filter margin structures and reshape envelope procurement decisions.
Growth Catalysts
- Foreign ownership liberalization:Vietnam's revised Housing Law expands condominium purchase rights for overseas Vietnamese and foreign residents, widening the buyer pool in Ho Chi Minh City and Hanoi corridors.
- Build-to-rent platforms:Institutional capital deployment into professionally managed rental stock addresses housing affordability gaps while generating yield-stable alternatives to speculative development.
- Cross-laminated timber adoption:Engineered wood systems reduce embodied carbon in mid-rise construction, aligning with Australia's National Construction Code sustainability pathways and Singapore's Green Mark incentives.
Market Restraints
- Reinforcing steel volatility:Input cost swings for rebar and structural mesh compress developer pro forma certainty, particularly in Philippine and Indonesian markets with thin margin buffers.
- Foreign quota ceilings:Thailand's Condominium Act caps non-Thai ownership at 49 percent per project, constraining capital inflows in Bangkok's prime districts where international demand concentrates.
- Curtain-wall procurement concentration:Specialized glazing and aluminum facade systems source predominantly from Chinese suppliers, exposing project timelines to geopolitical friction and logistics bottlenecks.
Strategic Opportunities
- Secondary city penetration:Philippine developers deploy integrated township models in Cebu and Davao, capturing manufacturing relocation spillover demand outside Metro Manila's saturated core.
- Retrofit-to-residential conversion:Aging office stock in Sydney and Melbourne repurposes under relaxed planning codes, activating stranded assets without greenfield land acquisition.
- Smart home infrastructure bundling:IoT-ready unit specifications command premium absorption from tech-sector employees in Bangalore and Singapore's one-north district.
Industry Challenges
- Waterproofing certification delays:Australia's National Construction Code amendments extend facade compliance timelines, compressing construction schedules and elevating carry costs.
- Strata management talent scarcity:Complex governance requirements for multi-owner buildings outpace qualified facility manager supply in Vietnam and Indonesia's emerging high-rise markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Condominiums and Apartments Market |
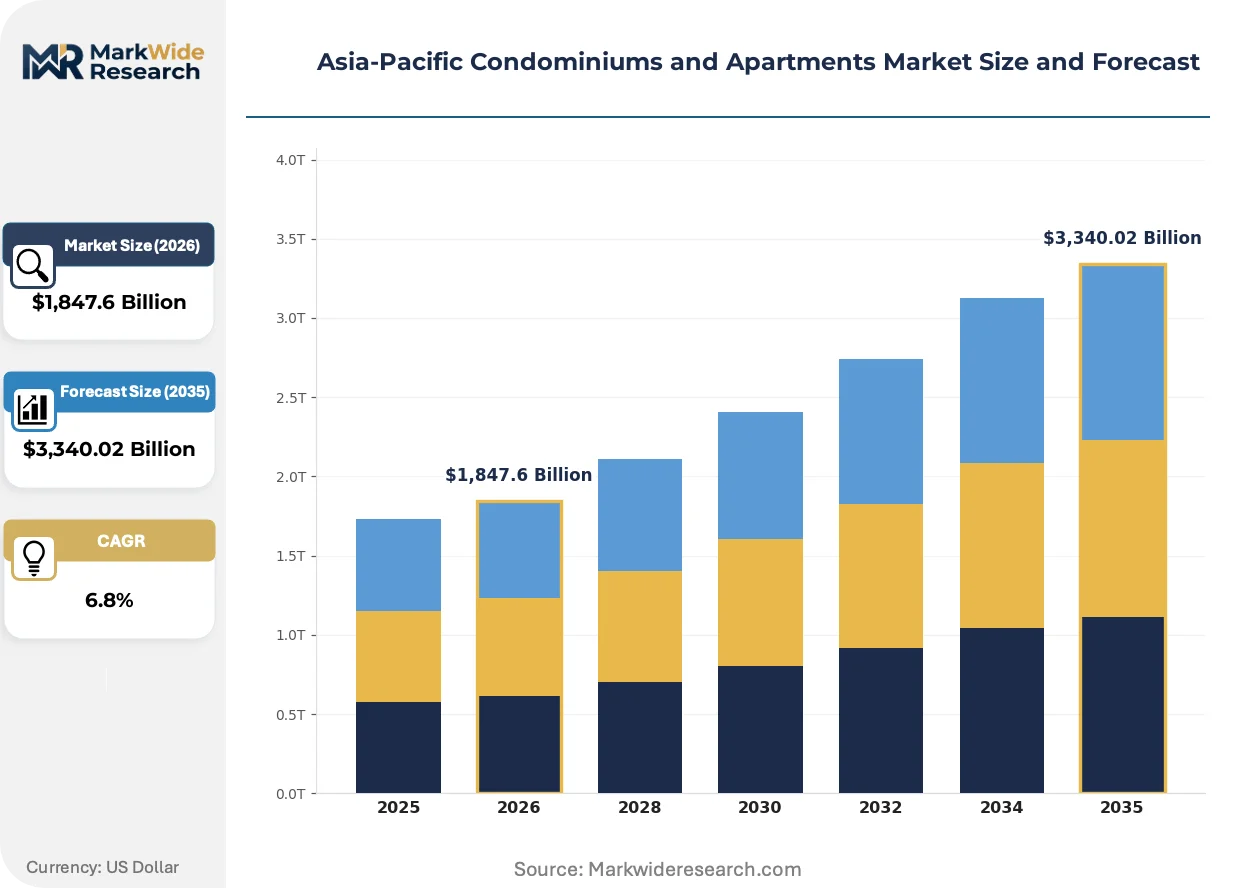
| Market Size in 2026 | $1,847.6 Billion |
| Market Size in 2035 | $3,340.02 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-rise, Low-rise, Duplex, Studio Customer Type: First-time Homebuyers, Investors, Renters, Luxury Buyers Financing Method: Cash Purchase, Mortgage, Leasehold, Equity Financing Service Type: Property Management, Real Estate Brokerage, Renovation Services, Valuation Services |
| Companies Covered | Sena Development, Asset Wise, Sansiri, Ayala Land, Reignwood Park, Supalai, Frasers Property, Megaworld, Asset World Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Condominiums and Apartments Market Strategic Shifts
Construction methodology and resident experience layers are converging as climate compliance tightens and digital infrastructure becomes table stakes. Developers now compete on operational efficiency and lifecycle performance rather than raw specifications.
Mass timber structural systems is hybridizing reinforced concrete dominance in mid-rise residential construction. Australian and Japanese developers pilot hybrid concrete-timber frames for 12-to-25-storey product, compressing carbon intensity while meeting seismic codes. The technology is hybridizing procurement patterns as engineered wood suppliers secure multi-project supply agreements with tier-one contractors.
Japan's METI progressive energy efficiency standards mandate thermal bridge mitigation and high-performance glazing in new condominium envelopes. Compliance elevates construction costs by 8-to-12 percent but unlocks green financing windows through Japan Housing Finance Agency preferential rates. Premium segment projects in Tokyo and Osaka absorb these premiums fastest, marketing certified units to ESG-constrained institutional buyers.
Domestic upgraders in Bangkok and Manila now prioritize leasehold structures with embedded facility management over freehold acquisition with fragmented strata governance. Professional operators like Sansiri and Ayala Land capture this preference shift through branded service tiers that unbundle maintenance from ownership. The model concentrates most visibly in Philippine secondary cities where first-generation homeowners lack experience managing multi-owner buildings.
Asia-Pacific Condominiums and Apartments Market Segmentation
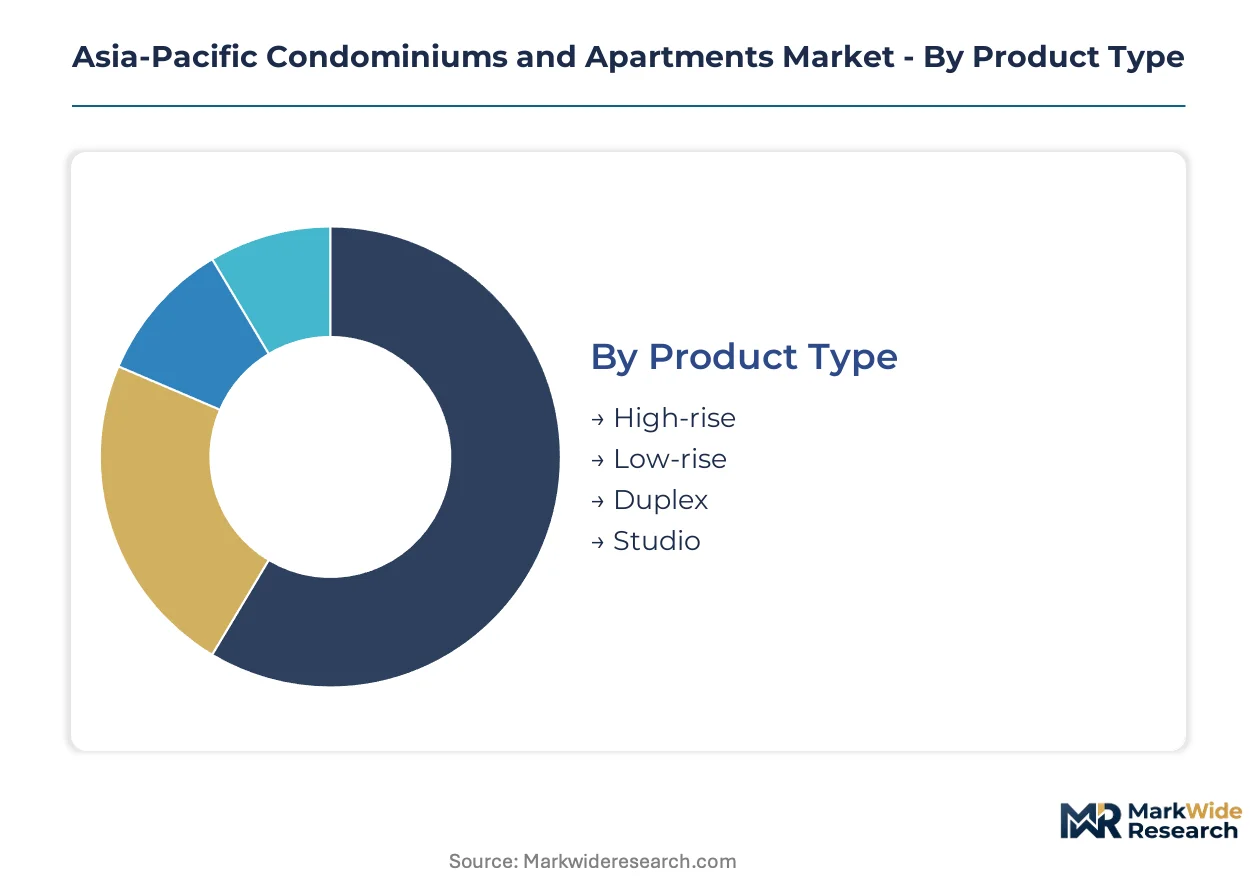
Segmentation in Asia-Pacific residential real estate reveals how capital sources, ownership structures, and service intensity reshape developer strategies across divergent regulatory environments. Understanding these divides clarifies where margin compression concentrates and where premium capture endures.
Product Type:
After-sales service intensity varies sharply by vertical scale, with high-rise towers demanding perpetual facility management contracts while low-rise stock shifts maintenance burden to owners.
- High-rise:Structures exceeding twelve storeys dominate transaction volume in Ho Chi Minh City and Bangkok. Reinforced concrete frames with centralized HVAC and curtain-wall envelopes require specialized strata management. Demand concentrates where urban densification mandates compress allowable floor area ratios and elevate land premiums.
- Low-rise:Four-to-eight storey walk-ups and podium buildings capture outsized margins in suburban Tokyo and Sydney where height restrictions preserve neighborhood character. Timber framing and smaller mechanical footprints reduce operational complexity. Australian developers pilot cross-laminated timber systems here to satisfy National Construction Code sustainability pathways.
- Duplex:Split-level units attached through common walls appeal to domestic upgraders in Philippine secondary cities seeking freehold alternatives to condominium strata governance.
- Studio:Compact single-room configurations absorb young professional households in urban centers across Vietnam and Thailand, with design-forward specifications commanding premium absorption from tech-sector employees.
High-rise holds the largest share; momentum sits with low-rise as timber hybridization and carbon compliance reshape mid-rise construction economics.
Customer Type:
Financing sophistication and holding-period expectations segment buyer pools, with institutional investors demanding yield-stabilized structures that first-time purchasers cannot access.
- First-time Homebuyers:The deepest demand pool across Southeast Asian markets, typically acquiring compact units through mortgage structures. Thailand's Condominium Act foreign ownership quotas constrain their competition with international capital in prime Bangkok districts.
- Investors:Deploy capital through build-to-rent platforms or speculative pre-sales, prioritizing leasehold structures with embedded facility management over fragmented strata governance. Australia's tightening risk weights on speculative lending filter this segment's access to leverage.
- Renters:Professionalized rental stock addresses affordability gaps in Singapore and Sydney, with institutional operators capturing yield premiums through branded service tiers.
- Luxury Buyers:ESG-constrained institutional purchasers in Tokyo and Osaka absorb METI-mandated envelope premiums fastest, marketing certified units to buyers prioritizing green financing windows through Japan Housing Finance Agency preferential rates.
First-time homebuyers dominate unit absorption; investors are expanding most quickly as build-to-rent platforms professionalize rental yield capture.
Financing Method:
Capital structure determines developer margin sensitivity to interest rate cycles and foreign exchange volatility across the region's divergent monetary policy regimes.
- Cash Purchase:Dominates ultra-prime transactions in Singapore and Hong Kong, insulating buyers from central bank risk-weight adjustments but concentrating price discovery in thin markets.
- Mortgage:Conventional bank financing faces tightening scrutiny as Australia's prudential regulator elevates risk weights on speculative lending, compressing investor purchasing power.
- Leasehold:Frasers Property deploys leasehold structures across Singapore and Australia to reduce entry barriers for younger buyers, capturing demand that freehold premiums would exclude.
- Equity Financing:Institutional capital deployment into professionally managed rental stock generates yield-stable alternatives to speculative development, particularly where REIT structures unlock retail investor participation.
Mortgage financing retains the largest share; leasehold structures are gaining share fastest as developers unbundle maintenance from ownership to capture domestic upgrader preferences.
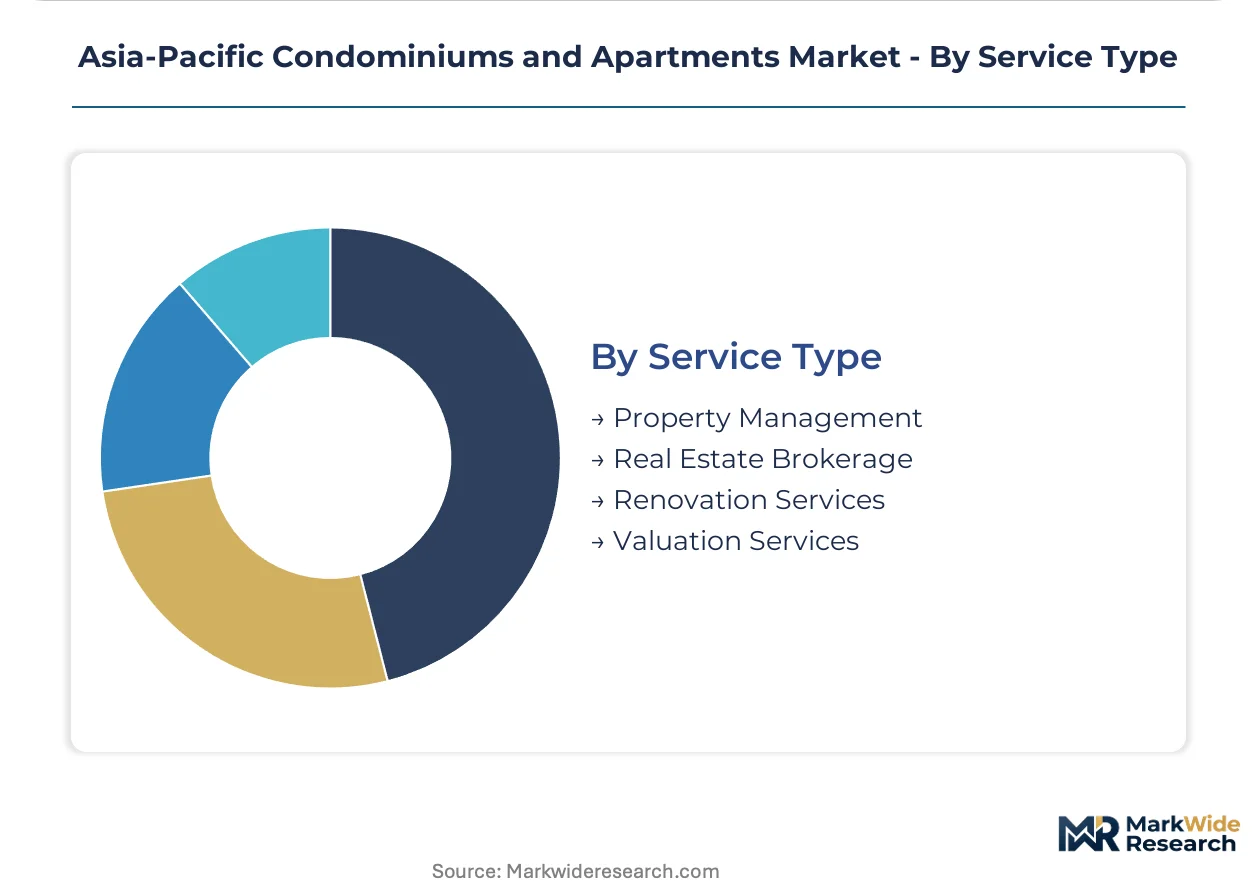
Service Type:
Revenue recurrence and margin stability separate transactional brokerage from annuity-style property management in developer portfolio construction.
- Property Management:Complex governance requirements for multi-owner buildings outpace qualified facility manager supply in Vietnam and Indonesia's emerging high-rise markets, creating capability scarcity that professional operators exploit.
- Real Estate Brokerage:Transactional fee income concentrates in Ho Chi Minh City and Hanoi corridors where Vietnam's revised Housing Law expands foreign purchase rights and widens the buyer pool.
- Renovation Services:Retrofit-to-residential conversion of aging office stock in Sydney and Melbourne activates stranded assets without greenfield land acquisition, demanding specialized contractor networks.
- Valuation Services:Institutional due diligence for build-to-rent platforms requires discounted cash flow expertise that domestic appraisers in secondary Philippine cities often lack.
Property management commands the largest service revenue share; renovation services show the steepest expansion trajectory as adaptive reuse accelerates under relaxed planning codes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across the Asia-Pacific region. Japanese buyers prioritize energy-certified envelopes with embedded green financing. Southeast Asian markets absorb compact studio configurations driven by young professional household formation. Australian demand tilts toward adaptive reuse of aging commercial stock.
Japan
Tokyo and Osaka corridors absorb METI-mandated envelope premiums fastest among premium-segment projects. Japan's METI progressive energy efficiency standards mandate thermal bridge mitigation and high-performance glazing. Kanto region developers market certified units to ESG-constrained institutional buyers through Japan Housing Finance Agency preferential rates.
Vietnam
Ho Chi Minh City corridors concentrate demand where manufacturing relocations from China swell middle-income workforce housing needs. Vietnam's revised Housing Law expands condominium purchase rights for overseas Vietnamese and foreign residents. Southern economic corridor supply pipelines tighten as developers pivot toward high-density residential construction.
Thailand
Bangkok's mid-market segment absorbs design-forward studios targeting domestic upgraders seeking leasehold structures with embedded facility management. Thailand's Condominium Act caps non-Thai ownership at 49 percent per project, constraining capital inflows in prime districts. Chao Phraya riverfront clusters see intensified competition for foreign quota allocation.
Philippines
Cebu and Davao secondary cities capture manufacturing relocation spillover demand outside Metro Manila's saturated core. Philippine developers deploy integrated township models with professional strata governance that first-generation homeowners lack experience managing. Ayala Land leverages this model to sustain premium pricing power across provincial urban centers.
Australia
Sydney and Melbourne activate stranded office assets through retrofit-to-residential conversion under relaxed planning codes without greenfield land acquisition. Australia's National Construction Code imposes waterproofing and fire safety protocols that extend facade compliance timelines. New South Wales and Victoria lead adaptive reuse volume as institutional capital seeks yield-stable rental platforms.
Asia-Pacific Condominiums and Apartments Market Competitive Environment
Capability concentration sits with integrated township specialists; scale advantage sits with diversified regional platforms. The market structures around three tiers: domestic upgrader specialists, foreign quota optimizers, and institutional rental operators. Strategic archetypes include design-forward lifestyle brands, secondary city township developers, and leasehold structure innovators. Competitive moves center on secondary city geographic expansion and professionalized facility management unbundling from ownership.
Within the integrated township tier, Ayala Land anchors Philippine secondary city penetration through professionalized governance structures. Sansiri exemplifies Bangkok's design-forward mid-market positioning for domestic upgraders. Frasers Property occupies the leasehold innovation vector across Singapore and Australian markets. These three represent distinct strategic archetypes: township integration, lifestyle branding, and tenure structure flexibility.
| Leading Market Players |
|---|
| Sena Development |
| Asset Wise |
| Sansiri |
| Ayala Land |
| Reignwood Park |
| Supalai |
| Frasers Property |
| Megaworld |
| Asset World Corporation |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Vietnamese curtain-wall glazing production is compressing developer pro forma certainty while elevating procurement premiums for high-rise envelopes across Ho Chi Minh City corridors. This utilization squeeze forces developers toward hybrid timber-concrete systems or extended supplier lead times, reshaping both cost structures and project timelines.
Pricing Analysis
Project-based contracting dominates developer-procurement relationships for structural steel and facade systems, with spot-market exposure for rebar and aluminum extrusions during construction ramps. Price differentiation hinges on green certification tier—Japan Housing Finance Agency preferential rates for METI-compliant envelopes versus standard financing—and volume scale for integrated township rollouts. Pricing pressure stems from reinforcing steel volatility in Philippine and Indonesian markets where thin margin buffers amplify input cost swings. First-time homebuyers exhibit acute price sensitivity, while luxury buyers in Tokyo absorb envelope premiums fastest.
Supply Chain Analysis
Upstream feedstock for reinforced concrete frames draws from Chinese cement and clinker production, Australian iron ore for rebar, and Indonesian nickel for stainless-steel facade fasteners. Cross-laminated timber procurement centers on Austrian and Canadian engineered-wood suppliers serving Australian hybrid-construction pilots. Single-source vulnerability concentrates in Chinese curtain-wall glazing and aluminum systems, exposing project timelines to geopolitical friction. Distribution runs through tier-one contractors with multi-project supply agreements, particularly for mid-rise timber hybridization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against build-to-rent platforms displacing speculative pre-sale absorption, as institutional capital professionalizes rental yield capture and reshapes buyer expectations toward service-embedded leasehold structures.
For Market Incumbents: Insulate margin structures by securing backward integration into cross-laminated timber supply chains for mid-rise product lines, countering steel-input volatility. Deepen facility management capabilities to capture recurring revenue from strata-titled towers, neutralizing the threat from professionalized rental operators. Prioritize green envelope certification to unlock Japan Housing Finance Agency preferential rates and differentiate from commodity developers. For New Entrants and Emerging Players: Establish a beachhead in Philippine secondary city integrated townships where Ayala Land's governance-heavy model leaves whitespace for design-forward competitors targeting manufacturing relocation spillover. Penetrate Bangkok's leasehold mid-market segment through embedded facility management unbundling, capturing domestic upgrader preference shifts away from fragmented strata ownership. Deploy smart-home infrastructure bundling as a go-to-market wedge in Bangalore and Singapore's one-north district. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among developers with professionalized property management arms serving high-rise strata buildings, generating annuity streams insulated from cyclical pre-sale volatility. Acquisition targets should display integrated township expertise in secondary Vietnamese or Philippine cities with tightening supply pipelines. Watch for inflection signals in central bank risk-weight adjustments on speculative lending, which filter investor access to leverage and reshape capital structure preferences.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Timber Supply | Captures cross-laminated timber procurement security for Australian National Construction Code compliance. |
| Green Envelope Certification Program | Unlocks Japan Housing Finance Agency preferential rates for METI-compliant Tokyo developments. |
| Facility Management Unbundling | Converts Bangkok domestic upgraders from fragmented strata governance to service-embedded leasehold. |
| Secondary City Township Expansion | Absorbs manufacturing relocation spillover in Cebu and Davao outside Metro Manila saturation. |
| Smart Home Infrastructure Partnership | Commands premium absorption from tech-sector employees in Singapore's one-north district. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, construction permit databases, and institutional capital deployment records. Interviews with property development executives, strata management operators, procurement directors at tier-one contractors, and central bank regulatory affairs specialists inform demand-side and financing-structure assessments. Secondary validation draws from Japan METI energy code amendments, Australia's National Construction Code updates, Thailand's Condominium Act interpretations, and Vietnam's revised Housing Law implementing decrees. Bottom-up project pipeline tracking triangulates against top-down macroeconomic absorption modeling.
Forecast inputs incorporate urban densification mandate trajectories, foreign ownership quota utilization rates, and green financing window availability across the projection horizon. Segmentation dimensions span product type, customer archetype, financing method, and service intensity. CAGRs derive from supply-demand balance modeling in corridor-specific submarkets, with sensitivity to reinforcing steel price indices and central bank risk-weight adjustments. Timber hybridization adoption curves and build-to-rent capital deployment velocity constitute industry-specific forecast inputs.
Sensitivities concentrate around geopolitical friction in Chinese facade-system supply, ASEAN member state energy transition timeline divergence, and prudential regulator recalibration of speculative lending risk weights. Cross-checking against Japan Housing Finance Agency disbursement data and Australian Bureau of Statistics construction approval series is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condominium and Apartments
Canada Condominiums and Apartments Market
Condominium and Apartments
ASEAN Condominiums and Apartments Market
Condominium and Apartments
Egypt Condominiums and Apartments Market
Condominium and Apartments
Condom Market
Condominium and Apartments
Global Condominiums and Apartments Market
Condominium and Apartments
Latin America Condominiums and Apartments Market
Condominium and Apartments
UAE Condominiums and Apartments Market
Condominium and Apartments
Spain Condominiums and Apartments Market
Condominium and Apartments
Saudi Arabia Condominiums and Apartments Market
Condominium and Apartments
Europe Condominiums and Apartments Market
Condominium and Apartments
Italy Condominiums and Apartments Market
Condominium and Apartments
Qatar Condominium and Apartment Market
Condominium and Apartments
Japan Condominiums and Apartments Market
Condominium and Apartments
India Condominium and Apartments Market
Condominium and Apartments
Germany Condominiums and Apartments Market