
 Italy Condominiums and Apartments Market | 2026-2036
Italy Condominiums and Apartments Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Condominiums and Apartments Market Foresight
Cross-laminated timber is consolidating its position in mid-rise residential construction across northern Italy. Salini Costruttori SPA leverages its engineering heritage to anchor large-scale condominium developments in Milan and Turin. Impresa Pizzarotti & C. SPA sustains competitive positioning through integrated project delivery that spans design, construction, and facility management.
Condominiums and apartments in Italy constitute multi-unit residential structures governed by codified ownership regimes, with construction typically employing reinforced concrete frames, masonry infill, or hybrid timber-steel systems to achieve seismic resistance under NTC 2018 standards. Luxury apartments command margin concentration in Rome and Florence where heritage restrictions limit new supply, while affordable condominiums absorb volume demand from first-time buyers priced out of premium tiers. Studio apartments represent the fastest-growing product type as remote-work professionals seek compact units in transit-connected districts.
Italy's NTC 2018 technical construction standards and the Superbonus 110% fiscal mechanism, administered through the Agenzia delle Entrate, are reshaping renovation demand and material specifications across the condominium stock. The EU Energy Performance of Buildings Directive, transposed through Italian legislative decree, mandates progressive efficiency upgrades that filter directly into apartment valuation and financing access. Stakeholders must weigh retrofit obligation timelines against the erosion of tax incentive generosity as policy priorities shift.
Market Dynamics
Italy's Superbonus 110% fiscal mechanism is compressing renovation timelines while forcing material specification shifts across the condominium stock. Developers now front-load energy retrofit investments to capture fading tax incentives before policy generosity erodes.
Growth Catalysts
- NTC 2018 Seismic Standards:Mandatory earthquake-resistant construction upgrades are triggering structural reinforcement demand across aging apartment buildings in high-risk zones.
- Milan-Turin Migration Corridor:Young professionals relocating to northern Italy's economic hubs are absorbing compact studio inventory at premium rents.
- Cross-Laminated Timber:Engineered wood systems are penetrating mid-rise residential construction as developers seek faster assembly cycles and carbon footprint reduction.
Market Restraints
- Heritage Zoning Restrictions:Florence and Rome's UNESCO-protected cores limit vertical expansion, capping new luxury supply and inflating land scarcity premiums.
- Reinforcement Steel Volatility:Input cost swings for rebar and structural concrete are compressing developer margins on mid-market condominium projects.
- Superbonus Administrative Complexity:Agenzia delle Entrate compliance documentation requirements are extending project approval cycles and deterring smaller contractors.
Strategic Opportunities
- Lombardy Secondary Cities:Bergamo and Brescia offer undeveloped transit-connected sites for affordable condominium clusters targeting first-time buyers priced out of Milan.
- EU Energy Performance of Buildings Directive:Progressive efficiency mandates are creating financing-linked valuation premiums for retrofitted apartment assets.
- Integrated Facility Management Bundles:Condominium associations are consolidating energy monitoring, maintenance, and insurance procurement under single-contractor arrangements.
Industry Challenges
- Certified Energy Auditor Scarcity:Superbonus eligibility requires accredited professionals, creating bottlenecks in project documentation and incentive claim processing.
- Legacy Building System Integration:Seismic retrofitting of 1960s-1970s reinforced concrete frames demands specialized engineering without standardized connection details.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Condominiums and Apartments Market |
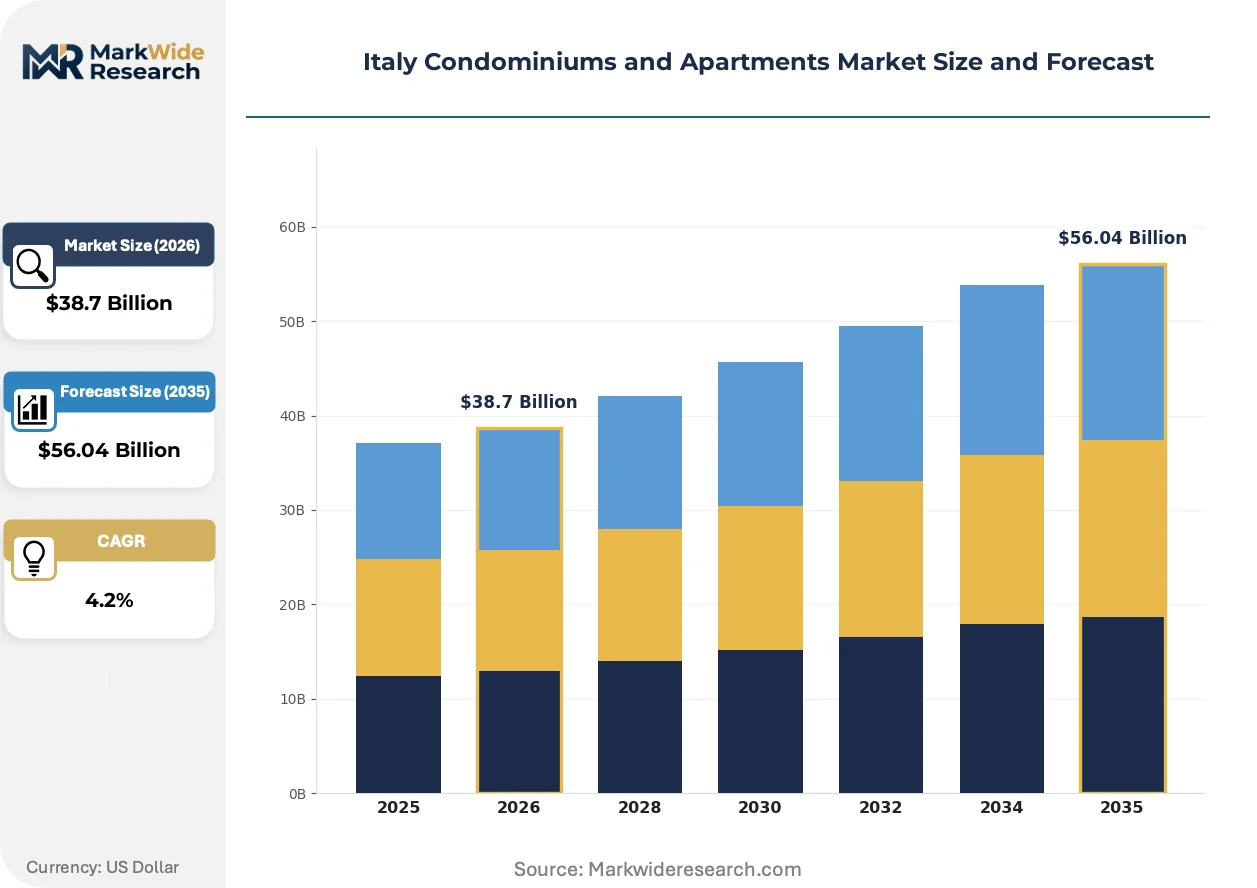
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $56.04 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luxury Apartments, Affordable Condominiums, Studio Apartments, Penthouse Suites Customer Type: First-time Buyers, Investors, Retirees, Families Price Tier: Economy, Mid-range, Premium, Ultra-Premium Distribution Channel: Real Estate Agents, Online Platforms, Direct Sales, Auctions |
| Companies Covered | Salini Costruttori SPA, Impresa Pizzarotti & C. SPA, Sicim SPA, C.M.B. Societa' Cooperativa Muratori E Braccianti Di Carpi, Rizzani De Eccher SPA, Borgosesia, DoveVivo, ALTIDO, Cushman & Wakefield, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Condominiums and Apartments Market Shifts & Advancements
Material substitution and regulatory compression are actively reshaping how Italian condominiums are financed, constructed, and retrofitted. Three interconnected developments are restructuring competitive positioning across the value chain.
Cross-laminated timber is consolidating its position in mid-rise residential construction across northern Italy. Developers in Milan and Turin are specifying engineered wood for 4-8 story condominium frames to reduce on-site labor hours and meet carbon disclosure requirements from institutional lenders. This material shift is compressing traditional concrete-masonry market share in the 50-120 unit project segment.
Italy's transposition of the EU Energy Performance of Buildings Directive through legislative decree is mandating progressive efficiency upgrades with binding timelines. The regulation is forcing condominium associations to front-load window replacement and HVAC system overhauls to avoid financing penalties and valuation discounts. Rome and Florence heritage buildings face the steepest compliance costs due to façade alteration restrictions.
Remote-work professionals are compressing their housing search criteria to transit-accessible micro-units under 45 square meters. This behavioral pivot is displacing traditional two-bedroom demand in Milan's Porta Nuova and Rome's EUR districts. Developers are responding with modular interior systems that enable flexible space reconfiguration within compact footprints.
Italy Condominiums and Apartments Market Segmentation
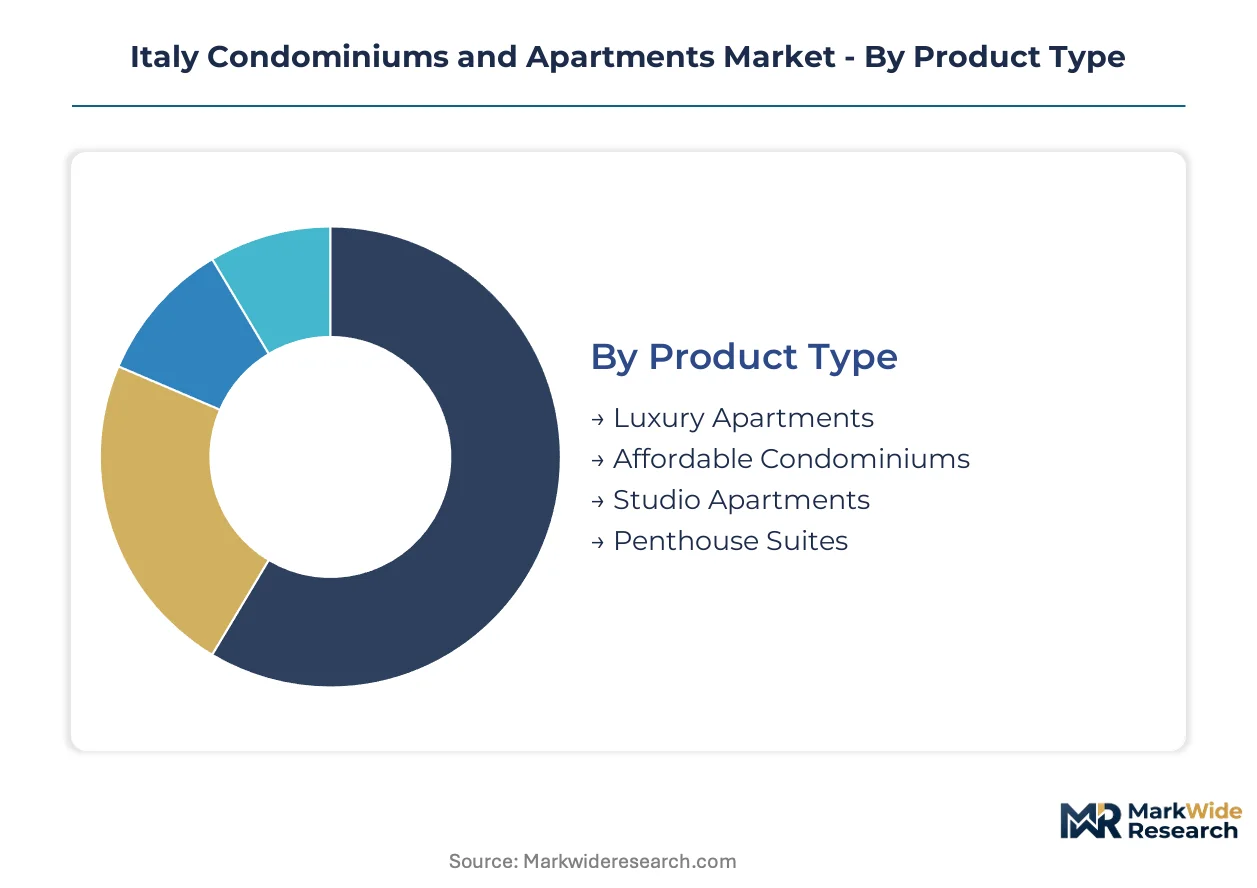
Segmentation in the Italy condominiums and apartments market exposes divergent demand drivers across buyer profiles and price tiers. Product type and customer composition dictate construction specifications, financing structures, and geographic concentration patterns.
Product Type:
Volume concentrates in compact units serving migration corridors, while premium tiers absorb scarcity premiums in supply-constrained historic cores.
- Luxury Apartments:Heritage-protected structures in Rome and Florence command valuation premiums due to UNESCO zoning restrictions that cap new supply. Demand clusters among international investors seeking trophy assets with concierge services and private terraces.
- Studio Apartments:Remote-work professionals migrating to Milan's Porta Nuova and Turin's Lingotto district are absorbing sub-45 square meter inventory at premium per-square-meter rates. This segment is expanding most quickly as developers optimize floorplates for single-occupant efficiency.
- Affordable Condominiums:First-time buyers priced out of Milan's core are driving absorption in Bergamo and Brescia transit corridors.
- Penthouse Suites:Ultra-high-net-worth purchasers concentrate demand in Lombardy's new-build towers with panoramic Alpine views.
Mature deployment sits with luxury apartments in heritage-constrained supply pools. Newer deployment is concentrated in studio apartments serving mobile professional cohorts.
Customer Type:
Purchaser motivation determines financing instrument selection and holding period expectations across the condominium stock.
- Investors:Institutional and private capital is concentrating in Lombardy's urban cores, with yield compression in Milan driving secondary city expansion. Rental demand from young professionals supports leveraged acquisition strategies with 5-7 year hold periods.
- First-time Buyers:Superbonus 110% eligibility is shaping purchase decisions toward renovation-ready units in seismic zones requiring structural upgrades. Agenzia delle Entrate compliance documentation extends transaction timelines for this capital-constrained segment.
- Retirees:Downsizing demand from northern Italy's aging population targets elevator-serviced mid-rise units with proximity to healthcare infrastructure.
- Families:Three-bedroom inventory in Turin's suburbs and Rome's EUR district absorbs demand from dual-income households prioritizing school district access.
Investor participation dominates transaction velocity in premium tiers. First-time buyer activity is accelerating most rapidly in affordable segments eligible for fiscal incentives.
Price Tier:
Construction cost inflation and land scarcity are compressing margins at the economy level while ultra-premium segments capture scarcity rents.
- Economy:Prefabricated envelope systems and standardized floorplates enable developers to hit affordability thresholds in Brescia and Verona peripheries. Reinforcement steel volatility compresses margins unless procurement is locked through captive supply arrangements.
- Mid-range:Cross-laminated timber specification is penetrating this tier in Milan's mid-rise developments, reducing on-site labor hours and meeting carbon disclosure requirements from institutional lenders.
- Premium:Buyers in this tier demand integrated facility management bundles covering energy monitoring, maintenance, and insurance procurement under single-contractor arrangements.
- Ultra-Premium:Custom interior architecture and smart home infrastructure differentiate penthouses in Porta Nuova towers from standardized luxury inventory.
Economy tier supply is concentrating in Lombardy secondary cities. Ultra-premium development is climbing the fastest as developers exploit vertical height allowances in Milan's business district.
Distribution Channel:
Channel selection reflects buyer sophistication, transaction complexity, and the administrative burden of Superbonus incentive claims.
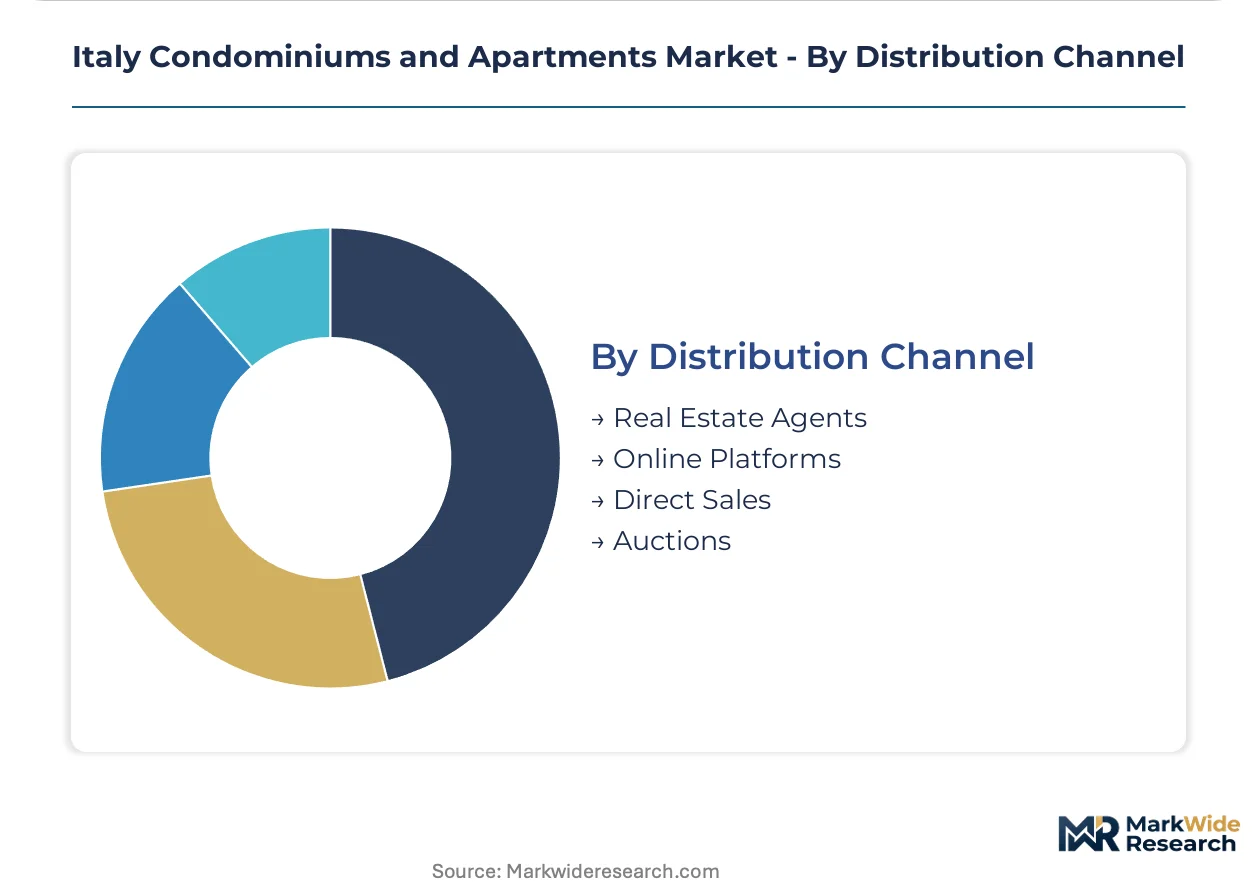
- Real Estate Agents:Traditional brokerage retains dominance in heritage-protected districts where off-market inventory and local zoning knowledge command fee premiums. Florence and Rome transactions rely on agent networks for navigating condominium association governance.
- Online Platforms:Digital listing aggregators are capturing first-time buyer search behavior for studio and one-bedroom inventory in Turin and Milan. Virtual tour functionality reduces physical viewing requirements for remote-work migrants.
- Direct Sales:Developer-led marketing bypasses intermediary fees in new-build condominium towers with standardized unit configurations.
- Auctions:Judicial sales of distressed condominium properties attract investor attention in seismic zones requiring substantial retrofit investment.
Agent-mediated transactions dominate complex heritage-zone deals. Online platform penetration is gaining share fastest among younger buyer cohorts seeking efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in northern Italy's economic corridor, with Lombardy and Piedmont absorbing migration flows from southern regions and abroad. Milan anchors transaction velocity for studio and compact units. Secondary cities in the north are capturing spillover demand as core urban premiums compress first-time buyer budgets.
Lombardy
Milan's Porta Nuova district absorbs premium studio inventory from remote-work professionals relocating from Rome and Naples. The Superbonus 110% mechanism, administered through Agenzia delle Entrate, accelerates retrofit permits across aging condominium stock in Brescia and Bergamo. Developer activity clusters along the Milan-Bergamo transit corridor where undeveloped sites enable affordable condominium clusters.
Piedmont
Turin's Lingotto district captures demand from young professionals priced out of Milan's core market. NTC 2018 seismic standards trigger structural reinforcement contracts across 1960s reinforced concrete buildings in the metropolitan area. Cross-laminated timber specification penetrates mid-rise residential construction in Turin's peripheral zones as developers seek faster assembly cycles.
Lazio
Rome's EUR district absorbs family-oriented three-bedroom demand from dual-income households prioritizing school access. Heritage zoning restrictions in the UNESCO-protected historic core cap vertical expansion and inflate land scarcity premiums. Judicial auctions of distressed condominium properties in seismic zones attract investor attention requiring substantial retrofit investment.
Tuscany
Florence's luxury apartment segment commands valuation premiums due to strict façade alteration restrictions limiting new supply. The EU Energy Performance of Buildings Directive, transposed through Italian legislative decree, mandates progressive efficiency upgrades with binding timelines. Developer activity concentrates in Prato and Pistoia peripheries where transit connectivity supports commuter-serving condominium development.
Veneto
Verona's mid-market affordable tier deploys prefabricated envelope systems to hit first-time buyer affordability thresholds. Reinforcement steel volatility compresses developer margins unless procurement locks through captive supply arrangements. Investor appetite is concentrating in Padua and Vicenza where secondary city premiums remain below Milan thresholds.
Italy Condominiums and Apartments Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with engineering heritage firms dominating large-scale developments and integrated service providers capturing facility management bundling opportunities. The vendor base organizes around three archetypes: heritage engineering contractors with multi-decade track records, integrated project delivery firms spanning design through asset management, and emerging flexible-housing operators disrupting traditional lease structures. Competitive moves center on M&A to secure land pipelines and strategic partnerships to front-load Superbonus eligibility documentation.
Within the heritage engineering tier, Salini Costruttori SPA and Impresa Pizzarotti & C. SPA exemplify scale-driven positioning anchored to northern Italy's metropolitan cores. Among specialized cooperatives, C.M.B. Societa' Cooperativa Muratori E Braccianti Di Carpi represents the employee-owned construction model concentrated in Emilia-Romagna's industrial zones. These entities occupy positions that reflect divergent capital structures rather than uniform strategic postures.
| Leading Market Players |
|---|
| Salini Costruttori SPA |
| Impresa Pizzarotti & C. SPA |
| Sicim SPA |
| C.M.B. Societa' Cooperativa Muratori E Braccianti Di Carpi |
| Rizzani De Eccher SPA |
| Borgosesia |
| DoveVivo |
| ALTIDO |
| Cushman & Wakefield |
| Others |
Supply & Pricing Matrix
Reinforcement steel volatility transmits directly from Turkish and Chinese mill pricing into mid-market condominium margins, compressing developer returns on standardized projects while amplifying cost pass-through capacity in heritage-constrained luxury tiers where land scarcity insulates pricing power.
Pricing Analysis
Volume concentrates in economy-tier prefabricated envelope systems where procurement locks through captive supply arrangements defend thinning margins, while ultra-premium penthouses in Milan's Porta Nuova capture scarcity rents from Alpine-view positioning. Three-tier pricing structure across premium, standard, and economy levels differentiates by seismic certification grade and integrated facility management bundling. Pricing pressure stems from Agenzia delle Entrate documentation complexity extending approval cycles. First-time buyers in Bergamo and Brescia corridors exhibit highest price sensitivity, while international trophy-asset investors in Rome's UNESCO core demonstrate lowest elasticity.
Supply Chain Analysis
Cross-laminated timber supply rests on Austrian and German engineered-wood producers, with Italian domestic capacity scaling through Veneto and Friuli-Venezia Giulia mills. Reinforcement steel draws from Turkish rolling mills and Chinese state-owned producers, while HVAC and window systems source from German and Polish manufacturing clusters. Single-source vulnerability concentrates in certified energy auditor talent pools bottlenecking Superbonus eligibility documentation. Distribution runs through Salini Costruttori SPA and Impresa Pizzarotti & C. SPA integrated project delivery networks, with regional cooperatives capturing Emilia-Romagna industrial zone contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's condominium market is becoming a vertical-integration race as developers pursue backward control over cross-laminated timber supply to secure carbon-disclosure compliance and compress assembly cycles.
For Market Incumbents: Hedge against reinforcement steel volatility through captive procurement arrangements with Turkish mills and Emilia-Romagna rolling stock. Secure certified energy auditor pipelines through training partnerships with technical universities to unblock Superbonus documentation bottlenecks. Defend margin position in mid-market tiers by specifying standardized floorplates that reduce on-site labor hours. For New Entrants and Emerging Players: Online platform aggregation of studio inventory in Turin's Lingotto district offers the most penetrable entry vector for remote-work professional cohorts. Target judicial auction channels for distressed seismic-zone properties requiring retrofit investment, leveraging Agenzia delle Entrate compliance expertise as differentiated service bundling. White-space sits in integrated facility management contracts for aging condominium associations in Milan's peripheral zones. For Investors and Strategic Acquirers: Superbonus 110% incentive erosion is the leading indicator that retrofit-dependent valuation premiums will compress, shifting returns toward new-build assets with embedded efficiency compliance. Long-term viability favors Lombardy secondary city land pipelines with transit connectivity to Milan. Acquisition target archetype: mid-cap developers with captive cross-laminated timber supply and documented Agenzia delle Entrate approval track records. Signal to monitor: certified energy auditor wage inflation as proxy for documentation bottleneck severity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Engineered Timber | Austrian and German CLT supply contracts secure carbon-disclosure compliance for institutional lenders. |
| Certified Energy Auditor Training Pipeline | Technical university partnerships unblock Agenzia delle Entrate documentation bottlenecks accelerating permit cycles. |
| Secondary City Land Pipeline Development | Bergamo and Brescia transit-connected sites capture Milan spillover demand from priced-out first-time buyers. |
| Integrated Facility Management Bundling | Single-contractor arrangements for energy monitoring and maintenance capture recurring revenue from condominium associations. |
| Judicial Auction Channel Specialization | Distressed seismic-zone property acquisition leverages retrofit expertise for Superbonus-eligible value creation. |
Research Methodology
Independent corroboration across Agenzia delle Entrate permit databases, Lombardy regional construction registries, and EU Energy Performance of Buildings Directive transposition documents underwrites the qualitative findings. Primary interviews with condominium developers, certified energy auditors, facility management contractors, and Agenzia delle Entrate compliance officers combined with secondary validation from NTC 2018 technical standards filings and Superbonus administrative records. Bottom-up project pipeline enumeration and top-down regional absorption rate triangulation anchored volume estimates.
Comparable-period anchoring to pre-Superbonus renovation permit baselines established the forecast reference frame. Segmentation modeling spanned product type, customer archetype, price tier, and distribution channel dimensions across the projection horizon. CAGRs derived from unit absorption trajectories in Milan, Turin, Rome, and Florence metropolitan zones, with cross-laminated timber penetration rates and certified energy auditor supply constraints as industry-specific forecast inputs.
Inputs from Agenzia delle Entrate administrative databases and Lombardy regional planning offices were available through the study window; gaps in real-time Superbonus claim processing data introduce uncertainty bands around retrofit-driven valuation estimates. Forecasts reflect documented assumptions regarding incentive generosity erosion and NTC 2018 enforcement intensity. Regulatory priority shifts, reinforcement steel price spikes, and certified energy auditor supply shocks warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condominium and Apartments
Latin America Condominiums and Apartments Market
Condominium and Apartments
Japan Condominiums and Apartments Market
Condominium and Apartments
Egypt Condominiums and Apartments Market
Condominium and Apartments
Qatar Condominium and Apartment Market
Condominium and Apartments
Germany Condominiums and Apartments Market
Condominium and Apartments
Spain Condominiums and Apartments Market
Condominium and Apartments
Saudi Arabia Condominiums and Apartments Market
Condominium and Apartments
Condom Market
Condominium and Apartments
UAE Condominiums and Apartments Market
Condominium and Apartments
Global Condominiums and Apartments Market
Condominium and Apartments
Asia-Pacific Condominiums and Apartments Market
Condominium and Apartments
Canada Condominiums and Apartments Market
Condominium and Apartments
Europe Condominiums and Apartments Market
Condominium and Apartments
India Condominium and Apartments Market
Condominium and Apartments
ASEAN Condominiums and Apartments Market