
 Latin America Condominiums and Apartments Market | 2026-2036
Latin America Condominiums and Apartments Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Condominiums and Apartments Market Foresight
Brokerage networks across Latin America is fragmenting as digital platforms and direct-to-developer channels erode traditional commission structures. Mrv Engenharia e Participacoes SA anchors its position through standardized construction modules that compress delivery timelines in Brazilian metros. Greystar Real Estate Partners extends its operational footprint by applying institutional property management protocols to mid-market rental stock in Mexico City and Santiago. Tishman Speyer competes through trophy asset concentration in São Paulo's Faria Lima corridor.
Latin American condominiums and apartments comprise multi-unit residential structures governed by horizontal property regimes, typically constructed with reinforced concrete frames, ceramic block infill, and flat slab systems designed for seismic resilience per local NBCC or NTC codes. Their commercial purpose centers on monetizing urban land scarcity through vertical density, generating recurring fee income for administrators while transferring maintenance liability to owner associations. Luxury and mid-range product types capture the dominant margin pools, as first-time buyer segments absorb the fastest-growing transaction volume across online platforms and direct sales channels. Studio configurations within value-for-money price tiers exhibit accelerating absorption rates in university-adjacent submarkets from Guadalajara to Curitiba.
Brazil's ABNT NBR standards, Mexico's PROFECO disclosure requirements for off-plan sales, and Colombia's Ley 675 of 2001 on horizontal property administration collectively elevate compliance costs while screening out informal developers. These frameworks shape demand by mandating reserve fund allocations and construction defect warranties that favor established builders with balance sheet depth. Stakeholders must monitor how municipal climate action plans in Buenos Aires and Santiago rewrite permissible density bonuses and energy performance thresholds for new approvals.
Market Dynamics
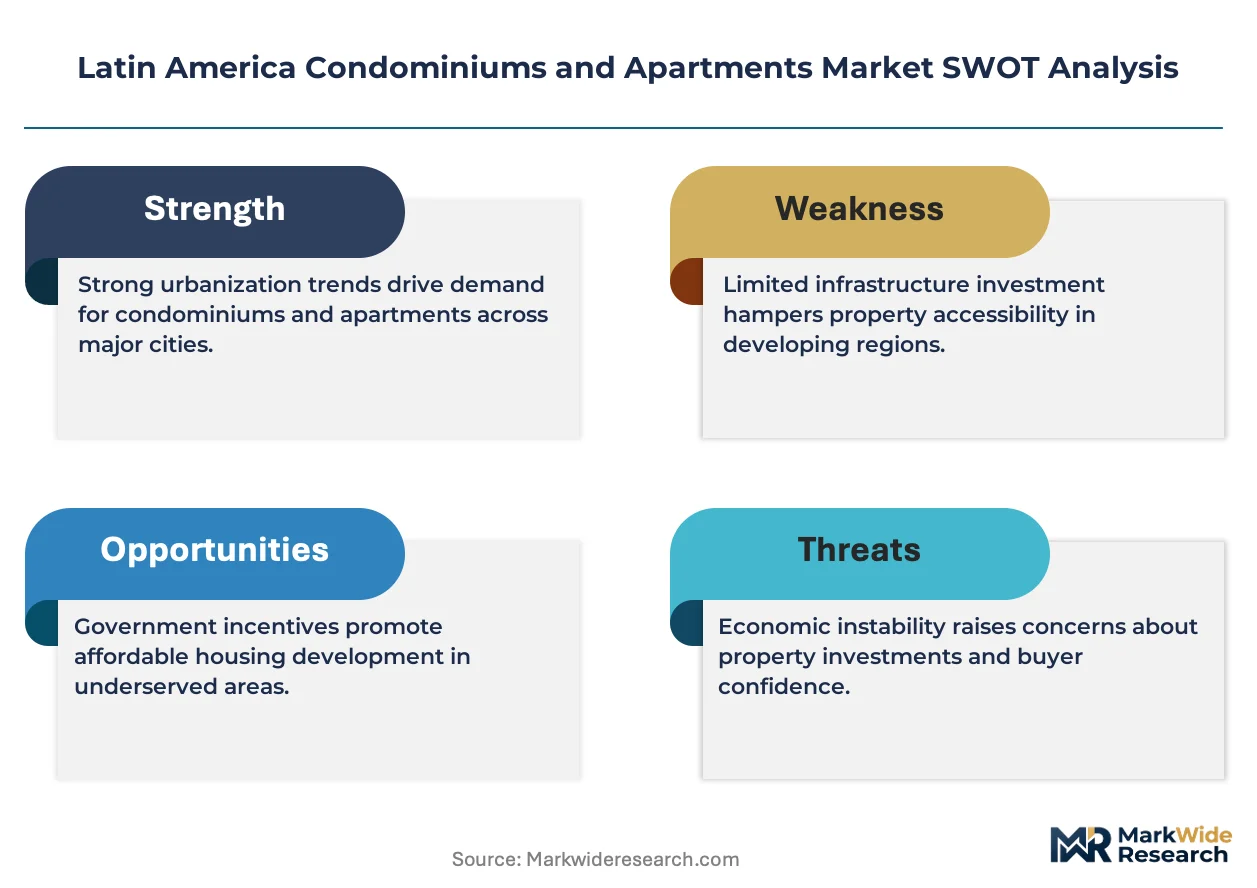
Horizontal property regimes across Latin America are recalibrating around seismic retrofit mandates and municipal climate action plans that rewrite density bonuses, forcing developers to absorb compliance costs or redesign unit mixes entirely.
Growth Catalysts
- Minha Casa Minha Vida:Brazil's federal housing program channels subsidized credit to first-time buyers, expanding the addressable base for studio and compact two-bedroom inventory in peripheral São Paulo districts.
- Digital direct-to-developer platforms:Online sales channels eliminate brokerage layers, compressing customer acquisition costs and accelerating absorption timelines for mid-range product in Mexico City.
- Reinforced concrete flat-slab systems:Standardized seismic-resistant construction modules reduce per-unit delivery timelines, enabling faster capital rotation for builders operating under Colombia's Ley 675 reserve fund requirements.
Market Restraints
- Portland cement price volatility:Input cost swings in reinforced concrete frames compress developer margins, particularly for value-tier projects in Brazilian interior markets lacking supply chain alternatives.
- Horizontal property administrator concentration:Professionalized association management remains scarce outside São Paulo, Mexico City, and Santiago, leaving owner associations in secondary cities exposed to maintenance liability gaps.
- PROFECO disclosure friction:Mexico's off-plan sales transparency requirements extend pre-construction marketing timelines, screening out speculative capital and favoring balance-sheet-heavy incumbents.
Strategic Opportunities
- Colombia's secondary metros:Medellín and Barranquilla exhibit underpenetrated institutional rental stock, creating white space for property management protocols adapted from Mexico City operations.
- Energy performance mandates:Buenos Aires municipal climate action plans introduce density bonuses tied to green building certification, rewarding developers who integrate solar thermal systems into new approvals.
- PropTech-embedded sales channels:Virtual staging and digital mortgage pre-qualification converge to compress the purchase funnel, capturing remote buyer segments in Riviera Maya and coastal Brazil.
Industry Challenges
- Certified property administrator scarcity:Ley 675 compliance requires specialized reserve fund management expertise that outstrips training pipeline capacity in Colombian secondary markets.
- Legacy condominium governance fragmentation:Pre-2001 horizontal property regimes in Brazil lack standardized maintenance protocols, complicating retrofit financing and insurance placement for aging stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Condominiums and Apartments Market |
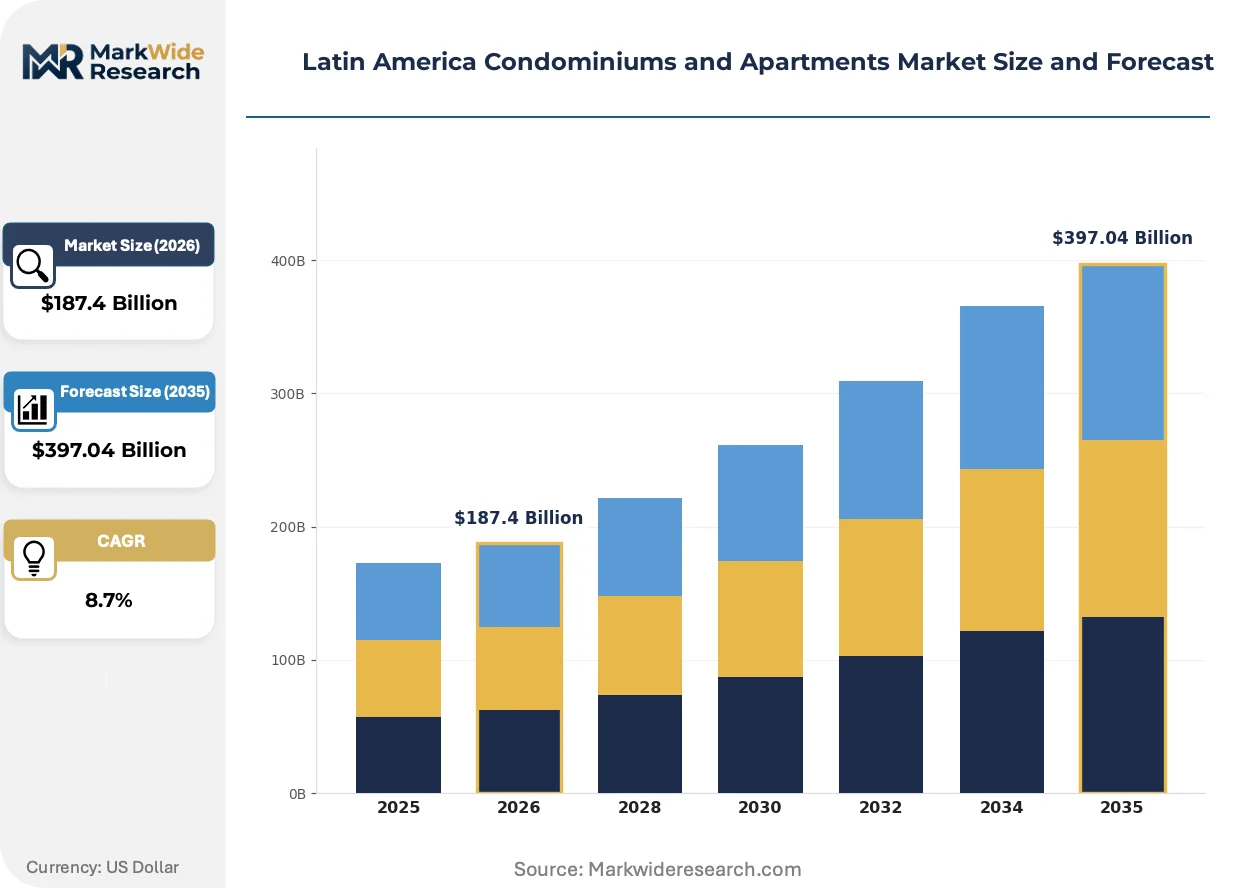
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luxury, Affordable, Mid-Range, Studio End User: First-Time Buyers, Investors, Renters, Families Distribution Channel: Online Platforms, Real Estate Agencies, Direct Sales, Auctions Price Tier: High-End, Budget, Value-For-Money, Others |
| Companies Covered | Tishman Speyer, Hines Group, Greystar Real Estate Partners, CBRE, JLL, Mrv Engenharia e Participacoes SA, Homex, Consorcio ARA, Desarrollos Inmobiliarios Sadasi SA de CV, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Condominiums and Apartments Market Shifts & Advancements
Construction methodologies and transaction channels across Latin American residential verticals are converging around standardization, digitization, and climate-responsive design that compress delivery timelines while elevating compliance thresholds.
Building Information Modeling (BIM) platforms coordinate reinforced concrete frame detailing with seismic load calculations per local NTC codes. Mid-tier developers in Guadalajara and Curitiba deploy these tools to compress design-review cycles. The technology is digitizing handoffs between structural engineers and site supervisors, reducing rework rates on flat-slab implementations.
Colombia's adaptation of Ley 675 reserve fund mandates now requires digitized financial reporting to municipal property registries. This regulatory layer elevates transparency for prospective unit buyers. Developers with captive property management capabilities capture margin pools that informal competitors forfeit to compliance friction.
Young professional buyers in São Paulo and Mexico City increasingly transact through developer-direct digital channels that disintermediate traditional brokerage networks. These segments prioritize virtual unit tours and embedded mortgage pre-approval over physical showroom visits. The shift compresses sales cycles for studio configurations in university-adjacent submarkets.
Latin America Condominiums and Apartments Market Segmentation
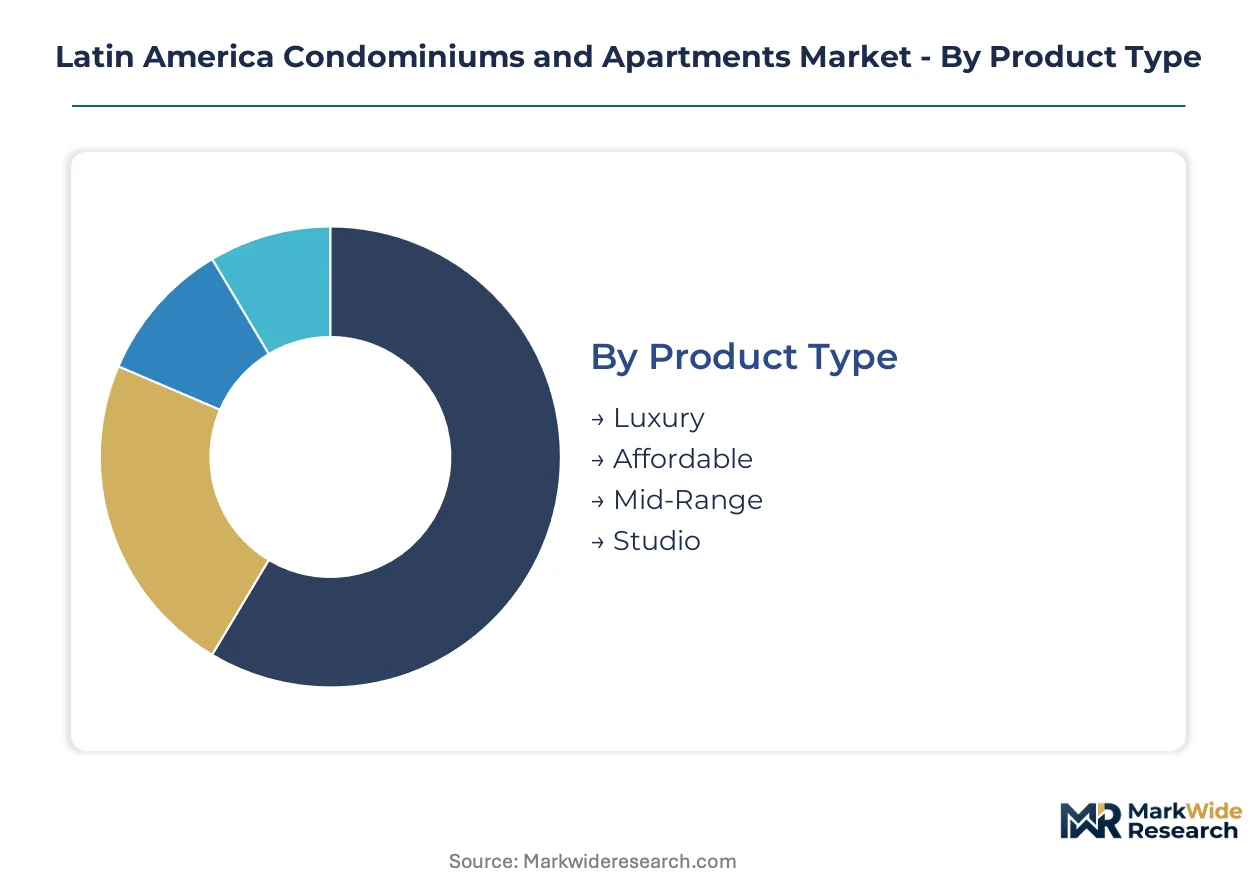
Segmentation across Latin American condominiums and apartments reveals how horizontal property regimes fragment along income stratification, transaction channel preferences, and regulatory exposure. Developers calibrate unit mixes against these axes to optimize absorption rates and compliance positioning.
Product Type:
Developers deploy reinforced concrete flat-slab systems across a use-case spectrum spanning trophy assets to compact starter units.
- Luxury:Reinforced concrete frames with ceramic block infill support amenity-intensive configurations in São Paulo's Faria Lima corridor and Mexico City's Polanco district. Brazilian ABNT NBR seismic standards and Colombian NTC codes elevate structural engineering costs, compressing margins for speculative entrants while rewarding balance-sheet-heavy incumbents with captive project management capabilities.
- Mid-Range:Standardized construction modules compress delivery timelines for two-bedroom and compact three-bedroom inventory targeting young professionals in Guadalajara, Curitiba, and Santiago's Ñuñoa commune. Digital direct-to-developer platforms accelerate absorption for this tier by eliminating brokerage layers.
- Affordable:Brazil's Minha Casa Minha Vida program channels subsidized credit toward peripheral São Paulo districts and interior municipalities.
- Studio:University-adjacent submarkets from Monterrey to Florianópolis exhibit accelerating absorption for sub-45-square-meter configurations.
Established volume favors mid-range inventory; emerging adoption favors studio configurations.
End User:
Customer archetypes stratify by financing access, holding period horizons, and exposure to horizontal property administrator scarcity.
- First-Time Buyers:Federal housing programs in Brazil and Mexico's INFONAVIT payroll-deduction mortgages expand addressable demand for value-tier product. These buyers concentrate in peripheral districts where municipal infrastructure lags, elevating resale risk and insurance placement complexity.
- Investors:Institutional and individual capital targets rental yield in Mexico City, Santiago, and Medellín where professionalized property management remains underpenetrated. Colombia's Ley 675 reserve fund mandates and Brazil's pre-2001 governance fragmentation create due diligence friction that screens out undercapitalized entrants.
- Renters:Mid-market rental stock in Buenos Aires and Barranquilla absorbs mobile professional segments prioritizing flexibility over equity accumulation.
- Families:Three-bedroom configurations in gated horizontal properties dominate demand in Colombian secondary metros and Brazilian southeastern coastal states.
First-time buyers anchor transaction volume; investors command the steepest expansion trajectory as institutional rental protocols migrate from Mexico City to Andean markets.
Distribution Channel:
Transaction infrastructure fragments between legacy brokerage networks and digitized direct channels that compress customer acquisition economics.
- Online Platforms:Virtual staging, drone-captured neighborhood flythroughs, and embedded mortgage pre-qualification converge to capture remote buyer segments in Riviera Maya and coastal Brazil. These platforms disintermediate traditional commission structures, forcing established agencies to defend position through exclusive developer relationships.
- Direct Sales:Developer-operated showrooms and digital-native sales funnels accelerate absorption timelines for mid-range product in Mexico City and São Paulo. PROFECO disclosure requirements for off-plan sales extend marketing timelines, favoring incumbents with balance sheet depth to carry pre-construction carrying costs.
- Real Estate Agencies:Fragmented brokerage networks persist in secondary Brazilian and Colombian markets where trust intermediation remains valued.
- Auctions:Distressed inventory and foreclosure pipelines concentrate in Argentine and Brazilian judicial sale channels.
Direct sales capture margin expansion; online platforms gain share fastest as PropTech-embedded channels penetrate younger demographic cohorts.
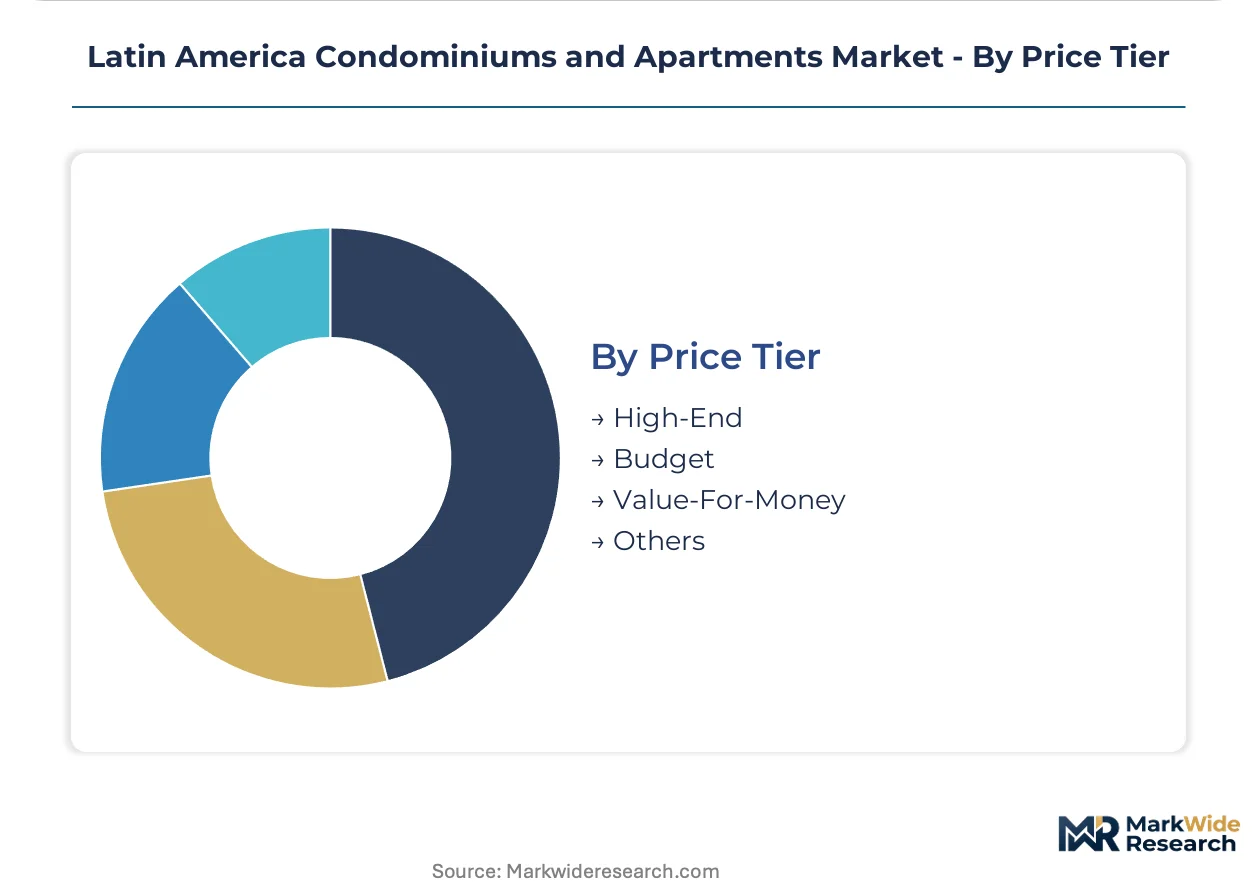
Price Tier:
Pricing stratification reflects construction input cost exposure, amenity bundling, and regulatory compliance burden differentials.
- Value-For-Money:Ceramic block infill and standardized flat-slab systems minimize per-unit delivery costs for studio and compact two-bedroom inventory. Portland cement price volatility compresses margins for this tier in Brazilian interior markets lacking supply chain alternatives.
- High-End:Seismic-resistant engineering, green building certification premiums, and density bonus capture in Buenos Aires climate action plans elevate development costs. These projects concentrate in São Paulo's Faria Lima corridor and Mexico City's Santa Fe district where trophy asset scarcity supports pricing power.
- Budget:Peripheral locations and reduced amenity loads target first-time buyer segments in Minha Casa Minha Vida program zones.
- Others:Niche configurations including co-living conversions and serviced apartment hybrids occupy experimental positioning.
Value-for-money configurations dominate unit absorption; high-end inventory concentrates margin capture in regulatory-constrained submarkets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Santos Port Complex anchors Brazil's southeastern corridor as the primary gateway for cement, steel rebar, and ceramic block imports that feed São Paulo's vertical construction pipeline.
Brazil
Minha Casa Minha Vida subsidized credit programs drive first-time buyer absorption in peripheral São Paulo districts like Itaquera and Guaianases. ABNT NBR seismic standards mandate reinforced concrete flat-slab engineering that elevates construction costs for speculative entrants. The Faria Lima financial corridor concentrates trophy asset development where Tishman Speyer and Hines Group compete for institutional capital allocation.
Mexico
INFONAVIT payroll-deduction mortgages expand addressable demand for compact two-bedroom inventory in Mexico City's Iztapalapa and Gustavo A. Madero boroughs. PROFECO disclosure requirements for off-plan sales extend pre-construction marketing timelines, screening out undercapitalized developers. Riviera Maya coastal submarkets from Playa del Carmen to Tulum absorb remote buyer capital through PropTech-embedded digital channels.
Colombia
Ley 675 of 2001 reserve fund mandates professionalize horizontal property administration, creating compliance friction that favors established builders with captive management capabilities. Medellín's El Poblado and Laureles communes exhibit underpenetrated institutional rental stock relative to Santiago or Mexico City. Barranquilla's Caribbean coastal position attracts value-tier development targeting mobile professional segments.
Chile
Santiago's Ñuñoa and Providencia communes anchor mid-market rental demand from young professionals prioritizing transit accessibility over equity accumulation. Municipal climate action plans in the Santiago Metropolitan Region rewrite density bonuses tied to energy performance thresholds. The Mapocho River corridor concentrates new approvals where green building certification captures regulatory premiums.
Argentina
Buenos Aires municipal climate action plans introduce density bonuses for solar thermal integration that reward developers with technical capabilities absent from informal competitors. Judicial foreclosure pipelines concentrate distressed inventory in auction channels across the Capital Federal and Greater Buenos Aires. The Puerto Madero waterfront redevelopment zone exemplifies trophy asset scarcity pricing in dollarized transaction environments.
Latin America Condominiums and Apartments Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on construction methodology and regulatory compliance. The market fragments across three structural tiers: institutional developers with balance-sheet depth to carry pre-construction carrying costs, mid-tier builders deploying standardized construction modules for velocity, and fragmented local operators lacking captive property management capabilities. Strategic positioning converges on geographic cluster concentration in São Paulo and Mexico City, plus regulatory arbitrage through green building certification capture.
Within the institutional developer tier, Tishman Speyer and Hines Group occupy positions exemplifying trophy asset concentration in premium submarkets. Mrv Engenharia e Participacoes SA anchors the standardized construction module segment, representing the mid-tier velocity archetype through its São Paulo metropolitan focus. Greystar Real Estate Partners sits within the institutional property management vector, applying operational protocols developed in US markets to Latin American rental stock.
| Leading Market Players |
|---|
| Tishman Speyer |
| Hines Group |
| Greystar Real Estate Partners |
| CBRE |
| JLL |
| Mrv Engenharia e Participacoes SA |
| Homex |
| Consorcio ARA |
| Desarrollos Inmobiliarios Sadasi SA de CV |
| Others |
Supply & Pricing Matrix
China's Portland cement production concentration feeds directly into reinforced concrete frame costs across São Paulo and Mexico City developments, concentrating margin capture with builders who locked in long-term supply contracts before input volatility accelerated. This upstream leverage forces mid-tier developers toward standardized flat-slab modules that compress per-unit delivery timelines and preserve working capital.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates Latin American condominium transactions. Premium tiers command structural engineering premiums for ABNT NBR seismic compliance and green building certification capture in Buenos Aires climate action zones. Value-for-money configurations face intensifying cost compression from ceramic block and rebar price swings, elevating price sensitivity among first-time buyers in Brazil's Minha Casa Minha Vida program zones. High-end trophy assets in Faria Lima and Polanco exhibit lowest price elasticity due to dollarized transaction environments and scarcity positioning.
Supply Chain Analysis
Extended payment terms from Brazilian steel rebar distributors and Chinese cement exporters now stretch to 90-120 days, straining working capital for speculative developers lacking balance sheet depth. Brazil, China, and Mexico anchor raw material flows for reinforced concrete frames, ceramic block infill, and flat-slab formwork systems. Single-source vulnerability concentrates in the Santos Port Complex customs clearance chokepoints. Distribution runs through developer-direct procurement channels for institutional tiers and fragmented local suppliers for value-tier projects in secondary Colombian and Brazilian interior markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin American residential verticals face structural disruption from PropTech-embedded sales channels and municipal climate action plans that rewrite density bonus economics. Ley 675 reserve fund digitization mandates in Colombia exemplify the regulatory inflection compressing informal operator margins.
For Market Incumbents: Build captive property management moats that capture compliance-driven margin pools from Ley 675 administration requirements and PROFECO disclosure friction. Consolidate reserve fund management capabilities in Medellín and Barranquilla before certified administrator training pipelines mature. Channel control through exclusive developer-direct digital platforms defends against brokerage disintermediation threatening commission structures in Mexico City and São Paulo.
For New Entrants and Emerging Players: Establish a beachhead in Colombia's secondary metro institutional rental stock where professionalized property management remains underpenetrated relative to Santiago or Mexico City. Target studio configurations in university-adjacent submarkets from Guadalajara to Curitiba where virtual staging and embedded mortgage pre-qualification compress customer acquisition economics. Deploy PropTech-native sales funnels to bypass legacy brokerage fragmentation in Brazilian interior markets.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier builders with standardized construction module capabilities and captive project management operations that navigate ABNT NBR compliance costs. Long-term viability hinges on exposure to climate-responsive density bonus capture in Buenos Aires and Santiago municipal planning frameworks. Monitor solar thermal integration mandates as the inflection signal for technical capability gaps that screen out informal competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| Standardized Construction Module Deployment | Mrv Engenharia's flat-slab systems compress São Paulo delivery timelines against ABNT NBR seismic mandates. |
| Captive Property Management Capability Buildout | Greystar's institutional protocols capture Ley 675 reserve fund administration margin pools in Colombian markets. |
| PropTech-Embedded Direct Sales Channel | Virtual staging and drone flythroughs disintermediate traditional brokerage networks in Riviera Maya coastal submarkets. |
| Green Building Certification Investment | Buenos Aires density bonuses for solar thermal integration reward technical capabilities absent from informal developers. |
| Secondary Metro Geographic Expansion | Medellín and Barranquilla institutional rental stock offers white space for Mexico City-derived operational protocols. |
Research Methodology
Initial hypotheses were tested against primary input from condominium developers, horizontal property administrators, municipal planning officials, and construction material procurement leads and refined through secondary validation. Developer executives in São Paulo and Mexico City provided absorption timeline data; regulatory affairs specialists clarified Ley 675 and PROFECO compliance cost structures. Secondary sources included municipal climate action plan filings, ABNT NBR technical standards documentation, INFONAVIT mortgage disbursement records, and customs data from the Santos Port Complex. Bottom-up unit absorption modeling and top-down construction value-add estimates were triangulated against macroeconomic indicators.
Demand-supply balance framing anchored the analytical framework across the analysis window. Segmentation dimensions modeled included product type tier, end-user financing access, distribution channel digitization intensity, and municipal regulatory cluster. CAGRs were derived from unit absorption trajectory analysis and construction value-per-square-meter escalation patterns. Forecast inputs incorporated Portland cement price volatility scenarios and seismic code amendment implementation timelines.
Stress conditions across cement input costs, interest rate environments, and municipal zoning amendment velocities were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding infrastructure completion schedules and federal housing program continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condominium and Apartments
Canada Condominiums and Apartments Market
Condominium and Apartments
Italy Condominiums and Apartments Market
Condominium and Apartments
Asia-Pacific Condominiums and Apartments Market
Condominium and Apartments
Japan Condominiums and Apartments Market
Condominium and Apartments
Saudi Arabia Condominiums and Apartments Market
Condominium and Apartments
Spain Condominiums and Apartments Market
Condominium and Apartments
Europe Condominiums and Apartments Market
Condominium and Apartments
Condom Market
Condominium and Apartments
India Condominium and Apartments Market
Condominium and Apartments
Qatar Condominium and Apartment Market
Condominium and Apartments
UAE Condominiums and Apartments Market
Condominium and Apartments
Global Condominiums and Apartments Market
Condominium and Apartments
Egypt Condominiums and Apartments Market
Condominium and Apartments
ASEAN Condominiums and Apartments Market
Condominium and Apartments
Germany Condominiums and Apartments Market