
 Global Condominiums and Apartments Market | 2026-2036
Global Condominiums and Apartments Market Size, Share, and Industry Trends Forecast 2026-2036
Global Condominiums and Apartments Market Foresight
Buyer concentration among institutional investors and cross-border wealth pools is recalibrating how developers structure condominium offerings and pricing tiers. Lennar Corporation leverages its national land-positioning strategy to capture first-time buyer flows across Sun Belt metros. Emaar Properties dominates waterfront and master-planned segments in Dubai through integrated design-build-operate capabilities. Greystar Real Estate Partners anchors its competitive stance via scale in build-to-rent multifamily, blending institutional capital with operational density.
Condominiums and apartments constitute vertically stacked residential dwellings featuring individual unit ownership or leasehold tenure, typically constructed with reinforced concrete or steel framing systems and governed by homeowners associations or management entities for common-area maintenance. High-rise developments concentrate in dense urban cores where land scarcity elevates per-unit premiums, while garden homes and low-rise configurations capture family-oriented demand in suburban infill zones. Freehold condominiums attract equity-building purchasers, whereas cooperative structures persist in legacy Northeast US markets where board approval mechanisms filter buyer pools.
EMA's building-product standards, the EU Green Deal's embodied-carbon thresholds, and local fire-safety codes enforced by municipal authorities in Shanghai and Dubai shape permissible materials, facade specifications, and energy-performance benchmarks. China's GB standards and the UAE's building codes impose seismic and cladding requirements that filter developer eligibility and construction-cost profiles. Stakeholders must track how evolving disclosure mandates around operational carbon and climate-risk exposure reshape financing terms and institutional capital allocation into multifamily assets.
Market Dynamics
Institutional capital allocation into multifamily assets is compressing development timelines and reshaping ownership structures, as pension funds and sovereign wealth vehicles prioritize yield stability over speculative appreciation in coastal metropolitan corridors.
Growth Catalysts
- Transit-oriented development mandates:Municipal zoning reforms in Vancouver, Singapore, and Stockholm are densifying station-adjacent parcels, accelerating multifamily absorption rates near mass-transit nodes.
- EU Green Deal embodied-carbon thresholds:The framework's tightening limits on construction-phase emissions are redirecting developer procurement toward low-carbon concrete and cross-laminated timber systems.
- Cross-border wealth migration:Capital flight from currency-volatile economies is concentrating foreign-buyer demand in Dubai, Miami, and Sydney luxury condominium towers.
Market Restraints
- Construction labor scarcity:Skilled trades shortages in Germany, Australia, and the US Sun Belt are extending project delivery schedules and inflating hard-cost contingencies.
- Cladding material liability exposure:Post-Grenfell fire-safety retrofits and insurance exclusions for combustible facade systems are trapping legacy assets in capital-access constraints across the UK and UAE.
- Interest rate sensitivity:Floating-rate construction debt exposure leaves mid-market developers vulnerable to central bank tightening cycles in Canada and New Zealand.
Strategic Opportunities
- Build-to-rent institutionalization:The UK's permitted development rights and Australia's build-to-rent tax concessions are unlocking single-family rental conversion pipelines for superannuation and pension capital.
- Modular prefabrication convergence:Factory-built volumetric units combined with digital twin commissioning are compressing on-site labor hours and quality variance in Scandinavian and Japanese markets.
- CSRD-aligned green financing:The EU's Corporate Sustainability Reporting Directive is creating labeled bond issuance advantages for developers with verified operational carbon disclosure.
Industry Challenges
- Façade engineer talent pipeline collapse:Specialized enclosure design expertise is concentrating among a shrinking cohort of consultancies, extending design-phase durations for complex high-rise envelopes.
- Homeowners association governance fragmentation:Collective decision-making paralysis in aging US and Canadian condominium corporations is deferring critical maintenance and eroding asset values.
- Seismic code retrofit compliance:Japan's updated earthquake resistance standards and California's mandatory soft-story programs are imposing capital calls that strain owner-occupier liquidity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Condominiums and Apartments Market |
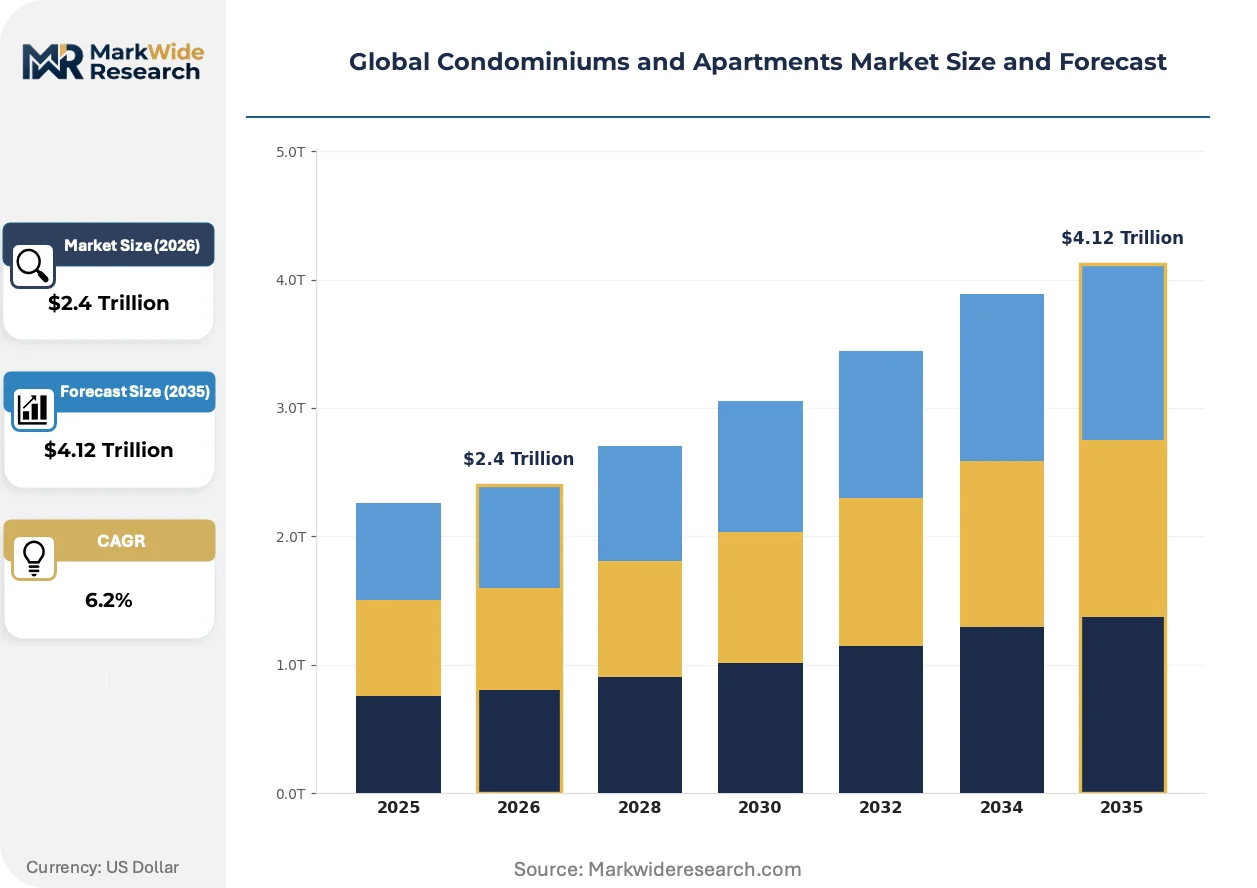
| Market Size in 2026 | $2.4 Trillion |
| Market Size in 2035 | $4.12 Trillion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: High-Rise, Mid-Rise, Low-Rise, Garden Homes, Duplexes Ownership Structure: Freehold, Leasehold, Cooperative, Community Land Trust End User: First-Time Buyers, Real Estate Investors, Vacation Renters, Retirees Distribution Channel: Real Estate Agents, Online Marketplaces, Property Management Firms, Direct Developers |
| Companies Covered | China Vanke Co., Ltd., Emaar Properties, Lennar Corporation, Brookfield Asset Management, Greystar Real Estate Partners, Lendlease Group, CapitaLand Limited, Mitsui Fudosan Co., Ltd., Equity Residential, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Condominiums and Apartments Market Shifts & Advancements
Digital design-to-fabrication workflows and performance-based building codes are compressing traditional development cycles while elevating material traceability requirements across the value chain.
Mass timber structural systems are absorbing mid-rise construction demand previously captured by cast-in-place concrete, as engineered wood products achieve two-hour fire ratings under updated NFPA and Eurocode standards. Scandinavian and Pacific Northwest developers are deploying cross-laminated timber for 12-to-18-story residential towers, shrinking foundation loads and accelerating floor-cycle times. The technology is absorbing risk-averse institutional capital that previously avoided combustible construction categories.
China's GB standards for building energy efficiency and the UAE's Al Sa'fat green building rating system are mandating real-time operational carbon monitoring and disclosure. These frameworks are forcing developer procurement departments to source low-embodied-carbon concrete mixes and high-performance glazing assemblies. High-rise residential in Shanghai and Dubai is experiencing the most acute compliance cost inflation as local authorities enforce facade thermal performance verification.
Subscription-based amenity access is displacing bundled common-area fees in US and German multifamily assets, as operators unbundle fitness, co-working, and concierge services into à-la-carte monthly charges. Institutional landlords including pension fund joint ventures are piloting this model in Berlin and Austin to capture ancillary revenue streams and reduce base-rent sticker shock. The shift is most visible in purpose-built rental assets targeting mobile professionals with variable tenure expectations.
Global Condominiums and Apartments Market Segmentation
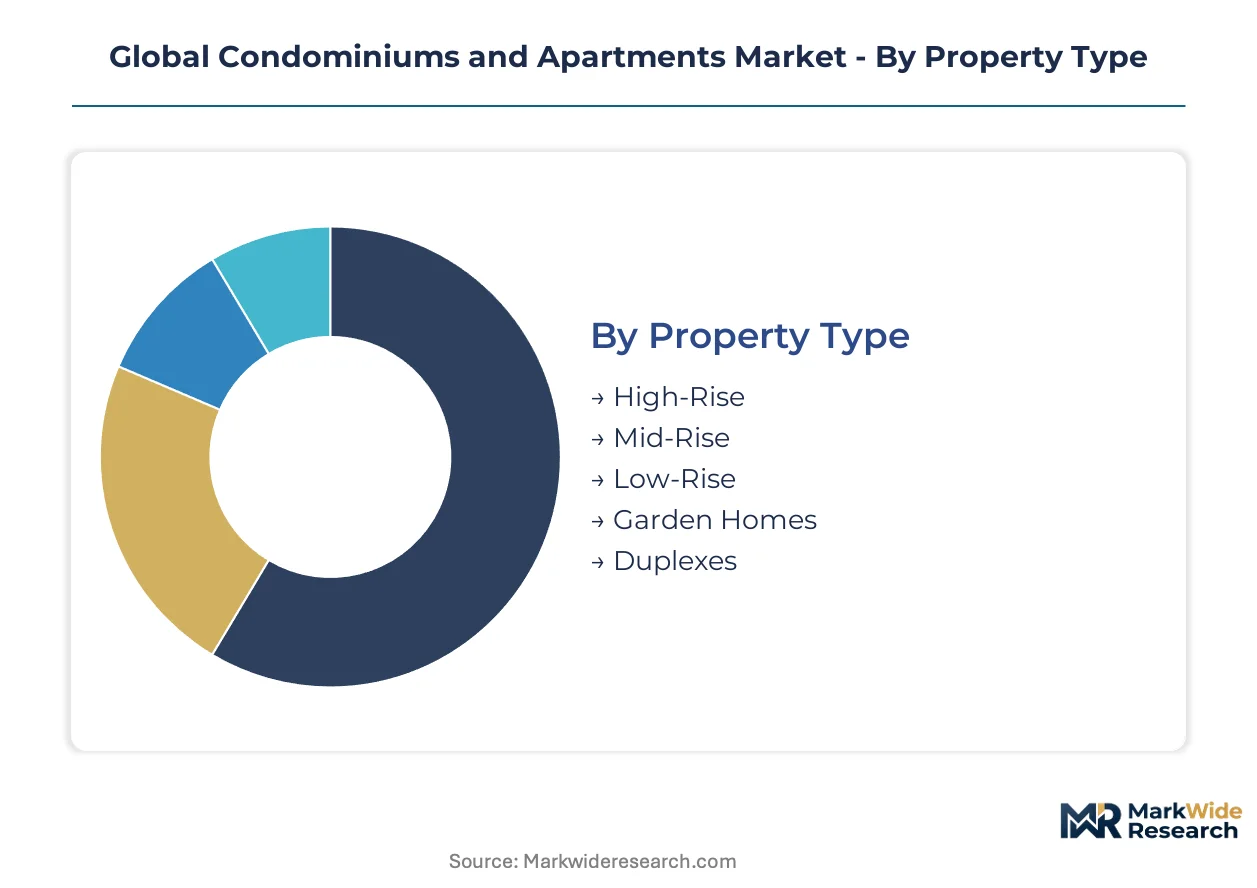
Segmentation in the Global Condominiums and Apartments Market reveals how ownership tenure, building typology, and buyer motivation reshape capital flows and construction specifications across metropolitan corridors. Developers calibrate unit mix and amenity bundling to match the liquidity preferences of institutional landlords versus equity-building owner-occupiers.
Property Type:
Standalone vertical structures dominate premium land positions in dense urban cores, while embedded low-rise configurations integrate into suburban fabric with lower per-unit infrastructure burdens.
- High-Rise:Reinforced concrete or steel-framed towers exceeding twelve stories concentrate in Shanghai, Dubai, and Miami where land scarcity justifies vertical construction premiums. Demand from cross-border wealth pools and sovereign wealth-backed developers drives absorption in waterfront and transit-adjacent parcels.
- Mid-Rise:Five-to-twelve-story structures employing podium-and-tower configurations balance density with construction cost efficiency. These assets dominate Berlin and Stockholm infill zones where municipal zoning caps height but permits floor-area-ratio bonuses near transit nodes.
- Low-Rise:Wood-framed walk-up buildings serve family-oriented demand in suburban Austin and Phoenix corridors.
- Garden Homes:Clustered townhome configurations with private outdoor space capture premium rents in Australian build-to-rent pipelines.
- Duplexes:Two-unit structures on single parcels dominate legacy Northeast US cooperative conversion markets.
Volume placements concentrate in Mid-Rise; the faster expansion belongs to Garden Homes.
Ownership Structure:
Cost-tier stratification separates equity-accumulating purchasers from tenure-flexible occupants, with capital intensity and governance complexity rising across the spectrum.
- Freehold:Perpetual ownership of individual units with undivided common-area interests attracts first-time buyers in Sun Belt metros and Canadian prairie cities. Title clarity accelerates mortgage financing and resale liquidity relative to alternative structures.
- Leasehold:Time-bound tenure with ground-rent obligations to underlying land owners dominates London prime central markets and Singapore's 99-year HDB resale segments. Depreciating lease terms compress financing leverage as expiration approaches.
- Cooperative:Share-based ownership with board approval requirements persists in pre-war Manhattan and Brooklyn assets where conversion to condominium remains economically prohibitive.
- Community Land Trust:Separated land ownership from building equity preserves long-term affordability in Austin and Minneapolis inclusionary housing programs.
Freehold claims the dominant placement volume; Community Land Trust is climbing the fastest amid municipal affordability mandates.
End User:
Customer-type segmentation determines absorption velocity, with institutional capital prioritizing yield stability while individual purchasers chase appreciation and lifestyle utility.
- Real Estate Investors:Yield-focused landlords and speculators concentrate in Dubai off-plan launches and Miami pre-construction towers. Leverage sensitivity and currency hedging requirements filter entry timing across tightening cycles.
- First-Time Buyers:Credit-constrained entrants dominate entry-level condominium absorption in Toronto and Vancouver where municipal shared-equity programs reduce deposit burdens.
- Vacation Renters:Short-term rental operators target Phuket and Dubai Marina assets with hotel-licensing flexibility and concierge infrastructure.
- Retirees:Downsizing empty-nesters drive low-rise garden home demand in Arizona and Florida age-restricted communities.
First-Time Buyers anchor placement volumes; Vacation Renters show the steepest expansion trajectory as platform-enabled short-term rental institutionalization spreads.
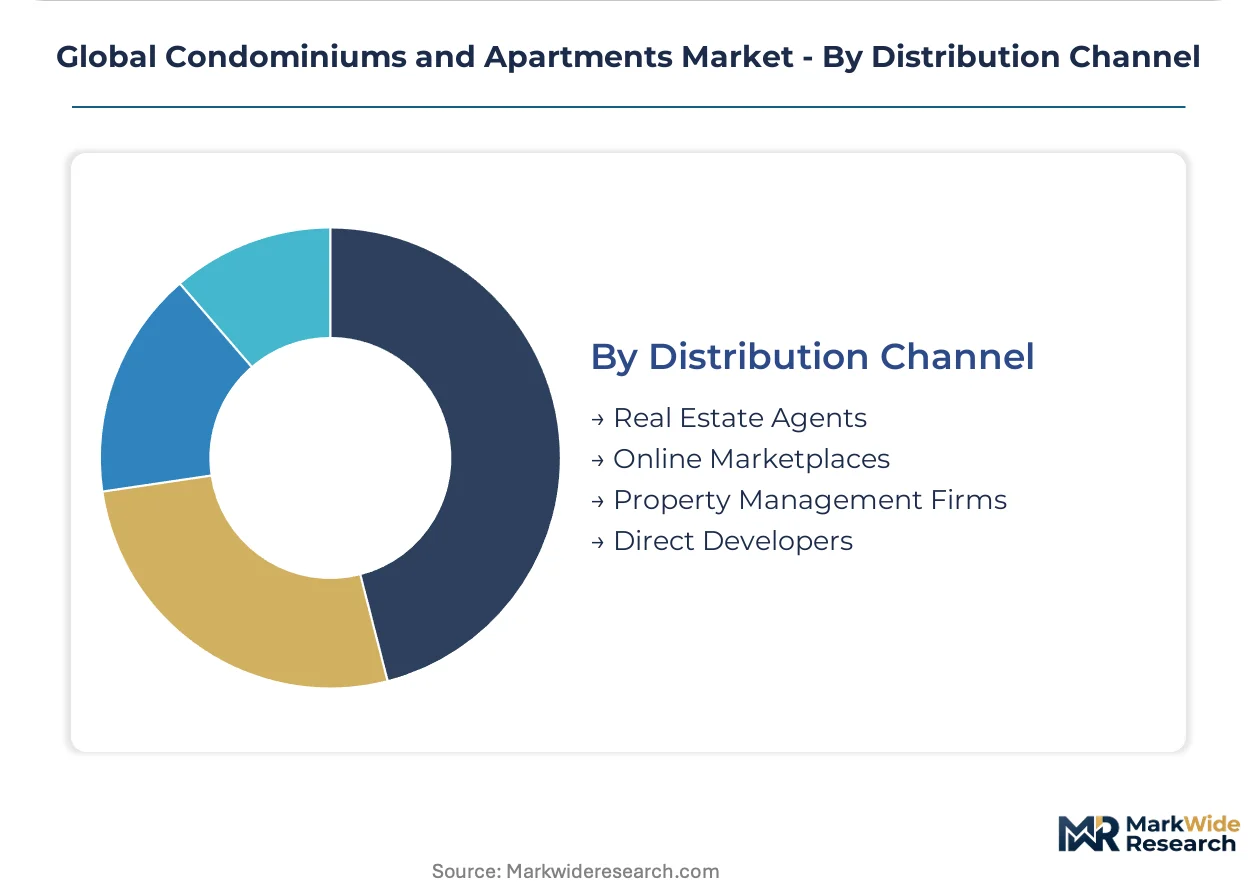
Distribution Channel:
Channel structure reflects buyer sophistication and transaction scale, with high-touch intermediation persisting in luxury segments while digital platforms compress search costs for standardized inventory.
- Real Estate Agents:Commission-based intermediaries dominate cooperative sales in legacy Northeast US markets and high-net-worth cross-border transactions in Dubai. Relationship depth and board-package preparation justify fee premiums.
- Online Marketplaces:Listing aggregators capture search initiation for standardized condominiums in Australian and German rental markets. Data transparency compresses information asymmetry for mobile professional tenants.
- Property Management Firms:Vertically integrated operators control leasing pipelines in UK build-to-rent and US single-family rental institutionalization waves.
- Direct Developers:Bypass intermediation concentrates in Singapore and Hong Kong launch events where buyer registration and ballot systems manage oversubscription.
Real Estate Agents retain volume concentration; Online Marketplaces are gaining share fastest as digital-native buyer cohorts mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border wealth migration and transit-oriented zoning reforms concentrate multifamily development in coastal metropolitan corridors across the United States, China, and the United Arab Emirates. Institutional capital allocation favors yield stability in dense urban nodes with mass-transit connectivity.
United States
Sun Belt metros attract first-time buyer flows through national land-positioning strategies. Municipal zoning reforms in Austin and Phoenix accelerate garden-home absorption in suburban infill zones. Lennar Corporation captures volume in Texas and Arizona corridors where employment growth outpaces housing supply.
China
Urban millennial demand concentrates in Yangtze River Delta and Pearl River Delta clusters. GB standards for building energy efficiency impose facade thermal performance verification in Shanghai high-rises. China Vanke anchors development pipelines in Shenzhen and Hangzhou where transit-adjacent parcels command premium pricing.
United Arab Emirates
Sovereign wealth-backed developers dominate waterfront master-planned segments. Dubai's Al Sa'fat green building rating system mandates real-time operational carbon monitoring. Emaar Properties controls absorption in Dubai Marina and Downtown Dubai where foreign-buyer registration drives pre-construction sales.
Germany
Build-to-rent institutionalization accelerates through permitted development rights and tax concessions. The EU Green Deal's embodied-carbon thresholds redirect procurement toward low-carbon concrete systems. Berlin infill zones absorb mid-rise construction where municipal height caps preserve floor-area-ratio bonuses near U-Bahn nodes.
Australia
Superannuation capital flows into single-family rental conversion pipelines. Seismic code requirements and cladding liability exposure filter developer eligibility in Sydney and Melbourne. Lendlease Group anchors competitive positioning through scale in master-planned communities across New South Wales and Victoria.
Global Condominiums and Apartments Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular prefabrication and sustainability-certified niches. The vendor base stratifies across integrated design-build-operate platforms, institutional capital aggregators, and regional land-positioning specialists. Three archetypes dominate: sovereign wealth-linked master developers, pension fund joint ventures, and vertically integrated homebuilders. Competitive moves concentrate on portfolio diversification into build-to-rent and geographic expansion through cross-border wealth corridor targeting.
Within the integrated master-developer tier, Emaar Properties and Mitsui Fudosan exemplify design-build-operate capabilities in waterfront and transit-oriented segments. Among institutional capital aggregators, Brookfield Asset Management and Greystar Real Estate Partners occupy positions blending operational density with yield-focused capital deployment. China Vanke represents the regional land-positioning archetype with concentrated exposure to transit-adjacent parcels in coastal metropolitan corridors.
| Leading Market Players |
|---|
| China Vanke Co., Ltd. |
| Emaar Properties |
| Lennar Corporation |
| Brookfield Asset Management |
| Greystar Real Estate Partners |
| Lendlease Group |
| CapitaLand Limited |
| Mitsui Fudosan Co., Ltd. |
| Equity Residential |
| Others |
Supply & Pricing Matrix
Backward integration into land acquisition and prefabrication capabilities anchors pricing power for developers controlling site pipelines in Sun Belt metros and coastal Chinese corridors. Sovereign wealth-backed master developers in Dubai and vertically integrated homebuilders in Texas leverage captive supply of entitled land to buffer margin compression from volatile construction inputs.
Pricing Analysis
Volume placements concentrate in mid-rise garden-home configurations where developers sacrifice margin for absorption velocity, while waterfront high-rises in Miami and Dubai Marina command premium-mid-economy pricing differentiation based on view premiums and concierge amenity tiers. Price differentiation hinges on green certification tier under EU Green Deal and Al Sa'fat frameworks, with verified low-carbon concrete specifications adding cost pass-through leverage. Pricing pressure stems from skilled trades shortages extending project timelines in Germany and Australia. First-time buyers in Toronto and Vancouver exhibit acute price sensitivity, whereas cross-border wealth pools in Dubai show elasticity for branded trophy assets.
Supply Chain Analysis
Workforce availability constraints in Germany, Australia, and the US Sun Belt are compressing on-site labor hours and accelerating factory-built volumetric adoption. Material supply concentrates in China for low-carbon concrete admixtures, Scandinavia for cross-laminated timber systems, and the UAE for high-performance glazing assemblies. Raw material dependencies include Portland cement alternatives, engineered wood products, and fire-rated facade composites. Supply chain risk centers on single-source vulnerability for specialized enclosure engineering consultancies. Distribution runs through vertically integrated property management firms in UK build-to-rent pipelines and direct developer launch events in Singapore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race where control over entitled land pipelines and modular fabrication capacity determines who captures margin. Players are pursuing upstream leverage through captive land positioning and downstream control via build-to-rent operating platforms.
For Market Incumbents: Hedge against cladding liability exposure and labor cost volatility by diversifying into factory-built volumetric systems and pre-certified material procurement. Emaar Properties and Lennar Corporation demonstrate how integrated design-build-operate capabilities buffer margin compression from municipal fire-safety retrofits. Prioritize backward integration into land banking in Austin and Phoenix corridors where employment growth outpaces supply. For New Entrants and Emerging Players: Enter via modular prefabrication niches serving Scandinavian and Japanese mid-rise segments where digital twin commissioning reduces quality variance. White-space targets include community land trust structures in Austin and Minneapolis inclusionary programs, and subscription-based amenity unbundling in Berlin build-to-rent assets. Go-to-market leverage rests on CSRD-aligned green financing credentials that unlock labeled bond issuance advantages. For Investors and Strategic Acquirers: Exit pathways concentrate in pension fund joint ventures seeking yield-stable multifamily platforms with operational density. Long-term viability favors developers with verified operational carbon disclosure and transit-adjacent parcel concentrations. Acquisition target archetype: vertically integrated regional specialists with captive land pipelines in Sun Belt metros. Watch for inflection in central bank tightening cycles affecting floating-rate construction debt exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Prefabrication Scale-Up | Factory-built volumetric units compress on-site labor hours in Scandinavian markets. |
| Green Certification Investment | Al Sa'fat and EU Green Deal compliance unlocks institutional capital allocation preferences. |
| Land Pipeline Expansion | Entitled site control in Phoenix and Austin corridors anchors absorption velocity. |
| Build-to-Rent Platform Integration | UK permitted development rights unlock single-family rental conversion pipelines. |
| Operational Carbon Disclosure | CSRD-aligned reporting creates labeled bond issuance advantages in EU markets. |
Research Methodology
Document review covered municipal zoning filings, green building certification databases, and customs trade data, complemented by interviews with development executives at sovereign wealth-linked master developers, procurement directors at modular fabrication facilities, and portfolio managers at pension fund joint ventures. Secondary validation drew from EU Green Deal regulatory texts, Dubai Al Sa'fat rating system documentation, and China GB standards publications. Bottom-up project pipeline tracking and top-down capital flow analysis were triangulated to reconcile volume estimates.
Segment-level projections across high-rise, mid-rise, and garden-home typologies were generated using absorption rate modeling near transit nodes, with ownership structure and end-user segmentation informing price elasticity assumptions. CAGRs were derived from regression against employment growth, cross-border wealth migration indices, and municipal density incentive adoption curves. Industry-specific inputs included skilled trades availability indices and embodied-carbon compliance cost trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt central bank tightening or cladding liability litigation waves. Forecasts reflect documented assumptions regarding transit-oriented zoning reform velocity and institutional capital allocation persistence. Material deviation in EU Green Deal enforcement timelines or seismic code retrofit compliance costs warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condominium and Apartments
Condom Market
Condominium and Apartments
Saudi Arabia Condominiums and Apartments Market
Condominium and Apartments
Europe Condominiums and Apartments Market
Condominium and Apartments
Spain Condominiums and Apartments Market
Condominium and Apartments
Qatar Condominium and Apartment Market
Condominium and Apartments
Germany Condominiums and Apartments Market
Condominium and Apartments
India Condominium and Apartments Market
Condominium and Apartments
Japan Condominiums and Apartments Market
Condominium and Apartments
Italy Condominiums and Apartments Market
Condominium and Apartments
Canada Condominiums and Apartments Market
Condominium and Apartments
UAE Condominiums and Apartments Market
Condominium and Apartments
ASEAN Condominiums and Apartments Market
Condominium and Apartments
Asia-Pacific Condominiums and Apartments Market
Condominium and Apartments
Egypt Condominiums and Apartments Market
Condominium and Apartments
Latin America Condominiums and Apartments Market