
 Condom Market | 2026-2036
Condom Market Size, Share, and Industry Trends Forecast 2026-2036
Condom Market Analysis
Malaysian rubber processors is hardening their grip on upstream latex supply for condom manufacturing. Karex Berhad leverages integrated plantation-to-factory operations across Southeast Asia. Okamoto Industries, Inc. sustains technology leadership in ultra-thin polyurethane films. Reckitt Benckiser Group dominates branded distribution through pharmacy and e-commerce channels in Western Europe and North America.
A condom is a barrier contraceptive device, typically manufactured from natural rubber latex, synthetic polyisoprene, or polyurethane, designed to prevent pregnancy and reduce transmission of sexually transmitted infections during sexual intercourse. Modern production involves dipped-mold vulcanization with electronic pinhole testing to ensure burst strength and integrity standards exceed ISO 4074 requirements. Latex variants still occupy the largest volume share, though polyisoprene segments are expanding fastest among latex-sensitive users. Ultra-thin thickness grades command premium shelf positioning, while extra-lubricated and ribbed formats target differentiated sexual wellness use cases rather than purely preventive health applications.
FDA clearance requirements govern United States market entry, while EMA and national competent authorities enforce CE marking under the EU Medical Device Regulation for contraceptive claims. WHO prequalification programs shape procurement eligibility for donor-funded distribution in low-income countries. Stakeholders must monitor evolving polymer standards and regional classification shifts that could reclassify certain flavored or textured variants from medical devices to consumer wellness products.
Market Dynamics
Malaysian plantation-to-factory consolidation is reshaping upstream latex economics for barrier contraceptive manufacturing, concentrating feedstock control among integrated processors while fragmenting downstream formulation competition.
Growth Catalysts
- WHO Prequalification Programs:Donor-funded procurement eligibility in sub-Saharan Africa drives institutional volume commitments for public health distribution networks.
- Graphene-Infused Latex:Enhanced thermal conductivity formulations reduce allergic sensitization rates while improving tactile feedback for latex-sensitive user segments.
- Brazil:Youth demographic expansion combined with retail pharmacy network densification accelerates category penetration in Latin America's largest consumer market.
Market Restraints
- Natural Rubber Price Volatility:Climatic disruption across Southeast Asian plantations creates input cost instability for latex-dependent manufacturers.
- Polyisoprene Substitution Ceiling:Synthetic alternatives face burst strength limitations under ISO 4074 testing protocols, constraining ultra-thin segment expansion.
- FDA 510(k) Pathway:Novel material submissions require extended clinical validation timelines, delaying market entry for innovative barrier technologies.
Strategic Opportunities
- India:Underpenetrated rural districts present whitespace for pharmacy-led distribution partnerships targeting first-time contraceptive adopters.
- E-Commerce Direct-to-Consumer:Discreet subscription models bypass traditional retail stigma barriers in conservative demographic segments.
- EU Medical Device Regulation:CE marking harmonization creates regulatory arbitrage potential for pre-qualified manufacturers entering European pharmacy chains.
Industry Challenges
- Electronic Pinhole Testing Calibration:Precision equipment maintenance demands specialized technician training that outpaces regional vocational pipeline output.
- Polymer Standard Convergence:Divergent national classification frameworks for flavored and textured variants complicate multi-territory product registration strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Condom Market |
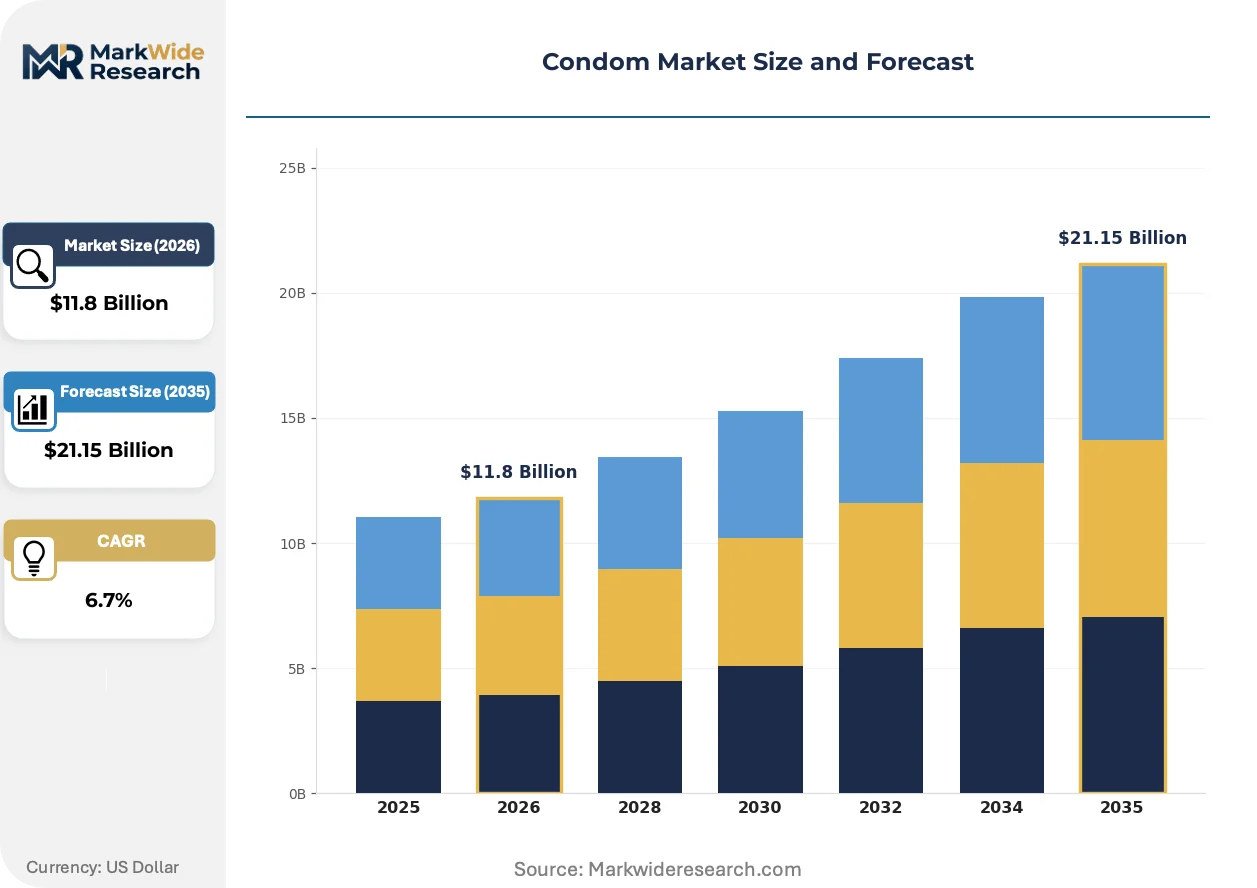
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $21.15 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Latex, Polyurethane, Polyisoprene, Lambskin Flavor: Strawberry, Chocolate, Mint, Vanilla Thickness: Ultra-Thin, Standard, Extra-Lubricated, Ribbed Use Case: Recreational, Preventive Health, Contraceptive, Sexual Wellness |
| Companies Covered | Ansell Limited, Okamoto Industries, Inc., Reckitt Benckiser Group, Ceylon Rubber Industries Ltd., Cupid Limited, Church & Dwight Co., Inc., LifeStyles Healthcare Pte. Ltd., Fuji Latex Co., Ltd., Karex Berhad, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Condom Market Emerging Trajectories
Material science breakthroughs and regulatory reclassification pressures are compressing traditional manufacturing margins while opening premium positioning for next-generation barrier technologies.
Polyisoprene synthetic elastomer is electrifying the latex-sensitive segment with protein-free formulations that match natural rubber elasticity. Allergy-prone consumers and healthcare procurement officers are accelerating adoption across European and North American pharmacy channels. The technology is electrifying competitive dynamics by forcing incumbent latex specialists to defend shelf space through price compression rather than formulation differentiation.
EU Medical Device Regulation reclassification mandates are tightening clinical evidence requirements for contraceptive device claims. Manufacturers must now submit biocompatibility testing data that exceeds prior self-certification standards. Flavored and textured variants face particular scrutiny, with several national competent authorities reviewing whether sensory modifications trigger consumer product rather than medical device classification.
Subscription-based replenishment models are displacing episodic retail purchasing among urban millennial and Gen-Z demographics. Direct-to-consumer platforms capture recurring revenue while reducing pharmacy visit friction for stigma-sensitive buyers. India and Brazil exhibit the strongest channel migration velocity, where smartphone penetration and digital payment infrastructure enable app-based reordering systems.
Condom Market Segmentation
Material composition and functional specifications dictate procurement patterns across institutional and retail channels. Upgrade cycles vary sharply by user sensitivity profiles and regulatory classification tiers.
Type:
Replacement decisions hinge on allergic response thresholds and burst-strength reliability requirements under ISO 4074 protocols.
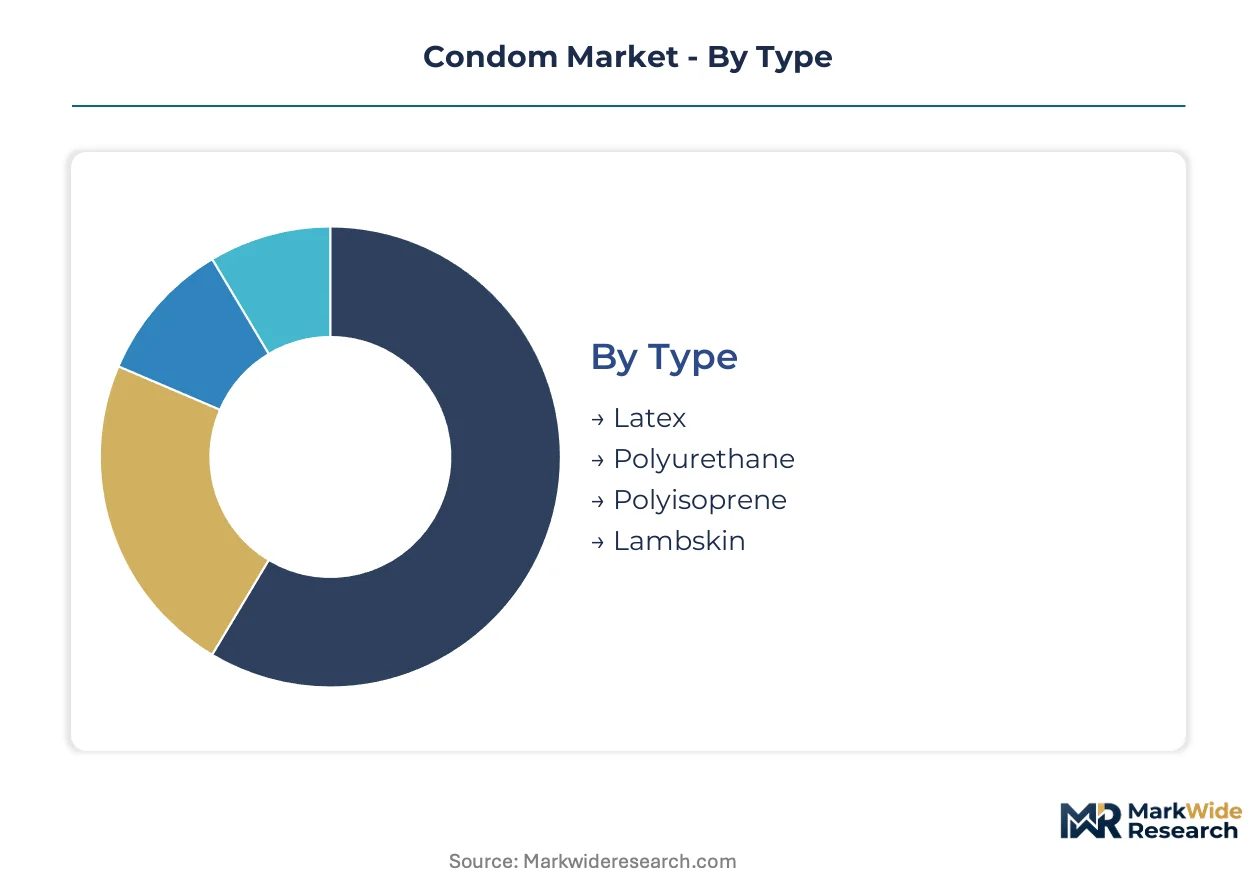
- Latex:Natural rubber formulations dominate procurement volumes through dipped-mold vulcanization. Plantation-to-factory integration in Malaysia secures feedstock for institutional buyers in India and Brazil.
- Polyisoprene:Synthetic elastomer eliminates protein allergens while matching natural rubber elasticity. European and North American pharmacy channels accelerate adoption among latex-sensitive demographics.
- Polyurethane:Thermoplastic films enable ultra-thin gauges with superior heat transfer. FDA 510(k) pathway constraints delay novel material submissions.
- Lambskin:Intestinal membrane construction transmits heat effectively but lacks viral barrier protection. Niche positioning persists among monogamous couples prioritizing sensation over STI prevention.
Latex sits at the top of the volume ranking, with Polyisoprene climbing the fastest.
Flavor:
Cost tiers separate pharmaceutical-grade offerings from novelty-positioned variants facing reclassification scrutiny.
- Strawberry:Glycerin-based formulations with artificial ester compounds. EU Medical Device Regulation reviews trigger consumer product classification risks in France and Germany.
- Chocolate:Cocoa-derived flavoring agents complicate biocompatibility dossiers. ANVISA in Brazil maintains stricter preservative limits than FDA counterparts.
- Mint:Menthol infusion creates cooling sensation marketed toward oral sex applications. Shelf positioning varies by regional obscenity regulations.
- Vanilla:Vanillin additive appeals to conservative demographic segments. E-commerce subscription bundles favor this neutral profile for discreet replenishment.
Strawberry leads volume concentration, with Chocolate expanding most quickly in Latin American pharmacy networks.
Thickness:
Margin structures stratify across performance tiers, with premium positioning commanding threefold unit economics over standard gauges.
- Ultra-Thin:Sub-50 micron specifications demand precision dipping equipment. Okamoto technology leadership in polyurethane films sets burst-strength benchmarks.
- Standard:70-micron nominal thickness satisfies WHO prequalification for donor-funded distribution. Procurement officers in sub-Saharan Africa prioritize reliability over sensation.
- Extra-Lubricated:Silicone oil or water-based gel coatings target vaginal dryness applications. Retail pharmacy networks in India stock this variant for first-time contraceptive adopters.
- Ribbed:Textured surface patterns enhance stimulation for recreational use cases. Classification ambiguity persists under divergent national medical device frameworks.
Standard thickness holds volume dominance, with Ultra-Thin gaining share fastest among urban millennial demographics.
Use Case:
Customer type fragmentation separates institutional procurement from direct-to-consumer wellness positioning.
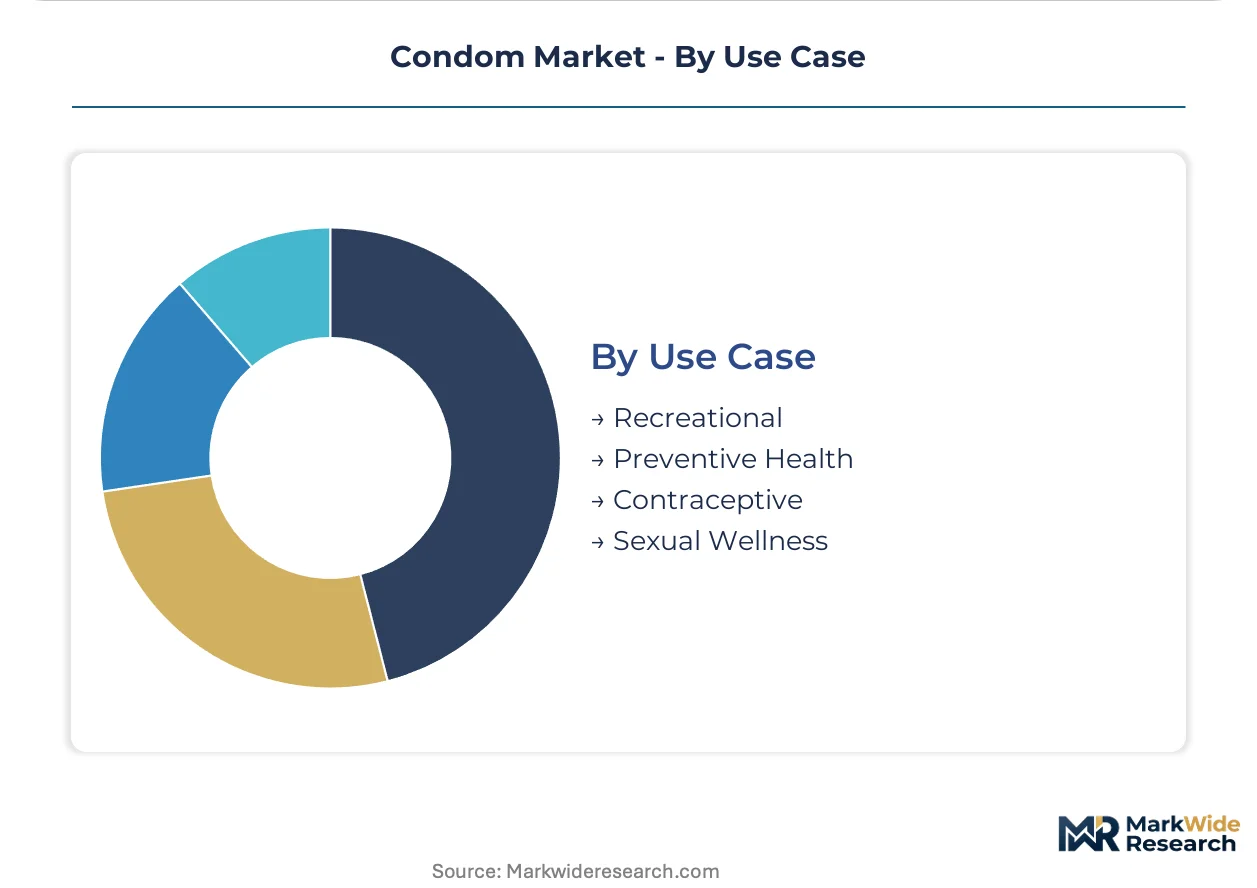
- Recreational:Sensory-enhancement variants with textured or flavored attributes. E-commerce platforms capture this segment through subscription models bypassing retail stigma.
- Preventive Health:STI reduction claims require FDA clearance or CE marking under EU MDR. Public health programs in sub-Saharan Africa drive volume through WHO prequalification.
- Contraceptive:Pregnancy prevention as primary indication triggers strictest regulatory oversight. Burst strength and pinhole testing protocols exceed recreational product requirements.
- Sexual Wellness:Emerging category positioning intimacy enhancement alongside health protection. Reclassification risk looms as national competent authorities review sensory modification thresholds.
Preventive Health anchors institutional procurement volumes, with Sexual Wellness climbing fastest through direct-to-consumer channel migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as producers migrate toward jurisdictions with streamlined medical device pathways and lower compliance burdens. Malaysia's plantation-to-factory integration attracts volume producers seeking captive latex supply, while India and Brazil emerge as demand anchors where retail pharmacy expansion outpaces regulatory stringency.
United States
FDA 510(k) clearance requirements govern market entry for novel barrier technologies, creating extended validation timelines that favor incumbent manufacturers with established predicate devices. Institutional procurement through CDC and USAID channels concentrates in the Southeast and Mid-Atlantic regions, where distribution hubs serve public health networks. Direct-to-consumer subscription models bypass traditional pharmacy stigma in urban coastal markets.
Germany
EMA oversight and BfArM national enforcement impose stringent biocompatibility dossier requirements under EU Medical Device Regulation, elevating compliance costs for flavored and textured variants. Pharmacy-led distribution dominates in Bavaria and North Rhine-Westphalia, where insurance reimbursement frameworks support preventive health positioning. Berlin-based e-commerce platforms pioneer discreet replenishment systems for millennial demographics.
India
CDSCO registration and BIS quality certification govern import and domestic manufacturing, though enforcement variance across states creates regulatory patchwork. Underpenetrated rural districts in Uttar Pradesh and Bihar present whitespace for pharmacy partnerships targeting first-time contraceptive adopters. Maharashtra and Karnataka anchor domestic production clusters with integrated latex processing capabilities.
Brazil
ANVISA maintains preservative limits stricter than FDA counterparts, particularly for cocoa-derived flavoring agents in novelty-positioned variants. Youth demographic expansion in São Paulo and Rio de Janeiro accelerates category penetration through retail pharmacy network densification. The country's national pharmaceutical regulator reviews sensory modification thresholds that could trigger consumer product reclassification.
Malaysia
Integrated plantation-to-factory operations across Southeast Asia secure upstream latex supply for institutional buyers. Karex Berhad leverages backward integration into rubber cultivation to control feedstock economics. The country's medical device regulatory framework aligns with ASEAN harmonization initiatives, facilitating regional export eligibility.
Condom Market Vendor Landscape
Malaysian producers anchor the upstream tier through plantation-to-factory integration; Japanese and European specialists hold technology leadership in ultra-thin and synthetic formulations. Market structure concentrates among integrated latex processors and branded distribution networks, with mid-tier private-label fabricators fragmenting downstream competition. Three archetypes dominate: captive supply operators, technology licensors, and pharmacy-channel brand owners. Competitive moves center on backward integration into rubber cultivation and direct-to-consumer channel migration to capture recurring revenue.
Within the integrated supply tier, Karex Berhad exemplifies plantation-to-factory consolidation that secures feedstock control across Southeast Asian operations. Okamoto Industries, Inc. occupies a position emphasizing material science specialization in ultra-thin barrier technologies. Reckitt Benckiser Group anchors branded distribution archetypes through pharmacy and e-commerce channel dominance in Western Europe and North America. These three represent distinct competitive vectors: upstream capture, formulation innovation, and retail brand equity.
| Leading Market Players |
|---|
| Ansell Limited |
| Okamoto Industries, Inc. |
| Reckitt Benckiser Group |
| Ceylon Rubber Industries Ltd. |
| Cupid Limited |
| Church & Dwight Co., Inc. |
| LifeStyles Healthcare Pte. Ltd. |
| Fuji Latex Co., Ltd. |
| Karex Berhad |
| Others |
Supply Flow & Price Mechanics
Captive plantation-to-factory integration across Malaysian rubber estates anchors both feedstock security and pricing power for latex-dependent manufacturers, compressing input cost volatility while enabling premium positioning for ultra-thin and synthetic formulations in pharmacy channels.
Pricing Analysis
Distributor margin layers stratify across three-tier pricing structure across premium, standard, and economy levels, with ultra-thin polyurethane and graphene-infused variants commanding shelf premiums based on ISO 4074 certification tier and brand heritage. Price differentiation separates institutional procurement volumes from direct-to-consumer subscription bundles, where discreet replenishment models capture recurring revenue at lower per-unit sensitivity. Cost compression in standard latex tiers is intensifying because Malaysian integrated processors leverage captive supply to undercut fragmented downstream competitors. Public health procurement officers in sub-Saharan Africa exhibit highest price sensitivity, while urban millennial subscribers in Western Europe demonstrate lowest elasticity for sensation-enhanced premium tiers.
Supply Chain Analysis
Returns and quality-control flows center on electronic pinhole testing recalibration, where defective batches cycle back to vulcanization units rather than downstream distribution. Geographic concentration clusters in Malaysia, Thailand, and Indonesia for natural rubber latex, while Japan and Germany anchor synthetic polyisoprene and polyurethane film production. Raw material dependencies draw from plantation-grade latex, synthetic elastomer polymers, and silicone-based lubricant formulations. Single-source vulnerability persists in Malaysian plantation-to-factory operations exposed to climatic disruption across Southeast Asian growing regions. Distribution runs through pharmacy-led networks in India and Brazil, direct-to-consumer platforms in North America and Western Europe, and institutional procurement channels in sub-Saharan Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with demand shifting toward ultra-thin and synthetic formulations that command premium positioning despite standard-tier price compression.
For Market Incumbents: Acquire plantation assets or long-term latex offtake contracts to secure feedstock against natural rubber price volatility and polyisoprene substitution threats. Deepen backward integration into rubber cultivation while defending pharmacy shelf space through ISO 4074 certification investment and graphene formulation R&D to differentiate beyond price. For New Entrants and Emerging Players: Enter via direct-to-consumer subscription models targeting stigma-sensitive demographics in conservative markets, bypassing established pharmacy distribution. Underpenetrated rural districts in Uttar Pradesh and Bihar present whitespace for pharmacy partnerships, while flavored variant reclassification risks in Europe create arbitrage potential for pre-qualified manufacturers. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier private-label fabricators because downstream fragmentation concentrates procurement leverage among integrated Malaysian processors and branded distribution networks. Five-to-ten year viability hinges on synthetic material substitution rates and regulatory classification stability. Monitor EU Medical Device Regulation enforcement variance across national competent authorities for early signals of flavored variant reclassification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rubber Cultivation | Captive latex supply secures feedstock economics against climatic volatility in Southeast Asian plantations. |
| Direct-to-Consumer Subscription Launch | Recurring revenue models bypass retail stigma barriers in conservative demographic segments across India and Brazil. |
| Graphene-Infused Formulation Development | Enhanced thermal conductivity reduces allergic sensitization while enabling premium positioning in pharmacy channels. |
| CE Marking Pathway Acceleration | EU MDR pre-qualification creates regulatory arbitrage for entry into European pharmacy chain distribution. |
| WHO Prequalification Pursuit | Donor-funded procurement eligibility unlocks institutional volume commitments in sub-Saharan African public health networks. |
Methodological Framework
Coverage spans Southeast Asian plantation operations, European pharmacy networks, North American direct-to-consumer platforms, Indian retail distribution, and Brazilian institutional procurement, with primary inputs from each. The approach combines interviews with rubber plantation managers, condom manufacturing plant engineers, pharmacy category buyers, public health procurement officers, and e-commerce platform operators with secondary validation from FDA 510(k) filings, EMA biocompatibility dossiers, WHO prequalification databases, and customs trade records. Bottom-up volume triangulation against top-down category spend estimates ensures cross-verification.
Granularity-level modeling disaggregates the analysis window by material composition, thickness specification, flavor variant, and distribution channel, with separate trajectory assumptions for institutional versus retail procurement patterns. CAGRs derive from segment-level growth rate reconciliation against macro demographic and regulatory drivers. Industry-specific inputs include youth population expansion rates in priority markets, pharmacy network densification indices, and medical device classification stability assessments.
The model holds under stable regulatory classification for barrier contraceptives; deviation in EU MDR enforcement stringency or FDA material approval pathways would shift volume trajectories. Forecasts embed assumptions regarding natural rubber supply continuity and synthetic elastomer burst-strength advancement. Practitioners should monitor national competent authority reclassification reviews and plantation yield reports for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condominium and Apartments
Saudi Arabia Condominiums and Apartments Market
Condominium and Apartments
Global Condominiums and Apartments Market
Condominium and Apartments
Latin America Condominiums and Apartments Market
Condominium and Apartments
Japan Condominiums and Apartments Market
Condominium and Apartments
ASEAN Condominiums and Apartments Market
Condominium and Apartments
Italy Condominiums and Apartments Market
Condominium and Apartments
Spain Condominiums and Apartments Market
Condominium and Apartments
Europe Condominiums and Apartments Market
Condominium and Apartments
Qatar Condominium and Apartment Market
Condominium and Apartments
Egypt Condominiums and Apartments Market
Condominium and Apartments
Asia-Pacific Condominiums and Apartments Market
Condominium and Apartments
Germany Condominiums and Apartments Market
Condominium and Apartments
India Condominium and Apartments Market
Condominium and Apartments
Canada Condominiums and Apartments Market
Condominium and Apartments
UAE Condominiums and Apartments Market