
 Camping and Caravanning Market | 2026-2036
Camping and Caravanning Market Size, Share, and Industry Trends Forecast 2026-2036
Camping and Caravanning Market Analysis
Aluminum chassis construction is hardening into composite polymer alternatives across premium caravan lines, cutting unit weight by substantial margins while improving thermal efficiency. Winnebago Industries leverages in-house lamination expertise to control material cost curves across its Class B and Class C motorhome ranges. Thor Industries anchors North American towable production through vertically integrated frame manufacturing in Indiana and Oregon facilities. Forest River competes on breadth, sustaining the industry's widest product catalog across entry-level travel trailers to luxury fifth-wheels.
Camping and caravanning encompasses temporary outdoor accommodation through towable and self-propelled recreational vehicles, tent-based shelters, and associated equipment designed for mobility, weather resistance, and off-grid functionality; units typically incorporate laminated sidewalls with foam-core insulation, galvanized steel frames, and 12-volt electrical systems supporting multi-day autonomy. The product-type dimension shows motorhomes commanding the highest per-unit margins while camping gear delivers the fastest inventory velocity through online retail channels. End-user segmentation reveals rental services as the fastest-growing demand pool, with platforms converting vehicle owners into fractional-income participants.
The US National Highway Traffic Safety Administration enforces Federal Motor Vehicle Safety Standards on trailer braking and lighting systems, while the EPA regulates emissions from motorized RV powertrains under Tier 3 standards. Europe's F-Gas Regulation restricts refrigerants in caravan climate systems, pushing manufacturers toward propane-based cooling alternatives. Stakeholders must monitor evolving carbon-border adjustments and electrification mandates that threaten to recalibrate powertrain strategies across motorized segments.
Market Dynamics
Lightweight composite materials are hardening into the dominant chassis construction across premium caravan lines, cutting unit weight substantially while forcing aluminum suppliers to reposition toward entry-tier segments. This material transition sits at the center of competitive differentiation.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on hydrofluorocarbon refrigerants in caravan climate systems push manufacturers toward propane-based absorption cooling, opening supplier diversification opportunities for component vendors.
- Experience economy preference:Millennial family segments prioritize mobile accommodation over traditional hospitality, converting discretionary leisure spend toward towable and self-propelled units with off-grid capability.
- Smart insulation adoption:Vacuum-insulated panels and aerogel composites improve thermal efficiency ratings, enabling four-season usage patterns that extend addressable rental calendars.
Market Restraints
- Galvanized steel frame cost volatility:Input price swings for chassis-grade steel concentrate margin pressure on mid-tier manufacturers without captive metallurgy contracts.
- German supply concentration:Laminated sidewall production clusters in Baden-Württemberg and Bavaria, creating single-source vulnerability for European assemblers.
- Lithium battery substitution ceiling:Lead-acid 12-volt systems retain cost advantage in entry trailers, slowing full electrification of auxiliary power systems.
Strategic Opportunities
- UK rental platform expansion:Peer-to-peer vehicle sharing models convert dormant owner assets into fractional-income streams, expanding addressable usage without manufacturing capacity expansion.
- Solar-integrated roof convergence:Photovoltaic laminates combined with structural composites enable true off-grid autonomy for remote destination camping.
- France's national camping infrastructure investment:Municipal and regional subsidies for serviced pitch upgrades create pull-through demand for higher-specification units.
Industry Challenges
- Composite lamination technician scarcity:Specialized vacuum-infusion and resin-transfer molding skills outpace vocational training output in manufacturing regions.
- Multi-homologation certification timelines:Simultaneous compliance with NHTSA lighting standards, EU Whole Vehicle Type Approval, and national braking regulations extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camping and Caravanning Market |
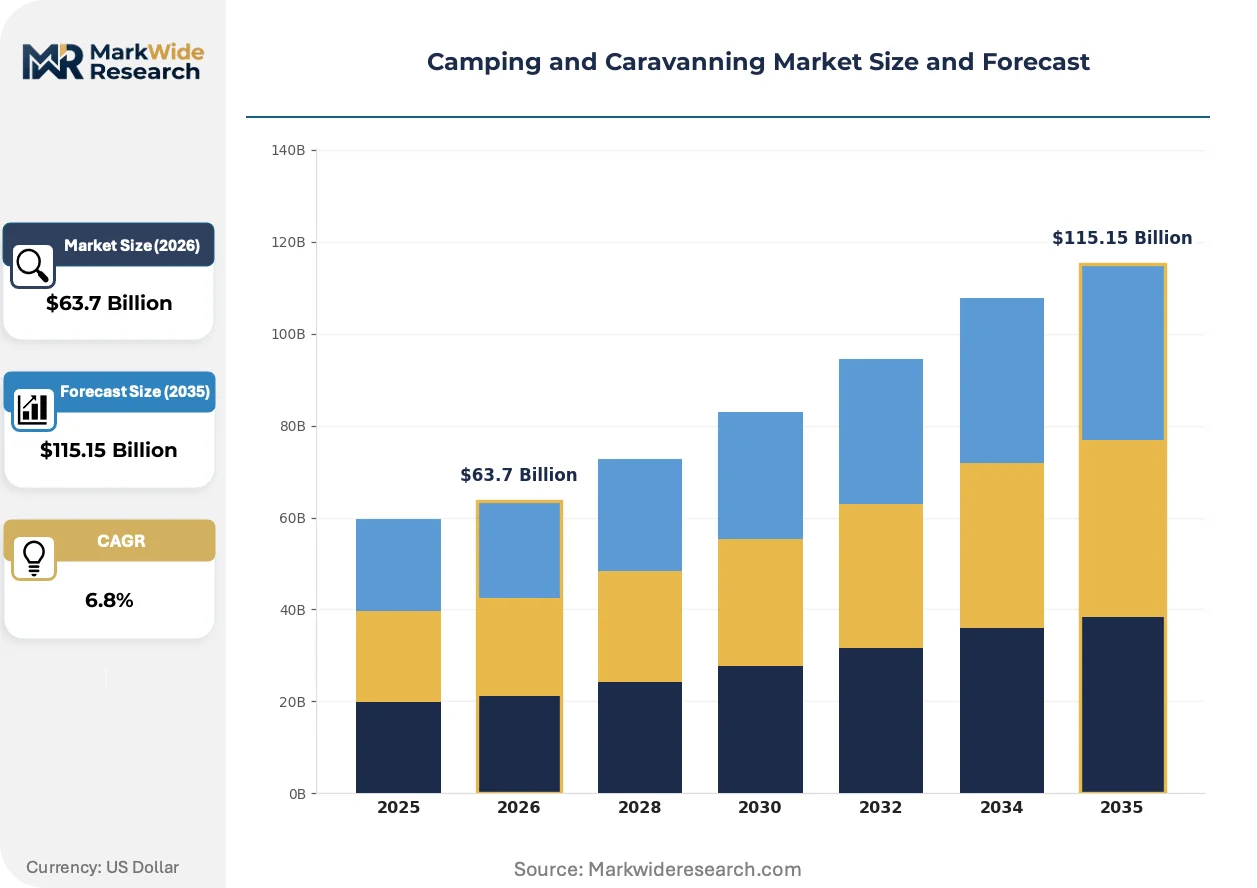
| Market Size in 2026 | $63.7 Billion |
| Market Size in 2035 | $115.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tents, Caravans, Motorhomes, Camping Gear End User: Families, Outdoor Enthusiasts, Tourists, Rental Services Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Trade Shows Usage Occasion: Seasonal Trips, Festivals, Adventure Travel, Weekend Getaways |
| Companies Covered | Kampgrounds of America (KOA), RVshare, Hipcamp, Glamping Hub, Camplify, Outdoorsy, Winnebago Industries, Thor Industries, Forest River, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camping and Caravanning Market Emerging Trajectories
Active material substitution and regulatory compliance redesign are compressing traditional product development cycles. Manufacturers must now synchronize chassis engineering with evolving refrigerant rules and buyer expectations for connected, autonomous-capable units.
Polymer-composite sandwich panels with foam-core construction are overtaking conventional fiberglass-aluminum laminated sidewalls in motorhome and premium caravan production. German and French assemblers have adopted these structures at scale since 2022. The shift is overtaking established supply relationships and forcing aluminum extruders to diversify into architectural and transportation markets.
Europe's F-Gas Regulation mandates phasedown of high-global-warming-potential refrigerants in mobile air conditioning and refrigeration units. Caravan climate system suppliers now engineer propane-based absorption cycles and CO2 transcritical heat pumps as compliance pathways. Motorhome segments with integrated kitchen refrigeration face the steepest redesign timelines and component sourcing challenges.
Fractional ownership and subscription-based access models are fragmenting traditional dealer-retail concentration. Rental platforms and manufacturer-direct membership programs capture younger buyer segments before first purchase consideration. This behavioral pivot is most visible in UK and Netherlands markets where urban density and storage constraints limit full ownership practicality.
Camping and Caravanning Market Segmentation
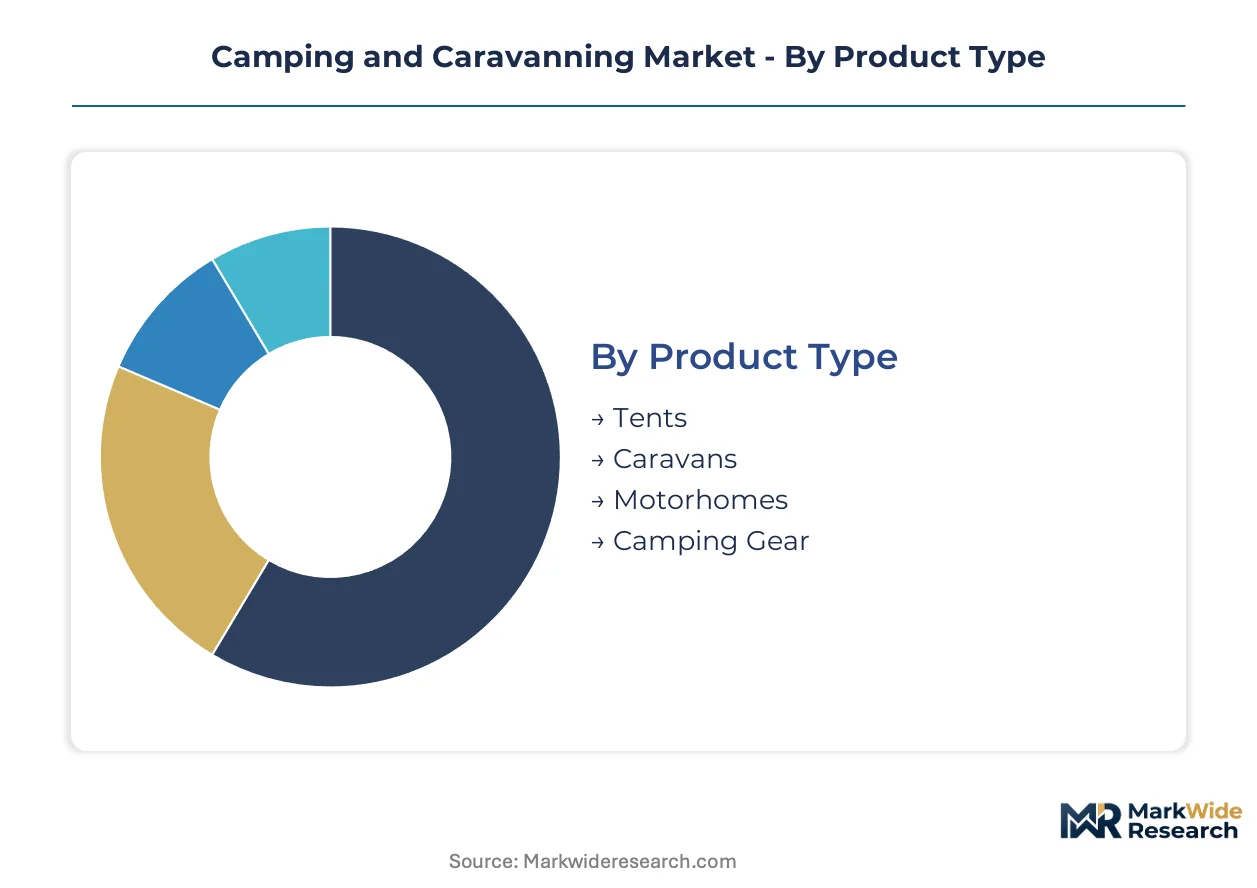
Segmentation in camping and caravanning reveals how material innovation, rental platform economics, and distribution channel fragmentation are redrawing competitive boundaries. Buyers now cross traditional category lines as composite construction and peer-to-peer access models reshape purchase logic.
Product Type:
Standardization dominates entry tiers while premium lines pursue bespoke lamination and smart-system integration.
- Motorhomes:Self-propelled units with integrated powertrains and living quarters command the highest per-unit margins in the category. Demand concentrates in Germany and France where retired couples prioritize extended touring autonomy; Tier 3 emissions compliance from the EPA and EU CO2 targets are forcing powertrain redesign timelines.
- Caravans:Towable units utilizing polymer-composite sandwich panels with foam-core construction are displacing conventional fiberglass-aluminum sidewalls. UK and German manufacturers lead this material transition as buyers seek lighter tow weights compatible with smaller passenger vehicles.
- Tents:Portable shelters range from basic nylon dome structures to inflatable beam-supported family units. Air-beam technology from Decathlon and Vango is penetrating the premium family segment.
- Camping Gear:Portable furniture, cooking systems, and off-grid power equipment deliver the fastest inventory velocity through Amazon and specialist online channels. Lithium battery substitution remains limited by lead-acid cost advantages in entry price tiers.
Leading the category by volume: Camping Gear. Growing fastest: Caravans.
End User:
Ownership models fragment across age cohorts as younger buyers defer purchase through rental access.
- Families:Millennial parents with children under 12 represent the fastest-expanding buyer segment. UK and Netherlands markets show particular strength as these households prioritize experience-based leisure over traditional hospitality spending.
- Rental Services:Peer-to-peer platforms and manufacturer-direct membership programs convert dormant owner assets into fractional-income streams. France and UK municipal camping infrastructure investments create pull-through demand for higher-specification rental fleets.
- Outdoor Enthusiasts:Dedicated hikers, cyclists, and climbers demand ultralight equipment and off-grid capability. Solar-integrated roof systems and vacuum-insulated panels enable four-season usage patterns.
- Tourists:International visitors seeking mobile accommodation during extended holidays favor fully equipped motorhomes with integrated kitchen and sanitation systems.
Volume leadership sits with Families. Steepest expansion trajectory belongs to Rental Services.
Distribution Channel:
Channel power shifts as digital platforms capture search and comparison behavior before physical inspection.
- Online Retail:Amazon, specialist camping portals, and manufacturer-direct sites dominate camping gear and accessory sales. Inventory velocity advantages concentrate in lightweight, shippable categories.
- Specialty Stores:Dedicated retailers provide hands-on product evaluation and after-sales service for complex purchases. German and UK chains maintain showroom networks for caravan and motorhome sales.
- Supermarkets:Mass-market retailers capture seasonal tent and basic equipment demand through limited summer assortments. Aldi and Lidl promotional cycles drive volume spikes.
- Trade Shows:Düsseldorf Caravan Salon and Birmingham NEC events remain critical for manufacturer product launches and dealer network development. Multi-homologation certification timelines compress traditional show-to-sale cycles.
Online Retail leads by transaction count. Specialty Stores retain margin concentration.
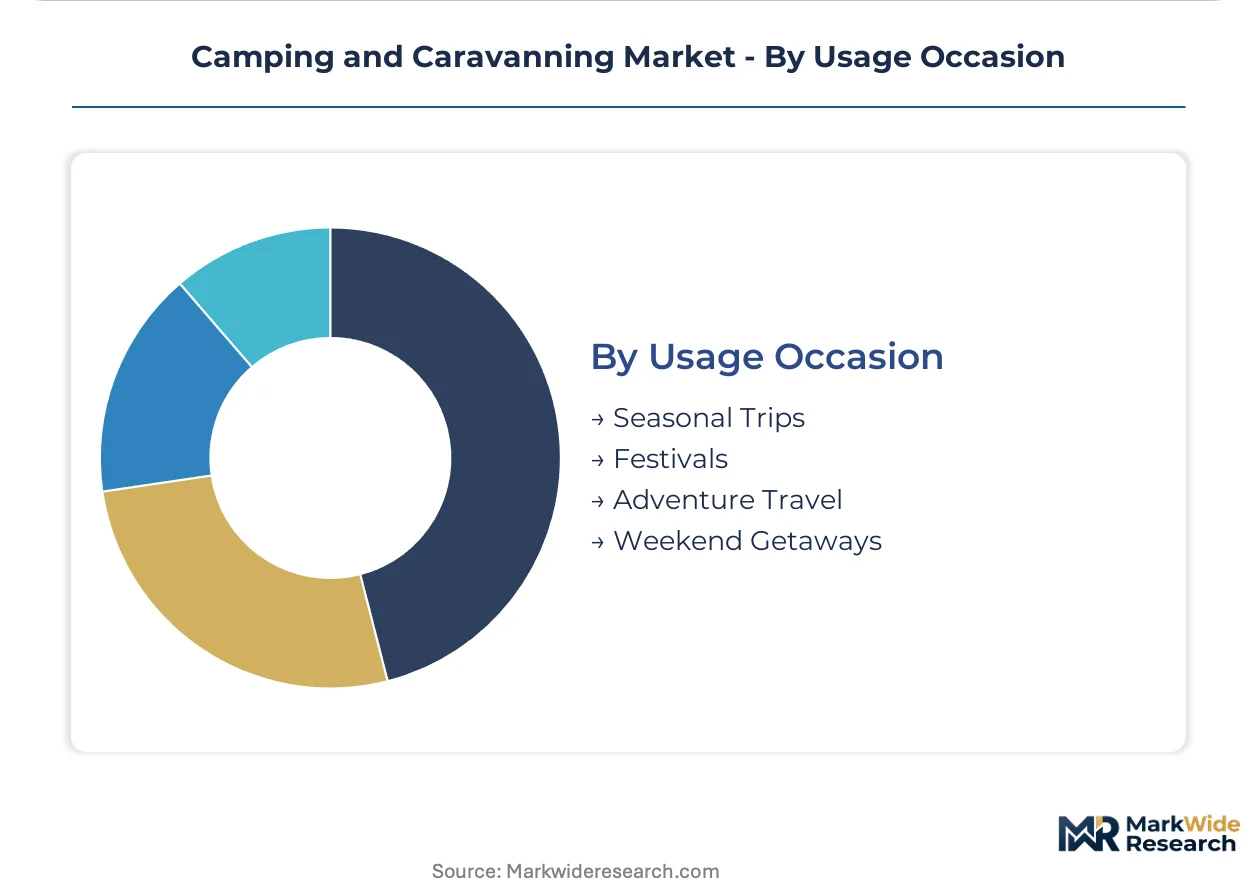
Usage Occasion:
Calendar extension strategies target off-peak utilization as manufacturers compete for limited owner leisure hours.
- Weekend Getaways:Short-duration trips within 150 kilometers of residence dominate utilization frequency. Proximity camping reduces fuel cost sensitivity and enables spontaneous departure.
- Seasonal Trips:Extended summer holidays of one to three weeks sustain caravan park occupancy rates across Mediterranean coastal regions. French municipal subsidies for serviced pitch upgrades reinforce this pattern.
- Adventure Travel:Remote destination camping demands off-grid autonomy and robust chassis construction. Solar-integrated roof laminates and composite polymer alternatives enable self-sufficiency.
- Festivals:Temporary accommodation at music and cultural events drives tent and basic caravan rental demand. UK market shows particular concentration around Glastonbury and Reading events.
Weekend Getaways generate highest trip frequency. Adventure Travel shows strongest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial parks in Baden-Württemberg and Bavaria anchor European caravan manufacturing through specialized lamination clusters and vocational training pipelines.
Germany
Retired couples prioritize extended touring autonomy through self-propelled motorhomes. The KBA enforces Whole Vehicle Type Approval standards on braking and lighting systems. Laminated sidewall production concentrates in Stuttgart and Munich industrial corridors.
United Kingdom
Millennial families convert discretionary leisure spend toward lightweight towable units compatible with smaller passenger vehicles. Municipal subsidies for serviced pitch upgrades pull through demand for higher-specification rental fleets. Birmingham and Manchester host the densest specialty retail showroom networks.
France
International tourists favor fully equipped motorhomes with integrated kitchen and sanitation systems for extended Mediterranean coastal holidays. Regional subsidies for camping infrastructure upgrades reinforce seasonal occupancy patterns. The Auvergne-Rhône-Alpes cluster specializes in propane-based absorption cooling manufacturing.
United States
Outdoor enthusiasts demand off-grid autonomy through solar-integrated roof systems and vacuum-insulated panels. The NHTSA enforces Federal Motor Vehicle Safety Standards on trailer braking and lighting. Indiana and Oregon facilities anchor North American towable production through captive frame manufacturing.
Australia
Adventure travel segments seek robust chassis construction for remote destination camping. The country's national vehicle safety regulator mandates compliance with Australian Design Rules on trailer construction. Queensland and New South Wales coastal regions sustain the highest seasonal pitch occupancy rates.
Camping and Caravanning Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated assemblers commanding premium-tier positioning while component suppliers serve multiple OEMs from standardized platforms. The vendor base organizes around three archetypes: vertically integrated chassis fabricators, specialist lamination houses, and peer-to-peer rental platforms. Competitive moves concentrate on backward integration into composite material supply and geographic expansion through municipal infrastructure partnerships.
Among North American-based assemblers, Winnebago Industries, Thor Industries, and Forest River occupy distinct positions across the motorhome and towable spectrum. Winnebago Industries exemplifies the integrated lamination specialist archetype through in-house material cost control. Thor Industries represents scale-driven manufacturing concentration across multiple facilities. Forest River anchors breadth-based competition through portfolio diversification across entry-level and luxury segments.
| Leading Market Players |
|---|
| Kampgrounds of America (KOA) |
| RVshare |
| Hipcamp |
| Glamping Hub |
| Camplify |
| Outdoorsy |
| Winnebago Industries |
| Thor Industries |
| Forest River |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap assemblers across Baden-Württemberg and Bavaria maintain pricing discipline through captive lamination expertise, while private-equity-rolled rental platforms compress asset utilization economics through dynamic yield management. This ownership fragmentation concentrates supply-side bargaining power with composite material suppliers while fragmenting downstream price-setting authority across peer-to-peer marketplaces.
Pricing Analysis
Short lead-time premiums attach to vacuum-insulated panel configurations and four-season motorhome specifications, while spot inventory of entry-tier caravans clears at distressed levels through supermarket promotional cycles. Three-tier pricing structure across premium composite, standard fiberglass-aluminum, and economy steel-frame tiers reflects certification grade and thermal efficiency ratings. Cost compression in entry trailers intensifies because lead-acid battery systems retain cost advantage over lithium substitution. Rental services exhibit highest price sensitivity due to fleet depreciation schedules, while adventure travel segments absorb premium positioning for off-grid autonomy packages.
Supply Chain Analysis
Single-source vulnerability sits with laminated sidewall production clusters in Stuttgart and Munich industrial corridors, where vacuum-infusion technician scarcity outpaces vocational training output. Manufacturing gravity centers on Germany, France, and the United Kingdom for final assembly, with galvanized steel frames and polymer-composite sandwich panels as critical inputs. Tariff exposure on chassis-grade steel concentrates margin pressure on mid-tier manufacturers without captive metallurgy contracts. Distribution runs through specialty retail showroom networks in Birmingham and Manchester, with online retail capturing camping gear velocity through Amazon and specialist portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite polymer chassis construction is displacing conventional aluminum and fiberglass across premium caravan lines, forcing incumbents to recalibrate material cost curves and supplier relationships. This technology-transition phase rewards backward integration into lamination expertise while penalizing asset-heavy aluminum extrusion exposure.
For Market Incumbents: Lock in captive supply of vacuum-insulated panels and resin-transfer molding capacity before composite technician scarcity worsens. Defend margin position by securing multi-homologation certification pipelines across NHTSA and EU Whole Vehicle Type Approval standards, insulating against regulatory delay risks that extend product launch cycles. For New Entrants and Emerging Players: Launch via peer-to-peer rental platform models in UK and Netherlands markets where urban density limits full ownership practicality. Target municipal camping infrastructure partnerships in France as the most penetrable geography, leveraging regional subsidies for serviced pitch upgrades to pull through fleet demand without manufacturing capital intensity. For Investors and Strategic Acquirers: F-Gas Regulation compliance timelines accelerating propane-based absorption cooling adoption is the leading indicator that component supplier consolidation will precede assembler margin recovery. Long-term viability favors vertically integrated lamination specialists with in-house material science capabilities over pure-play assemblers exposed to aluminum cost volatility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Composite Lamination | Captive supply of polymer sandwich panels insulates Thor Industries and Winnebago from aluminum cost swings. |
| Peer-to-Peer Rental Platform Expansion | RVshare and Outdoorsy convert dormant owner assets into fractional-income streams without capacity expansion. |
| Propane-Based Cooling System Redesign | Auvergne-Rhône-Alpes suppliers engineer absorption cycles compliant with EU F-Gas phasedown mandates. |
| Municipal Infrastructure Partnership | French regional subsidies for serviced pitch upgrades create pull-through demand for higher-specification rental fleets. |
| Multi-Homologation Certification Investment | Simultaneous NHTSA and EU compliance compresses show-to-sale cycles at Düsseldorf Caravan Salon launches. |
Methodological Framework
Trade association filings, customs records for caravan and motorhome imports, and SEC 10-K disclosures from publicly listed assemblers formed the secondary backbone. Primary interviews with lamination technicians, caravan park operators, rental platform fleet managers, and KBA certification officers combined with bottom-up and top-down triangulation to validate segment sizing.
Bottom-up modeling built unit economics from material input costs and assembly labor rates, while top-down cross-checks applied demographic leisure spending patterns across millennial family cohorts. Segmentation dimensions included product type, end-user archetype, distribution channel, and usage occasion across the projection horizon. CAGRs derived from historical production data and forward capacity announcements, with EU F-Gas compliance timelines and lithium battery substitution curves as industry-specific forecast inputs.
Regulatory delay, composite material cost volatility, and rental platform yield compression are the dominant revision risks that could recalibrate powertrain and ownership model trajectories. Forecasts reflect documented assumptions about technician training pipeline output and municipal subsidy continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Incentive Travel Market
Travel and Tourism
Surfing Tourism Market
Travel and Tourism
Asia-Pacific MICE Tourism Market
Travel and Tourism
Singapore Travel Retail Market
Travel and Tourism
Greece Tourism Market
Travel and Tourism
Yacht Charter Market
Travel and Tourism
Special Interest Tourism Market
Travel and Tourism
France Culinary Tourism Market
Travel and Tourism
Middle East and Africa Travel Retail Market
Travel and Tourism
Yoga Tourism Market
Travel and Tourism
India Wellness Tourism Market
Travel and Tourism
Europe Driving Vacation Market
Travel and Tourism
USA Sports Tourism Market
Travel and Tourism
Global Ecotourism Market
Travel and Tourism
Tourism Vehicle Rental Market
Travel and Tourism
Hong Kong Outbound Tourism Market