
 Tourism Vehicle Rental Market | 2026-2036
Tourism Vehicle Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Tourism Vehicle Rental Market Intelligence
Telematics integration with mobile-native booking platforms is narrowing the operational gap between legacy fleet operators and digital-first entrants. Enterprise Holdings leverages its airport concession network to sustain dominant pickup location coverage. Avis Budget Group anchors its competitiveness through centralized fleet rebalancing algorithms. Sixt SE differentiates via premium vehicle specialization in European urban centers.
Tourism vehicle rental denotes the short-term commercial provision of motorized transport—ranging from compact passenger cars to Class C motorhomes—through daily, weekly, or multi-month contracts, with fleet maintenance governed by manufacturer service intervals and local roadworthiness certifications. The primary commercial purpose centers on substituting ownership for travelers requiring temporary mobility at destinations away from their residence. Cars and SUVs command the largest installed rental base, though motorhomes capture disproportionate margin per rental day due to lower fleet depreciation velocity and higher ancillary revenue attachment. Online distribution channels are displacing traditional counter-based bookings fastest, while luxury service categories retain pricing power through corporate travel agency relationships.
Fleet emissions standards enforced by the EPA in the United States, EU Green Deal vehicle targets under European Commission oversight, and China's dual carbon goals administered by MEE collectively mandate accelerated electrification of rental inventories. These frameworks elevate capital expenditure requirements while restricting internal combustion engine fleet renewals in regulated jurisdictions. Operators must weigh battery electric vehicle total cost of ownership against residual value uncertainty when structuring procurement timelines.
Market Dynamics
The EU F-Gas Regulation and EPA fleet emissions standards are compressing internal combustion engine procurement timelines while elevating battery electric vehicle capital requirements across rental portfolios.
Growth Catalysts
- Leisure road trip extension:Extended domestic and cross-border driving vacations are stretching average rental durations from weekend bookings into multi-week contracts, improving fleet utilization rates during shoulder seasons.
- EU Green Deal vehicle targets:The European Commission's mandated electrification trajectory is channeling public and private capital toward charging infrastructure density at tourism corridors, reducing range anxiety for rental customers.
- Peer-to-peer platform maturation:Digital-native operators are aggregating underutilized private vehicle inventory into commercial rental pools, expanding addressable fleet supply without balance-sheet expansion.
Market Restraints
- Battery residual value uncertainty:Rapid electric vehicle technology iteration and chemistry shifts are compressing secondary market valuations, complicating fleet depreciation schedules and lease-end pricing.
- Seasonal demand concentration:Mediterranean coastal markets exhibit 4-5x summer volume spikes versus winter troughs, forcing fleet idling or costly inter-regional rebalancing during off-peak months.
- Charging infrastructure asymmetry:Rural tourism destinations and secondary airports lack sufficient high-speed charging density, constraining electric fleet deployment outside urban nodes.
Strategic Opportunities
- Motorhome category expansion:Class C and camper van segments command premium daily rates with lower per-unit depreciation velocity, offering margin expansion potential for operators with specialized maintenance capabilities.
- Telematics-integrated insurance products:Real-time driving behavior data enables usage-based coverage pricing, creating ancillary revenue streams and risk selection advantages over traditional fleet policies.
- Corporate travel agency channel deepening:Luxury and executive vehicle categories retain pricing power through managed travel relationships, insulating premium tiers from price compression in leisure segments.
Industry Challenges
- Electric vehicle technician scarcity:High-voltage battery diagnostics and powertrain maintenance require specialized certification pathways that outpace current vocational training program output.
- Legacy fleet management system integration:Established reservation and yield management platforms require substantial middleware development to interface with telematics APIs and dynamic pricing engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tourism Vehicle Rental Market |
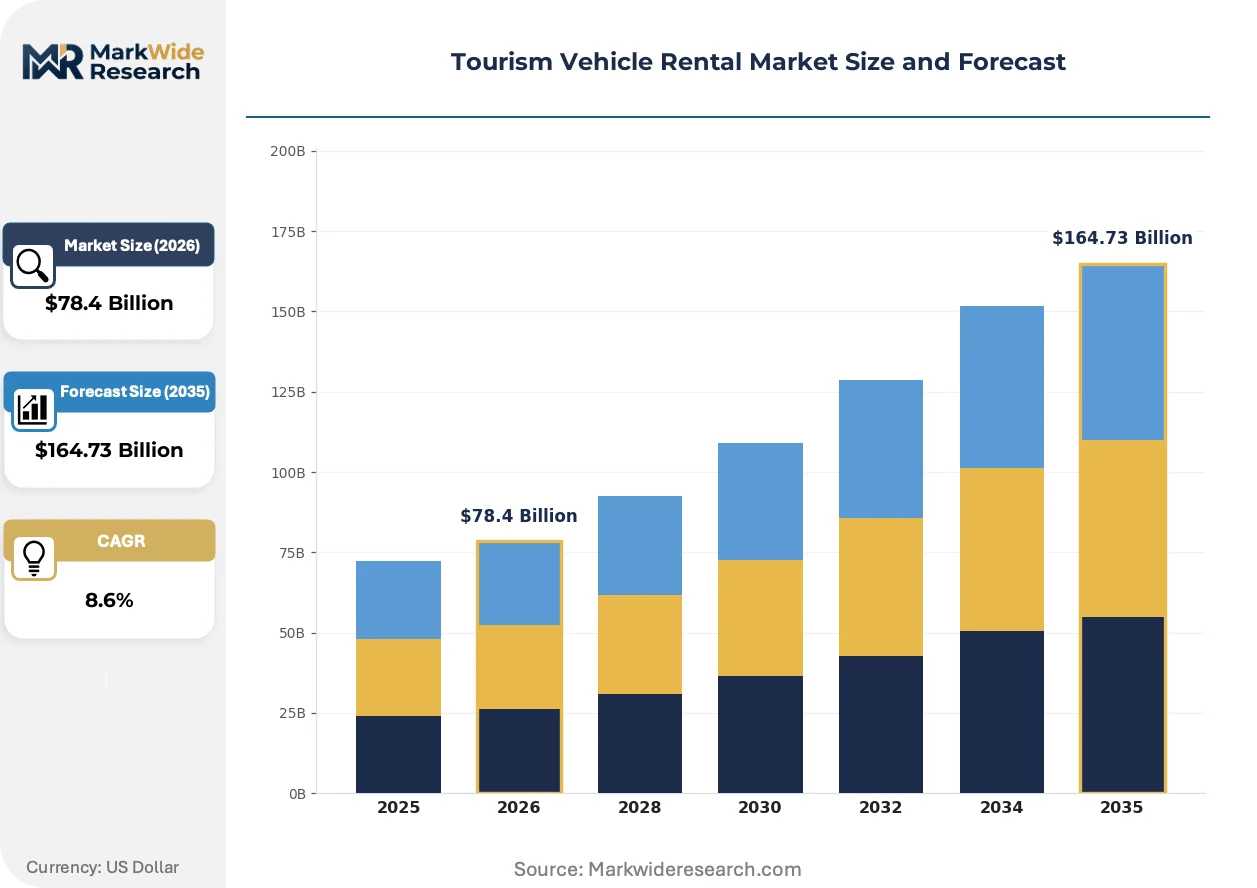
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $164.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Cars, Vans, SUVs, Motorhomes Rental Duration: Daily, Weekly, Monthly, Long-term Service Category: Luxury, Budget, Economy, Premium Distribution Channel: Online, Offline, Travel Agencies, Direct Rentals |
| Companies Covered | Enterprise Holdings, Avis Budget Group, Hertz Global Holdings, Europcar Mobility Group, Sixt SE, Booking.com, Expedia Group, National Car Rental, Alamo Rent A Car, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tourism Vehicle Rental Market Strategic Shifts & Innovations
Mobile-native booking interfaces and embedded telematics are collapsing the operational gap between asset-heavy incumbents and digital-first entrants across pickup location density and fleet visibility.
Connected vehicle platforms aggregating GPS location, fuel state, and diagnostic codes into single-pane operator dashboards are digitizing fleet rebalancing decisions. Traditional counter-based operators are deploying these systems to match digital-native competitors' real-time availability transparency. The structural consequence is compression of yield management latency from daily to hourly optimization cycles.
China's dual carbon goals administered by MEE are accelerating domestic electric vehicle procurement mandates for commercial fleet operators. Domestic manufacturers are prioritizing battery supply contracts with rental aggregators to secure volume offtake. The rental segment most affected is airport-based operators in tier-one cities, where charging infrastructure density supports full-electric commitments.
Subscription-based mobility packages are displacing traditional daily-rate structures among frequent leisure travelers. These contracts bundle insurance, maintenance, and vehicle swaps into fixed monthly fees, capturing customer lifetime value across multiple trips. Spain's coastal tourism corridors exhibit the fastest uptake, where seasonal residents prefer flexible vehicle access without ownership burdens.
Tourism Vehicle Rental Market Segmentation
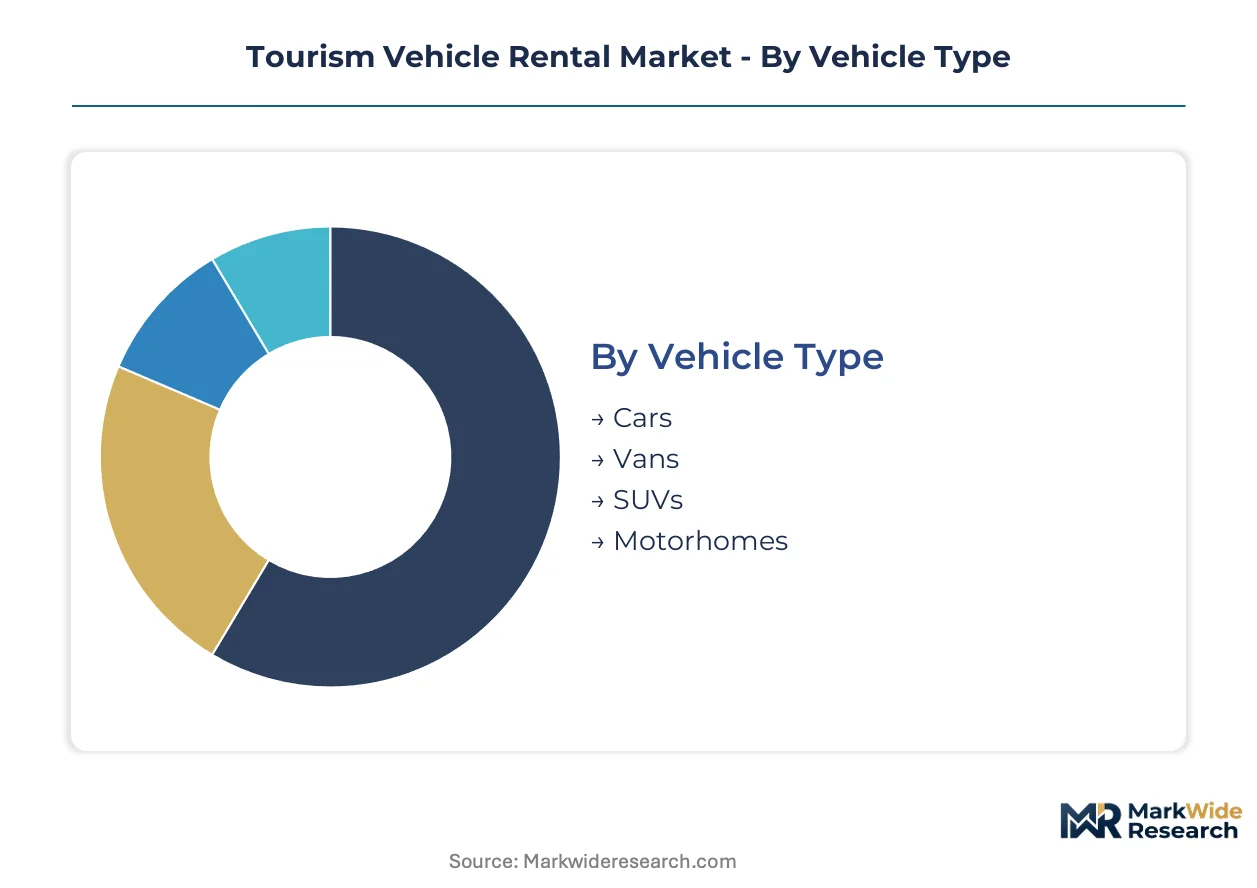
Fleet composition and booking modality choices determine capital intensity and yield management complexity for tourism vehicle rental operators. Segment-level differentiation shapes maintenance protocols, insurance structures, and channel economics across regional markets.
Vehicle Type:
After-sales service intensity varies dramatically across vehicle categories, with powertrain complexity and utilization patterns dictating workshop capacity planning and spare parts inventory requirements.
- Cars:Compact and mid-size passenger vehicles dominate fleet depreciation schedules due to high turnover velocity and standardized maintenance intervals. Demand concentrates in Spain's coastal tourism corridors where summer fleet utilization peaks force rapid brake and tire replacement cycles.
- Motorhomes:Class C and camper van configurations carry extended service intervals for chassis components while requiring specialized habitation system maintenance. Demand concentrates in German and Dutch source markets for Mediterranean touring routes, with lower per-kilometer depreciation offsetting higher acquisition costs.
- Vans:Commercial-derived passenger variants serve group travel and equipment-intensive leisure segments with reinforced suspension requirements.
- SUVs:All-terrain capability commands rate premiums in alpine and Nordic destinations where seasonal weather conditions drive 4WD specifications.
Cars hold the largest share; momentum sits with motorhomes as extended road trip duration expands.
Rental Duration:
Contract length directly correlates with pricing elasticity and customer acquisition cost recovery timelines, with structural differences in fleet planning horizons across duration tiers.
- Long-term:Multi-month contracts spanning 90+ days enable seasonal fleet rotation strategies and reduced per-transaction overhead. Demand concentrates among remote workers and digital nomads in Portugal's Algarve region where winter residency patterns stretch traditional tourism seasonality.
- Monthly:30-day rolling agreements capture subscription-oriented travelers seeking flexibility without ownership burdens. Demand concentrates in peer-to-peer platform inventory where private vehicle utilization gaps align with extended leisure booking windows.
- Daily:Single-day urban and airport pickups maximize revenue per available vehicle day through aggressive yield management.
- Weekly:Seven-day blocks dominate traditional vacation package bundling through travel agency channels.
Daily rentals retain volume dominance; monthly contracts are climbing the fastest as subscription models displace episodic booking.
Service Category:
Capital deployment per unit and residual value risk profiles stratify sharply across service tiers, with premium positioning requiring differentiated fleet age management and reconditioning standards.
- Economy:High-mileage, older fleet vintages minimize per-unit capital at risk while maximizing asset sweated life. Demand concentrates in price-sensitive leisure segments booking through online aggregators with minimal brand loyalty.
- Luxury:Premium marques and executive configurations sustain pricing power through corporate travel agency relationships and event-driven demand. Demand concentrates in London, Paris, and Milan urban centers where diplomatic and financial services clientele require chauffeur-ready specifications.
- Budget:Stripped-down service levels with limited included mileage and insurance coverage target cost-optimized segments.
- Premium:Near-new fleet age and inclusive service bundles bridge economy and luxury positioning for aspirational leisure travelers.
Economy commands unit volume leadership; luxury shows steepest expansion trajectory as corporate travel recovery accelerates.
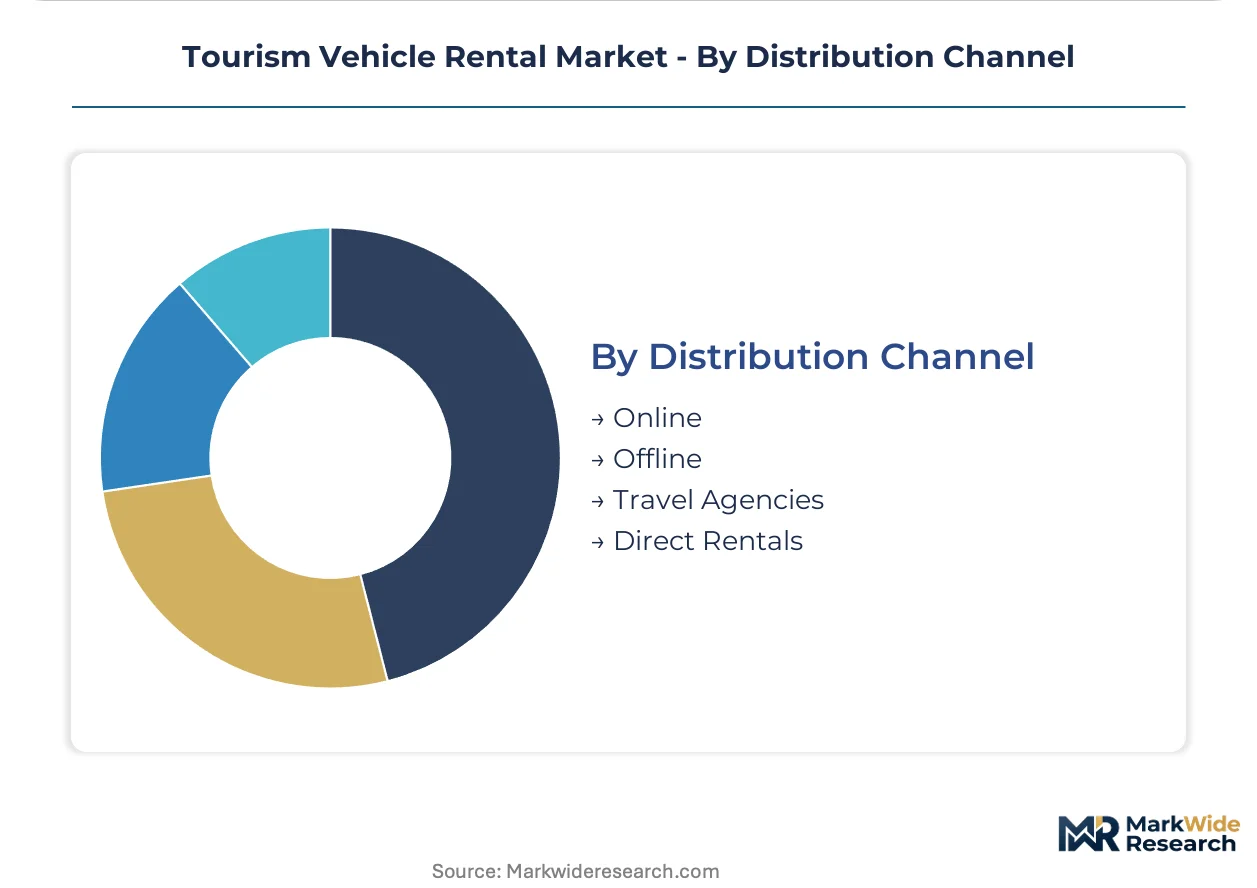
Distribution Channel:
Customer acquisition economics and fleet visibility capabilities diverge fundamentally between digital-native platforms and legacy counter-based infrastructure.
- Online:Mobile-native booking interfaces aggregate inventory visibility across fragmented supplier bases while collapsing search-to-transaction friction. Demand concentrates in millennial and Gen-Z leisure segments prioritizing instant confirmation and digital check-in workflows.
- Travel Agencies:Managed corporate travel relationships and package tour bundling sustain offline intermediation for complex multi-leg itineraries. Demand concentrates in German-speaking markets where TUI and DER Touristik maintain strong retail presence.
- Offline:Airport and downtown counter locations capture walk-up demand and service recovery scenarios requiring human intervention.
- Direct Rentals:Operator-owned websites and loyalty program channels bypass intermediary commissions while capturing customer data for repeat targeting.
Online channels hold transaction volume leadership; direct rentals are gaining share fastest as operators invest in loyalty infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German motorhome manufacturers export Class C vehicles to Dutch and British leisure travelers booking Mediterranean touring routes. Spain's coastal corridors absorb peak summer fleet demand from northern European source markets.
United States
Domestic road trip extension drives multi-week rental contracts through national park corridors. EPA fleet emissions standards compress internal combustion engine procurement timelines for airport-based operators. Florida's Orlando and Miami metropolitan clusters concentrate winter fleet utilization spikes from snowbird migration patterns.
Germany
Motorhome manufacturing anchors export demand to Mediterranean tourism destinations via Dutch and Scandinavian intermediary markets. KBA vehicle certification requirements govern rental fleet roadworthiness standards for cross-border operations. Bavaria's Munich-Stuttgart corridor hosts premium vehicle specialization clusters serving executive travel segments.
Spain
Coastal tourism corridors exhibit extreme seasonal demand concentration with summer volume multiples over winter troughs. EU Green Deal vehicle targets channel charging infrastructure investment toward Costa del Sol and Balearic Islands nodes. Barcelona and Madrid urban centers sustain year-round utilization through business travel agency relationships.
China
Domestic leisure travel recovery drives airport-based rental demand in tier-one city clusters. MEE-administered dual carbon goals accelerate electric vehicle procurement mandates for commercial fleet operators. Shanghai and Beijing metropolitan areas concentrate charging infrastructure density supporting full-electric fleet commitments.
France
Alpine destination demand commands all-terrain SUV rate premiums during winter ski seasons. ANSM and CNIL data governance frameworks shape telematics deployment for usage-based insurance products. Paris Île-de-France anchors luxury service category pricing power through diplomatic and financial services clientele.
Tourism Vehicle Rental Market Key Industry Players
On the supply side, the industry is consolidating around airport concession networks and digital platform aggregation. Legacy fleet operators with centralized rebalancing capabilities compete against peer-to-peer inventory aggregators. Two strategic archetypes dominate: asset-heavy incumbents leveraging physical location density, and asset-light digital natives optimizing private vehicle utilization gaps. Competitive moves concentrate on telematics integration partnerships and subscription-based mobility package launches.
Among US-based holding companies, Enterprise Holdings and Avis Budget Group exemplify airport concession network dominance. Sixt SE occupies a position within the European premium specialization tier. Booking.com and Expedia Group represent digital platform aggregators collapsing search-to-transaction friction across fragmented supplier bases.
| Leading Market Players |
|---|
| Enterprise Holdings |
| Avis Budget Group |
| Hertz Global Holdings |
| Europcar Mobility Group |
| Sixt SE |
| Booking.com |
| Expedia Group |
| National Car Rental |
| Alamo Rent A Car |
| Others |
Cost & Logistics Intelligence
German motorhome chassis manufacturing concentrates upstream capacity for Mediterranean-bound fleet operators, anchoring margin pools in specialized habitation system integration and seasonal rebalancing services rather than commodity vehicle procurement. Battery electric vehicle procurement timelines compress as EU F-Gas Regulation enforcement elevates capital requirements across rental portfolios.
Pricing Analysis
Internal combustion engine fleet rates trade at prior-generation discounts against battery electric vehicle premiums reflecting charging infrastructure access and residual value risk. Three-tier pricing structure across premium, standard, and economy levels stratifies by fleet age, included mileage thresholds, and telematics-enabled insurance bundling. Cost compression in economy tiers intensifies because peer-to-peer platform aggregation floods price-sensitive segments with underutilized private inventory. Corporate travel agency channels exhibit lowest price sensitivity due to managed travel policy compliance requirements.
Supply Chain Analysis
Contract manufacturing for rental fleet vehicles concentrates with Stellantis, Volkswagen Group, and Ford commercial vehicle divisions holding dedicated rental-specification capacity. Vehicle assembly draws from Germany, Spain, and Czech Republic production hubs while battery cell supply rests on South Korean and Chinese chemistry suppliers. Single-source vulnerability in semiconductor content for telematics and advanced driver assistance systems exposes fleet delivery timelines. Distribution runs through manufacturer fleet sales divisions, rental operator direct procurement, and peer-to-peer platform aggregator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against ride-hailing and micro-mobility substitution eroding urban short-rental demand, requiring fleet specialization strategies that escape commodity price competition.
For Market Incumbents: Pre-empt peer-to-peer platform encroachment by embedding telematics-enabled subscription mobility packages capturing customer lifetime value across multiple trips. Accelerate electric vehicle technician certification partnerships with vocational training institutions to close service capacity gaps before battery fleet scale-up. Vertical integration into charging infrastructure at airport concession nodes creates location-level moats against digital-native aggregators lacking physical asset control.
For New Entrants and Emerging Players: Motorhome category specialization in Mediterranean coastal corridors represents the most penetrable entry point given incumbent underinvestment in habitation system maintenance capabilities. Peer-to-peer platform aggregation of Dutch and German source market private inventory for Spanish destination delivery captures seasonal demand spikes without balance-sheet fleet exposure. Direct-to-consumer subscription positioning bypasses travel agency commission structures while building proprietary customer data assets.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional rental operators holding airport concession networks in tier-two European tourism destinations. Five-to-ten year viability hinges on electric fleet transition execution speed and charging infrastructure partnership depth. Monitor EU Green Deal vehicle target compliance cost pass-through to rental rates as the inflection indicator for margin sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Real-time fleet visibility collapses yield management latency from daily to hourly optimization cycles. |
| Electric Fleet Procurement Acceleration | EU F-Gas Regulation compliance mandates battery electric vehicle share expansion ahead of residual value stabilization. |
| Subscription Mobility Package Launch | Fixed monthly fee bundling captures customer lifetime value across episodic leisure travel patterns. |
| Airport Charging Infrastructure Partnership | Concession network electrification secures location dominance against asset-light platform competitors. |
| Motorhome Service Capability Buildout | Specialized habitation maintenance commands premium daily rates with lower depreciation velocity. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet procurement directors, yield management analysts, airport concession managers, and peer-to-peer platform operators. Secondary validation drew from EPA fleet emissions filings, EU Green Deal regulatory texts, KBA vehicle certification databases, and airport authority concession bid documents. Bottom-up fleet inventory modeling triangulated against top-down tourism expenditure projections across the analysis window.
Calibration anchored volume and value outputs to historical fleet utilization rates, seasonal demand concentration patterns, and electric vehicle procurement commitment announcements. Segmentation dimensions spanned vehicle type, rental duration tier, service category positioning, and distribution channel architecture. CAGRs were derived from regression analysis against macro tourism indicators and regulatory compliance cost trajectories. Forecast inputs incorporated charging infrastructure deployment schedules and battery residual value depreciation curves.
Macroeconomic conditions sit as an overlay; deviation in leisure travel expenditure, cross-border mobility policy, or battery technology cost curves would shift the trajectory. Forecasts reflect documented assumptions regarding EU F-Gas Regulation enforcement timing and electric vehicle secondary market depth. Cross-checking against national tourism board arrival statistics and airport passenger traffic benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Asia-Pacific Travel Retail Market
Travel and Tourism
Asia-Pacific MICE Tourism Market
Travel and Tourism
North America Travel Retail Market
Travel and Tourism
North America Driving Vacation Market
Travel and Tourism
Inflight Shopping Market
Travel and Tourism
Global Ecotourism Market
Travel and Tourism
UK Outbound Travel Market
Travel and Tourism
Bleisure Tourism Market
Travel and Tourism
Latin America Inflight Services Market
Travel and Tourism
China Outbound Travel Market
Travel and Tourism
Africa Wellness Tourism Market
Travel and Tourism
Yacht Charter Service Market
Travel and Tourism
Wedding Tourism Market
Travel and Tourism
Middle East and Africa Travel Retail Market
Travel and Tourism
North America Pet Travel Services Market
Travel and Tourism
Global Golf Travel Market