
 Surfing Tourism Market | 2026-2036
Surfing Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Surfing Tourism Market Analytics
Premium eco-certified surf camp tier is rotating toward the center of operator investment. Wavehunters Surf Travel Pty Ltd leverages direct charter partnerships across the Pacific Rim to sustain margin capture. The Perfect Wave Travel anchors its portfolio on guided tour logistics spanning Indonesia, Fiji, and the Maldives. Mojosurf Pty Ltd differentiates through beginner-focused camp infrastructure along Australia's eastern seaboard.
Surfing tourism comprises destination-based recreational travel where participants engage in wave riding across coastal or reef break environments, typically requiring equipment provision, instructional services, and accommodation bundled into multi-day itineraries. Operators coordinate watercraft access, local guide certification, and marine conservation fees as core functional parameters to deliver safe, repeatable surf experiences in remote locations. Luxury and eco-tourism type segments command premium pricing through carbon-offset partnerships and reef restoration levies, while adventure and group tour categories compete on volume throughput and seasonal discounting. Surf camps and guided tours within activity type segmentation generate recurring revenue through repeat-booking loyalty programs, whereas competition-based travel remains episodic and sponsor-dependent.
Indonesia's Ministry of Tourism and Creative Economy coordinates with the International Surfing Association on athlete visa facilitation and break preservation zoning. Australia's Great Barrier Reef Marine Park Authority enforces seasonal access limits that constrain peak-period operator capacity. Hawaii's Department of Land and Natural Resources mandates reef-safe sunscreen compliance and coral impact assessments for commercial permits. Stakeholders must monitor evolving marine protected area expansions and their permit allocation mechanisms to secure long-term access to priority break locations.
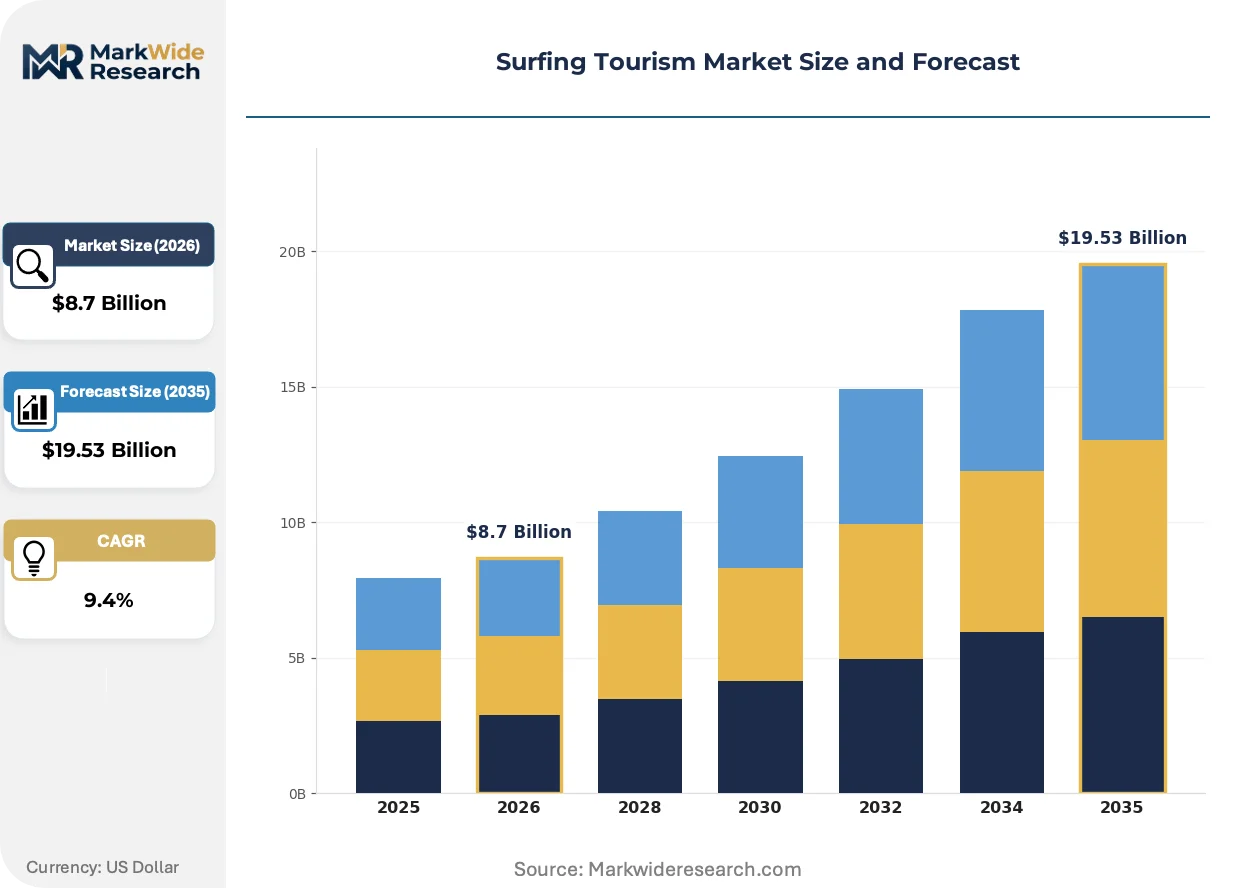
Market Dynamics
Olympic inclusion protocols and reef-safe sunscreen mandates are compressing operator compliance timelines while charter boat density in Indonesia's Mentawai Islands concentrates supply-side investment around premium eco-certified camp tiers.
Growth Catalysts
- ISA Olympic Protocol:The International Surfing Association's standardized athlete visa facilitation expands competition tourism pipelines into Indonesia, Portugal, and Japan.
- Reef Restoration Levies:Carbon-offset partnerships bundled into luxury itineraries attract ESG-mandated corporate retreat budgets.
- Charter Infrastructure:Direct boat partnerships across the Pacific Rim reduce intermediary costs for remote break access.
Market Restraints
- Seasonal Access Limits:Australia's Great Barrier Reef Marine Park Authority constrains peak-period operator capacity through permit quotas.
- Input Cost Volatility:Marine fuel prices and vessel maintenance costs fluctuate with crude benchmarks, squeezing charter margins.
- Permit Allocation Risk:Hawaii's Department of Land and Natural Resources coral impact assessments create multi-month approval bottlenecks for new commercial entrants.
Strategic Opportunities
- Beginner Camp Expansion:Australia's eastern seaboard remains underpenetrated for novice-focused infrastructure compared to Indonesia's expert concentration.
- Guided Tour Logistics:Multi-destination itineraries spanning Fiji and the Maldives capture repeat-booking loyalty through portfolio breadth.
- Marine Protected Area Partnerships:Conservation fee structures in Palau and Hawaii create regulatory tailwinds for premium pricing differentiation.
Industry Challenges
- Guide Certification Bottlenecks:Local water safety credentials and ISA instructor qualifications require 6-18 month training pipelines in remote archipelagos.
- Capex Intensity:Vessel acquisition and camp infrastructure demand upfront capital that conflicts with seasonal cash flow cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surfing Tourism Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Adventure, Eco-tourism, Luxury, Group Tours Experience Level: Beginner, Intermediate, Advanced, Professional Activity Type: Surf Camps, Competitions, Rentals, Guided Tours Customer Type: Families, Solo Travelers, Couples, Groups |
| Companies Covered | Channel Islands Surfboards Inc., Wavehunters Surf Travel Pty Ltd, The Perfect Wave Travel, Waterways Surf Adventures, Mojosurf Pty Ltd, World Surfaris Pty Ltd, Body Glove International LLC, Nomad Surfers, LineUpEXplorers GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surfing Tourism Market Evolving Landscape
Digital booking platforms and predictive wave forecasting tools are compressing traditional travel agency intermediation while reshaping how operators manage inventory and guest expectations across dispersed coastal destinations.
Artificial intelligence-powered swell prediction algorithms is fragmenting how charter operators schedule vessel deployments and price daily slots. Mid-tier surf camps in Indonesia and Fiji adopt these tools fastest, shifting from fixed weekly rotations to dynamic daily availability. This compression of planning horizons is fragmenting traditional package tour economics and forcing smaller operators into revenue-sharing partnerships with platform intermediaries.
The EU's Corporate Sustainability Reporting Directive and expanding marine protected area designations in the Pacific are tightening disclosure requirements for tourism operators accessing sensitive reef ecosystems. Commercial permit holders in Hawaii and Palau must now document reef-safe sunscreen compliance and coral impact mitigation expenditures in annual filings. Luxury segment operators absorb these costs through premium pricing, while volume-focused camps face margin compression or exit pressures.
Direct-to-consumer booking via specialized surf travel platforms is displacing traditional travel agency channels for multi-day camp reservations. Indonesian operators report 40-60% of reservations now originate through Instagram and dedicated surf travel apps rather than legacy wholesalers. This channel shift concentrates marketing spend on visual content production and influencer partnerships, particularly among millennial and Gen-Z demographics booking Mentawai charters.
Surfing Tourism Market Segmentation
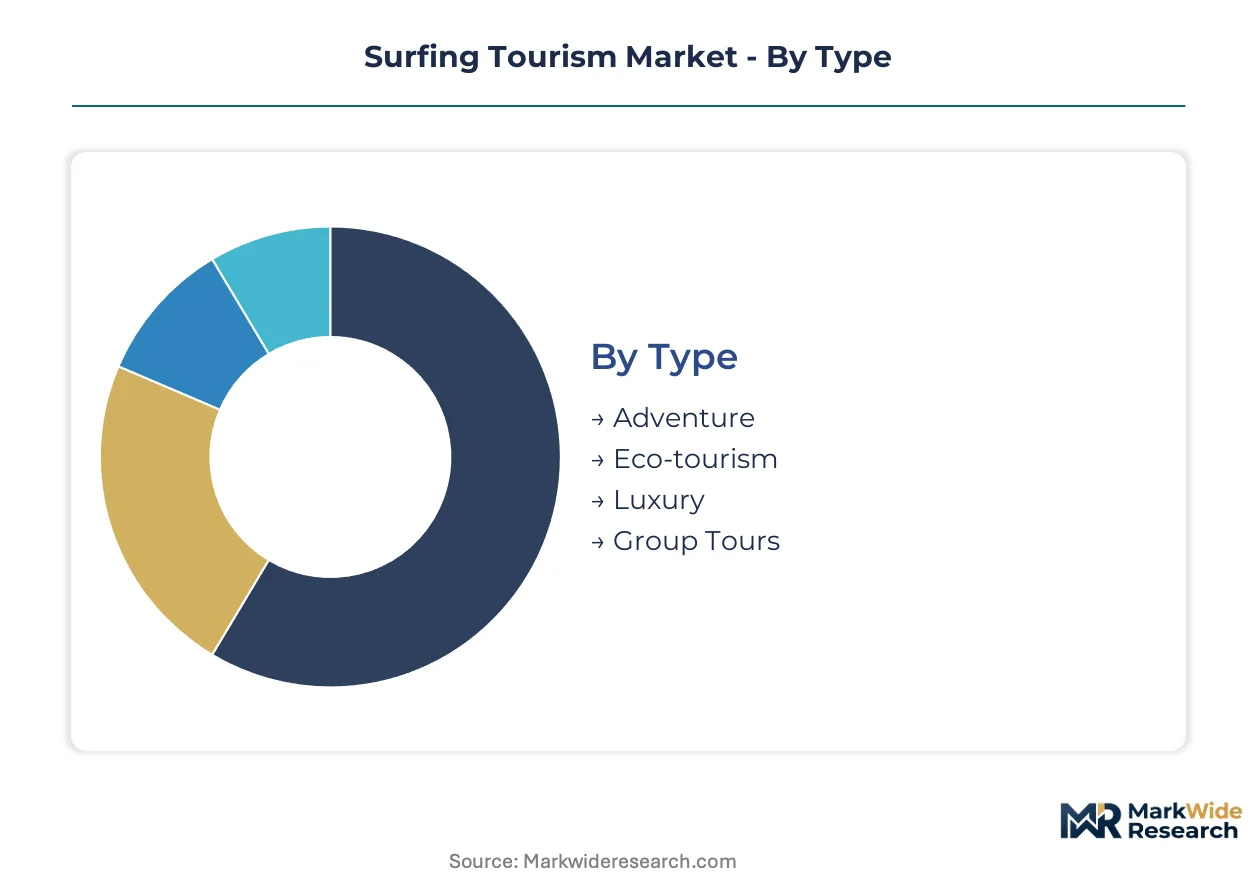
Surfing tourism operators calibrate inventory and pricing through distinct segmentation lenses, each revealing divergent channel economics and guest acquisition costs. Understanding how luxury eco-tourism diverges from volume adventure packages shapes capital allocation across camp infrastructure and charter partnerships.
Type:
Channel mix varies sharply by tourism type, with luxury and eco-tourism flowing through direct booking platforms and corporate retreat planners, while adventure and group tours rely on wholesale aggregators and seasonal discount channels.
- Luxury:Carbon-offset partnerships and reef restoration levies bundle into premium itineraries targeting ESG-mandated corporate retreat budgets. Demand concentrates in Fiji and the Maldives where charter vessel specifications and private guide ratios justify per-guest pricing multiples above standard tiers.
- Eco-tourism:Reef-safe sunscreen compliance and coral impact assessments in Hawaii and Palau create regulatory tailwinds for certified operators. Palau's conservation fee structures and Hawaii's Department of Land and Natural Resources permit requirements favor established players with documented mitigation expenditures.
- Adventure:Volume throughput and seasonal discounting dominate economics, with Indonesian operators leveraging fixed weekly rotations to maximize berth occupancy during shoulder seasons.
- Group Tours:Wholesale channel dependence compresses margins but delivers predictable occupancy through European and Australian outbound tour operator contracts.
By volume, Adventure leads. By growth pace, Eco-tourism is ahead.
Experience Level:
Cost tier stratification separates beginner infrastructure investments from advanced break access economics, with intermediate segments capturing the widest margin spread through equipment rental and instruction bundling.
- Beginner:Australia's eastern seaboard hosts purpose-built camp infrastructure with shallow reef alternatives and ISA-certified instructor pools. Mojosurf Pty Ltd anchors this tier through dedicated novice facilities spanning Byron Bay to Noosa.
- Intermediate:Equipment rental and progressive break access generate recurring revenue through multi-week skill development packages. Indonesia's Mentawai Islands and Fiji's Tavarua region concentrate demand for guided reef pass transitions.
- Advanced:Charter boat density in Indonesia's archipelagos and Pacific Rim direct partnerships reduce intermediary costs for remote break access. Wavehunters Surf Travel Pty Ltd sustains margin capture through exclusive vessel arrangements.
- Professional:ISA Olympic protocol visa facilitation and competition tourism pipelines concentrate episodic demand around Indonesia, Portugal, and Japan event calendars.
By participation volume, Beginner dominates. By revenue per guest, Professional commands the steepest premium.
Activity Type:
Customer type dictates activity selection, with families and couples gravitating toward surf camps and guided tours while solo travelers and groups split between competition spectating and rental-based exploration.
- Surf Camps:Multi-day accommodation bundling with instruction and equipment generates recurring revenue through repeat-booking loyalty programs. The Perfect Wave Travel leverages portfolio breadth across Indonesia, Fiji, and the Maldives to capture return guests.
- Guided Tours:Multi-destination logistics spanning archipelagos require marine conservation fee coordination and local guide certification compliance. Australia's Great Barrier Reef Marine Park Authority seasonal access limits constrain peak-period operator capacity.
- Competitions:Sponsor-dependent episodic revenue concentrates around ISA calendar events with athlete visa facilitation requirements.
- Rentals:Equipment provision without instruction or accommodation yields the lowest margin but captures spontaneous demand at high-traffic break locations.
By booking frequency, Surf Camps lead. By expansion trajectory, Guided Tours are climbing the fastest.
Customer Type:
Supply concentration aligns with customer composition, with family-oriented infrastructure clustering in Australia's supervised beach zones while solo traveler demand concentrates in Indonesia's charter-dependent archipelagos.
- Families:Safety-certified instruction and shore-based accommodation preferences drive demand toward Australia's eastern seaboard and Hawaii's regulated beach concessions.
- Solo Travelers:Digital platform booking and flexible itinerary modifications favor Indonesian charter operations with dynamic daily availability.
- Couples:Premium eco-certified camp tiers in Fiji and the Maldives capture paired bookings through carbon-offset partnership marketing.
- Groups:Wholesale contract economics and fixed-date commitments align with European outbound tour operator seasonality patterns.
By absolute participant count, Solo Travelers lead. By value per booking, Couples are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Charter boat density in Indonesia's Mentawai Islands and Australia's eastern seaboard camps concentrate supply-side investment. Municipalities from Portugal to Hawaii embed surf infrastructure within destination marketing budgets. Regulatory frameworks in Palau and Hawaii reshape operator compliance through reef-safe mandates and coral impact assessments.
Indonesia
Mentawai Islands charter operations and land-based camp development outpace other archipelagos in vessel deployment density. The Ministry of Tourism and Creative Economy coordinates with the International Surfing Association on athlete visa facilitation and break preservation zoning. Bali and Lombok host supervised beginner infrastructure with ISA-certified instructor pools.
Australia
Byron Bay to Noosa camp corridors anchor beginner-focused infrastructure along the eastern seaboard. The Great Barrier Reef Marine Park Authority enforces seasonal access limits that constrain peak-period operator capacity through permit quotas. Queensland's supervised beach zones cluster family-oriented safety-certified instruction facilities.
United States
Hawaii concentrates competition tourism pipelines and luxury eco-certified camp tiers through reef restoration levy structures. The Department of Land and Natural Resources mandates reef-safe sunscreen compliance and coral impact assessments for commercial permits. Oahu and Maui host regulated beach concessions with documented mitigation expenditure requirements.
Portugal
ISA Olympic protocol visa facilitation expands competition tourism infrastructure along the Atlantic coast. Municipal destination marketing budgets now embed surf infrastructure within regional economic development frameworks. Ericeira and Peniche host athlete training facilities tied to Olympic qualification event calendars.
Palau
Conservation fee structures and marine protected area designations create regulatory tailwinds for premium pricing differentiation. Reef-safe sunscreen mandates and coral impact mitigation expenditures feature in annual commercial permit filings. Koror-based operators absorb compliance costs through carbon-offset partnership bundling.
Surfing Tourism Market Competitive Landscape
Concentration sits with charter operators and camp infrastructure specialists rather than consolidated multinational platforms. The vendor base spans three tiers: Pacific Rim charter partnerships, multi-destination guided tour logistics, and beginner-focused coastal camp networks. Strategic moves center on direct vessel arrangements and dynamic booking platform partnerships rather than vertical integration.
Within the charter partnership tier, Wavehunters Surf Travel Pty Ltd and World Surfaris Pty Ltd exemplify vessel-exclusive margin capture across remote archipelagos. The Perfect Wave Travel anchors multi-destination logistics spanning Indonesia, Fiji, and the Maldives through portfolio breadth. Mojosurf Pty Ltd occupies the beginner infrastructure position with dedicated novice facilities along Australia's eastern seaboard. These three archetypes represent the dominant competitive positioning vectors.
| Leading Market Players |
|---|
| Channel Islands Surfboards Inc. |
| Wavehunters Surf Travel Pty Ltd |
| The Perfect Wave Travel |
| Waterways Surf Adventures |
| Mojosurf Pty Ltd |
| World Surfaris Pty Ltd |
| Body Glove International LLC |
| Nomad Surfers |
| LineUpEXplorers GmbH |
| Others |
Value Network & Pricing Analysis
Vessel utilization rates above 80% during peak swell windows in Indonesia's Mentawai Islands compress per-berth fixed costs and establish price floors that smaller operators cannot match. Australia's Great Barrier Reef Marine Park Authority permit quotas and Hawaii's Department of Land and Natural Resources coral impact assessments further stratify supply-side capacity, concentrating pricing power with established charter partnerships and eco-certified camp tiers.
Pricing Analysis
Hawaii's reef-safe sunscreen mandates and Palau's conservation fee structures dictate the pricing tier structure across the surfing tourism market. Three-tier pricing structure across premium, standard, and economy levels separates carbon-offset bundled luxury itineraries from volume-focused adventure packages and bare-bones rental services. Price differentiation stems from ISA certification grade and marine conservation compliance documentation. Pricing pressure intensifies in the adventure segment as Indonesian operators compete on shoulder-season berth occupancy. Corporate retreat planners exhibit the lowest price sensitivity, while European wholesale-contract group tours face acute margin compression.
Supply Chain Analysis
Strategic vessel pre-positioning ahead of monsoon transitions dominates inventory strategy over just-in-time charter arrangements. Supply concentrates in Indonesia, Australia, and Fiji for vessel deployment and camp infrastructure. Raw material dependencies include marine diesel, fiberglass hull composites, and reef-safe sunscreen formulations. Single-source vulnerability runs through Pacific Rim vessel maintenance yards concentrated in Port Moresby and Denpasar. Distribution runs through direct-to-consumer booking platforms and specialized surf travel apps rather than legacy travel agency channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital platform intermediation and AI-powered swell forecasting are restructuring surfing tourism into a platform-economics inflection, where dynamic inventory allocation and predictive pricing algorithms reward operators with proprietary data feeds and direct guest relationships.
For Market Incumbents: Compound defensive moats through exclusive vessel arrangements across the Pacific Rim and ISA instructor certification pipeline control. Charter boat density in Indonesia's Mentawai Islands and direct booking platform partnerships defend margin capture against emerging platform intermediaries. Carbon-offset partnership documentation and reef restoration levy bundling reinforce premium tier positioning against price-competitive adventure operators.
For New Entrants and Emerging Players: Anchor in Australia's eastern seaboard beginner infrastructure gap, where Mojosurf Pty Ltd's camp network remains regionally concentrated and novice-focused ISA-certified instruction pools are underdeveloped compared to Indonesia's expert concentration. Target family-oriented shore-based accommodation with safety-certified instruction protocols. Pursue wholesale contracts with European outbound tour operators for predictable shoulder-season occupancy.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors operators with proprietary swell prediction data and direct guest relationship infrastructure over asset-heavy vessel owners. Long-term viability hinges on marine protected area permit security and regulatory compliance documentation depth. Acquisition targets should demonstrate documented coral impact mitigation expenditures and established relationships with Indonesia's Ministry of Tourism and Creative Economy. The signal to watch is charter boat density thresholds triggering break preservation zoning restrictions.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct Charter Partnership Expansion | Exclusive vessel arrangements in Indonesia's Mentawai Islands reduce intermediary costs and sustain margin capture. |
| ISA Instructor Certification Pipeline Investment | Controlled training pipelines in remote archipelagos address 6-18 month qualification bottlenecks and secure guide supply. |
| Carbon-Offset Partnership Bundling | Reef restoration levies attract ESG-mandated corporate retreat budgets and justify premium pricing in Fiji and the Maldives. |
| Dynamic Booking Platform Integration | AI-powered swell prediction tools enable daily slot pricing and compress traditional travel agency intermediation. |
| Marine Protected Area Permit Securement | Documented compliance with Hawaii's Department of Land and Natural Resources and Palau's conservation fee structures ensures long-term break access. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted to ground quantitative projections in operational reality. Primary interviews spanned surf camp operators, charter vessel captains, ISA-certified instructors, destination marketing officials at Indonesia's Ministry of Tourism and Creative Economy, and marine conservation officers at Australia's Great Barrier Reef Marine Park Authority. Secondary validation drew from International Surfing Association competition calendars, Hawaii Department of Land and Natural Resources permit filings, Palau conservation fee documentation, and Pacific Rim customs vessel registration data. Bottom-up charter berth capacity estimates triangulated against top-down tourism arrival statistics.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmentation dimensions spanning tourism type, experience level, activity type, and customer archetype. CAGRs were derived from historical booking pattern analysis and forward-looking capacity deployment schedules. Industry-specific inputs included seasonal swell probability distributions, marine fuel price sensitivity coefficients, and permit allocation queue lengths at regulatory bodies.
Decision-makers should treat outputs as directional under stable marine protected area designation and ISA Olympic protocol continuity assumptions; material deviation would warrant model refresh. Forecasts reflect these base conditions and embedded traveler demographic shifts. Revision becomes warranted when charter boat density triggers break preservation zoning moratoria or when reef-safe sunscreen mandates expand to additional jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Latin America Inflight Services Market
Travel and Tourism
Yacht Charter Market
Travel and Tourism
Singapore Travel Retail Market
Travel and Tourism
Japan Sports Tourism Market
Travel and Tourism
Japan Travel Retail Market
Travel and Tourism
Russia Outbound Tourism Market
Travel and Tourism
Domestic Tourism Market
Travel and Tourism
Germany Outbound Tourism Market
Travel and Tourism
Travel and Tourism User Generated Content Market
Travel and Tourism
Travel Retail Market
Travel and Tourism
Wedding Tourism Market
Travel and Tourism
India Sports Tourism Market
Travel and Tourism
Ethno Tourism Community Based Eco Tourism Market
Travel and Tourism
Yacht Charter Service Market
Travel and Tourism
India Sustainable Tourism Market
Travel and Tourism
India Travel Retail Market