
 Europe Driving Vacation Market | 2026-2036
Europe Driving Vacation Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Driving Vacation Market Insights
Modular itinerary bundling is recalibrating how European travelers assemble driving holidays, combining vehicle rental, accommodation vouchers, and route planning into configurable packages. Europcar Mobility Group leverages its integrated fleet and lodging partnerships to anchor premium self-drive offerings across France and Italy. Sixt SE competes through technology leadership in mobile-first booking and digital key handover, while Audley Travel specializes in bespoke guided driving routes with concierge support.
Europe driving vacations encompass self-directed automobile journeys where travelers rent vehicles and follow pre-planned or improvised routes across national and cross-border road networks, typically spanning three to fourteen days with overnight stops at hotels, agritourism estates, or campervan sites. The primary commercial purpose centers on delivering autonomy, scenic immersion, and multi-destination access that fixed-itinerary tours cannot replicate. SUVs and convertibles command the strongest margin pools in the vehicle type dimension, reflecting preference for comfort on mountain roads and open-air coastal exposure. Online travel agencies and direct booking platforms capture the fastest-growing share of the travel booking channel segment, displacing brick-and-mortar agents as younger travelers prioritize instant confirmation and dynamic pricing transparency.
EU Green Deal emission benchmarks and the F-Gas Regulation constrain fleet composition, pushing rental operators toward electrified or low-emission vehicle procurement to maintain airport access and urban center operating permits. EMA safety protocols and national tourism board certifications shape vehicle maintenance standards and driver eligibility requirements across member states. Stakeholders must monitor how carbon-border adjustments and evolving low-emission zone expansions in German, French, and Italian cities redefine total cost of ownership for combustion-engine fleet retention.
Market Dynamics
EU Green Deal vehicle-emission benchmarks are forcing rental operators to accelerate electrified fleet turnover while maintaining profitability on combustion-engine residual values. This regulatory pressure intersects with Mediterranean coastal demand concentration to reshape procurement geography and pricing power across the sector.
Growth Catalysts
- Low-Emission Zone Expansion:German, French, and Italian cities are tightening urban access rules, creating captive demand for compliant rental vehicles that bypass driving restrictions.
- Multi-Generational Travel Patterns:Family road-trippers across Portugal, Spain, and Italy are prioritizing flexible, self-directed itineraries over fixed-package tours.
- Integrated Digital Platforms:Mobile-first booking systems with dynamic pricing transparency are displacing brick-and-mortar agents among younger European travelers.
Market Restraints
- Residual Value Compression:Accelerated EU Green Deal phase-out timelines for combustion engines are collapsing secondary market prices for rental fleet disposals.
- Charging Infrastructure Gaps:Uneven high-speed charging coverage across Alpine corridors and rural Mediterranean routes limits electric vehicle itinerary flexibility.
- F-Gas Regulation Compliance:Vehicle air-conditioning system retrofits required under updated EU rules add per-unit conversion costs to existing fleet assets.
Strategic Opportunities
- Agritourism Route Integration:Untapped vineyard and olive estate partnerships in Portugal's Alentejo region offer margin expansion through accommodation bundling.
- Cross-Border Itinerary Packages:Schengen-zone seamless travel enables multi-country coastal circuits spanning Spain's Costa Brava through France's Côte d'Azur.
- EMA Safety Certification Premiums:Enhanced vehicle maintenance protocols create tiered pricing potential for certified operators serving safety-conscious family segments.
Industry Challenges
- Electrification Skill Shortages:Maintenance technicians trained on high-voltage battery systems remain scarce across Italian and Spanish rental hubs.
- Legacy Reservation System Integration:Real-time fleet availability APIs must synchronize with third-party accommodation platforms without disrupting direct booking channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Driving Vacation Market |
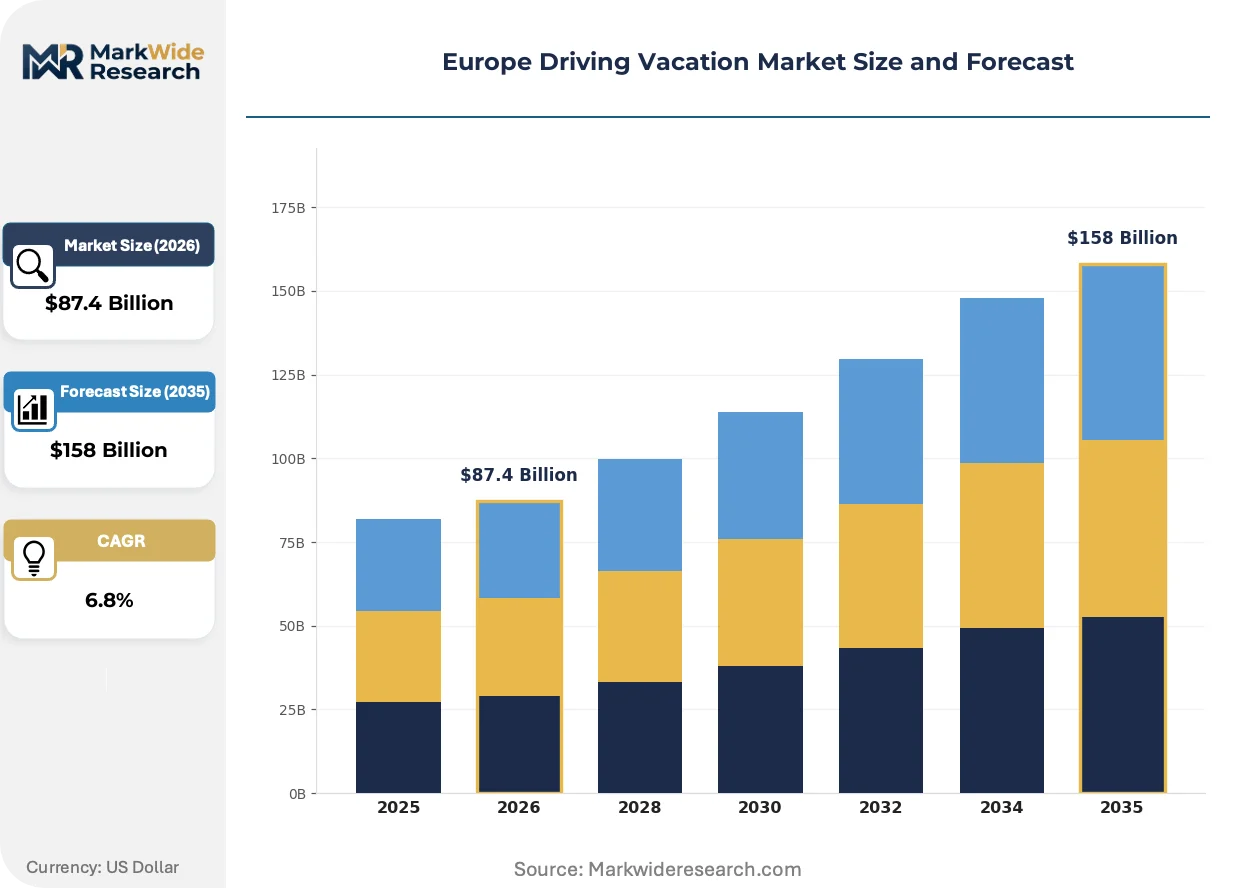
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $158 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Car, SUV, Van, Convertible Travel Booking Channel: Online Travel Agency, Direct Booking, Travel Aggregator, Brick-and-Mortar Agent Customer Type: Family, Solo Traveler, Couple, Group Route Preference: Coastal Drive, Mountain Road, Scenic Route, City Escape |
| Companies Covered | Europcar Mobility Group, Sixt SE, Avis Rent A Car System LLC, Hertz Global Holdings Inc., Enterprise Holdings Inc., Audley Travel, Scott Dunn Ltd., Tripadvisor LLC, Auto Europe, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Driving Vacation Market Trends and Innovations
Digital itinerary orchestration is compressing the traditional travel planning cycle from weeks to hours, while regulatory compliance costs are accelerating fleet technology turnover beyond natural replacement cycles.
Telematics-integrated rental platforms are rewriting how operators manage vehicle utilization and customer risk profiles. Younger travelers booking through mobile-first interfaces now expect real-time fuel level monitoring and automated damage assessment. This technology is rewriting fleet insurance economics by enabling usage-based pricing and predictive maintenance scheduling.
The EU Green Deal's F-Gas Regulation and expanding low-emission zone mandates are forcing vehicle procurement committees to weight total cost of ownership over acquisition price. Rental operators face compressed depreciation schedules as city access rules tighten. SUV and convertible categories in Mediterranean markets are most affected, with procurement shifting toward plug-in hybrid configurations that preserve open-air options while meeting emission thresholds.
Modular package assembly is displacing pre-set tour products as the dominant booking pattern. Travelers now configure vehicle class, accommodation tier, and route guidance through self-service interfaces rather than accepting bundled offerings. This shift is most visible among family road-trippers in Spain and Italy, where dynamic packaging platforms capture margin that traditionally flowed to tour operators.
Europe Driving Vacation Market Segmentation
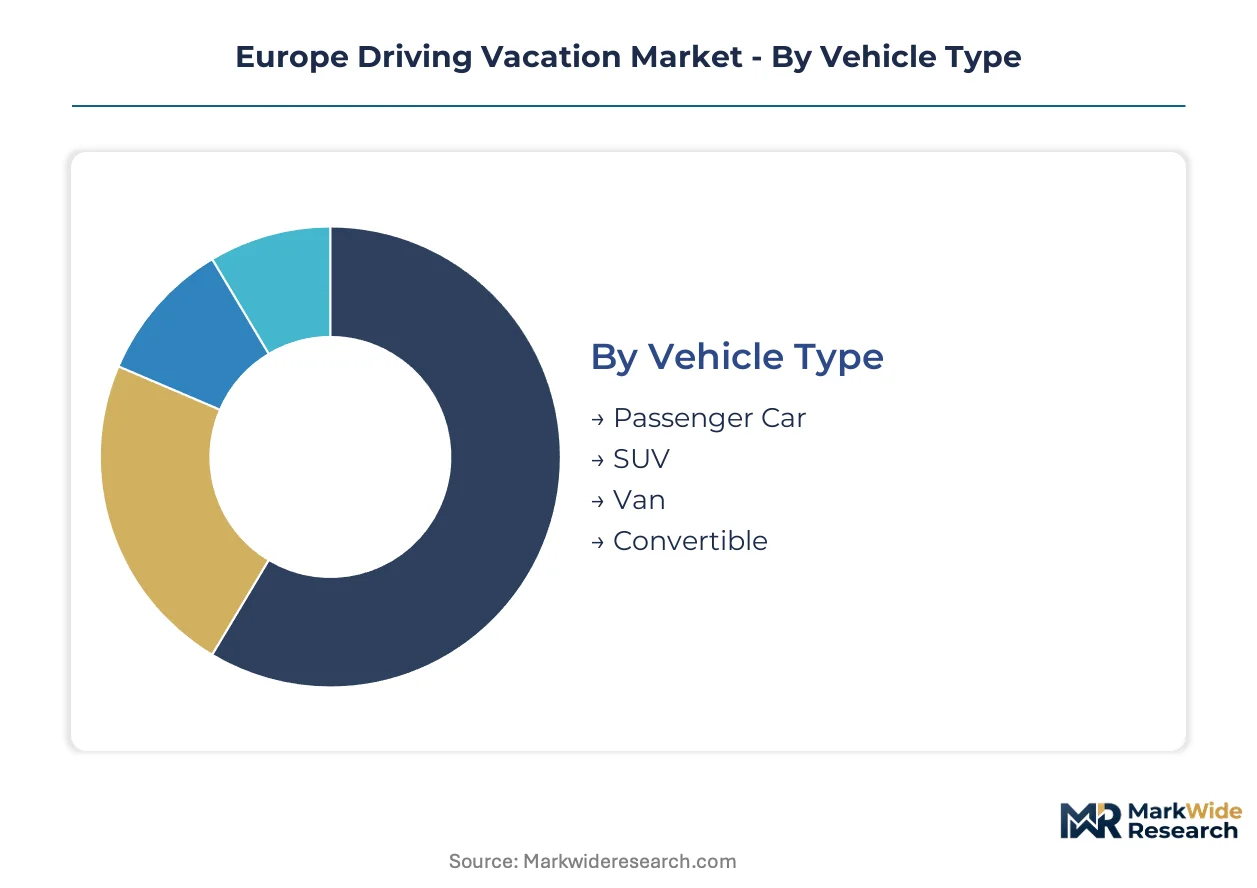
Segmentation in Europe driving vacations reveals how vehicle choice, booking behavior, and route preferences interact with regulatory constraints and generational travel patterns. Fleet procurement strategies and digital platform investments depend on understanding which combinations concentrate margin and volume.
Vehicle Type:
Upgrade cycles in this category accelerate as EU Green Deal emission benchmarks force rental operators toward electrified or low-emission configurations before natural replacement timelines.
- SUV:Higher ground clearance and cargo capacity suit Alpine corridor traverses and multi-generational family loads. Demand concentrates in German and Austrian mountain regions where comfort on switchback roads overrides fuel economy concerns, though plug-in hybrid procurement is rising to meet urban low-emission zone requirements.
- Convertible:Open-air configurations dominate Mediterranean coastal demand from Portugal's Algarve through Italy's Amalfi Coast. Margin pools here exceed other categories due to seasonal premium pricing, but F-Gas Regulation compliance costs for air-conditioning retrofits compress residual values faster than hardtop alternatives.
- Passenger Car:Compact and mid-size sedans serve cost-conscious solo travelers and couples on city-to-city circuits.
- Van:Multi-passenger configurations capture extended family groups and campervan conversions for agritourism estate hopping.
SUV sits at the top of the volume ranking, with Convertible climbing the fastest as coastal corridor demand intensifies.
Travel Booking Channel:
Cost tier differentiation in this category separates instant-confirmation platforms from high-touch advisory services, with younger travelers gravitating toward price-transparent digital interfaces.
- Online Travel Agency:Dynamic packaging engines aggregate vehicle rental, accommodation vouchers, and route guidance into configurable bundles. These platforms capture margin that traditionally flowed to tour operators, particularly among family road-trippers in Spain and Italy who prioritize self-service itinerary assembly.
- Direct Booking:Rental operator proprietary platforms bypass intermediary commissions and enable loyalty program integration. Demand concentrates in France and Germany where repeat customers value fleet consistency and streamlined digital key handover protocols.
- Travel Aggregator:Metasearch interfaces compare rates across multiple suppliers without transaction completion on-platform.
- Brick-and-Mortar Agent:Physical advisory services retain relevance for complex multi-country Schengen-zone itineraries requiring visa and insurance coordination.
Direct Booking commands the largest transaction volume, with Online Travel Agency expanding most quickly as mobile-first adoption displaces traditional intermediaries.
Customer Type:
Application patterns in this category map directly to vehicle class selection and average trip duration, with flexibility requirements varying sharply across group composition.
- Family:Multi-generational European holidaymakers prioritize self-directed itineraries over fixed-package tours, driving demand for spacious vehicles with child-safety certification and flexible cancellation terms. This segment shows strongest growth in Portugal, Spain, and Italy where agritourism estate partnerships enable accommodation bundling.
- Couple:Romantic getaway travelers concentrate on scenic coastal and wine region routes, favoring convertible and premium SUV categories with concierge-supported dining reservations.
- Solo Traveler:Individual explorers prioritize compact vehicle economy and single-occupancy accommodation flexibility.
- Group:Coordinated friend circles and special-interest clubs require van or multi-vehicle coordination for festival and sporting event circuits.
Family sits at the top of the volume ranking, with Couple climbing the fastest as experiential travel preferences reshape Mediterranean destination selection.
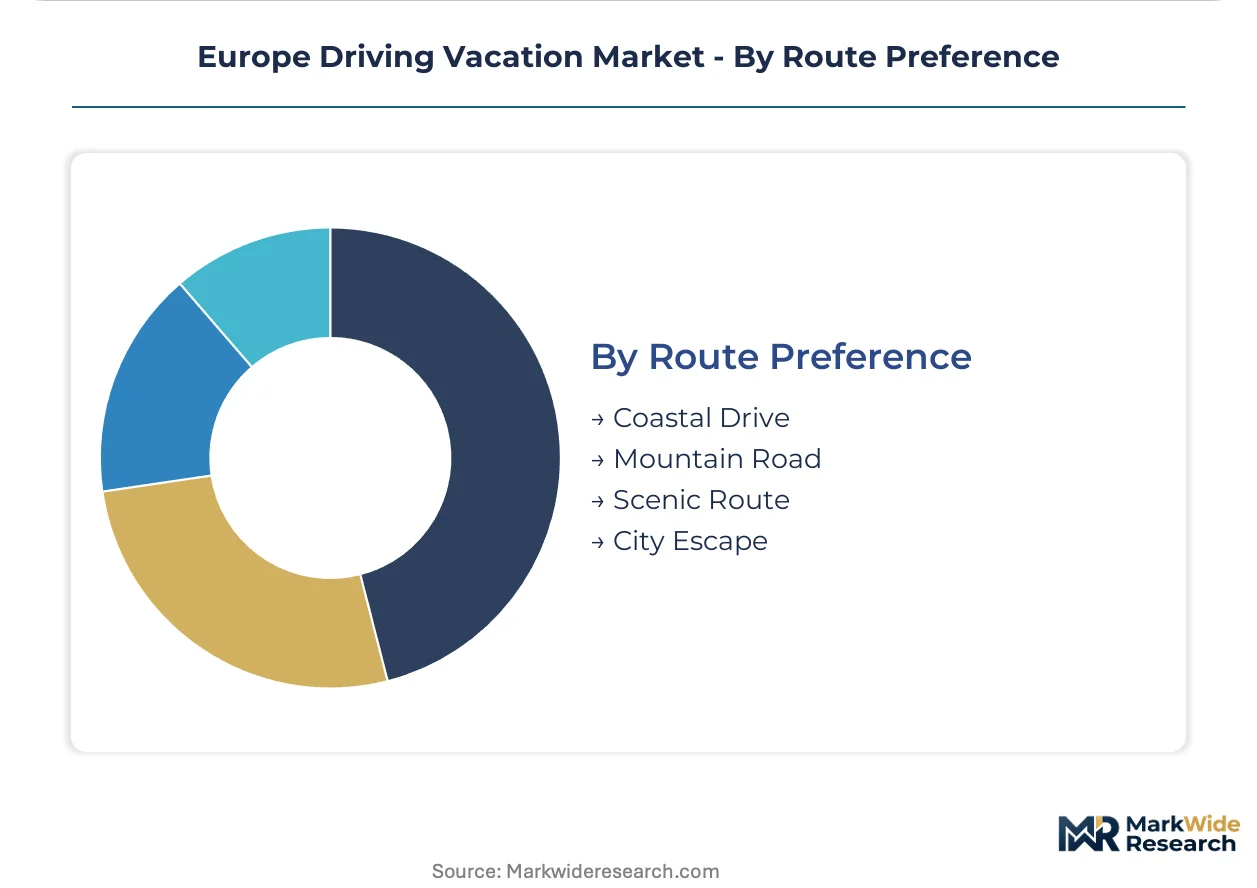
Route Preference:
Geographic concentration in this category aligns with seasonal weather patterns and charging infrastructure availability, particularly for electrified fleet deployment.
- Coastal Drive:Atlantic and Mediterranean shoreline routes from Portugal through Greece command peak summer pricing and highest vehicle utilization rates. These corridors face constraints from uneven high-speed charging coverage that limits electric vehicle itinerary flexibility in rural Alentejo and southern Italian segments.
- Mountain Road:Alpine passes and Pyrenean traverses demand all-wheel-drive capability and seasonal tire compliance under EMA safety protocols.
- Scenic Route:Designated national tourism board trails combine cultural waypoint density with driving pleasure.
- City Escape:Short-duration rural departures from urban centers require low-emission zone compliant vehicles for origin access.
Coastal Drive sits at the top of the volume ranking, with Mountain Road climbing the fastest as Alpine infrastructure investments improve accessibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The driving vacation industry took root in post-war Europe when improved road networks and rising car ownership enabled leisure motoring across national borders. Early package tours through France and Italy established the commercial template that rental operators and travel platforms later scaled.
France
Coastal circuits along the Côte d'Azur and Provence wine routes sustain peak seasonal demand for convertible and premium SUV categories. The EU Green Deal's low-emission zone mandates in Paris, Lyon, and Marseille are accelerating fleet electrification timelines for rental operators serving urban pickup locations. Bordeaux and the surrounding Nouvelle-Aquitaine region anchor agritourism integration, where vineyard estate partnerships enable accommodation bundling with vehicle rental.
Italy
Amalfi Coast and Tuscany driving routes command the strongest margin premiums in Mediterranean Europe, with multi-generational family groups prioritizing flexible itineraries between agritourism estates. F-Gas Regulation compliance costs for air-conditioning retrofits compress residual values for convertible fleet assets faster than hardtop alternatives. The Alpine corridors of South Tyrol and Trentino concentrate demand for all-wheel-drive SUVs with seasonal tire certification under EMA safety protocols.
Spain
Costa Brava and Andalusian coastal drives attract the fastest-growing segment of younger travelers booking through mobile-first platforms with dynamic pricing expectations. National tourism board certifications for scenic route designation create tiered pricing opportunities for operators meeting enhanced vehicle maintenance standards. Barcelona and Madrid rental hubs face tightening low-emission zone rules that favor plug-in hybrid procurement over pure combustion engines.
Germany
Bavarian Alpine passes and Black Forest scenic routes sustain year-round demand for SUVs with all-wheel-drive capability and cargo capacity for multi-generational family loads. KBA vehicle registration standards intersect with EU Green Deal benchmarks to constrain fleet composition for operators maintaining airport access permits. Munich and Frankfurt serve as primary pickup hubs where direct booking platforms capture repeat customers through loyalty program integration and streamlined digital key handover.
Portugal
The Algarve coastal corridor and Alentejo vineyard routes represent the fastest-expanding geography for family road-trippers seeking self-directed alternatives to fixed-package tours. Uneven high-speed charging coverage across rural Alentejo segments limits electric vehicle itinerary flexibility, preserving demand for plug-in hybrid configurations. Lisbon and Porto rental hubs are developing integrated digital platforms that bundle vehicle rental with agritourism estate accommodation vouchers.
Europe Driving Vacation Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the service integration dimension, with bespoke route designers commanding pricing power that transactional rental brokers cannot replicate. The vendor base concentrates around three strategic archetypes: integrated mobility groups with fleet and lodging partnerships, technology-forward platforms emphasizing mobile-first booking infrastructure, and specialist tour operators crafting guided driving experiences with concierge support. Competitive moves center on modular package assembly capabilities and cross-border itinerary orchestration rather than fleet scale alone.
Among integrated mobility groups, Europcar Mobility Group and Sixt SE exemplify divergent paths to margin capture. Europcar anchors premium self-drive offerings through France and Italy by leveraging combined vehicle rental and accommodation partnerships. Sixt occupies a position defined by technology leadership in mobile-first booking interfaces and digital key handover protocols. Specialist operator Audley Travel represents the bespoke tier, where concierge-supported route planning commands premium pricing from experiential travelers.
| Leading Market Players |
|---|
| Europcar Mobility Group |
| Sixt SE |
| Avis Rent A Car System LLC |
| Hertz Global Holdings Inc. |
| Enterprise Holdings Inc. |
| Audley Travel |
| Scott Dunn Ltd. |
| Tripadvisor LLC |
| Auto Europe |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal emission benchmarks are forcing rental operators toward electrified fleet procurement ahead of natural replacement cycles, compressing residual values for combustion-engine assets and reshaping total cost of ownership calculations across Mediterranean and Alpine markets.
Pricing Analysis
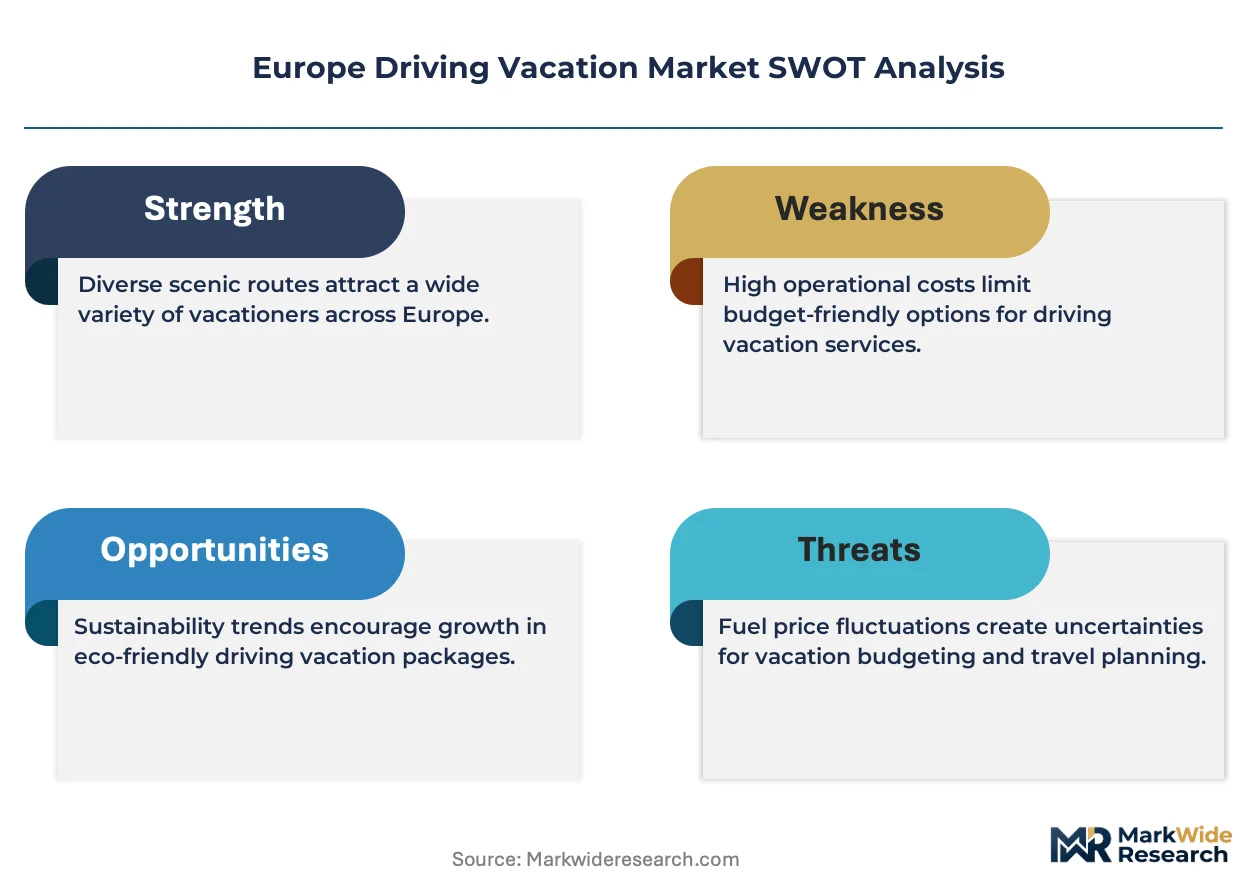
Three-tier pricing structure across premium, standard, and economy levels dominates the Europe driving vacation market, with premium tiers commanding substantial markups for EMA safety certification and plug-in hybrid configurations. Price differentiation rests on vehicle emission compliance status and concierge-supported itinerary bundling. Cost compression in the economy tier is intensifying because accelerated EU Green Deal phase-out timelines collapse secondary market prices for non-compliant fleet disposals. Family road-trippers exhibit highest price sensitivity, while couple segments prioritize experiential value over base rate.
Supply Chain Analysis
Cross-border vehicle logistics costs from German manufacturing hubs to Mediterranean pickup locations anchor supply chain economics for rental operators. Fleet procurement draws from Germany, France, and Spain for vehicle sourcing, with battery system components resting on South Korean and Chinese supplier networks. Single-source vulnerability in high-voltage technician training across Italian and Spanish hubs creates operational risk. Distribution runs through airport hub networks and urban center depots coordinated via real-time fleet management platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe driving vacation market represents a late-cycle quality story as multi-generational travelers shift demand toward certified premium fleet configurations and integrated digital booking experiences.
For Market Incumbents: Acquire agritourism estate partnerships in Portugal's Alentejo and Italy's Tuscany corridors to lock in accommodation bundling margin. Incumbents must accelerate plug-in hybrid fleet turnover to defend airport access permits against tightening EU Green Deal low-emission zone mandates in Paris, Lyon, and Milan. Backward integration into charging infrastructure partnerships along coastal corridors reduces itinerary flexibility constraints that currently limit electric vehicle deployment. For New Entrants and Emerging Players: Mobile-first dynamic packaging platforms offer the most penetrable entry point, targeting younger travelers in Spain and Italy who prioritize self-service itinerary assembly over traditional tour operator bundles. New entrants should concentrate on white-space coastal routes with uneven incumbent coverage, particularly rural Alentejo segments where high-speed charging gaps preserve demand for hybrid configurations. A direct-to-consumer subscription model for repeat Mediterranean travelers bypasses established OTA commission structures. For Investors and Strategic Acquirers: Asymmetric upside sits with technology-forward platforms possessing proprietary route orchestration algorithms and integrated lodging partnerships. Long-term viability favors operators with demonstrated compliance navigation across expanding EU Green Deal emission benchmarks and F-Gas Regulation retrofit requirements. The signal to watch is low-emission zone expansion velocity in secondary German, French, and Italian cities, which will accelerate captive demand for compliant fleet assets.| Strategic Initiative | Industry Significance |
|---|---|
| Agritourism Partnership Network | Vineyard estate alliances in Bordeaux and Tuscany capture accommodation bundling margin from family road-trippers. |
| Plug-in Hybrid Fleet Conversion | EMA safety certification and EU Green Deal compliance preserve urban center operating permits and airport access. |
| Mobile-First Platform Launch | Dynamic pricing transparency and digital key handover displace brick-and-mortar intermediaries among younger travelers. |
| Cross-Border Itinerary Integration | Schengen-zone seamless routing from Spain's Costa Brava through France's Côte d'Azur expands addressable trip duration. |
| Charging Infrastructure Partnership | Alpine corridor and rural Mediterranean coverage gaps currently constrain electric vehicle itinerary flexibility. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with rental fleet procurement directors, digital platform product managers, agritourism estate operators, and EU regulatory affairs specialists with secondary validation. Data sources included customs vehicle registration records, EMA safety protocol filings, national tourism board certification databases, and operator financial disclosures. Bottom-up segment sizing and top-down market triangulation cross-validated volume and value estimates.
Historical reference periods anchored the projection horizon to established seasonal patterns and regulatory implementation timelines. The analytical framework modeled vehicle type, travel booking channel, customer segment, and route preference dimensions alongside emission compliance tier and charging infrastructure availability. CAGRs were derived from segment-level growth trajectory analysis incorporating EU Green Deal phase-out schedules and low-emission zone expansion maps. Forecast inputs included fleet turnover velocity assumptions and residual value compression curves for combustion-engine assets.
The model holds under stable EU regulatory implementation schedules; deviation in accelerated F-Gas Regulation enforcement or unilateral national low-emission zone expansions would shift fleet procurement economics and operator margin structures. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Tourism Market
Travel and Tourism
Asia-Pacific Travel Retail Market
Travel and Tourism
Europe Wellness Tourism Market
Travel and Tourism
Russia Outbound Tourism Market
Travel and Tourism
Global Ecotourism Market
Travel and Tourism
Hong Kong Tourism Market
Travel and Tourism
Singapore Tourism Market
Travel and Tourism
Educational Tourism Market
Travel and Tourism
Travel Retail Market
Travel and Tourism
Japan Sports Tourism Market
Travel and Tourism
Indonesia Sustainable Tourism Market
Travel and Tourism
Luxury Travel Market
Travel and Tourism
France Culinary Tourism Market
Travel and Tourism
Canada Travel and Tourism Market
Travel and Tourism
Sustainable Tourism Market
Travel and Tourism
Pet Travel Services Market