
 USA Sports Tourism Market | 2026-2036
USA Sports Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
USA Sports Tourism Market Analytics
Event hospitality staffing pools is rotating toward specialized sports travel coordination, tightening labor supply for peak tournament weekends. Classic Sports Travel leverages long-standing relationships with NCAA and professional league venues to secure premium inventory blocks. QuintEvents anchors its model around exclusive official hospitality packages for signature events like the Super Bowl and Kentucky Derby. IMG Travel competes through integrated media rights and destination management capabilities that bundle broadcast exposure with traveler experiences.
USA Sports Tourism encompasses the organized travel of individuals and groups to attend, participate in, or support sporting events, combining transportation logistics, accommodation procurement, event ticketing, and ancillary destination services into packaged itineraries. The sector operates through high-touch coordination across fragmented supplier networks, with technology platforms increasingly automating inventory aggregation and dynamic pricing. Football Games command the largest revenue share within Event Type segmentation due to concentrated season schedules and premium seating economics. Families within the Consumer Segment represent the fastest-growing pool as multi-generational travel packages gain traction around youth tournaments and accessible professional fixtures. Hotels dominate Accommodation Type revenue, though Vacation Rentals capture growing share among extended-stay sports families seeking kitchen facilities and cost control.
The Department of Transportation coordinates with FAA and TSA to manage air capacity surges around mega-events, while state-level tourism boards navigate environmental review requirements under NEPA for new stadium and arena construction. OSHA standards govern temporary event worker safety protocols, and local zoning ordinances shape hotel density patterns near emerging sports venues. Stakeholders must weigh infrastructure investment timelines against shifting fan preferences for immersive, technology-enhanced in-venue experiences.
Market Dynamics
The Infrastructure Investment and Jobs Act is channeling federal funding toward stadium modernization and transit connectivity, reshaping how host cities compete for recurring event calendars and corporate group contracts.
Growth Catalysts
- Corporate Experiential Travel:Organizations are prioritizing team-building travel packages that bundle professional sporting events with hospitality programming, expanding the buyer base beyond traditional leisure segments.
- OSHA Temporary Worker Standards:Standardized safety protocols for event staffing are enabling larger-scale tournament operations by reducing liability exposure for venue operators and travel coordinators.
- Stadium Digital Infrastructure:5G-enabled venue upgrades are creating immersive in-seat experiences that justify premium pricing and extend dwell time for traveling fan bases.
Market Restraints
- Labor Pool Concentration:Specialized sports travel coordination expertise concentrates in Florida and California, creating staffing bottlenecks for peak tournament weekends in secondary markets.
- NEPA Environmental Review:Federal review requirements for new stadium and arena construction extend development timelines and increase pre-revenue carrying costs for host municipalities.
- Aviation Capacity Constraints:FAA-coordinated airspace management around mega-events limits inbound passenger volumes, capping attendance scalability for destination tournaments.
Strategic Opportunities
- Youth Tournament Ecosystems:Multi-generational family travel packages around youth sports events represent underdeveloped inventory in Texas and Arizona relative to established Florida operations.
- Vacation Rental Integration:Extended-stay sports families are shifting toward kitchen-equipped rental properties, creating channel diversification beyond traditional hotel blocks.
- State Tourism Board Incentives:Local zoning ordinances near emerging venues are being relaxed to accelerate hotel density, reducing accommodation scarcity for repeat visitation.
Industry Challenges
- Fragmented Supplier Networks:High-touch coordination across transportation, accommodation, and ticketing providers requires manual reconciliation that automation platforms have not yet fully displaced.
- Dynamic Pricing Complexity:Real-time inventory aggregation across NCAA and professional league venues demands specialized data infrastructure that mid-tier operators struggle to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USA Sports Tourism Market |
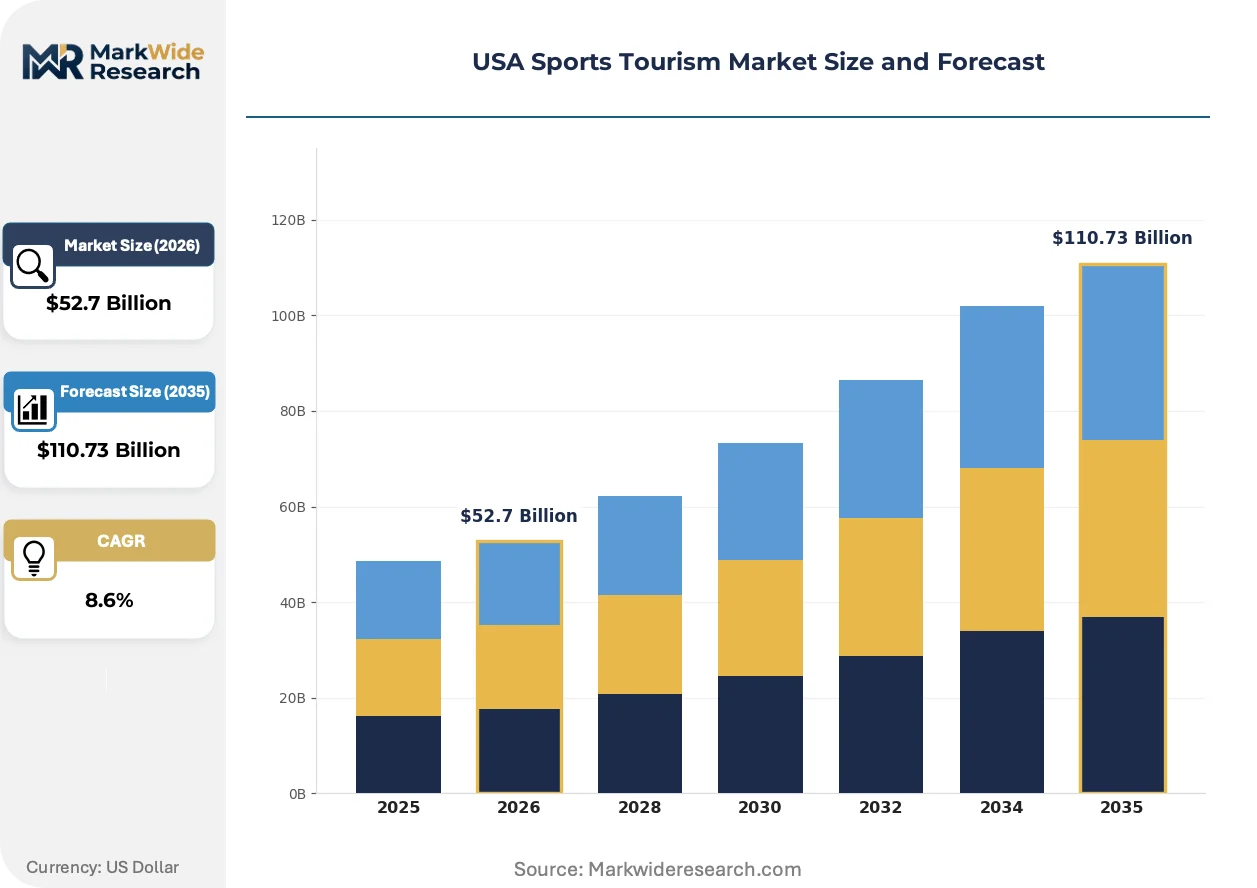
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $110.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Event Type: Marathons, Football Games, Basketball Tournaments, Ice Hockey Matches Consumer Segment: Sports Enthusiasts, Families, Corporate Groups, Adventurers Accommodation Type: Hotels, Hostels, Vacation Rentals, Campsites Activity Level: Active Participants, Spectators, Coaches, Officials |
| Companies Covered | Classic Sports Travel, SportsTravel, Inc., Sports Tours International, XLSportsTours, Navigo Sports, ABSOLUT Sport, ATPI Sports Travel, IMG Travel, QuintEvents, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USA Sports Tourism Market Evolving Landscape
Technology platforms are compressing the coordination layer between fragmented suppliers and group buyers, while experiential design is displacing transactional ticketing as the core value proposition.
Mobile credentialing systems are replacing physical tickets and room keys across major sporting venues. Corporate group buyers and extended-stay families are adopting these platforms fastest, driven by demand for seamless multi-event itineraries. The technology is miniaturizing the check-in footprint, enabling venues to convert former queue space into monetized hospitality zones.
The Department of Transportation coordinates with FAA and TSA to manage air capacity surges through temporary slot allocations and security lane expansions. This federal coordination is reducing ground delay programs that previously disrupted tournament arrival patterns. Mega-events in Florida and California are the primary beneficiaries, with secondary markets now petitioning for equivalent protocol designations.
After-sales service unbundling is separating travel insurance, cancellation flexibility, and concierge access from base package pricing. Youth tournament families and corporate incentive planners are purchasing these components à la carte through direct channels, bypassing traditional bundled markups. Texas and Arizona host cities are seeing this shift most acutely as they compete with established Florida operators on total trip cost transparency.
USA Sports Tourism Market Segmentation
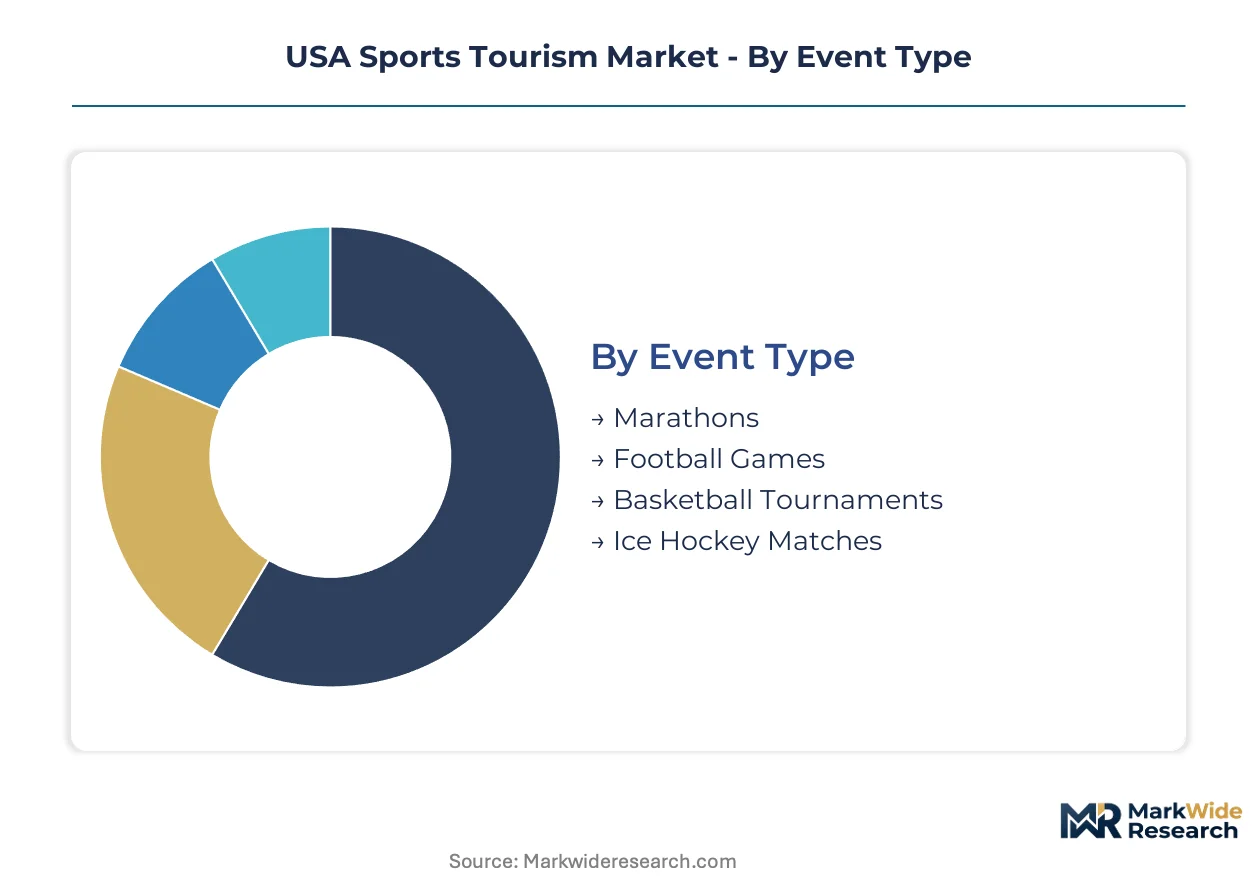
Travel coordinators structure inventory procurement around event calendars and group composition, with each segment demanding distinct supplier relationships and pricing architectures. Channel strategy diverges sharply between spectator-driven mass events and participant-centric tournament ecosystems.
Event Type:
Football Games and Basketball Tournaments flow through official hospitality package channels with contracted hotel blocks, while Marathons and Ice Hockey Matches distribute more heavily through direct-to-consumer booking platforms and running club partnerships.
- Football Games:Concentrated season schedules create compressed demand windows requiring advance inventory commitments. NFL and NCAA venues in Texas and Florida drive premium seating economics with corporate hospitality programming dominating the buyer mix.
- Basketball Tournaments:March Madness and NBA playoff circuits generate multi-city travel patterns with rapid inventory turnover. Demand concentrates in host cities with integrated arena-district hotel density and light rail connectivity.
- Marathons:Major city races like Boston and New York attract international participant travel with extended booking horizons.
- Ice Hockey Matches:Regional fan migration patterns link Midwest and Northeast markets with seasonal travel clustering.
By volume, Football Games leads. By growth pace, Basketball Tournaments is ahead.
Consumer Segment:
Cost tier differentiation separates corporate hospitality buyers seeking bundled experiential programming from price-sensitive family segments optimizing total trip expenditure through vacation rental platforms.
- Corporate Groups:Organizations purchase official hospitality packages combining premium seating with networking programming. This segment commands highest per-capita spend and is expanding most quickly as experiential team-building travel displaces traditional incentive structures.
- Families:Multi-generational travel around youth tournaments drives extended-stay patterns with kitchen-equipped rental preference. Texas and Arizona host cities see accelerating demand as Florida operations face capacity constraints.
- Sports Enthusiasts:Individual travelers pursuing bucket-list events across multiple professional leagues.
- Adventurers:Niche segment combining endurance sports participation with destination exploration.
Corporate Groups generates highest revenue per trip. Families shows steepest expansion trajectory.
Accommodation Type:
Supply concentration in Florida and California shapes availability patterns, with secondary markets building inventory to capture tournament overflow.
- Hotels:Traditional room blocks anchor corporate contracts and official hospitality packages. Properties near NCAA and professional venues in host cities command rate premiums during peak tournament weekends.
- Vacation Rentals:Kitchen-equipped properties capture extended-stay sports families seeking cost control and flexibility. Arizona and Texas markets see accelerating platform penetration as inventory scales to match Florida's established supply.
- Hostels:Budget positioning serves solo marathon participants and youth tournament support staff.
- Campsites:Outdoor endurance events and regional youth tournaments drive seasonal demand clustering.
Hotels dominates current revenue. Vacation Rentals gains share fastest.
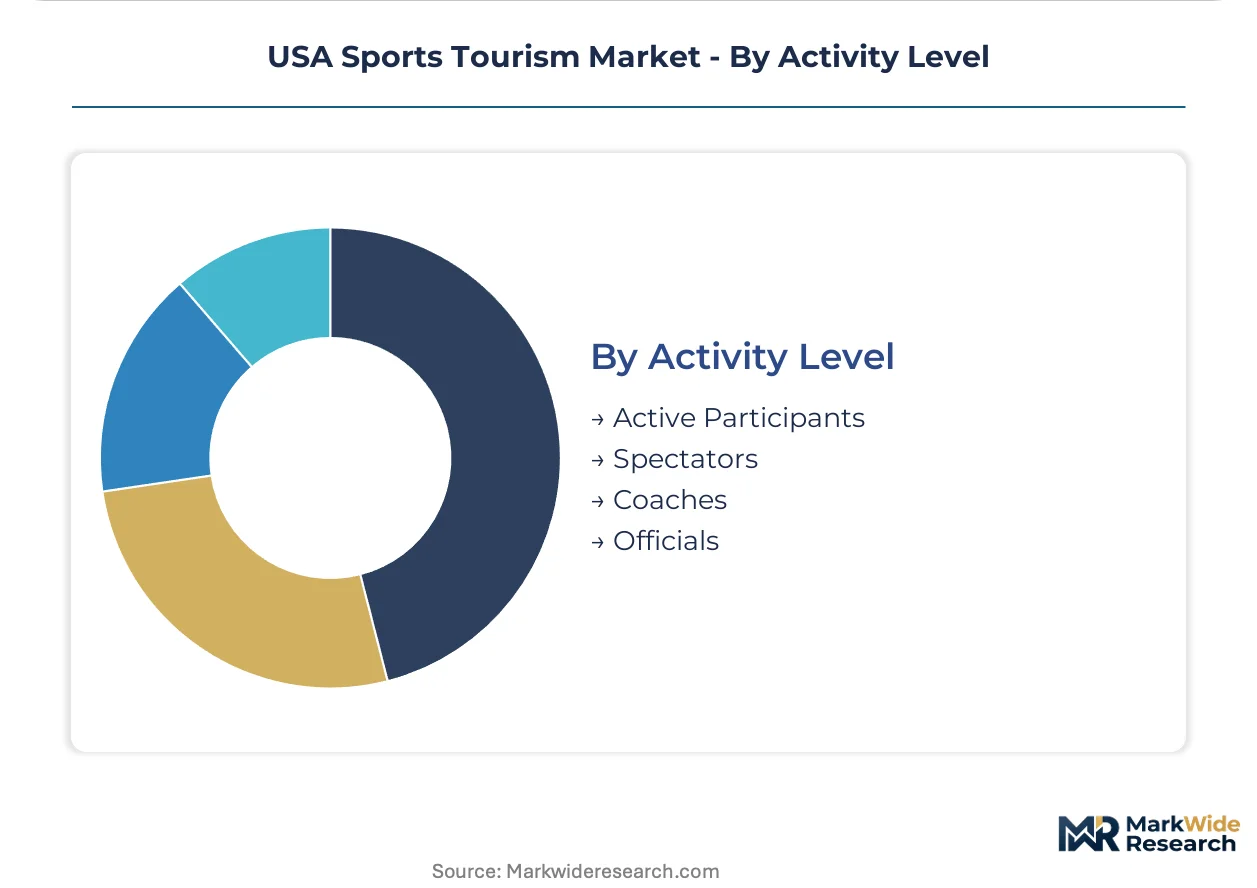
Activity Level:
Application-based segmentation determines ancillary service bundling, with Active Participants requiring equipment logistics and Spectators demanding premium viewing experiences.
- Active Participants:Runners, amateur athletes, and youth competitors need race registration integration, equipment transport, and recovery services. Marathon and triathlon travel coordinators bundle these requirements into premium package tiers.
- Spectators:Viewing-focused travelers prioritize seat location, in-venue hospitality access, and ground transportation efficiency. This segment drives technology adoption for mobile credentialing and frictionless venue entry.
- Coaches:Team travel coordinators manage group logistics for youth tournament circuits with complex roster requirements.
- Officials:Referee and judge travel follows standardized league protocols with contracted accommodation tiers.
Spectators represents the volume base. Active Participants carries highest service attachment rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Florida and California deploy sports tourism infrastructure for year-round repeat visitation, while Texas and Arizona concentrate demand around compressed youth tournament seasons with extended-stay family patterns.
Florida
Orlando and Miami host overlapping professional and collegiate event calendars that drive corporate hospitality procurement. State tourism boards leverage relaxed zoning ordinances to accelerate hotel density near emerging venues. The Interstate 4 corridor anchors multi-generational family travel packages around youth soccer and baseball tournaments.
California
Los Angeles and San Francisco markets command premium seating economics through integrated arena-district development. The Department of Transportation coordinates FAA slot allocations for mega-event air capacity surges. San Diego's coastal concentration captures marathon participant travel with extended booking horizons.
Texas
Dallas-Fort Worth and Houston compete for NCAA tournament circuits with rapid inventory turnover requirements. Infrastructure Investment and Jobs Act funding channels toward stadium modernization and light rail connectivity. Austin's emerging venue cluster targets overflow demand from saturated Florida operations.
Arizona
Phoenix and Tucson markets scale vacation rental inventory to match kitchen-equipped family preferences. OSHA temporary worker standards enable larger-scale tournament operations by reducing venue operator liability exposure. The Cactus League spring training corridor anchors seasonal demand clustering with established hospitality infrastructure.
Northeast Corridor
Boston and New York City concentrate marathon participant travel with international booking patterns. NEPA environmental review requirements extend new arena development timelines and increase municipal carrying costs. The I-95 corridor links regional ice hockey fan migration between Midwest and Northeast markets.
USA Sports Tourism Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier controlling official hospitality package distribution and the lower tier competing on niche tournament coordination. The vendor base organizes around three strategic archetypes: venue-integrated operators with long-standing NCAA relationships, media-rights bundlers combining broadcast exposure with traveler experiences, and technology-enabled aggregators automating inventory procurement. Competitive moves concentrate on exclusive inventory contracting and mobile credentialing platform deployment.
Within the venue-integrated tier, Classic Sports Travel and QuintEvents exemplify contrasting approaches to premium access procurement, with the former anchoring long-standing NCAA relationships and the latter securing official hospitality blocks for signature professional events. IMG Travel occupies a position among media-rights bundlers, integrating destination management with broadcast exposure capabilities. These three operators represent the dominant competitive archetypes shaping inventory access and pricing architectures across host city markets.
| Leading Market Players |
|---|
| Classic Sports Travel |
| SportsTravel, Inc. |
| Sports Tours International |
| XLSportsTours |
| Navigo Sports |
| ABSOLUT Sport |
| ATPI Sports Travel |
| IMG Travel |
| QuintEvents |
| Others |
Value Network & Pricing Analysis
Capacity reservation contracts with NCAA venues and professional league properties lock in inventory access months ahead of tournament dates, anchoring price visibility for corporate hospitality buyers while exposing operators to carrying costs if demand patterns shift. These advance commitments concentrate pricing power among venue-integrated operators with established relationship networks across Florida and California host markets.
Pricing Analysis
Long-term offtake agreements dominate premium inventory procurement, with official hospitality packages commanding rate premiums over direct-to-consumer channels. Price differentiation rests on seating tier certification and bundled experiential programming rather than base ticket value. Cost compression in secondary market hotel blocks is intensifying because vacation rental platforms are disintermediating traditional room-night aggregators. Corporate incentive planners show lowest price sensitivity, while extended-stay families optimize total trip expenditure through kitchen-equipped rental properties.
Supply Chain Analysis
Strategic stockpiling of contracted hotel inventory prevails over just-in-time procurement, as peak tournament weekends create instantaneous demand spikes that spot markets cannot absorb. Geographic supply concentration centers on Florida, California, and Texas, with Arizona scaling inventory to capture overflow from saturated primary markets. Raw material dependencies include aviation slot allocations, venue credentialing systems, and temporary event staffing pools. Single-source vulnerability concentrates in specialized sports travel coordination expertise, which remains concentrated in established host cities. Distribution runs through fragmented supplier networks requiring manual reconciliation across transportation, accommodation, and ticketing providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sports tourism operators should treat mobile credentialing platforms and after-sales service unbundling as the primary service-attach layers, with à-la-carte concierge access and cancellation flexibility expanding faster than base package pricing.
For Market Incumbents: Shield exclusive venue relationships by embedding deeper into NCAA and professional league digital infrastructure before technology-enabled aggregators automate inventory procurement. Invest in certification for OSHA temporary worker standards to reduce liability exposure and enable larger-scale tournament operations. Channel control through mobile credentialing platform deployment represents the critical defensive lever against disintermediation. For New Entrants and Emerging Players: After-sales service gaps in youth tournament ecosystems present the most penetrable white space, with Texas and Arizona host cities seeing accelerating demand as Florida operations face capacity constraints. Target multi-generational family segments with kitchen-equipped vacation rental integration and transparent total-trip cost structures. A direct-to-consumer go-to-market angle bypassing traditional bundled markups captures price-sensitive buyers. For Investors and Strategic Acquirers: Capital is best deployed toward venue-integrated operators with captive NCAA relationships and technology-enabled inventory aggregation capabilities. Long-term viability across the analysis window hinges on exclusive contracting power and mobile platform penetration. The signal to watch is FAA protocol designations for secondary market mega-events, which would unlock attendance scalability and repeat visitation economics.| Strategic Initiative | Industry Significance |
|---|---|
| Venue Digital Infrastructure Partnership | 5G-enabled upgrades create immersive experiences justifying premium pricing tiers. |
| Vacation Rental Platform Integration | Kitchen-equipped properties capture extended-stay sports families seeking cost control. |
| Mobile Credentialing System Deployment | Replaces physical tickets and room keys, converting queue space into monetized zones. |
| Official Hospitality Package Expansion | Bundled experiential programming commands highest per-capita spend from corporate buyers. |
| Youth Tournament Ecosystem Development | Multi-generational travel packages build recurring revenue in underdeveloped Texas and Arizona markets. |
Research Methodology
A standing panel of travel coordinators, venue hospitality directors, NCAA tournament operators, and corporate incentive planners provided ongoing calibration across primary fieldwork, with secondary validation drawing from DOT coordination protocols, FAA slot allocation records, state tourism board development filings, and OSHA temporary worker standard documentation. Bottom-up inventory aggregation modeling triangulated against top-down event calendar analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include event type, consumer segment, accommodation type, and activity level, with regional regulatory clusters capturing Infrastructure Investment and Jobs Act funding flows. CAGRs were derived from trend extrapolation anchored in historical tournament attendance patterns and hospitality procurement data.
Underlying assumptions cover Infrastructure Investment and Jobs Act funding continuity, FAA coordination protocol expansion, and vacation rental platform penetration rates, with deviation risk concentrated in NEPA environmental review timelines and aviation capacity constraints around mega-events. Revision becomes warranted when federal infrastructure funding allocations or secondary market FAA protocol designations cross thresholds that materially alter host city competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Malaysia Tourism Market
Travel and Tourism
India Outbound Tourism Market
Travel and Tourism
Flower Delivery Services Market
Travel and Tourism
Ethno Tourism Community Based Eco Tourism Market
Travel and Tourism
South Korea Tourism Market
Travel and Tourism
North America Travel Retail Market
Travel and Tourism
Water Park Market
Travel and Tourism
Airline Retailing Market
Travel and Tourism
Cycle Tourism Market
Travel and Tourism
China Online Travel Market
Travel and Tourism
Europe Tourism Vehicle Rental Market
Travel and Tourism
Vietnam Online Travel Market
Travel and Tourism
Domestic Tourism Market
Travel and Tourism
Latin America Inflight Services Market
Travel and Tourism
Canada Travel and Tourism Market
Travel and Tourism
Yacht Charter Service Market