
 India Wellness Tourism Market | 2026-2036
India Wellness Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
India Wellness Tourism Market Foresight
Telemedicine integration with pre-arrival health assessments is rewriting how wellness programs are designed and delivered across Indian retreats. Kairali Ayurvedic Healing Village leverages proprietary Ayurveda protocols to sustain its position in Kerala's competitive backwater circuit. Ananda in the Himalayas anchors premium pricing through its mountain-integrated spa and yoga programming in Uttarakhand. Atmantan Wellness Centre differentiates via its metabolic health focus and in-house diagnostic capabilities near Pune.
India wellness tourism encompasses structured travel for preventive health, combining traditional medicine systems, therapeutic spa interventions, and lifestyle coaching across residential programs typically lasting three to twenty-one days. Ayurveda service types command established revenue pools through standardized Panchakarma protocols, while yoga sessions attract the fastest-growing domestic cohort seeking stress management alternatives. Hill station destinations occupy premium positioning due to climate-linked therapeutic claims, whereas urban wellness centers compete on accessibility and corporate contract volumes. Weekend getaway durations dominate booking frequency, though extended retreats generate disproportionate per-visitor margins.
The Ministry of AYUSH and the Ministry of Tourism jointly govern wellness center accreditation under the National Wellness Tourism Standards, with BIS technical specifications governing equipment and facility benchmarks. State-level tourism boards in Kerala and Uttarakhand enforce additional environmental and heritage compliance for coastal and Himalayan properties respectively. Stakeholders must track how AYUSH certification mandates expand beyond current voluntary frameworks into compulsory market access requirements.
Market Dynamics
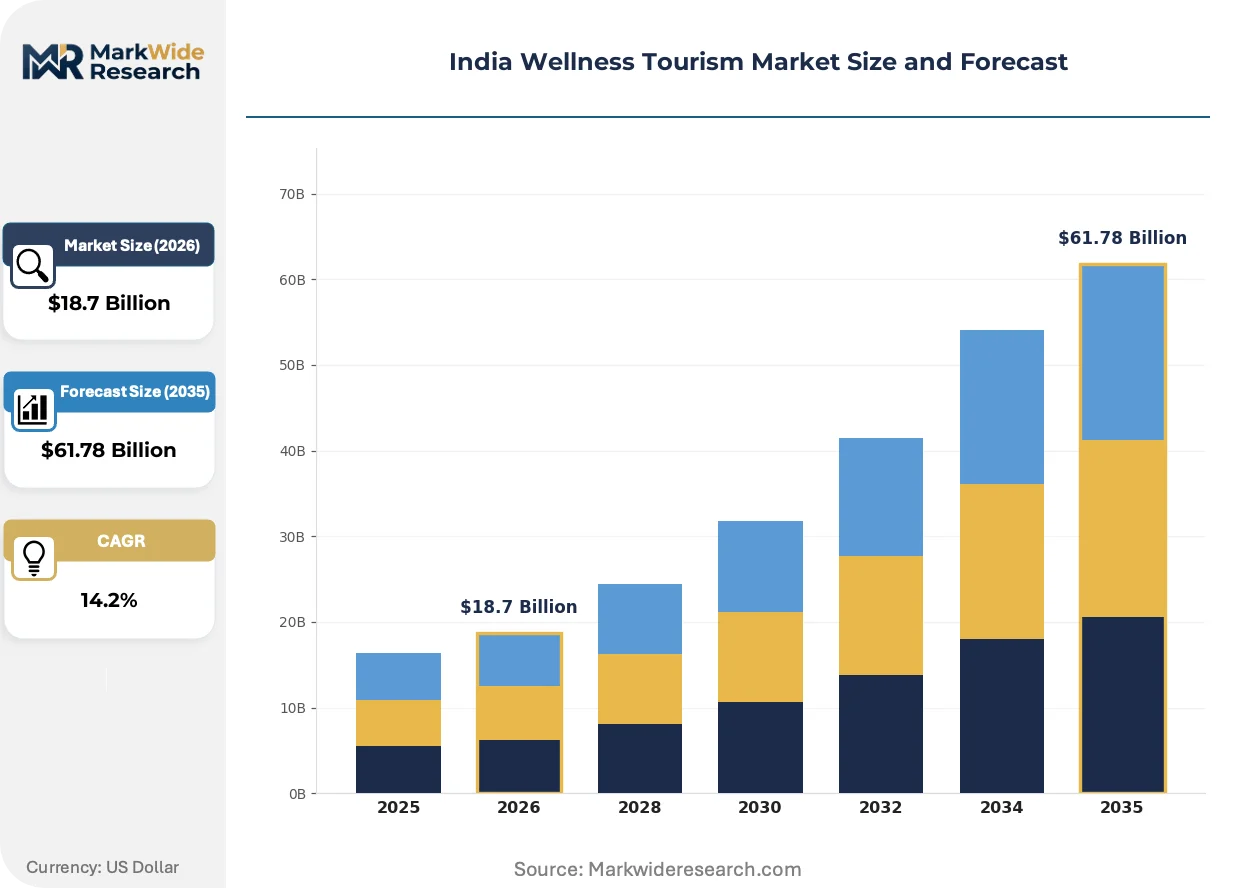
Telemedicine integration with pre-arrival health assessments is compressing booking cycles and expanding addressable customer bases for residential wellness programs across Kerala, Uttarakhand, and Karnataka.
Growth Catalysts
- Ministry of AYUSH Certification Mandates:The National Wellness Tourism Standards framework is elevating quality benchmarks and filtering substandard operators from Kerala's backwater Ayurveda clusters.
- Domestic Tourist Surge:Urban professionals from Mumbai, Delhi, and Bangalore are driving weekend retreat bookings for stress management through Panchakarma and yoga protocols.
- Telemedicine Infrastructure:Pre-arrival diagnostic capabilities are enabling personalized program design and reducing on-site assessment time for metabolic health and lifestyle coaching interventions.
Market Restraints
- Certified Practitioner Scarcity:Trained Ayurveda physicians and yoga therapists concentrate in established Kerala and Rishikesh corridors, creating talent bottlenecks for new entrants in secondary locations.
- Seasonal Demand Concentration:Monsoon-season Ayurveda protocols generate revenue concentration risk for coastal properties dependent on international medical tourist arrivals.
- Real Estate Cost Escalation:Premium hill station land in Uttarakhand and Himachal Pradesh is compressing margins for mid-tier wellness center developers.
Strategic Opportunities
- Corporate Wellness Contracts:IT and financial services sectors in Bangalore and Hyderabad are sourcing residential preventive health programs for executive cohorts.
- Metabolic Health Specialization:Diabetes reversal and obesity management protocols are attracting domestic medical tourists seeking alternatives to pharmaceutical interventions.
- State Tourism Board Incentives:Kerala's Responsible Tourism Mission and Uttarakhand's heritage compliance frameworks are channeling subsidized capital toward certified greenfield developments.
Industry Challenges
- AYUSH Certification Timelines:Mandatory facility audits and physician credentialing under Ministry of AYUSH protocols are extending pre-operational lead times for new centers.
- Technology-Tradition Integration:Diagnostic equipment standardization under BIS technical specifications is creating friction with classical Ayurveda assessment methodologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Wellness Tourism Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ayurveda, Spa Treatments, Wellness Retreats, Yoga Sessions Customer Type: Domestic Tourists, International Visitors, Corporates, Families Destination Type: Hill Stations, Coastal Regions, Heritage Sites, Urban Wellness Centers Duration: Weekend Getaways, Week-long Packages, Short Stays, Extended Retreats |
| Companies Covered | Omnia Wellness Retreats, Kairali Ayurvedic Healing Village, Ananda in the Himalayas, Swastha Resort, Atmantan Wellness Centre, Shreyas Retreat, Somatheeram Ayurveda Resort, Antara Wellness Resort, Ennakkathara Arya Vaidyasala, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Wellness Tourism Market Shifts & Advancements
Digital health infrastructure is merging with classical healing systems to create measurable outcome frameworks that satisfy domestic corporate buyers and international medical tourists simultaneously.
Artificial intelligence-driven dosha assessment tools are hybridizing traditional Ayurveda diagnostic protocols with biometric data streams from wearable devices. Domestic wellness chains near Pune and Bangalore are deploying these platforms to personalize Panchakarma intensity and dietary recommendations. This convergence is compressing the gap between standardized hospitality service delivery and individualized therapeutic outcomes.
The Ministry of AYUSH and Ministry of Tourism joint accreditation framework is mandating real-time facility monitoring and outcome documentation for National Wellness Tourism Standards compliance. Properties in Rishikesh's yoga corridor are retrofitting legacy ashram infrastructure to meet these technical specifications. Himalayan destinations face elevated capital requirements for environmental and heritage compliance layered atop central certification mandates.
Corporate procurement departments are unbundling annual wellness budgets into modular residential program contracts rather than per-diem hospitality arrangements. IT sector HR functions in Hyderabad and Chennai are sourcing fixed-duration metabolic health interventions for high-stress employee cohorts. This shift is visible most acutely in Maharashtra and Tamil Nadu, where wellness centers are restructuring sales teams to engage enterprise benefit administrators directly.
India Wellness Tourism Market Segmentation
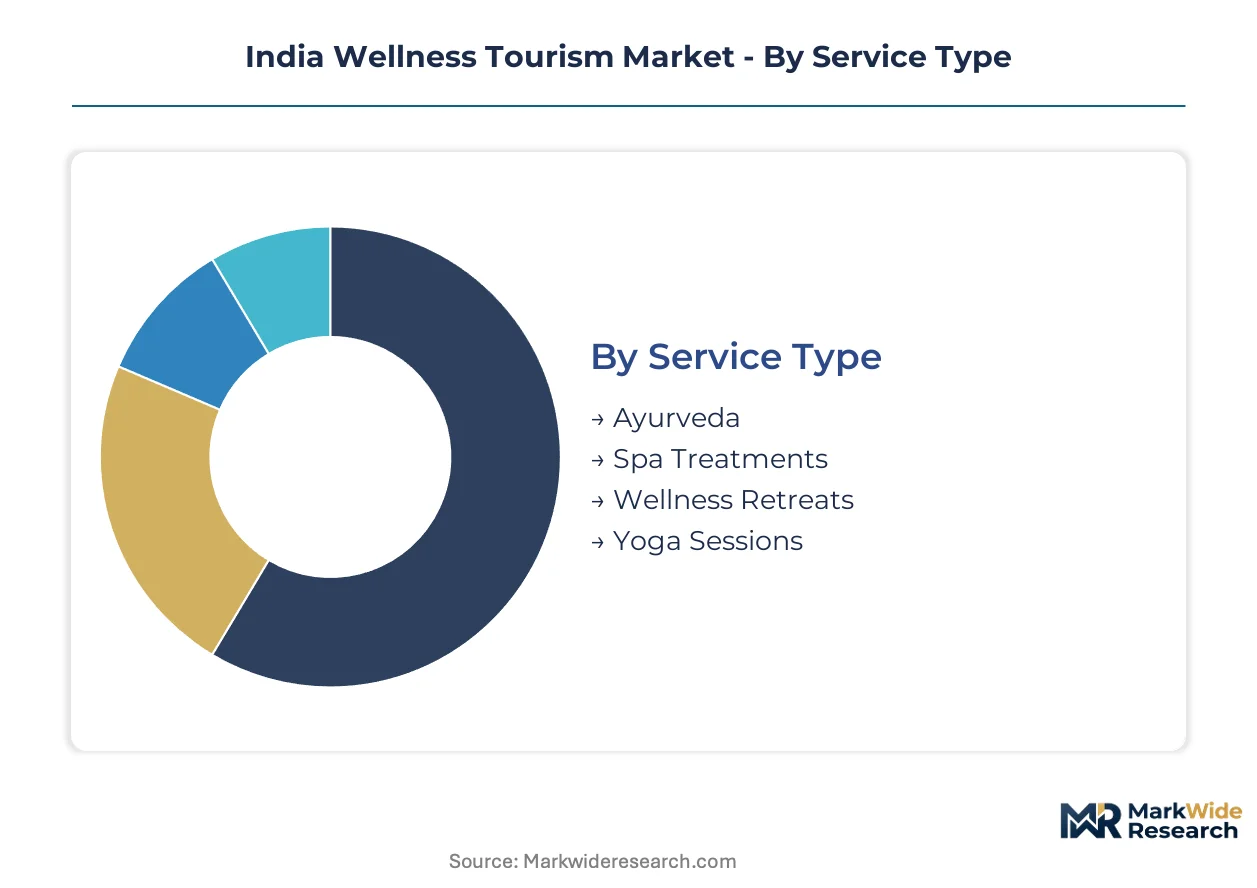
Segmentation in India's wellness tourism market reveals how distinct service modalities, customer profiles, and destination characteristics create specialized revenue pools. Understanding these divides allows operators to align certification investments, staffing models, and facility specifications with specific demand pockets across Kerala's backwater circuits, Uttarakhand's Himalayan corridors, and urban satellite markets.
Service Type:
After-sales service intensity varies sharply across service modalities, with Ayurveda and spa treatments requiring sustained physician engagement versus yoga's lighter touch maintenance protocols.
- Ayurveda:Panchakarma protocols demand residential physician supervision across 14-21 day cycles, with Ministry of AYUSH certification requirements for diagnostic equipment and treatment rooms driving capital intensity. Kerala's backwater clusters concentrate the highest-volume operations, though Karnataka's Mysore corridor is attracting second-location expansions from established Ayurveda hospital chains seeking to diversify beyond monsoon-season dependency.
- Spa Treatments:Therapeutic massage and hydrotherapy services operate on shorter duration models with lower regulatory barriers, enabling faster inventory turns in urban wellness centers. Demand concentrates in Bangalore and Hyderabad's corporate catchments, where IT sector HR departments source executive wellness contracts on quarterly renewal cycles rather than annual hospitality agreements.
- Wellness Retreats:Integrated programming combining multiple modalities requires cross-trained staff and higher fixed-cost structures.
- Yoga Sessions:Rishikesh's yoga corridor anchors instructor certification density, with domestic professionals from Mumbai and Delhi driving weekend intensive bookings.
By volume, Ayurveda leads. By growth pace, yoga sessions are expanding most quickly.
Customer Type:
Cost tier stratification separates premium international medical tourists from price-sensitive domestic weekenders and corporate procurement departments.
- Domestic Tourists:Urban professionals from tier-1 cities now drive the majority of booking volume across Kerala and Uttarakhand properties, with stress management and metabolic health protocols displacing leisure tourism as the primary motivation. These customers compress booking cycles through telemedicine-enabled pre-arrival assessments and favor shorter-duration interventions that minimize work absence.
- International Visitors:European and North American medical tourists sustain premium pricing for extended Panchakarma programs, particularly during monsoon months when domestic leisure demand contracts. Their longer average stays and higher per-visitor spend justify specialized international patient coordination staff and multilingual physician coverage at certified centers.
- Corporates:Fixed-duration preventive health contracts are restructuring revenue predictability for Maharashtra and Tamil Nadu wellness centers.
- Families:Multi-generational bookings concentrate in heritage site destinations combining wellness with cultural programming.
Domestic tourists dominate transaction frequency. International visitors generate the steepest expansion trajectory in per-visitor yield metrics.
Destination Type:
Geographic clustering reflects climate-linked therapeutic claims and regulatory differentiation across state-level tourism board jurisdictions.
- Hill Stations:Uttarakhand's Himalayan properties command premium positioning through altitude-integrated yoga and spa programming, with Ananda in the Himalayas anchoring pricing benchmarks. Real estate cost escalation in Mussoorie and Nainital corridors is compressing margins for mid-tier developers, pushing new supply toward Himachal Pradesh's secondary hill destinations.
- Coastal Regions:Kerala's backwater Ayurveda clusters benefit from established international reputation and Ministry of AYUSH certification density, though monsoon concentration risk requires revenue diversification strategies. State tourism board incentives through the Responsible Tourism Mission channel subsidized capital toward greenfield certified developments.
- Heritage Sites:Rajasthan and Madhya Pradesh properties compete on cultural-therapeutic integration.
- Urban Wellness Centers:Accessibility and corporate contract proximity drive volume in Pune, Bangalore, and Hyderabad satellite locations.
Hill stations lead in revenue per available room. Urban wellness centers are gaining share fastest through corporate contract penetration.
Duration:
Booking frequency and margin structure invert across duration categories, with shorter stays driving volume and extended retreats capturing disproportionate profitability.
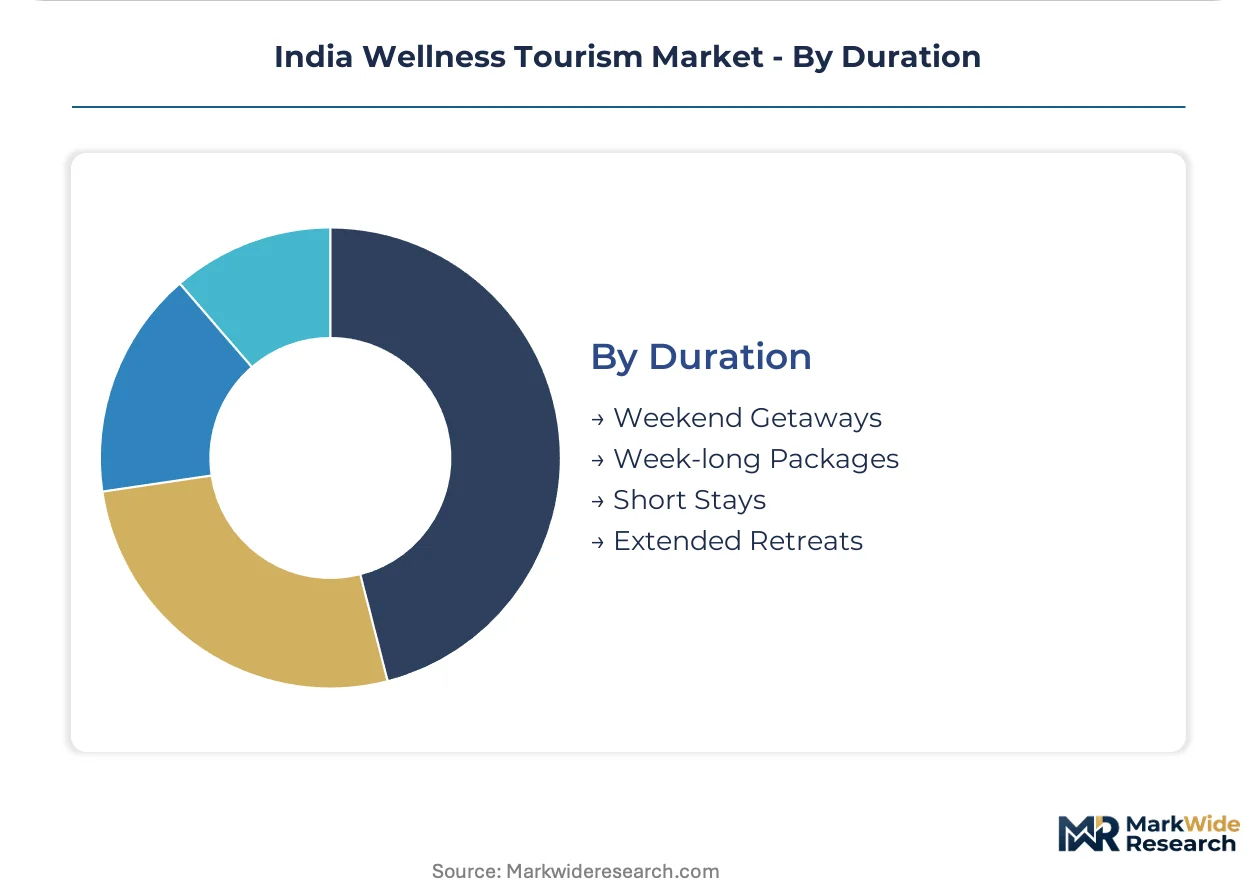
- Weekend Getaways:Two-to-three-day intensive programs dominate transaction frequency among domestic professionals from Delhi, Mumbai, and Bangalore, with yoga and introductory Ayurveda assessments as core offerings. These bookings exhibit highest price elasticity and require aggressive digital marketing spend to maintain occupancy against competing leisure alternatives.
- Extended Retreats:Fourteen-to-twenty-one-day Panchakarma and metabolic health interventions generate the highest per-visitor margins and enable physician staffing efficiency through predictable census patterns. Kerala's certified centers and Uttarakhand's premium properties concentrate this demand, with pre-arrival diagnostic protocols reducing on-site assessment overhead.
- Week-long Packages:Seven-day structured programs balance accessibility with therapeutic credibility for first-time wellness tourists.
- Short Stays:Single-day spa and consultation services compete with urban hospitality alternatives on convenience.
Weekend getaways lead in booking volume. Extended retreats are climbing the fastest in revenue contribution share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's wellness tourism exports therapeutic protocols to European and North American medical tourists seeking alternatives to pharmaceutical interventions, while domestic demand from tier-1 cities now drives volume expansion across Kerala, Uttarakhand, and Karnataka corridors.
Kerala
Backwater Ayurveda clusters generate the highest international patient concentration through established Panchakarma protocols. The Ministry of AYUSH certification density here exceeds national averages, filtering substandard operators from the market. Kairali Ayurvedic Healing Village and Somatheeram Ayurveda Resort anchor quality benchmarks in the state's coastal belt.
Uttarakhand
Himalayan altitude-integrated programming commands premium positioning through climate-linked therapeutic claims. State tourism board heritage compliance frameworks layer environmental mandates atop central certification requirements. Ananda in the Himalayas sets pricing anchors in the Rishikesh-Mussoorie corridor where real estate costs are compressing mid-tier developer margins.
Karnataka
Mysore's yoga corridor attracts second-location expansions from established Ayurveda hospital chains seeking monsoon-season revenue diversification. The Ministry of AYUSH protocols govern diagnostic equipment standardization across Mysore and Bangalore satellite markets. Domestic professionals from Bangalore drive weekend intensive bookings for stress management alternatives.
Maharashtra
Pune's metabolic health specialization leverages proximity to Mumbai's corporate procurement departments. IT and financial services sectors source fixed-duration preventive health contracts for executive cohorts. Atmantan Wellness Centre anchors diagnostic capabilities in this urban satellite market where accessibility trumps destination premium.
Tamil Nadu
Chennai's wellness centers restructure sales teams to engage enterprise benefit administrators directly on modular residential program contracts. State-level environmental compliance for coastal properties adds regulatory layers to central AYUSH mandates. Heritage site destinations here compete on cultural-therapeutic integration for multi-generational family bookings.
India Wellness Tourism Market Competitive Landscape
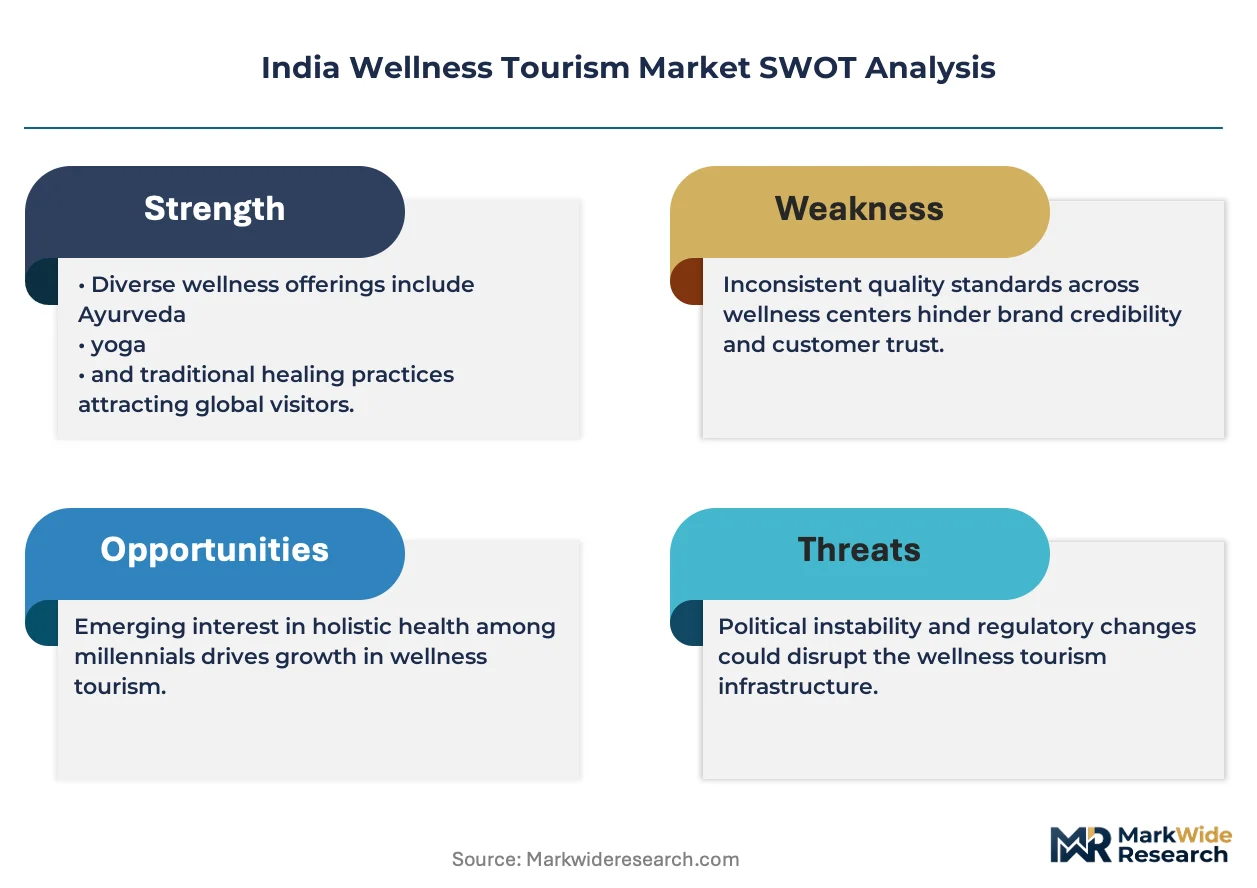
Channel-controlling players compete with product-specialist players across India's wellness tourism market, where certification density and physician credentialing create tiered entry barriers. The competitive structure concentrates around three archetypes: established Ayurveda hospital chains with proprietary protocols, premium Himalayan destination resorts, and urban satellite centers with metabolic health specializations. Dominant competitive moves include geographic diversification to escape monsoon-season dependency and backward integration into diagnostic capabilities to reduce pre-arrival assessment overhead.
Within the established Ayurveda hospital chain archetype, Kairali Ayurvedic Healing Village and Somatheeram Ayurveda Resort exemplify Kerala's backwater cluster dominance through Ministry of AYUSH certification density. Among premium Himalayan destination operators, Ananda in the Himalayas occupies a position anchoring Uttarakhand's pricing benchmarks through altitude-integrated spa and yoga programming. At the metabolic health specialization tier, Atmantan Wellness Centre represents Pune's urban satellite model where in-house diagnostic capabilities differentiate against destination-dependent competitors.
| Leading Market Players |
|---|
| Omnia Wellness Retreats |
| Kairali Ayurvedic Healing Village |
| Ananda in the Himalayas |
| Swastha Resort |
| Atmantan Wellness Centre |
| Shreyas Retreat |
| Somatheeram Ayurveda Resort |
| Antara Wellness Resort |
| Ennakkathara Arya Vaidyasala |
| Others |
Supply & Pricing Matrix
Kerala's certified Ayurveda physician concentration anchors premium pricing power for residential Panchakarma programs, while diagnostic equipment import dependencies from Germany and Japan compress margins for mid-tier wellness centers seeking Ministry of AYUSH compliance.
Pricing Analysis
Certified-premium versus uncertified-standard versus unregulated-economy pricing gaps widen as Ministry of AYUSH mandates harden. Price differentiation hinges on physician credential grade and BIS equipment certification tier. Pricing pressure intensifies in urban satellite markets where corporate procurement departments demand outcome documentation. Domestic weekend tourists exhibit highest price elasticity, while international medical tourists accept premium positioning for extended monsoon-season protocols.
Supply Chain Analysis
Tariff exposure between India and medical equipment manufacturing hubs in Germany, Japan, and South Korea dominates supply chain risk for diagnostic-capable wellness centers. Therapeutic oil formulations draw from Kerala's coastal cultivation clusters and imported herbal concentrates from Sri Lanka and Nepal. Single-source vulnerability concentrates in specialized Panchakarma apparatus fabrication. Distribution runs through state tourism board-certified channels for international patient coordination, with direct digital booking platforms gaining domestic share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India wellness tourism sits at a high-growth inflection as telemedicine infrastructure collapses pre-arrival assessment friction and expands addressable demand beyond traditional geographic catchments.
For Market Incumbents: Build proprietary protocol moats through backward integration into Ayurvedic herb cultivation and captive diagnostic laboratory capacity. Kairali Ayurvedic Healing Village's Kerala land holdings exemplify this defensive posture against new entrants facing real estate cost escalation. Certification density investments under Ministry of AYUSH protocols create regulatory barriers that compound over time. For New Entrants and Emerging Players: Build out metabolic health specialization in underserved urban satellite corridors like Hyderabad and Chennai where corporate wellness contract penetration remains below Kerala and Maharashtra benchmarks. Weekend-intensive yoga programming for Bangalore IT professionals offers the most penetrable white-space, with telemedicine-enabled pre-arrival assessment as the differentiated go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Ayurveda hospital chains seeking geographic diversification beyond monsoon-season dependency. Long-term viability across the next decade hinges on outcome documentation capabilities that satisfy corporate procurement departments. Watch for Ministry of AYUSH mandatory certification expansion as the signal that regulatory moats are hardening into market access gates.| Strategic Initiative | Industry Significance |
|---|---|
| Telemedicine Platform Integration | Pre-arrival diagnostic capabilities compress booking cycles and expand corporate contract eligibility for certified centers. |
| AYUSH Certification Investment | Mandatory facility audits under Ministry of AYUSH protocols filter substandard operators and anchor premium pricing tiers. |
| Metabolic Health Specialization | Diabetes reversal protocols attract domestic medical tourists seeking pharmaceutical alternatives in Pune and Bangalore corridors. |
| Corporate Wellness Contracting | Fixed-duration preventive health agreements with IT sector HR functions restructure revenue predictability for urban satellite centers. |
| Herb Cultivation Backward Integration | Captive therapeutic oil supply chains reduce input cost volatility for Kerala's coastal Ayurveda clusters. |
Research Methodology
Operator-level perspectives from wellness center medical directors, state tourism board certification officers, corporate HR benefit administrators, and Ayurveda physician networks anchored the qualitative base for this analysis. Primary interview findings triangulated against Ministry of AYUSH regulatory filings, Kerala and Uttarakhand state tourism board development reports, and BIS technical specification documents. Secondary validation drew from hospital procurement databases, wellness center occupancy disclosures, and corporate wellness contract announcements. Bottom-up facility-level capacity modeling converged with top-down tourism expenditure estimates across the analysis window.
Scenario-bracketing framed the quantitative projection, with segmentation dimensions spanning service modality, customer archetype, destination cluster, and program duration. CAGRs derived from physician staffing capacity constraints, certification pipeline timelines, and corporate contract penetration curves. Forecast inputs incorporated telemedicine adoption velocity and Ministry of AYUSH mandate escalation patterns throughout the modeling period.
Stress conditions across monsoon-season revenue concentration, certified practitioner scarcity, and real estate cost escalation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory trajectory and technology diffusion rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
North America Travel Retail Market
Travel and Tourism
GCC Outbound Tourism Market
Travel and Tourism
France Culinary Tourism Market
Travel and Tourism
New Zealand Sustainable Tourism Market
Travel and Tourism
Yoga Tourism Market
Travel and Tourism
Special Interest Tourism Market
Travel and Tourism
South Korea Tourism Market
Travel and Tourism
Sustainable Tourism Market
Travel and Tourism
China Online Travel Market
Travel and Tourism
New Zealand Sports Tourism Market
Travel and Tourism
Singapore Travel Retail Market
Travel and Tourism
Leisure Travel Market
Travel and Tourism
Educational Tourism Market
Travel and Tourism
Maldives Hospitality Market
Travel and Tourism
Dark Tourism Market
Travel and Tourism
Flower Delivery Services Market