
 Incentive Travel Market | 2026-2036
Incentive Travel Market Size, Share, and Industry Trends Forecast 2026-2036
Incentive Travel Market Outlook
Premium experiential tiering is bifurcating the incentive travel landscape into ultra-luxury immersive journeys and scaled performance-trip programs. ITA Group leverages its proprietary event technology platform to sustain group-retreat market leadership across North American pharmaceutical accounts. Crystal Cruises anchors high-end ocean incentive programming with curated destination immersion. Air Partner differentiates through private aviation logistics that controls executive participant movement across remote itineraries.
Incentive travel constitutes employer-funded reward mobility designed to recognize performance, build loyalty, and stimulate revenue productivity through curated group or individual journeys. Programs integrate destination management, curated activity architecture, risk mitigation protocols, and participant engagement metrics to deliver measurable organizational returns. International travel type commands margin concentration due to extended duration and complex logistics coordination. Experience packages within incentive structure categories capture fastest expansion as millennials and Gen Z participants prioritize memory creation over material rewards. Technology vertical among industry verticals leads absolute spend due to competitive talent retention pressures and distributed workforce normalization.
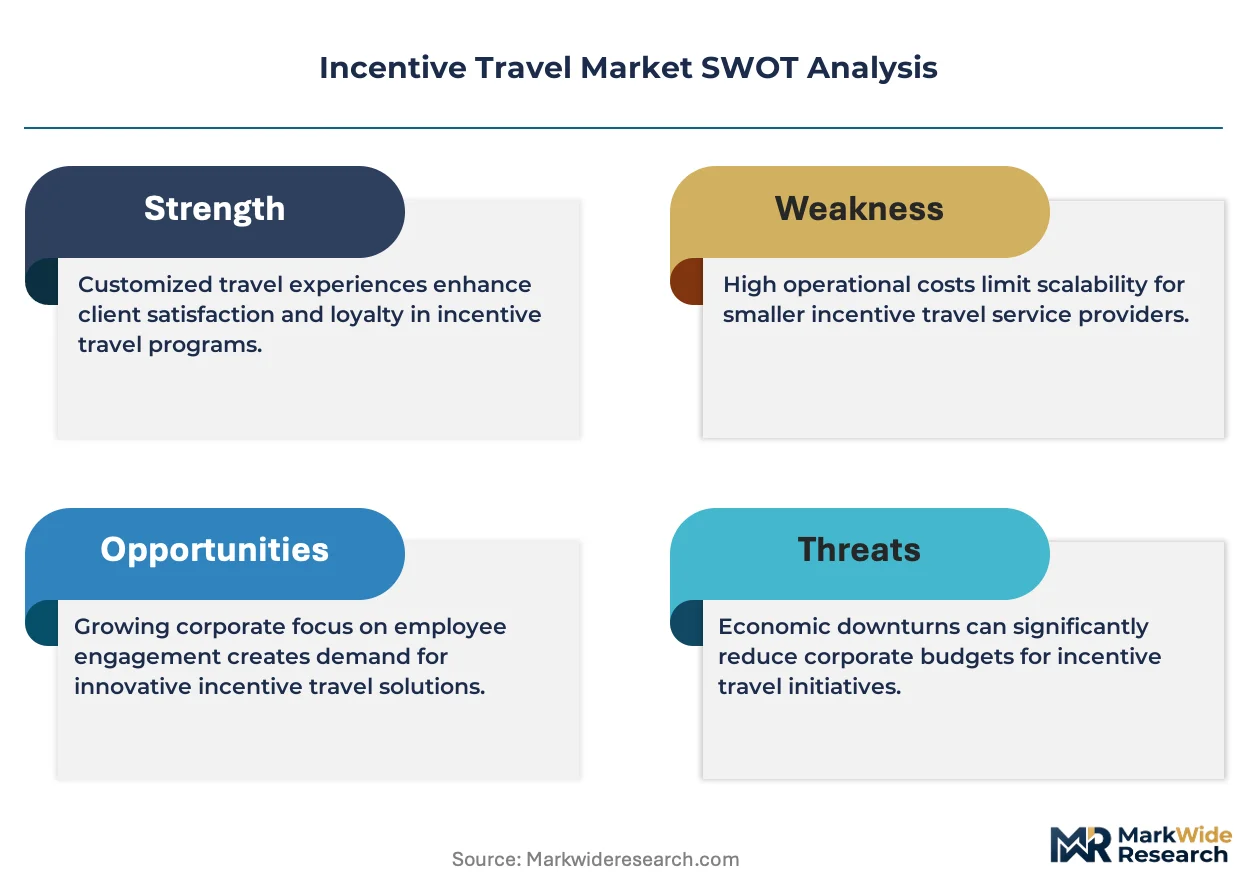
ISO 31030 travel risk management standards, EU CSRD sustainability disclosure requirements, and US OSHA duty-of-care precedents collectively elevate supplier compliance burdens and client liability frameworks. ESG alignment now functions as a market-access gate for destination management companies seeking corporate accounts. Stakeholders must monitor evolving carbon reporting obligations and duty-of-care litigation trends to preserve program viability and competitive positioning.
Market Dynamics
Pharmaceutical sales force restructuring is replacing cash bonuses with performance-linked travel rewards, while EU CSRD disclosure mandates and ISO 31030 risk protocols are redefining supplier qualification thresholds across corporate program procurement.
Growth Catalysts
- EU Corporate Sustainability Reporting Directive:Mandatory ESG disclosure requirements are compelling destination management companies to obtain ISO sustainability certification, creating competitive differentiation for compliant suppliers.
- Millennial workforce normalization:Technology sector employers now allocate substantial incentive travel budgets to experiential memory-creation packages rather than material rewards, accelerating demand for curated destination immersion.
- Thailand destination clustering:Southeast Asian experiential packages concentrate booking volumes through integrated wellness, cultural, and adventure programming that pharmaceutical sales teams prioritize.
Market Restraints
- Aviation fuel cost volatility:Private aviation logistics providers face margin compression from jet fuel price instability that directly impacts executive participant movement costs across remote itineraries.
- Destination management concentration:Vietnam and Thailand currently host limited certified supplier networks, creating bottleneck risks for scaled program deployment during peak corporate booking windows.
- OSHA duty-of-care precedent expansion:US employer liability frameworks now extend to international travel incidents, elevating insurance and risk mitigation costs for cross-border incentive programming.
Strategic Opportunities
- Vietnam infrastructure development:Underpenetrated central Vietnam coastal regions offer white-space potential for integrated resort-experience complexes targeting pharmaceutical account retreats.
- Carbon accounting technology convergence:Integration of emissions tracking platforms with booking systems enables real-time ESG reporting that satisfies EU CSRD audit requirements.
- Hybrid individual-group program architecture:Flexible participant selection models allow tiered reward structures that accommodate both top-performer individual journeys and team-based retreats.
Industry Challenges
- ISO 31030 implementation timelines:Destination management companies face 12-18 month certification cycles that delay market access to risk-averse corporate accounts.
- Multigenerational engagement design:Program architects must reconcile divergent experience preferences between Gen Z memory-seekers and senior executive luxury expectations within single itineraries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Incentive Travel Market |
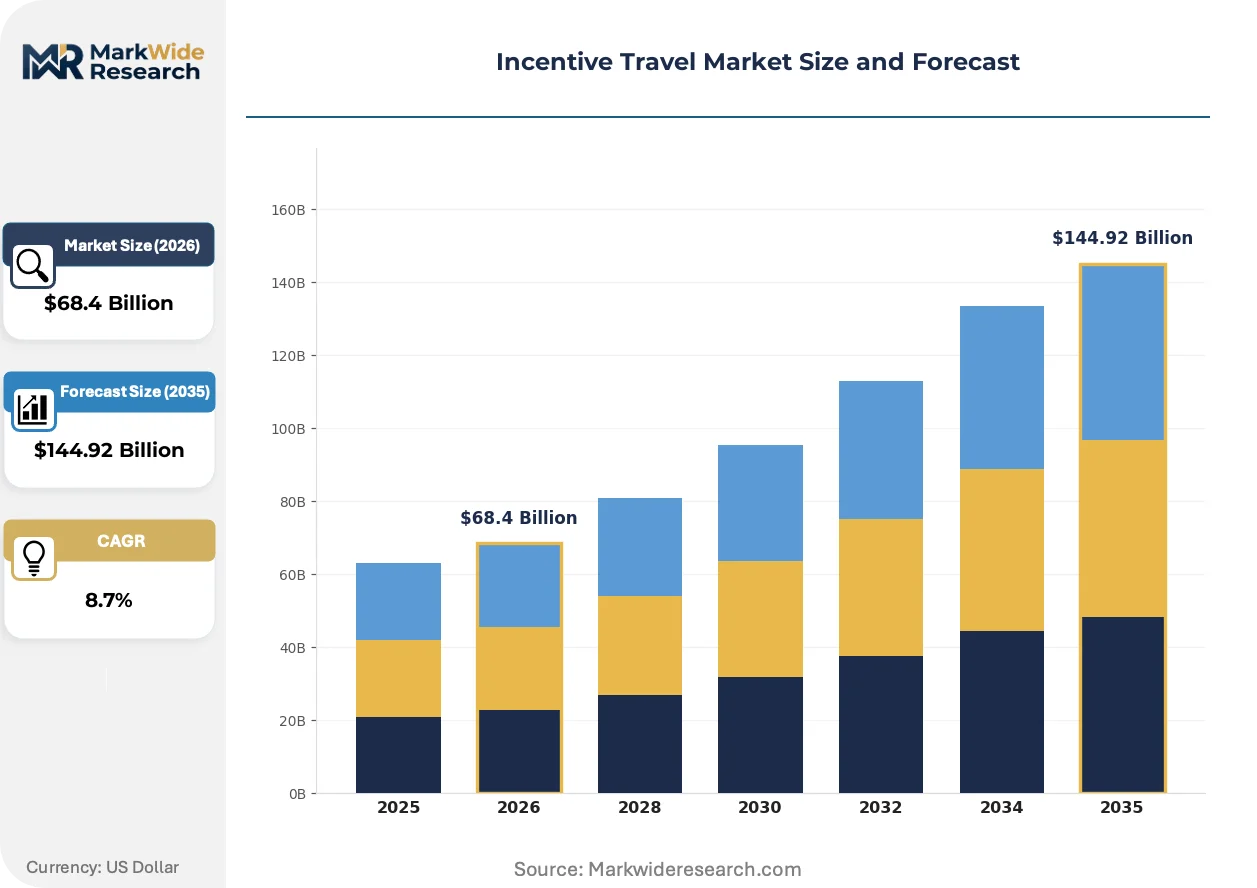
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Travel Type: Domestic, International, Short-haul, Long-haul Incentive Structure: Cash Rewards, Experience Packages, Group Retreats, Performance-Based Trips Industry Vertical: Technology, Pharmaceuticals, Finance, Retail Participant Demographics: Executives, Sales Teams, Top Performers, Mid-level Employees |
| Companies Covered | Crystal Cruises, ITA Group, Intrepid Travel, 212F, MC&A DMC, Regent Seven Seas Cruises, Atlas Ocean Voyages, Air Partner, Silversea Cruises, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Incentive Travel Market Strategic Shifts
Participant data analytics and immersive technology deployment are restructuring how corporate travel managers design, measure, and justify incentive program investments to CFO oversight.
Virtual reality destination pre-visualization is fragmenting traditional site inspection workflows. Pharmaceutical procurement teams now mandate immersive preview experiences before committing to multi-million dollar group programs. This compression of physical scouting requirements is reducing planning cycles from months to weeks while elevating technology-enabled supplier competitive positioning.
EU CSRD sustainability disclosure requirements now mandate granular carbon footprint reporting across Scope 3 travel emissions. Corporate travel managers must integrate destination-level emissions data into quarterly ESG filings. Pharmaceutical and technology verticals are responding fastest, embedding carbon budgeting into program design specifications and disqualifying non-compliant destination partners.
Experience-package procurement now favors modular component assembly over bundled destination management contracts. Corporate buyers increasingly unbundle accommodation, activity architecture, and risk mitigation services to optimize unit economics and participant satisfaction metrics. This unbundling is most visible in North American pharmaceutical accounts, where procurement teams apply pharmaceutical sourcing discipline to travel supplier selection.
Incentive Travel Market Segmentation
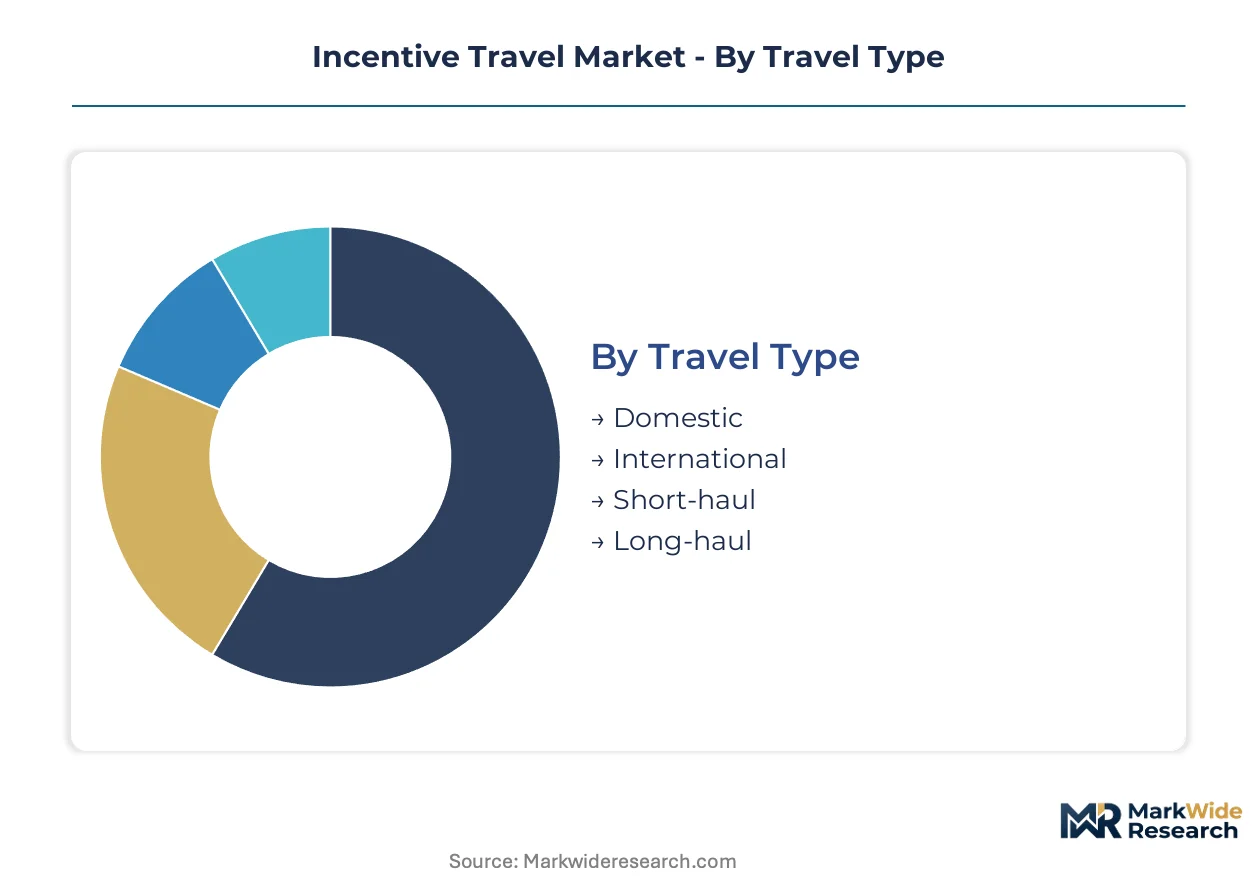
Segmentation in incentive travel determines procurement complexity, margin structure, and risk exposure for corporate travel managers. Each dimension carries distinct supplier qualification requirements and participant engagement protocols that shape program design.
Travel Type:
Domestic programs face the strongest substitution pressure from virtual recognition platforms and local experience vouchers, while international travel retains irreplaceable prestige value.
- International:Extended-duration journeys across multiple destinations requiring complex logistics coordination, visa management, and duty-of-care protocols. Pharmaceutical sales teams in the United States and Germany drive concentrated booking volumes as performance-linked trip structures displace cash bonuses. Extended planning cycles and elevated per-participant costs compress margins for non-certified destination management companies.
- Long-haul:Intercontinental itineraries exceeding eight hours flight time that demand private aviation logistics and jet-lag mitigation programming. Technology sector employers in California and Washington prioritize Southeast Asian destinations including Thailand and Vietnam for memory-creation experiences that support talent retention objectives.
- Domestic:Within-border programming leveraging established supplier networks and simplified risk mitigation frameworks.
- Short-haul:Regional itineraries under four hours flight time emphasizing compressed duration and reduced carbon footprint.
International anchors the volume base while long-haul gains share at the steepest rate.
Incentive Structure:
Cost tier differentiation separates scalable recognition programs from capital-intensive experiential investments, with procurement teams applying divergent sourcing discipline to each.
- Experience Packages:Modular activity architecture combining wellness, cultural immersion, and adventure components into curated participant journeys. Millennial and Gen Z demographics in technology verticals across the United States prioritize memory creation over material rewards, accelerating demand for Thailand's integrated wellness programming.
- Performance-Based Trips:Revenue-threshold-triggered travel rewards replacing traditional cash bonuses in sales force compensation structures. Pharmaceutical accounts in the United States and Germany now mandate ISO 31030 risk certification and ESG disclosure alignment for all destination partners.
- Cash Rewards:Monetary recognition alternatives facing displacement pressure from experiential preference shifts.
- Group Retreats:Team-based programming emphasizing collective achievement recognition and cross-functional relationship building.
Performance-based trips anchor the volume base while experience packages expand most quickly.
Industry Vertical:
Application-specific requirements create divergent supplier capability demands, with regulatory exposure and talent competition intensity determining program sophistication levels.
- Technology:Distributed workforce normalization and competitive talent retention pressures generate substantial incentive travel budgets. Employers in California, Washington, and Texas prioritize experiential memory-creation packages with embedded carbon accounting to satisfy EU CSRD disclosure requirements for multinational operations.
- Pharmaceuticals:Sales force restructuring is replacing cash bonuses with performance-linked travel rewards. Corporate procurement teams apply pharmaceutical sourcing discipline to supplier selection, mandating ISO 31030 certification and granular emissions reporting for destination partners.
- Finance:Conservative risk frameworks and compliance-sensitive participant demographics favor established destination networks with proven duty-of-care protocols.
- Retail:Volume-scaled programs targeting mid-level employee recognition with standardized itinerary templates and compressed planning cycles.
Pharmaceuticals anchors the volume base while technology climbs the fastest.
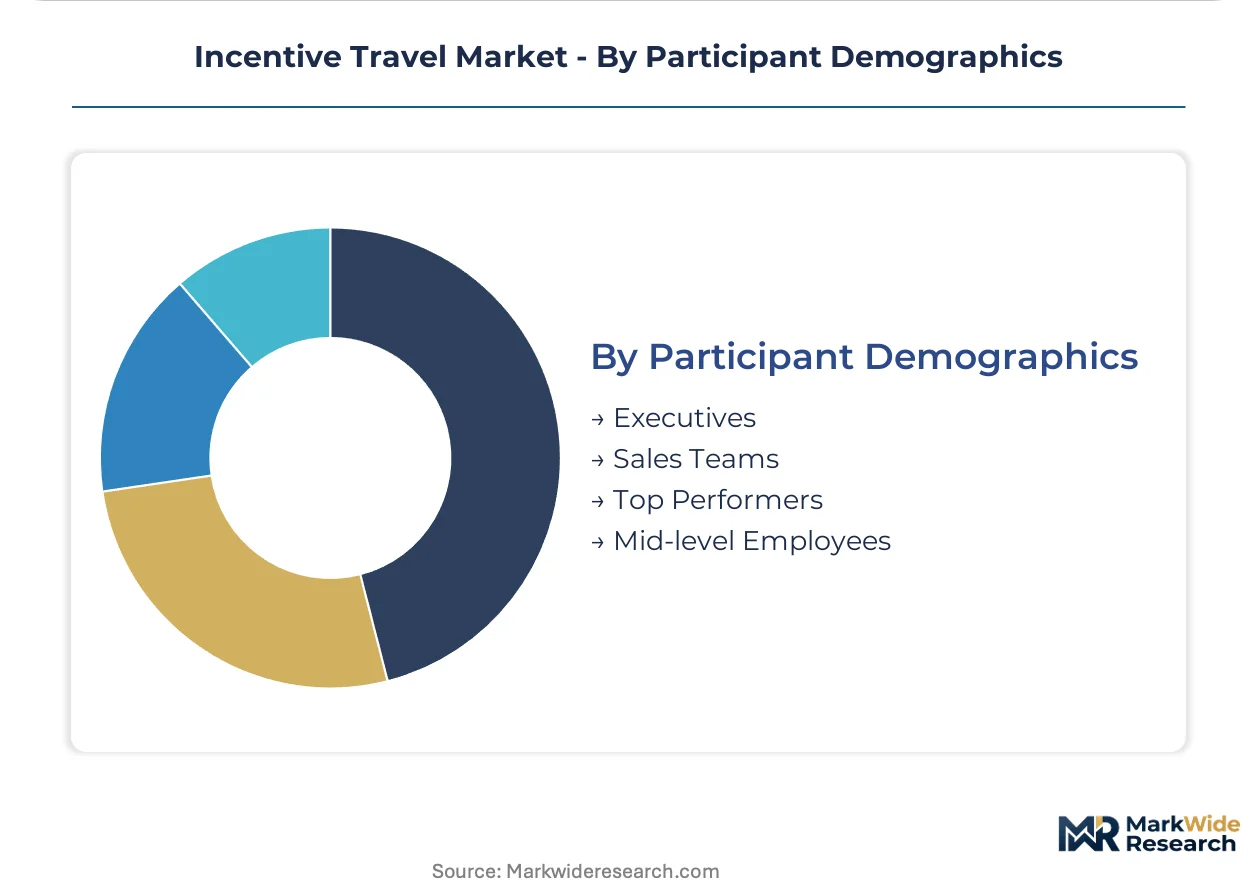
Participant Demographics:
Customer type segmentation determines engagement architecture complexity, with seniority level correlating directly to customization requirements and risk mitigation investment.
- Sales Teams:Group-based programming for revenue-generating personnel with performance-linked qualification thresholds. Pharmaceutical sales teams across the United States and Germany constitute the dominant booking volume, with Thailand and Vietnam emerging as preferred destinations for integrated wellness and cultural programming.
- Executives:Individual or small-cohort journeys demanding private aviation logistics, curated destination immersion, and elevated security protocols. Air Partner and similar providers control executive movement across remote itineraries in Southeast Asia and the Middle East.
- Top Performers:Elite recognition tier combining individual flexibility with premium experience components.
- Mid-level Employees:Scaled group programming emphasizing accessibility and standardized engagement metrics.
Sales teams anchor the volume base while executives gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Destination management capacity clusters in Thailand and Vietnam as pharmaceutical and technology employers concentrate incentive program deployment across Southeast Asian experiential corridors. Supplier certification bottlenecks in these markets create competitive differentiation for ISO-compliant operators.
United States
Pharmaceutical sales force restructuring drives concentrated booking volumes as performance-linked travel rewards displace cash bonuses. OSHA duty-of-care precedents now extend employer liability frameworks to international travel incidents, elevating insurance and risk mitigation investment requirements. California and Texas technology employers anchor domestic demand for experiential memory-creation packages targeting distributed workforce retention.
Germany
EU CSRD disclosure mandates compel corporate travel managers to integrate granular carbon footprint reporting into quarterly ESG filings. The country's national pharmaceutical regulator aligns with broader EU sustainability frameworks that disqualify non-certified destination partners. Bavaria-based pharmaceutical procurement teams apply sourcing discipline mandating ISO 31030 risk certification for all international program vendors.
Thailand
Integrated wellness, cultural immersion, and adventure programming attracts pharmaceutical sales team bookings seeking differentiated experiential rewards. The country's tourism authority enforces sustainability certification requirements that filter supplier access to corporate accounts. Bangkok and Phuket host concentrated destination management company networks serving North American and European pharmaceutical retreat demand.
Vietnam
Underpenetrated central Vietnam coastal regions offer white-space development potential for integrated resort-experience complexes. Limited certified supplier networks create bottleneck risks for scaled program deployment during peak corporate booking windows. Da Nang and Hoi An emerging clusters attract technology sector employers prioritizing memory-creation experiences for millennial and Gen Z talent retention.
United Kingdom
Technology sector competitive talent retention pressures generate substantial incentive travel budgets with embedded carbon accounting requirements. GDPR data protection frameworks extend to participant information management across international program logistics. London-based financial services firms favor established destination networks with proven duty-of-care protocols for executive participant movement.
Incentive Travel Market Competitive Environment
Concentration sits with diversified event technology platforms and specialized aviation logistics providers that control distinct value chain segments. The market structures around three archetypes: integrated destination management companies, proprietary technology platform operators, and private aviation specialists. Strategic moves center on ISO 31030 certification acquisition and carbon accounting technology integration to satisfy EU CSRD audit requirements.
Within the cruise-experience tier, Crystal Cruises and Silversea Cruises exemplify ultra-luxury immersive journey positioning. ITA Group occupies a position among technology-anchored platform operators serving North American pharmaceutical accounts. Air Partner represents the private aviation logistics archetype controlling executive participant movement across remote Southeast Asian itineraries.
| Leading Market Players |
|---|
| Crystal Cruises |
| ITA Group |
| Intrepid Travel |
| 212F |
| MC&A DMC |
| Regent Seven Seas Cruises |
| Atlas Ocean Voyages |
| Air Partner |
| Silversea Cruises |
| Others |
Value Chain & Pricing Dynamics
ISO 31030 certification requirements gate both supplier qualification and price differentiation simultaneously, compelling destination management companies to absorb 12-18 month compliance costs while pharmaceutical procurement teams apply tiered sourcing discipline that separates certified premium operators from uncertified economy alternatives.
Pricing Analysis
EU CSRD disclosure mandates dictate the pricing tier structure across corporate incentive travel procurement. Three-tier pricing structure across premium, standard, and economy levels separates ISO-certified destination partners with embedded carbon accounting from uncertified operators facing disqualification. Price differentiation rests on certification grade and geographic delivery cost, with Southeast Asian suppliers commanding premiums for integrated wellness programming. Cost compression in the economy tier is intensifying because aviation fuel volatility erodes margins for non-specialized logistics providers. Mid-level pharmaceutical accounts demonstrate highest price sensitivity, while technology sector employers prioritize experience quality over unit cost minimization.
Supply Chain Analysis
Port congestion across Pacific trade lanes elevates inbound logistics costs for experiential equipment and wellness programming imports into Thailand and Vietnam. Geographic supply concentrates in Thailand, Vietnam, and the United States, with Bangkok and Phuket hosting dense destination management networks while central Vietnam remains underpenetrated. Raw material dependencies include sustainable aviation fuel, luxury accommodation inventory, and certified activity infrastructure. Single-source vulnerability in certified supplier networks creates bottleneck risks during peak pharmaceutical booking windows. Distribution runs through direct corporate procurement relationships and specialized incentive travel management companies serving North American and European accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Virtual recognition platforms and local experience vouchers threaten to displace domestic incentive programming, forcing incumbent destination management companies to defend irreplaceable prestige value in international experiential travel.
For Market Incumbents: Fortify market position by accelerating ISO 31030 certification completion to capture risk-averse pharmaceutical accounts, while embedding carbon accounting technology to satisfy EU CSRD audit requirements. Backward integration into private aviation logistics reduces exposure to fuel cost volatility and secures executive participant movement control across remote Southeast Asian itineraries. For New Entrants and Emerging Players: Carbon accounting technology integration represents a service-layer gap where incumbent destination management companies under-serve EU CSRD disclosure requirements. White-space concentration in central Vietnam coastal regions offers resort-experience complex development potential for technology sector millennial retention programs. Modular component assembly procurement patterns favor unbundled accommodation and activity architecture specialists over bundled destination contracts. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed event technology platform operators seeking exit liquidity after multi-year pharmaceutical account consolidation. Long-term viability across the analysis window hinges on regulatory compliance technology integration rather than pure destination inventory ownership. Watch ISO 31030 certification completion rates as inflection indicator for supplier competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 31030 Certification Acquisition | Mandatory market access gate for pharmaceutical procurement teams mandating risk management protocols. |
| Carbon Accounting Platform Integration | Enables real-time Scope 3 emissions reporting that satisfies EU CSRD quarterly disclosure requirements. |
| Private Aviation Logistics Expansion | Controls executive participant movement across remote Thailand and Vietnam itineraries for technology accounts. |
| Central Vietnam Resort Development | Captures white-space demand from technology employers prioritizing millennial memory-creation experiences. |
| Hybrid Individual-Group Program Architecture | Accommodates tiered reward structures for both top-performer journeys and team-based pharmaceutical retreats. |
Study Parameters
Cross-validation between primary interviews with corporate travel managers and secondary validation through SEC filings, EU regulatory databases, and destination management company sustainability reports anchors the qualitative findings. Stakeholder roles engaged include pharmaceutical procurement directors, technology sector HR executives, destination management company operators, private aviation logistics coordinators, and sustainability certification auditors. Bottom-up triangulation across booking volume data and top-down validation through corporate travel budget disclosures ensure methodological rigor.
Sensitivity analysis around aviation fuel cost assumptions and certification completion timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include travel type, incentive structure, industry vertical, and participant demographics, with regional regulatory cluster as an additional travel-specific dimension. CAGRs derive from trend extrapolation adjusted for substitution effects and compliance-driven supplier disqualification rates. Forecast inputs incorporate EU CSRD implementation pace and OSHA duty-of-care precedent expansion.
Forecasts assume regulatory continuity in EU CSRD disclosure regimes and US OSHA liability frameworks; material policy shifts would require re-modeling. Specific risks that could revise projections include accelerated virtual recognition platform substitution, destination management company certification bottlenecks, and sustained aviation fuel price volatility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Asia-Pacific Tourism Market
Travel and Tourism
Water Park Market
Travel and Tourism
Travel and Tourism Market
Travel and Tourism
Maldives Hospitality Market
Travel and Tourism
China Outbound Travel Market
Travel and Tourism
Halal Tourism Market
Travel and Tourism
Global Enotourism Market
Travel and Tourism
Wedding Tourism Market
Travel and Tourism
MICE Travel Service Market
Travel and Tourism
Tourism Vehicle Rental Market
Travel and Tourism
GCC Outbound Tourism Market
Travel and Tourism
New Zealand Sports Tourism Market
Travel and Tourism
North America Pet Travel Services Market
Travel and Tourism
Educational Tourism Market
Travel and Tourism
Europe Wellness Tourism Market
Travel and Tourism
Germany Outbound Tourism Market