
 Singapore Travel Retail Market | 2026-2036
Singapore Travel Retail Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Travel Retail Market Analytics
Singapore is fragmenting its travel retail footprint across Jewel Changi Airport and expanded terminal concessions. Changi Airport Group leverages its monopoly over airport real estate to control premium lease structures. WH Smith competes through convenience-store density in departure gates. Lotte Duty Free anchors the beauty and fragrance corridor with Korean product specialization.
Singapore travel retail encompasses duty-paid and duty-free merchandise sold to international passengers in airport, downtown, and in-flight environments, operating under strict customs-controlled supply chains with bonded warehousing and passenger verification protocols. The primary commercial purpose is capturing discretionary spending from transit passengers with limited alternative shopping windows. Cosmetics and electronics dominate transaction value, with alcohol retaining margin density despite volume constraints from liquid carry-on rules. Store format segmentation reveals duty-free shops occupying the highest square-meter productivity tier, while online pre-ordering through airport kiosks captures time-pressed business travelers.
Singapore Customs administers the duty-free concession framework, while the Civil Aviation Authority of Singapore regulates terminal commercial zoning. The Inland Revenue Authority of Singapore's tourist GST refund scheme directly shapes price positioning against downtown competitors. Stakeholders must monitor passenger traffic recovery trajectories and Chinese visa policy adjustments to calibrate inventory and staffing commitments.
Market Dynamics
Chinese tourist spending patterns are fragmenting Singapore travel retail demand across duty-free corridors and downtown GST-refund zones, forcing operators to rebalance inventory density between Changi Airport terminals and city-center collection points.
Growth Catalysts
- Inland Revenue Authority of Singapore Tourist Refund Scheme:Departing visitors reclaim GST on purchases above minimum thresholds, narrowing price gaps between airport duty-free and downtown retail.
- Transit passenger dwell-time extension:Changi Airport's Jewel complex and integrated terminal walkways lengthen passenger exposure to retail environments beyond traditional gate-side concessions.
- K-beauty product specialization:Korean cosmetics brands anchor fragrance and skincare corridors, capturing Chinese tourist preference shifts toward Asian-origin luxury goods.
Market Restraints
- Liquid carry-on restrictions:International aviation security protocols limit alcohol and large-format cosmetic volumes, compressing margin-rich category sales despite high unit profitability.
- Passenger traffic concentration:Changi Airport Group's monopoly over terminal real estate constrains lease negotiation leverage for retail operators.
- Chinese visa policy volatility:Bilateral travel documentation requirements create demand forecasting uncertainty for inventory and staffing commitments.
Strategic Opportunities
- Online pre-order kiosk networks:Digital reservation systems with airport collection points capture time-constrained business travelers who bypass traditional browsing.
- Terminal 5 expansion footprint:Planned capacity additions will create fresh concession allocations for specialty retailers beyond existing Jewel and Terminal 1-4 saturation.
- Singapore Customs bonded warehousing optimization:Streamlined duty-free supply chain protocols reduce working capital requirements for inventory staging.
Industry Challenges
- Multilingual sales associate recruitment:Mandarin and Korean language capabilities are essential for Chinese and Korean tourist segments, tightening talent pools.
- Legacy POS-terminal integration:GST refund processing systems require real-time customs verification links, complicating checkout infrastructure upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Travel Retail Market |
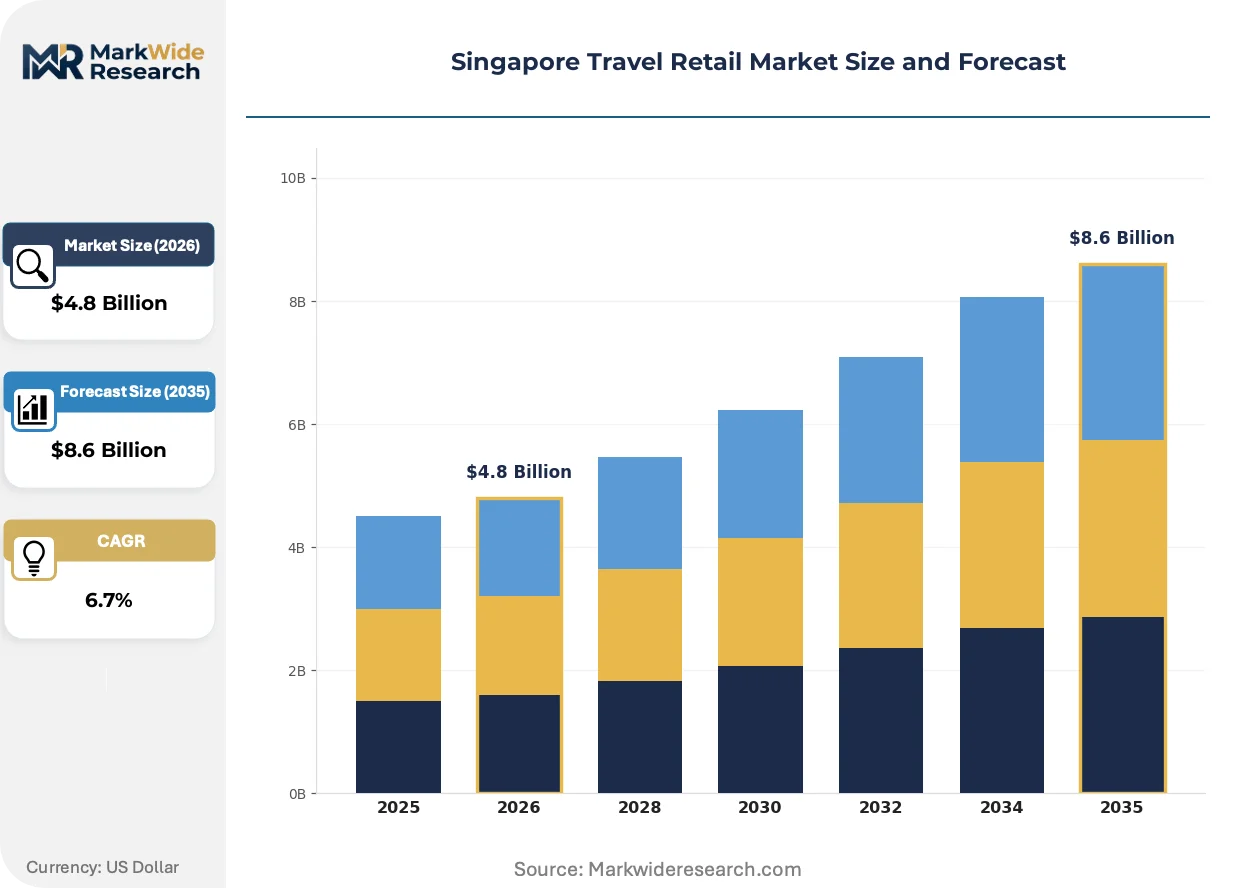
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
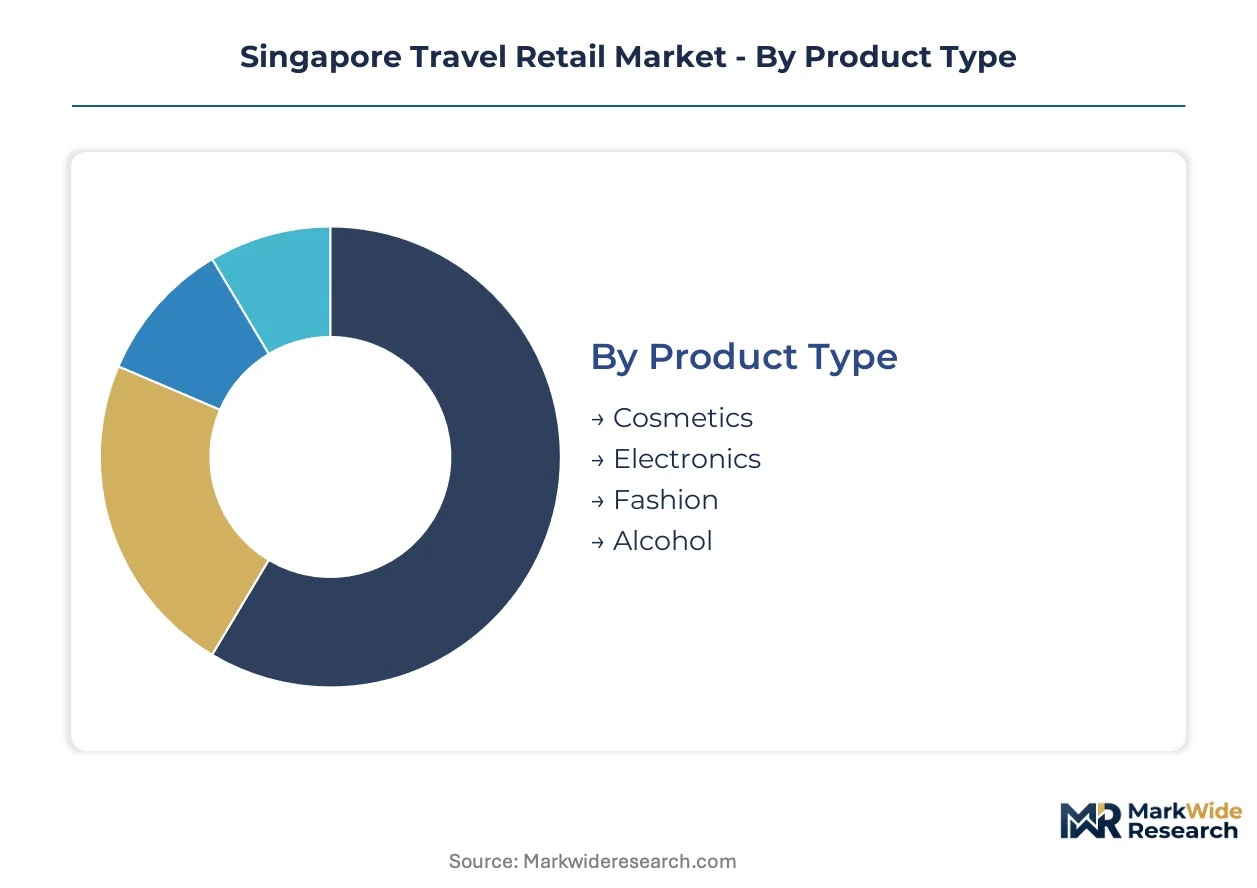
| Segmentation | Product Type: Cosmetics, Electronics, Fashion, Alcohol Consumer Type: Tourists, Business Travelers, Locals, Expatriates Store Format: Duty-Free Shops, Convenience Stores, Specialty Retailers, Supermarkets Sales Channel: Online, Offline, Airport Kiosks, In-Flight |
| Companies Covered | Changi Airport Group, WH Smith, Lagardère Travel Retail, Jewel Changi Airport, Gebr. Heinemann, Lotte Duty Free, DFS, iShopChangi, The Shilla Duty Free, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Travel Retail Market Evolving Landscape
Digital integration is compressing the traditional browse-and-buy cycle into pre-trip reservation and grab-and-go collection models. Retailers are racing to capture passenger attention before airport arrival through mobile platforms and loyalty program pre-loading.
Mobile pre-order platforms are collapsing the distinction between discovery and transaction phases in travel retail. Chinese tourists now browse duty-free catalogs on WeChat mini-programs before departure, arriving at Changi with purchase intentions already formed. This behavioral compression is forcing operators to shift square-meter productivity metrics from dwell-time conversion to fulfillment speed.
Singapore Customs administers tightened verification protocols for GST refund claims, requiring item-by-item inspection at departure gates. The regulatory friction is pushing retailers toward integrated digital receipt systems that pre-validate purchases against passenger itineraries. Electronics and high-value cosmetics categories face the strictest documentation requirements, prompting concessionaires to embed customs-compliant tagging at point of sale.
Destination shopping is displacing impulse browsing as the dominant travel retail mode. Chinese tourists now research Singapore-exclusive product bundles and limited editions through Xiaohongshu and Douyin before travel, arriving with specific purchase targets. This pre-commitment pattern concentrates transaction value in pre-identified SKUs while compressing discovery-driven exploration of full product ranges.
Singapore Travel Retail Market Segmentation
Singapore travel retail operators calibrate inventory mix and service intensity across distinct passenger profiles and purchase contexts. Segmentation reveals where margin compression versus volume concentration occurs within Changi Airport's constrained commercial footprint.
Product Type:
After-sales service intensity varies sharply across categories, with cosmetics requiring sampling consultation while electronics demand warranty documentation support.
- Cosmetics:Skincare and fragrance portfolios dominate transaction value through Korean brand specialization. Chinese tourists concentrate purchases at Lotte Duty Free corridors in Jewel Changi Airport, drawn by exclusive regional launches unavailable in mainland retail. Sampling stations and Mandarin-speaking beauty advisors compress conversion cycles for time-pressed transit passengers.
- Electronics:Mobile accessories, noise-canceling headphones, and regional voltage appliances anchor this segment. Singapore Customs' tightened GST refund verification protocols impose item-by-item inspection requirements, forcing retailers to embed compliant digital receipt systems at point of sale for high-value devices.
- Fashion:Limited-edition collaborations and Southeast Asia-exclusive colorways capture destination shoppers. Singapore's tropical climate influences lightweight fabric preferences among European and North Asian visitors.
- Alcohol:Premium spirits and regional wine selections retain margin density despite liquid carry-on restrictions constraining volume. Changi Airport's bonded warehousing optimization reduces working capital requirements for aged inventory staging.
By volume, Cosmetics leads. By growth pace, Electronics is ahead.
Consumer Type:
Application context shapes everything from browsing duration to price sensitivity and loyalty program engagement depth.
- Tourists:Chinese visa policy volatility creates demand forecasting uncertainty for inventory commitments. This segment concentrates spending in duty-free cosmetics and GST-refund eligible downtown purchases, with Xiaohongshu research pre-committing purchase targets before airport arrival.
- Business Travelers:Time-compressed itineraries favor online pre-order kiosk networks with grab-and-go collection. Mobile platform penetration through WeChat mini-programs collapses discovery-transaction cycles into fulfillment speed metrics.
- Locals:Singapore residents access duty-paid travel retail through downtown collection points and Jewel Changi Airport's public-facing zones. GST-inclusive pricing narrows arbitrage against suburban mall alternatives.
- Expatriates:Regional residents leverage transit connections to access Singapore-exclusive product bundles. Multilingual sales associate recruitment tightens talent pools for Korean and Mandarin capabilities.
Tourists generate highest per-passenger yield. Business travelers are expanding most quickly through digital channel migration.
Store Format:
Margin structure and square-meter productivity diverge based on real estate control and passenger dwell-time capture mechanics.
- Duty-Free Shops:Bonded warehousing and customs-controlled supply chains enable tax-advantaged pricing. Changi Airport Group's monopoly over terminal real estate constrains lease negotiation leverage, compressing operator margins despite highest revenue per square meter.
- Convenience Stores:WH Smith competes through departure gate density, capturing impulse snack and reading material purchases. Limited browsing windows favor grab-and-go formats over experiential retail.
- Specialty Retailers:Curated brand houses and category-dedicated corridors anchor destination shopping behavior. Korean cosmetics specialization creates differentiation against generic duty-free assortments.
- Supermarkets:Local food products and regional confectionery target expatriate gift purchasers. Singapore Customs verification protocols apply differentially to consumable versus durable categories.
Duty-Free Shops dominate revenue concentration. Specialty Retailers are gaining share fastest through brand exclusivity positioning.
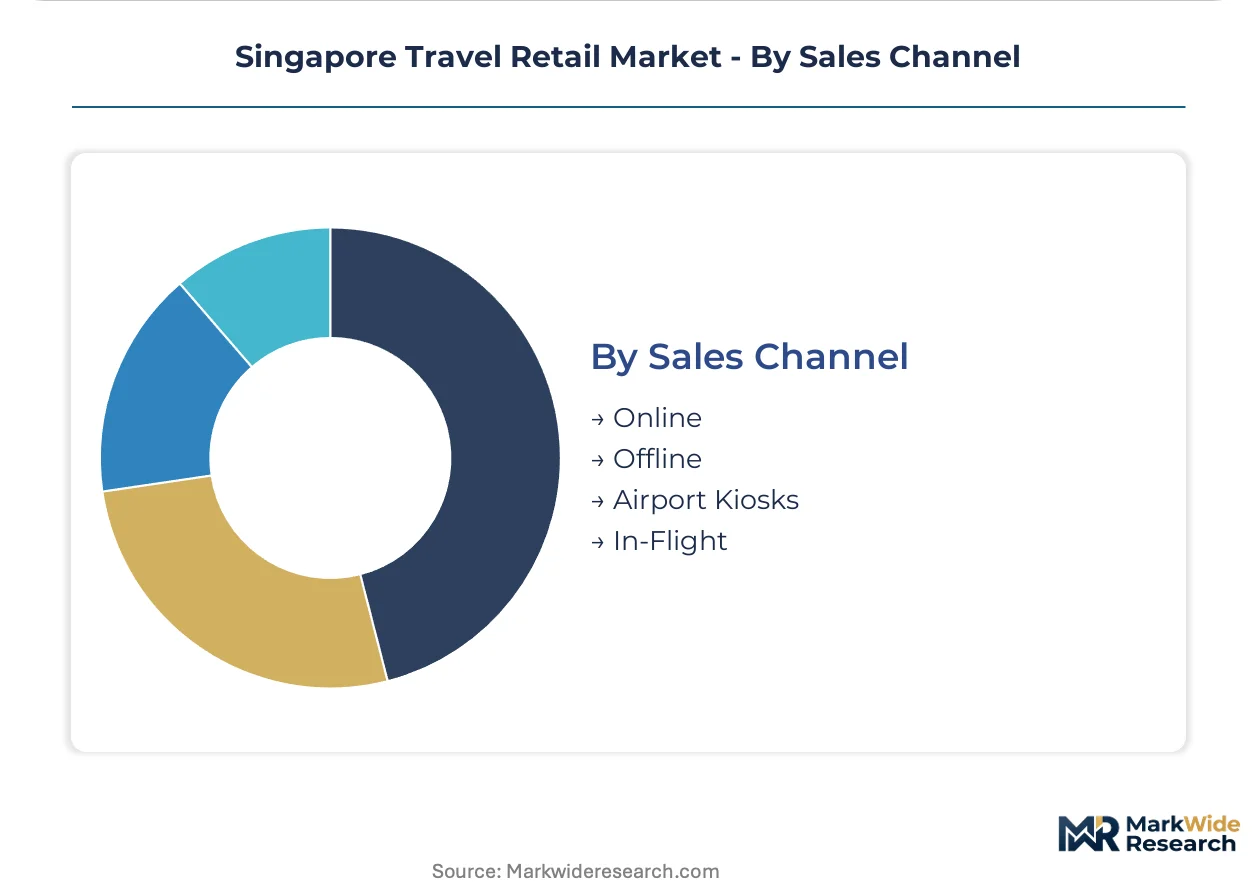
Sales Channel:
Supply chain configuration and passenger verification protocol integration determine channel viability and working capital intensity.
- Online:Mobile pre-order platforms with airport collection points capture attention before physical arrival. Inland Revenue Authority of Singapore's tourist refund scheme integration requires real-time customs verification links, complicating checkout infrastructure.
- Offline:Traditional browse-and-buy cycles persist in Jewel Changi Airport's experiential retail zones. Terminal 5 expansion will create fresh concession allocations beyond existing saturation.
- Airport Kiosks:Self-service collection points reduce staffing requirements for pre-committed purchases. Legacy POS-terminal integration challenges persist across GST refund processing systems.
- In-Flight:Catalog-based sales with post-purchase delivery face compression from liquid carry-on restrictions and pre-trip digital research habits. Singapore Airlines' KrisShop competes through loyalty program pre-loading.
Offline retains transaction volume leadership. Online is climbing the fastest through behavioral compression of purchase cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Inland Revenue Authority of Singapore anchors commercial policy for this city-state travel retail jurisdiction. Singapore Customs administers bonded warehousing and duty-free verification protocols. The Civil Aviation Authority of Singapore regulates terminal commercial zoning across Changi Airport's integrated retail corridors.
Changi Airport Precinct
Jewel Changi Airport and Terminals 1-4 concentrate passenger dwell-time extension through integrated walkways and experiential retail zones. The GST refund scheme for departing visitors narrows price gaps between airport duty-free and downtown collection points. Lotte Duty Free and The Shilla Duty Free anchor the beauty corridors in this cluster.
Downtown Core
Marina Bay and Orchard Road shopping belts capture GST-refund eligible purchases from Chinese tourists researching Singapore-exclusive bundles on Xiaohongshu. Singapore Customs' tightened verification protocols push retailers toward integrated digital receipt systems. DFS and Gebr. Heinemann operate flagship collection points in this zone.
Sentosa Island
Resort World Sentosa and integrated entertainment complexes draw leisure tourists with extended Singapore stays. The Inland Revenue Authority of Singapore's tourist refund scheme applies differentially to consumable versus durable categories here. Lagardère Travel Retail maintains convenience-store density across ferry terminals.
Jurong Lake District
Planned commercial expansion will create secondary retail footprints beyond Changi Airport saturation. Singapore Customs bonded warehousing optimization reduces working capital requirements for inventory staging in this emerging zone. iShopChangi pre-order kiosks extend digital capture into western catchment areas.
Greater Southern Waterfront
Tanjong Pagar terminal redevelopment and cruise passenger corridors diversify travel retail touchpoints beyond air transit. The Civil Aviation Authority of Singapore's zoning influence diminishes here, shifting regulatory framing to Maritime and Port Authority of Singapore oversight. WH Smith competes through grab-and-go formats in ferry and cruise terminals.
Singapore Travel Retail Market Competitive Landscape
Capability concentration sits with airport real estate controllers; scale advantage sits with global duty-free operators. Changi Airport Group's monopoly over terminal concessions constrains lease negotiation leverage for retail tenants. Two strategic archetypes dominate: integrated airport developers and specialized duty-free concessionaires. Competitive moves center on digital pre-order platform deployment and Korean cosmetics exclusivity contracting.
Within the airport developer tier, Changi Airport Group exemplifies real estate control over premium lease structures. Among global duty-free specialists, Lotte Duty Free and The Shilla Duty Free occupy positions anchored by K-beauty product specialization and Chinese tourist segment capture. WH Smith represents the convenience-store density archetype competing through departure gate proximity rather than experiential retail investment.
| Leading Market Players |
|---|
| Changi Airport Group |
| WH Smith |
| Lagardère Travel Retail |
| Jewel Changi Airport |
| Gebr. Heinemann |
| Lotte Duty Free |
| DFS |
| iShopChangi |
| The Shilla Duty Free |
| Others |
Value Network & Pricing Analysis
Korean cosmetics manufacturers anchor upstream supply for Singapore travel retail's highest-margin category, concentrating pricing power with Lotte Duty Free and The Shilla Duty Free as gatekeepers of K-beauty exclusivity. Changi Airport Group's monopoly over terminal real estate transfers this supplier leverage into premium lease structures that compress operator margins while inflating downstream shelf prices.
Pricing Analysis
Price spreads between airport duty-free and downtown GST-refund zones have narrowed to single-digit percentages under Inland Revenue Authority of Singapore policies. Three-tier pricing structure across premium, standard, and economy levels differentiates Korean exclusive launches from mass-market SKUs and entry-level travel sizes. Pricing pressure stems from Chinese tourist pre-commitment behaviors formed on Xiaohongshu before airport arrival, collapsing impulse-driven margin capture. Tourists exhibit lowest price sensitivity for Singapore-exclusive bundles, while time-compressed business travelers prioritize fulfillment speed over cost comparison.
Supply Chain Analysis
Extended payment terms from Singapore Customs bonded warehousing facilities reduce working capital requirements for inventory staging at Changi Airport. Supply draws from South Korea for K-beauty, France for luxury fragrance, and Japan for electronics regional voltage adaptations. Single-source vulnerability concentrates in Korean cosmetics exclusivity contracts that lock competitors out of high-yield corridors. Distribution runs through customs-controlled bonded warehouses with passenger verification protocols at departure gates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore travel retail incumbents face substitution pressure from downtown GST-refund zones and mobile pre-order platforms that collapse the airport's captive-audience advantage. Defense requires locking in exclusivity windows and compressing fulfillment friction.
For Market Incumbents: Entrench K-beauty exclusivity through multi-year contracts with Korean houses before Terminal 5 concession allocations open. Deepen backward integration into Singapore Customs-compliant digital receipt systems to accelerate GST refund processing against tightening verification protocols. Channel control through Jewel Changi Airport's experiential zones defends against downtown collection point substitution. For New Entrants and Emerging Players: Jurong Lake District's planned commercial expansion offers underpenetrated secondary retail footprints beyond Changi Airport saturation. Target business traveler segments through WeChat mini-program pre-order interfaces with grab-and-go kiosk collection, bypassing the multilingual sales associate recruitment bottleneck that constrains incumbents. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across online pre-order platform infrastructure as cloud deployment reduces fixed POS-terminal integration costs. Long-term viability centers on digital-physical hybrid models with customs verification pre-embedded at point of sale. Acquisition targets should show integrated digital receipt capability and Mandarin-speaking talent pools. Monitor Chinese visa policy adjustments as the critical demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| K-Beauty Exclusivity Contracting | Locks margin-rich Korean cosmetics corridors away from competitor access at Jewel Changi Airport. |
| Digital Pre-Order Platform Deployment | Captures Xiaohongshu-researching Chinese tourists before physical airport arrival compresses discovery cycles. |
| Terminal 5 Concession Positioning | Secures fresh retail footprints before existing Jewel and Terminal 1-4 saturation constrains growth. |
| Singapore Customs Compliance Integration | Embeds item-by-item verification tagging at point of sale for tightened GST refund protocols. |
| Multilingual Talent Pipeline Investment | Addresses Mandarin and Korean capability scarcity that tightens conversion cycles for core tourist segments. |
Research Methodology
A standing panel of airport concession managers, duty-free procurement directors, Chinese tourist travel planners, and Singapore Customs officials provided ongoing calibration for this study. Primary interviews with these stakeholders combined with secondary validation against Civil Aviation Authority of Singapore zoning filings, Inland Revenue Authority of Singapore tourist refund statistics, and Changi Airport Group passenger traffic disclosures. Bottom-up SKU-level transaction modeling and top-down sector revenue aggregation triangulated market sizing.
Scenario-bracketing framed demand projections across passenger traffic recovery trajectories and Chinese visa policy volatility. Segmentation dimensions modeled include product category, consumer type, store format, and sales channel across the projection horizon. CAGRs derived from trend-line extrapolation adjusted for regulatory inflection points and competitive entry timing. Forecast inputs incorporated GST refund scheme utilization rates and K-beauty brand launch calendars.
Practitioners should monitor Chinese visa policy adjustments, Singapore Customs verification protocol tightening, and Terminal 5 construction timelines for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Asia Pacific Wellness Travel Market
Travel and Tourism
Domestic Tourism Market
Travel and Tourism
North America Pet Travel Services Market
Travel and Tourism
Wedding Tourism Market
Travel and Tourism
Special Interest Tourism Market
Travel and Tourism
Ethno Tourism Community Based Eco Tourism Market
Travel and Tourism
Asia Pacific Wellness Tourism Market
Travel and Tourism
Travel and Tourism Market
Travel and Tourism
USA Sports Tourism Market
Travel and Tourism
India Travel Retail Market
Travel and Tourism
Tourism Vehicle Rental Market
Travel and Tourism
Halal Tourism Market
Travel and Tourism
France Luxury Travel Market
Travel and Tourism
Germany Outbound Tourism Market
Travel and Tourism
Educational Tourism Market
Travel and Tourism
New Zealand Sports Tourism Market