
 Hong Kong Outbound Tourism Market | 2026-2036
Hong Kong Outbound Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Hong Kong Outbound Tourism Market Foresight
Modular tour packaging is realigning how Hong Kong residents assemble outbound trips, with travelers mixing self-booked flights, third-party accommodations, and local activity vouchers into personalized itineraries rather than purchasing fixed bundles. China Travel Service (Hong Kong) Limited leverages its mainland China network to anchor cross-border rail-and-hotel combinations. EGL Tours Company Limited competes through cruise-and-resort pairings targeting family segments. Hong Thai Travel Services Ltd. specializes in ad-hoc group charter arrangements for corporate and association departures.
Hong Kong outbound tourism comprises resident departures for temporary stays outside the Special Administrative Region, encompassing air, sea, and land crossings with average trip durations spanning two to fourteen nights and booking lead times compressing to under thirty days for short-haul routes. The primary commercial purpose is foreign exchange outflow for experiential consumption, generating commission and fee revenue across transport, lodging, and activity intermediaries. Leisure destination types occupy the largest volume share, while medical travel purpose segments command the highest per-trip expenditure due to bundled healthcare and recuperation stays. Online travel agencies are displacing traditional travel agents as the dominant booking channel among millennials, though direct airline and hotel app bookings are capturing growing share for simple city-break itineraries.
The Hong Kong Tourism Board coordinates outbound promotion schemes alongside the Immigration Department's e-visa facilitation partnerships, while destination countries enforce health screening protocols through their national border control agencies. These frameworks shape demand by determining which destinations receive marketing support and which entry requirements constrain spontaneous booking behavior. Stakeholders must monitor evolving visa reciprocity agreements and health credential recognition systems to anticipate corridor-specific volume shifts.
Market Dynamics
Modular itinerary assembly is fragmenting Hong Kong's traditional tour package market, compressing booking lead times below thirty days and forcing intermediaries to unbundle fixed bundles into flight-hotel-activity components.
Growth Catalysts
- E-Visa Facilitation Partnerships:The Immigration Department's streamlined digital entry protocols with Japan, South Korea, and Taiwan reduce friction for spontaneous departures. Hong Kong residents complete applications within 48 hours.
- Millennial Booking Behavior:Travelers aged 28-43 now dominate long-haul reservation volumes, prioritizing experiential consumption over standardized sightseeing circuits. This cohort drives demand for self-curated multi-city itineraries.
- Medical Travel Infrastructure:Thailand and Singapore have expanded recuperation-stay licensing for post-procedure visitors, bundling healthcare with extended accommodation. Per-trip expenditure in this segment exceeds leisure departures substantially.
Market Restraints
- Aviation Slot Concentration:Hong Kong International Airport's runway capacity constraints during peak departure windows limit seat supply to secondary Japanese and Southeast Asian destinations. Carriers prioritize trunk routes.
- Currency Volatility Exposure:Yen and won fluctuations against the Hong Kong dollar create pricing uncertainty for repeat visitors to Japan and South Korea, dampening advance commitment rates.
- Health Credential Recognition Gaps:Inconsistent mutual recognition of vaccination records between Hong Kong and certain Southeast Asian border control agencies forces duplicate documentation and itinerary abandonment.
Strategic Opportunities
- Vietnam Coastal Expansion:Da Nang and Phu Quoc remain underpenetrated relative to Thai beach destinations, presenting white space for resort-and-flight combinations targeting family segments.
- Rail-Land Corridor Development:Cross-border high-speed rail integration with mainland China enables multi-city itineraries combining Guangdong, Guilin, and Hunan without aviation dependency.
- Corporate Retreat Specialization:Association and incentive departures to secondary Japanese onsen towns offer higher margin capture than standardized leisure packages, with lower competitive density.
Industry Challenges
- Legacy System Integration:Traditional travel agencies struggle to connect fragmented booking APIs from low-cost carriers and independent accommodation platforms into unified customer-facing interfaces.
- Specialized Product Talent Scarcity:Medical travel packaging requires staff with dual competency in healthcare liaison and hospitality logistics, a combination absent from conventional tour operator training pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hong Kong Outbound Tourism Market |
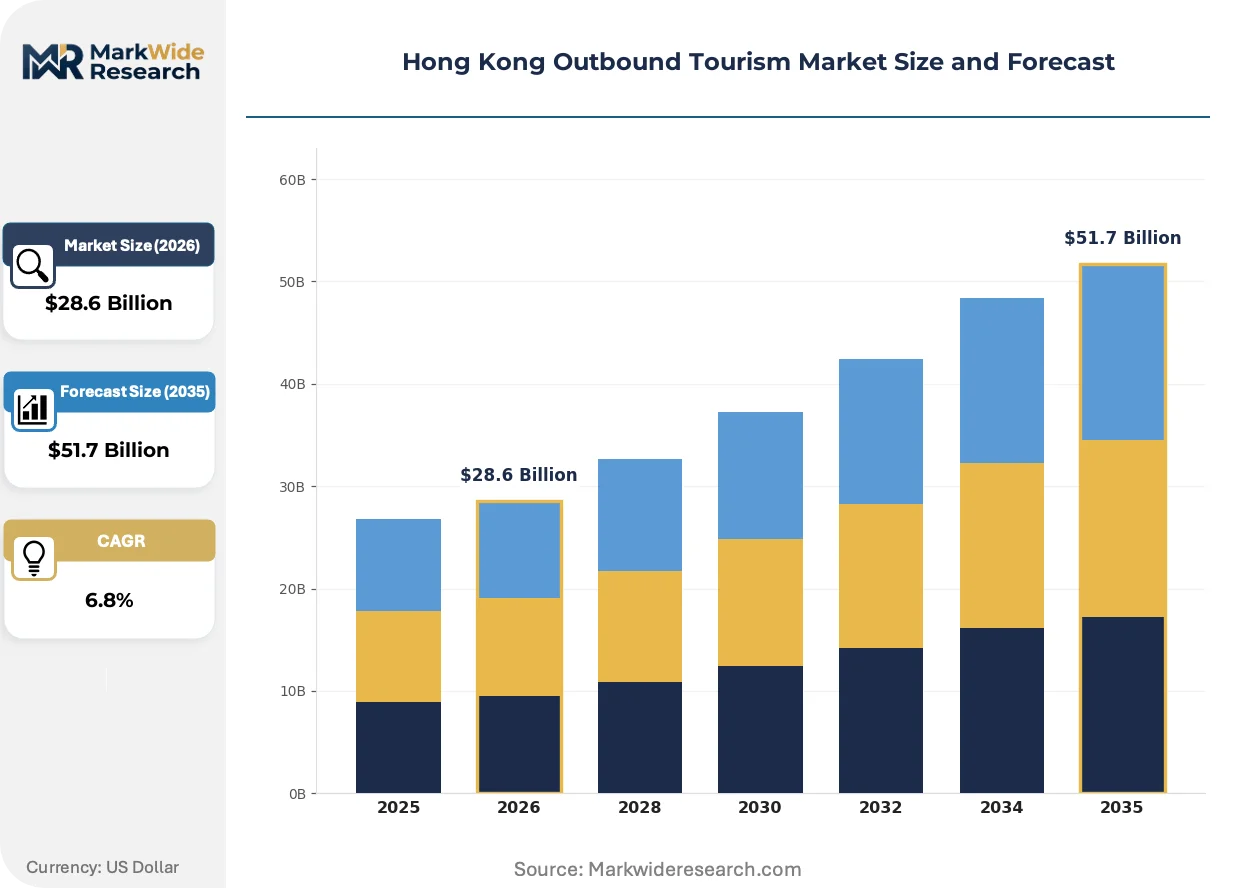
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Destination Type: Leisure, Business, Adventure, Cultural Customer Demographic: Families, Millennials, Seniors, Couples Travel Purpose: Vacation, Education, Medical, Religious Booking Channel: Online Travel Agencies, Direct Booking, Travel Agents, Mobile Apps |
| Companies Covered | China Travel Service (Hong Kong) Limited, EGL Tours Company Limited, Hong Thai Travel Services Ltd., Wing On Travel Service Ltd., Travel Expert (H.K.) Limited, China CYTS Tours Holding Co., Ltd., CTS HK Express (CTS Group), Nam Ho Travel Service (Hong Kong) Co., Ltd., Chan Brothers Travel (Hong Kong) Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hong Kong Outbound Tourism Market Shifts & Advancements
Digital distribution infrastructure is compressing the Hong Kong outbound booking funnel, collapsing the traditional travel agent intermediary layer while enabling real-time inventory aggregation across previously siloed suppliers.
Artificial intelligence recommendation engines are automating itinerary construction by cross-referencing traveler preference data with live availability across airlines, hotels, and activity vendors. Millennial users adopt these tools for 60-70% of short-haul bookings. The technology is automating the matching process that previously required human agent consultation, reducing search-to-purchase cycles from days to hours.
The Hong Kong Tourism Board's coordination with the Immigration Department on outbound promotion schemes is reshaping corridor-specific marketing investment. Destinations receiving official partnership designation gain preferential placement in digital campaigns and travel fair positioning. Japan and South Korea currently absorb the largest share of this coordinated promotional resource allocation.
Channel disintermediation is accelerating as direct airline and hotel application bookings capture simple city-break itineraries previously routed through online travel agencies. Short-haul routes to Taipei, Osaka, and Bangkok show the highest direct booking penetration. This shift concentrates commission pressure on intermediaries while rewarding asset owners with improved yield management control and customer data retention.
Hong Kong Outbound Tourism Market Segmentation
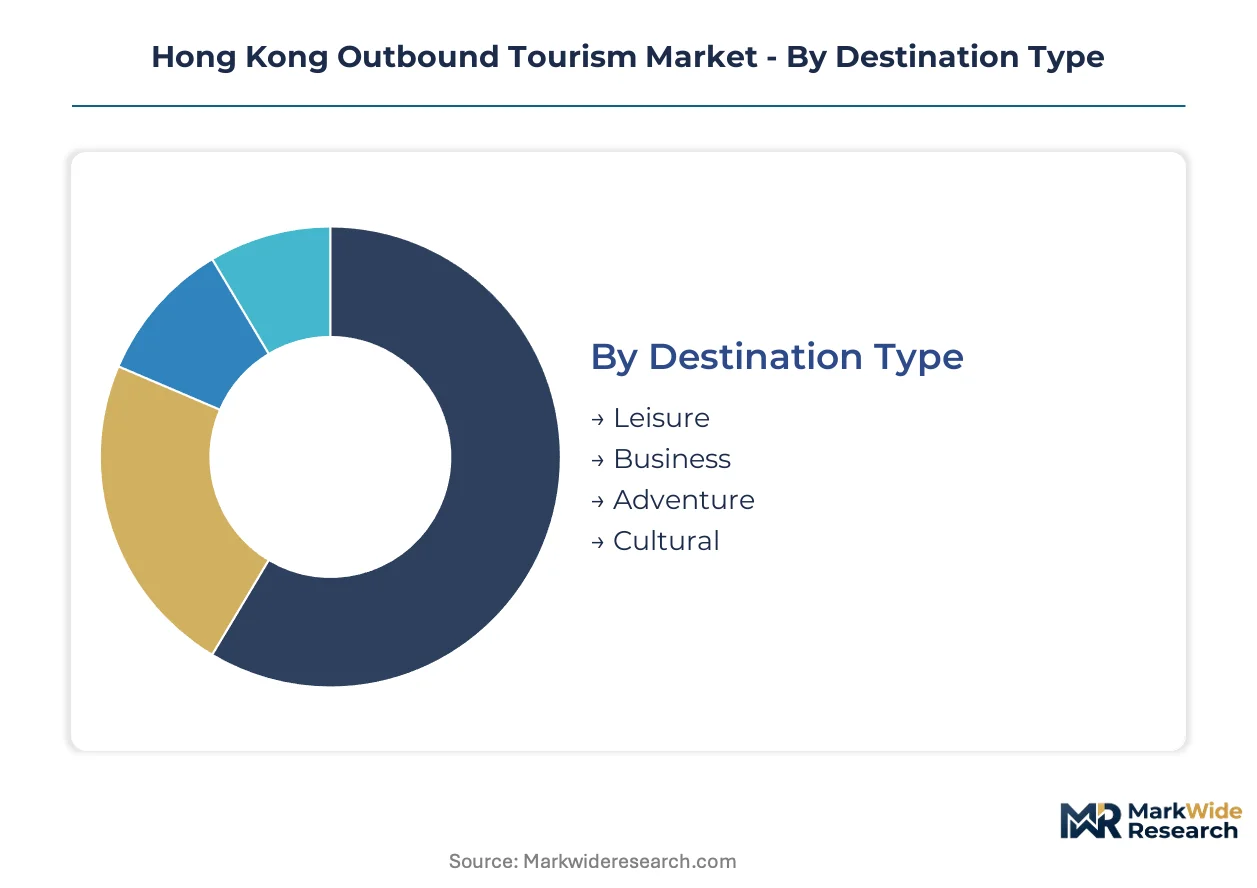
Hong Kong outbound tourism segments fragment along four distinct buyer dimensions. Each category captures different behavioral triggers, from destination motivation to booking platform preference. Understanding these partitions reveals where commission pools concentrate and where channel disruption is deepest.
Destination Type:
Buyer differentiation here hinges on trip duration flexibility and repeat visit frequency rather than distance alone.
- Leisure:Beach resort and urban shopping circuits dominate departure volumes. Japan's onsen towns and Thailand's island provinces absorb the highest repeat visitation from Hong Kong residents seeking short-haul recuperation.
- Business:Corporate travel concentrates in Greater Bay Area corridor cities and Singapore financial district. Guangzhou-Shenzhen same-day returns represent the highest-frequency subsegment with compressed booking windows.
- Adventure:Nepal trekking permits and New Zealand outdoor itineraries attract extended-leave professionals. Per-trip expenditure exceeds leisure averages due to specialized equipment logistics and guide licensing.
- Cultural:Museum-heavy European itineraries and Japanese heritage town visits appeal to educated empty-nesters. Seasonal festival timing drives concentrated booking surges.
Volume sits with Leisure; growth tilts toward Adventure.
Customer Demographic:
Age cohort and household composition determine package customization depth and price sensitivity thresholds.
- Millennials:Self-curated multi-city itineraries booked through mobile interfaces. This cohort drives adoption of AI recommendation engines and abandons fixed tour bundles fastest.
- Families:Cruise-and-resort combinations with child-care provisions dominate. School holiday calendars create predictable demand spikes that strain Japan and Southeast Asian family room inventory.
- Seniors:Medical travel packaging and slow-paced cultural circuits with accessibility accommodations. Thailand recuperation-stay licensing expansion directly serves this segment's healthcare-hospitality bundling preference.
- Couples:Boutique accommodation and experiential dining reservations. Direct hotel app bookings capture this segment most completely for simple city-break itineraries.
Volume concentrates with Families; Millennial bookings are climbing the fastest.
Travel Purpose:
Purpose determines pre-departure planning intensity and in-destination spending composition.
- Medical:Thailand and Singapore have expanded post-procedure recuperation licensing. Per-trip expenditure substantially exceeds other purposes due to bundled healthcare and extended accommodation stays.
- Vacation:Standard leisure departures with the broadest destination spread. Online travel agencies retain strongest position here through package comparison interfaces.
- Education:Language immersion and university campus tours with seasonal concentration. UK and Australia boarding school visits drive peak summer volumes.
- Religious:Buddhist temple stays in Japan and spiritual retreats in India. Small group charter arrangements dominate this specialized segment.
Volume rests with Vacation; Medical commands the steepest expansion trajectory.
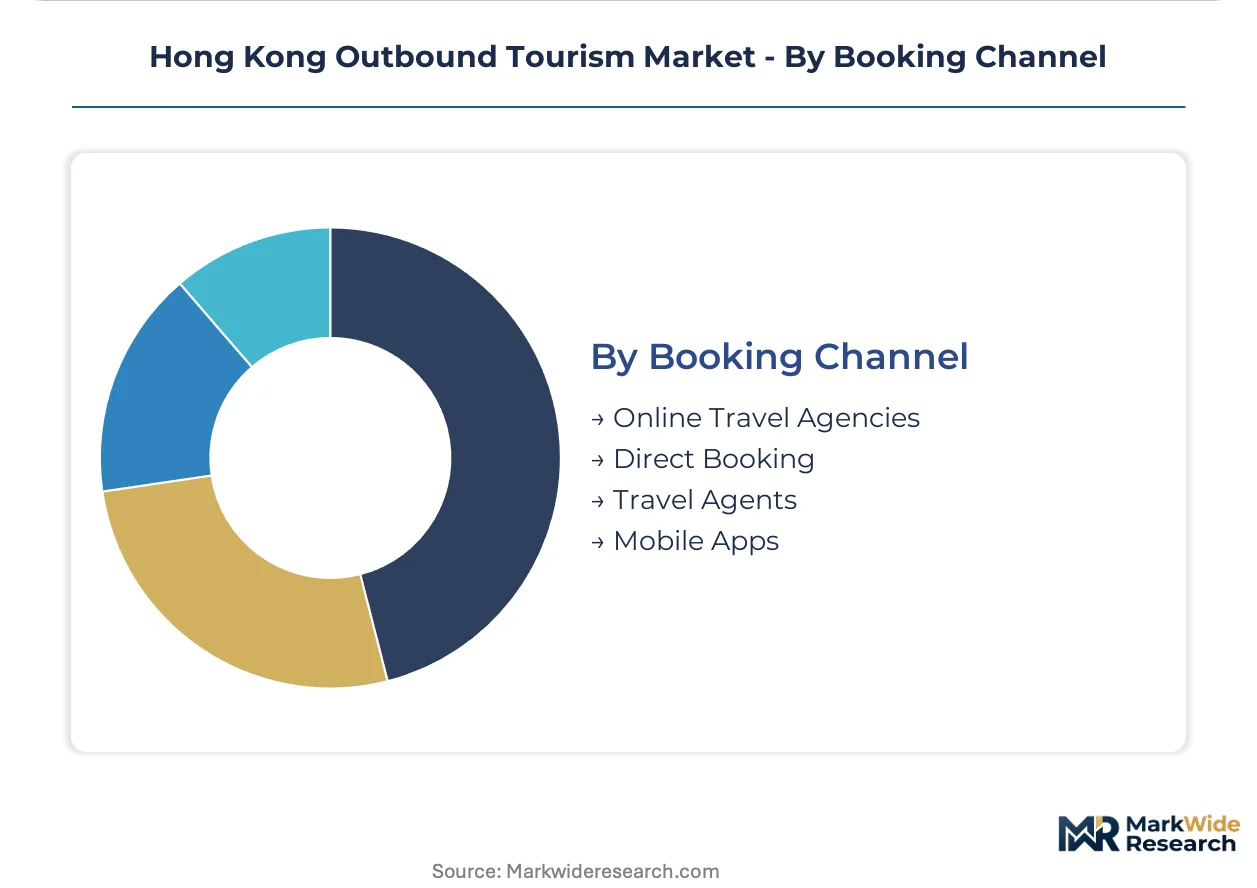
Booking Channel:
Channel selection reflects itinerary complexity tolerance and data-sharing willingness.
- Online Travel Agencies:Comparison aggregation across airlines, hotels, and activities. Millennials have displaced traditional agents through this channel for 60-70% of short-haul bookings.
- Direct Booking:Airline and hotel application interfaces for simple city-break routes. Taipei, Osaka, and Bangkok show highest penetration as carriers improve yield management control.
- Travel Agents:Legacy storefronts and call centers struggling with API fragmentation. Medical travel and complex multi-country itineraries retain agent dependency.
- Mobile Apps:Native platform bookings with AI-driven itinerary construction. Real-time inventory aggregation compresses search-to-purchase cycles from days to hours.
Volume remains with Online Travel Agencies; Mobile Apps gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hong Kong generates substantial outbound tourism expenditure without significant domestic production capacity, creating a pure consumption economy dependent on destination country infrastructure. The analysis examines five destination markets capturing the largest share of Hong Kong resident departures.
Japan
Japan absorbs the highest volume of Hong Kong leisure departures through onsen town and urban shopping circuits. The Japan National Tourism Organization coordinates with Hong Kong's Immigration Department on streamlined e-visa protocols that reduce application friction. Osaka and Kyoto anchor the Kansai corridor where hotel inventory expansion targets repeat visitors seeking cultural immersion.
South Korea
South Korea captures millennial demand through K-culture experiential packages and cosmetic surgery recuperation stays. The Korea Tourism Organization partners with Hong Kong authorities on digital entry permit facilitation. Seoul's Gangnam district concentrates medical travel infrastructure serving Hong Kong residents seeking bundled healthcare-hospitality arrangements.
Thailand
Thailand dominates beach resort and medical travel segments through competitive pricing and extended-stay licensing. The Tourism Authority of Thailand operates dedicated Hong Kong marketing offices promoting recuperation-stay programs. Phuket and Bangkok anchor the infrastructure network where post-procedure accommodation bundling generates premium per-trip expenditure.
Singapore
Singapore attracts high-value medical and business travel through healthcare quality certification and financial district proximity. The Singapore Tourism Board coordinates with Hong Kong's outbound promotion schemes on cross-marketing campaigns. The Orchard Road medical cluster specializes in recuperation-stay licensing for post-procedure Hong Kong visitors.
Taiwan
Taiwan captures short-haul leisure demand through cultural proximity and competitive air connectivity. The Taiwan Tourism Administration leverages e-visa facilitation partnerships with Hong Kong's Immigration Department. Taipei anchors the northern corridor where night market tourism and hot spring infrastructure target weekend departures.
Hong Kong Outbound Tourism Market Competitive Landscape
The competitive structure tilts toward established travel service operators with cross-border infrastructure. Hong Kong's outbound tourism sector maintains moderate concentration among legacy agencies possessing mainland China rail partnerships and cruise charter capabilities. Three strategic archetypes dominate: rail-land corridor specialists bundling cross-border high-speed combinations, cruise-resort packagers targeting family segments, and ad-hoc charter arrangers serving corporate associations. Competitive moves concentrate on API integration investments and medical travel certification acquisitions.
Among established Hong Kong-based service operators, China Travel Service (Hong Kong) Limited exemplifies the rail-land corridor archetype through its mainland network integration, while EGL Tours Company Limited represents cruise-resort packaging specialization. Hong Thai Travel Services Ltd. occupies the ad-hoc group charter segment. These operators anchor the competitive landscape as intermediaries navigate the shift from fixed bundles toward modular itinerary components.
| Leading Market Players |
|---|
| China Travel Service (Hong Kong) Limited |
| EGL Tours Company Limited |
| Hong Thai Travel Services Ltd. |
| Wing On Travel Service Ltd. |
| Travel Expert (H.K.) Limited |
| China CYTS Tours Holding Co., Ltd. |
| CTS HK Express (CTS Group) |
| Nam Ho Travel Service (Hong Kong) Co., Ltd. |
| Chan Brothers Travel (Hong Kong) Ltd. |
| Others |
Supply & Pricing Matrix
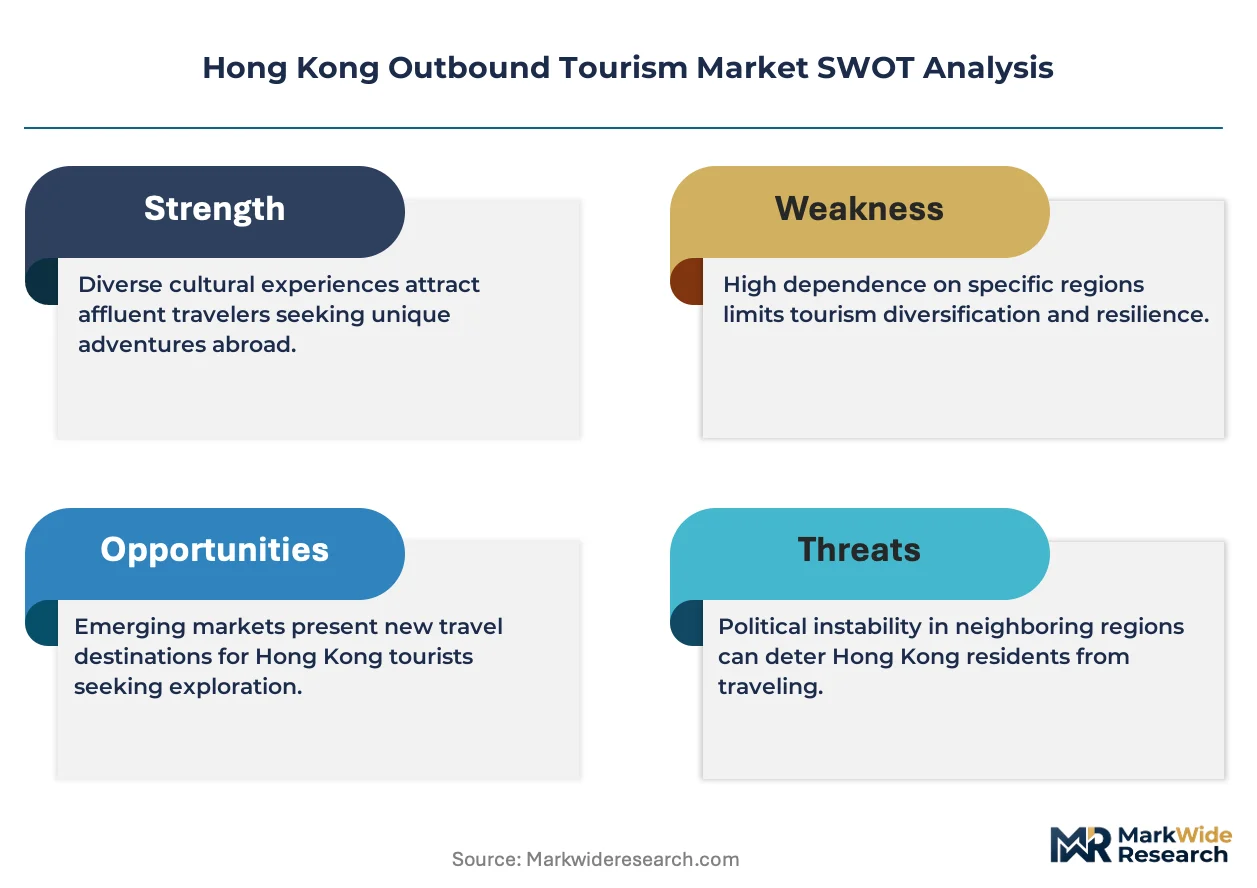
Carbon-neutral destination certification gates both qualified supply and premium-tier pricing access for Hong Kong outbound tour operators, as carriers and hotel partners with verified sustainability credentials command rate premiums while uncertified suppliers face exclusion from corporate account RFPs.
Pricing Analysis
Margin tightening in economy-tier packages reflects unbundling pressure as travelers assemble modular components independently. Three-tier pricing structure across premium, standard, and economy levels segments by service bundling depth and cancellation flexibility. Price differentiation traces to loyalty program tier status and advance purchase commitment windows. Corporate accounts demonstrate lowest price sensitivity; leisure impulse bookers exhibit highest elasticity to currency-adjusted rate fluctuations.
Supply Chain Analysis
Itinerary modification and refund processing flows strain legacy operator systems as modular booking patterns increase post-purchase change volumes. Supply concentrates in Japan, Thailand, and South Korea as primary destination nodes. Seat inventory and room stock draw from flag carrier allocations and hotel group block contracts. Single-source vulnerability runs through Hong Kong International Airport slot concentration for secondary Japanese destinations. Distribution runs through online travel agency aggregators and direct carrier applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hong Kong International Airport runway capacity constraints prop pricing power for incumbent operators holding confirmed seat allocations, creating a supply-constrained market structure favoring established intermediaries with aviation partnerships.
For Market Incumbents: To counter direct booking channel erosion, secure exclusive block allocations with Japan and Thailand resort properties, and deepen API integration with low-cost carrier inventory systems to maintain package assembly speed against mobile-native competitors. For New Entrants and Emerging Players: Online travel agency partnerships offer the fastest traction path for modular itinerary tools targeting millennial self-curators, with Vietnam coastal resort inventory representing the most penetrable white-space destination for family segment entry. For Investors and Strategic Acquirers: Immigration Department e-visa facilitation partnership announcements are the leading indicator that corridor-specific volume inflections are imminent. Long-term viability centers on medical travel packaging capabilities requiring dual healthcare-hospitality competency. Acquisition targets should combine mainland China rail network access with AI-driven itinerary construction technology. Monitor Taiwan Tourism Administration campaign spend shifts for early signals of short-haul demand rotation.| Strategic Initiative | Industry Significance |
|---|---|
| API Integration Investment | Connects fragmented low-cost carrier inventory into unified customer-facing booking interfaces. |
| Medical Travel Certification | Enables Thailand and Singapore post-procedure recuperation package licensing compliance. |
| Rail-Land Corridor Development | Leverages mainland China high-speed rail networks for multi-city itinerary assembly without aviation dependency. |
| AI Itinerary Engine Deployment | Automates millennial preference matching across siloed airline, hotel, and activity vendor inventory. |
| Sustainability Partnership | Secures carbon-neutral hotel and carrier credentials for corporate account RFP qualification. |
Research Methodology
Multi-period observation of booking lead time compression and channel migration patterns anchored the trend analysis, supplemented by interviews with tour operation directors, airline revenue management executives, hotel distribution strategists, and Immigration Department policy officers. Secondary validation drew from Hong Kong Tourism Board departure statistics, IATA passenger traffic data, destination country e-visa issuance disclosures, and online travel agency commission structure filings. Bottom-up segment sizing and top-down expenditure calibration triangulated market estimates.
Segment-weighting across destination type, customer demographic, travel purpose, and booking channel dimensions structured the analytical framework over the projection horizon. CAGRs derived from corridor-specific volume trajectories and per-trip expenditure evolution. Forecast inputs incorporated aviation capacity expansion timelines and destination country recuperation-stay licensing policy shifts.
Caveats apply where health credential recognition agreements or currency volatility spikes could materially shift the outlook, as forecasts reflect assumptions about sustained e-visa facilitation and slot allocation stability. Practitioners should monitor Immigration Department partnership announcements and Hong Kong International Airport capacity utilization reports for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Solo Ecotourism Market
Travel and Tourism
Wedding Tourism Market
Travel and Tourism
UK Outbound Travel Market
Travel and Tourism
Dark Tourism Market
Travel and Tourism
Russia Outbound Tourism Market
Travel and Tourism
Travel and Tourism User Generated Content Market
Travel and Tourism
Asia-Pacific Tourism Market
Travel and Tourism
Special Interest Tourism Market
Travel and Tourism
Group Travel Market
Travel and Tourism
Halal Tourism Market
Travel and Tourism
Water Park Market
Travel and Tourism
Europe Wellness Tourism Market
Travel and Tourism
Educational Tourism Market
Travel and Tourism
LAMEA Pet Travel Services Market
Travel and Tourism
New Zealand Sustainable Tourism Market
Travel and Tourism
Singapore Tourism Market