
 Yacht Charter Market | 2026-2036
Yacht Charter Market Size, Share, and Industry Trends Forecast 2026-2036
Yacht Charter Market Analysis
Corporate retreat demand is rebalancing the traditional leisure-heavy charter calendar, with technology firms and private equity groups now occupying prime summer windows. Fraser Yachts leverages its London-based brokerage network to sustain access to superyacht owners across the Mediterranean. Dream Yacht Charter anchors its competitive position through fleet scale in the Caribbean and Indian Ocean basins. Ocean Independence differentiates via crewed charter specialization in the 40-60 meter segment.
A yacht charter constitutes the time-bound lease of a vessel with or without professional crew, governed by maritime commercial law and typically structured through MYBA or CYBA standard contracts specifying insurance, APA provisioning, and delivery terms. Crewed charters command premium daily rates reflecting captain, chef, and deck personnel costs alongside fuel and berth provisioning. The service type dimension shows luxury and catamaran categories capturing expanding margin pools as experiential travel preferences shift toward multihull stability and onboard amenities. Motor yachts dominate transaction volume within yacht type segmentation, though superyachts concentrate value per charter week.
The International Maritime Organization's carbon intensity regulations and the EU's F-Gas framework constrain refrigerant choices and propulsion specifications for vessels operating in European waters. The US Coast Guard and flag-state registries including the Marshall Islands and Cayman Islands enforce manning, safety, and environmental compliance standards that shape fleet deployment decisions. Stakeholders must monitor evolving bunker fuel taxation regimes and zero-emission port infrastructure timelines to align charter offerings with regulatory trajectories.
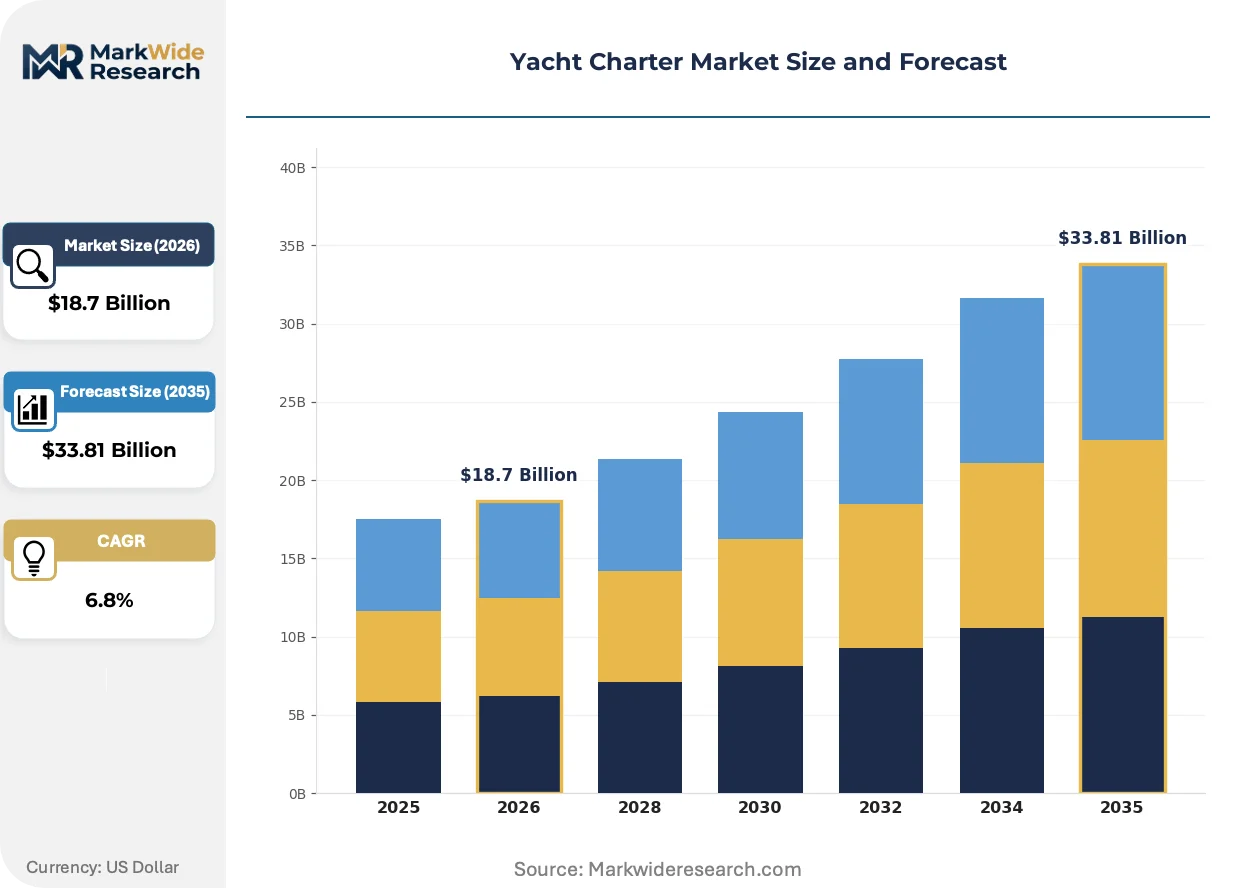
Market Dynamics
The EU's F-Gas Regulation and IMO decarbonization protocols are compressing fleet composition timelines, forcing operators to reconfigure propulsion systems and refrigerant choices ahead of enforcement windows. This regulatory pressure is reshaping capital allocation across Mediterranean and Caribbean basins.
Growth Catalysts
- Technology sector retreat demand:Ultra-high-net-worth individuals from software and venture capital are booking prime summer windows previously reserved for traditional leisure clients. This injects corporate procurement discipline into seasonal scheduling.
- F-Gas Regulation retrofit cycle:The EU's phasedown of hydrofluorocarbon refrigerants is accelerating hull upgrade investments. Fleet operators are modernizing older vessels to retain European water access.
- Greek Islands infrastructure:Expanded marina capacity in Corfu, Mykonos, and Rhodes is concentrating Eastern Mediterranean demand. New deep-water berths accommodate 60-meter plus vessels previously excluded.
Market Restraints
- Bunker fuel cost volatility:Marine gasoil price swings compress operating margins on conventional motor yacht fleets. Fuel surcharges trigger booking cancellations during spike periods.
- Superyacht builder concentration:Italian and Dutch shipyards control 70% of 40-meter plus new construction. Delivery backlogs extend 24-36 months, constraining fleet expansion.
- IMO carbon intensity technical limitation:Current battery-electric and hydrogen fuel cell propulsion cannot yet substitute diesel-mechanical systems for transoceanic range requirements.
Strategic Opportunities
- Croatian Adriatic corridor underpenetration:Split and Dubrovnik marinas offer lower berthing costs versus French Riviera equivalents. The Kornati archipelago remains underserved by crewed catamaran inventory.
- MYBA contract digitalization:Blockchain-anchored smart contracts for APA provisioning and delivery terms reduce escrow friction. Early adopters are compressing booking-to-departure timelines.
- EU Green Deal port infrastructure:Shore power installation timelines at Barcelona, Palma, and Monaco create first-mower advantage for vessels with compatible electrical systems.
Industry Challenges
- Master mariner certification scarcity:STCW compliance requirements for captains on 3,000 GT plus vessels outstrip training pipeline output. Crew costs inflate 15% annually for qualified personnel.
- CYBA-to-MYBA contract migration friction:Caribbean and Mediterranean brokers operate under incompatible standard terms. Cross-basin charterers face legal reconciliation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yacht Charter Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Crewed, Bareboat, Luxury, Catamaran Customer Type: Individuals, Corporations, Event Planners, Travel Agents Yacht Type: Sailing Yachts, Motor Yachts, Superyachts, Gulets Booking Channel: Direct, Online Platforms, Agents, Charters Brokers |
| Companies Covered | Ocean Independence, Dream Yacht Charter, Y.CO, Imperial Yachts, Yachtico, Fraser Yachts, Northrop and Johnson, Simpson Marine, Burgess, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yacht Charter Market Emerging Trajectories
Propulsion technology and contractual infrastructure are undergoing parallel transformation. Hybrid architectures and digital booking platforms are compressing traditional operational models while regulatory compliance costs accelerate fleet stratification.
Hybrid diesel-electric propulsion is modularizing vessel powertrain architecture. Greek and Croatian operators are retrofitting existing hulls with battery banks for harbor maneuvering and anchorages. This technology is modularizing maintenance schedules and enabling segmented insurance pricing between coastal and offshore legs.
The EU's F-Gas Regulation is eliminating R-404A and R-507 refrigerants from new yacht construction. Shipyards in Italy and the Netherlands are transitioning to CO2-based and hydrocarbon alternatives for galley and cabin climate systems. The 40-60 meter segment faces the steepest re-engineering costs due to space constraints for alternative hardware.
Corporate procurement departments are displacing family office booking agents for technology sector retreats. Fixed summer window contracts with cancellation flexibility are replacing traditional spot-market arrangements. This pattern concentrates most visibly in San Francisco and London-based firm deployments to Mediterranean circuits.
Yacht Charter Market Segmentation
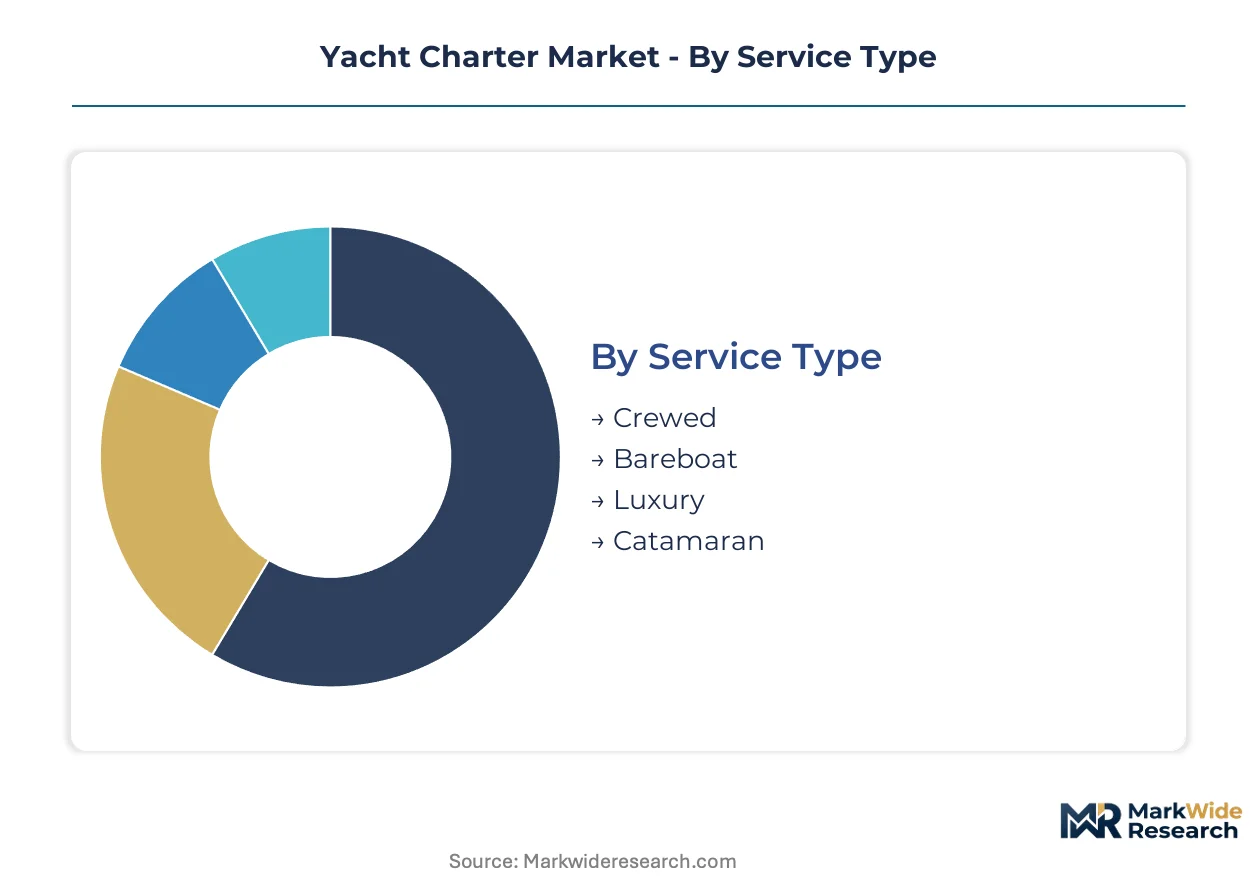
Yacht charter segmentation reveals divergent compliance burdens across service tiers. Crewed and luxury segments face intensive STCW manning certifications and flag-state safety audits. Bareboat operators navigate simpler recreational licensing frameworks.
Service Type:
Certification intensity separates crewed operations from self-operated alternatives. STCW-compliant manning certificates, MCA coding, and flag-state commercial endorsements create tiered regulatory entry barriers.
- Crewed:Professional captain, chef, and deck crew included in the charter rate. Demand concentrates among technology sector corporate retreats booking prime Mediterranean summer windows, driven by liability insulation requirements. STCW 95 certification and MCA commercial coding are mandatory for vessels over 24 meters.
- Luxury:Premium amenities with concierge-level provisioning and bespoke itinerary planning. Greek Islands and Croatian Adriatic corridors show strongest concentration as ultra-high-net-worth individuals seek experiential differentiation beyond traditional French Riviera circuits.
- Catamaran:Multihull stability appeals to family groups and novice sailors. EU F-Gas Regulation compliance for dual-hull climate systems adds retrofit complexity.
- Bareboat:Self-skippered vessels requiring recreational sailing certifications only. Lower regulatory burden attracts cost-sensitive European holidaymakers.
Leading the category by volume: Crewed. Growing fastest: Luxury.
Customer Type:
Procurement sophistication varies sharply across buyer categories. Corporate departments impose fixed-window contracts with cancellation flexibility, displacing traditional family office spot-market booking patterns.
- Corporations:Technology firms and private equity groups now dominate prime summer scheduling. San Francisco and London-based entities drive Mediterranean circuit demand with structured procurement protocols.
- Individuals:Traditional leisure clients facing compressed availability windows due to corporate pre-booking. Family office booking agents retain preference for flexibility over rate optimization.
- Event Planners:Wedding and celebration segments cluster in Greek Islands infrastructure expansion zones. Corfu and Rhodes marina upgrades accommodate group embarkation logistics.
- Travel Agents:Consolidated booking intermediaries accessing wholesale charter rates. Caribbean and Indian Ocean basin inventory flows through established agency networks.
Corporations command premium rate tolerance. Individuals represent largest absolute transaction count.
Yacht Type:
Builder concentration and flag-state registration requirements stratify capital deployment. Italian and Dutch shipyard backlogs constrain 40-meter plus fleet expansion.
- Motor Yachts:Diesel-mechanical propulsion dominates transaction volume. IMO carbon intensity regulations and bunker fuel cost volatility compress operating margins on conventional fleets.
- Superyachts:Vessels exceeding 40 meters concentrating value per charter week. Marshall Islands and Cayman Islands registries enforce manning and environmental compliance standards shaping deployment decisions.
- Sailing Yachts:Wind-assisted propulsion aligns with EU Green Deal trajectory. Lower fuel exposure insulates against marine gasoil price spikes.
- Gulets:Traditional wooden motor-sailers concentrated in Turkish and Greek coastal operations. Heritage construction methods face modern safety coding challenges.
Motor yachts lead transaction frequency. Superyachts capture highest revenue per vessel.
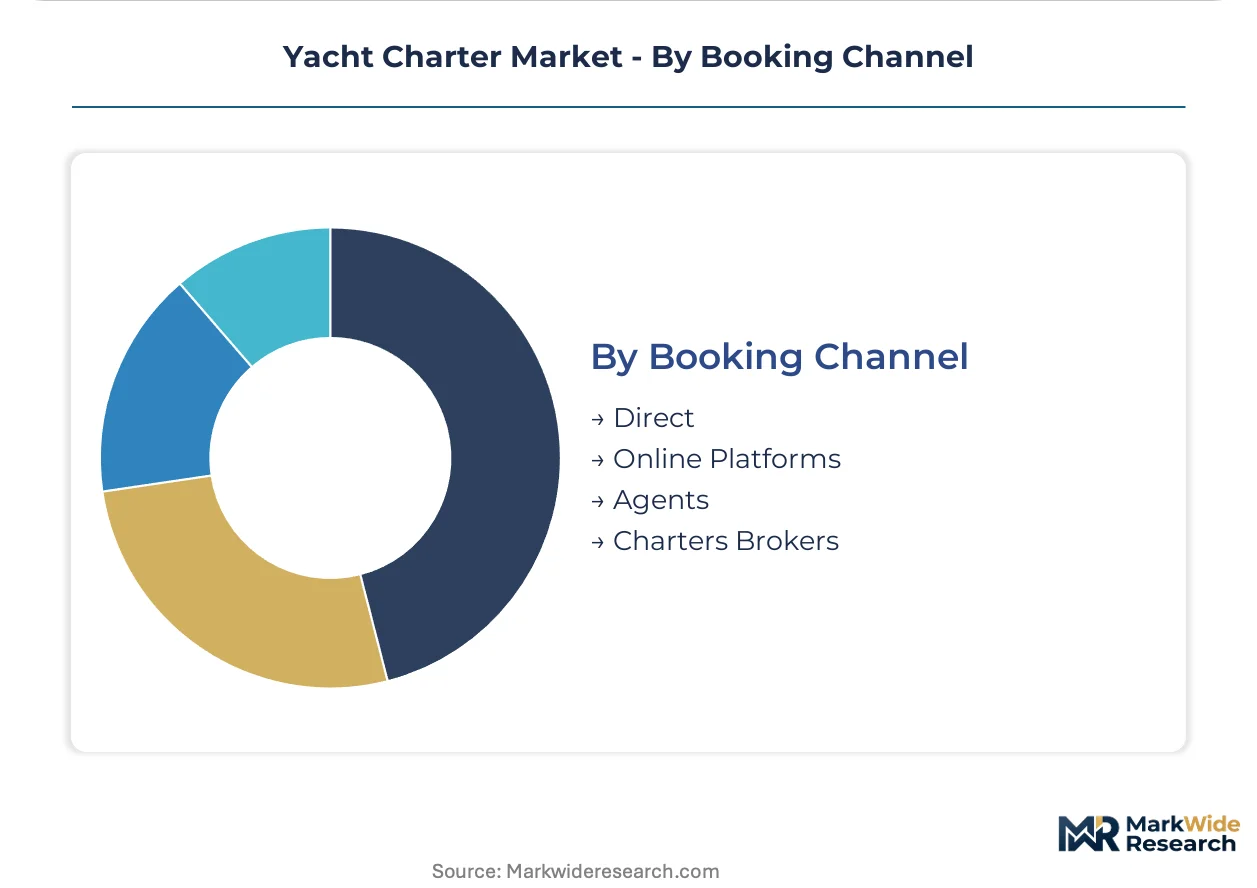
Booking Channel:
Digital infrastructure is compressing traditional brokerage timelines. MYBA contract standardization and blockchain-anchored smart contracts reduce escrow friction for early technology adopters.
- Charters Brokers:Established intermediaries with London-based networks sustaining superyacht owner access. MYBA standard contract expertise differentiates premium service tiers.
- Online Platforms:Direct booking engines compressing research-to-reservation cycles. Real-time availability displays challenge traditional broker information asymmetry.
- Agents:Geographic specialists with local marina relationship depth. Croatian Adriatic corridor penetration relies on Split and Dubrovnik-based agency networks.
- Direct:Owner-operator relationships bypassing commission structures. Fleet-scale operators in Caribbean and Indian Ocean basins leverage repeat-client loyalty programs.
Brokers retain superyacht segment dominance. Online platforms expanding fastest in sub-40-meter categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet ownership clusters in Italian and Dutch shipyards while charter demand concentrates in Mediterranean and Caribbean consumption basins. This geographic split shapes capital deployment patterns across vessel construction, crew training, and marina infrastructure.
Italy
Superyacht construction dominates the Ligurian and Tuscan coastlines with Genoa and Viareggio anchoring builder concentration. The EU's F-Gas Regulation is eliminating R-404A refrigerants from new builds, forcing shipyards to re-engineer climate systems. The Azimut-Benetti and Ferretti industrial clusters in these cities are retrofitting production lines for CO2-based alternatives ahead of enforcement windows.
France
Antibes and Monaco sustain the densest superyacht brokerage networks in the Mediterranean basin. The EU Green Deal's shore power installation timelines at Marseille and Nice are creating first-mover advantages for vessels with compatible electrical systems. The Côte d'Azur corridor from Saint-Tropez to Menton concentrates high-value charter weeks during prime summer scheduling.
Greece
Island-hopping itineraries from Corfu, Mykonos, and Rhodes are absorbing expanded corporate retreat demand from technology sector clients. The country's national maritime regulator enforces flag-state safety audits that align with Marshall Islands and Cayman Islands registries. The Saronic Gulf and Cyclades archipelagos are concentrating new marina investment as deep-water berths accommodate 60-meter plus vessels.
United States
Florida's Fort Lauderdale and Miami anchor the Western Hemisphere's largest yacht brokerage concentration. The US Coast Guard enforces manning and environmental compliance standards that shape Caribbean fleet deployment decisions. The Intracoastal Waterway corridor from Palm Beach to Key West channels winter charter demand toward Bahamian and Virgin Islands circuits.
Croatia
Split and Dubrovnik marinas offer berthing cost advantages versus French Riviera equivalents while the Kornati archipelago remains underserved by crewed inventory. The EU's F-Gas framework applies fully to vessels operating in Adriatic waters, accelerating retrofit investments. The Dalmatian coast from Zadar to Dubrovnik is absorbing spillover demand from saturated Western Mediterranean circuits.
Yacht Charter Market Vendor Landscape
Top-tier vendors anchor superyacht brokerage and crewed charter operations, while mid-tier operators concentrate on fleet scale and bareboat categories. The market structure fragments across service tiers rather than consolidating around volume leaders. Three strategic archetypes dominate: London-centered brokerage networks with owner access, Caribbean and Indian Ocean fleet-scale operators, and specialized crewed charter boutiques in the 40-60 meter segment. Competitive moves center on MYBA contract digitalization and geographic expansion into underpenetrated Adriatic corridors.
Within the brokerage network tier, Fraser Yachts and Burgess exemplify London-based operations sustaining superyacht owner relationships across Mediterranean basins. Dream Yacht Charter occupies a position among fleet-scale operators with Caribbean and Indian Ocean inventory concentration. Ocean Independence represents the specialized crewed charter archetype with focus on the 40-60 meter segment. These three company structures illustrate how geographic origin and service tier alignment shape competitive positioning without requiring vertical integration into shipyard ownership.
| Leading Market Players |
|---|
| Ocean Independence |
| Dream Yacht Charter |
| Y.CO |
| Imperial Yachts |
| Yachtico |
| Fraser Yachts |
| Northrop and Johnson |
| Simpson Marine |
| Burgess |
| Others |
Supply Flow & Price Mechanics
Family-owned Italian and Dutch shipyards anchor superyacht construction, translating builder concentration into pricing power for vessels exceeding 40 meters while compressing margins for mid-tier operators dependent on spot-market charter rates. This ownership structure feeds directly into supply discipline and rate-setting behavior across Mediterranean and Caribbean basins.
Pricing Analysis
Margin tightening in the 40-60 meter crewed segment reflects Italian and Dutch shipyard backlogs extending delivery timelines. Three-tier pricing structure across superyacht, luxury crewed, and bareboat categories tracks certification intensity and manning requirements. Bunker fuel cost volatility intensifies cost-down pressure on conventional motor yacht fleets. Corporate technology sector clients exhibit lowest price sensitivity due to liability insulation requirements, while European family holidaymakers drive bareboat price elasticity.
Supply Chain Analysis
Regional distribution centers in Genoa, Viareggio, and Fort Lauderdale coordinate hull delivery and crew deployment across consumption basins. Vessel construction concentrates in Italy, the Netherlands, and Turkey. Steel, marine-grade aluminum, and climate system refrigerants constitute critical input dependencies. Single-source vulnerability sits with Italian and Dutch yards controlling 70% of 40-meter plus new construction. Distribution runs through London-centered brokerage networks and Caribbean fleet-scale operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum is accelerating as operators pursue backward integration into marina infrastructure and crew training pipelines to capture margin pools currently flowing to third-party providers.
For Market Incumbents: Anticipate regulatory compliance cost escalation from EU F-Gas Regulation and IMO carbon intensity protocols by retrofitting existing hulls with hybrid diesel-electric architectures. Deepen owner relationships through MYBA contract digitalization to reduce booking friction and defend against online platform disintermediation. For New Entrants and Emerging Players: Direct booking platforms offer the lowest customer acquisition cost route into the sub-40-meter segment. Target the Croatian Adriatic corridor where Split and Dubrovnik marinas remain underserved by crewed catamaran inventory. Deploy fixed summer window contracts with cancellation flexibility to attract technology sector corporate procurement departments. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized crewed charter boutiques in the 40-60 meter segment with established MCA commercial coding and STCW-compliant manning certificates. Long-term viability hinges on fleet decarbonization readiness and shore power compatibility at EU Green Deal ports. Monitor bunker fuel taxation regime announcements as inflection indicators for conventional motor yacht fleet valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Propulsion Retrofit | Battery bank installations enable harbor maneuvering compliance with EU F-Gas Regulation refrigerant mandates. |
| Marina Infrastructure Investment | Deep-water berth expansion at Corfu and Rhodes accommodates 60-meter plus vessels previously excluded. |
| Crew Training Pipeline Development | STCW 95 certification programs address master mariner scarcity inflating qualified personnel costs. |
| Blockchain Contract Digitalization | Smart contracts for APA provisioning compress booking-to-departure timelines for Mediterranean circuits. |
| Adriatic Geographic Expansion | Kornati archipelago penetration captures spillover demand from saturated Western Mediterranean routes. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with yacht brokers, fleet operators, marina managers, and STCW training providers. MYBA and CYBA contract databases, IMO submissions, EU F-Gas Regulation enforcement schedules, and Marshall Islands registry filings provided triangulation points. Bottom-up vessel inventory counts reconciled against top-down charter revenue estimates.
Data-stream reconciliation across service type, customer category, yacht type, and booking channel dimensions generated volume and value outputs over the projection horizon. CAGRs derived from hull delivery backlogs, marina berth expansion timelines, and corporate retreat booking patterns. Forecast inputs incorporated bunker fuel price trajectories and EU Green Deal shore power installation schedules.
The model holds under stable regulatory enforcement timelines; deviation in IMO carbon intensity protocol acceleration or F-Gas Regulation phase-in delays would shift fleet retrofit investment schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Europe Tourism Vehicle Rental Market
Travel and Tourism
Russia Outbound Tourism Market
Travel and Tourism
Inflight Shopping Market
Travel and Tourism
UK Outbound Travel Market
Travel and Tourism
India Travel Retail Market
Travel and Tourism
Bleisure Tourism Market
Travel and Tourism
Mexico Sustainable Tourism Market
Travel and Tourism
US and Canada Travel Market
Travel and Tourism
Agritourism Market
Travel and Tourism
France Outbound Tourism Market
Travel and Tourism
Hong Kong Outbound Tourism Market
Travel and Tourism
Maldives Hospitality Market
Travel and Tourism
Ecotel Tourism Market
Travel and Tourism
MICE Travel Service Market
Travel and Tourism
Camping and Caravanning Market
Travel and Tourism
UAE Sustainable Tourism Market