
 Europe Camping and Caravanning Market | 2026-2036
Europe Camping and Caravanning Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Camping and Caravanning Market Analytics
The EU Green Deal is realigning the cost-of-entry calculus for campsite operators and equipment manufacturers across Europe. Knaus Tabbert leverages its German manufacturing scale to navigate stricter carbon-border requirements on imported components. Adria Mobil anchors its competitive position through Slovenian-based production that sustains proximity to Mediterranean demand clusters. Eurocamp differentiates via managed campsite networks that control premium coastal locations in France and Italy.
Camping and caravanning encompasses temporary outdoor accommodation using towable units, motorized recreational vehicles, or portable shelter systems typically constructed from aluminum framing, composite panels, and weather-resistant textiles rated for extended UV exposure and thermal insulation. The primary commercial purpose centers on enabling mobile leisure tourism with self-contained sleeping, cooking, and sanitation facilities independent of fixed hospitality infrastructure. Motorhomes command the highest average transaction values and margin pools among product types due to integrated drivetrain and living-system complexity. Families dominate end-user demand volume, though solo travelers represent the fastest-expanding segment as remote-work flexibility extends trip durations. Direct sales and specialty stores retain channel dominance for high-consideration purchases, while online retail captures accessory and replacement-part transactions.
EMA environmental guidelines, EU Green Deal carbon targets, and national building codes in France and Germany collectively shape product standards for wastewater systems, electrical hookups, and thermal efficiency in new caravan models. REACH chemical restrictions further limit material choices for interior finishes and insulation foams, pushing manufacturers toward certified alternative suppliers. Stakeholders must monitor evolving national transpositions of EU-wide sustainability mandates and assess whether retrofit obligations on existing campsite infrastructure will accelerate replacement cycles or compress operator margins.
Market Dynamics
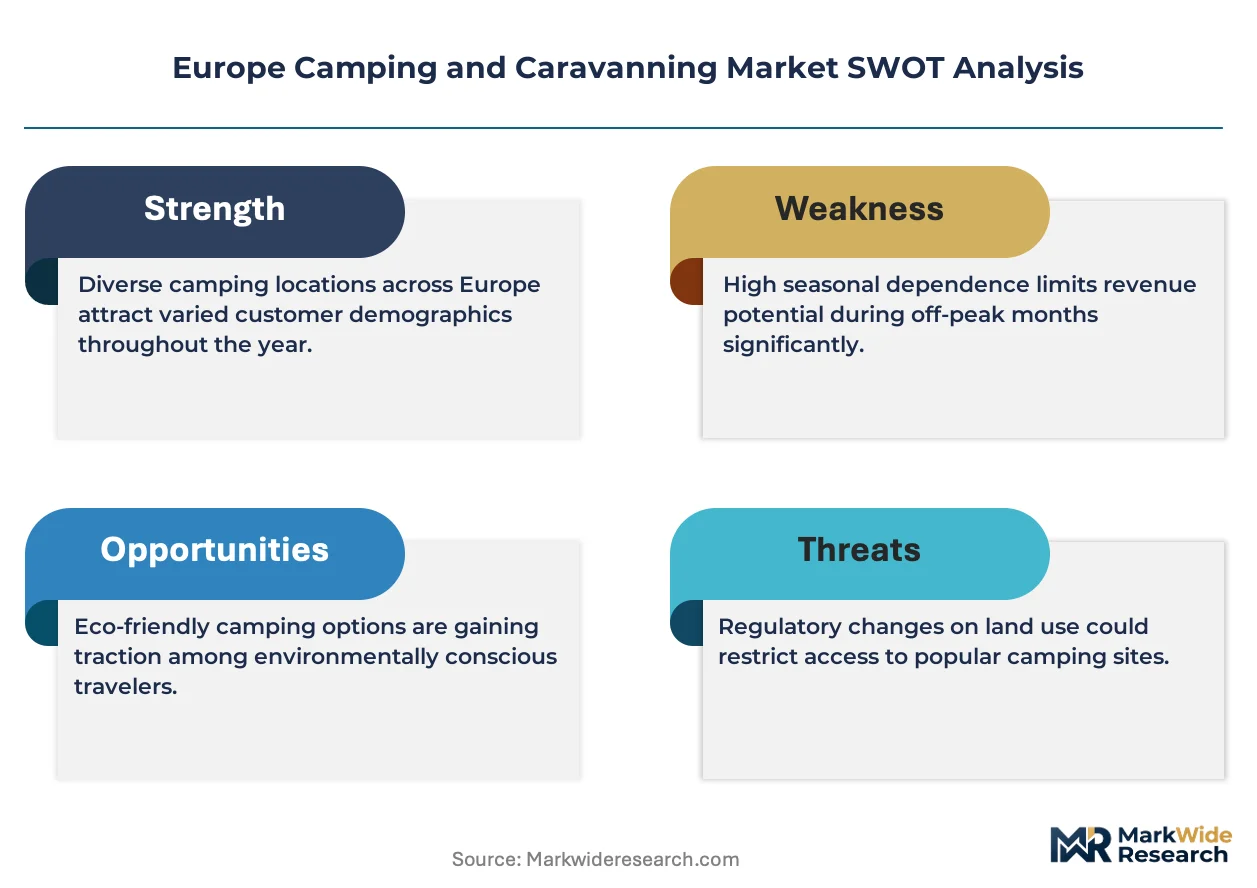
The EU Green Deal is forcing campsite operators and equipment manufacturers to restructure capital allocation around carbon-border compliance and energy retrofit obligations, compressing margins for legacy infrastructure while advantaging integrated producers with captive component supply.
Growth Catalysts
- Domestic outdoor holiday prioritization:Young families across France, Germany, and Spain are redirecting travel budgets from long-haul destinations to regional camping circuits, sustaining pitch occupancy rates above seasonal norms.
- REACH chemical compliance:Restrictions on interior finish materials are accelerating certified supplier consolidation, locking in preferred vendor relationships for compliant foam and textile producers.
- Remote-work trip extension:Solo travelers with location-flexible employment are booking longer-duration stays, expanding addressable revenue per pitch beyond traditional weekend-peak patterns.
Market Restraints
- Aluminum and composite panel cost volatility:Raw material input swings for caravan structural components compress manufacturer margins when long-term retail pricing remains fixed.
- German manufacturing concentration:Heavy reliance on Bavarian and Baden-Württemberg production clusters creates vulnerability to regional energy price shocks and logistics bottlenecks.
- Motorhome drivetrain complexity:Integration of living systems with vehicle platforms elevates warranty exposure and service network requirements beyond traditional caravan economics.
Strategic Opportunities
- Eastern European pitch expansion:Underdeveloped campsite infrastructure in Poland, Romania, and Bulgaria offers first-mover positioning ahead of EU cohesion fund accessibility improvements.
- Solar-integrated electrical hookups:Campsite operators deploying photovoltaic canopy systems over parking bays can capture feed-in tariffs while differentiating premium pitch tiers.
- Online replacement-part retail:Direct-to-consumer channels for weather-resistant textiles and UV-rated components bypass specialty store markups and capture recurring accessory revenue.
Industry Challenges
- Certified installation technician scarcity:Complex wastewater and electrical systems in new caravan models require trained service personnel that manufacturer networks struggle to recruit at sufficient scale.
- Retrofit capex timing uncertainty:Campsite operators face ambiguous national transposition timelines for EU Green Deal thermal efficiency mandates, freezing infrastructure investment decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Camping and Caravanning Market |
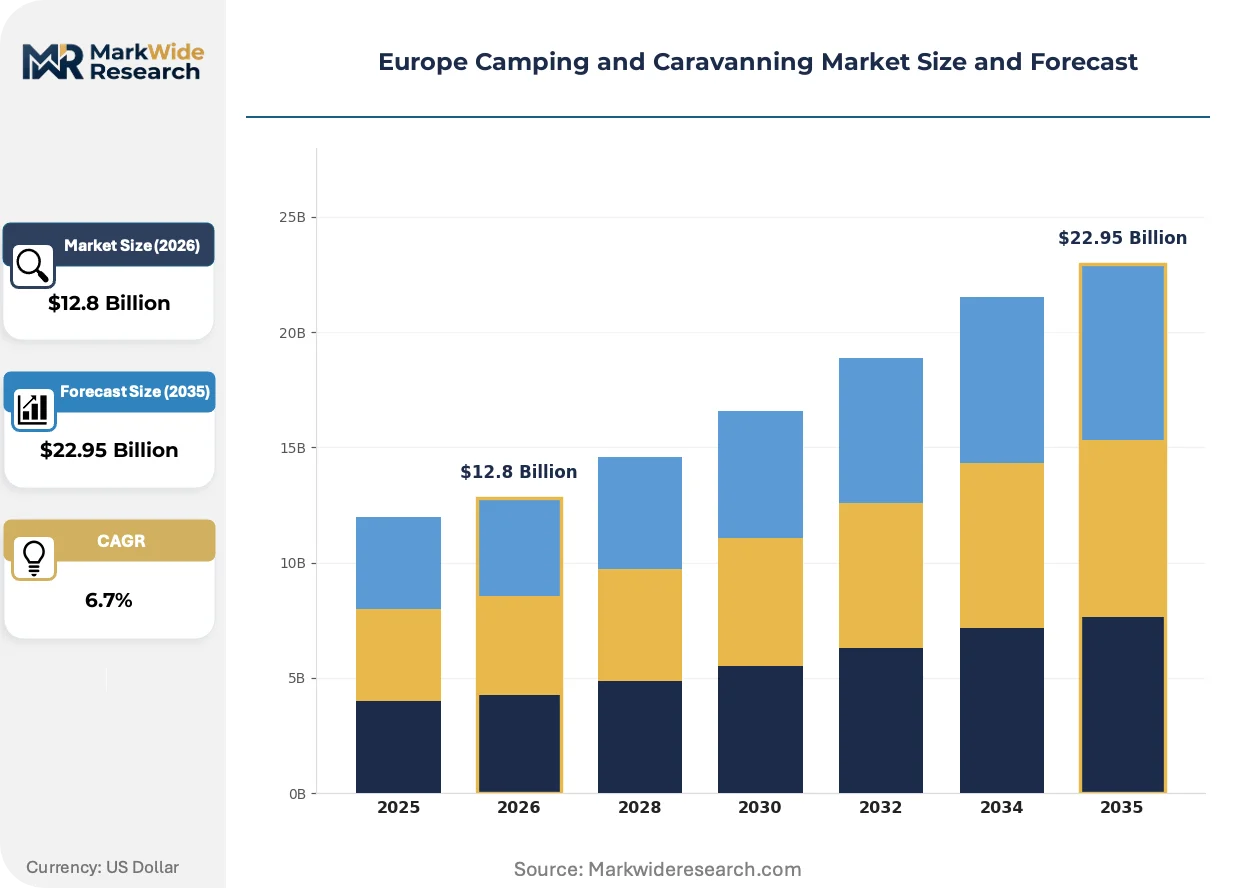
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tents, Caravans, Motorhomes, Campers End User: Families, Solo Travelers, Couples, Adventure Seekers Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales Service Type: Rental Services, Maintenance Services, Tour Packages, Campsite Services |
| Companies Covered | Knaus Tabbert, Adria Mobil, European Camping Group, Eurocamp, First Camp, Erwin Hymer Group, ACSI, Swift Group, Trigano, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Camping and Caravanning Market Evolving Landscape
Product design and campsite operations are converging around electrification, material compliance, and digitally mediated booking relationships that reshape how value is captured across the accommodation chain.
Lightweight composite sandwich panels with integrated thermal breaks are integrating into caravan wall systems to meet escalating insulation standards without payload penalties. German and French manufacturers are adopting these substrates fastest, converting aluminum-intensive production lines. The technology is integrating living-space climate control with reduced HVAC energy draw, enabling smaller battery banks and solar arrays.
EU Green Deal carbon targets are mandating progressive emissions thresholds for motorized recreational vehicles sold in member states. KBA type-approval processes in Germany now incorporate lifecycle carbon calculations that extend to supplier tiers. Motorhome segments face the steepest compliance gradients, pushing drivetrain electrification roadmaps that outpace consumer charging infrastructure readiness.
Managed campsite networks are unbundling after-sales service from equipment purchase, selling maintenance subscriptions through proprietary mobile applications. Young families in France and Italy show highest uptake of these bundled pitch-plus-service contracts. Digital channel penetration for booking and on-site service requests is displacing traditional telephone and walk-in reservation systems at coastal locations.
Europe Camping and Caravanning Market Segmentation
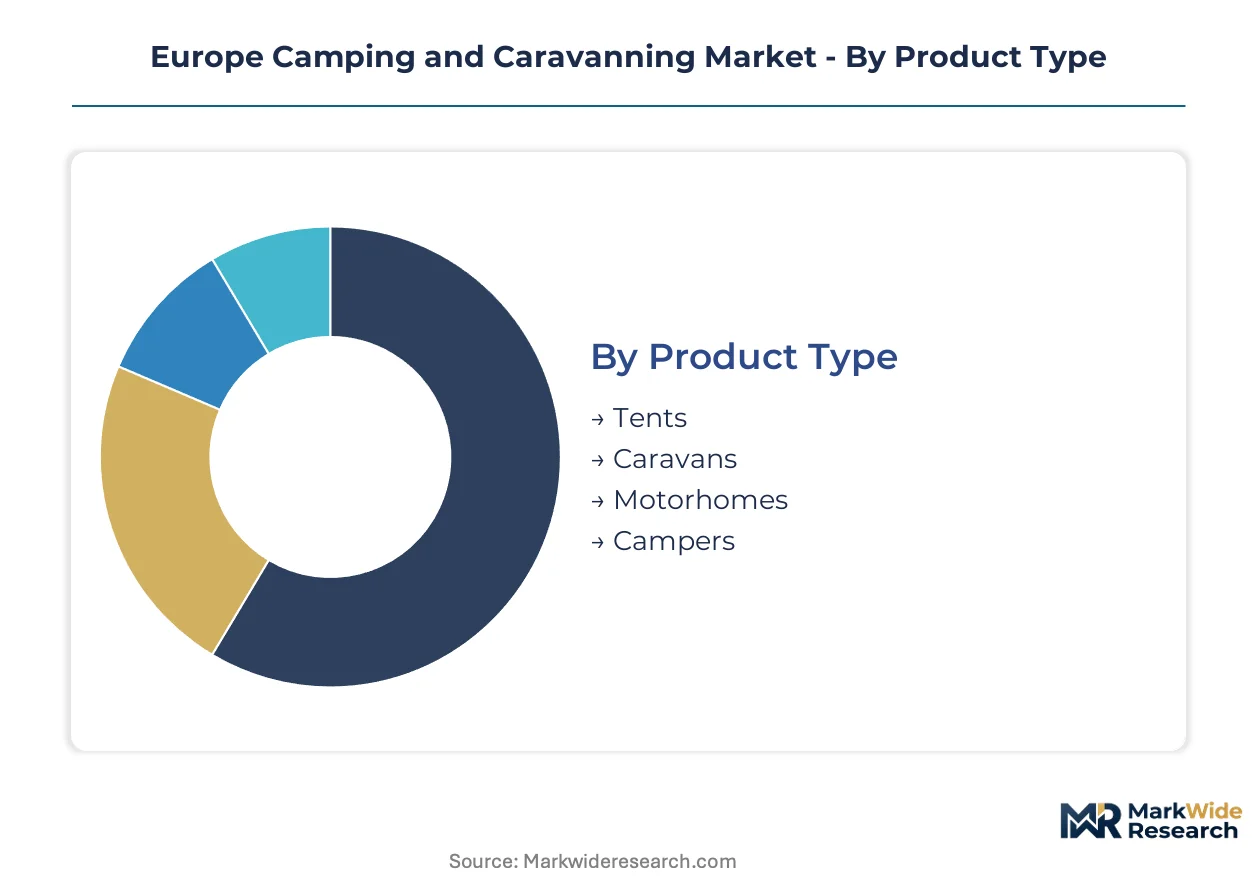
Segmentation across the Europe Camping and Caravanning Market reveals distinct margin architectures and capital intensity profiles. Equipment categories separate by manufacturing complexity while service models diverge around asset ownership versus recurring revenue capture.
Product Type:
Standardization decreases from fixed shelter systems through integrated drivetrain platforms, with customization options expanding proportionally to unit value.
- Motorhomes:Self-propelled recreational vehicles combine living quarters with internal combustion or electrified drivetrains. German KBA type-approval processes now embed lifecycle carbon calculations that extend compliance obligations to supplier tiers. Families in France and Germany concentrate demand here, though solo travelers with remote-work flexibility are extending average trip durations and elevating per-unit utilization rates.
- Caravans:Towable accommodation units constructed from aluminum framing, composite panels, and weather-resistant textiles. REACH chemical restrictions on interior finishes and insulation foams are pushing manufacturers toward certified alternative suppliers in Bavaria and Baden-Württemberg production clusters. Young families across France, Germany, and Spain prioritize these for domestic outdoor holidays over long-haul travel.
- Campers:Compact van conversions offering sleeping and basic cooking facilities within modified commercial vehicle platforms. Urban professionals in Spain and Italy favor these for weekend mobility.
- Tents:Portable shelter systems rated for UV exposure and thermal insulation. Lowest capital barrier attracts price-sensitive entry segments and seasonal users.
Most installed capacity flows through Caravans. Expansion is steepest in Motorhomes.
End User:
Volume concentration sits with multi-person travel parties while margin expansion tracks individual travelers seeking extended-duration stays.
- Families:Multi-generational travel parties prioritizing shared accommodation and self-contained cooking facilities. Domestic outdoor holiday prioritization across France, Germany, and Spain sustains pitch occupancy above seasonal norms for this segment.
- Solo Travelers:Individual travelers with location-flexible employment arrangements. Remote-work trip extension is expanding addressable revenue per pitch beyond traditional weekend-peak patterns at managed campsite networks in coastal France and Italy.
- Couples:Dual-person travel parties balancing comfort requirements with mobility preferences. Mid-tier motorhome configurations attract this group.
- Adventure Seekers:Activity-focused travelers prioritizing equipment durability and off-grid capability. Eastern European pitch expansion in Poland, Romania, and Bulgaria targets this segment ahead of EU cohesion fund accessibility improvements.
Volume leadership rests with Families. Solo Travelers are gaining share fastest.
Distribution Channel:
Channel selection correlates with purchase consideration cycles and technical complexity of the underlying product.
- Direct Sales:Manufacturer-controlled channels for high-consideration motorized and towable units. Knaus Tabbert leverages German manufacturing scale to navigate stricter carbon-border requirements through captive customer relationships.
- Specialty Stores:Dedicated retail networks offering installation and after-sales service for complex electrical and wastewater systems. Certified installation technician scarcity constrains network expansion.
- Online Retail:Digital channels capturing accessory transactions and replacement-part revenue. Weather-resistant textiles and UV-rated components bypass specialty store markups here.
- Supermarkets:Mass retail for entry-level tents and basic camping equipment. Seasonal merchandising drives volume concentration.
Transaction value concentrates through Direct Sales. Digital penetration is climbing the fastest.
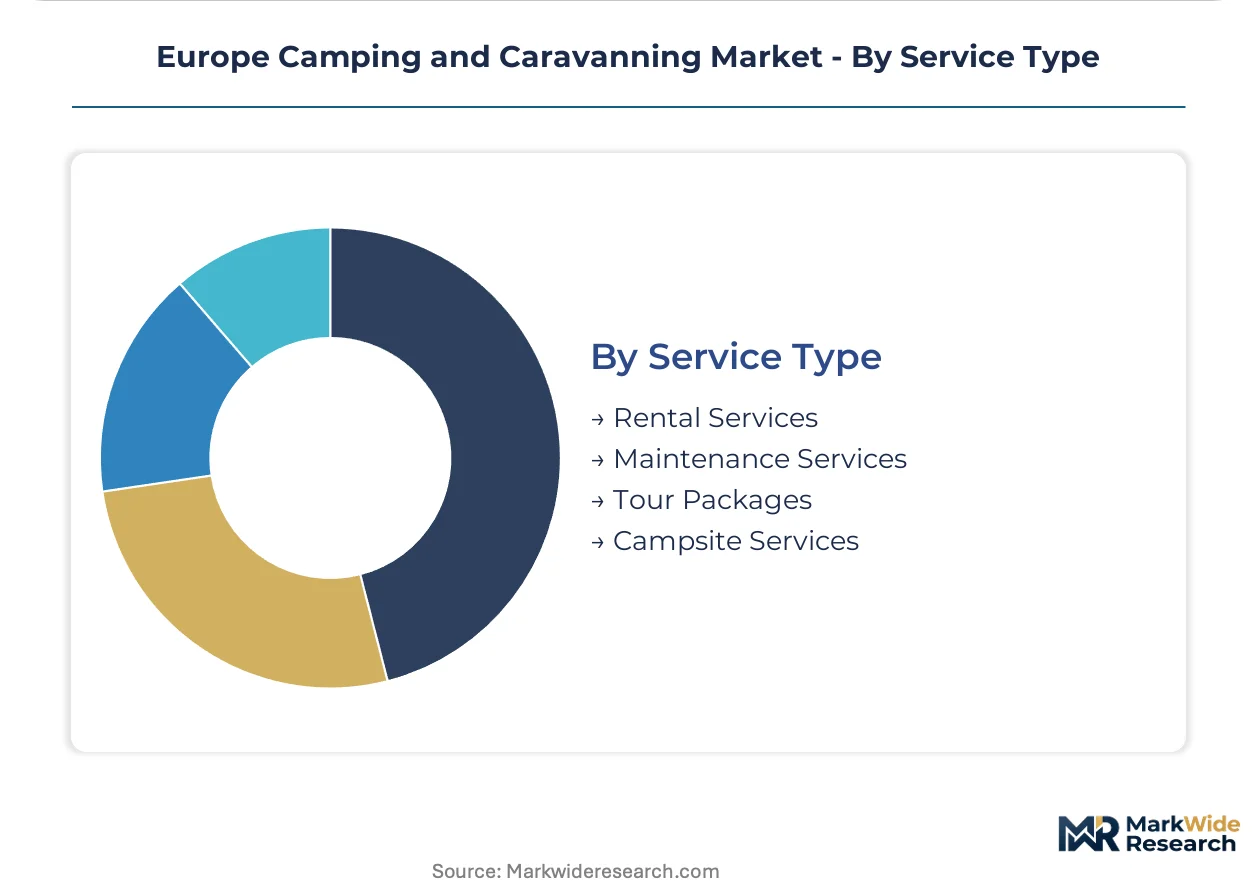
Service Type:
Revenue models diverge around asset ownership, with rental and subscription formats reducing capital barriers for intermittent users.
- Campsite Services:Pitch provision with electrical hookups, sanitation, and amenity access. Solar-integrated photovoltaic canopy systems over parking bays enable feed-in tariff capture and premium tier differentiation.
- Rental Services:Short-term equipment access without ownership obligation. Eurocamp differentiates via managed networks controlling premium coastal locations in France and Italy.
- Maintenance Services:Technical support for wastewater, electrical, and HVAC systems. Mobile application subscriptions bundle after-sales service with pitch bookings.
- Tour Packages:Curated itinerary products combining transportation, accommodation, and activity access. Lowest capital intensity attracts new market entrants.
Revenue stability flows through Campsite Services. Rental Services are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled technicians and certified installation specialists concentrate in Bavarian and Baden-Württemberg production clusters, anchoring equipment manufacturing quality standards across the continent.
Germany
KBA type-approval processes now embed lifecycle carbon calculations extending to supplier tiers, tightening compliance for motorized recreational vehicles. The EU Green Deal drives progressive emissions thresholds through German federal transposition. Bavarian and Baden-Württemberg manufacturing clusters host captive component supply chains insulating against carbon-border shocks.
France
Young families prioritize domestic outdoor holidays over long-haul travel, sustaining pitch occupancy above seasonal norms. National building codes shape wastewater systems and electrical hookup standards for new caravan models. Coastal Provence-Alpes-Côte d'Azur and Nouvelle-Aquitaine regions concentrate managed campsite networks controlling premium locations.
Spain
Urban professionals favor compact van conversions for weekend mobility, expanding camper segment addressability. REACH chemical restrictions transposed through Spanish product safety regulations limit interior finish material choices. Madrid and Catalonia host distribution hubs serving Mediterranean demand clusters with reduced logistics friction.
Italy
Solo travelers with remote-work flexibility extend trip durations, elevating per-pitch revenue beyond weekend-peak patterns. ECHA enforcement of REACH compliance accelerates certified supplier consolidation for foam and textile producers. Northern Lombardy and Veneto regions anchor manufacturing subcontractor networks feeding German and French assemblers.
Poland
Adventure seekers target underdeveloped campsite infrastructure ahead of EU cohesion fund accessibility improvements. National environmental ministry guidelines anticipate EU Green Deal thermal efficiency mandate transposition. Warsaw and Kraków metropolitan areas concentrate emerging equipment rental service operators building first-mover positioning.
Europe Camping and Caravanning Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across equipment manufacturing and managed campsite services. The vendor base organizes around three strategic archetypes: integrated manufacturers with captive component supply, managed network operators controlling premium locations, and rental service platforms reducing ownership barriers. M&A activity concentrates among campsite network consolidators. Technology licensing partnerships proliferate between motorhome drivetrain suppliers and living-system integrators.
Among German-based manufacturers, Knaus Tabbert and Erwin Hymer Group exemplify integrated production archetypes with proximity to Bavarian supplier clusters. Adria Mobil anchors Slovenian-based positioning sustaining Mediterranean market access. Eurocamp occupies a distinct tier within managed campsite services through coastal location control in France and Italy.
| Leading Market Players |
|---|
| Knaus Tabbert |
| Adria Mobil |
| European Camping Group |
| Eurocamp |
| First Camp |
| Erwin Hymer Group |
| ACSI |
| Swift Group |
| Trigano |
| Others |
Value Network & Pricing Analysis
EU Green Deal carbon targets gate both qualified component supply and premium-tier pricing access, as REACH-compliant foam and textile producers command material premiums while campsite operators with solar-integrated infrastructure capture tariff-linked rate premiums from sustainability-focused travelers.
Pricing Analysis
Bundled pitch-plus-service contracts diverge from unbundled equipment-only transactions across managed campsite networks. Three-tier pricing structure across premium, standard, and economy levels separates solar-canopy pitches with feed-in tariff eligibility from basic electrical hookup tiers. Price differentiation hinges on after-sales service bundling and thermal efficiency certification grades. Cost compression in entry-level caravan segments intensifies because aluminum and composite panel input volatility outpaces retail pricing flexibility. Young families show highest price sensitivity, while solo travelers with extended remote-work stays exhibit lowest sensitivity to per-night rates.
Supply Chain Analysis
REACH certification and KBA type-approval gating concentrate qualified supplier relationships among Bavarian and Baden-Württemberg production clusters. Component supply draws from Germany, Slovenia, and Italy for aluminum framing, composite panels, and weather-resistant textiles. Raw material dependencies center on aluminum sheet, polyurethane foam insulation, and UV-rated acrylic fabrics. Single-source vulnerability runs through certified adhesive and sealant suppliers subject to ECHA enforcement actions. Distribution runs through direct manufacturer channels for motorized units and specialty retail networks for towable equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal thermal efficiency mandate transposition acts as a regulatory compounder, accelerating replacement cycles for non-compliant campsite infrastructure and certified-component caravan models.
For Market Incumbents: Deepen captive supply relationships with REACH-certified foam and textile producers to insulate margin structures from carbon-border adjustment exposure. Expand installation technician training pipelines in France and Germany to address certified service personnel scarcity threatening aftermarket revenue capture. Prioritize backward integration into photovoltaic canopy system deployment to lock in premium pitch tier positioning ahead of national mandate clarity. For New Entrants and Emerging Players: Launch via online replacement-part retail channels targeting weather-resistant textiles and UV-rated components, bypassing specialty store markups with direct-to-consumer logistics. Target underdeveloped campsite infrastructure in Poland and Romania where EU cohesion fund accessibility improvements will elevate pitch demand ahead of supply response. Pursue rental service platform models reducing ownership barriers for intermittent young family users. For Investors and Strategic Acquirers: Valuations sit cheapest among equipment rental operators with coastal location control in France and Italy, where recurring revenue visibility extends beyond transactional manufacturing margins. Long-term viability favors managed campsite network consolidators with proprietary mobile application service bundling capabilities. Monitor national transposition timelines for EU Green Deal thermal efficiency mandates as the signal indicating infrastructure replacement capex acceleration or deferral.| Strategic Initiative | Industry Significance |
|---|---|
| Solar-Integrated Infrastructure Deployment | Photovoltaic canopy systems over parking bays enable feed-in tariff capture and premium pitch tier differentiation in coastal France and Italy. |
| REACH-Certified Supplier Consolidation | Preferred vendor relationships with compliant foam and textile producers lock in material access as ECHA enforcement accelerates. |
| Mobile Application Service Bundling | Proprietary platforms unbundling after-sales maintenance from equipment purchase capture recurring subscription revenue from young families. |
| Eastern European Pitch Expansion | First-mover positioning in Poland, Romania, and Bulgaria precedes EU cohesion fund accessibility improvements driving adventure seeker demand. |
| Lightweight Composite Panel Adoption | Integrated thermal break technology converts aluminum-intensive production lines while meeting escalating insulation standards without payload penalties. |
Research Methodology
Multiple input streams — campsite operator financial disclosures, equipment manufacturer production data, and national regulatory filings — were reconciled against primary interviews with campsite network directors, caravan manufacturer procurement leads, and certified installation technicians. Secondary validation drew from KBA type-approval databases, ECHA REACH substance registrations, and EU cohesion fund accessibility project trackers. Bottom-up pitch occupancy modeling and top-down equipment shipment aggregation were cross-referenced to establish volume baselines.
Historical booking pattern analysis was cross-referenced against expert panel input from managed campsite network executives and motorhome drivetrain suppliers. Segmentation dimensions modeled include product type, end-user archetype, distribution channel, and service format across the projection horizon. CAGRs were derived from segment-level growth trajectory blending rather than aggregate market extrapolation. Forecast inputs incorporated remote-work trip duration elasticity and national transposition timeline uncertainty for EU Green Deal mandates.
Several conditions sit outside the modeled scope, including abrupt aluminum commodity price shocks, unilateral national regulatory accelerations beyond EU baseline timelines, and pandemic-scale mobility restrictions. Forecasts reflect documented assumptions regarding cohesion fund disbursement schedules and certified supplier capacity expansion rates. A model refresh is warranted upon material change in EU Green Deal national transposition timelines or REACH substance restriction amendments affecting interior finish material availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accommodation
Switzerland Hospitality Market
Accommodation
France Online Accommodation Market
Accommodation
Hong Kong Hospitality Industry Market
Accommodation
Hotel Market
Accommodation
Asia-Pacific Travel Accommodation Market
Accommodation
Recreational and Vacation Camp Market
Accommodation
US Student Accommodation Market
Accommodation
US Recreational and Vacation Camp Market
Accommodation
Luxury Hotel Market
Accommodation
Europe Student Accommodation Market
Accommodation
Japan Hospitality Market
Accommodation
ASEAN Online Accommodation Market
Accommodation
Global Travel Accommodation Market
Accommodation
Glamping Market
Accommodation
France Hospitality Market
Accommodation
Japan Online Accommodation Market