
 Middle East and Africa Travel Retail Market | 2026-2036
Middle East and Africa Travel Retail Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Travel Retail Market Foresight
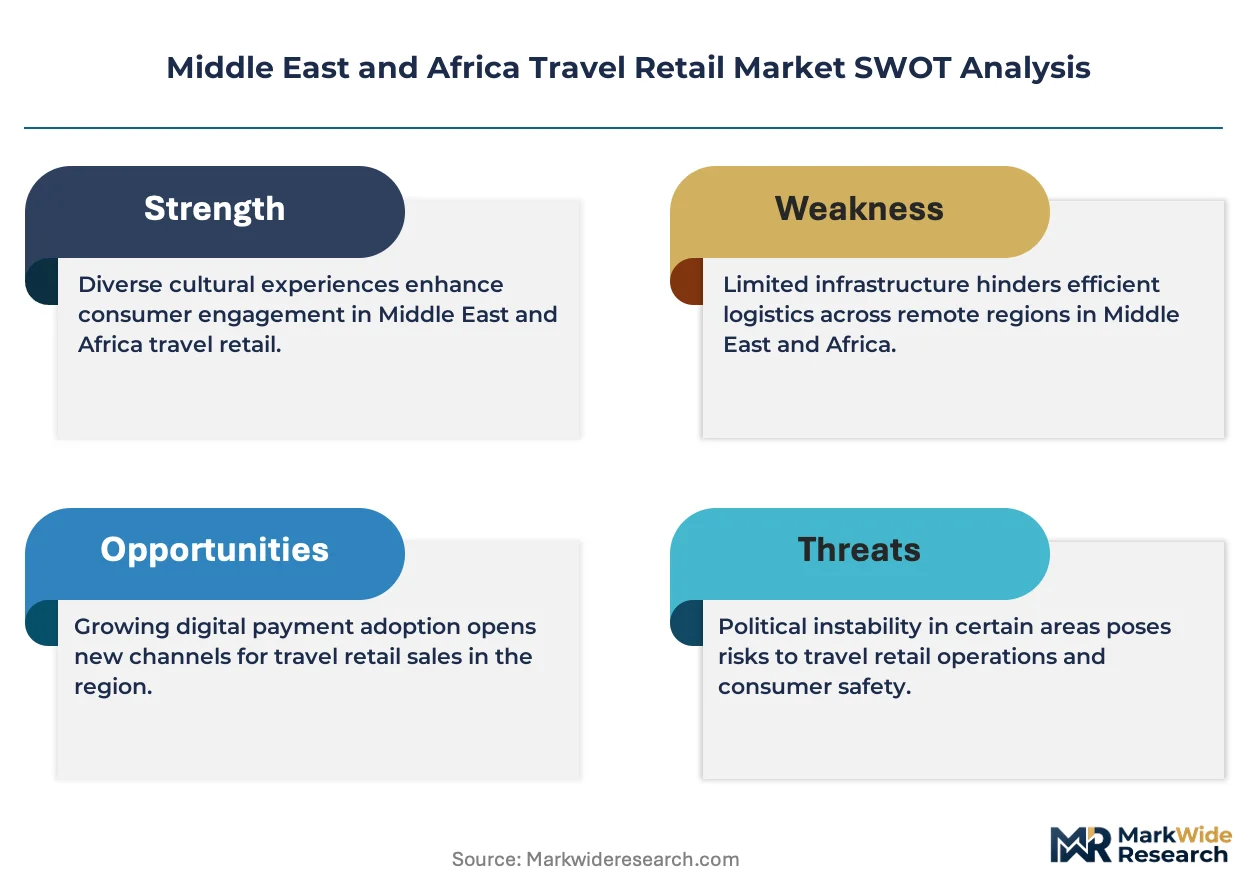
The split between luxury flagship concessions and standardized convenience retail is realigning how operators bid for airport contracts across the Middle East and Africa. Qatar Duty Free leverages its Doha Hamad International hub dominance to secure exclusive luxury brand partnerships. Dufry AG competes through its scale advantage across multiple African airport portfolios. Dubai Duty Free anchors regional profitability with one of the world's highest per-passenger spending rates.
Travel retail encompasses tax-exempt and duty-free merchandise sold to international passengers within transit zones, typically requiring proof of onward travel and subject to quantity limits on alcohol, tobacco, and fragrances. The channel functions as a controlled commercial environment where pricing advantages derive from suspended customs duties and value-added taxes rather than conventional retail markups. Cosmetics and alcohol command the strongest margin pools among product categories, while airport retail maintains structural dominance over online and ferry channels due to captive audience dynamics. Luxury brand positioning captures disproportionate profit share, though mid-range and emerging labels are expanding shelf space to serve price-sensitive African transit routes.
Saudi Food and Drug Authority regulations govern alcohol-free fragrance formulations and tobacco display standards across Kingdom airports, while UAE customs frameworks set duty-free allowance thresholds that directly shape basket size optimization. South Africa's National Regulator for Compulsory Specifications enforces product authenticity protocols that affect cross-border inventory movement. Stakeholders must monitor how Gulf state tourism diversification strategies and evolving passenger duty allowances will reshape concession economics and inventory mix priorities.
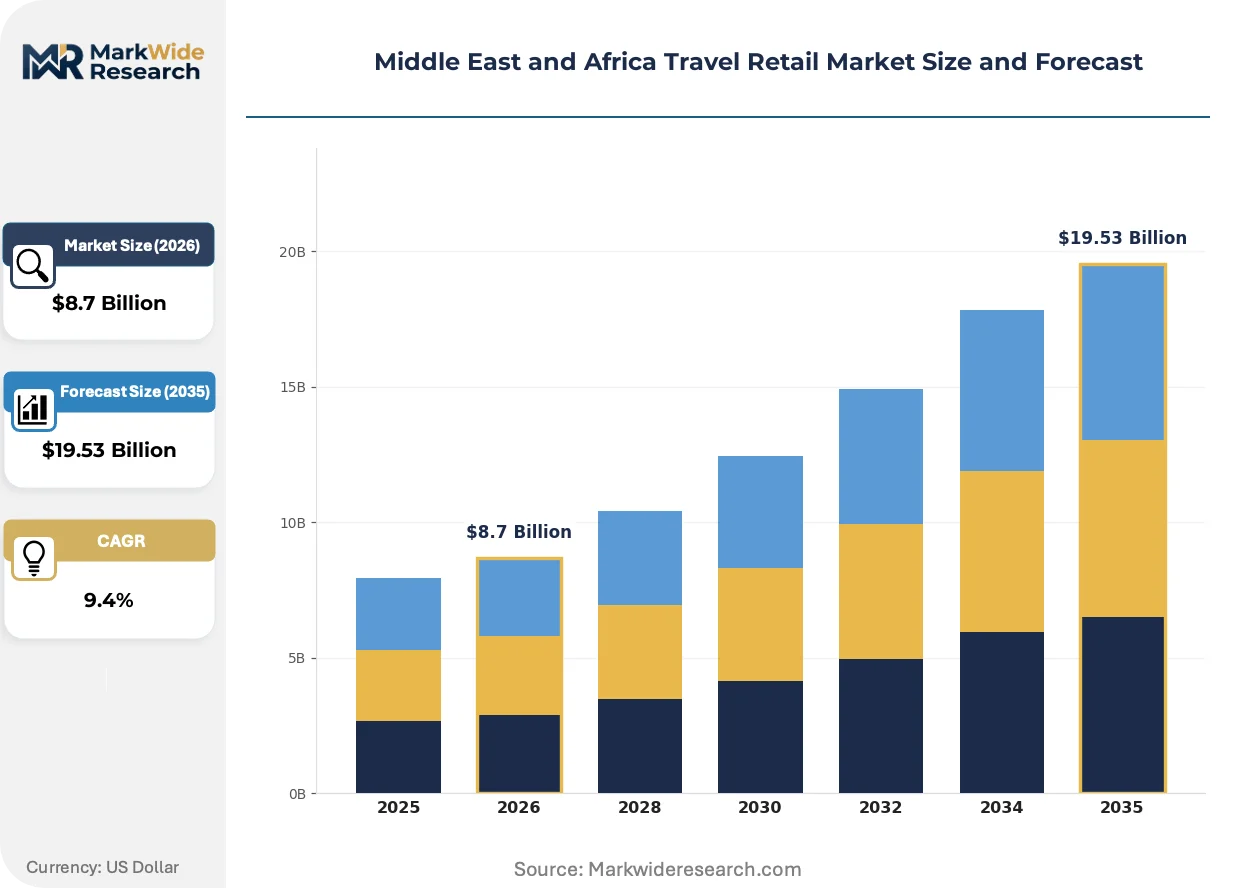
Market Dynamics
The GCC aviation expansion pipeline is restructuring concession economics across Middle East and Africa travel retail, with Saudi Arabia's giga-project tourism infrastructure and secondary African hub development redistributing passenger flow patterns.
Growth Catalysts
- Visa Liberalization Frameworks:Saudi Arabia's e-visa rollout and UAE golden visa extensions are expanding eligible international passenger pools for duty-free eligibility.
- Fragrance Formulation Standards:Alcohol-free perfume innovations compliant with SFDA and MOHAP regulations are unlocking new product lines for conservative Gulf markets.
- Secondary Hub Development:Morocco, Kenya, and Ethiopia are expanding airport retail footprints to capture intra-African transit traffic previously routed through European hubs.
Market Restraints
- Duty Allowance Compression:UAE and Qatar customs frameworks impose strict tobacco and alcohol quantity thresholds that cap maximum transaction values per passenger.
- Inventory Authenticity Enforcement:South Africa's National Regulator for Compulsory Specifications mandates costly product verification protocols that slow cross-border stock movements.
- Luxury Brand Concentration:LVMH, Kering, and Estée Lauder control premium shelf access terms, squeezing margin flexibility for airport concessionaires.
Strategic Opportunities
- Saudi Giga-Project Corridors:NEOM, Red Sea Project, and Qiddiya are creating new destination-driven passenger flows requiring dedicated retail concepts.
- Digital Pre-Order Platforms:Click-and-collect duty-free systems are reducing physical footprint requirements while capturing passenger spend before airport arrival.
- African Route Densification:Underpenetrated routes connecting Lagos, Nairobi, and Cairo to Asian hubs represent white-space concession bidding opportunities.
Industry Challenges
- Concession Bidding Intensity:Airport authorities are shortening contract tenures and demanding higher minimum revenue guarantees from operators.
- Halal Certification Complexity:Multi-jurisdictional fragrance and cosmetics compliance across Gulf states requires parallel formulation and labeling workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Travel Retail Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Category: Cosmetics, Alcohol, Tobacco, Fashion Accessories Customer Type: Tourists, Business Travelers, Local Shoppers, Duty-Free Buyers Sales Channel: Airport Retail, Online Retail, Ferry Terminals, High Street Brand Positioning: Luxury Brands, Mid-Range Brands, Budget Offerings, Emerging Brands |
| Companies Covered | Qatar Duty Free, Aer Rianta International, Dufry AG, Gebr. Heinemann SE & Co. KG, King Power International Group, Lagardère Travel Retail, The Shilla Duty Free, Avolta AG, Dubai Duty Free, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Travel Retail Market Shifts & Advancements
Biometric passenger processing and pre-journey digital engagement are compressing dwell-time windows and reshaping how travel retail captures discretionary spend.
AI-powered personalized recommendation engines deployed through airline app integrations are overtaking traditional in-terminal discovery browsing. Emirates and Etihad loyalty programs are feeding passenger preference data to duty-free operators in real-time. This data conduit is enabling dynamic pricing and inventory alerts that compress decision cycles before travelers reach physical retail zones.
MOHAP's updated cosmetic product registration requirements in the UAE are forcing reformulation timelines for international beauty brands seeking Gulf market access. The regulator's tightened ingredient disclosure rules are extending new product launch cycles by four to six months. Fragrance houses are responding by establishing dedicated Middle East R&D facilities to accelerate regional compliance.
Chinese outbound traveler preferences are rotating away from bulk luxury purchases toward experiential and wellness-oriented retail categories. Dubai Duty Free and Qatar Duty Free are reallocating square meters from traditional leather goods to traditional medicine and premium dates. This category pivot is most visible at Doha Hamad International's expanded wellness retail zone targeting Asia-Pacific transit routes.
Middle East and Africa Travel Retail Market Segmentation
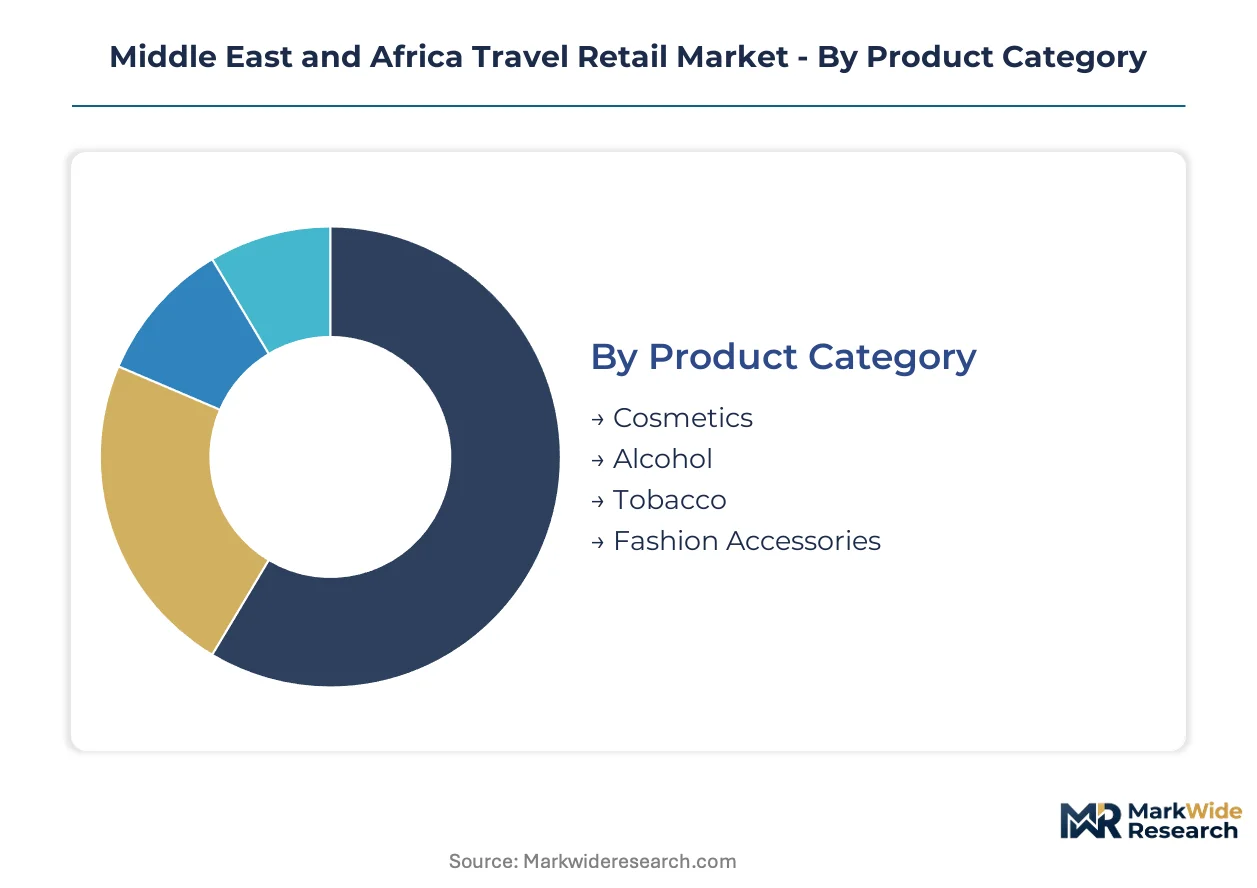
Travel retail segmentation in the Middle East and Africa follows passenger behavioral patterns and regulatory boundaries rather than conventional retail demographics. Duty-free eligibility rules, visa frameworks, and transit corridor economics create distinct commercial zones that operators must navigate through differentiated inventory and pricing architectures.
Product Category:
Product mix decisions hinge on margin architecture and customs allowance thresholds rather than pure volume velocity.
- Cosmetics:Skincare and fragrance formulations dominate basket composition, with alcohol-free perfume variants engineered for SFDA and MOHAP compliance unlocking Gulf market access. Demand clusters at Dubai International and Doha Hamad International, where Asian transit passengers sustain premium unit economics.
- Alcohol:Whisky and champagne portfolios generate the highest per-transaction values but face strict quantity caps under UAE and Qatari customs frameworks. Saudi Arabia's prohibition eliminates this category entirely from Kingdom airport concessions, reshaping regional inventory allocation.
- Tobacco:Cigarette and cigar sales remain volume-stable despite allowance compression, with Dubai Duty Free maintaining dedicated humidor concepts for Havanas and limited regional exclusives.
- Fashion Accessories:Leather goods and watches command discretionary spend from Chinese and Indian outbound travelers, though square-meter productivity lags cosmetics in constrained terminal footprints.
Cosmetics leads on scale; alcohol leads on margin contribution per square meter where regulatory permits.
Customer Type:
Passenger segmentation reflects visa eligibility, travel purpose, and duty-free qualification status rather than income brackets alone.
- Tourists:Saudi e-visa holders and UAE golden visa visitors drive seasonal volume spikes, with spending concentrated in fragrance and dates during religious pilgrimage windows.
- Business Travelers:Premium cabin passengers exhibit compressed dwell times but elevated conversion rates on electronics and luxury accessories.
- Local Shoppers:UAE and Qatar residents exploit duty-free access on outbound journeys, creating a distinct "fly-to-buy" segment for tobacco and alcohol categories unavailable domestically.
- Duty-Free Buyers:Eligibility-verified international transit passengers represent the core addressable market, with biometric boarding pass integration streamlining purchase authorization.
Tourists deliver volume concentration; business travelers deliver the steepest expansion trajectory as Gulf aviation capacity adds premium seats.
Sales Channel:
Channel economics diverge sharply on captive audience dynamics and real estate cost structures.
- Airport Retail:Concession-based terminal operations capture ninety percent of regional travel retail value, with Dubai International and Abu Dhabi Zayed International anchoring per-passenger spending benchmarks.
- Online Retail:Pre-order platforms and click-and-collect systems reduce physical footprint requirements while capturing spend before terminal arrival, expanding fastest among Emirates and Etihad loyalty program integrations.
- Ferry Terminals:Red Sea and Gulf maritime corridors serve limited passenger volumes with restricted product categories, concentrated at Jeddah Islamic Port and Djibouti transit routes.
- High Street:Downtown duty-free zones in Dubai and Abu Dhabi serve non-traveling residents through specialized licensing, blurring traditional channel boundaries.
Airport retail dominates current revenue; online retail is gaining share fastest through airline app ecosystem penetration.
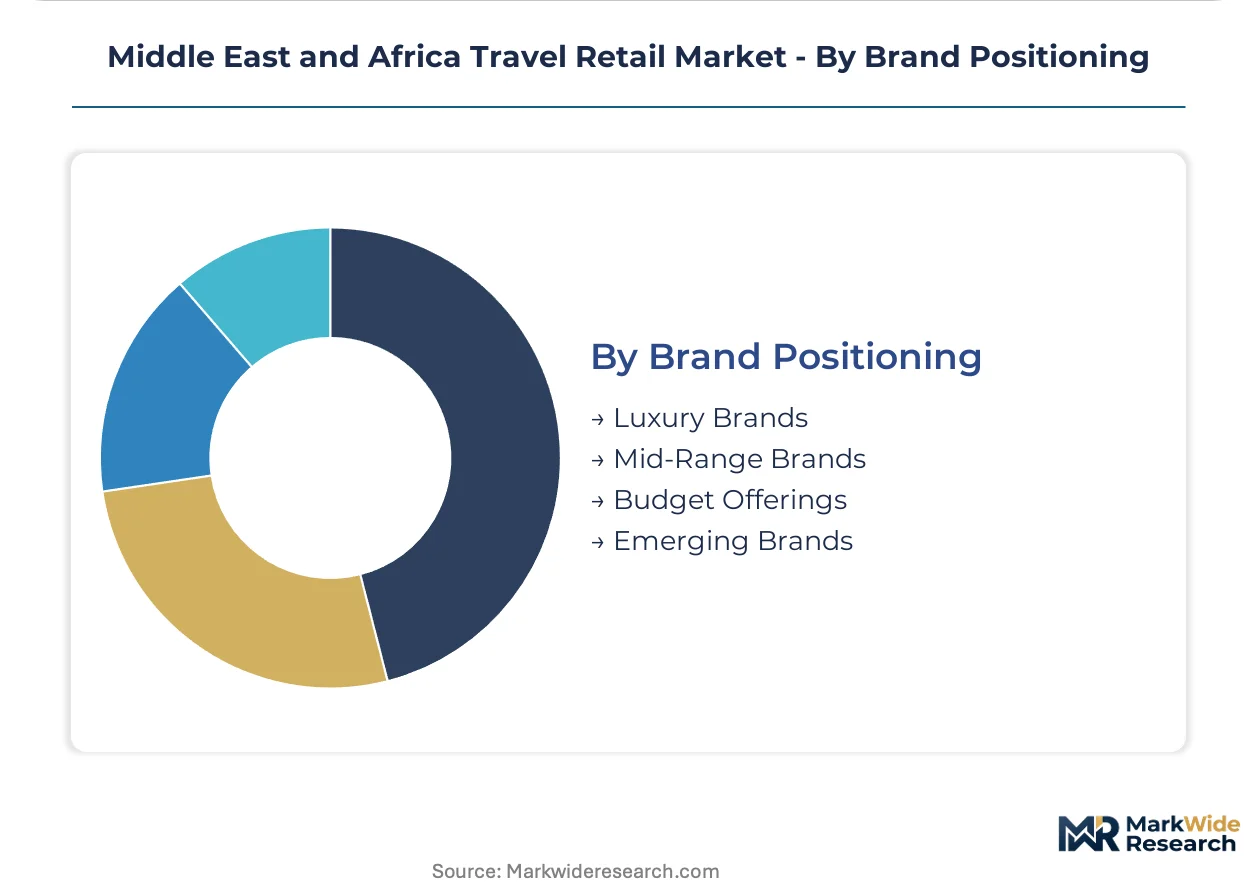
Brand Positioning:
Brand tiering reflects shelf access negotiations and minimum revenue guarantee structures rather than pure consumer preference mapping.
- Luxury Brands:LVMH, Kering, and Estée Lauder portfolios command prime location terms and dedicated boutique formats, extracting favorable concession economics through exclusive distribution rights.
- Mid-Range Brands:Coty and Shiseido segments serve price-sensitive African transit routes and secondary Gulf hubs, filling inventory gaps between flagship and entry tiers.
- Budget Offerings:Local fragrance houses and regional cosmetics labels capture intra-African traffic at Nairobi and Lagos airports, where passenger purchasing power constrains premium penetration.
- Emerging Brands:Korean beauty and halal-certified startups are securing trial placement at Doha and Dubai, testing Gulf market receptivity before full concession rollout.
Luxury brands anchor profitability; emerging brands climb the fastest as Korean and halal-certified portfolios expand shelf trials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aviation infrastructure specialists and hospitality workforce clusters in Dubai and Doha anchor travel retail operations across the Middle East and Africa corridor. These talent concentrations support concession management, luxury brand partnerships, and passenger experience design that differentiate regional hubs.
United Arab Emirates
Dubai International Airport and Abu Dhabi Zayed International Airport process the highest per-passenger spending volumes in the region, driven by Asian transit traffic and resident fly-to-buy patterns. MOHAP regulates cosmetic product registrations with tightened ingredient disclosure rules that extend launch cycles. Dubai Duty Free operates flagship concessions at DXB Terminal 3, where biometric boarding pass integration streamlines purchase authorization.
Saudi Arabia
NEOM, Red Sea Project, and Qiddiya giga-projects are generating destination-driven passenger flows that require dedicated retail concepts beyond traditional airport formats. SFDA governs alcohol-free fragrance formulations and tobacco display standards across Kingdom airports. Riyadh King Khalid International Airport is expanding terminal retail footprints to capture e-visa tourist arrivals.
Qatar
Doha Hamad International Airport leverages its hub dominance to secure exclusive luxury brand partnerships and wellness retail zones targeting Asia-Pacific transit routes. The country's customs frameworks impose strict alcohol and tobacco quantity thresholds that cap transaction values. Qatar Duty Free operates expanded retail concepts in the airport's central concourse.
South Africa
Cape Town and Johannesburg OR Tambo International Airports serve as gateways for intra-African traffic previously routed through European hubs. The National Regulator for Compulsory Specifications enforces product authenticity protocols that slow cross-border inventory movements. Durban's coastal position supports limited maritime duty-free corridors.
Morocco
Casablanca Mohammed V International Airport is expanding retail footprints to capture West African transit traffic and religious pilgrimage flows. The country's aviation authority is liberalizing concession access rules to attract international operators. Marrakech Menara Airport serves as a secondary hub for European leisure routes.
Middle East and Africa Travel Retail Market Competitive Landscape
Top-tier vendors anchor hub-specific concessions, while mid-scale operators compete across secondary African portfolios. The market structures around airport authority contract tenures and minimum revenue guarantee demands that compress operator margins. Three archetypes dominate: Gulf-based hub specialists, European multinational concessionaires, and Asian luxury retail platforms. Competitive positioning depends on securing exclusive brand partnerships and deploying digital pre-order platforms that reduce physical footprint requirements.
Within the hub-specialist tier, Qatar Duty Free and Dubai Duty Free represent geographic concentration strategies that leverage single-airport dominance for favorable concession terms. Dufry AG occupies a position exemplifying scale-driven portfolio diversification across multiple jurisdictions. These three entities anchor distinct competitive vectors: exclusive brand access, per-passenger spending optimization, and geographic breadth.
| Leading Market Players |
|---|
| Qatar Duty Free |
| Aer Rianta International |
| Dufry AG |
| Gebr. Heinemann SE & Co. KG |
| King Power International Group |
| Lagardère Travel Retail |
| The Shilla Duty Free |
| Avolta AG |
| Dubai Duty Free |
| Others |
Supply & Pricing Matrix
Biometric boarding pass integration and pre-order platform deployment are compressing physical retail footprints while simultaneously elevating fixed-cost absorption pressures across concession operations. This technology shift concentrates procurement leverage among operators with scale to amortize digital infrastructure investments, reshaping how margin pools distribute between hub specialists and fragmented African portfolio players.
Pricing Analysis
The bundled-vs-unbundled service split separates full-service concession packages from modular fixture-only arrangements. Three-tier pricing structure across premium flagship, standard inline, and economy convenience formats governs shelf access negotiations. Price differentiation rests on location traffic density and exclusive brand distribution rights. Pricing pressure stems from airport authorities demanding higher minimum revenue guarantees. Budget-tier African transit routes exhibit the steepest price sensitivity; Gulf hub concessions show the most inelastic demand.
Supply Chain Analysis
Direct-to-brand partnerships handle luxury fragrance and cosmetics demand, while consolidated distributors manage mid-range inventory for secondary African hubs. Geographic supply concentration centers on France, Switzerland, and South Korea for fragrance formulations; China and South Korea for electronics and Korean beauty. Raw material dependencies include alcohol-free perfume bases, halal-certified cosmetic ingredients, and tobacco leaf sourcing. Single-source vulnerability runs through exclusive LVMH and Estée Lauder distribution agreements. Distribution runs through bonded warehouse networks at Dubai Airport Freezone and Doha Logistics City.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa travel retail market functions as a stable compounder anchored by aviation infrastructure expansion across Gulf Cooperation Council states. Visa liberalization and giga-project tourism corridors generate durable passenger flow growth that supports concession economics through cyclical fluctuations.
For Market Incumbents: To counter shortening concession contract tenures and escalating minimum revenue guarantees, Dubai Duty Free and Qatar Duty Free should deepen exclusive brand partnerships through dedicated boutique investments. Backward integration into halal-certified R&D facilities accelerates MOHAP and SFDA compliance timelines. Channel control through airline loyalty app ecosystems preserves pre-order capture rates. For New Entrants and Emerging Players: Airport authorities in Lagos, Nairobi, and Cairo represent the most penetrable concession bidding opportunities as these hubs densify Asian route connectivity. Korean beauty and halal-certified fragrance startups should target trial placement at Doha Hamad International's wellness retail zone before pursuing full concession rollout. A go-to-market angle emphasizing digital pre-order platform deployment reduces physical footprint requirements and minimum guarantee exposure. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale African portfolio operators with concentrated exposure to intra-African transit traffic growth. Long-term viability over a five-to-ten year window favors operators securing exclusive distribution rights for emerging halal-certified and Korean beauty brands. The signal to watch is Saudi giga-project corridor passenger flow maturation as NEOM and Red Sea Project infrastructure reaches operational scale.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Brand Partnership Expansion | Secures dedicated boutique formats with LVMH and Estée Lauder at DXB Terminal 3. |
| Halal-Certified R&D Facility Investment | Accelerates MOHAP and SFDA compliance timelines for alcohol-free fragrance launches. |
| Digital Pre-Order Platform Deployment | Captures passenger spend through Emirates and Etihad loyalty app integrations. |
| Secondary African Hub Concession Bidding | Targets underpenetrated routes connecting Lagos, Nairobi, and Cairo to Asian hubs. |
| Biometric Boarding Pass Integration | Streamlines purchase authorization and reduces terminal dwell-time friction. |
Research Methodology
Multiple input streams — primary interviews with airport concession directors, luxury brand regional heads, and aviation infrastructure planners; secondary validation through customs authority filings, airport authority procurement disclosures, and airline passenger traffic databases — were reconciled through bottom-up and top-down triangulation. Stakeholder roles included duty-free operators, fragrance house regulatory affairs leads, airport retail procurement managers, and Gulf aviation expansion project developers.
Historical passenger spending patterns were cross-referenced against expert panel assessments of giga-project corridor maturation and visa liberalization impacts. Segmentation dimensions modeled include product category, customer type, sales channel, and brand positioning tier across the projection horizon. CAGRs were derived through trend extrapolation adjusted for regulatory constraint scenarios. Industry-specific forecast inputs incorporated biometric processing adoption curves and digital pre-order penetration rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Saudi tourism diversification execution and African route densification timing. Forecasts reflect documented assumptions regarding passenger duty allowance stability and concession contract tenure evolution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
New Zealand Sports Tourism Market
Travel and Tourism
Travel Intermediaries Business Market
Travel and Tourism
Water Park Market
Travel and Tourism
France Culinary Tourism Market
Travel and Tourism
Domestic Tourism Market
Travel and Tourism
B2B Travel Market
Travel and Tourism
Mexico Sustainable Tourism Market
Travel and Tourism
US and Canada Travel Market
Travel and Tourism
Halal Tourism Market
Travel and Tourism
United Kingdom Casino Tourism Market
Travel and Tourism
Asia-Pacific Travel Retail Market
Travel and Tourism
US Outbound Tourism Market
Travel and Tourism
Sustainable Tourism Market
Travel and Tourism
Sustainable Traveling Market
Travel and Tourism
UAE Sustainable Tourism Market
Travel and Tourism
Digital Travel Market