
 RV Rental Market | 2026-2036
RV Rental Market Size, Share, and Industry Trends Forecast 2026-2036
RV Rental Market Intelligence
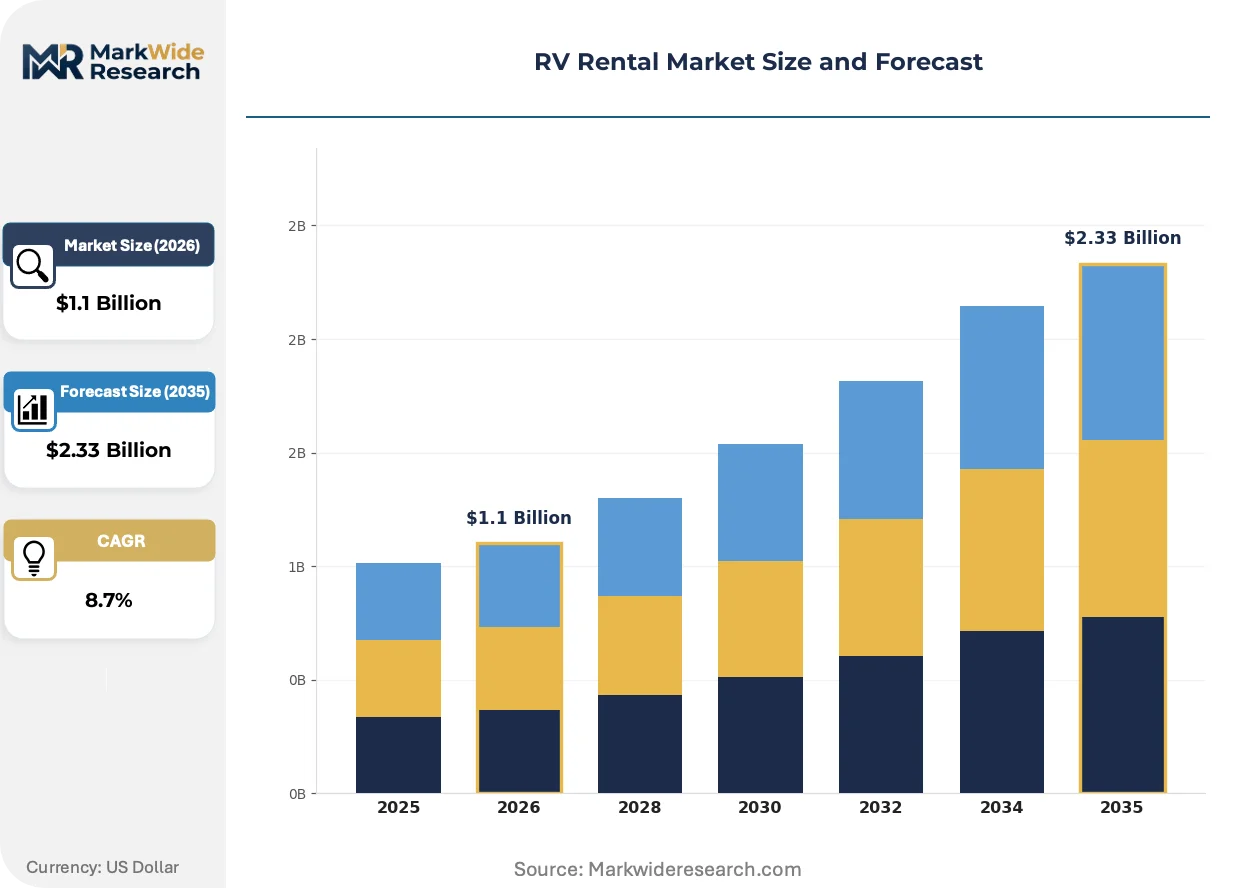
The RV rental sector is pivoting as premium motorhome experiences split from commodity camper van offerings in fleet composition, pricing architecture, and service bundling. Cruise America leverages its national depot network to sustain geographic dominance across the United States. Outdoorsy competes through peer-to-peer marketplace density, while El Monte RV anchors its position in long-term destination rentals.
RV rental denotes the short-term commercial provision of motorized and towable recreational vehicles to consumers for leisure travel, with units typically ranging from compact camper vans to Class A motorhomes exceeding thirty-five feet in length and incorporating self-contained power, water, and sanitation systems. The primary commercial purpose centers on delivering mobile lodging that eliminates fixed accommodation costs while enabling itinerary flexibility. Motorhomes command the largest revenue share due to higher daily rates and extended rental durations, while camper vans represent the fastest-growing vehicle type among solo travelers and couples prioritizing fuel efficiency and urban maneuverability. Online platforms capture growing booking volume as direct-to-consumer interfaces disintermediate traditional travel agencies.
The US DOT and NHTSA govern vehicle safety standards and commercial operator compliance, while state-level DMV regulations dictate driver licensing thresholds for heavier vehicle classes. These frameworks elevate fleet maintenance costs and restrict market entry for non-compliant operators. Stakeholders must monitor evolving emissions standards and electric RV prototype viability as zero-emission mandates begin penetrating commercial vehicle segments.
Market Dynamics
Fleet electrification pressure from California's Advanced Clean Trucks regulation is forcing capital reallocation across rental operators, while peer-to-peer platform density fragments traditional depot-based supply structures.
Growth Catalysts
- Experiential Travel Preference:Families prioritize mobile lodging over fixed accommodations, extending average rental durations during peak migration seasons.
- Remote Work Normalization:Digital nomadism sustains mid-week booking demand outside traditional weekend peaks, smoothing revenue volatility.
- US DOT Safety Compliance:Standardized commercial motor vehicle protocols elevate barrier-to-entry, protecting compliant fleet operators from informal competition.
Market Restraints
- Vehicle Acquisition Costs:Class A motorhome chassis and drivetrain component prices constrain fleet expansion timelines for mid-size operators.
- Seasonal Utilization Compression:Snowbird migration patterns concentrate demand in Arizona and Florida winters, leaving northern depots underutilized.
- Insurance Premium Escalation:Commercial liability coverage for motorized rentals outpaces general automotive policy inflation.
Strategic Opportunities
- Electric RV Prototyping:Zero-emission drivetrain development aligned with California Air Resources Board mandates creates first-mover positioning.
- Airport Hub Integration:On-site depot placement at Phoenix Sky Harbor and Orlando International captures fly-and-drive vacationers.
- Subscription Membership Models:Annual access passes convert episodic renters into recurring revenue streams with predictable utilization forecasting.
Industry Challenges
- Certified Technician Scarcity:EPA Section 609 refrigerant handling and propane system credentials limit maintenance workforce scaling.
- Fleet Management System Integration:Legacy reservation platforms require costly API overhauls to synchronize with telematics and dynamic pricing engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RV Rental Market |
| Market Size in 2026 | $1.1 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Motorhomes, Travel Trailers, Fifth Wheels, Camper Vans Booking Channel: Online Platforms, Travel Agencies, Direct Rentals, Corporate Partnerships Customer Type: Families, Couples, Solo Travelers, Adventure Seekers Duration: Short-Term, Long-Term, Weekend Rentals, One-Way Rentals |
| Companies Covered | El Monte RV, Goss RV, Cruise America, Travellers Autobarn, Boho Vans, Road Bear RV, Allstar Coaches, Outdoorsy, Native Campervans, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RV Rental Market Strategic Shifts & Innovations
Digital infrastructure is compressing booking friction and enabling real-time fleet repositioning, while powertrain diversification and service unbundling reshape operator economics.
Telematics-integrated reservation platforms are automating dynamic pricing adjustments based on inventory positioning and demand signals. Regional operators adopting these systems capture yield improvements without dedicated revenue management teams. The technology is automating what previously required manual rate board updates across dispersed depot networks.
California's Advanced Clean Trucks regulation mandates escalating zero-emission vehicle sales thresholds through 2035. Fleet operators face compliance capital requirements or geographic market exit. Long-term destination rental specialists with Arizona and Florida concentration are accelerating electrification pilot programs to maintain California market access.
Subscription-based access models are displacing traditional per-night booking for frequent renters. Younger demographics in urban coastal markets prioritize membership flexibility over ownership. This shift concentrates most visibly in Pacific Northwest metropolitan corridors where storage constraints suppress personal RV purchase intent.
RV Rental Market Segmentation
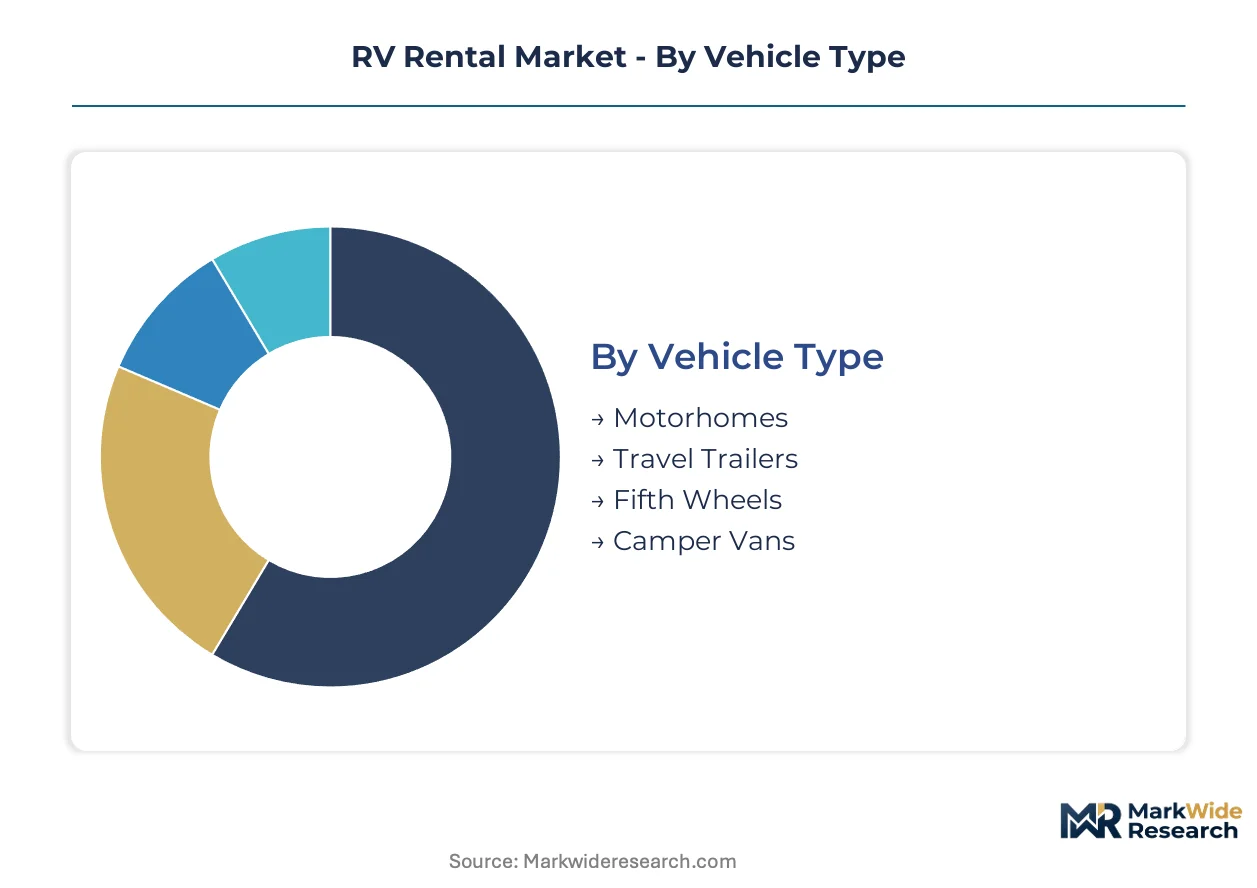
RV rental segmentation reveals how distinct customer journeys, vehicle specifications, and booking behaviors fragment revenue capture across operator business models. Fleet composition and channel strategy must align to specific trip archetypes rather than treating demand as uniform.
Vehicle Type:
Motorhomes and fifth wheels trigger NHTSA commercial motor vehicle compliance thresholds above 26,000 pounds GVWR, while camper vans and travel trailers operate under lighter regulatory burdens with standard driver's license requirements.
- Motorhomes:Self-propelled units integrating chassis, engine, and living quarters in a single structure. Demand concentrates among multi-generational families undertaking cross-country itineraries, with Class A diesel pushers commanding premium daily rates for extended seasonal migrations to Arizona and Florida.
- Camper Vans:Compact van conversions prioritizing fuel efficiency and urban parking compatibility. Solo travelers and remote workers in Pacific Northwest metropolitan corridors drive fastest expansion, with rental density surging where personal RV storage constraints suppress ownership.
- Travel Trailers:Towable units requiring separate vehicle hitching, ranging from lightweight teardrops to multi-slide bunkhouse configurations. Couples seeking flexible basecamp lodging represent core demand.
- Fifth Wheels:Heavy-duty towables connecting via in-bed hitch systems, offering residential-scale amenities. Snowbird retirees dominate this segment for extended winter destination stays.
Motorhomes sit at the top of the volume ranking, with camper vans climbing the fastest.
Booking Channel:
Channel selection determines customer acquisition economics and fleet utilization predictability, with digital interfaces compressing booking friction while traditional relationships sustain corporate contract stability.
- Online Platforms:Direct-to-consumer interfaces with real-time inventory visibility and dynamic pricing algorithms. Millennials and Gen Z renters in coastal urban markets show steepest adoption curves, with mobile-first booking displacing telephone reservations.
- Direct Rentals:Depot-based transactions with established fleet operators offering walk-in availability and personalized trip planning. Midwest and Mountain West regions retain higher direct rental preference due to lower platform penetration.
- Travel Agencies:Intermediary bookings bundling RV rental with campground reservations and attraction tickets. International inbound tourists to California and Florida sustain this channel despite overall decline.
- Corporate Partnerships:B2B contracts with event management companies, film production units, and disaster relief organizations. Multi-unit fleet commitments provide revenue baselines during leisure demand troughs.
Online platforms command the largest transaction volume, with corporate partnerships delivering the most stable utilization forecasting.
Customer Type:
Customer archetype shapes vehicle selection, trip duration, and ancillary service attachment rates, requiring differentiated fleet positioning and marketing investment.
- Families:Multi-occupant groups prioritizing sleeping capacity and onboard entertainment systems. Peak demand aligns with school holiday calendars, concentrating bookings in summer months and spring break windows.
- Couples:Dual-occupant travelers favoring compact motorhomes or travel trailers with premium finishes. Empty-nesters and honeymoon segments show highest per-night spending on convenience packages.
- Solo Travelers:Individual renters selecting camper vans for cost control and itinerary spontaneity. Digital nomadism sustains mid-week demand outside traditional weekend peaks.
- Adventure Seekers:Activity-focused groups requiring toy hauler configurations or off-grid capability. Mountain biking, rock climbing, and overlanding communities drive specialty vehicle development.
Families generate the highest absolute rental volume, with solo travelers expanding most quickly.
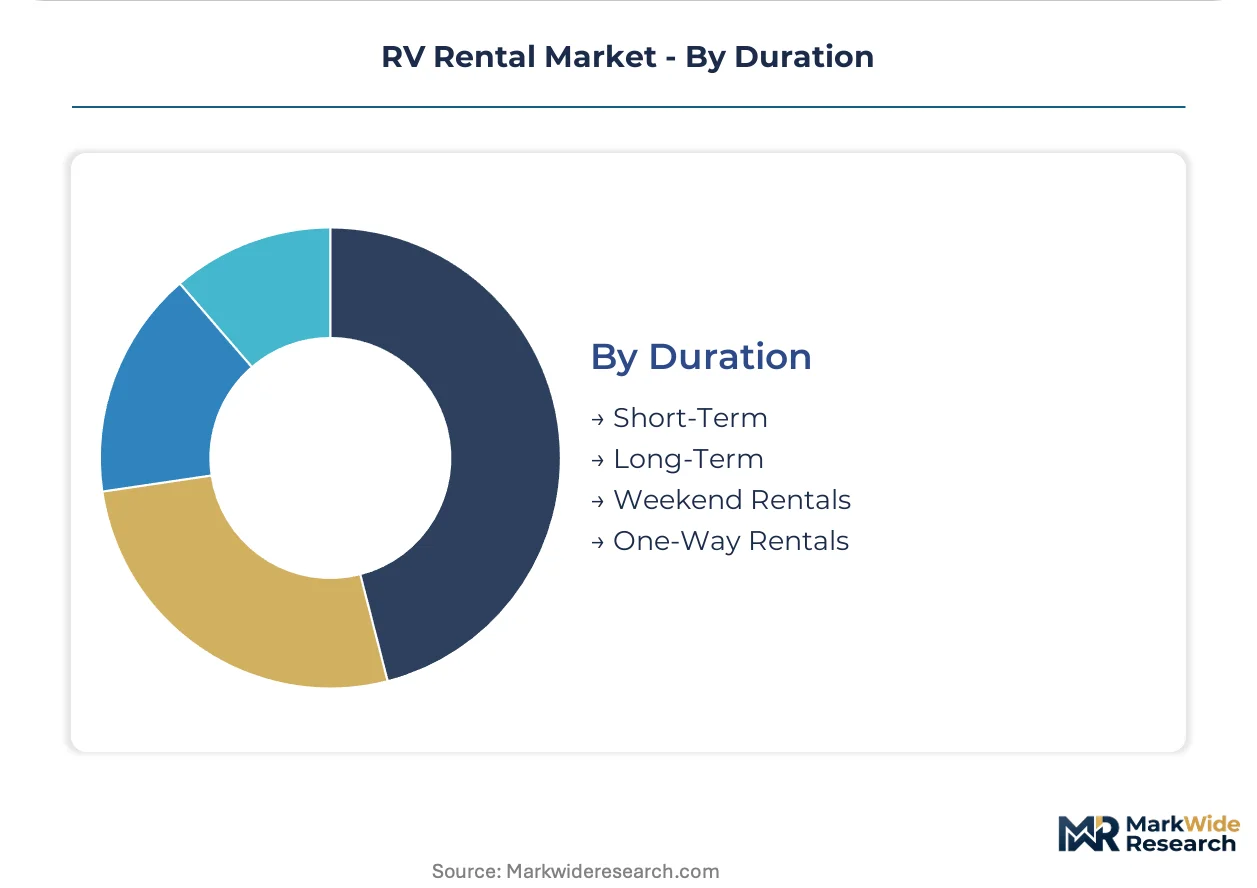
Duration:
Rental length determines fleet turnover economics and revenue recognition patterns, with structural differences between episodic leisure demand and recurring extended-stay contracts.
- Long-Term:Rentals exceeding thirty days, typically by snowbirds relocating seasonally between northern states and Arizona or Florida. Operators secure committed revenue with reduced per-trip preparation costs.
- One-Way Rentals:Point-to-point trips allowing pickup and drop-off at different depots. Migration corridor density between northeastern states and Sun Belt destinations enables viable repositioning economics.
- Short-Term:Rentals under seven days for local recreation and event attendance. High turnover demands intensive vehicle preparation protocols.
- Weekend Rentals:Friday-to-Sunday trips concentrated within 200 miles of urban centers. Saturated competitive dynamics compress margins in major metropolitan markets.
Long-term rentals anchor revenue stability, with one-way rentals gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands substantially larger RV rental transaction volume than Canada, though both markets share snowbird migration corridors that sustain cross-border fleet repositioning economics.
United States
Multi-generational family road trips and remote work flexibility sustain demand across California, Arizona, and Florida. The US DOT's commercial motor vehicle safety standards govern fleet maintenance protocols and operator certification thresholds. Phoenix and Orlando anchor the densest depot networks, capturing fly-and-drive vacationers through airport-adjacent facilities.
Canada
Summer wilderness tourism and international inbound travelers to Banff and Jasper National Parks concentrate rental activity in western provinces. Transport Canada aligns commercial vehicle regulations with US standards to facilitate cross-border fleet circulation. Calgary and Vancouver serve as primary pickup hubs for Rocky Mountain itineraries.
Germany
Domestic camper van culture and Dutch tourist inflows sustain rental density across Bavaria and Baden-Württemberg. The KBA enforces type-approval standards for modified vehicle conversions entering commercial service. Munich and Stuttgart host the largest specialized conversion workshops serving rental fleet procurement.
Australia
Coastal road trip tourism and working holiday visa holders generate consistent demand along the eastern seaboard. The country's national transport regulator mandates heavy vehicle inspection intervals for motorhomes exceeding prescribed weight thresholds. Brisbane and Cairns anchor Queensland's peak-season fleet concentration.
France
Summer migration to Mediterranean coastlines and ski-season alpine access sustain dual-peak utilization patterns. EU type-approval directives govern vehicle modification standards for rental fleet compliance. The Provence-Alpes-Côte d'Azur region concentrates the highest depot density for international tourist pickup.
RV Rental Market Key Industry Players
Top-tier vendors anchor national depot networks, while peer-to-peer marketplace operators fragment supply through distributed owner-participant models. The market exhibits tiered concentration with scale-dependent fleet operators commanding premium positioning and regional specialists occupying service-niche segments. Three archetypes dominate: legacy depot-based renters, digital marketplace platforms, and premium experience curators. Consolidation pressure manifests through geographic expansion and technology licensing arrangements rather than horizontal merger activity.
Within the legacy depot-based tier, Cruise America and El Monte RV exemplify scale-driven national coverage, while Outdoorsy occupies a distinct position as a peer-to-peer marketplace aggregator. These three entities represent the primary competitive anchors shaping pricing architecture and service bundling across the sector.
| Leading Market Players |
|---|
| El Monte RV |
| Goss RV |
| Cruise America |
| Travellers Autobarn |
| Boho Vans |
| Road Bear RV |
| Allstar Coaches |
| Outdoorsy |
| Native Campervans |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap depot operators anchor fleet procurement networks across the southwestern United States, concentrating purchasing power with chassis manufacturers while maintaining pricing discipline through long-term maintenance contracts and seasonal rate premiums.
Pricing Analysis
The bundled-vs-unbundled service split separates full-service motorhome rentals with concierge trip planning from bare-metal camper van transactions where customers self-provision insurance and campground reservations. Pricing stratifies across premium, standard, and economy tiers based on vehicle age and included mileage allowances. Cost compression in the economy tier is intensifying because peer-to-peer platform density fragments traditional depot-based supply structures. Corporate partnership clients show lowest price sensitivity while weekend leisure renters in saturated urban markets exhibit highest elasticity.
Supply Chain Analysis
Reverse-logistics flows for one-way rentals between northeastern states and Arizona-Florida migration corridors create dedicated refurbishment cycles at destination depots, with vehicles undergoing deep cleaning and mechanical inspection before re-entering northern fleets. Chassis sourcing draws from Indiana manufacturing clusters and Mexican assembly plants for compact van conversions. Supply chain risk centers on single-source vulnerability for Class A diesel powertrain components. Distribution runs through airport-adjacent depot networks capturing fly-and-drive vacationers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
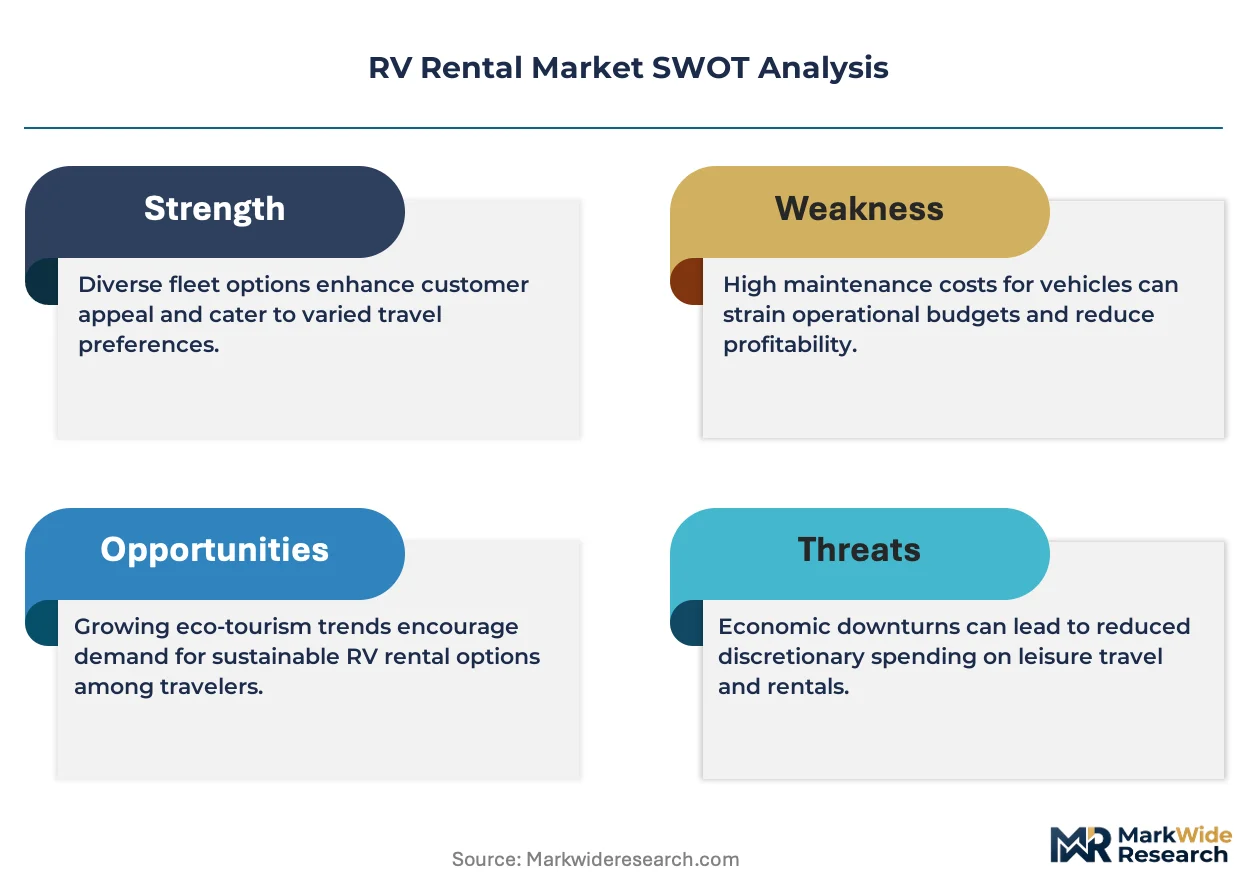
The RV rental market functions as a stable compounder where experiential vacation preference sustains durable demand through economic cycles, with snowbird migration patterns providing predictable utilization baselines.
For Market Incumbents: Cement geographic dominance by accelerating electrification pilot programs aligned with California Air Resources Board mandates, protecting California market access against compliance-driven exits. Deepen captive maintenance capabilities through EPA Section 609 refrigerant handling certification programs, offsetting certified technician scarcity that constrains fleet scaling.
For New Entrants and Emerging Players: Telematics-integrated dynamic pricing platforms offer a technology-first wedge into mid-size regional operators lacking dedicated revenue management teams. Target Pacific Northwest metropolitan corridors where storage constraints suppress personal RV ownership and subscription membership models show steepest adoption curves. Pursue white-label platform licensing to established depot operators seeking yield improvements without internal development costs.
For Investors and Strategic Acquirers: Valuations sit cheapest among long-term destination rental specialists with Arizona-Florida concentration and established snowbird customer relationships. The five-to-ten year viability window hinges on electric RV prototype commercialization timelines and zero-emission mandate penetration rates. Monitor California fleet electrification compliance costs as the primary inflection indicator for capital reallocation across the sector.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric RV Fleet Pilot Program | California Air Resources Board compliance secures market access against regulatory exclusion. |
| Telematics Platform Integration | Dynamic pricing automation captures yield improvements without dedicated revenue teams. |
| Airport Hub Depot Expansion | Phoenix Sky Harbor and Orlando International placement captures fly-and-drive vacationers. |
| Subscription Membership Launch | Annual access passes convert episodic renters into recurring revenue with predictable utilization. |
| Certified Technician Training Program | EPA Section 609 credentials address maintenance workforce scaling constraints. |
Research Approach
Bottom-up fleet utilization modeling reconciled against top-down booking channel tracking forms the analytical core, combining primary interviews with fleet operations directors, revenue management officers, campground association executives, and NHTSA compliance specialists with secondary validation through US DOT commercial motor vehicle safety filings, state DMV regulatory databases, and airport authority concession records.
Input-output matrices map vehicle type demand against seasonal migration patterns, propulsion architecture transitions, and customer archetype evolution across the analysis window. Segmentation dimensions include vehicle class, booking channel, trip duration tier, and regional depot density. CAGRs derive from fleet expansion timelines constrained by chassis availability and certified technician workforce scaling.
The model holds under stable experiential travel preference and remote work normalization; deviation in electric RV commercialization timelines or zero-emission mandate acceleration would shift fleet replacement economics. Practitioners should monitor California Advanced Clean Trucks regulation enforcement patterns and peer-to-peer platform transaction growth rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Short-term Rentals and Vacation Homes
Short-Term Vacation Rental Market
Short-term Rentals and Vacation Homes
Short-Term Rental Platform Market
Short-term Rentals and Vacation Homes
Vacation Ownership Timeshare Market
Short-term Rentals and Vacation Homes
Vacation Rental Website Market
Short-term Rentals and Vacation Homes
Australia Glamping Market
Short-term Rentals and Vacation Homes
Vacation Rentals Market
Short-term Rentals and Vacation Homes
Treehouse Glamping Market
Short-term Rentals and Vacation Homes
North America Glamping Market
Short-term Rentals and Vacation Homes
Vacation Ownership Market
Short-term Rentals and Vacation Homes
Online Home Rental Services Market
Short-term Rentals and Vacation Homes
Asia-Pacific Glamping Market
Short-term Rentals and Vacation Homes
Luxury Vacation Rental Market
Short-term Rentals and Vacation Homes
Europe Glamping Market