
 Greece Tourism Market | 2026-2036
Greece Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Greece Tourism Market Foresight
Traditional printed guidebooks and fixed-package itineraries is shifting toward dynamic, app-driven travel planning in the Greek islands. Ferryhopper leverages its proprietary ferry-routing engine to control inter-island transportation bookings. Greece Insiders specializes in bespoke cultural itineraries that anchor high-margin visitor spending. Smirili Nature Experiences differentiates through eco-certified trekking and marine excursions.
Greece tourism encompasses destination-specific travel services spanning accommodation procurement, gastronomic experiences, entertainment programming, and multimodal transport coordination, typically delivered through digital platforms that aggregate real-time availability across fragmented island suppliers. The primary commercial purpose is to capture and retain visitor expenditure across extended stays in geographically dispersed coastal and island locations. Accommodation and transportation services currently dominate revenue capture, while eco tours represent the fastest-expanding segment as sustainability criteria reshape booking preferences among Northern European source markets. Adventure tours command premium pricing but remain volume-constrained by seasonal weather windows and protected-area access permits.
Greece's Ministry of Tourism enforces star-rating standards for lodging establishments, while EU Green Deal compliance requirements are reshaping energy-efficiency investments in island hotels. The country's national tourism organization coordinates with regional port authorities to manage cruise-ship passenger caps that limit peak-season congestion. Stakeholders must monitor evolving EU-wide sustainability reporting obligations and their spillover effects on small-island supplier certification costs.
Market Dynamics
EU Green Deal compliance requirements are compressing investment timelines for island hotel energy retrofits while simultaneously opening premium rate capture for certified properties. This regulatory pressure layer sits atop existing capacity constraints in the Cyclades ferry network.
Growth Catalysts
- EU Green Deal energy mandates:Island hotels must meet efficiency thresholds to retain operating licenses, accelerating renovation cycles and enabling rate premiums for compliant properties.
- Cyclades visitor concentration:Santorini and Mykonos anchor premium demand flows that subsidize infrastructure investment across secondary islands in the archipelago.
- Heritage cultural tourism:European tour operators are expanding fixed-commitment contracts for archaeology-focused itineraries, reducing revenue volatility for local guides and site managers.
Market Restraints
- Ferry network capacity ceilings:Regional port authorities enforce passenger caps that hard-limit inter-island visitor volumes during peak summer windows.
- Seasonal weather dependency:Adventure tour operators face compressed operating calendars due to protected-area access permit restrictions and winter maritime conditions.
- Small-island supplier certification costs:EU-wide sustainability reporting obligations spill over into disproportionate compliance burdens for family-run accommodations.
Strategic Opportunities
- Peloponnese mainland circuits:Underdeveloped archaeological corridors offer white-space expansion for operators seeking to reduce Cyclades dependency.
- Digital platform aggregation:Real-time inventory systems are penetrating fragmented island supplier networks, enabling dynamic packaging previously impossible.
- Eco-certification tiering:Streamlined sustainability requirements from Greece's National Tourism Organization create faster paths to premium positioning for mid-market properties.
Industry Challenges
- Maritime logistics coordination:Ferry schedule volatility forces accommodation providers to absorb cancellation risk or overbuild buffer inventory.
- Multilingual guide scarcity:Specialized cultural interpretation skills concentrate in Athens and Thessaloniki, leaving island destinations talent-constrained.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Greece Tourism Market |
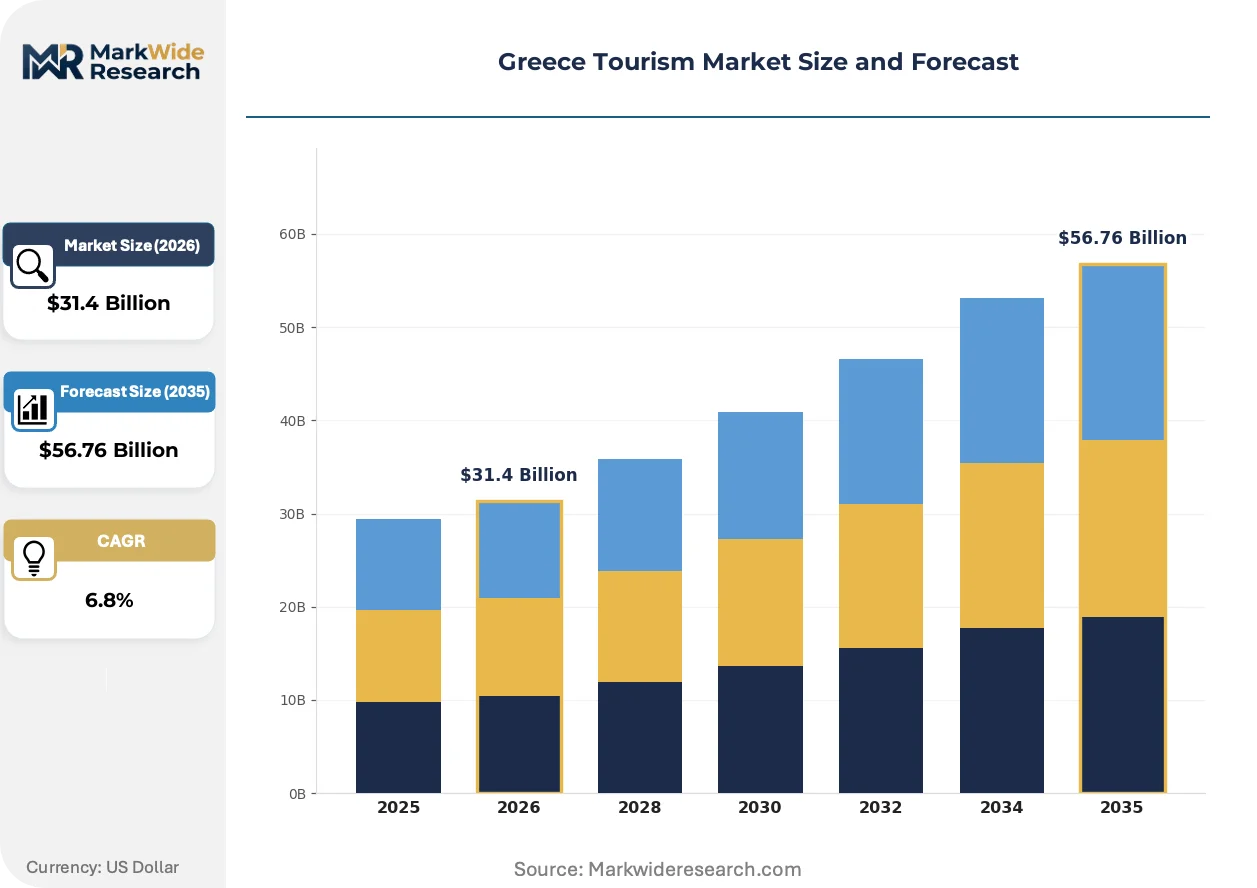
| Market Size in 2026 | $31.4 Billion |
| Market Size in 2035 | $56.76 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Accommodation, Dining, Entertainment, Transportation Tour Type: Cultural Tours, Adventure Tours, Leisure Tours, Eco Tours Customer Type: Families, Couples, Solo Travelers, Business Travelers Seasonality: Summer, Winter, Spring, Autumn |
| Companies Covered | Tourix, Aephoria.net, Ferryhopper, Smirili Nature Experiences, TRIPWAY.GR, TicketSeller.gr, ROOMCASE, Greece Insiders, Meli Tours, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Greece Tourism Market Shifts & Advancements
Digital infrastructure is compressing planning cycles from months to hours while regulatory compliance is becoming a rate-determining variable rather than a cost center. Sustainability credentials are shifting from marketing overlay to booking gate.
Proprietary ferry-routing engines are consolidating control over inter-island transportation bookings. Independent travelers and small-group operators now rely on algorithmic coordination that aggregates real-time seat availability across competing maritime carriers. This technology is compressing the traditional travel agent intermediary layer and capturing margin that previously fragmented across multiple booking touchpoints.
EU Green Deal compliance timelines are forcing accelerated capital deployment into island hotel energy systems. Properties must meet efficiency thresholds to retain operating licenses, with retrofit costs concentrated in HVAC and building envelope upgrades. The Cyclades premium segment is responding fastest, using certification as a rate-justification mechanism against uncertified competitors.
Dynamic itinerary construction is displacing fixed-package bookings among Northern European source markets. Travelers now assemble accommodation, transport, and experience components through app-based platforms that expose real-time pricing volatility. This pattern is most visible in German and Dutch visitor segments, where sustainability criteria increasingly filter initial search results before price comparison occurs.
Greece Tourism Market Segmentation
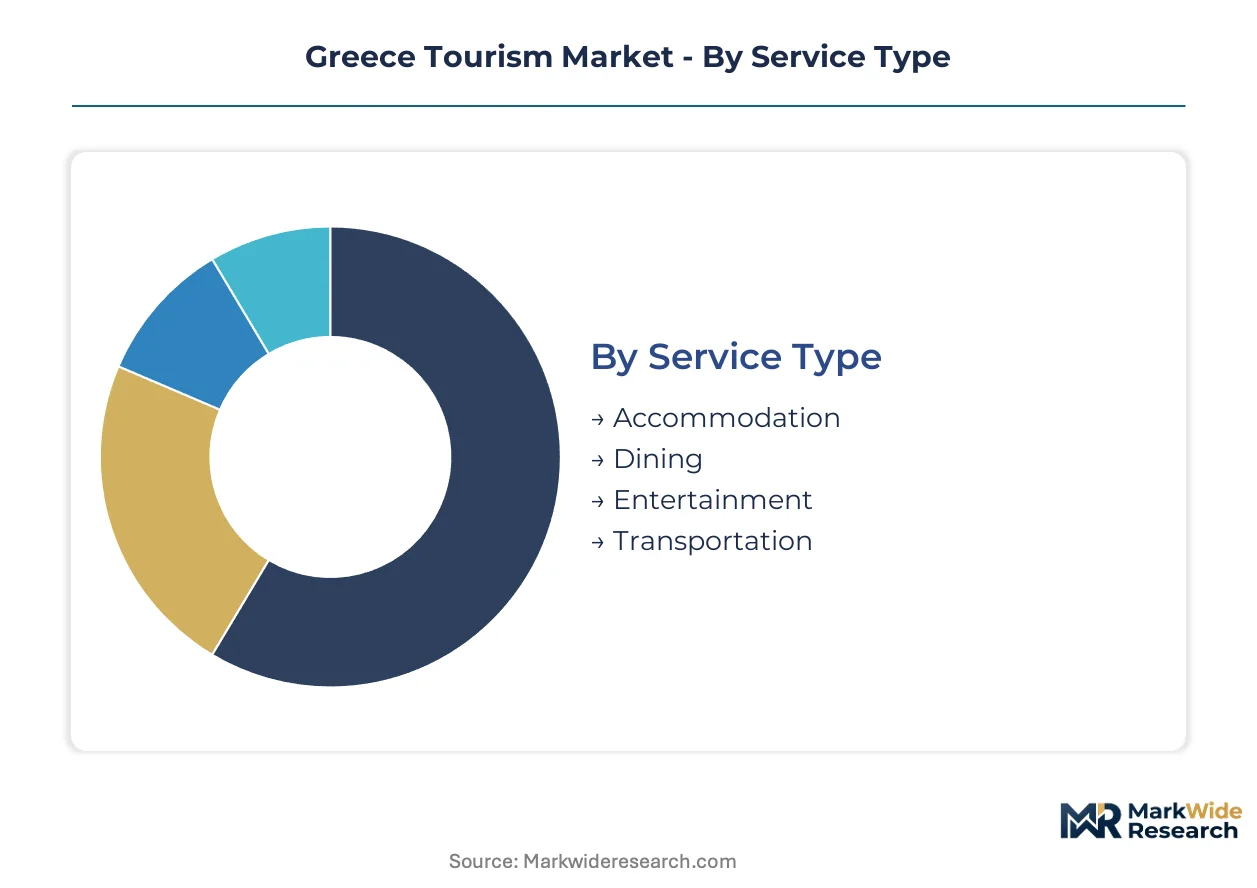
Service type segmentation reveals where visitor expenditure concentrates across fragmented island supply chains. Tour type and customer type dimensions expose margin and volume trade-offs that shape operator positioning strategies.
Service Type:
Upgrade cycles in island hospitality infrastructure are compressing as EU Green Deal mandates force accelerated renovation timelines across Cyclades properties.
- Accommodation:Properties span boutique cave hotels in Santorini to family-run guesthouses on Naxos and Paros. Demand concentrates in certified sustainable properties where EU Green Deal compliance enables rate premiums against uncertified competitors on Mykonos and Santorini.
- Transportation:Ferry networks, domestic aviation, and private yacht charters coordinate multimodal island access. Inter-island ferry bookings dominate volume through proprietary routing engines that aggregate real-time seat availability across competing maritime carriers serving the Cyclades archipelago.
- Dining:Traditional tavernas and fine-dining establishments source from local fisheries and island agriculture.
- Entertainment:Nightlife venues, archaeological site performances, and marina events program visitor evenings.
Transportation sits at the top of the volume ranking, with accommodation climbing the fastest as certification requirements reshape competitive positioning.
Tour Type:
Cost tier stratification separates premium archaeological itineraries from mass-market leisure packages across Greek island circuits.
- Cultural Tours:Archaeology-focused itineraries anchor high-margin visitor spending at Delphi, Knossos, and Acropolis sites. European tour operators are expanding fixed-commitment contracts for these programs, reducing revenue volatility for local guides and site managers operating under Ministry of Culture licensing.
- Eco Tours:Eco-certified trekking and marine excursions differentiate through sustainability credentials that Northern European source markets filter before price comparison. Greece's National Tourism Organization has streamlined certification requirements, creating faster paths to premium positioning for mid-market properties seeking eco-label status.
- Adventure Tours:Rock climbing, diving, and sailing operations face compressed operating calendars due to seasonal weather windows.
- Leisure Tours:Beach-focused packages concentrate volume in July-August peak windows.
Leisure tours sit at the top of the volume ranking, with eco tours gaining share fastest as sustainability criteria reshape booking preferences.
Customer Type:
Application-based segmentation maps distinct service requirements across family multi-generational travel, romantic getaway programming, independent exploration, and corporate retreat logistics.
- Couples:Honeymoon and anniversary travelers command premium rate capture in Santorini caldera-view suites and Mykonos boutique properties. This segment concentrates discretionary spending on private yacht charters and fine-dining experiences that subsidize infrastructure investment across secondary islands.
- Families:Multi-generational groups require interconnected room configurations, child-safe amenities, and activity programming that spans age ranges. Demand concentrates in Crete and Rhodes where larger resort properties offer dedicated kids' clubs and shallow-water beach access.
- Solo Travelers:Independent explorers utilize app-driven itinerary construction that aggregates real-time availability across fragmented island suppliers.
- Business Travelers:Corporate retreat and conference demand concentrates in Athens and Thessaloniki with limited island penetration.
Couples sit at the top of the volume ranking, with solo travelers climbing the fastest as digital platform penetration enables dynamic, self-assembled itineraries.
Seasonality:
Supply concentration patterns dictate pricing power across compressed operating calendars in island destinations.
- Summer:Peak demand from June through August saturates Cyclades ferry capacity and triggers cruise-ship passenger caps enforced by regional port authorities. Properties capture annual revenue targets within this twelve-week window, forcing overbuilding of buffer inventory to absorb maritime schedule volatility.
- Spring:Shoulder-season cultural tourism expands as archaeological site access improves and wildflower trekking conditions peak on Crete and Peloponnese mainland circuits. European tour operators advance-book fixed-commitment contracts during this period to secure guide availability before summer competition intensifies.
- Autumn:Wine harvest programming and reduced-rate yacht charters attract repeat visitors.
- Winter:Urban concentration in Athens and Thessaloniki dominates as island ferry schedules contract sharply.
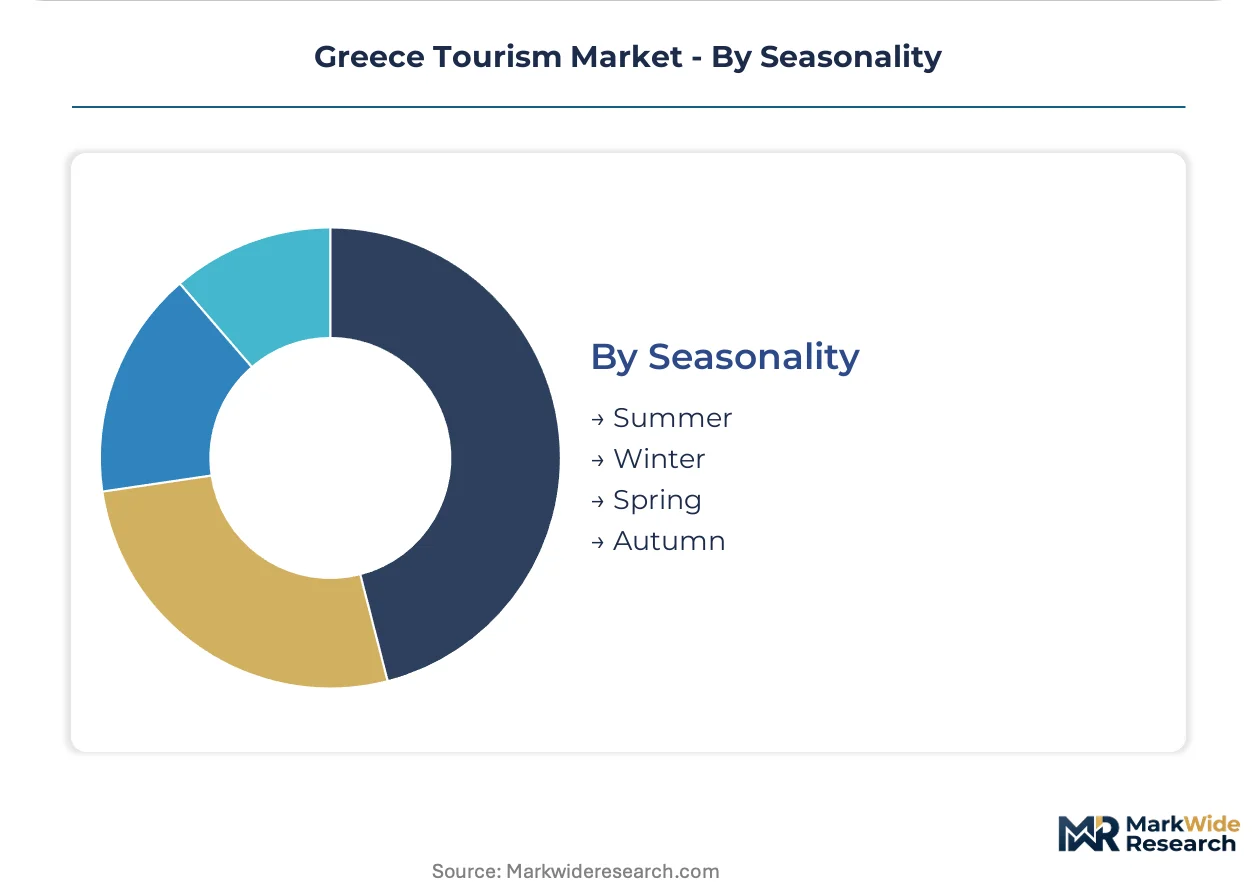
Summer sits at the top of the volume ranking, with spring climbing the fastest as heritage-focused itineraries extend booking windows earlier into the calendar.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cyclades archipelago anchors visitor flows across the Greek islands, with Santorini and Mykonos commanding premium rate capture that subsidizes infrastructure investment throughout the region.
Cyclades Islands
Caldera-view suites in Santorini and boutique properties in Mykonos drive discretionary spending on private yacht charters and fine-dining experiences. EU Green Deal compliance requirements from the European Commission mandate energy-efficiency retrofits for operating licenses. Ferryhopper's proprietary routing engine consolidates inter-island transportation bookings across competing maritime carriers serving this archipelago.
Crete
Multi-generational family groups concentrate demand for interconnected room configurations and dedicated kids' clubs at larger resort properties. Greece's Ministry of Tourism enforces star-rating standards that shape competitive positioning across Heraklion and Chania coastal zones. The island's shallow-water beach access and wildflower trekking conditions extend visitor seasons beyond peak summer windows.
Peloponnese Mainland
Underdeveloped archaeological corridors at Delphi and Epidaurus offer white-space expansion for operators reducing Cyclades dependency. Regional development programs from the Greek national tourism organization coordinate infrastructure investment across Nafplio and Kalamata access points. Heritage-focused itineraries from European tour operators advance-book fixed-commitment contracts during spring shoulder seasons.
Ionian Islands
Corfu and Zakynthos capture repeat visitors through wine harvest programming and reduced-rate yacht charters during autumn months. The Hellenic Ministry of Maritime Affairs and Insular Policy manages port authority coordination for cruise-ship passenger caps. Family-run accommodations across Kefalonia face disproportionate compliance burdens from EU-wide sustainability reporting obligations.
Athens Metropolitan Area
Corporate retreat and conference demand concentrates in Athens hotels with limited island penetration during winter ferry schedule contractions. The Greek Ministry of Culture licenses specialized interpretation guides whose skills concentrate in the capital. Acropolis site performances and urban gastronomic experiences program visitor evenings before island extensions.
Greece Tourism Market Competitive Landscape
Platform aggregation dominates the current landscape as digital inventory systems penetrate fragmented island supplier networks. The vendor base splits between ferry-routing technology specialists, bespoke itinerary designers, and eco-certified experience operators. Three archetypes define positioning: proprietary algorithm developers, high-margin cultural curators, and sustainability credential aggregators. M&A activity remains limited while strategic partnerships between maritime carriers and accommodation platforms accelerate.
Within the technology-enabled tier, Ferryhopper exemplifies proprietary routing engine development, while Greece Insiders occupies a position as a bespoke cultural itinerary specialist. Smirili Nature Experiences anchors the eco-certification vector, representing sustainability-focused marine and trekking excursion providers. These three companies illustrate how competitive positioning stratifies across transportation control, high-margin visitor spending capture, and premium eco-label differentiation.
| Leading Market Players |
|---|
| Tourix |
| Aephoria.net |
| Ferryhopper |
| Smirili Nature Experiences |
| TRIPWAY.GR |
| TicketSeller.gr |
| ROOMCASE |
| Greece Insiders |
| Meli Tours |
| Others |
Supply & Pricing Matrix
Proprietary ferry-routing engines are compressing booking margins across Greek island transportation while simultaneously concentrating supplier control in platform operators. This technology shift simultaneously reduces fragmentation costs for travelers and eliminates intermediary markups that previously sustained small-island travel agents.
Pricing Analysis
Input-cost pass-through from EU Green Deal compliance mandates is intensifying across Cyclades accommodation tiers. Three-tier pricing structure across certified sustainable, standard-rated, and uncertified properties dominates Santorini and Mykonos, where certification grade and caldera-view positioning drive differentiation. Pricing pressure stems from accelerated HVAC retrofit timelines that properties must absorb or pass to rate cards. Independent travelers booking through app-based platforms exhibit highest price sensitivity, while couples on honeymoon itineraries show lowest elasticity.
Supply Chain Analysis
Reverse-logistics flows for seasonal equipment repositioning—yacht fleet migration, temporary venue infrastructure, and guided tour assets—create coordination complexity across the Aegean maritime network. Supply concentration rests on Greece, Italy, and Turkey for ferry vessel maintenance and crew provisioning. Raw material dependencies include marine fuel bunkering, hospitality linens and amenities, and specialized archaeological interpretation equipment. Single-source vulnerability runs through Athens-based multilingual guide talent pools. Distribution runs through proprietary digital platforms that aggregate fragmented island supplier inventory into dynamic packaging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Greece tourism operates as a regulatory compounder where EU Green Deal energy mandates are accelerating capital deployment into certified properties and reshaping competitive tiers.
For Market Incumbents: Anchor rate premiums through accelerated sustainability certification completion before compliance deadlines tighten. Defend positioning by securing fixed-commitment contracts with European tour operators for archaeology-focused itineraries, reducing revenue volatility against maritime logistics disruption. Deepen backward integration into ferry capacity allocation through strategic partnerships with maritime carriers. For New Entrants and Emerging Players: Enter via Peloponnese mainland archaeological corridors where white-space expansion opportunities exceed Cyclades saturation. Target underdeveloped heritage circuits at Delphi and Epidaurus with bespoke cultural programming that captures high-margin visitor spending. Deploy direct-to-traveler app-based platforms that bypass established intermediary layers. For Investors and Strategic Acquirers: Roll-up economics work for eco-certified experience operators because fragmented family-run accommodations face disproportionate EU sustainability reporting burdens that favor scaled compliance platforms. Long-term viability hinges on properties achieving certification tiers that gate premium rate capture. Monitor ferry network capacity allocation decisions by regional port authorities as inflection indicators for inter-island volume constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Sustainability Certification Fast-Track | EU Green Deal compliance deadlines from the European Commission accelerate renovation cycles and enable rate premiums against uncertified competitors. |
| Ferry Capacity Partnership | Proprietary routing engine integration with maritime carriers consolidates inter-island transportation control and captures previously fragmented margins. |
| Peloponnese Circuit Development | Underdeveloped archaeological corridors at Delphi reduce Cyclades dependency and extend operating calendars beyond peak summer windows. |
| Dynamic Platform Aggregation | Real-time inventory systems penetrate fragmented island supplier networks and enable self-assembled itinerary construction for independent travelers. |
| Heritage Guide Talent Pipeline | Specialized cultural interpretation skills concentrated in Athens create acquisition targets for operators seeking to secure scarce multilingual capabilities. |
Research Methodology
Direct dialogue with ferry operators, island hotel proprietors, archaeological site managers, and European tour operator procurement leads grounded qualitative findings in operational reality. Primary insights combined with secondary validation from EU Green Deal implementation documents, Hellenic Ministry of Tourism star-rating databases, and regional port authority passenger cap records. Bottom-up accommodation inventory analysis triangulated against top-down visitor expenditure flows from national tourism organization statistics.
Segmentation outputs across service type, tour type, customer application, and seasonal demand patterns calibrated growth projections across the modeling period. CAGRs derived from historical visitor volume trajectories, infrastructure investment pipelines, and regulatory compliance timeline impacts. Forecast inputs incorporated ferry network capacity constraints, EU energy mandate phase-in schedules, and Northern European source market sustainability preference shifts.
Inputs from maritime carrier scheduling systems and island accommodation reservation platforms were available through the study window; gaps in real-time small-island supplier financial performance introduce uncertainty bands around secondary property investment forecasts. Practitioners should monitor EU-wide sustainability reporting obligation expansions and regional port authority cruise-ship cap adjustments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Camping and Caravanning Market
Travel and Tourism
Cycle Tourism Market
Travel and Tourism
India Sports Tourism Market
Travel and Tourism
India Travel Retail Market
Travel and Tourism
Yacht Charter Service Market
Travel and Tourism
B2B Travel Market
Travel and Tourism
Travel Retail Market
Travel and Tourism
Yacht Charter Market
Travel and Tourism
Luxury Travel Market
Travel and Tourism
Global Enotourism Market
Travel and Tourism
Canada Travel and Tourism Market
Travel and Tourism
India Outbound Tourism Market
Travel and Tourism
Europe Driving Vacation Market
Travel and Tourism
Travel and Tourism Market
Travel and Tourism
North America Driving Vacation Market
Travel and Tourism
Halal Tourism Market