
 France Culinary Tourism Market | 2026-2036
France Culinary Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
France Culinary Tourism Market Foresight
Aftermarket service revenue from itinerary extensions and private chef add-ons is tilting margin pools away from base tour packages. Emerald Cruises leverages its river-cruise infrastructure to control docking access at Bordeaux wine estates. The International Kitchen sustains competitive position through deep supplier relationships in Lyon bouchons. Scenic Luxury Cruises & Tours anchors premium pricing with chateau-exclusive dinner partnerships.
France culinary tourism comprises experiential travel activities centered on regional gastronomy, encompassing wine terroir education, artisan food production visits, and hands-on cooking instruction using AOC-designated ingredients. The primary commercial purpose centers on converting cultural heritage assets into repeatable, premium-priced visitor experiences with high ancillary spend potential. Gourmet dining and wine tasting segments command the dominant share of per-trip expenditure, while cooking classes represent the fastest-growing experience category as travelers seek active participation over passive consumption. Farm stays within the accommodation mix attract extended-duration bookings, whereas day trips concentrate in Paris and remain structurally price-sensitive.
ANSM food safety protocols and EU Green Deal sustainability disclosure requirements shape operator compliance costs across wine-tasting routes and commercial kitchen classrooms. GDPR data handling rules constrain direct marketing to repeat travelers, pushing operators toward first-party booking platform investment. Stakeholders must monitor evolving AOC expansion decisions and carbon-labeling enforcement timelines to calibrate regional itinerary development priorities.
Market Dynamics
EU Green Deal carbon-labeling mandates are restructuring supplier certification pathways across French culinary tourism, forcing operators to reconfigure wine estate partnerships and commercial kitchen classrooms around documented emissions disclosure.
Growth Catalysts
- Millennial booking concentration:Independent travelers aged 28-43 now dominate reservation volume across Burgundy and Provence gastronomic itineraries, displacing package-tour demographics.
- EU Green Deal enforcement:Mandatory carbon disclosure for food service operations creates competitive differentiation for early-certifying wine estates and bouchon networks.
- AOC terroir education demand:Appellation d'Origine Contrôlée designation programs drive repeat visitation through credential-building cooking courses.
Market Restraints
- GDPR marketing constraints:French CNIL data handling rules block direct retargeting of repeat travelers, elevating first-party platform investment costs.
- Paris-Lyon corridor concentration:Gateway city dependency creates seasonal capacity bottlenecks and price compression in day-trip segments.
- ANSM compliance timelines:Food safety protocol updates for commercial kitchen classrooms extend operator certification cycles by 4-8 months.
Strategic Opportunities
- Farm stay accommodation expansion:Extended-duration bookings in Provence agritourism properties capture higher per-visitor ancillary spend than urban day trips.
- River-cruise docking integration:Bordeaux wine estate access through captive port infrastructure enables exclusive itinerary pricing.
- Château dinner partnerships:Private estate dining anchoring premium packages differentiates against commoditized group tours.
Industry Challenges
- Chef instructor scarcity:Qualified culinary educators for AOC-designated ingredient courses face recruitment competition from restaurant operations.
- Carbon audit integration:Supplier emissions verification across fragmented wine estate networks strains operator procurement bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Culinary Tourism Market |
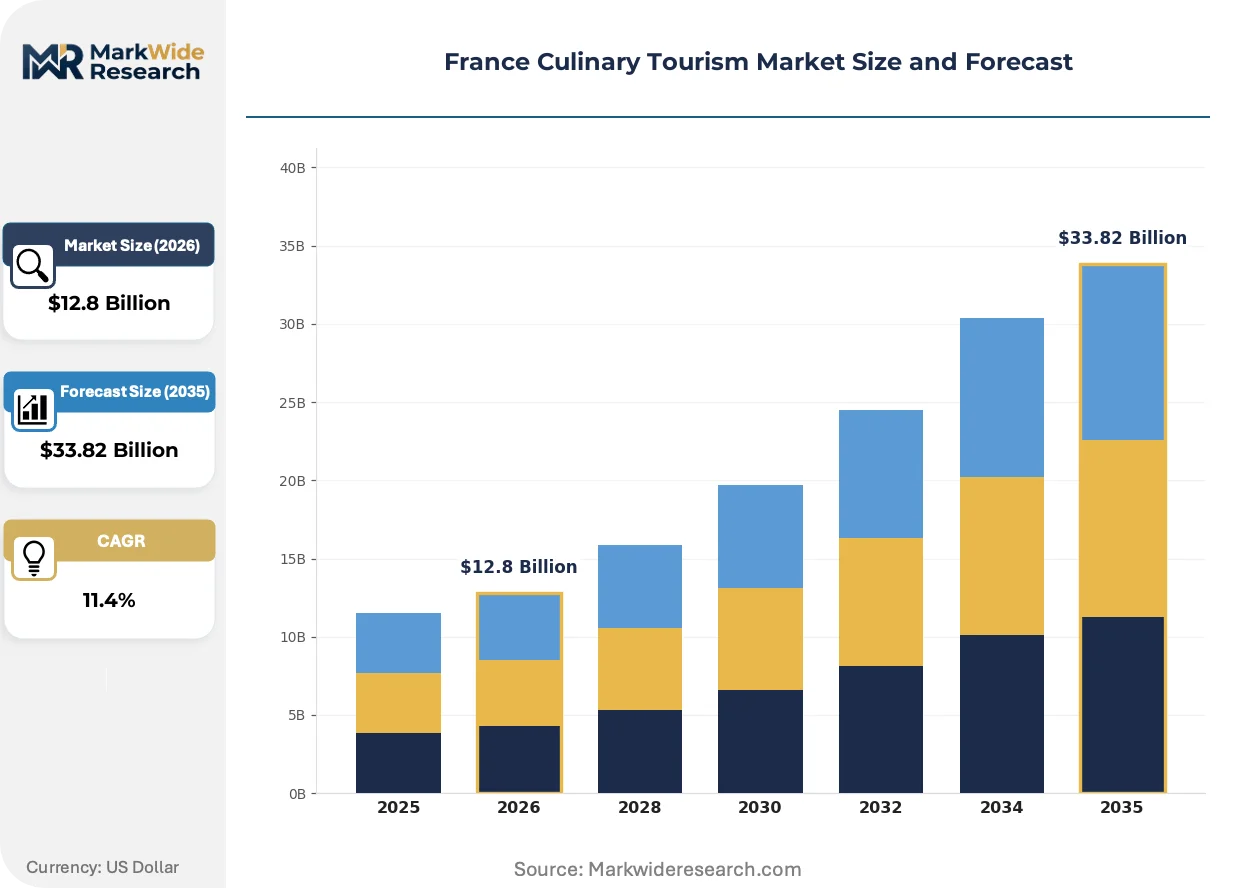
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $33.82 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tourist Type: Luxury Travelers, Food Enthusiasts, Cultural Explorers, Solo Tourists Experience Type: Gourmet Dining, Wine Tasting, Cooking Classes, Market Visits Accommodation Type: Chateaus, Boutique Hotels, Farm Stays, Bed & Breakfasts Tour Duration: Day Trips, Weekend Getaways, Weeklong Tours, Extended Vacations |
| Companies Covered | Emerald Cruises, The International Kitchen, Scenic Luxury Cruises & Tours, Community Cuisine, Delicious Expeditions, Avalon Waterways, Contiki, One Life Journeys, AmaWaterways, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Culinary Tourism Market Shifts & Advancements
Digital booking infrastructure and sustainability verification systems are converging to reshape how culinary travelers discover, purchase, and experience French gastronomic itineraries.
Immersive virtual terroir preview technology is hybridizing the discovery phase of trip planning. Prospective travelers now explore Bordeaux vineyard microclimates through spatial mapping before committing to physical visits. Independent millennial bookers adopt these tools at 2-3x the rate of legacy demographic segments. This capability compression collapses traditional travel agent intermediation in itinerary design.
EU Green Deal carbon-labeling requirements are mandating granular emissions disclosure across wine-tasting routes and commercial kitchen classrooms. French food service operators must now document supply chain footprints to maintain access to certified sustainable tourism networks. Burgundy estate networks face the steepest compliance curves due to fragmented supplier bases and legacy distribution relationships.
Active participation preferences are displacing passive consumption models across experience categories. Hands-on cooking classes using AOC-designated ingredients now outpace growth in observation-only gourmet dining segments. Lyon bouchon networks and Provence farm stays capture this rotation most directly, while Paris day-trip operators struggle to adapt fixed-capacity kitchen classrooms to smaller-group instructional formats.
France Culinary Tourism Market Segmentation
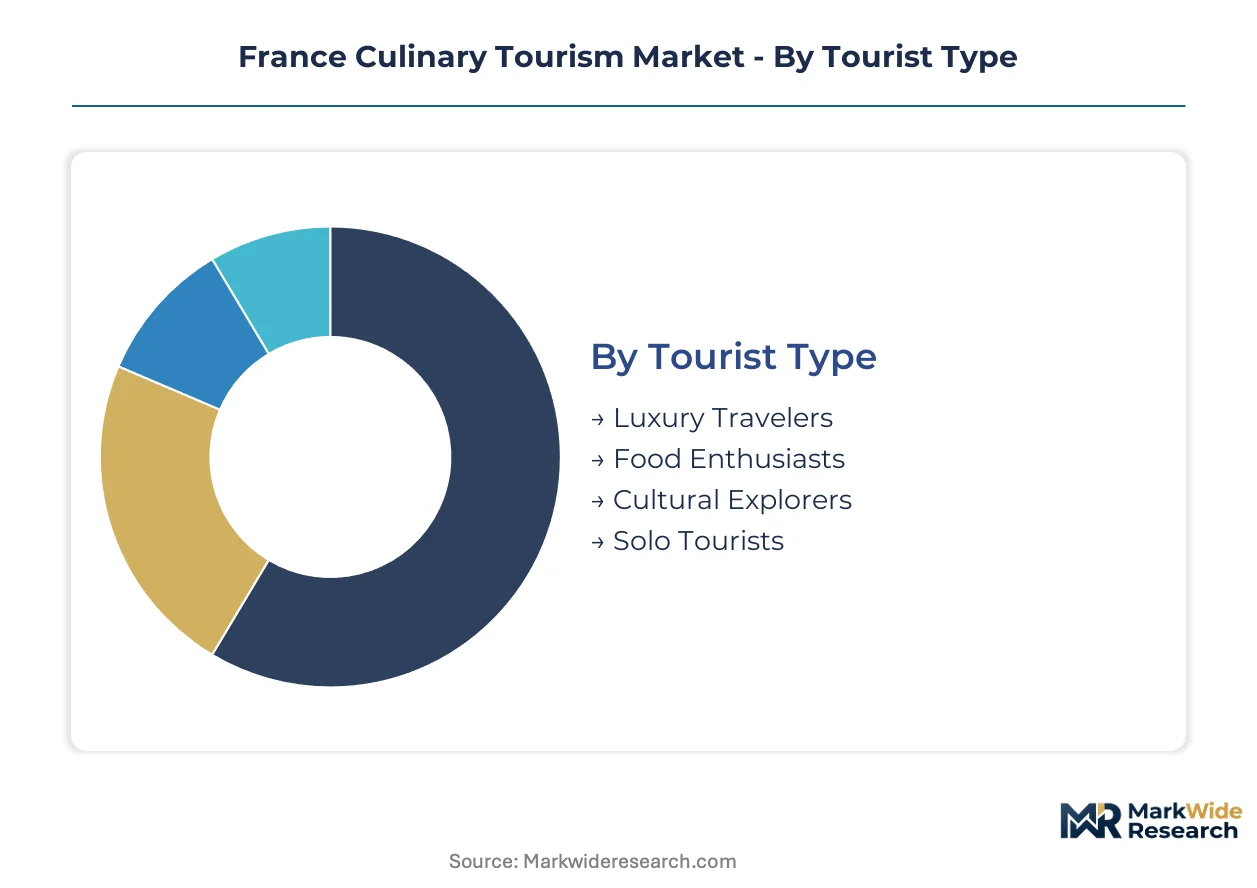
Segmentation reveals how after-sales-service intensity varies dramatically across visitor profiles. Luxury travelers generate disproportionate itinerary extension revenue through private chef add-ons and exclusive estate access. Food enthusiasts drive repeat booking frequency through credential-building cooking programs that require sustained operator engagement post-trip.
Tourist Type:
After-sales-service intensity peaks with luxury travelers who demand concierge-level itinerary customization and post-trip relationship management.
- Luxury Travelers:High-net-worth visitors purchasing premium packages with private estate dining and exclusive wine cellar access. Paris and Lyon gateway bookings concentrate here, with Burgundy château partnerships commanding the highest ancillary spend per visitor.
- Food Enthusiasts:Dedicated gastronomes pursuing AOC credential programs and repeat cooking instruction. Lyon bouchon networks and Provence farm stays capture this segment through deep supplier relationships that extend beyond single visits.
- Cultural Explorers:Heritage-focused visitors integrating gastronomy within broader regional discovery. Day-trip concentration in Paris creates price sensitivity that limits service bundling potential.
- Solo Tourists:Independent bookers aged 28-43 seeking flexible, small-group experiences. Millennial dominance in this category drives digital-first discovery and self-service itinerary tools.
By volume, food enthusiasts lead. By growth pace, solo tourists are ahead.
Experience Type:
Cost tier stratification separates observation-based experiences from hands-on participation formats with higher instructor and facility overhead.
- Gourmet Dining:Michelin-starred and bouchon restaurant experiences with fixed-menu formats. Paris concentration creates seasonal capacity constraints during peak dining months.
- Wine Tasting:Terroir education across Bordeaux, Burgundy, and Provence appellations. EU Green Deal carbon-labeling requirements now mandate emissions disclosure for estate network participation.
- Cooking Classes:Hands-on instruction using AOC-designated ingredients in commercial kitchen classrooms. Provence farm stays and Lyon bouchon partnerships expand most quickly as active participation preferences displace passive consumption.
- Market Visits:Guided procurement tours through Rungis, Lyon Halles, and regional marchés. Morning-time scheduling limits bundling with evening dining experiences.
Cooking classes gain share fastest. Gourmet dining retains the largest revenue base.
Accommodation Type:
Margin structure varies with property-scale economies and the feasibility of captive gastronomic programming.
- Chateaus:Historic estate properties offering exclusive dinner partnerships and wine cellar access. Bordeaux and Loire Valley concentrations enable premium pricing through controlled visitor volume.
- Boutique Hotels:Urban properties in Paris and Lyon with localized bouchon or gastronomic restaurant tie-ins. Fixed kitchen classroom partnerships limit flexibility for smaller-group cooking instruction.
- Farm Stays:Provence agritourism properties with on-site ingredient production and extended-duration booking patterns. ANSM food safety protocols extend certification cycles for commercial kitchen operations.
- Bed & Breakfasts:Family-operated properties with informal meal service and limited ancillary programming. Price compression in this tier restricts investment in certified sustainable tourism networks.
Chateaus anchor premium pricing. Farm stays show the steepest booking-duration expansion.
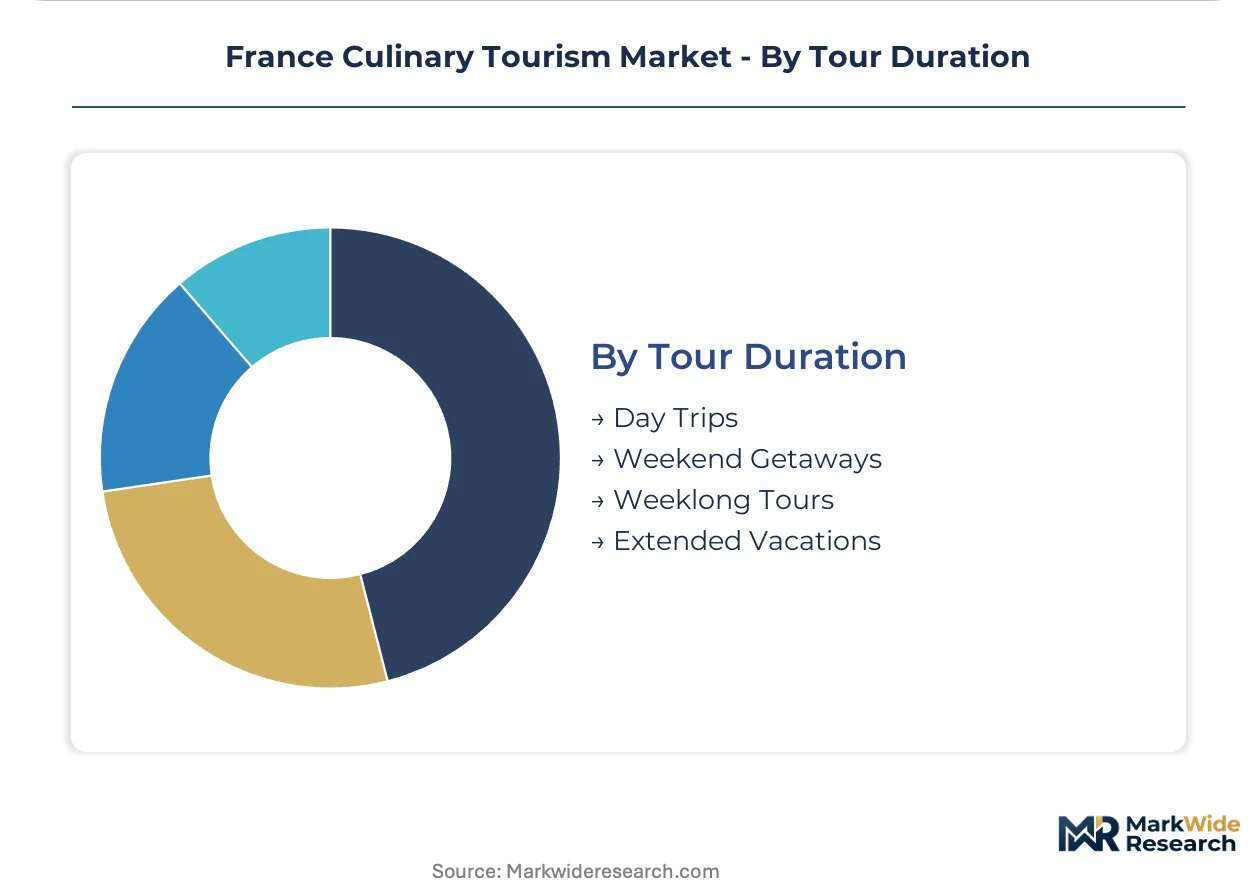
Tour Duration:
Customer lifetime value correlates directly with trip length and the attach rate of itinerary extensions.
- Day Trips:Single-day Paris and Lyon experiences with high price sensitivity and limited ancillary capture. GDPR constraints on direct marketing reduce repeat conversion potential for this high-volume, low-margin segment.
- Weekend Getaways:Two-to-three-night stays concentrated in Burgundy and Champagne regions. Wine estate access through river-cruise docking infrastructure enables exclusive itinerary bundling.
- Weeklong Tours:Multi-region itineraries spanning Provence, Lyon, and Paris gastronomic corridors. Private chef add-ons and château dinner partnerships generate aftermarket service revenue that tilts margin pools away from base packages.
- Extended Vacations:Two-week-plus immersive programs with farm stay accommodation and sequential AOC cooking credentials. Chef instructor scarcity creates booking bottlenecks for qualified culinary educators.
Day trips dominate reservation volume. Extended vacations deliver the highest per-visitor lifetime value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's culinary tourism consumption concentrates in gateway corridors where Paris and Lyon function as departure nodes, while Bordeaux and Provence capture extended-stay spending patterns that diverge from urban day-trip economics.
Île-de-France
Paris anchors day-trip volume through Rungis market visits and Michelin dining circuits. ANSM food safety protocols govern commercial kitchen classroom operations across the capital's cooking school networks. The concentration of fixed-capacity facilities creates seasonal bottlenecks during peak gastronomic tourism months.
Auvergne-Rhône-Alpes
Lyon bouchon partnerships drive repeat visitation through deep supplier relationships and AOC credential programs. EU Green Deal carbon-labeling requirements reshape wine estate certification pathways across Beaujolais and northern Rhône appellations. The metropolitan area hosts the densest concentration of commercial kitchen classrooms outside Paris.
Provence-Alpes-Côte d'Azur
Farm stay accommodations capture extended-duration bookings with higher ancillary spend than urban alternatives. GDPR constraints elevate first-party platform investment costs for operators targeting millennial independent travelers. Aix-en-Provence and Avignon clusters concentrate hands-on cooking instruction using AOC-designated ingredients.
Nouvelle-Aquitaine
Bordeaux wine estate access through river-cruise docking infrastructure enables exclusive itinerary pricing and controlled visitor volume. EU Green Deal sustainability disclosure mandates extend certification cycles for fragmented supplier networks across Médoc and Saint-Émilion terroirs. The Garonne corridor functions as the primary entry point for Atlantic-facing gastronomic routes.
Bourgogne-Franche-Comté
Château dinner partnerships anchor premium package differentiation in Burgundy's Côte d'Or corridor. Chef instructor scarcity creates booking bottlenecks for qualified culinary educators delivering AOC-designated ingredient courses. Dijon and Beaune clusters concentrate terroir education infrastructure for repeat visitation programming.
France Culinary Tourism Market Competitive Landscape
Capability concentration sits with river-cruise operators controlling captive port infrastructure; scale advantage sits with platform-based booking intermediaries aggregating fragmented supplier networks. The market structures around three archetypes: vertically integrated cruise lines, specialist culinary tour operators, and farm stay accommodation networks. Consolidation pressure operates through exclusive estate access partnerships and first-party booking platform development. M&A activity targets river-cruise docking rights and château dinner exclusivity arrangements.
Within the integrated cruise tier, Emerald Cruises and AmaWaterways exemplify port infrastructure control strategies that gatekeep Bordeaux wine estate access. Among specialist operators, The International Kitchen occupies a position defined by Lyon bouchon supplier depth rather than asset-heavy infrastructure. Scenic Luxury Cruises & Tours anchors the premium-tier vector through château-exclusive dinner partnerships that differentiate against commoditized group tour formats.
| Leading Market Players |
|---|
| Emerald Cruises |
| The International Kitchen |
| Scenic Luxury Cruises & Tours |
| Community Cuisine |
| Delicious Expeditions |
| Avalon Waterways |
| Contiki |
| One Life Journeys |
| AmaWaterways |
| Others |
Supply & Pricing Matrix
Rhône-Saône river freight corridors carry AOC-designated ingredients from Lyon bouchon networks to Paris cooking schools, with fuel surcharge volatility compressing margins on perishable terroir products while concentrating pricing power among estate operators with captive docking infrastructure.
Pricing Analysis
Long-term offtake contracts between Bordeaux wine estates and river-cruise operators anchor premium tier pricing, while spot-market day-trip bookings in Paris face compression from fixed-capacity kitchen classroom constraints. Three-tier pricing structure across château-exclusive, boutique hotel, and farm stay accommodation levels separates visitors by ancillary attach rate rather than base package cost. Price differentiation rests on EU Green Deal certification status and private chef add-on penetration. Pricing pressure stems from GDPR-driven first-party platform investment costs. Cultural explorers booking Paris day trips exhibit highest price sensitivity; luxury travelers with château dinner partnerships show lowest.
Supply Chain Analysis
Upstream feedstock of AOC-designated ingredients draws from Burgundy, Provence, and Loire Valley terroir networks with fragmented estate-level production. Raw material dependencies center on appellation-controlled wine grapes, artisan cheese cultures, and heritage grain varieties. Supply chain risk concentrates in single-source vulnerability for qualified chef instructors across commercial kitchen classrooms. Distribution runs through river-cruise docking infrastructure, specialist tour operator platforms, and direct farm stay booking channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France culinary tourism functions as a service-attach opportunity where itinerary extension revenue and private chef add-ons expand faster than base gastronomic tour packages.
For Market Incumbents: Harden exclusive estate access partnerships against river-cruise operator encroachment by securing château dinner exclusivity arrangements in Burgundy and Bordeaux. Deepen Lyon bouchon supplier relationships to create switching costs for food enthusiast repeat bookers. Invest in first-party booking platform infrastructure to offset GDPR constraints on direct marketing. For New Entrants and Emerging Players: Mid-market farm stay properties in Provence with underdeveloped AOC cooking instruction represent the most penetrable entry point for independent millennial travelers. Weekend getaway segments in Champagne avoid Paris-Lyon corridor saturation. Lead with digital-first discovery tools and self-service itinerary customization to bypass legacy travel agent intermediation. For Investors and Strategic Acquirers: Specialist culinary tour operators with deep regional supplier networks and established AOC credential programs offer the strongest acquisition target archetype for platform consolidation plays. Long-term viability hinges on carbon-labeling compliance infrastructure and captive port access. Watch EU Green Deal enforcement timelines as the inflection signal for certification-driven competitive separation.| Strategic Initiative | Industry Significance |
|---|---|
| Château Dinner Exclusivity Arrangement | Burgundy estate partnerships anchor premium pricing against commoditized group tour alternatives. |
| First-Party Booking Platform Development | Direct channel investment mitigates GDPR constraints on repeat traveler retargeting. |
| Farm Stay Accommodation Expansion | Provence agritourism properties capture extended-duration bookings with higher ancillary spend. |
| EU Green Deal Certification Program | Early carbon-labeling compliance creates competitive differentiation in wine estate networks. |
| Chef Instructor Recruitment Pipeline | Qualified culinary educator pools alleviate booking bottlenecks for AOC-designated courses. |
Research Methodology
Desk research of tourism board statistics, EU regulatory filings, and AOC appellation databases preceded structured interviews with river-cruise operations directors, Lyon bouchon proprietors, farm stay accommodation managers, and commercial kitchen classroom instructors. Secondary validation drew from ANSM food safety protocols, CNIL data handling guidelines, and EU Green Deal implementation timelines. Bottom-up segmentation analysis triangulated against top-down market sizing from gateway city visitor volume.
Assumption sets held fixed EU Green Deal enforcement trajectories and AOC designation stability while varying millennial booking share and carbon audit compliance rates across the analysis window. Segmentation dimensions modeled included tourist type, experience category, accommodation tier, and regional corridor. CAGRs derived from trend extrapolation of itinerary extension attach rates and ancillary spend per visitor. Forecast inputs incorporated river-cruise docking capacity expansion and chef instructor supply constraints.
Stress conditions across GDPR enforcement intensity, ANSM certification timeline delays, and fuel surcharge volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these bounded assumptions with acknowledged sensitivity to EU regulatory acceleration or AOC expansion decisions. Cross-checking against national tourism board arrival statistics and regional DMO spending surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
US and Canada Travel Market
Travel and Tourism
Sustainable Tourism Market
Travel and Tourism
USA Sports Tourism Market
Travel and Tourism
Global Enotourism Market
Travel and Tourism
Asia-Pacific MICE Tourism Market
Travel and Tourism
New Zealand Sports Tourism Market
Travel and Tourism
UAE Sustainable Tourism Market
Travel and Tourism
Customised Holidays Market
Travel and Tourism
Hong Kong Outbound Tourism Market
Travel and Tourism
Japan Outbound Tourism Market
Travel and Tourism
Mexico Sustainable Tourism Market
Travel and Tourism
Middle East and Africa Travel Retail Market
Travel and Tourism
South Africa Sports Tourism Market
Travel and Tourism
USA Sustainable Tourism Market
Travel and Tourism
Travel Retail Market
Travel and Tourism
Wedding Tourism Market