
 Special Interest Tourism Market | 2026-2036
Special Interest Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Special Interest Tourism Market Analytics
Buyer concentration among ultra-high-net-worth households is restructuring demand patterns across the special interest tourism landscape. TCS World Travel leverages private jet logistics to control end-to-end itinerary execution for wealthy clientele. Quasar Expeditions anchors its competitive position through Galápagos vessel ownership and naturalist guide certification programs. Black Tomato differentiates via bespoke trip architecture that embeds local artisans and conservation scientists directly into guest experiences.
Special interest tourism encompasses curated travel experiences designed around specific passions, expertise acquisition, or skill development rather than generic leisure, typically involving small group sizes, specialized guides, and extended on-site engagement of five to fourteen days. Its commercial purpose centers on extracting premium pricing through scarcity, knowledge transfer, and access to restricted environments. Culinary tours and eco-tourism command the deepest margin pools due to ingredient provenance requirements and conservation partnership licensing. Adventure tourism sustains the fastest expansion trajectory as equipment innovations and safety protocols broaden participant demographics beyond elite athletes. Cultural tours occupy a mature position with established supply chains but face pressure from digital replication of heritage site access.
FAA Part 135 certification governs U.S. air charter operations that underpin luxury special interest logistics, while EU ETS carbon pricing affects transatlantic itinerary economics. Costa Rica's SINAC permit system restricts visitor volumes to protected areas, creating artificial scarcity that operators must navigate through concession partnerships. Stakeholders must monitor how biodiversity credit frameworks and indigenous land-rights adjudication reshape access terms to destination assets.
Market Dynamics
Affluent retiree households are consolidating demand around experiential travel formats that require specialized logistics and exclusive access arrangements, compressing operator margins while elevating service complexity thresholds.
Growth Catalysts
- EU Green Deal carbon-border adjustments:Aviation fuel taxation is accelerating route optimization investments among European operators, creating competitive differentiation for carriers with lower-emission fleets.
- Costa Rica's SINAC permit scarcity:Protected-area access restrictions generate artificial capacity constraints that sustain premium pricing power for concession holders in the ecotourism corridor.
- Adventure tourism equipment innovation:Safety protocol advances and gear lightweighting are expanding participant demographics beyond elite athletes into mass-affluent segments.
Market Restraints
- Aviation compliance cost escalation:FAA Part 135 certification requirements and EU ETS carbon pricing are inflating fixed costs for luxury air charter operations that underpin itinerary execution.
- Galápagos vessel supply concentration:Fleet ownership concentration among established operators limits new entrant capacity in this high-yield destination, constraining market expansion.
- Indigenous land-rights adjudication uncertainty:Pending territorial claims in Costa Rica and Ecuador are freezing concession renewals and deterring infrastructure investment.
Strategic Opportunities
- Biodiversity credit framework integration:Emerging conservation finance mechanisms allow operators to monetize guest participation in habitat restoration, creating new revenue streams beyond trip fees.
- Culinary tourism ingredient provenance verticalization:Direct sourcing partnerships with artisan producers enable margin capture currently lost to intermediaries in established food tourism supply chains.
- Conservation scientist embedding:Research institution collaborations transform guest experiences into citizen science contributions, justifying super-premium positioning.
Industry Challenges
- Naturalist guide certification bottlenecks:Extended training timelines and limited examination capacity in Ecuador and Costa Rica are throttling service quality expansion.
- Concession partnership negotiation complexity:Multi-stakeholder agreements involving SINAC, indigenous authorities, and local municipalities extend deal closure cycles and elevate legal costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Special Interest Tourism Market |
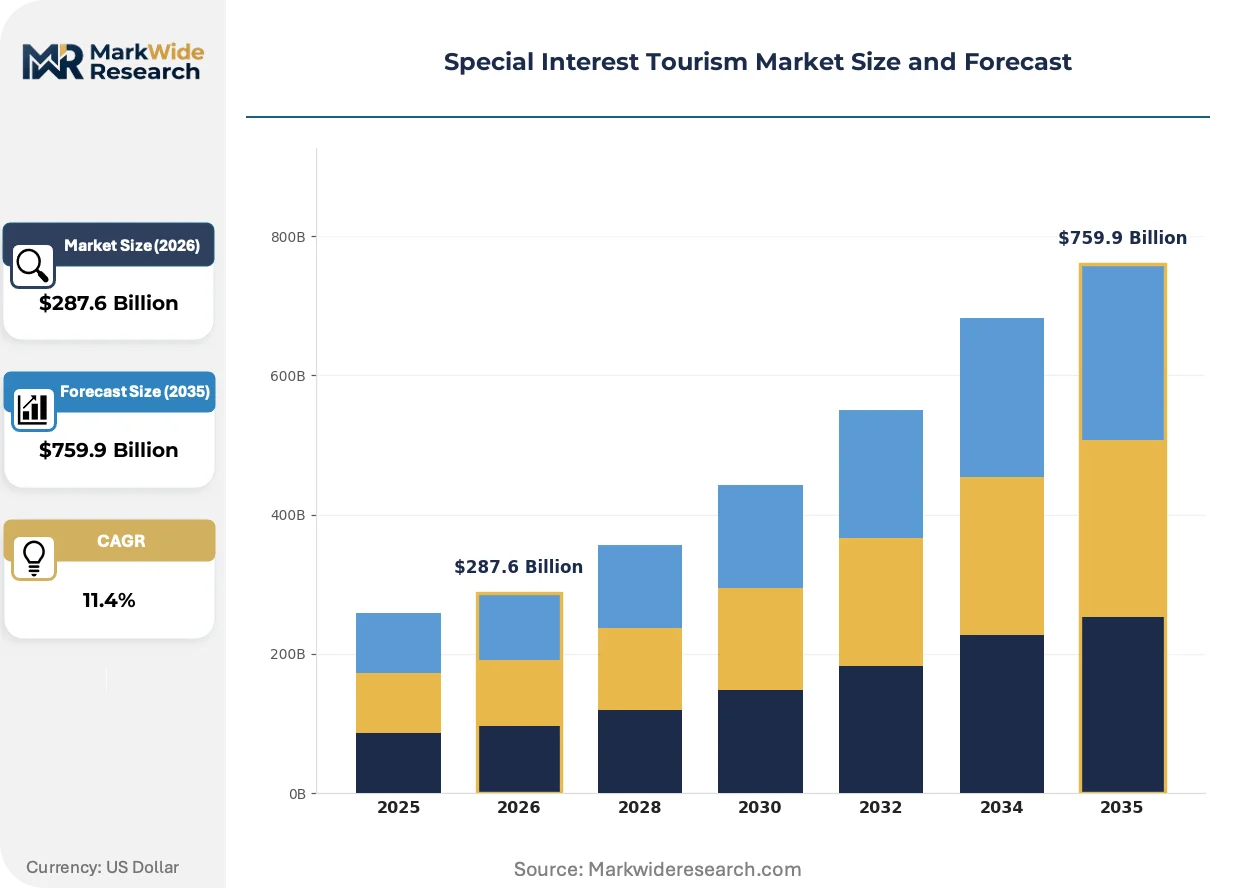
| Market Size in 2026 | $287.6 Billion |
| Market Size in 2035 | $759.9 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Culinary Tours, Eco-Tourism, Adventure Tourism, Cultural Tours Activity: Wildlife Watching, Bird Watching, Trekking, Historical Exploration Demographic: Solo Travelers, Families, Couples, Senior Citizens Duration: Weekend Trips, Week-Long Excursions, Month-Long Expeditions, Short Getaways |
| Companies Covered | TCS World Travel, Quasar Expeditions, Artisans of Leisure, Scott Dunn, Black Tomato, Timbuktu, Unforgettable Travel Company, Backroads, Wilderness Travel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Special Interest Tourism Market Evolving Landscape
Special interest tourism is pivoting from standardized itinerary packages toward hyper-customized experiences that embed technical expertise and restricted-access credentials as core value propositions.
Lightweight satellite communication systems are overtaking traditional radio-based safety protocols in remote expedition settings. Adventure tourism operators serving Patagonian and Himalayan routes are adopting these devices for real-time weather monitoring and emergency response coordination. The technology is overtaking established safety infrastructure investments as the baseline operational requirement for insurance underwriting.
EU ETS carbon pricing mechanisms are restructuring transatlantic itinerary economics. Operators now face marginal cost increases on every aviation segment touching European airspace, forcing consolidation of multi-destination trips into single-continent circuits. Culinary and cultural tour segments with dense European routing are absorbing the steepest margin compression and responding with extended on-ground stays to reduce flight segments.
Direct-to-traveler booking platforms are disintermediating traditional wholesale distribution channels for specialized experiences. Affluent households increasingly research and purchase Galápagos expeditions and Costa Rica ecotours through operator-owned digital interfaces rather than travel advisor networks. This pattern concentrates most visibly in North American source markets where household research sophistication and credit card travel benefits reduce intermediary value.
Special Interest Tourism Market Segmentation

Special interest tourism operators design packaging and pricing architectures around distinct traveler psychographics rather than generic destination appeal. Segmentation precision determines concession access negotiations, guide certification investments, and partnership structures with conservation authorities.
Type:
Buyer differentiation in this category hinges on margin depth and supply chain complexity rather than trip frequency or booking channel.
- Culinary Tours:These itineraries center on ingredient provenance verification and direct artisan producer relationships. Gastronomic corridors in Italy's Emilia-Romagna and Japan's Hokkaido command premium positioning through controlled supply chain verticalization and seasonal harvest timing.
- Eco-Tourism:Protected-area access credentials and biodiversity partnership licensing define competitive position. Costa Rica's SINAC permit scarcity and Ecuador's Galápagos vessel ownership constraints create artificial capacity limits that sustain super-premium pricing.
- Adventure Tourism:Equipment innovation and safety protocol advances are expanding participant demographics beyond elite athletes. Lightweight satellite communication systems now serve as baseline insurance requirements for Patagonian and Himalayan route operators.
- Cultural Tours:Established heritage site supply chains face margin pressure from digital replication technologies. Extended on-ground stays are replacing multi-destination circuits as EU ETS carbon pricing restructures transatlantic itinerary economics.
Culinary Tours lead volumes today; Adventure Tourism is gaining share fastest.
Activity:
Volume concentration in this category tracks directly to equipment requirements and guide specialization intensity.
- Wildlife Watching:Specialized vessel logistics and naturalist guide certification programs anchor competitive position. Kenya's Maasai Mara and Botswana's Okavango Delta attract affluent retirees through exclusive concession partnerships and seasonal migration timing.
- Bird Watching:Avitourism concentrates in biodiversity hotspots with endemic species density. Colombia's Andean cloud forests and Papua New Guinea's highlands sustain premium pricing through restricted-access arrangements with local conservation trusts.
- Trekking:Safety infrastructure investments and permit allocation systems structure market access. Nepal's Sagarmatha National Park and Peru's Inca Trail impose strict daily visitor caps that concession holders navigate through advance booking partnerships.
- Historical Exploration:Archaeological site licensing and scholar guide networks differentiate offerings. Jordan's Petra and Cambodia's Angkor Wat face capacity management challenges as direct-to-traveler booking platforms disintermediate traditional wholesale channels.
Trekking dominates current booking volumes; Bird Watching shows the steepest expansion trajectory.
Demographic:
Service complexity thresholds and logistics coordination requirements separate buyer groups in this dimension.
- Solo Travelers:Individual itinerary customization demands flexible guide allocation and single-occupancy accommodation sourcing. This segment absorbs the highest per-capita pricing premiums across all special interest categories.
- Families:Multi-generational safety protocols and age-appropriate activity calibration drive operator investment in specialized equipment inventories and guide training extensions.
- Couples:Romantic positioning and exclusive-access arrangements command margin premiums in culinary and eco-tourism verticals through private dining installations and after-hours site access.
- Senior Citizens:Affluent retiree households are consolidating demand around experiential formats requiring specialized logistics and extended on-site engagement of five to fourteen days.
Senior Citizens anchor revenue concentration today; Solo Travelers are climbing the fastest.
Duration:
Fixed cost recovery patterns and guide utilization rates determine profitability architecture across trip lengths.
- Weekend Trips:Compressed logistics demand regional proximity and streamlined permit processing. These itineraries concentrate in domestic markets and near-border corridors to minimize aviation segment exposure.
- Week-Long Excursions:Seven-day formats optimize guide deployment efficiency and accommodation contract terms. This duration captures the deepest market penetration across culinary and cultural verticals.
- Month-Long Expeditions:Extended itineraries require complex multi-country visa coordination and sequential concession partnerships. Polar expedition and trans-Himalayan routes sustain pricing through equipment provision and technical guide certification.
- Short Getaways:Two-to-four-day formats target urban affluent households with limited discretionary time allocation. These trips emphasize intensity over breadth through concentrated activity scheduling.
Week-Long Excursions hold the largest volume position; Month-Long Expeditions are expanding most quickly.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Costa Rica commands premium pricing in ecotourism corridors while Germany's outbound operators navigate EU ETS carbon adjustments. The United States, Australia, and Kenya complete the geographic spread where specialized logistics and restricted-access credentials concentrate demand.
United States
Affluent retiree households drive demand for private jet logistics and extended on-site engagement formats. FAA Part 135 certification governs air charter operations that underpin luxury itinerary execution. Greater Miami serves as the primary embarkation hub for Galápagos and Costa Rica expeditions.
Costa Rica
SINAC permit scarcity generates artificial capacity constraints that sustain super-premium pricing for concession holders. The EU Green Deal's carbon-border adjustments affect European visitor volume economics. The Osa Peninsula and Monteverde cloud forest corridor attract biodiversity-focused operators through protected-area access partnerships.
Germany
Outbound experiential travel demand concentrates among high-net-worth households seeking technical expertise acquisition formats. EU ETS carbon pricing inflates transatlantic aviation segment costs for itinerary planners. Munich-based operators specialize in culinary provenance tours to Italy's Emilia-Romagna corridor.
Australia
Domestic adventure tourism participation expands through equipment innovation and safety protocol advances. The country's national park permit systems restrict access to biodiversity hotspots including Tasmania's Southwest Wilderness. Cairns and Port Douglas anchor Great Barrier Reef specialized diving logistics.
Kenya
Wildlife watching demand consolidates around exclusive concession partnerships in the Maasai Mara ecosystem. Kenya Wildlife Service licensing frameworks structure operator access to protected areas. Nairobi serves as the logistics coordination hub for mobile tented camp operations across the Rift Valley.
Special Interest Tourism Market Competitive Landscape
North American operators anchor the premium logistics tier; European specialists hold position in culinary and cultural verticals. Market structure fragments across vessel ownership, guide certification networks, and concession partnerships rather than consolidating around scale. Three archetypes dominate: private jet logistics integrators, vessel-owning expedition operators, and bespoke itinerary architects. Competitive moves concentrate on concession partnership negotiation and direct-to-traveler platform development.
Within the expedition vessel tier, Quasar Expeditions exemplifies ownership-based competitive positioning. TCS World Travel and Black Tomato occupy distinct archetypes as logistics integrators and bespoke architects respectively. These three operators represent the span of strategic approaches from asset-heavy to asset-light market participation.
| Leading Market Players |
|---|
| TCS World Travel |
| Quasar Expeditions |
| Artisans of Leisure |
| Scott Dunn |
| Black Tomato |
| Timbuktu |
| Unforgettable Travel Company |
| Backroads |
| Wilderness Travel |
| Others |
Value Network & Pricing Analysis
Certification-tier divergence between SINAC concession holders and non-permitted operators manifests in pricing premiums exceeding threefold for identical biodiversity experiences, while supply chain configurations split between asset-heavy vessel ownership in Ecuador and asset-light guide-network models in Costa Rica. EU ETS carbon pricing feeds back into route architecture, forcing operators to consolidate multi-destination itineraries into single-continent circuits that alter fixed cost recovery patterns.
Pricing Analysis
Capacity additions in Kenya's Maasai Mara concession system are reshaping price floors for wildlife watching itineraries, compressing margins for mid-tier operators while premium holders defend positioning through exclusive after-hours access rights. Pricing stratifies across SINAC permit tiers, naturalist guide certification levels, and private aviation integration depth. Cost compression in European-sourced culinary tours intensifies as EU ETS obligations inflate transatlantic segment economics. Affluent retiree households show lowest price sensitivity; mass-affluent adventure tourists absorb highest booking abandonment rates.
Supply Chain Analysis
Direct-to-traveler digital channels handle North American affluent household demand, disintermediating traditional travel advisor networks that previously captured margin. Supply concentrates in Ecuador for Galápagos vessel operations, Costa Rica for cloud forest biodiversity access, and Kenya for savanna concession logistics. Raw material dependencies include lightweight satellite communication hardware, specialized expedition vessel hull materials, and naturalist guide training capacity. Single-source vulnerability runs through SINAC permit allocation systems that gate protected-area access. Distribution runs through operator-owned booking platforms and exclusive travel advisor networks serving ultra-high-net-worth segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Special interest tourism operates as a regulatory compounder where EU Green Deal carbon-border adjustments and SINAC permit scarcity simultaneously constrain supply and inflate demand for credentialed operators.
For Market Incumbents: Anchor competitive position through concession partnership renewals in Costa Rica's Osa Peninsula and Monteverde corridors before indigenous land-rights adjudication freezes access terms. Deepen naturalist guide certification pipelines in Ecuador to preempt service quality bottlenecks. Vertical integration into private aviation logistics through FAA Part 135 certification or exclusive carrier contracts defends margin against EU ETS cost pass-through.
For New Entrants and Emerging Players: Conservation scientist embedding partnerships offer white-space entry with lower capital requirements than vessel ownership or concession acquisition. Target bird watching avitourism in Colombia's Andean cloud forests where endemic species density supports premium positioning without Galápagos-level fleet investment. Direct-to-traveler platform development with citizen science integration provides go-to-market differentiation against established wholesale channels.
For Investors and Strategic Acquirers: Consolidation pressure builds where SINAC permit scarcity concentrates pricing power among incumbent concession holders with indigenous authority relationships. Long-term viability favors asset-light operators with exclusive guide networks and research institution partnerships over capital-intensive vessel fleets. Monitor biodiversity credit framework maturation as inflection indicator for conservation finance revenue stream viability.
| Strategic Initiative | Industry Significance |
|---|---|
| SINAC Concession Partnership Renewal | Secures protected-area access credentials that sustain super-premium pricing in Costa Rica's ecotourism corridor. |
| Naturalist Guide Certification Pipeline Investment | Expands service quality capacity in Ecuador and Costa Rica where examination bottlenecks throttle supply. |
| Direct-to-Traveler Platform Development | Captures North American affluent household bookings disintermediating traditional travel advisor networks. |
| Conservation Scientist Embedding Program | Transforms guest experiences into citizen science contributions justifying super-premium positioning. |
| Lightweight Satellite Communication Adoption | Meets baseline insurance requirements for Patagonian and Himalayan route operators expanding demographics. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with tour operators, naturalist guide training directors, SINAC permit administrators, and conservation finance specialists alongside secondary validation. Bottom-up data drew from SINAC concession records, Kenya Wildlife Service licensing frameworks, FAA Part 135 certification databases, and EU ETS carbon pricing disclosures. Top-down triangulation referenced hospitality industry filings, aviation regulatory registers, and conservation partnership announcements. Cross-referencing between booking platform analytics and guide certification pipeline data reinforced segment-level demand estimates.
Segment-weighting approaches distributed value and volume across culinary, eco-tourism, adventure, and cultural tour types, further disaggregated by wildlife watching, bird watching, trekking, and historical exploration activities. Demographic stratification captured solo travelers, families, couples, and senior citizens with duration tiers from short getaways through month-long expeditions. CAGRs derived from elasticity modeling against discretionary spending indicators, regulatory cost pass-through assumptions, and permit scarcity premiums. Forecast inputs included EU Green Deal implementation trajectories, indigenous land-rights adjudication timelines, and biodiversity credit market development.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to SINAC permit allocation shifts, indigenous territorial claim resolutions, and aviation carbon pricing escalation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Ethno Tourism Community Based Eco Tourism Market
Travel and Tourism
Europe Wellness Tourism Market
Travel and Tourism
Solo Ecotourism Market
Travel and Tourism
Airline Retailing Market
Travel and Tourism
US Outbound Tourism Market
Travel and Tourism
Japan Outbound Tourism Market
Travel and Tourism
India Travel Retail Market
Travel and Tourism
Mexico Sustainable Tourism Market
Travel and Tourism
Latin America Inflight Services Market
Travel and Tourism
MICE Travel Service Market
Travel and Tourism
Yacht Charter Market
Travel and Tourism
United Kingdom Casino Tourism Market
Travel and Tourism
France Luxury Travel Market
Travel and Tourism
Japan Sports Tourism Market
Travel and Tourism
Asia Pacific Wellness Tourism Market
Travel and Tourism
North America Travel Retail Market