
 Integrated Stove Market | 2026-2036
Integrated Stove Market Size, Share, and Industry Trends Forecast 2026-2036
Integrated Stove Market Foresight
Buyer concentration among large-scale property developers and hospitality procurement groups is hardening across the integrated stove supply base. SENG leverages its vertical manufacturing footprint in Zhejiang to control component costs and shorten lead times for bulk commercial orders. AUPU anchors its position through sustained R&D spending on smart ignition systems and IoT-enabled safety controls. OLHENC competes aggressively on price in the entry-level residential segment while building distributor density in tier-two Chinese cities.
An integrated stove combines fuel source, burner assembly, ventilation capture, and control interface into a single kitchen appliance unit, typically fabricated from stainless steel housings with cast-iron or ceramic-glass cooktops and integrated grease filtration systems rated for residential or commercial duty cycles. The primary purpose is to consolidate cooking and exhaust functions into space-optimized footprints for modern kitchen layouts where wall-mounted range hoods are impractical. Induction product types now lead value contribution due to efficiency premiums and compatibility with smart home ecosystems, while gas configurations retain volume dominance in markets with established pipeline infrastructure. Commercial end users represent the fastest-expanding demand pool as ghost kitchen operators and centralized food prep facilities seek standardized, high-throughput cooking stations. Smart technology variants command margin premiums through sensor-driven temperature modulation and remote diagnostics, though traditional technology still occupies the bulk of replacement-cycle purchases.
China's SAMR enforces GB standards for gas appliance safety and combustion efficiency, directly shaping product certification requirements for domestic sales and export qualification. The EU's Ecodesign Directive and CE marking framework impose minimum energy performance thresholds that filter non-compliant induction and electric models from European market access. India's BIS certification for domestic gas stoves creates a parallel compliance pathway that manufacturers must navigate for import clearance. Stakeholders should monitor divergence between regional efficiency test protocols, as harmonization gaps between Chinese GB methods and EU measurement standards threaten to fragment R&D allocation and lengthen product validation timelines.
Market Dynamics
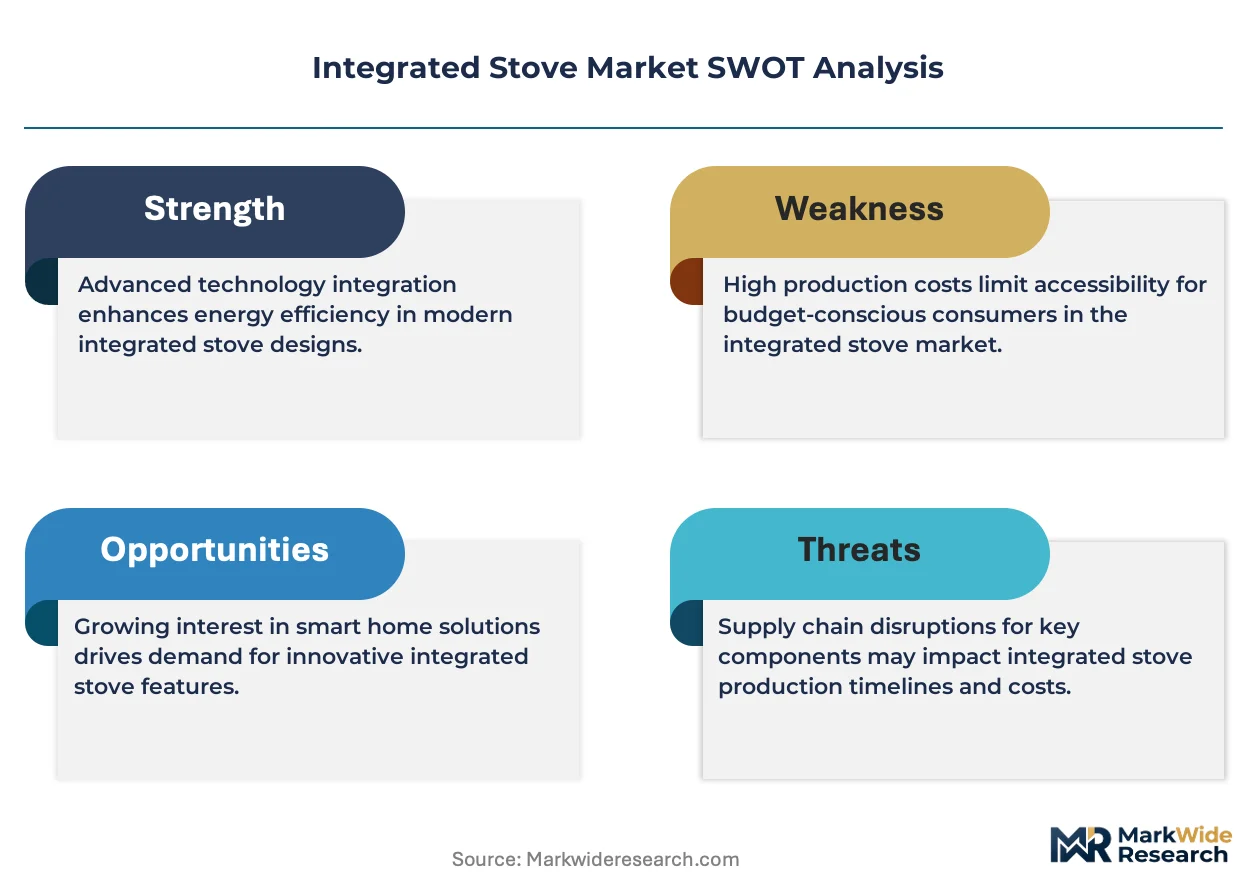
China's SAMR efficiency mandates and the EU's Ecodesign Directive are compressing product development cycles while forcing R&D reallocation toward induction platforms. Dual certification requirements for GB standards and CE marking now dominate capital allocation decisions across the supply base.
Growth Catalysts
- Multi-burner induction systems:Residential kitchen renovations in China's coastal provinces are accelerating replacement of standalone gas cooktops with integrated ventilation units. Zhejiang and Guangdong manufacturing clusters provide component proximity for rapid scaling.
- EU Ecodesign thresholds:Minimum energy performance standards for electric cooking appliances are filtering non-compliant models from European market access, creating certification-based competitive moats for prepared manufacturers.
- Ghost kitchen standardization:Centralized food prep facilities and delivery-only restaurant operators are specifying high-throughput cooking stations with integrated exhaust capture for space-constrained urban real estate.
Market Restraints
- Copper and rare-earth magnet costs:Induction coil assemblies depend on copper winding and neodymium magnet supply chains concentrated in Chinese processing facilities, exposing margins to raw material volatility.
- Gas infrastructure lock-in:Established pipeline networks in India and Southeast Asian markets perpetuate demand for conventional gas configurations despite efficiency disadvantages, fragmenting R&D priorities.
- Harmonization gaps:Divergence between Chinese GB test protocols and EU measurement standards for energy efficiency extends product validation timelines and duplicates certification expenditures.
Strategic Opportunities
- India BIS pathway:Domestic gas stove certification requirements create a compliance barrier that prepared entrants can leverage against unqualified imports in a market with underpenetrated integrated appliance adoption.
- IoT-enabled safety controls:Convergence of smart ignition systems with remote diagnostic platforms opens premium positioning in commercial segments where downtime costs exceed hardware premiums.
- Tier-two distributor density:Entry-level residential segments in China's interior provinces remain underserved by integrated stove specialists focused on coastal metros.
Industry Challenges
- Embedded software certification:Smart technology variants require cybersecurity validation alongside traditional safety testing, extending development timelines and demanding new technical competencies from engineering teams.
- Legacy ventilation retrofit compatibility:Replacement-cycle purchases often encounter ductwork configuration mismatches between older buildings and standardized integrated unit dimensions, complicating installation and service provisioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Integrated Stove Market |
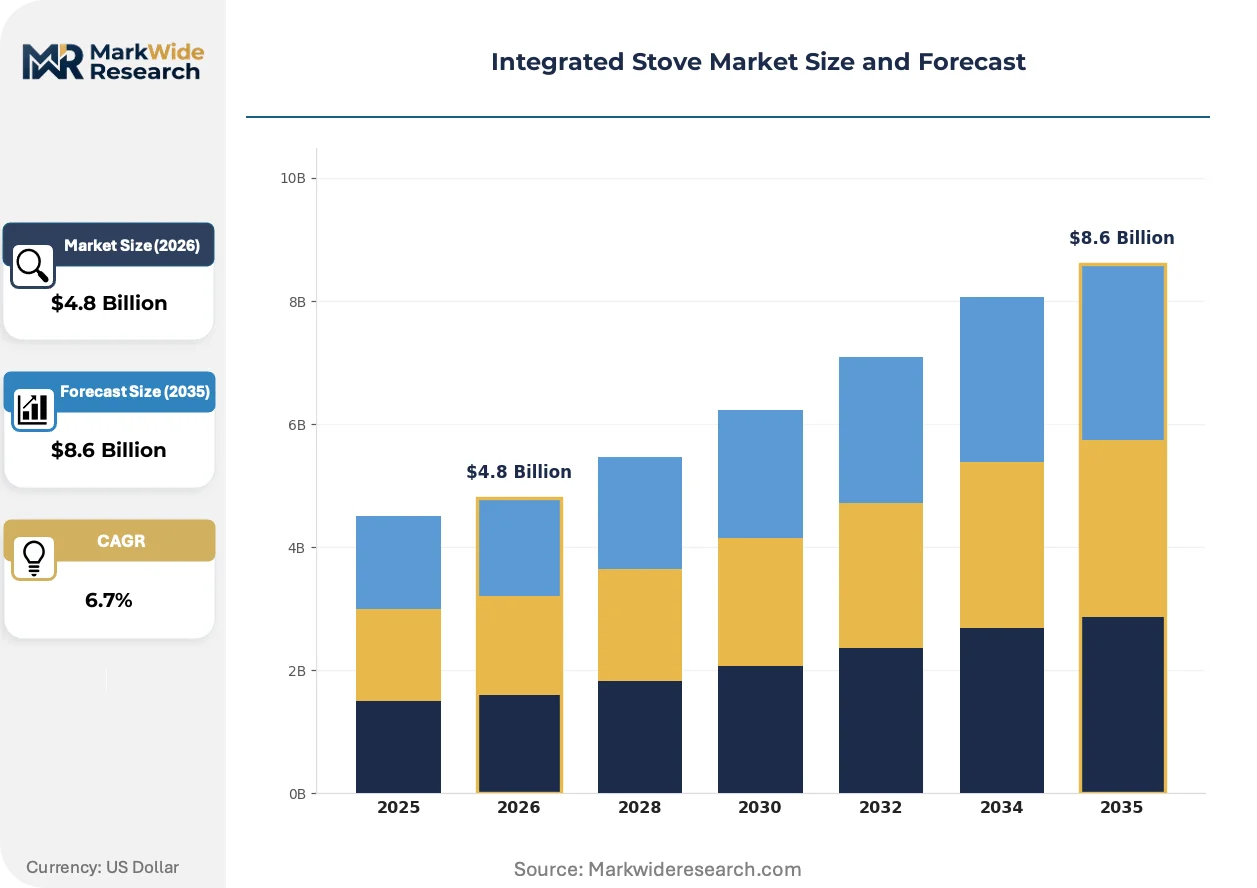
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Induction, Gas, Electric, Charcoal End User: Residential, Commercial, Food Service, Hospitality Technology: Smart Technology, Traditional, Hybrid, Automated Capacity: Single Burner, Double Burner, Multi-Burner, High Capacity |
| Companies Covered | OLHENC, Medal, AOTIN, KODEAR, LSA, AUPU, SENG, Fairui, DRESSY, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Integrated Stove Market Shifts & Advancements
Sensor-driven temperature modulation and connected diagnostics are absorbing development resources while reshaping how commercial operators specify cooking equipment. Procurement criteria now weight total cost of ownership over upfront capital expenditure.
Induction coil assemblies with variable frequency drives are absorbing the performance gap between residential and commercial duty cycles. Ghost kitchen operators in China's urban centers are specifying these units for rapid thermal response and reduced ventilation load. The technology is absorbing margin pressure from energy efficiency mandates by enabling premium pricing through measurable operating cost reductions.
China's SAMR enforcement of updated GB standards for gas appliance combustion efficiency is compressing certification timelines for dual-fuel product lines. Manufacturers must now validate products against stricter thermal efficiency floors before domestic market release. Induction-dominant portfolios are absorbing the compliance burden as gas configurations face extended retesting requirements.
Large-scale property developers are consolidating vendor relationships around integrated stove suppliers capable of volume consistency and standardized service terms. Hospitality procurement groups are displacing fragmented local distributor networks with direct manufacturer agreements. This concentration is most visible in China's tier-one cities where commercial kitchen fit-outs require synchronized delivery across multiple project sites.
Integrated Stove Market Segmentation
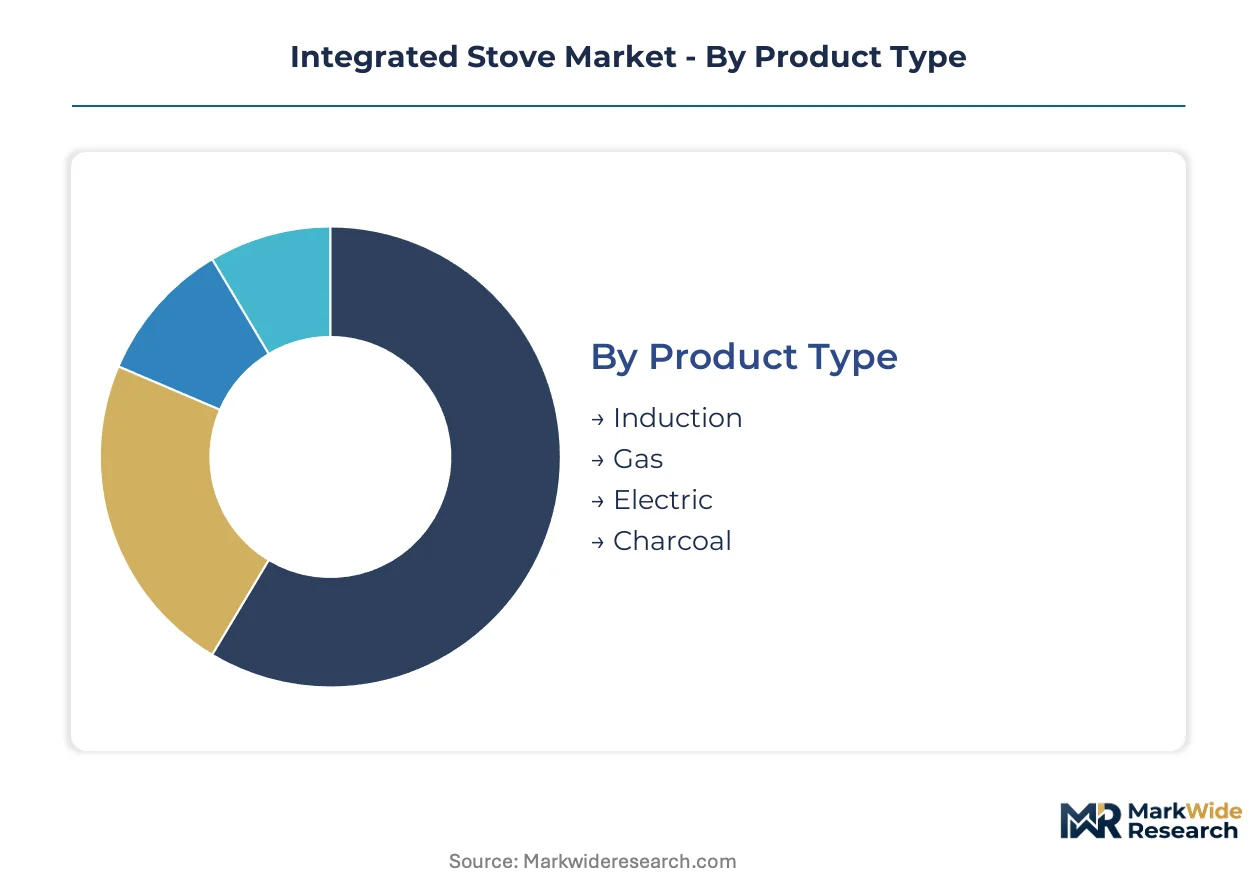
Segmentation reveals how capital allocation, regulatory compliance, and end-use requirements fragment the integrated stove supply base. Product type and capacity decisions determine coil winding specifications, ventilation ratings, and certification pathways. Technology tier selection locks in margin structure and service revenue potential across multi-year replacement cycles.
Product Type:
Capital intensity peaks with induction platforms requiring precision-wound copper coils and frequency inverter assemblies.
- Induction:Copper winding assemblies with neodymium magnet cores deliver rapid thermal response and programmable power modulation. Demand concentrates in China's coastal renovation markets where SAMR efficiency mandates accelerate displacement of conventional gas units. Premium positioning depends on compatibility with smart home ecosystems and variable frequency drive performance.
- Gas:Cast-iron burner heads with brass valve trains and piezoelectric ignition systems dominate volume in pipeline-connected markets. India's BIS certification pathway and Southeast Asian infrastructure lock-in perpetuate demand despite efficiency disadvantages versus electric alternatives. Margin compression follows commodity stainless steel pricing and combustion efficiency retesting requirements.
- Electric:Resistive coil elements with ceramic-glass cooktops serve budget residential retrofits and markets with unreliable gas infrastructure.
- Charcoal:Steel housings with adjustable airflow grates retain niche demand in outdoor cooking and specialized hospitality applications.
Most installed capacity flows through Gas configurations. Expansion is steepest in Induction.
End User:
Application type dictates duty cycle ratings, grease filtration specifications, and service contract structures.
- Residential:Single-family and multi-unit dwellings specify space-optimized footprints with integrated downdraft ventilation. China's tier-two cities and interior provinces show underpenetrated adoption versus coastal metros, creating distributor density opportunities for entry-level specialists. Replacement cycles align with kitchen renovation timelines.
- Commercial:Ghost kitchen operators and centralized food prep facilities demand high-throughput stations with standardized exhaust capture. Urban real estate constraints in China's tier-one cities drive specification of multi-burner induction units with reduced ventilation loads. Procurement criteria weight total cost of ownership over upfront capital expenditure.
- Food Service:Quick-service restaurants and institutional cafeterias require rapid recovery times and modular maintenance access.
- Hospitality:Full-service hotels and banquet facilities prioritize aesthetic integration with kitchen design and synchronized delivery across project sites.
Volume concentration sits with Residential replacement cycles. Commercial segments are climbing the fastest.
Technology:
Development resource allocation splits between embedded software validation and traditional safety testing competencies.
- Smart Technology:Sensor-driven temperature modulation, remote diagnostic platforms, and IoT-enabled safety controls command margin premiums. Commercial operators absorb hardware premiums where downtime costs exceed equipment expenditure. Cybersecurity certification extends development timelines beyond traditional appliance validation.
- Traditional:Mechanical ignition systems and analog temperature controls occupy bulk replacement-cycle purchases in cost-sensitive segments. Sustained R&D spending on smart ignition systems by established manufacturers pressures traditional positioning.
- Hybrid:Dual-fuel configurations combining gas burners with electric oven elements serve markets with intermittent energy reliability.
- Automated:Programmable cooking sequences and automated grease management target high-labor-cost commercial environments.
Smart Technology captures the steepest margin expansion. Traditional platforms retain volume dominance.
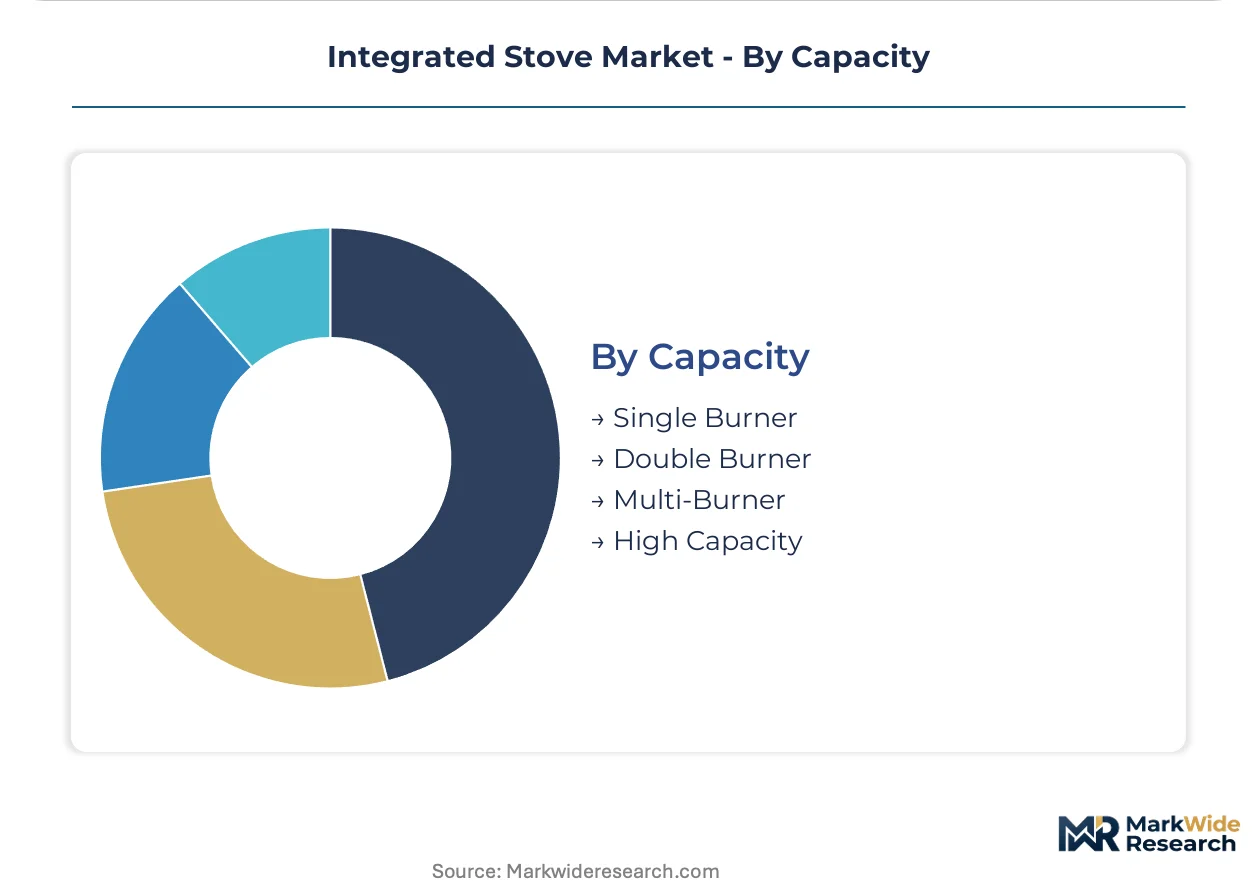
Capacity:
Manufacturing fixture investment scales with burner count and thermal output ratings.
- Multi-Burner:Three to six induction zones or gas burners with integrated ventilation capture serve residential renovations and commercial throughput requirements. Zhejiang and Guangdong manufacturing clusters provide component proximity for rapid scaling of coil winding and housing fabrication.
- High Capacity:Heavy-duty configurations for institutional kitchens and centralized prep facilities demand reinforced stainless steel housings and enhanced grease filtration. Ghost kitchen standardization in China's urban centers drives specification for synchronized delivery across multiple sites.
- Single Burner:Compact units target studio apartments and auxiliary cooking stations.
- Double Burner:Entry-level residential configurations balance footprint constraints with basic meal preparation needs.
Multi-Burner configurations absorb the majority of production throughput. High Capacity segments are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's coastal manufacturing clusters generate integrated stove volumes that dwarf Germany's precision-engineered premium segment, yet both markets now face converging efficiency mandates from their respective regulators.
China
Residential kitchen renovations in Zhejiang and Guangdong provinces are accelerating displacement of standalone gas cooktops with multi-burner induction systems. SAMR enforcement of updated GB standards for combustion efficiency compresses certification timelines for dual-fuel product lines. Zhejiang manufacturing clusters provide component proximity for rapid scaling of coil winding and housing fabrication.
Germany
Commercial hospitality procurement groups specify integrated cooking stations with reduced ventilation loads for urban real estate constraints. The EU Ecodesign Directive imposes minimum energy performance thresholds that filter non-compliant induction models from market access. Industrial concentration in Baden-Württemberg anchors precision manufacturing of frequency inverter assemblies.
India
Pipeline infrastructure lock-in perpetuates demand for conventional gas configurations despite efficiency disadvantages versus electric alternatives. BIS certification for domestic gas stoves creates a compliance barrier that prepared entrants leverage against unqualified imports. Maharashtra and Gujarat manufacturing hubs concentrate brass valve train and cast-iron burner head production.
United States
Ghost kitchen operators and centralized food prep facilities specify high-throughput cooking stations with integrated exhaust capture. EPA efficiency guidelines for commercial kitchen equipment shape procurement criteria for institutional buyers. California's building electrification mandates accelerate induction adoption in new commercial construction.
Japan
Smart home ecosystem compatibility drives premium positioning for sensor-driven temperature modulation systems. METI energy efficiency standards for household appliances tighten minimum performance thresholds for electric cooking equipment. Kanto region manufacturing maintains precision coil winding capabilities for variable frequency drive assemblies.
Integrated Stove Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The supply base concentrates around three strategic archetypes: vertically integrated manufacturers controlling component costs, R&D-intensive technology developers, and price-aggressive entry-level distributors. Consolidation pressures intensify as large-scale property developers consolidate vendor relationships around suppliers capable of volume consistency. Dominant competitive moves include backward integration into coil winding and housing fabrication, plus strategic partnerships for IoT platform integration.
Among Chinese fabricators, SENG Co., Ltd. exemplifies the vertically integrated archetype through its Zhejiang-based manufacturing footprint, while AUPU occupies a position within the technology-driven tier emphasizing connected safety systems. OLHENC anchors the price-competitive entry-level segment focused on distributor density expansion. These three represent the dominant competitive vectors reshaping procurement relationships across residential and commercial end-use segments.
| Leading Market Players |
|---|
| OLHENC |
| Medal |
| AOTIN |
| KODEAR |
| LSA |
| AUPU |
| SENG |
| Fairui |
| DRESSY |
| Others |
Supply & Pricing Matrix
Copper winding and neodymium magnet costs flow from Chinese processing facilities through induction coil assemblies into premium-tier pricing, while gas configuration margins compress under stainless steel commodity pressure and combustion efficiency retesting burdens.
Pricing Analysis
Capacity additions in Zhejiang and Guangdong are reshaping price floors for multi-burner induction systems as component proximity shortens lead times for bulk orders. Pricing stratifies across smart-enabled premium tiers, standard efficiency-compliant mid-tiers, and entry-level gas configurations where OLHENC competes on distributor density. Cost compression in gas segments is intensifying because SAMR efficiency mandates force extended retesting cycles. Tier-two residential buyers in China's interior provinces exhibit highest price sensitivity, while ghost kitchen operators absorb hardware premiums where downtime costs dominate.
Supply Chain Analysis
Dual certification requirements for GB standards and CE marking gate supplier participation and fragment R&D allocation across validation protocols. Manufacturing concentrates in China, Germany, and India, with coil winding and housing fabrication anchored in Zhejiang clusters. Supply chains draw from copper winding assemblies, neodymium magnet cores, and cast-iron burner heads. Single-source vulnerability concentrates in Chinese rare-earth processing facilities. Distribution runs through consolidated vendor relationships with large-scale property developers and hospitality procurement groups displacing fragmented local networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The integrated stove market reads as a late-cycle quality story where procurement criteria weight total cost of ownership over upfront capital expenditure, with ghost kitchen operators and centralized food prep facilities driving specification toward sensor-driven temperature modulation systems.
For Market Incumbents: Anticipate margin compression from rare-earth magnet cost volatility by securing captive supply of neodymium through backward integration into Chinese processing partnerships. Defend against price-aggressive entry-level specialists by accelerating IoT-enabled safety control certification ahead of embedded software validation requirements that extend development timelines for unprepared competitors. For New Entrants and Emerging Players: Tier-two distributor density in China's interior provinces represents the most penetrable white-space target, as coastal specialists under-serve entry-level residential segments. India's BIS certification pathway for domestic gas stoves offers a compliance-based competitive moat against unqualified imports. A go-to-market angle anchored to aftermarket service bundling for legacy ventilation retrofit compatibility addresses installation friction that complicates replacement-cycle purchases. For Investors and Strategic Acquirers: Consolidation pressure builds where large-scale property developers consolidate vendor relationships around suppliers capable of volume consistency and synchronized delivery across multiple project sites. Long-term viability favors vertically integrated fabricators controlling coil winding and housing fabrication over pure-play distributors. The signal to watch is divergence between Chinese GB test protocols and EU measurement standards, as harmonization gaps that lengthen product validation timelines advantage prepared manufacturers with dual certification capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Processing | Captive neodymium supply from Chinese facilities insulates margins against magnet cost volatility. |
| Dual Certification Investment | Parallel GB standards and CE marking validation opens access to both domestic and European market access. |
| IoT Platform Partnership | Remote diagnostic integration with smart home ecosystems commands premium positioning in commercial segments. |
| Tier-Two Distributor Expansion | Density buildout in China's interior provinces captures underpenetrated residential replacement cycles. |
| Ghost Kitchen Specification Capture | Standardized high-throughput cooking station contracts with delivery-only operators secure recurring revenue. |
Research Methodology
Multiple input streams — primary interviews with appliance manufacturing executives, regulatory affairs specialists at SAMR and EU notified bodies, hospitality procurement managers, and residential distributor network heads — were reconciled against secondary validation from customs trade data, GB standards documentation, Ecodesign Directive filings, and SEC 10-K disclosures from diversified conglomerates with appliance segments. Bottom-up unit economics triangulated against top-down market sizing from coastal manufacturing cluster output data.
Data-stream reconciliation across product type, end-user application, technology tier, and regional regulatory cluster dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level replacement cycle timing, efficiency mandate compliance deadlines, and commercial kitchen fit-out pipelines. Industry-specific forecast inputs incorporated ghost kitchen operator expansion rates and tier-two city renovation permit volumes.
Inputs from SAMR enforcement bulletins and EU Ecodesign preparatory studies were available through the study window; gaps in real-time rare-earth magnet pricing transparency introduce uncertainty bands around induction platform margin projections. Forecasts reflect documented assumptions regarding harmonization gap persistence and infrastructure lock-in duration. A model refresh is warranted upon material change in SAMR combustion efficiency enforcement intensity or EU measurement standard revision timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Restaurant Griddle Market
Food Service
Germany Smokeless Indoor Grills Market
Food Service
Online Grocery Market
Food Service
Global Delivery Takeaway Food Market
Food Service
Restaurants in Belgium Market
Food Service
Netherlands Food Service Market
Food Service
Aquarium Protein Skimmers Market
Food Service
Global Food Retail Market
Food Service
Commercial Grills Market
Food Service
India Quick Service Restaurant Market
Food Service
Virtual Kitchen Market
Food Service
Breakfast Takeout Market
Food Service
United Kingdom Foodservice Market
Food Service
Europe Smokeless Indoor Grills Market
Food Service
Light Meal Market
Food Service
Saudi Arabia Inflight Catering Market