
 Latin America Online Grocery Delivery Market | 2026-2036
Latin America Online Grocery Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Online Grocery Delivery Market Foresight
Urban household procurement patterns are recalibrating as time-constrained families in Latin American megacities substitute physical supermarket visits with app-based ordering. Cornershop leverages its Uber-owned logistics backbone to sustain rapid fulfillment across Mexican and Chilean urban zones. Rappi anchors its position through super-app convergence, embedding grocery within a broader on-demand services architecture that deepens user retention. Mercado Fresh differentiates by specializing in fresh-produce sourcing direct from Brazilian agricultural cooperatives, reducing spoilage rates relative to conventional supermarket supply chains.
Latin America online grocery delivery denotes a digitally intermediated fulfillment system wherein consumers select food and household items through connected interfaces for transport from retail or dedicated fulfillment nodes to residential addresses, typically requiring cold-chain integrity for perishables and delivery completion within windows ranging from fifteen minutes to forty-eight hours. The primary commercial purpose centers on substituting consumer travel time with coordinated picking, packing, and last-mile distribution executed through algorithmic route optimization and gig-economy labor pools. Express delivery commands premium pricing and attracts venture capital deployment, though scheduled delivery captures higher basket values from planned household replenishment cycles. Subscription services represent the fastest-growing structural segment as operators seek to lock recurring revenue and predict demand patterns for inventory positioning.
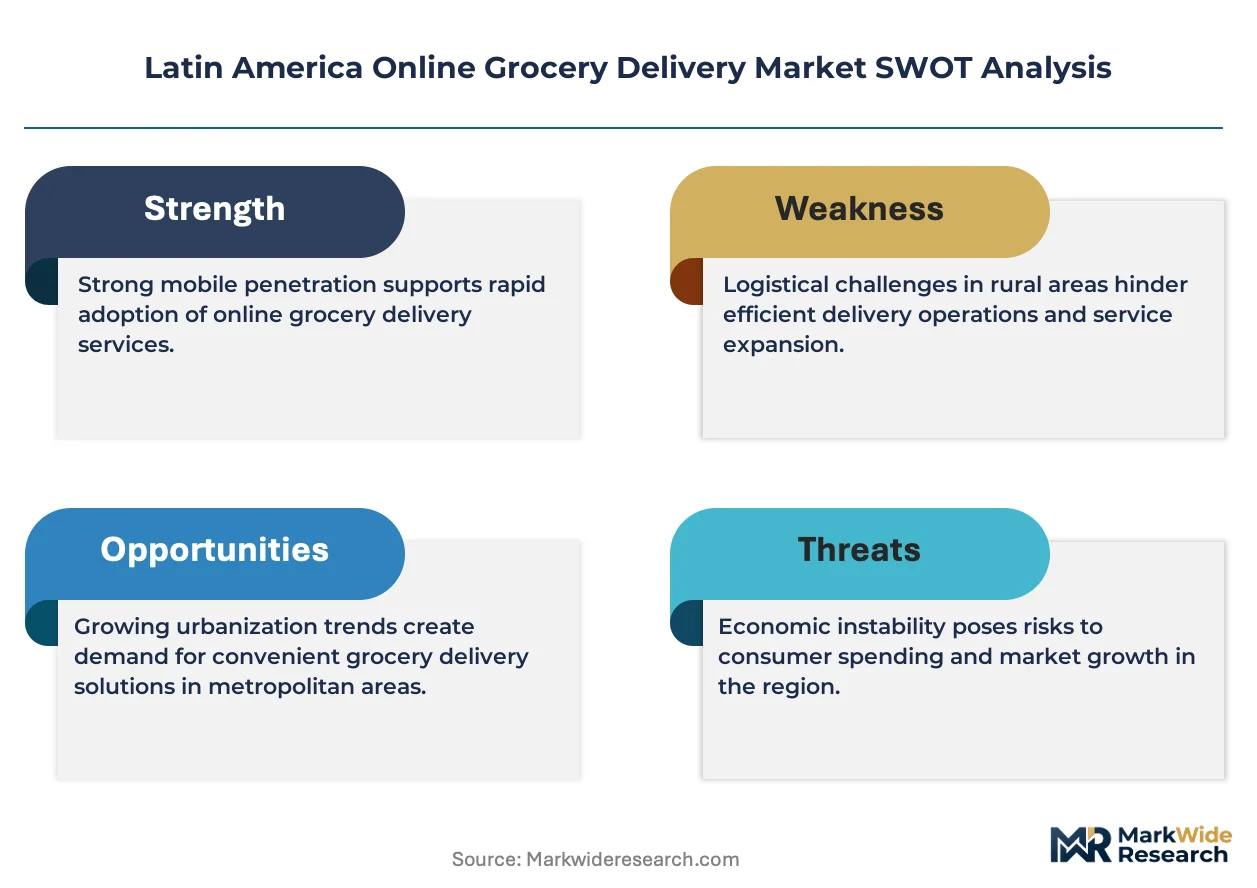
Brazil's ANPD data governance standards, Mexico's PROFECO consumer protection mandates, and Argentina's import licensing requirements for refrigerated transport equipment collectively shape operational compliance burdens and capital thresholds for market entry. These frameworks force platform operators to maintain localized legal infrastructure and adapt data handling practices to jurisdiction-specific consent protocols. Stakeholders must monitor regulatory divergence across Mercosur and Pacific Alliance trade configurations when designing cross-border fulfillment networks and supplier integration strategies.
Market Dynamics
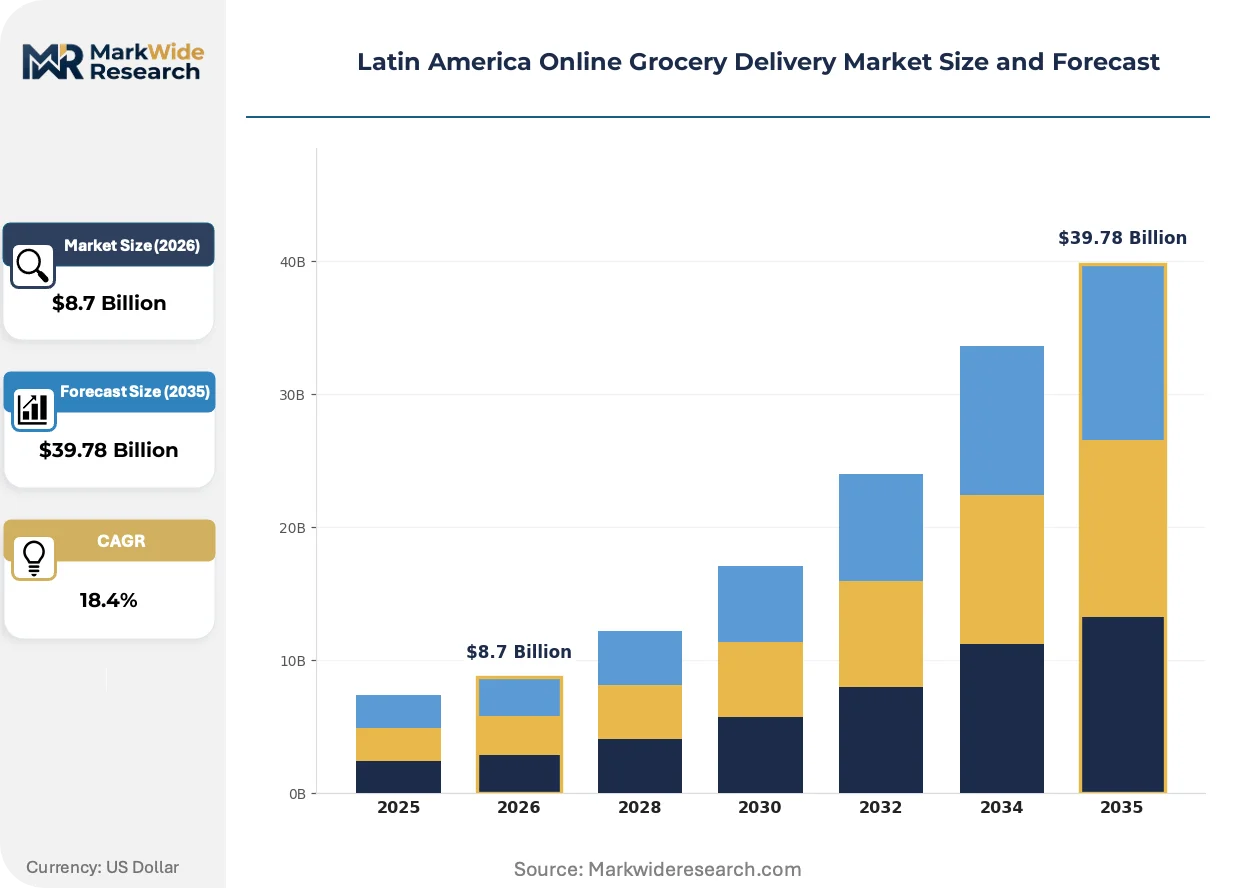
Dark-store infrastructure deployment is compressing fulfillment timelines across Latin American megacities, forcing capital reallocation from traditional retail footprints to algorithmic inventory positioning and temperature-controlled micro-fulfillment nodes.
Growth Catalysts
- ANPD Data Governance Standards:Brazil's privacy framework mandates localized data handling, creating competitive moats for compliant operators while raising barriers for cross-border entrants.
- Dual-income household density:Time-constrained families in São Paulo and Mexico City are substituting physical supermarket visits with scheduled replenishment cycles that lock recurring revenue.
- Cold-chain integrity protocols:Direct sourcing from agricultural cooperatives reduces spoilage rates and enables premium positioning for perishable categories.
Market Restraints
- Refrigerated transport equipment licensing:Argentina's import controls delay fleet expansion and inflate capex timelines for temperature-controlled last-mile operators.
- Gig-economy labor pool volatility:Delivery workforce turnover in Brazilian metropolitan corridors disrupts service-level consistency during peak demand windows.
- Dark-store real estate concentration:Prime urban logistics space scarcity in Buenos Aires and Santiago drives rental premiums that compress unit economics.
Strategic Opportunities
- Subscription service penetration:Recurring revenue models remain underdeveloped in Colombian and Peruvian urban markets relative to Brazilian adoption baselines.
- Super-app convergence:Embedding grocery within broader on-demand service architectures deepens user retention and cross-sells financial services.
- PROFECO consumer protection alignment:Mexico's refund and transparency mandates favor platform operators with localized legal infrastructure over informal competitors.
Industry Challenges
- Algorithmic route optimization talent:Scarce data science capacity in Latin American labor markets constrains dynamic fleet dispatch improvements.
- Legacy supermarket ERP integration:Inventory synchronization between dark-store systems and traditional retail backends creates fulfillment accuracy gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Online Grocery Delivery Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Express Delivery, Scheduled Delivery, Same-Day Delivery, Subscription Services Product Type: Fresh Produce, Packaged Goods, Dairy Products, Frozen Foods Customer Type: Families, Young Professionals, Seniors, Health-Conscious Consumers Distribution Channel: Mobile Apps, E-Commerce Websites, Third-Party Platforms, Social Media |
| Companies Covered | Cornershop, Instacart, Rappi, Walmart Grocery, Amazon Grocery, Glovo, Mercadoni, Mercado Fresh, Uber Eats, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Online Grocery Delivery Market Shifts & Advancements
Automated picking systems and predictive demand algorithms are restructuring fulfillment economics, while regulatory data-localization mandates and shifting household replenishment behaviors are redefining competitive positioning across the region.
Robotic picking arms coupled with computer-vision inventory tracking are automating order assembly in São Paulo and Mexico City dark stores. Mid-scale operators are deploying these systems to reduce labor cost per order. The technology is automating fulfillment throughput compression, enabling fifteen-minute delivery windows at previously unsustainable unit economics.
Brazil's ANPD data governance standards now require explicit consumer consent for cross-border data transfers and mandate localized server infrastructure. This policy shift forces platform operators to maintain jurisdiction-specific legal entities and adapt recommendation algorithms to on-premise processing constraints. Express delivery providers with existing Brazilian data centers are absorbing compliance costs faster than multinational entrants.
Planned household replenishment cycles are displacing impulse-driven express orders as primary revenue drivers. Scheduled delivery slots now capture higher basket values from time-constrained families, while on-demand positioning retreats to premium niche positioning. This behavioral pivot is most pronounced in Buenos Aires and Santiago metropolitan corridors where subscription penetration rates exceed regional averages.
Latin America Online Grocery Delivery Market Segmentation
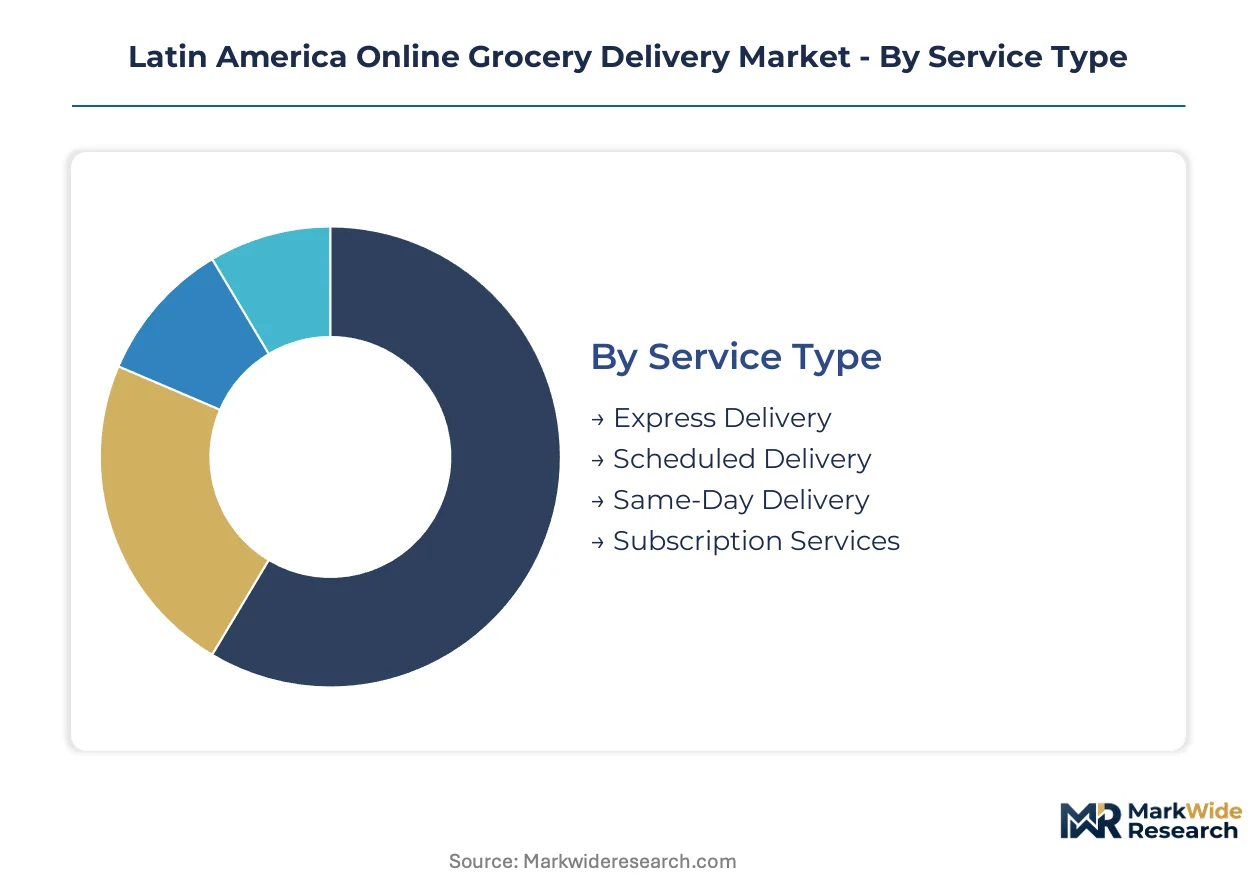
Service architecture and customer archetype definitions determine fulfillment economics and retention mechanics for Latin American online grocery operators. Segmentation reveals where platform investments in cold-chain infrastructure, subscription tooling, and channel-specific interfaces generate differentiated returns across metropolitan corridors.
Service Type:
Upgrade cycles in fulfillment speed are recalibrating household procurement patterns as platform operators deploy dark-store density to compress delivery windows.
- Express Delivery:Fifteen-to-sixty-minute fulfillment windows demand algorithmic route optimization and gig-economy labor pools concentrated in São Paulo and Mexico City. Premium pricing attracts venture deployment, though unit economics remain pressured by workforce turnover during peak windows.
- Scheduled Delivery:Pre-selected time slots enable batch picking and route consolidation, capturing higher basket values from planned replenishment cycles in Buenos Aires and Santiago. Dark-store positioning and predictive demand algorithms improve margin structure relative to on-demand alternatives.
- Same-Day Delivery:Hybrid model balancing speed with operational efficiency through inventory positioning in urban micro-fulfillment nodes.
- Subscription Services:Recurring revenue models lock demand predictability for inventory planning, with penetration climbing fastest in Brazilian metropolitan zones.
Volume placements concentrate in Scheduled Delivery; the faster expansion belongs to Subscription Services.
Product Type:
Cost tier differentiation separates commodity staples from temperature-sensitive categories requiring specialized handling infrastructure.
- Fresh Produce:Direct sourcing from agricultural cooperatives reduces spoilage rates versus conventional supermarket supply chains. Brazilian operators leveraging ANPD-compliant data handling optimize procurement algorithms for seasonal availability.
- Packaged Goods:Shelf-stable categories with lower fulfillment complexity dominate basket composition in Colombian and Peruvian markets where cold-chain infrastructure remains underdeveloped.
- Dairy Products:Refrigerated transport compliance under Argentina's import licensing requirements constrains fleet expansion timelines.
- Frozen Foods:Deep-freeze integrity protocols necessitate specialized last-mile equipment, limiting viable service zones to dense urban corridors.
Packaged goods anchor current volume; fresh produce is gaining share fastest through cooperative sourcing advantages.
Customer Type:
Application-based segmentation maps fulfillment interface investments to distinct household structures and purchasing cadences.
- Families:Dual-income households in São Paulo and Mexico City substitute weekly supermarket visits with scheduled replenishment, driving subscription adoption and higher average order values.
- Young Professionals:Time-constrained urban cohorts favor express delivery for impulse-driven meal solutions, though retention rates lag family segments.
- Seniors:Interface simplicity requirements and payment trust barriers limit penetration; specialized onboarding flows show promise in Chilean markets.
- Health-Conscious Consumers:Organic and specialty diet preferences command premium positioning, with demand clustering in Buenos Aires metropolitan corridors.
Family segments dominate revenue contribution; health-conscious consumers are climbing the fastest on per-order value metrics.
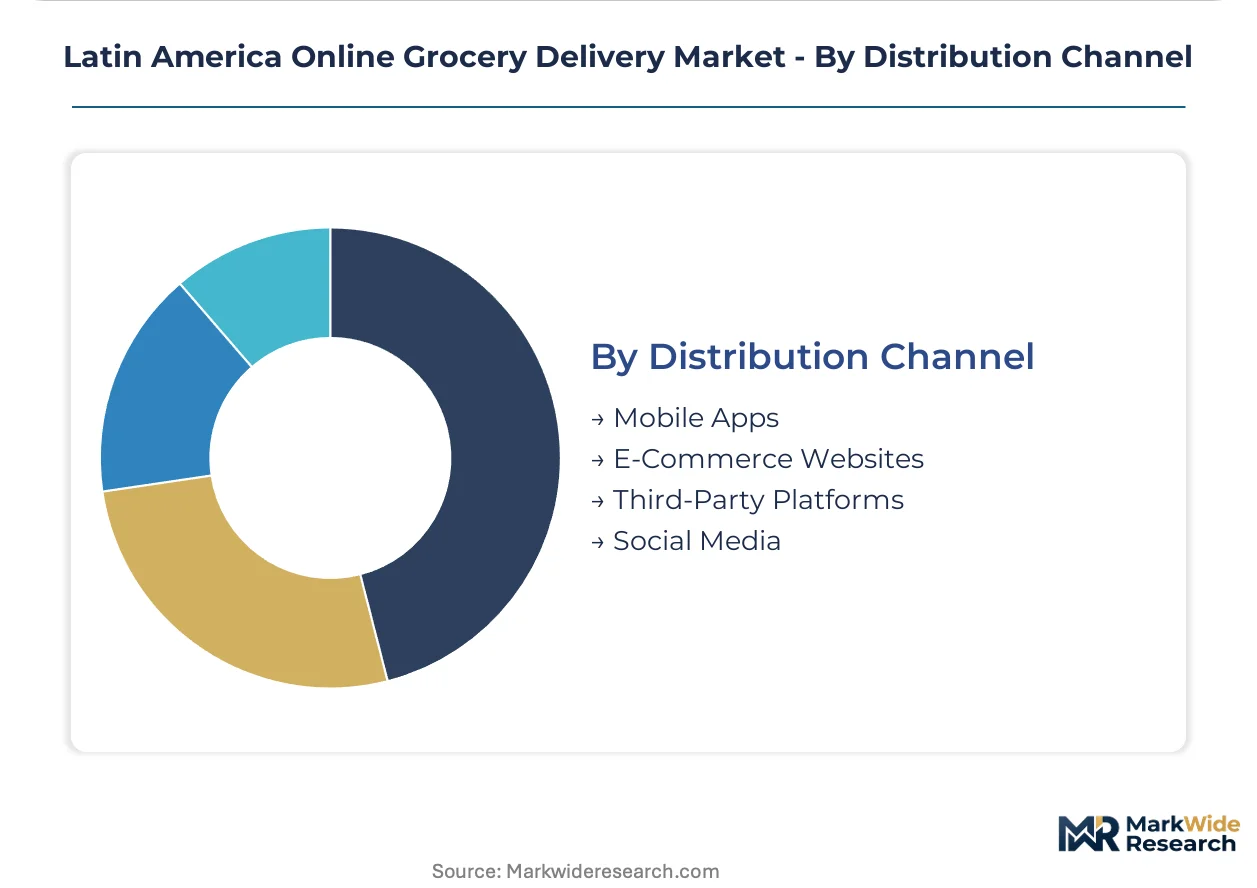
Distribution Channel:
Customer acquisition cost structures vary sharply across interface types, with super-app convergence reshaping channel economics.
- Mobile Apps:Primary interface for retention and subscription management, with push notification systems driving reorder rates in Brazilian urban zones.
- E-Commerce Websites:Desktop and mobile web interfaces capture planned large-basket purchases, particularly among family segments conducting weekly menu planning.
- Third-Party Platforms:Marketplace integration expands reach without proprietary fulfillment investment, though margin compression and data access limitations apply.
- Social Media:Emerging discovery and conversion channel through integrated checkout, with adoption concentrated among young professional demographics.
Mobile apps capture the steepest expansion trajectory; third-party platforms retain volume concentration in markets with fragmented operator presence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manaus Free Trade Zone tax incentives and São Paulo state logistics subsidies concentrate fulfillment infrastructure investment across Brazil's urban corridors. Special economic zones in Nuevo León and Mexico City Metro drive dark-store deployment decisions for operators targeting the Mexican market. Argentina's Tierra del Fuego industrial promotion zone shapes cold-chain equipment sourcing strategies for southern cone operators.
Brazil
Dual-income household density in São Paulo and Rio de Janeiro accelerates scheduled delivery adoption for weekly replenishment cycles. ANPD data governance standards mandate localized server infrastructure and explicit consent protocols for cross-border data transfers. Dark-store clusters in São Paulo's Pinheiros and Vila Madalena neighborhoods enable fifteen-minute fulfillment windows through algorithmic inventory positioning.
Mexico
PROFECO consumer protection mandates and refund transparency requirements favor platform operators with established legal infrastructure over informal competitors. Nuevo León's Monterrey metropolitan corridor attracts fulfillment investment due to cross-border logistics connectivity with Texas distribution networks. Mexico City Metro's Polanco and Condesa districts sustain the highest express delivery density through gig-economy labor pool concentration.
Argentina
Import licensing requirements for refrigerated transport equipment delay fleet expansion timelines and inflate capital expenditure schedules for temperature-controlled operators. Buenos Aires metropolitan corridor leads regional subscription penetration rates as planned household replenishment displaces impulse-driven express orders. Palermo and Recoleta neighborhoods anchor premium positioning for health-conscious consumer segments seeking organic and specialty diet categories.
Chile
Santiago's urban density and elevated smartphone penetration support super-app convergence strategies embedding grocery within broader on-demand service architectures. The country's national consumer protection regulator enforces strict refund and transparency standards that raise operational compliance thresholds. Las Condes and Providencia districts concentrate dark-store infrastructure serving affluent family segments with higher average order values.
Colombia
Bogotá and Medellín metropolitan areas present underdeveloped subscription service penetration relative to Brazilian adoption baselines, creating expansion opportunities for recurring revenue models. National data protection authority guidelines require localized data handling practices similar to ANPD frameworks. Chapinero and El Poblado neighborhoods emerge as initial dark-store deployment zones for operators testing fulfillment economics in Andean urban corridors.
Latin America Online Grocery Delivery Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with super-app operators and dedicated grocery platforms dividing the Latin American landscape through divergent retention mechanics. Platform concentration remains moderate as regional specialists defend position against multinational entrants through localized compliance infrastructure and cooperative sourcing relationships. Three archetypes dominate: super-app conglomerates embedding grocery within service ecosystems, pure-play grocery specialists leveraging fresh-produce sourcing advantages, and marketplace extensions of traditional retail banners. Competitive dynamics center on dark-store density expansion and subscription service penetration as primary defensive moves.
Among the named operators in this study, Cornershop, Rappi, and Mercado Fresh occupy distinct archetype positions within the competitive structure. Cornershop exemplifies the logistics-backbone model leveraging parent-company infrastructure for rapid fulfillment across Mexican and Chilean urban zones. Rappi anchors the super-app convergence tier, embedding grocery within broader on-demand services to deepen user retention and cross-sell adjacent financial products. Mercado Fresh represents the fresh-produce specialization archetype, sourcing direct from Brazilian agricultural cooperatives to reduce spoilage rates relative to conventional supermarket supply chains.
| Leading Market Players |
|---|
| Cornershop |
| Instacart |
| Rappi |
| Walmart Grocery |
| Amazon Grocery |
| Glovo |
| Mercadoni |
| Mercado Fresh |
| Uber Eats |
| Others |
Supply & Pricing Matrix
Dual-income household demand for fifteen-minute fulfillment windows in São Paulo and Mexico City forces operators to absorb dark-store rental premiums and gig-economy wage volatility, compressing margins and stratifying service tiers by speed.
Pricing Analysis
Lead-time compression commands premium positioning, with express slots priced above scheduled delivery windows that capture higher basket values through batch consolidation. Three-tier pricing structure across express, scheduled, and subscription levels reflects fulfillment infrastructure investment and cold-chain complexity. Pricing pressure stems from gig-economy labor turnover during peak windows in Brazilian metropolitan corridors. Young professionals exhibit highest price sensitivity for impulse orders, while family segments accept premium positioning for reliability.
Supply Chain Analysis
Multi-supplier qualification mandates from Brazilian agricultural cooperatives and Mexican retail banners reduce single-source vulnerability for fresh-produce categories. Geographic supply concentration centers on Brazil, Mexico, and Argentina for last-mile fleet equipment and temperature-controlled packaging. Raw material dependencies include refrigerated transport units, insulated packaging, and algorithmic routing software. Tariff exposure on Argentine import licensing for refrigeration equipment constrains fleet expansion timelines. Distribution runs through dark-store micro-fulfillment nodes positioned in dense urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated picking systems and predictive demand algorithms are displacing manual fulfillment labor, creating a technology-transition phase where capital deployment favors operators with robotic infrastructure and localized data compliance.
For Market Incumbents: Lock in dark-store density advantages in São Paulo's Pinheiros and Mexico City's Polanco districts before rental premiums escalate further. Anchor subscription retention through predictive replenishment algorithms that reduce customer acquisition costs. Vertical integration into Brazilian agricultural cooperatives secures fresh-produce margin advantages against supermarket banner extensions.
For New Entrants and Emerging Players: PROFECO consumer protection mandates in Mexico open a window for compliant operators to capture share from informal competitors lacking localized legal infrastructure. Target Colombian and Peruvian urban markets where subscription penetration remains underdeveloped relative to Brazilian baselines. Embed grocery within super-app architectures to cross-sell financial services and deepen user retention.
For Investors and Strategic Acquirers: The window for entry favors pure-play grocery specialists with cooperative sourcing relationships and ANPD-compliant data infrastructure. Long-term viability hinges on subscription revenue predictability and dark-store network effects rather than express delivery volume. Watch for inflection in gig-economy labor regulation as signal for margin structure stability.
| Strategic Initiative | Industry Significance |
|---|---|
| Dark-Store Network Expansion | Algorithmic inventory positioning in São Paulo and Mexico City enables fifteen-minute fulfillment windows at sustainable unit economics. |
| Subscription Service Penetration | Recurring revenue models in Colombian and Peruvian markets lock demand predictability for inventory planning and reduce acquisition costs. |
| Cooperative Sourcing Integration | Direct procurement from Brazilian agricultural cooperatives reduces spoilage rates and differentiates fresh-produce positioning. |
| Super-App Convergence | Embedding grocery within Rappi's broader on-demand architecture deepens retention and enables cross-selling of adjacent financial products. |
| ANPD Compliance Infrastructure | Localized data handling and server investment creates competitive moats against multinational entrants lacking Brazilian legal entities. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with dark-store operations managers, grocery platform executives, agricultural cooperative procurement leads, and last-mile logistics coordinators validated demand assumptions. Secondary sources included ANPD enforcement notices, PROFECO consumer complaint databases, Brazilian customs import records for refrigerated transport equipment, and municipal logistics subsidy disclosures. Bottom-up demand modeling triangulated against top-down market sizing from platform revenue disclosures and venture capital deployment tracking.
Granularity-level modeling captured service-type segmentation at the metropolitan corridor level, with product-type splits across fresh produce, packaged goods, dairy, and frozen categories. Customer-type archetypes included families, young professionals, seniors, and health-conscious consumers. Distribution channel modeling encompassed mobile apps, e-commerce websites, third-party platforms, and social media integration. CAGRs were derived from cohort-based adoption curves and infrastructure investment pipelines. Forecast inputs incorporated dark-store deployment timelines, gig-economy labor pool growth, and regulatory compliance cost trajectories across the projection horizon.
The model assumes a particular technology adoption path for automated picking systems; alternative pathways for robotic fulfillment would alter the outlook for labor cost compression and delivery speed viability. Forecasts reflect assumptions around household replenishment behavior shifts and regulatory enforcement intensity. A model refresh is warranted upon material change in ANPD data governance interpretation or gig-economy labor classification rulings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Asia-Pacific and Middle-East Inflight Catering Market
Food Service
Asia-Pacific Cloud Kitchen Market
Food Service
United States Smokeless Indoor Grills Market
Food Service
China Inflight Catering Market
Food Service
Hyperlocal Grocery Delivery Market
Food Service
Bahrain Food Service Market
Food Service
Global Self Heating Instant Hot Pot Market
Food Service
Pizza Foodservice Market
Food Service
Limited-Service Restaurants Market
Food Service
Commercial Sink Market
Food Service
Contract Blending Services Market
Food Service
Haute Cuisine Market
Food Service
Latin America Airport Quick Service Restaurant Market
Food Service
Air Fryer Market
Food Service
Bottled Water Cooler Market
Food Service
United Arab Emirates Full Service Restaurants Market