
 Calprotectin Testing Market | 2026-2036
Calprotectin Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Calprotectin Testing Market Analysis
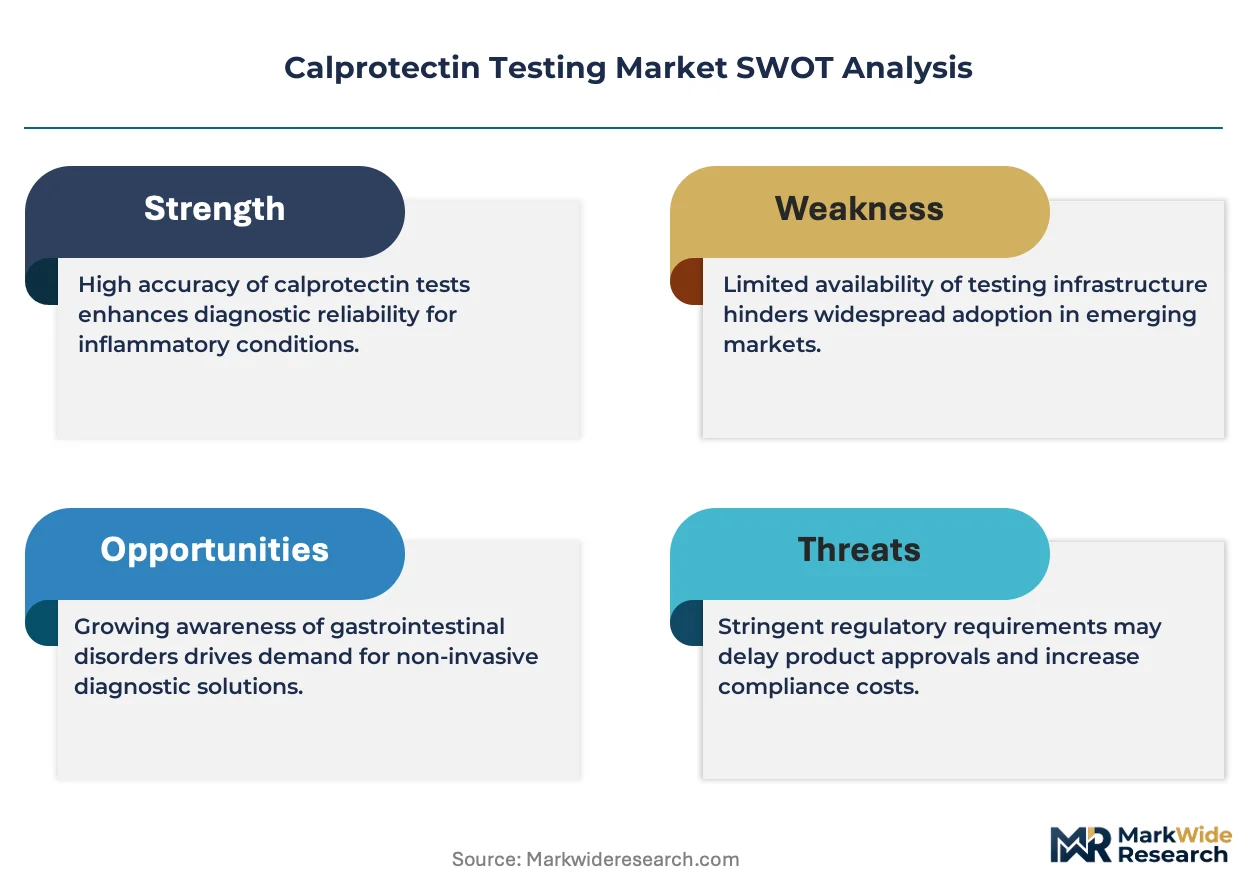
The EU In Vitro Diagnostic Regulation is restructuring procurement criteria for gastrointestinal biomarker assays across European hospital systems. DiaSorin leverages its chemiluminescence platform breadth to anchor automated calprotectin workflows in high-throughput laboratories. BÜHLMANN Laboratories specializes in quantitative fecal calprotectin ELISA formats that sustain strong positions in reference lab networks. R-Biopharm competes through integrated assay-reagent-instrument bundles that control total cost-per-test metrics for mid-volume sites.
Calprotectin testing measures the S100A8/A9 heterodimer complex in fecal or serum specimens to quantify neutrophil-driven intestinal inflammation with ng/g sensitivity thresholds. Manufacturers typically employ monoclonal antibody capture systems on polystyrene microplate or lateral flow membranes, with chromogenic or fluorescent readout modalities calibrated against WHO reference standards. ELISA formats currently occupy the largest installed base among product types due to established reimbursement codes and laboratory familiarity, while lateral flow assays represent the fastest-expanding segment as point-of-care adoption accelerates in gastroenterology clinics. Among applications, inflammatory bowel disease monitoring commands the deepest margin pools because of chronic patient monitoring frequency and guideline-mandated testing intervals.
FDA 510(k) clearance pathways and Clinical Laboratory Improvement Amendments shape analytical validation requirements for calprotectin devices entering the United States market. The EU IVDR imposes notified body oversight and performance study documentation that extends development timelines but elevates barrier-to-entry for non-compliant manufacturers. Japan's PMDA enforces Japan-specific clinical evidence standards for fecal biomarker diagnostics that filter market access. Stakeholders must monitor evolving guideline revisions from the American Gastroenterological Association and European Crohn's and Colitis Organisation that directly determine test-ordering volume and reimbursement durability.
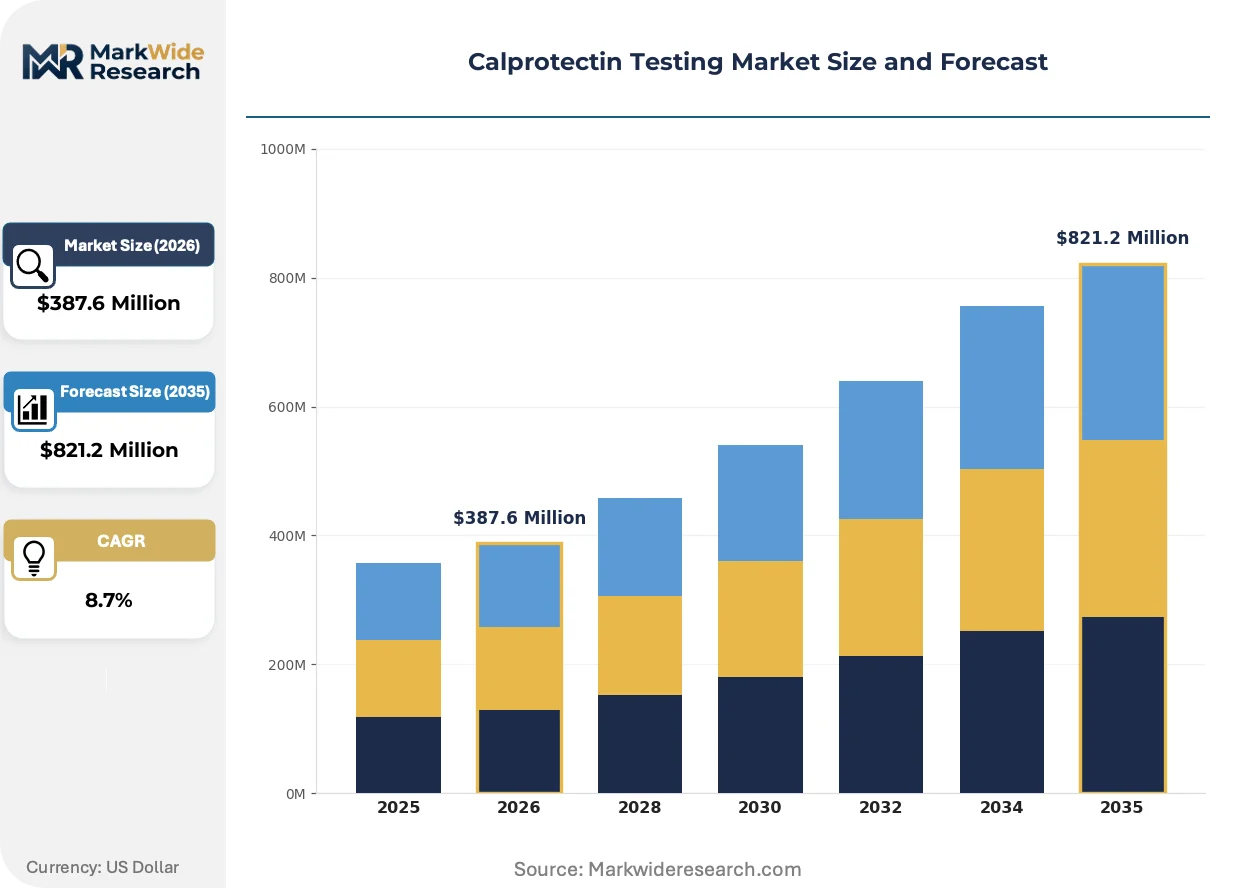
Market Dynamics
The EU In Vitro Diagnostic Regulation is compressing development timelines while elevating performance-study documentation requirements, forcing manufacturers to consolidate assay portfolios around high-throughput automated platforms.
Growth Catalysts
- Non-invasive IBD monitoring protocols:Clinical guidelines from the European Crohn's and Colitis Organisation now prioritize fecal biomarker testing over endoscopy-first pathways, expanding test-ordering volume in gastroenterology clinics.
- Point-of-care lateral flow expansion:Rapid cartridge formats are penetrating physician office laboratories, enabling same-result consultation workflows that accelerate patient management decisions.
- Reimbursement code consolidation:CPT coding updates in the United States have stabilized coverage for quantitative calprotectin assays, reducing prior-authorization friction for hospital outpatient departments.
Market Restraints
- Monoclonal antibody supply concentration:Capture antibody production concentrates among contract manufacturers in Switzerland and Germany, creating input vulnerability for assay developers.
- EU IVDR notified body bottleneck:Limited designated conformity assessment capacity extends certification timelines by 12-18 months for novel quantitative immunoassay submissions.
- Endoscopy service line economics:Hospital systems retain financial incentives to maintain procedural revenue from colonoscopy, creating institutional resistance to biomarker-first substitution.
Strategic Opportunities
- Pediatric IBD screening protocols:Underpenetrated diagnostic pathways in children with suspected inflammatory bowel disease present volume expansion potential as non-invasive alternatives to sedation-requiring endoscopy.
- Serum calprotectin assay development:Liquid biopsy formats for systemic inflammation monitoring could capture rheumatology and critical care applications beyond gastrointestinal indications.
- Japan PMDA biomarker qualification:Early engagement with Japan's pharmaceutical regulator on fecal biomarker clinical evidence standards offers first-mover positioning in the Asia-Pacific's second-largest diagnostic market.
Industry Challenges
- Cross-platform standardization gaps:Variability between ELISA, chemiluminescence, and lateral flow quantitative outputs complicates longitudinal patient monitoring when laboratories switch methods.
- WHO reference material access:Limited commercial availability of certified calprotectin reference standards delays in-house assay validation for mid-size diagnostic manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calprotectin Testing Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ELISA, Lateral Flow Assays, Rapid Tests, Immunoassays End User: Hospitals, Diagnostic Laboratories, Research Facilities, Homecare Settings Application: Inflammatory Bowel Disease, Gastrointestinal Disorders, Autoimmune Diseases, Cancer Screening Distribution Channel: Online Sales, Direct Sales, Retail Pharmacies, Distributors |
| Companies Covered | DiaSorin, Euroimmun, BÜHLMANN Laboratories, Biohit, Boditech Med, Svar Life Science, R-Biopharm, Actim, ALPCO Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calprotectin Testing Market Emerging Trajectories
Automation and regulatory harmonization are compressing the gap between centralized reference laboratory performance and distributed point-of-care testing capabilities.
Random-access chemiluminescence immunoassay analyzers are electrifying workflow efficiency in high-throughput hospital laboratories. These systems process calprotectin alongside 50-plus other inflammatory and infectious markers on a single instrument platform. Large integrated delivery networks in the United States and Germany are consolidating fecal biomarker testing onto such multi-analyte lines, reducing dedicated technician labor and floor space requirements.
The EU In Vitro Diagnostic Regulation's Common Specifications for class C devices impose clinical evidence thresholds that previously applied only to novel biomarkers. Manufacturers must now generate analytical and clinical performance studies even for established fecal calprotectin assays seeking IVDR certification. This regulatory elevation is filtering the competitive landscape toward firms with dedicated clinical affairs infrastructure and European authorized representative networks.
Gastroenterology clinics are unbundling diagnostic testing from endoscopy suite scheduling, establishing standalone biomarker collection protocols that decouple screening from procedural slots. Patients complete at-home stool sample collection with prepaid return logistics, receiving quantitative results before specialist consultation. This consumption-pattern shift is most visible in the Netherlands and Denmark, where national health IT infrastructure supports asynchronous result delivery and automated triage algorithms.
Calprotectin Testing Market Segmentation
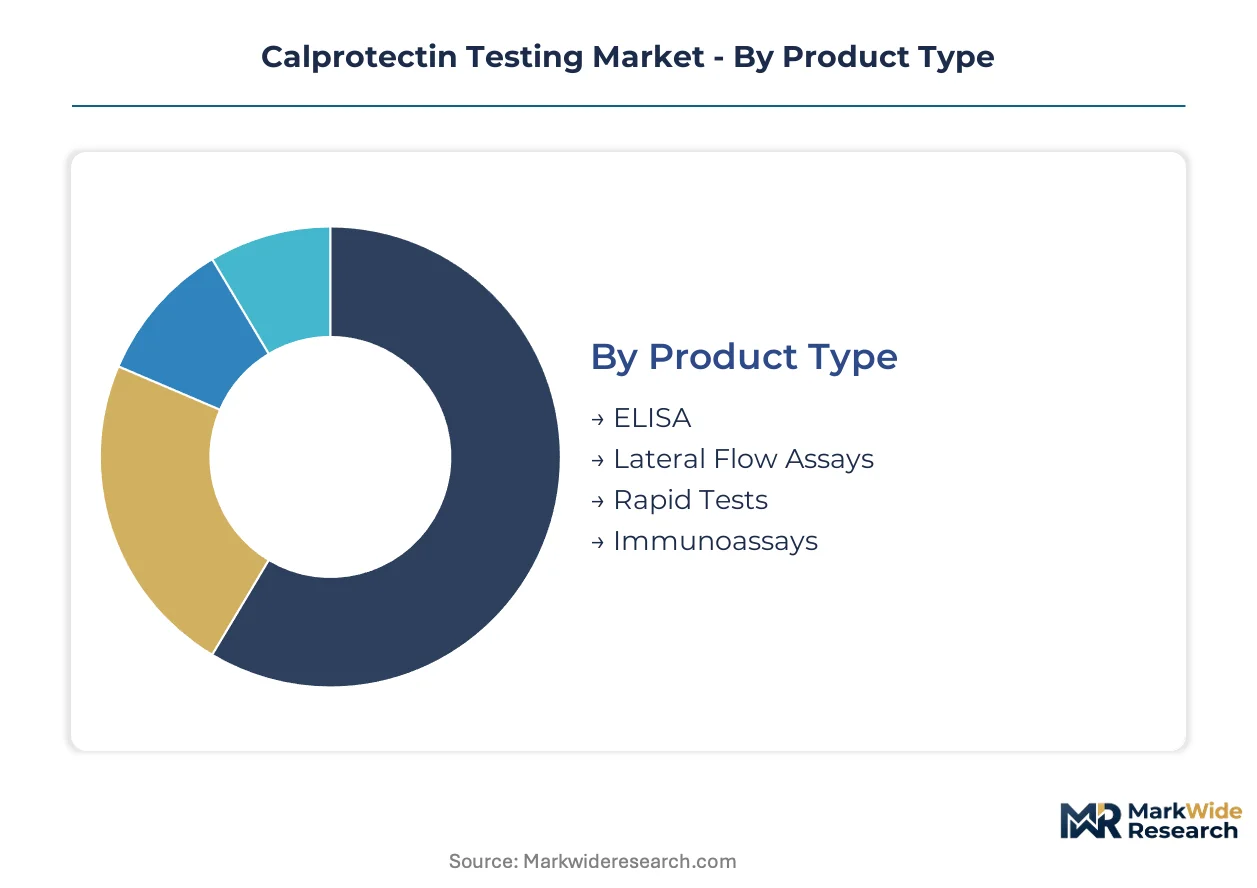
Calprotectin testing segments diverge sharply in regulatory burden and reimbursement pathways. ELISA formats carry established CPT codes in the United States, while lateral flow devices face steeper clinical evidence demands under EU IVDR Class C requirements.
Product Type:
FDA 510(k) clearances dominate ELISA and chemiluminescence pathways, whereas lateral flow assays trigger stricter Clinical Laboratory Improvement Amendments scrutiny for waived versus moderate-complexity classification.
- ELISA:Polystyrene microplate formats with chromogenic readout calibrated against WHO reference standards. Demand concentrates in hospital-affiliated diagnostic networks across Germany and the United States, driven by established reimbursement codes and laboratory familiarity with open-system automation.
- Lateral Flow Assays:Rapid cartridge membranes employing monoclonal antibody capture with fluorescent or visual endpoint detection. Gastroenterology clinics in the Netherlands and Denmark are adopting these for same-result consultation workflows, though IVDR performance-study documentation extends European launch timelines.
- Rapid Tests:Qualitative point-of-care formats targeting physician office laboratories seeking waived-complexity status under CLIA regulations.
- Immunoassays:Automated chemiluminescence platforms processing calprotectin alongside multi-analyte inflammatory panels in high-throughput hospital laboratories.
Leading the category by volume: ELISA. Growing fastest: Lateral Flow Assays.
End User:
Procurement authority shifts dramatically across settings—hospital systems negotiate enterprise contracts, while homecare channels rely on direct-to-patient logistics and asynchronous result delivery.
- Hospitals:Integrated delivery networks in the United States and Germany consolidate testing onto random-access analyzers, reducing dedicated technician labor through multi-analyte line consolidation.
- Diagnostic Laboratories:Reference lab networks sustain quantitative ELISA volumes through contracted service agreements with gastroenterology practices.
- Research Facilities:Academic medical centers drive assay validation studies for novel serum calprotectin applications beyond gastrointestinal indications.
- Homecare Settings:At-home stool collection with prepaid return logistics is penetrating pediatric IBD screening protocols, decoupling diagnostic testing from endoscopy suite scheduling.
Highest absolute spend: Hospitals. Steepest expansion trajectory: Homecare Settings.
Application:
Margin pools correlate directly with monitoring frequency—chronic conditions generate recurring revenue, while screening applications face episodic demand and price compression.
- Inflammatory Bowel Disease:Chronic patient monitoring with guideline-mandated testing intervals commands the deepest margin pools in gastroenterology practice economics.
- Gastrointestinal Disorders:Functional GI conditions with ambiguous diagnostic criteria drive variable test-ordering patterns and reimbursement uncertainty.
- Autoimmune Diseases:Rheumatology applications for serum calprotectin represent emerging volume beyond traditional fecal testing.
- Cancer Screening:Colorectal neoplasia detection protocols compete with established fecal immunochemical testing for inclusion in preventive care guidelines.
Deepest revenue concentration: Inflammatory Bowel Disease. Gaining share fastest: Autoimmune Diseases.
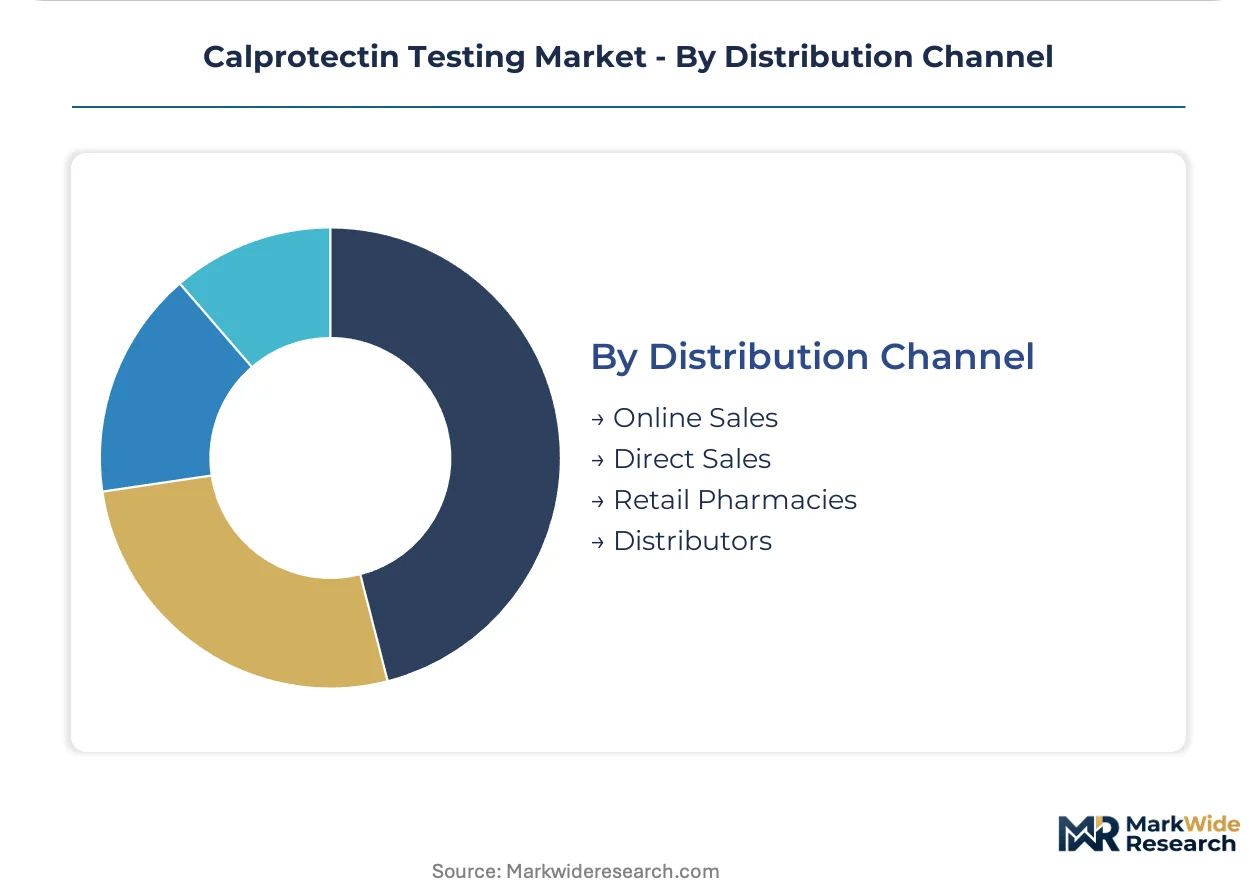
Distribution Channel:
Channel economics reflect inventory carrying costs and technical support requirements—complex assays demand field service presence, while commoditized formats shift toward e-commerce.
- Online Sales:Direct-to-patient platforms for home collection kits are expanding in Denmark and the Netherlands where national health IT infrastructure supports asynchronous result delivery.
- Direct Sales:Manufacturer field organizations serve high-throughput hospital laboratories with integrated instrument-reagent contracts.
- Retail Pharmacies:Over-the-counter rapid test availability remains limited by FDA and EU IVDR device classification requirements.
- Distributors:Regional medical-surgical distributors dominate mid-volume diagnostic laboratory procurement in fragmented European markets.
Dominant by transaction volume: Direct Sales. Expanding most quickly: Online Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors clinical biomarker development with Massachusetts General Hospital's gastroenterology research corridor driving protocol standardization for fecal calprotectin monitoring.
United States
Hospital-affiliated diagnostic networks in the United States consolidate testing onto automated platforms as gastroenterology clinics adopt at-home collection protocols. FDA 510(k) clearance pathways and CLIA complexity classifications shape device market entry requirements. The Mayo Clinic in Rochester, Minnesota validates multi-analyte integration workflows that reduce dedicated technician labor.
Germany
Reference laboratory networks across Germany sustain quantitative ELISA volumes through contracted service agreements with gastroenterology practices. EU IVDR notified body oversight extends certification timelines for novel assay submissions. The Rhine-Main metropolitan region around Frankfurt concentrates high-throughput diagnostic infrastructure serving hospital systems.
Japan
PMDA clinical evidence standards filter market access for fecal biomarker diagnostics entering the Asia-Pacific's second-largest diagnostic market. Tokyo's academic medical centers drive assay validation studies for novel serum calprotectin applications. The Kanto region's integrated delivery networks prioritize multi-analyte chemiluminescence platforms.
Netherlands
National health IT infrastructure supports asynchronous result delivery and automated triage algorithms across Dutch gastroenterology clinics. At-home stool collection with prepaid return logistics decouples diagnostic testing from endoscopy suite scheduling. Amsterdam's diagnostic networks pioneer same-result consultation workflows using lateral flow formats.
Denmark
Pediatric IBD screening protocols expand non-invasive alternatives to sedation-requiring endoscopy in Danish healthcare regions. Direct-to-patient platforms for home collection kits leverage national digital health infrastructure. Copenhagen's hospital systems consolidate biomarker-first substitution pathways reducing procedural dependency.
Calprotectin Testing Market Vendor Landscape
Premium-margin players sit above commodity-margin players across automation capability and regulatory compliance infrastructure. The vendor base stratifies between high-throughput platform specialists and point-of-care rapid test developers. Three archetypes dominate: integrated instrument-reagent bundlers, reference laboratory service providers, and lateral flow cartridge specialists. Consolidation pressures favor M&A activity among mid-size assay developers and strategic partnerships between manufacturers and diagnostic distribution networks.
Among European-based diagnostic specialists, DiaSorin, BÜHLMANN Laboratories, and R-Biopharm occupy distinct positioning archetypes. DiaSorin exemplifies the multi-analyte platform bundler with chemiluminescence infrastructure spanning inflammatory marker menus. BÜHLMANN Laboratories represents the reference laboratory-focused quantitative ELISA specialist sustaining contracted service relationships. R-Biopharm anchors the integrated assay-reagent-instrument tier controlling total cost-per-test economics for mid-volume installation sites.
| Leading Market Players |
|---|
| DiaSorin |
| Euroimmun |
| BÜHLMANN Laboratories |
| Biohit |
| Boditech Med |
| Svar Life Science |
| R-Biopharm |
| Actim |
| ALPCO Diagnostics |
| Others |
Supply Flow & Price Mechanics
Monoclonal antibody production specialists concentrated in Switzerland and Germany command wage premiums that compress margin spreads between economy-tier lateral flow assays and premium chemiluminescence platforms. Labor-cost differentials between Basel-region biologics manufacturers and Southern European contract producers feed directly into tiered reagent pricing structures across the European diagnostic market.
Pricing Analysis
Value-based pricing anchored to test throughput and laboratory workflow efficiency separates premium automated platforms from manual ELISA formats. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade under EU IVDR and volume-scale commitments. Cost compression in economy-tier lateral flow segments is intensifying because of antibody input scarcity and notified body certification backlogs. Hospital-affiliated diagnostic networks exhibit lowest price sensitivity due to bundled instrument-reagent contracts, while physician office laboratories face acute budget constraints driving rapid test commoditization.
Supply Chain Analysis
Dual-sourcing requirements for monoclonal antibody capture reagents mandate multi-supplier qualification across Swiss and German contract manufacturers, extending procurement cycles for assay developers. Geographic supply concentration centers on Switzerland, Germany, and Denmark for antibody production, with polystyrene microplate substrates drawing from Chinese and U.S. molded plastics suppliers. Single-source vulnerability in high-affinity monoclonal antibody clones creates input risk for novel assay launches. Distribution runs through regional medical-surgical distributors in fragmented European markets, with direct sales dominating high-throughput hospital laboratory procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU IVDR compliance costs are forcing consolidation among mid-size assay developers without dedicated clinical affairs infrastructure. Regulatory elevation filters the competitive landscape toward scale players with European authorized representative networks.
For Market Incumbents: To counter lateral flow commoditization in physician office laboratories, incumbents should deepen backward integration into monoclonal antibody production through captive supply agreements with Swiss contract manufacturers. Second, anchor hospital system loyalty through multi-analyte platform bundling that consolidates fecal biomarker testing with infectious disease and inflammatory marker menus. For New Entrants and Emerging Players: Enter via pediatric IBD screening protocols in Denmark and the Netherlands, where national digital health infrastructure supports at-home collection workflows decoupled from endoscopy scheduling. Target homecare settings with direct-to-patient logistics partnerships, leveraging prepaid return sample infrastructure already validated in Dutch gastroenterology networks. For Investors and Strategic Acquirers: The window for entry favors mid-cap quantitative ELISA specialists with established WHO reference standard calibration and contracted service relationships with German reference laboratory networks. Long-term viability hinges on IVDR certification completion timelines and serum calprotectin assay development pipelines. The signal to watch is PMDA biomarker qualification progress in Japan, which would unlock Asia-Pacific expansion for first movers with liquid biopsy formats.| Strategic Initiative | Industry Significance |
|---|---|
| EU IVDR Certification Completion | Notified body approval unlocks European hospital system procurement and reimbursement durability. |
| Serum Calprotectin Assay Development | Liquid biopsy formats capture rheumatology and critical care applications beyond gastrointestinal indications. |
| Multi-Analyte Platform Integration | Random-access chemiluminescence consolidation reduces dedicated technician labor in high-throughput laboratories. |
| Pediatric IBD Screening Protocol Partnership | Danish and Dutch national health IT infrastructure enables at-home collection with asynchronous result delivery. |
| Japan PMDA Biomarker Qualification | Early regulatory engagement positions first-mover advantage in Asia-Pacific's second-largest diagnostic market. |
Methodological Framework
Multi-period observation of test-ordering volume shifts and reimbursement code consolidation anchored the trend analysis, supplemented by interviews with hospital laboratory directors, gastroenterology practice administrators, diagnostic manufacturer regulatory affairs leads, and GPO contracts managers. Secondary validation drew from FDA 510(k) clearance databases, EU IVDR notified body certification records, CMS Medicare reimbursement schedules, and hospital procurement database aggregators. Bottom-up test volume modeling and top-down market sizing triangulated segment-level outputs.
Segment-weighting across product type, end user, application, and distribution channel dimensions shaped the analytical framework throughout the projection horizon. Modeled dimensions included ELISA versus lateral flow versus chemiluminescence platform categories, hospital versus homecare versus diagnostic laboratory settings, IBD monitoring versus emerging autoimmune applications, and direct sales versus distributor versus online channel pathways. CAGRs were derived from test volume growth trajectories calibrated against guideline-mandated monitoring frequency and point-of-care adoption curves. Forecast inputs incorporated EU IVDR implementation timelines and PMDA biomarker qualification pathway developments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged notified body bottlenecks or accelerated endoscopy-first pathway reversals in hospital systems defending procedural revenue. A model refresh is warranted upon material change in American Gastroenterological Association or European Crohn's and Colitis Organisation guideline revisions that directly determine test-ordering volume and reimbursement durability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Pharmaceutical Dosage Form Testing Systems Market
Testing Services
Global Specimen Validity Testing Market
Testing Services
Monkeypox Testing Market
Testing Services
Global Helicobacter Pylori (H. Pylori) Non-Invasive Testing Market
Testing Services
Ferritin Testing Market
Testing Services
Ready-To-Use Laboratory Test Kits Market
Testing Services
Global Endocrine Testing Market
Testing Services
Global CA 125 Test Market
Testing Services
Anti-Nuclear Antibody (ANA) Testing Market
Testing Services
IVD Quality Control Market
Testing Services
Platelet Function Testing Market
Testing Services
Thrombophilia Testing Market
Testing Services
Global Mycoplasma Testing Market
Testing Services
Nucleic Acid Testing Market
Testing Services
North America Newborn Screening Market
Testing Services
Staphylococcus Aureus Testing Market