
 Oral Transmucosal Drugs Market | 2026-2036
Oral Transmucosal Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Oral Transmucosal Drugs Market Analytics
CE marking under the EU Medical Device Regulation is rotating competitive access for European manufacturers of drug-device combination products. Aquestive Therapeutics leverages its PharmFilm technology platform to sustain leadership in buccal film manufacturing scale. LTS Lohmann Therapie-Systeme AG anchors transatlantic supply through specialized oral dissolvable film capacity. BioDelivery Sciences International differentiates via BEMA drug delivery technology for pain and addiction therapy segments.
Oral transmucosal drugs administer therapeutic agents through the mucosal surfaces of the oral cavity, bypassing hepatic first-pass metabolism to achieve rapid systemic absorption with bioavailability typically ranging from 30% to 90% depending on molecular properties and mucosal contact duration. These formulations serve patients requiring swift onset, gastrointestinal intolerance, or needle-free administration across anesthesia, breakthrough pain, and emergency neurological intervention. Buccal films command expanding share in pain management due to controlled dissolution profiles and patient compliance advantages over conventional tablets. Sublingual tablets dominate hormonal therapy where precise dosing and rapid absorption prove clinically critical. Liquid formulations retain stronghold in pediatric and geriatric homecare settings where swallowing difficulties limit solid dosage form utility.
The FDA governs transmucosal products through 505(b)(2) new drug applications and combination product regulations, while the EMA applies MDR and pharmaceutical quality guidelines to oromucosal preparations entering European markets. REACH chemical safety requirements and USP dissolution standards further constrain excipient selection and manufacturing process validation. Stakeholders must monitor evolving bioequivalence guidance for complex generic transmucosal formulations and prepare for tightened endotoxin specifications as sterile manufacturing claims expand across the category.
Market Dynamics
The FDA's 505(b)(2) pathway is compressing reformulation timelines for transmucosal platforms while hospital emergency departments accelerate buccal film procurement for seizure protocols. This regulatory velocity is concentrating competitive advantage among manufacturers with pre-validated mucoadhesive film infrastructure.
Growth Catalysts
- Regulatory Streamlining:The FDA's 505(b)(2) new drug application pathway reduces clinical data requirements for reformulated transmucosal products, accelerating time-to-market for buccal film generics.
- Hospital Protocol Expansion:Emergency medicine departments in the United States are standardizing buccal midazolam administration for pediatric status epilepticus, creating institutional demand pull.
- Needle-Avoidance Preference:Chronic pain and opioid dependence treatment protocols favor non-invasive administration, positioning sublingual buprenorphine-naloxone films as first-line maintenance therapy.
Market Restraints
- Excipient Supply Concentration:Specialized mucoadhesive polymers and film-forming agents concentrate among European and Japanese chemical suppliers, creating input vulnerability.
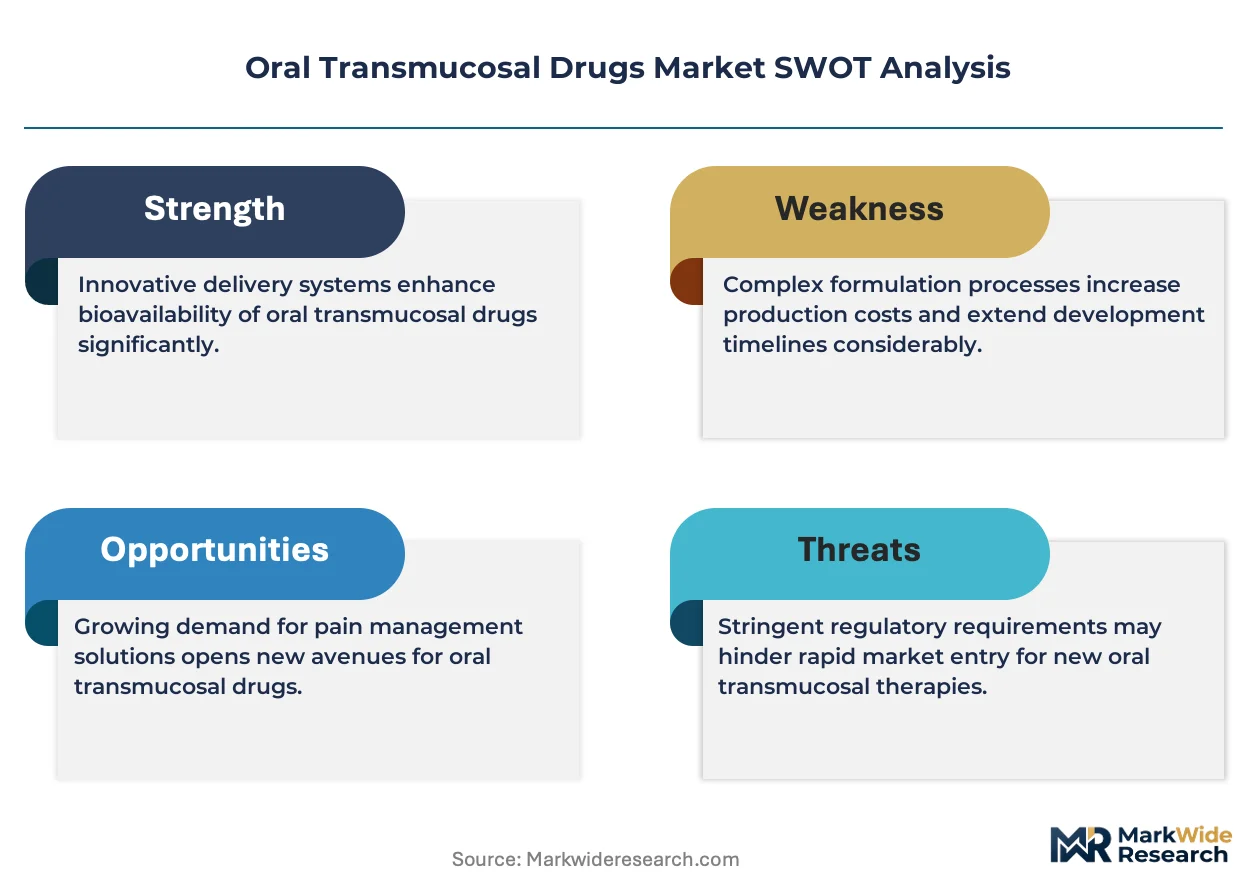
- MDR Compliance Burden:The EU Medical Device Regulation's CE marking requirements for drug-device combinations extend validation timelines and inflate regulatory expenditure for European market entry.
- Oral Dissolving Tablet Substitution:Conventional ODT formulations using superdisintegrants compete on manufacturing simplicity and lower unit economics, pressuring film-based platforms in price-sensitive segments.
Strategic Opportunities
- Pediatric Homecare Expansion:Liquid transmucosal formulations for breakthrough pain and antiemetic therapy address swallowing difficulties in pediatric oncology, an underpenetrated indication cluster.
- EMA Orphan Designation Pathway:The European Medicines Agency's incentives for rare disease therapeutics create regulatory tailwinds for buccal films targeting small-population neurological conditions.
- Telehealth Distribution Integration:Direct-to-patient pharmacy models for maintenance addiction therapy bypass traditional clinic-based dispensing, expanding reach for sublingual product lines.
Industry Challenges
- Bioequivalence Validation Complexity:Demonstrating equivalence for complex generic transmucosal formulations requires specialized clinical pharmacology expertise and extended study protocols.
- Sterile Manufacturing Scale-Up:Transitioning from standard oral solid dosage facilities to endotoxin-controlled environments for sterile film claims demands significant capital redeployment and process revalidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oral Transmucosal Drugs Market |
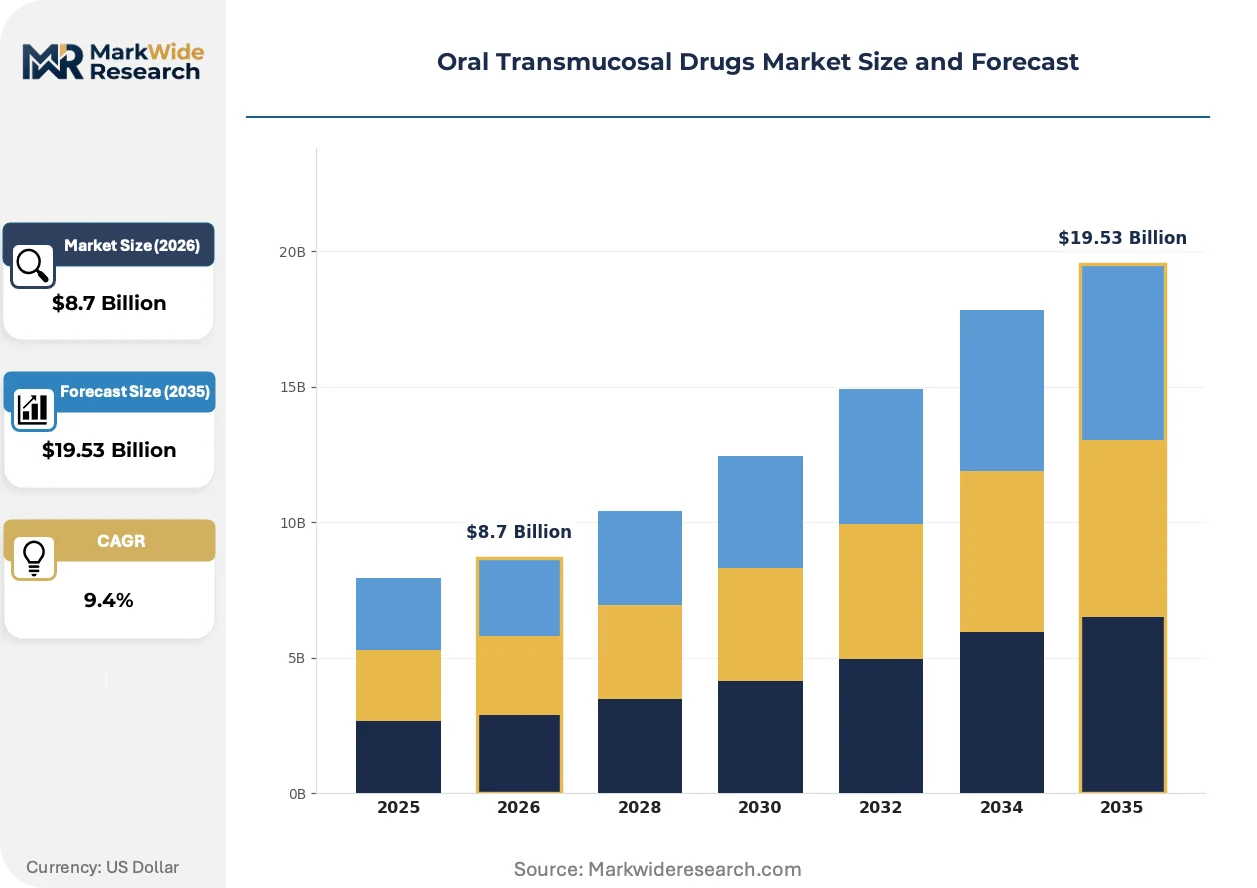
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sublingual Tablets, Buccal Films, Oral Sprays, Lozenges Therapy Area: Anesthesia, Pain Management, Hormonal Therapy, Neurological Disorders End User: Hospitals, Clinics, Homecare, Pharmacies Formulation Type: Liquid Formulations, Solid Formulations, Gel Formulations, Powder Formulations |
| Companies Covered | ZIM Laboratories Limited, Aquestive Therapeutics, Inc., IntelGenx Corp., Sunovion Pharmaceuticals, Inc., LTS Lohmann Therapie-Systeme AG, C.L. Pharm, Cure Pharmaceutical, Indivior PLC, BioDelivery Sciences International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oral Transmucosal Drugs Market Evolving Landscape
Multilayer mucoadhesive film architectures are displacing conventional single-layer designs by enabling incompatible drug combinations and controlled release profiles within one dosage unit. This platform evolution is compressing development cycles and expanding therapeutic reach.
Nanocrystal dispersion technology is displacing conventional salt-formulation approaches for poorly soluble APIs in buccal films. Manufacturers are integrating high-shear homogenization and spray-drying capabilities to achieve particle sizes below 400 nanometers. Hospital formularies are prioritizing these enhanced-bioavailability products for rapid-onset analgesia and emergency neurological intervention.
The EMA's tightened endotoxin specifications for oromucosal preparations are forcing manufacturing retrofits across European supply chains. Facilities previously validated for standard oral solids must install depyrogenation tunnels and closed aseptic processing lines. German and Swiss contract manufacturers are capturing restructuring expenditure through specialized sterile film capacity.
Patient-administered therapy models for addiction maintenance are compressing traditional clinic-visit frequencies. Sublingual buprenorphine protocols now permit monthly or bimonthly pharmacy pickup with remote monitoring, displacing weekly supervised dosing. This pattern concentrates most visibly in United States Medicaid programs and United Kingdom opioid substitution services.
Oral Transmucosal Drugs Market Segmentation
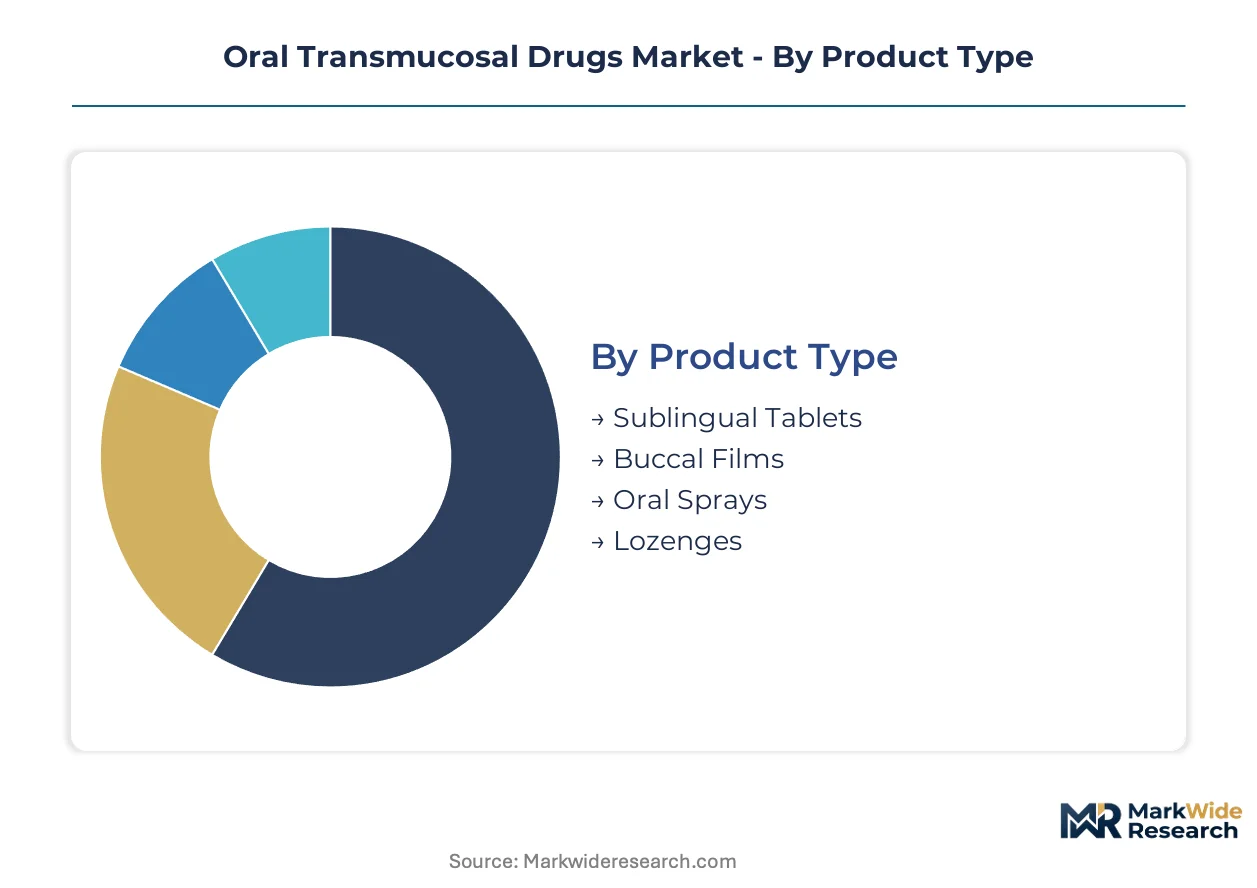
Oral transmucosal drug segmentation reveals distinct channel affinities that shape commercial strategy. Product format dictates whether formulations reach patients through institutional procurement, retail pharmacy networks, or direct-to-patient subscription models.
Product Type:
Hospital emergency departments and retail pharmacies split procurement volume across these formats based on onset speed requirements and storage infrastructure.
- Buccal Films:Mucoadhesive polymer matrices dissolve against the cheek mucosa over 5-30 minutes, enabling controlled release of high-potency APIs. Demand concentrates in United States hospital formularies where midazolam films for pediatric status epilepticus bypass IV setup delays. The FDA's 505(b)(2) pathway accelerates generic entry for this format.
- Sublingual Tablets:Compressed dosage forms placed under the tongue achieve rapid systemic absorption through the ventral tongue's dense vascularization. Pain management protocols in United States addiction treatment centers favor buprenorphine-naloxone sublingual tablets for take-home dispensing compliance.
- Oral Sprays:Metered-dose pump systems deliver atomized drug particles to the buccal or sublingual mucosa. Geriatric homecare settings in Germany and Japan adopt sprays where swallowing dysfunction limits solid dosage form utility.
- Lozenges:Hard candy matrices dissolve slowly to provide sustained mucosal contact for local or systemic drug delivery. Pediatric oncology units in France and Italy utilize medicated lozenges for breakthrough pain with reduced choking risk.
By volume, sublingual tablets lead. By growth pace, buccal films are expanding most quickly.
Therapy Area:
Reimbursement intensity and clinical urgency create four distinct margin tiers across therapeutic applications.
- Pain Management:Opioid and non-opioid analgesics delivered transmucosally address breakthrough cancer pain and chronic non-malignant pain where GI intolerance or rapid onset needs exist. United States Medicaid and commercial formularies increasingly require transmucosal alternatives to injectable products for cost containment.
- Neurological Disorders:Anticonvulsant and anxiolytic formulations target emergency seizure termination and acute agitation. Buccal midazolam protocols in United Kingdom ambulance services and United States pediatric emergency departments drive institutional procurement volume.
- Anesthesia:Preoperative anxiolysis and intraoperative adjunctive sedation utilize sublingual benzodiazepines and dissociative agents. Ambulatory surgery centers in Germany and Switzerland favor transmucosal premedication to reduce IV line placement in anxious patients.
- Hormonal Therapy:Sublingual estradiol and testosterone formulations bypass hepatic first-pass metabolism to achieve more stable serum levels. Gender-affirming care clinics in Spain and Netherlands prescribe these for patients seeking alternative to parenteral or transdermal routes.
Pain management commands the highest revenue per unit dose. Neurological applications show the steepest expansion trajectory.
End User:
Patient acuity and regulatory oversight intensity separate these channels into distinct operational requirements.
- Hospitals:Acute care institutions with 24-hour pharmacy services and crash cart standardization. United States Level I trauma centers and United Kingdom NHS Trusts maintain buccal midazolam and fentanyl film stocks for emergency protocols.
- Homecare:Patient-directed administration settings including hospice and long-term care. German Pflegekassen reimbursement policies increasingly cover transmucosal breakthrough pain medications for home-based palliative care.
- Clinics:Outpatient facilities with supervised dosing requirements. Opioid treatment programs in France and Italy utilize clinic-based sublingual buprenorphine induction before transitioning to take-home privileges.
- Pharmacies:Community and specialty retail dispensing with direct patient counseling. United States pharmacy benefit managers negotiate exclusive sublingual film formulary placement for addiction maintenance therapy.
Hospitals dominate absolute procurement volume. Homecare channels are gaining share fastest as telehealth-integrated dispensing expands.
Formulation Type:
Manufacturing complexity and stability requirements create divergent supply chain economics across physical states.
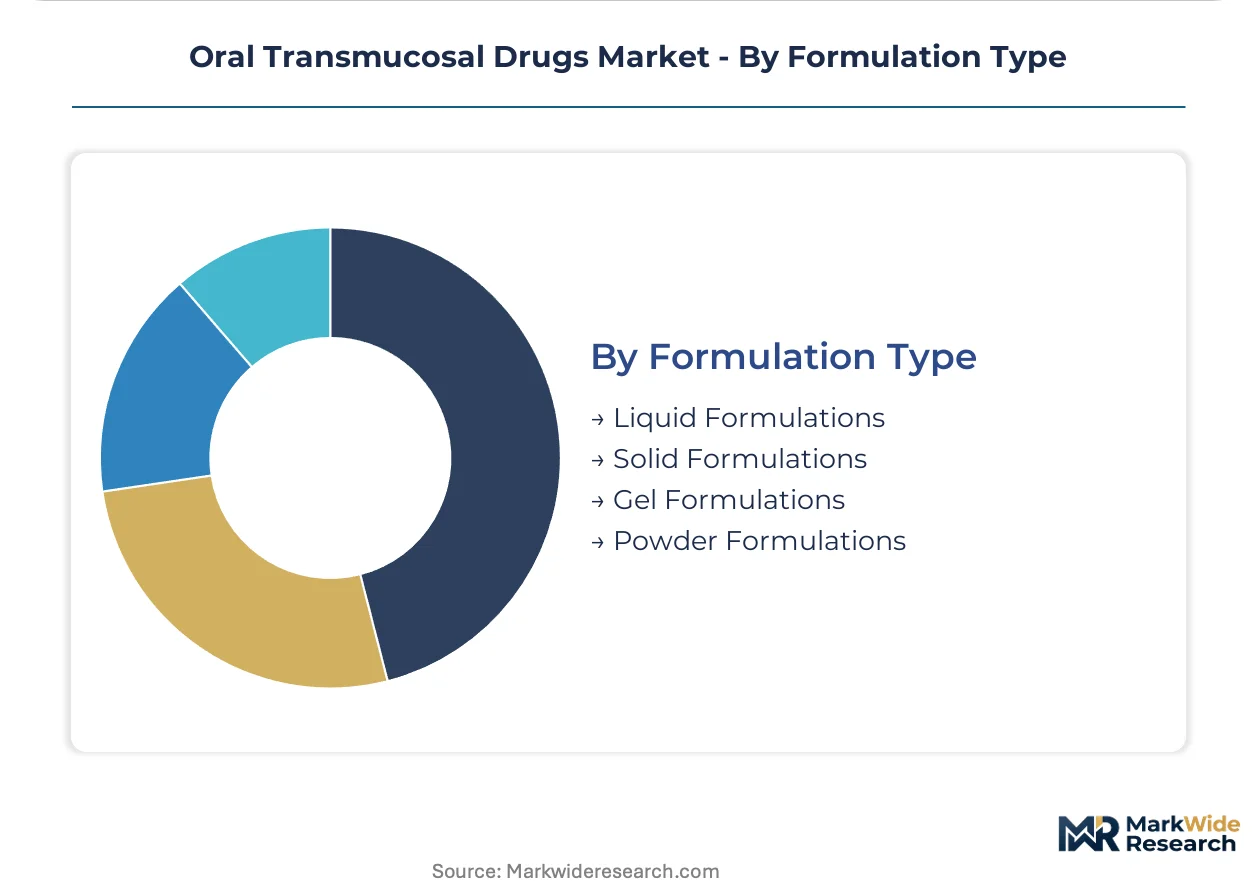
- Solid Formulations:Tablets, films, and lozenges with defined dissolution profiles and extended shelf stability. Contract manufacturers in Switzerland and Germany specialize in multilayer mucoadhesive film production for European and export markets.
- Liquid Formulations:Solutions and suspensions for pediatric, geriatric, and dysphagic populations. Japanese pharmaceutical companies lead in preservative-free oral spray technologies for sensitive patient groups.
- Gel Formulations:Semisolid mucoadhesive preparations for localized buccal delivery or extended contact time. Compounding pharmacies in United States and Australia customize gel formulations for rare disease patients with swallowing disorders.
- Powder Formulations:Micronized or spray-dried particles for reconstitution or direct sublingual application. Limited commercial presence due to dosing precision challenges and patient acceptance barriers in most therapeutic areas.
Solid formulations lead by manufacturing scale. Liquid formats are climbing the fastest as pediatric indication expansion accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold chain infrastructure underwrites Europe's distribution dominance for temperature-sensitive transmucosal films. FedEx Express hubs at Memphis and Indianapolis anchor North American just-in-time hospital replenishment. The Shanghai Yangshan deep-water port's bonded pharmaceutical zones expedite API importation for Asia-Pacific formulation.
United States
Medicaid expansion in 40 states drives sublingual buprenorphine volume for opioid substitution therapy. The FDA's 505(b)(2) pathway compresses generic approval timelines for buccal film reformulations. Philadelphia's contract manufacturing cluster hosts endotoxin-controlled facilities serving hospital emergency department procurement.
Germany
Pflegekassen reimbursement policies cover homecare transmucosal breakthrough pain medications for palliative patients. The EU MDR's CE marking requirements extend validation timelines for drug-device combination products. Baden-Württemberg's specialized polymer suppliers concentrate mucoadhesive excipient production for European film manufacturers.
Japan
Aging demographics and dysphagia prevalence expand oral spray demand in geriatric long-term care facilities. PMDA's streamlined review pathways for pediatric formulations accelerate transmucosal antiemetic approvals. Osaka's pharmaceutical manufacturing corridor specializes in preservative-free liquid technologies for sensitive patient populations.
United Kingdom
NHS ambulance services standardize buccal midazolam protocols for pediatric status epilepticus pre-hospital care. The MHRA's post-Brexit regulatory autonomy permits faster adoption of EMA-approved transmucosal generics. London's hospital procurement consortia negotiate exclusive buccal film formularies for emergency medicine.
India
CDSCO's accelerated approval pathways for essential medicines prioritize transmucosal anticonvulsant manufacturing. Government PLI scheme incentives attract domestic film-forming capacity for export markets. Hyderabad's active pharmaceutical ingredient cluster supplies specialized polymers to European and North American contract manufacturers.
Oral Transmucosal Drugs Market Competitive Landscape
Listed leaders compete with private specialists across mucoadhesive technology platforms and regulatory submission velocity. The market structures around three tiers: integrated film technology platforms, regional contract manufacturing organizations, and niche indication specialists. Two dominant competitive moves concentrate competitive advantage: vertical integration into specialized polymer supply and strategic partnerships with hospital procurement networks.
Within the integrated technology tier, Aquestive Therapeutics and LTS Lohmann Therapie-Systeme AG exemplify platform-scale competitors with validated manufacturing infrastructure. BioDelivery Sciences International occupies a position among indication-focused specialists leveraging differentiated delivery technology. These three anchors represent divergent strategic postures—platform breadth, transatlantic supply scale, and therapeutic segment depth—shaping competitive dynamics across hospital, homecare, and retail pharmacy channels.
| Leading Market Players |
|---|
| ZIM Laboratories Limited |
| Aquestive Therapeutics, Inc. |
| IntelGenx Corp. |
| Sunovion Pharmaceuticals, Inc. |
| LTS Lohmann Therapie-Systeme AG |
| C.L. Pharm |
| Cure Pharmaceutical |
| Indivior PLC |
| BioDelivery Sciences International, Inc. |
| Others |
Value Network & Pricing Analysis
Nanocrystal dispersion technology displacing conventional salt-formulation approaches simultaneously redraws European manufacturing geography and compresses pricing premiums for enhanced-bioavailability buccal films. This substitution dynamic concentrates value capture among German and Swiss contract manufacturers with validated high-shear homogenization infrastructure while eroding margins for legacy formulation suppliers.
Pricing Analysis
Certification level creates the primary spread across oral transmucosal drug pricing, with FDA 505(b)(2) validated and CE-marked MDR-compliant products commanding substantial premiums over standard oral solid dosage equivalents. Three-tier pricing structure across premium, standard, and economy levels reflects endotoxin specification stringency, multilayer film architecture complexity, and sterile manufacturing claims. Cost compression in economy-tier sublingual tablets is intensifying because oral dissolving tablet substitutes compete aggressively on unit economics. Hospital emergency departments exhibit lowest price sensitivity due to protocol-driven procurement, while retail pharmacy channels for maintenance addiction therapy show highest sensitivity to patient copay burdens.
Supply Chain Analysis
Baden-Württemberg's specialized polymer corridor anchors mucoadhesive excipient supply for European film manufacturers, creating geographic concentration risk for North American and Asia-Pacific formulation facilities. Active pharmaceutical ingredient production draws from Indian and Chinese chemical clusters, while film-forming agent supply rests on German and Japanese specialty chemical producers. Single-source vulnerability persists for high-purity hydroxypropyl methylcellulose grades essential to PharmFilm-type platforms. Distribution runs through temperature-controlled pharmaceutical logistics networks anchored at Rotterdam's cold chain hub for European hospital replenishment and FedEx Express nodes for North American just-in-time delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face intensifying substitution pressure from oral dissolving tablet platforms and conventional parenteral alternatives that threaten transmucosal film volume in price-sensitive therapeutic segments.
For Market Incumbents: Shield formulation portfolios by securing captive supply of specialized mucoadhesive polymers through backward integration into Baden-Württemberg or Swiss polymer corridors, and accelerate 505(b)(2) pathway submissions for complex generic buccal films before ODT substitution erodes hospital formulary placement. The priority lever sits with sterile manufacturing certification investments that create regulatory moats against lower-cost competitors. For New Entrants and Emerging Players: Lead with pediatric homecare liquid formulations for breakthrough pain and antiemetic therapy, where swallowing dysfunction creates addressable white space with limited incumbent concentration. Telehealth-integrated direct-to-patient dispensing for rare disease neurological indications offers the most penetrable entry vector, with EMA orphan designation incentives providing regulatory tailwinds for initial market establishment. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform-scale manufacturers with validated sterile film infrastructure over indication-focused specialists with single-product dependencies. Acquisition targets should demonstrate endotoxin-controlled manufacturing capabilities and established hospital procurement relationships. The signal to watch is FDA bioequivalence guidance tightening for complex generic transmucosal formulations, which would accelerate competitive shakeout among undercapitalized entrants.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 505(b)(2) Submission Acceleration | Compresses approval timelines for reformulated buccal films against IV reference products. |
| CE Marking Pathway Investment | Secures European market access as MDR compliance burdens filter out under-resourced competitors. |
| Hospital System Partnership | Locks in emergency department formulary placement for pediatric status epilepticus protocols. |
| Manufacturing Scale-Up | Captures restructuring expenditure from EMA endotoxin specification retrofits across European supply chains. |
| Reimbursement Strategy | Aligns sublingual buprenorphine positioning with Medicaid expansion and telehealth dispensing authorization. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists; and secondary validation against FDA 505(b)(2) filings, EMA oromucosal submission databases, ClinicalTrials.gov protocols, and hospital formulary databases. Bottom-up demand modeling across patient population segments triangulated against top-down market sizing from trade flow analysis and contract manufacturing capacity disclosures.
Across the analysis window, the forecasting framework applied treatment line, dosage form, administration route, and regional regulatory cluster segmentation dimensions. CAGRs derived from patient volume epidemiology, reimbursement trajectory assumptions, and technology substitution curves for ODT versus buccal film platforms. Forecast inputs incorporated FDA bioequivalence guidance evolution and EMA orphan designation pathway utilization rates.
The analysis sits within stated boundaries; outcomes outside sustained Medicaid reimbursement for sublingual addiction therapy and continued FDA 505(b)(2) pathway efficiency would require recalibration. Practitioners should keep alternative scenarios live as MDR compliance cost trajectories and oral dissolving tablet bioequivalence standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Diclofenac Sodium API Market
Pharmaceutical Ingredients
Global Chlorpheniramine Maleate Market
Pharmaceutical Ingredients
Medicinal Chemistry for Drug Discovery Market
Pharmaceutical Ingredients
Active Pharmaceutical Ingredient for Cancer Market
Pharmaceutical Ingredients
Amphetamine Drug Market
Pharmaceutical Ingredients
Global Dexamethasone Market
Pharmaceutical Ingredients
Nortriptyline Hydrochloride Market
Pharmaceutical Ingredients
Taxifolin Market
Pharmaceutical Ingredients
Global Antazoline Market
Pharmaceutical Ingredients
Alpha Lipoic Acid API Market
Pharmaceutical Ingredients
Acetaminophen API Market
Pharmaceutical Ingredients
Antipyretic Analgesic Active Pharmaceutical Ingredients Market
Pharmaceutical Ingredients
Pharma-Grade Magnesium Trisilicate Market
Pharmaceutical Ingredients
Sterile Active Pharmaceutical Ingredients Market
Pharmaceutical Ingredients
Pharmaceutical Lactose Market
Pharmaceutical Ingredients
Global Glycine Supplement Market