
 Pharmaceutical Chemicals Market | 2026-2036
Pharmaceutical Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Chemicals Market Intelligence
The rising emphasis on biopharmaceuticals over traditional small-molecule drugs is recalibrating sourcing priorities for pharmaceutical manufacturers. This shift demands higher purity and more complex chemical compounds. BASF leverages its extensive chemical production scale to supply a wide array of excipients and intermediates for various drug formulations. In contrast, Merck & Co specializes in high-purity reagents and critical raw materials essential for the development and manufacturing of complex biologic drugs.
Pharmaceutical chemicals are the foundational raw materials used to produce finished drug products, encompassing both active pharmaceutical ingredients and inert excipients. These substances must adhere to stringent purity standards, often exceeding 99.5%, as stipulated by official pharmacopeias. Their primary function is to deliver a specific therapeutic effect or to act as a vehicle for the active drug within a formulation. Active Pharmaceutical Ingredients (APIs) continue to form the largest product segment by value. Within therapy areas, oncology applications represent the fastest-growing source of demand for novel and highly specialized chemical inputs.
The market operates under a strict regulatory framework enforced by bodies like the FDA in the United States, the EMA in Europe, and China's NMPA. These agencies mandate compliance with Good Manufacturing Practices (GMP), which governs production standards and ensures product safety and efficacy. Navigating the divergent requirements for Drug Master File (DMF) submissions across these key jurisdictions remains a critical competency for chemical suppliers seeking broad market access.
Market Dynamics
The pharmaceutical chemicals market is shaped by the dual pressures of scaling up traditional active pharmaceutical ingredient (API) production while simultaneously developing novel, high-purity compounds for the expanding biologics sector, forcing a bifurcation in manufacturing strategies and supply chain priorities.
Growth Catalysts
- Oncology Pipeline Expansion:Intense research and development in oncology is creating demand for a new generation of highly potent APIs and specialized chemical intermediates designed for targeted therapies and immunotherapies.
- Continuous Manufacturing Adoption:The implementation of continuous manufacturing processes for APIs and intermediates is enhancing production efficiency, improving product consistency, and reducing manufacturing footprints for chemical producers.
- API Production Consolidation:Chemical manufacturing hubs in India and China continue to attract investment due to their vast production capacity, skilled labor, and government support, solidifying their role as primary suppliers of APIs and key starting materials.
Market Restraints
- Regulatory Fragmentation:Navigating the divergent and complex requirements for Drug Master File (DMF) submissions to agencies like the US FDA, Europe's EMA, and China's NMPA creates significant compliance costs and delays market access.
- Stringent Purity Mandates:The requirement to meet or exceed 99.5% purity levels as defined by pharmacopeias necessitates sophisticated purification technologies and rigorous quality control, increasing operational costs for all chemical suppliers.
- Supply Chain Vulnerabilities:High geographic concentration of API and intermediate production in a few Asian countries exposes the global pharmaceutical supply chain to risks from geopolitical tensions, trade policy shifts, and localized disruptions.
Strategic Opportunities
- Cell and Gene Therapy Inputs:Supplying high-purity reagents, solvents, and custom-synthesized oligonucleotides for the burgeoning cell and gene therapy sector represents a significant high-value opportunity for specialized chemical manufacturers.
- AI in Chemical Synthesis:Leveraging artificial intelligence and machine learning platforms to accelerate the discovery of new molecules and optimize synthetic routes can create a strong competitive advantage and reduce R&D timelines.
- Emerging Market Formulation:Developing and supplying excipients tailored for drug formulations in emerging pharmaceutical markets in Latin America and Southeast Asia can capture growth as local manufacturing capabilities expand.
Industry Challenges
- GMP Compliance Costs:The substantial capital investment required to construct, validate, and maintain manufacturing facilities in accordance with Good Manufacturing Practices (GMP) presents a high barrier to entry and ongoing operational expense.
- Specialized Talent Scarcity:A persistent shortage of process chemists and chemical engineers with expertise in both complex biologic raw materials and advanced continuous manufacturing systems hinders innovation and operational scale-up.
- Intellectual Property Protection:Safeguarding proprietary synthesis pathways and novel molecular structures is a constant challenge, particularly for innovative firms operating in a global market with varying IP enforcement standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Chemicals Market |
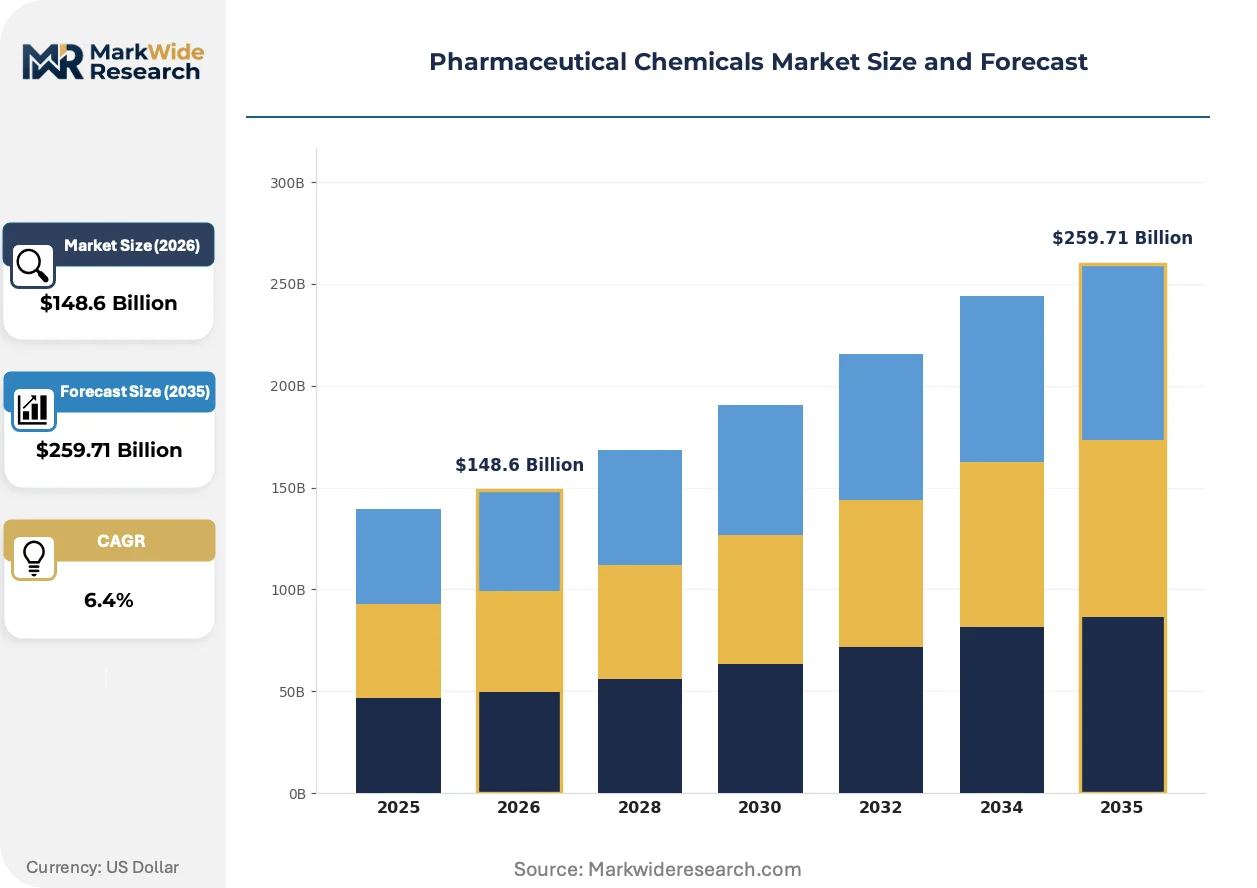
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $259.71 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Pharmaceutical Ingredients, Intermediates, Excipients, Biopharmaceuticals Therapy Area: Cardiovascular, Oncology, Central Nervous System, Anti-Infectives, Dermatology End User: Pharmaceutical Manufacturers, Contract Research Organizations, Biotechnology Companies, Academic Institutions Formulation Technology: Solid Dosage, Liquid Dosage, Semi-solid Dosage, Parenteral, Inhalation |
| Companies Covered | Dow, Sinopec, BASF, Sibur, Hengli Petrochemical, Wanhua Chemical Group, LyondellBasell, Merck & Co, Shin-Etsu Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Chemicals Market Strategic Shifts & Innovations
The modernization of chemical synthesis and quality assurance is a dominant theme, driven by the adoption of digital process controls and a regulatory push for deeper process understanding. This evolution is moving the industry away from traditional batch production toward more integrated and data-rich manufacturing models.
Continuous manufacturing is an automated production method used for APIs and intermediates. Major API producers are adopting these systems to improve process control and product consistency. This technology is integrating process analytical technology (PAT) to enable real-time quality monitoring, which reduces batch failures and shortens overall production timelines.
The European Medicines Agency's (EMA) initiative promoting Quality by Design (QbD) principles is a significant regulatory development. This framework compels manufacturers to build quality into processes from the outset, moving beyond a reliance on final product testing. API and excipient suppliers are most impacted, as they must now provide more comprehensive process validation data to pharmaceutical clients.
A key demand-side shift involves pharmaceutical companies pursuing strategic partnerships over transactional purchasing with their chemical suppliers. This collaborative model is displacing older vendor relationships for complex drug programs that require co-development of critical raw materials. The trend is most prominent in the development of specialized oncology and orphan drugs, where chemical novelty and supply security are crucial.
Pharmaceutical Chemicals Market Segmentation
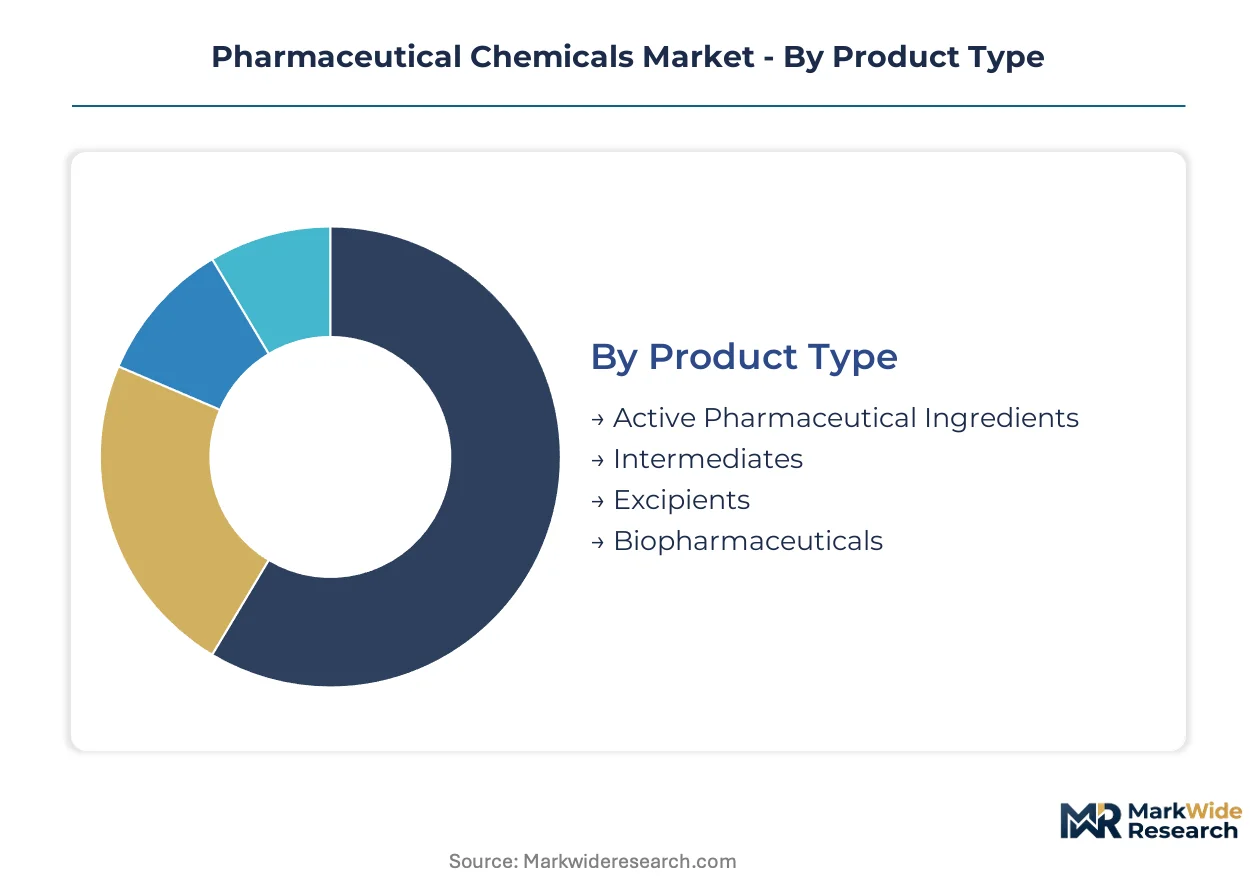
The pharmaceutical chemicals market segments across diverse dimensions, reflecting the varied requirements for drug development and manufacturing. Understanding these distinctions helps stakeholders identify areas of concentrated investment, specialized technological needs, and evolving demand patterns. Each segment presents unique challenges and opportunities for chemical suppliers.
Product Type:
The capital intensity across product types varies significantly, with advanced biopharmaceutical inputs requiring substantial investment in specialized synthesis and purification infrastructure.
- Active Pharmaceutical Ingredients:These are the biologically active components in finished drug products, requiring stringent purity standards exceeding 99.5% and adherence to Good Manufacturing Practices. Demand for APIs concentrates in large-scale generic drug production in India and China, driven by cost-effective manufacturing capabilities.
- Biopharmaceuticals:This segment includes complex biological molecules like proteins, peptides, and antibodies, necessitating high-purity reagents and advanced synthesis techniques. Growth in biopharmaceuticals is concentrated in oncology and autoimmune disease therapies, due to the need for highly specific and potent compounds.
- Intermediates:Chemical compounds formed during the synthesis of an API, these materials require careful quality control to ensure the final product meets regulatory specifications.
- Excipients:Inert substances used as vehicles for active drugs, excipients enhance stability, bioavailability, or ease of administration in drug formulations.
Most installed capacity flows through Active Pharmaceutical Ingredients. Expansion is steepest in Biopharmaceuticals.
Therapy Area:
Therapy areas dictate the complexity and specificity of chemical inputs, with specialized applications requiring highly tailored compounds.
- Oncology:This area demands novel, highly potent APIs and specialized intermediates for targeted therapies and immunotherapies, driving significant research and development. Demand is concentrated in developed markets like the United States and Europe, where advanced cancer treatments are prevalent.
- Cardiovascular:Chemicals for cardiovascular drugs address a broad range of conditions, often requiring high-volume production of established APIs and excipients. Procurement for these drugs remains substantial in densely populated regions, including China, due to the high incidence of heart disease.
- Central Nervous System:This segment encompasses chemicals for neurological and psychiatric disorders, often requiring specialized compounds that can cross the blood-brain barrier.
- Anti-Infectives:Inputs for anti-infective drugs target bacterial, viral, and fungal infections, with a constant need for new chemical entities to combat resistance.
- Dermatology:Chemicals for dermatological applications include active ingredients and specialized excipients for topical and systemic skin treatments.
Demand for Cardiovascular chemicals remains substantial, while Oncology drives significant innovation.
End User:
Different end-user segments demand distinct levels of regulatory support and supply chain integration from chemical suppliers.
- Pharmaceutical Manufacturers:These entities are the primary consumers of pharmaceutical chemicals, requiring bulk quantities of APIs and excipients for drug production. Their procurement strategies often involve long-term contracts and rigorous supplier qualification processes.
- Biotechnology Companies:Focused on biologics and advanced therapies, these companies require high-purity reagents, custom synthesis services, and specialized raw materials. Their needs are concentrated in research-intensive regions like Boston and San Francisco.
- Contract Research Organizations:CROs utilize pharmaceutical chemicals for drug discovery, preclinical, and clinical trials, often requiring smaller, specialized batches of compounds.
- Academic Institutions:Universities and research centers use pharmaceutical chemicals for basic research, drug discovery, and educational purposes.
The largest volume of chemical inputs serves Pharmaceutical Manufacturers, with Biotechnology Companies exhibiting rapid growth in specialized material procurement.
Formulation Technology:
Formulation technologies present varying cost tiers for chemical inputs, influenced by processing requirements and final product purity standards.
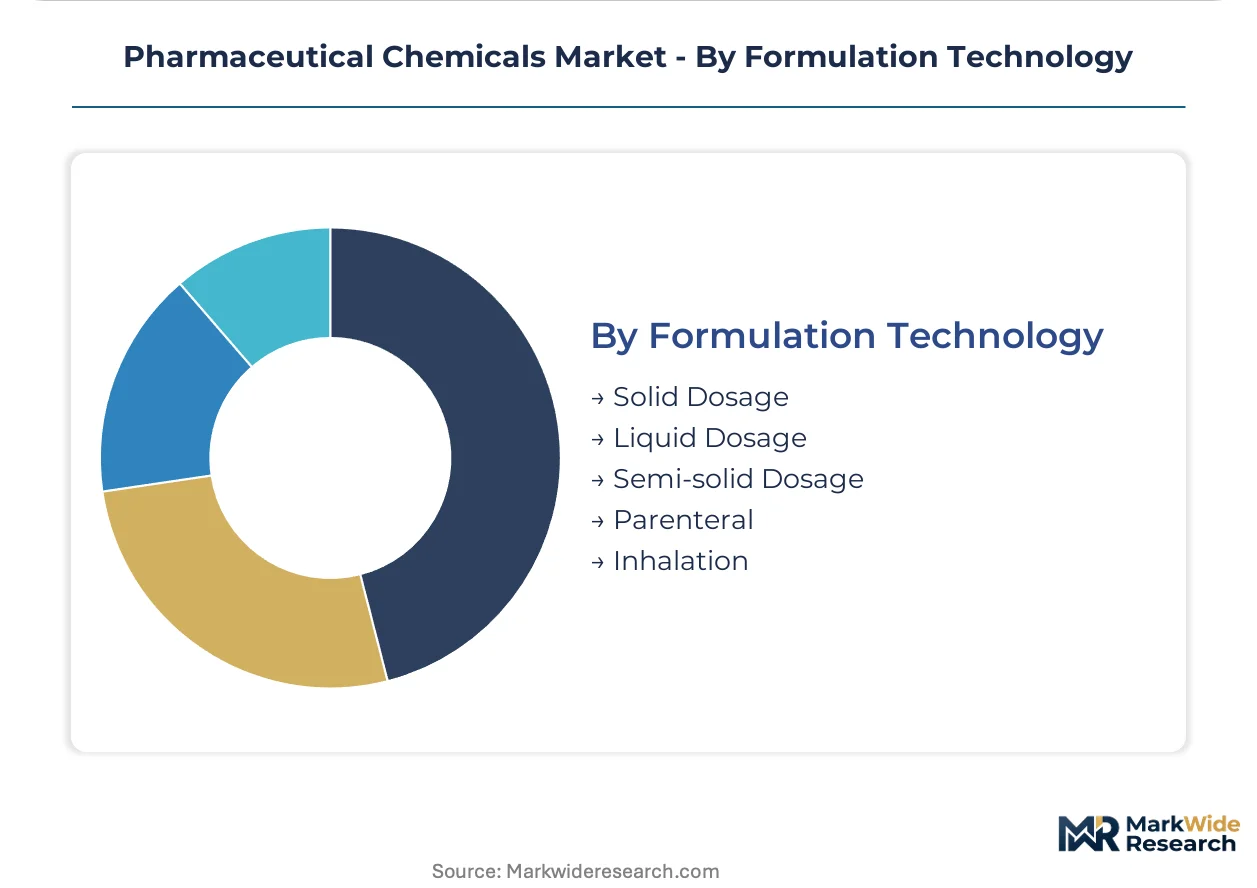
- Parenteral:These formulations, administered via injection, demand the highest purity and sterility for all chemical inputs, significantly increasing material costs. Demand for parenteral inputs is growing for complex biologics and vaccines globally.
- Solid Dosage:This category includes tablets and capsules, representing high-volume production and requiring a balance of cost-effectiveness and functional excipients. Production for solid dosage forms is widespread, with major hubs in India.
- Liquid Dosage:Formulations like syrups and solutions require excipients that ensure solubility, stability, and palatability for oral or topical administration.
- Semi-solid Dosage:Creams, gels, and ointments require specific chemical bases and penetration enhancers to deliver active ingredients effectively to the skin.
- Inhalation:Inhalation products demand fine particle-sized APIs and specialized excipients for targeted delivery to the respiratory tract.
Traditional high-volume manufacturing centers on Solid Dosage, but advanced drug delivery systems increasingly rely on inputs for Parenteral.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence often drives the geographic distribution of pharmaceutical chemical production, as manufacturers seek optimal compliance costs and operational efficiencies. This dynamic encourages a strategic relocation of certain manufacturing processes to regions offering favorable regulatory environments or established infrastructure. Such shifts influence sourcing decisions for critical raw materials and intermediates across the global supply chain.
United States
Demand for specialized pharmaceutical chemicals in the United States is driven by extensive biopharmaceutical research and development, particularly in novel biologics. The FDA's stringent guidelines for drug purity and manufacturing processes necessitate advanced quality control systems from suppliers. Biotech clusters in Boston and San Francisco concentrate the need for high-purity reagents and custom synthesis services.
Germany
Germany's pharmaceutical chemical sector benefits from a strong tradition in fine chemicals and a robust pharmaceutical industry, fueling demand for high-quality intermediates. The EMA's rigorous Good Manufacturing Practices (GMP) require significant investment in compliant production facilities. Chemical parks like Ludwigshafen and Leverkusen serve as hubs for advanced chemical synthesis and process optimization.
India
India's large-scale generic drug production creates substantial demand for cost-effective active pharmaceutical ingredients and excipients. The Central Drugs Standard Control Organization (CDSCO) regulates the quality and safety of pharmaceutical products, influencing local manufacturing standards. Major pharmaceutical clusters in Hyderabad and Ahmedabad are key centers for API and intermediate manufacturing.
China
China's vast chemical manufacturing capacity and government support underpin its role as a primary supplier of APIs and key starting materials globally. The NMPA's evolving regulatory framework increasingly pushes for higher quality standards and environmental compliance in chemical production. Production hubs in the Yangtze River Delta and Shandong Peninsula dominate the supply of bulk pharmaceutical chemicals.
United Kingdom
The United Kingdom experiences demand for specialized chemical inputs, especially for oncology and rare disease therapeutics, supported by a strong research base. The Medicines and Healthcare products Regulatory Agency (MHRA) enforces strict quality and safety standards for all pharmaceutical ingredients. Biotech parks around Oxford and Cambridge foster innovation in novel chemical entities for drug development.
Pharmaceutical Chemicals Market Key Industry Players
Capacity expansion dominates the current landscape of the pharmaceutical chemicals market, driven by the need to meet rising demand for both traditional APIs and complex biopharmaceutical inputs. The market structure exhibits a tiered consolidation, with a few large, diversified chemical giants operating alongside numerous specialized manufacturers. Strategic archetypes include integrated chemical producers, niche high-purity material suppliers, and regional API manufacturers. Companies pursue geographic expansion and portfolio diversification as primary competitive moves.
The landscape features large, diversified chemical producers such as BASF and Dow, which leverage extensive global manufacturing footprints to supply a broad spectrum of excipients and intermediates. These companies often anchor the market for high-volume traditional APIs and inert substances, benefiting from significant economies of scale and established supply chains. Conversely, Merck & Co exemplifies the specialized supplier archetype, focusing on high-purity reagents and critical raw materials essential for the burgeoning biopharmaceutical sector. This bifurcation in strategic focus highlights the diverse operational models and investment priorities defining market participation, from commodity chemical supply to advanced biologic input provision, creating distinct competitive arenas.
| Leading Market Players |
|---|
| Dow |
| Sinopec |
| BASF |
| Sibur |
| Hengli Petrochemical |
| Wanhua Chemical Group |
| LyondellBasell |
| Merck & Co |
| Shin-Etsu Chemical |
Cost & Logistics Intelligence
Global chemical feedstock pricing benchmarks influence the cost structure for pharmaceutical chemicals, cascading through the supply chain to define distinct pricing tiers for active pharmaceutical ingredients, intermediates, and excipients.
Pricing Analysis
Distributor margins often reflect the complexity of logistics and regulatory compliance for specialized chemical inputs. Contract-based long-term offtake agreements dominate for bulk active pharmaceutical ingredients, providing stability for pharmaceutical manufacturers. Price differentiation stems from purity grade requirements, specific pharmacopeial certifications, and large-volume purchasing scales. Pricing pressure stems from generic drug manufacturers seeking cost-effectiveness, making them the most price-sensitive segment, while biopharmaceutical companies prioritize performance over cost.
Supply Chain Analysis
Skilled workforce availability in key manufacturing geographies like India and China underpins large-scale active pharmaceutical ingredient production. The supply chain draws from basic chemical building blocks and specialized reagents, primarily sourced from these concentrated hubs. Single-source vulnerability for critical intermediates presents a structural risk, particularly during geopolitical tensions. Distribution runs through direct sales from chemical producers to pharmaceutical companies, with specialized distributors handling niche biopharmaceutical inputs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pharmaceutical chemicals market presents a late-cycle quality story, driven by a pronounced demand-shift toward premium specifications for complex biopharmaceutical inputs.
For Market Incumbents: To counter regulatory fragmentation and supply chain vulnerabilities, large chemical producers must invest in advanced Good Manufacturing Practice-compliant facilities across diverse geographies. Diversifying active pharmaceutical ingredient production sites in regions like the United States and Europe mitigates localized disruptions. Deepening process analytical technology integration enhances product consistency and streamlines regulatory submissions. Leveraging certification investments for Drug Master File submissions secures market access.
For New Entrants and Emerging Players: Capture opportunities within the burgeoning cell and gene therapy sector by specializing in high-purity reagents and custom-synthesized oligonucleotides. The niche segment of advanced biologic raw materials for biotechnology companies in research-intensive regions like Boston offers significant white-space. A co-development partnership model with biopharma firms can accelerate market penetration and product validation.
For Investors and Strategic Acquirers: Consolidation pressure builds where high capital investment for Good Manufacturing Practice compliance and specialized talent scarcity create barriers to entry. Long-term viability rests on the essential nature of pharmaceutical inputs and the sustained innovation in advanced therapies. Niche high-purity material suppliers with robust intellectual property and strong regulatory track records represent attractive acquisition archetypes. Monitor accelerated regulatory approvals for novel biopharmaceuticals as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | For large-scale active pharmaceutical ingredient production in India and China, ensuring volume supply. |
| Green Manufacturing Transition | To meet evolving NMPA and EMA environmental compliance standards, enhancing market access. |
| Long-term Supply Agreement | With pharmaceutical manufacturers for critical raw materials, securing stable demand and supply. |
| Joint Venture | For specialized biopharmaceutical input development, pooling expertise and mitigating R&D risks. |
| Regulatory Approval Pathway | For new chemical entities in the United States and Europe, accelerating market entry. |
Research Approach
Direct dialogue with R&D directors, procurement leads, regulatory affairs specialists, and plant managers provided qualitative insights into market dynamics. This primary research was validated through extensive secondary analysis of FDA filings, EMA submissions, NMPA reports, and chemical industry association reports. A robust bottom-up and top-down triangulation approach ensured comprehensive data integrity.
Comprehensive volume and value projections were generated through a multi-variable regression model, analyzing market trajectories across the analysis window. Segmentation dimensions modeled included product type, therapy area, end-user, and formulation technology, alongside regional production hubs. Compound Annual Growth Rates were derived from historical data trends and projected market influences. Key forecast inputs included R&D pipeline growth and continuous manufacturing adoption rates.
Underlying measurement precision varies by segment; established API segments carry tighter precision than nascent cell and gene therapy inputs. Forecasts reflect assumptions concerning regulatory stability and technological advancements, acknowledging potential revisions from geopolitical shifts or major drug recalls. Practitioners should monitor changes in pharmacopeial standards and major investment announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Diosmin API Market
Pharmaceutical Ingredients
Duloxetine API Market
Pharmaceutical Ingredients
Folinic Acid Market
Pharmaceutical Ingredients
Taxifolin Market
Pharmaceutical Ingredients
Cetrorelix Acetate API Market
Pharmaceutical Ingredients
India Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Flurbiprofen Market
Pharmaceutical Ingredients
Prescription Hair Loss and Hair Removal Drugs Market
Pharmaceutical Ingredients
Tranexamic Acid API Market
Pharmaceutical Ingredients
Pharma Grade Sodium Bicarbonate Market
Pharmaceutical Ingredients
Originator Small Molecule Drug Market
Pharmaceutical Ingredients
Small-Molecule Injectable Market
Pharmaceutical Ingredients
Small Molecule Drug Discovery Market
Pharmaceutical Ingredients
Small-Molecule Injectable Drugs Market
Pharmaceutical Ingredients
Calcium Gluconate Market
Pharmaceutical Ingredients
Asia-Pacific Pharmaceutical Glycerin Based Products Market