
 Penciclovir API Market | 2026-2036
Penciclovir API Market Size, Share, and Industry Trends Forecast 2026-2036
Penciclovir API Market Insights
Contract manufacturing services for penciclovir API is repositioning how buyers structure supply relationships, shifting from spot purchases to multi-year partnership agreements with quality-assured foundries. ChemWerth Inc leverages its US-based regulatory navigation to serve specialty pharmaceutical clients requiring FDA-compliant documentation packages. Alembic Pharmaceuticals Limited anchors its position through backward integration into key starting materials, insulating margin pools from raw material volatility. Chongqing Shenghuaxi Pharmaceutical dominates regional supply to domestic Chinese formulators while building export dossiers for emerging markets.
Penciclovir API is a synthetic nucleoside analogue with a molecular formula of C10H15N5O3, manufactured through multi-step organic synthesis involving purine ring construction and stereoselective hydroxylation, serving primarily as the active moiety in antiviral therapeutics targeting herpes simplex virus infections. Oral tablet formulations command the largest volume share due to established bioequivalence pathways and patient compliance advantages in recurrent genital herpes protocols. Topical cream applications compete on dermatological prescription volumes where cold sore management generates recurring seasonal demand. Lyophilized form production concentrates margin pools with specialized manufacturers serving parenteral formulation clients requiring extended shelf stability.
FDA Current Good Manufacturing Practice enforcement and EMA ICH Q7 guidelines for API manufacture dictate batch documentation, impurity profiling, and facility inspection schedules that determine market access eligibility for penciclovir producers. India's CDSCO manufacturing license requirements and PLI scheme incentives for bulk drug parks redirect capital toward domestic API self-sufficiency, reshaping import dependency patterns. Stakeholders must monitor evolving pharmacopoeial monograph revisions and bioequivalence study design changes that could alter qualification thresholds for generic penciclovir entrants.
Market Dynamics
Contract manufacturing consolidation in India is compressing supply chain tiers for penciclovir API, forcing formulators to requalify fewer, larger suppliers against tightening FDA and EMA purity benchmarks.
Growth Catalysts
- CDSCO PLI scheme:India's production-linked incentives for bulk drug parks redirect capital toward domestic API self-sufficiency, reducing import dependency for domestic formulators.
- Herpes simplex virus prevalence:Recurrent infection rates sustain prescription volumes for oral and topical penciclovir formulations across dermatology and infectious disease practices.
- EMA ICH Q7 harmonization:Aligned manufacturing standards streamline multi-market dossier submissions, lowering regulatory friction for qualified API exporters.
Market Restraints
- Key starting material volatility:Purine derivative feedstock prices fluctuate with agrochemical input costs, squeezing margin pools for non-integrated manufacturers.
- Single-source concentration risk:China's dominance in specialized chemical intermediates exposes penciclovir synthesis to geopolitical supply interruptions.
- Acyclovir substitution pressure:The established antiviral alternative commands preferential formulary placement in cost-constrained healthcare systems.
Strategic Opportunities
- Brazil ANVISA pathway acceleration:Emerging market regulators are streamlining bioequivalence requirements for generic antiviral APIs, opening volume expansion for qualified exporters.
- Lyophilized parenteral formats:Hospital-administered antiviral protocols create premium positioning for stabilized injectable formulations requiring specialized manufacturing.
- Continuous flow synthesis:Adoption of modular reactor technology reduces batch cycle times and solvent waste profiles for ESG-conscious pharmaceutical buyers.
Industry Challenges
- Qualified personnel scarcity:Stereoselective hydroxylation expertise remains concentrated among veteran organic chemists, constraining capacity expansion timelines.
- Multi-year qualification cycles:FDA pre-approval inspection backlogs and complete response letter iterations extend time-to-revenue for new API entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Penciclovir API Market |
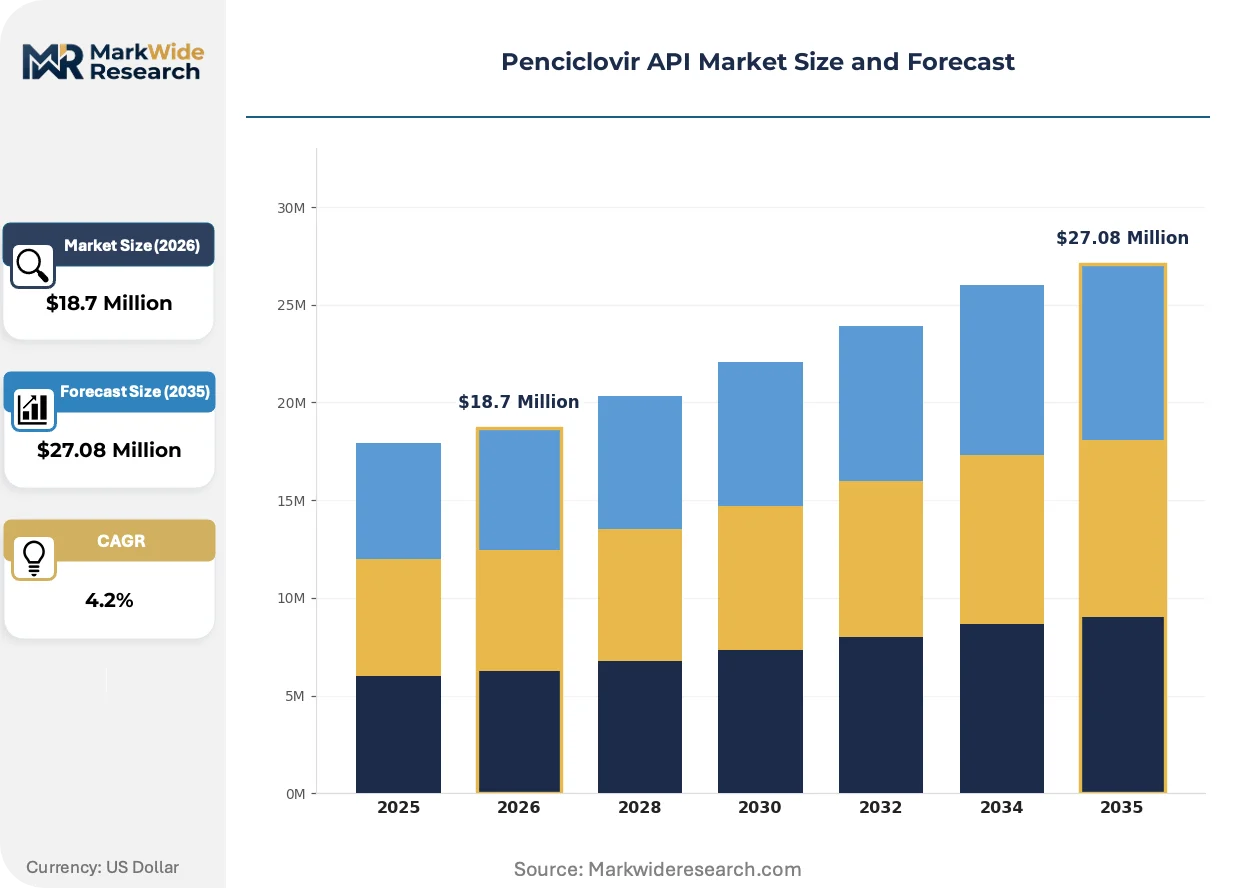
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $27.08 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Tablet, Topical Cream, Injectable Solution, Powder End User: Pharmaceutical Companies, Contract Manufacturing Organizations, Research Institutions, Hospitals Application: Antiviral Treatment, Cold Sore Management, Dermatological Use, Clinical Research Formulation: Lyophilized Form, Emulsion, Gel, Granules |
| Companies Covered | ChemWerth Inc, Alembic Pharmaceuticals Limited, Chongqing Shenghuaxi Pharmaceutical, Charioteer, MSN Laboratories, Prajna Generics, SMS Pharmaceuticals, Shouyuan Chemical, Tecoland Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Penciclovir API Market Trends and Innovations
Process intensification and regulatory data harmonization are compressing development cycles while procurement models migrate toward integrated supply partnerships rather than transactional spot purchasing.
Continuous manufacturing platforms are decentralizing penciclovir API production from large-batch facilities to modular, skid-mounted systems. Mid-size contract manufacturers in India and China are piloting these units to serve regional formulators with reduced lead times. This technology is decentralizing geographic supply concentration and enabling smaller production runs tailored to niche therapeutic indications.
REACH authorization requirements for hazardous chemical intermediates are tightening documentation burdens for European penciclovir manufacturers. Substance volume tracking and extended safety data sheet obligations now extend through the API supply chain. Specialized toxicology consultancies are absorbing expanded compliance budgets as manufacturers restructure substance registration portfolios.
Multi-year offtake agreements with quality-assured foundries are displacing quarterly spot auctions as the dominant procurement mechanism. Large pharmaceutical buyers are consolidating supplier panels to three to five qualified partners with dedicated capacity allocations. This pattern is most visible among North American specialty pharmaceutical companies seeking FDA-compliant documentation packages and audit transparency.
Penciclovir API Market Segmentation
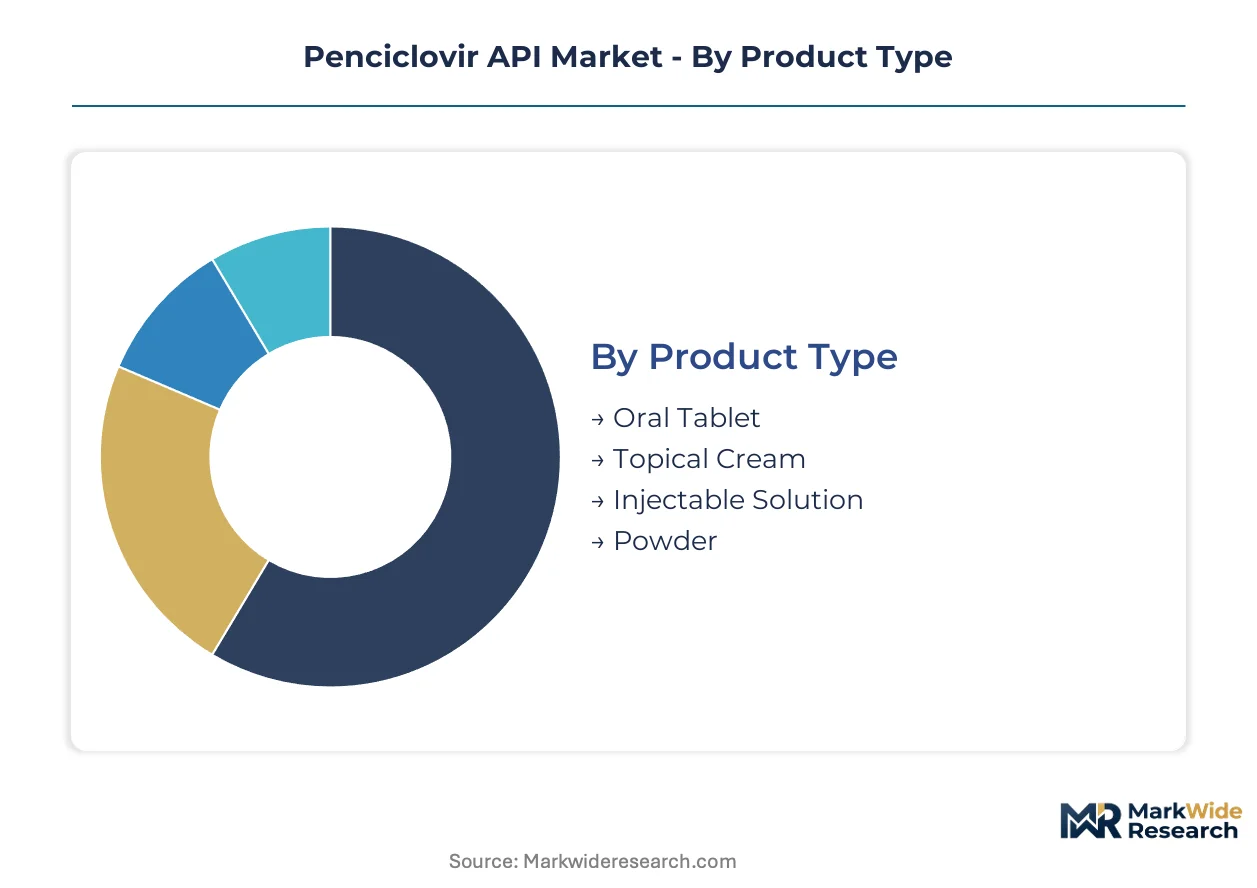
Penciclovir API procurement patterns diverge sharply across formulation types and end-user categories, with FDA pre-approval inspection requirements and EMA ICH Q7 dossier standards determining which segments command premium pricing versus commodity positioning. Understanding these certification tiers allows manufacturers to align capacity investments with margin structures.
Product Type:
FDA Current Good Manufacturing Practice and EMA ICH Q7 documentation burdens vary substantially across delivery formats, with sterile injectable formats requiring the most extensive validation protocols.
- Oral Tablet:Compressed solid dosage forms containing penciclovir API with established bioequivalence pathways dominate prescription volumes for recurrent genital herpes protocols. Pharmaceutical companies in India concentrate procurement here due to mature CDSCO manufacturing license frameworks and streamlined USANDA submission routes. The segment absorbs the largest share of contract manufacturing capacity across Mumbai and Hyderabad bulk drug parks.
- Topical Cream:Semisolid emulsion-based formulations for dermal application compete on seasonal prescription volumes tied to cold sore management cycles. Demand clusters in North American dermatology practices where patient self-administration drives compliance advantages over oral alternatives.
- Injectable Solution:Parenteral formats require sterile manufacturing suites and endotoxin testing protocols that restrict supply to specialized facilities with FDA establishment registration.
- Powder:Bulk API for in-house formulation by integrated pharmaceutical manufacturers offers margin protection through backward integration into key starting materials.
Leading the category by volume: Oral Tablet. Growing fastest: Topical Cream.
End User:
Procurement scale and technical sophistication separate large-volume buyers from niche research consumers, with multi-year offtake agreements concentrating among the former.
- Pharmaceutical Companies:Integrated formulators with internal regulatory affairs teams drive the largest API volumes, leveraging dedicated quality agreements and audit rights to secure supply continuity. These buyers prioritize FDA-compliant documentation packages and EMA CEP availability for multi-market launches.
- Contract Manufacturing Organizations:Third-party producers serving specialty pharmaceutical clients absorb expanding share as virtual pharma models displace captive manufacturing. Indian CMOs in Gujarat and Andhra Pradesh scale generic API production for export markets under CDSCO PLI scheme incentives.
- Research Institutions:Academic and government laboratories source smaller quantities for clinical trial material and pharmacokinetic studies.
- Hospitals:Institutional procurement of compounded formulations serves niche parenteral antiviral protocols in tertiary care settings.
Pharmaceutical Companies anchor procurement volumes. Contract Manufacturing Organizations are expanding most quickly.
Application:
Clinical indication determines pricing power, with approved therapeutic uses commanding substantial premiums over investigational or off-label demand.
- Antiviral Treatment:Systemic herpes simplex virus suppression protocols generate the largest revenue pools, with oral penciclovir formulations competing against acyclovir for formulary placement in cost-constrained healthcare systems. EMA marketing authorization holders concentrate supply relationships with qualified API foundries.
- Cold Sore Management:Recurrent herpes labialis treatment drives seasonal demand spikes with lower regulatory barriers than systemic indications. Topical formats dominate this segment with over-the-counter availability in select markets.
- Dermatological Use:Off-label skin condition applications generate niche prescription volumes with variable reimbursement coverage.
- Clinical Research:Investigator-initiated trials and pharmaceutical pipeline studies source API under exploratory IND mechanisms with reduced batch size requirements.
Antiviral Treatment leads by revenue contribution. Cold Sore Management shows the steepest expansion trajectory.
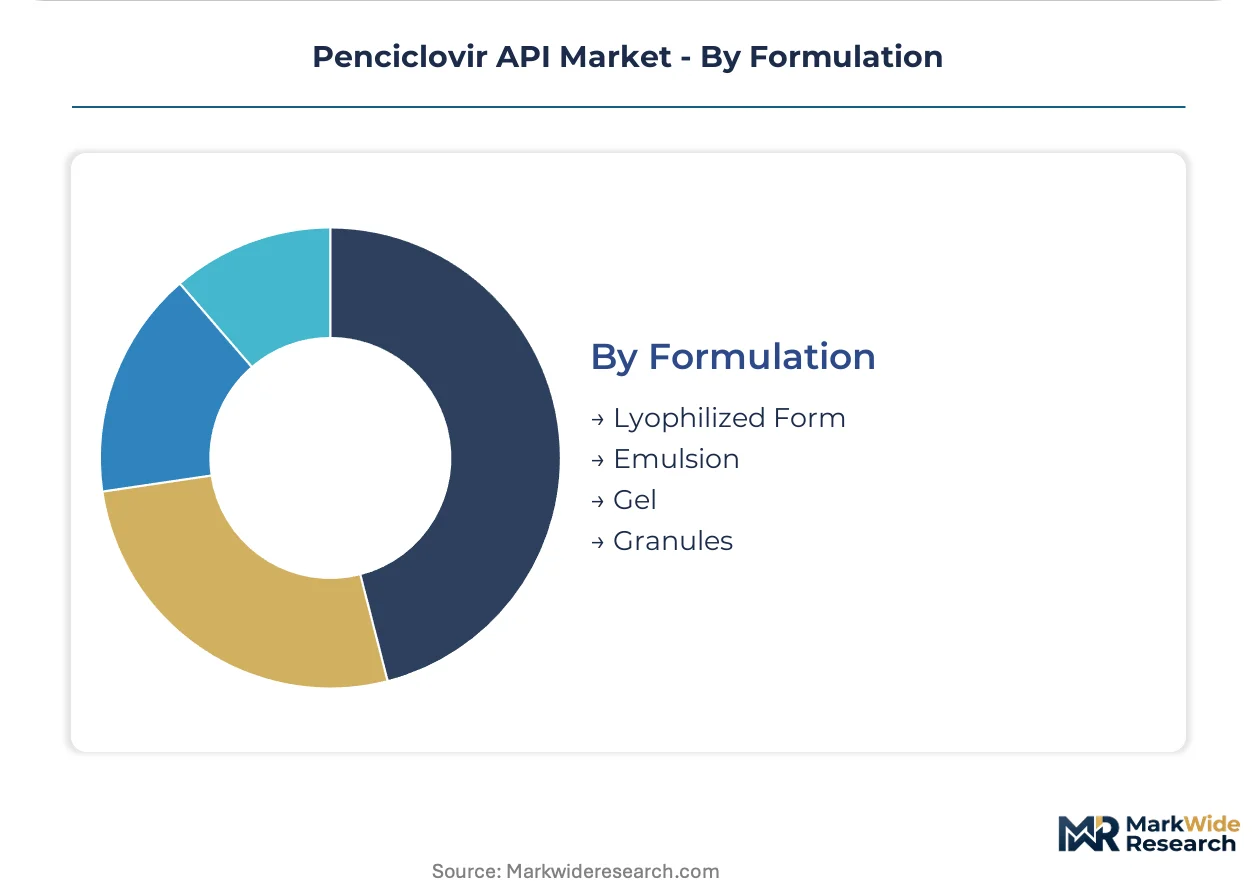
Formulation:
Stability requirements and manufacturing complexity stratify margin pools, with lyophilized formats requiring specialized equipment and extended development timelines.
- Lyophilized Form:Freeze-dried powder for reconstitution offers extended shelf stability critical for parenteral formulations in hospital-administered antiviral protocols. Production concentrates with specialized manufacturers serving clients requiring multi-year stability data and FDA pre-approval inspection clearance.
- Emulsion:Oil-in-water or water-in-oil dispersions enable topical delivery with enhanced skin penetration for dermatological applications.
- Gel:Hydrogel and organogel matrices provide controlled release characteristics for localized antiviral action.
- Granules:Intermediate processing forms facilitate tableting operations with improved flow properties and content uniformity.
Lyophilized Form commands the highest unit economics. Emulsion formats are gaining share fastest in topical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Penciclovir API production concentrates in Asian manufacturing hubs while consumption spreads across North American and European pharmaceutical markets. India's contract manufacturing sector absorbs the largest share of export-oriented capacity under production-linked incentive schemes. Regulatory divergence between FDA and EMA purity standards shapes qualification requirements for multi-market suppliers.
United States
Specialty pharmaceutical companies in New Jersey and Massachusetts drive demand for FDA-compliant documentation packages and pre-approval inspection clearance. The FDA Current Good Manufacturing Practice enforcement mandates batch documentation and impurity profiling that determine market access eligibility. Boston-area formulators source through multi-year offtake agreements with quality-assured foundries to secure supply continuity for antiviral portfolios.
India
CDSCO manufacturing license requirements and PLI scheme incentives for bulk drug parks redirect capital toward domestic API self-sufficiency in Gujarat and Andhra Pradesh. Mumbai and Hyderabad bulk drug parks concentrate contract manufacturing capacity for generic penciclovir production. Alembic Pharmaceuticals anchors its position through backward integration into key starting materials, insulating margin pools from raw material volatility.
China
Chongqing Shenghuaxi Pharmaceutical dominates regional supply to domestic Chinese formulators while building export dossiers for emerging markets. NMPA registration requirements and dual carbon goals pressure manufacturers to adopt cleaner synthesis pathways. The Yangtze River Delta hosts specialized chemical intermediate producers that feed penciclovir synthesis chains.
Germany
EMA ICH Q7 guidelines for API manufacture dictate facility inspection schedules and dossier standards that qualified exporters must satisfy for European market access. REACH authorization requirements for hazardous chemical intermediates tighten documentation burdens through extended safety data sheet obligations. Frankfurt and Munich host regulatory affairs consultancies that absorb expanded compliance budgets for substance registration portfolios.
Brazil
ANVISA pathway acceleration for generic antiviral APIs opens volume expansion opportunities for qualified exporters from Asian manufacturing hubs. São Paulo-based formulators seek bioequivalence study partnerships to navigate streamlined approval routes for penciclovir generics. The Southeast region concentrates pharmaceutical distribution infrastructure serving Latin American markets.
Penciclovir API Market Competitive Landscape
Top-tier vendors anchor regulatory-compliant supply chains, while mid-tier specialists compete on backward integration and regional market access. The vendor base stratifies across three tiers: integrated pharmaceutical companies with captive API production, quality-certified contract manufacturers serving multi-market formulators, and regional suppliers focused on domestic qualification pathways. Two dominant competitive moves are reshaping positioning: multi-year partnership agreements displacing spot purchasing, and continuous flow synthesis adoption reducing batch cycle times for ESG-conscious buyers.
Among US-based regulatory specialists, ChemWerth Inc occupies a position exemplifying quality-assured documentation services for specialty pharmaceutical clients. Indian integrated manufacturers Alembic Pharmaceuticals Limited and MSN Laboratories represent the backward-integration archetype, controlling key starting material supply chains. Chongqing Shenghuaxi Pharmaceutical anchors the China-based regional supplier tier, serving domestic formulators while building export dossier capabilities for emerging markets.
| Leading Market Players |
|---|
| ChemWerth Inc |
| Alembic Pharmaceuticals Limited |
| Chongqing Shenghuaxi Pharmaceutical |
| Charioteer |
| MSN Laboratories |
| Prajna Generics |
| SMS Pharmaceuticals |
| Shouyuan Chemical |
| Tecoland Corporation |
| Others |
Pricing and Supply Chain Analysis
Stereoselective hydroxylation expertise concentration in Gujarat and Andhra Pradesh bulk drug parks drives labor-cost differentials that widen pricing-tier spreads between FDA-certified and domestic-grade penciclovir API. Indian contract manufacturers leverage this skilled workforce pool to undercut European foundries on standard-grade material while commanding premiums for EMA-compliant documentation packages.
Pricing Analysis
Margin tightening in standard-grade oral tablet API reflects CDSCO PLI scheme capacity additions flooding export markets with qualified generic supply. Three-tier pricing structure across premium, standard, and economy levels separates lyophilized parenteral formats with FDA pre-approval inspection clearance from commodity oral grades and unregistered research material. Price differentiation hinges on certification tier—EMA CEP availability and USANDA submission support command 40-60% premia over basic GMP material. Cost-down pressure on oral tablet grades accelerates because Brazilian and Southeast Asian formulators negotiate volume offtakes against spot-market alternatives. Hospital procurement committees demonstrate lowest price sensitivity for sterile injectable formats, while virtual pharma startups sourcing clinical trial material exhibit highest elasticity.
Supply Chain Analysis
India's domestic-content mandates under the PLI scheme for bulk drug parks are redirecting formulator sourcing toward Gujarat and Andhra Pradesh contract manufacturers with CDSCO manufacturing licenses. Geographic supply concentration centers on India, China, and Germany, with Mumbai and Hyderabad bulk drug parks absorbing the largest share of export-oriented penciclovir API capacity. Raw material dependencies draw from Chinese purine derivative feedstock producers, Indian key starting material specialists, and European solvent suppliers. Single-source concentration risk in Yangtze River Delta chemical intermediates exposes synthesis chains to geopolitical supply interruptions. Distribution runs through multi-year offtake agreements with quality-assured foundries displacing quarterly spot auctions among North American specialty pharmaceutical buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
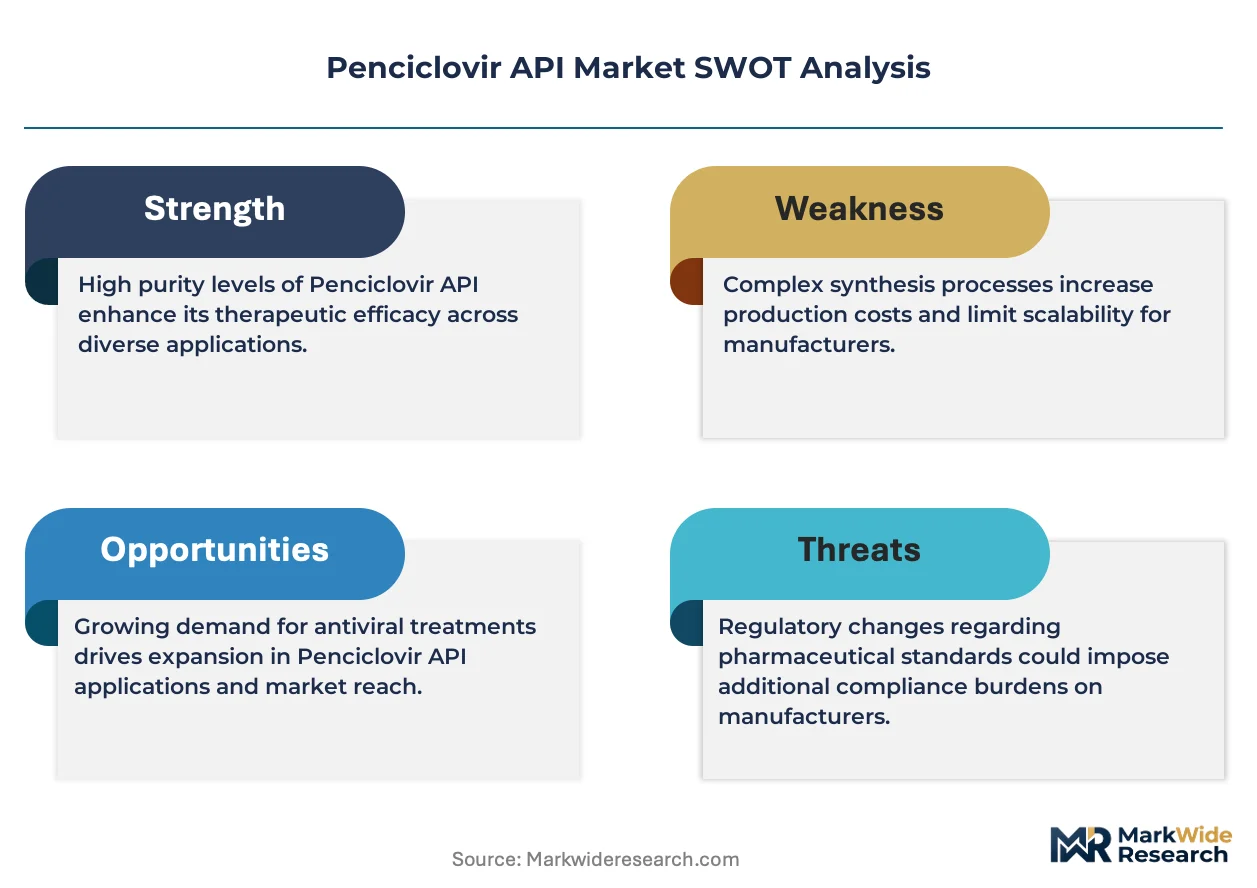
Penciclovir API competitive dynamics have shifted into a vertical-integration race where backward control over key starting materials determines margin sustainability. Players are pursuing upstream leverage into purine derivative supply chains to insulate against feedstock volatility.
For Market Incumbents: Hedge against acyclovir substitution pressure by deepening backward integration into key starting materials and securing dedicated capacity allocations at Indian bulk drug parks. Alembic Pharmaceuticals anchors its positioning through captive supply of critical intermediates, insulating margin pools from agrochemical input cost swings. Incumbents should prioritize FDA pre-approval inspection clearance investments to defend formulary placement against emerging generic entrants.
For New Entrants and Emerging Players: Capture white-space opportunity in lyophilized parenteral formats where sterile manufacturing suite requirements restrict supply to specialized facilities. Brazil ANVISA pathway acceleration offers the most penetrable regulatory entry point for qualified exporters from Asian manufacturing hubs. New entrants should pursue bioequivalence study partnerships with São Paulo-based formulators as the primary go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier Indian CMOs possessing CDSCO manufacturing licenses and PLI scheme incentives given continued capital redirection toward domestic API self-sufficiency. Long-term viability over a five-to-ten-year window favors targets with established EMA ICH Q7 compliance and multi-market dossier submission capabilities. The signal to watch as inflection indicator is ANVISA approval timeline compression for generic antiviral APIs.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Key Starting Materials | Purine derivative captive supply insulates margin pools from agrochemical input cost volatility. |
| Continuous Flow Synthesis Adoption | Modular reactor technology reduces batch cycle times and solvent waste profiles for ESG-conscious pharmaceutical buyers. |
| FDA Pre-Approval Inspection Clearance | Establishment registration unlocks multi-year offtake agreements with North American specialty pharmaceutical companies. |
| Brazil ANVISA Bioequivalence Partnership | Streamlined approval routes for generic antiviral APIs open volume expansion in Latin American markets. |
| Lyophilized Parenteral Format Capacity Addition | Sterile manufacturing suites serve hospital-administered antiviral protocols with premium unit economics. |
Research Methodology
FDA filings, EMA submission databases, and ClinicalTrials.gov records formed the secondary backbone for penciclovir API market sizing and competitive positioning. Primary interviews with drug development executives, regulatory affairs leads at Indian CMOs, formulary directors at North American specialty pharmaceutical companies, and hospital procurement managers validated secondary findings and informed demand elasticity assumptions. Bottom-up capacity assessments at Mumbai and Hyderabad bulk drug parks were triangulated against top-down prescription volume analysis across oral tablet and topical cream formulations.
Historical trendline analysis of penciclovir API contract manufacturing capacity additions and pricing trajectories informed projection frameworks across the analysis window. The analytical framework segmented by formulation type, end-user category, and regional regulatory cluster to capture divergence in qualification requirements and margin structures. CAGRs were derived from regression analysis of volume and value outputs against herpes simplex virus prevalence trends and generic substitution patterns. Forecast inputs incorporated CDSCO PLI scheme incentive disbursement timelines and EMA ICH Q7 harmonization progress.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH authorization requirement changes for hazardous chemical intermediates and geopolitical disruptions in Chinese purine derivative supply. Forecasts reflect documented assumptions regarding regulatory inspection backlog resolution and bioequivalence study design standardization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Celecoxib API Market
Pharmaceutical Ingredients
Montelukast API Market
Pharmaceutical Ingredients
Oral Transmucosal Drugs Market
Pharmaceutical Ingredients
Global Fibrate Drugs Market
Pharmaceutical Ingredients
Pharmaceutical Grade Beta-Alanine Market
Pharmaceutical Ingredients
Diosmin API Market
Pharmaceutical Ingredients
Pharmaceutical Thermal Analysis Market
Pharmaceutical Ingredients
Pharma-Grade Magnesium Trisilicate Market
Pharmaceutical Ingredients
Cetrorelix Acetate API Market
Pharmaceutical Ingredients
Vitamins and Derivatives Market
Pharmaceutical Ingredients
Asia-Pacific Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceutical Ingredients
Small-Molecule Injectable Market
Pharmaceutical Ingredients
Global Aspirin Market
Pharmaceutical Ingredients
Global Small Molecule API Market
Pharmaceutical Ingredients
Quinoline Market
Pharmaceutical Ingredients
Chlorzoxazone Market