
 Maltitol Based on Corn Starch Market | 2026-2036
Maltitol Based on Corn Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Maltitol Based on Corn Starch Market Insights
ISO 22000 certification is redrawing competitive boundaries for corn-starch-derived maltitol suppliers. Roquette Frères leverages its European malting heritage to sustain premium positioning in pharmaceutical-grade material. Cargill Incorporated anchors North American supply through captive corn processing networks. Shandong Futaste Co. dominates domestic Chinese volume by controlling regional starch conversion capacity.
Maltitol based on corn starch is a hydrogenated disaccharide polyol with approximately ninety percent of sucrose's sweetness and half its caloric value, produced through catalytic hydrogenation of maltose extracted from enzymatically hydrolyzed corn starch. Powder Maltitol leads food manufacturing applications due to superior flow properties in high-speed tableting and coating operations. Liquid Maltitol is gaining traction in beverage formulations where rapid dissolution and viscosity control matter more than shelf stability. Crystal Maltitol occupies the premium tier, serving pharmaceutical firms that require precise particle size distribution for active ingredient binding.
The FDA governs maltitol labeling as a sugar alcohol under 21 CFR 101.80, while the EMA monitors its use in excipient applications through the European Pharmacopoeia. China's SAMR enforces GB standards for food-grade polyol purity, creating divergent compliance pathways for exporters. Stakeholders must track evolving low-sugar claims regulation in target jurisdictions before committing to capacity expansion or formulation partnerships.
Market Dynamics
The FDA's updated nutrition labeling requirements for added sugars are redirecting formulation strategies across North American processed food operations, forcing manufacturers to reformulate with maltitol and other polyols to maintain clean-label positioning while preserving sweetness profiles.
Growth Catalysts
- Sugar Reduction Mandates:The FDA's added sugar disclosure rules under 21 CFR 101.9 are compelling confectionery manufacturers to substitute sucrose with maltitol in chocolate coatings and hard candies.
- China's Shandong Province:Corn starch processing clusters supply multiple maltitol refineries with captive feedstock access, lowering input costs for regional producers serving Asia-Pacific demand.
- Enzymatic Hydrolysis Advances:Improved amylase efficiency in starch conversion is raising maltose yields and reducing hydrogenation cycle times for crystalline maltitol production.
Market Restraints
- Feedstock Concentration Risk:Corn price volatility tied to US Midwest harvest conditions transmits directly to maltitol production economics, squeezing margin buffers for non-integrated refiners.
- Regulatory Divergence:China's SAMR enforces GB 1886.245 purity standards that differ from EMA's European Pharmacopoeia excipient specifications, fragmenting compliance costs for exporters.
- Erythritol Substitution:Zero-calorie sugar alcohols are capturing share in beverage applications where maltitol's laxative warning limits formulation flexibility.
Strategic Opportunities
- Pharmaceutical Excipient Certification:EMA's tightened excipient guidelines under the ICH Q3D elemental impurities framework favor suppliers with documented USP-NF compliance, opening premium tier access.
- India's FSSAI Reformulation Window:Front-of-pack labeling rules for sugar content are accelerating maltitol trials in domestic confectionery and traditional sweet manufacturing.
- Clean-Label Convergence:Pairing maltitol with natural high-intensity sweeteners like stevia glycosides enables deeper sugar reduction without sensory trade-offs in premium chocolate.
Industry Challenges
- ISO 22000 Certification Timelines:Food safety management system audits require 12-18 month implementation cycles, delaying market entry for new entrants targeting European retail chains.
- Hydrogenation Reactor Capex:High-pressure catalytic hydrogenation vessels and palladium catalyst recovery systems demand substantial upfront investment, favoring incumbent capacity expansion over greenfield projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maltitol Based on Corn Starch Market |
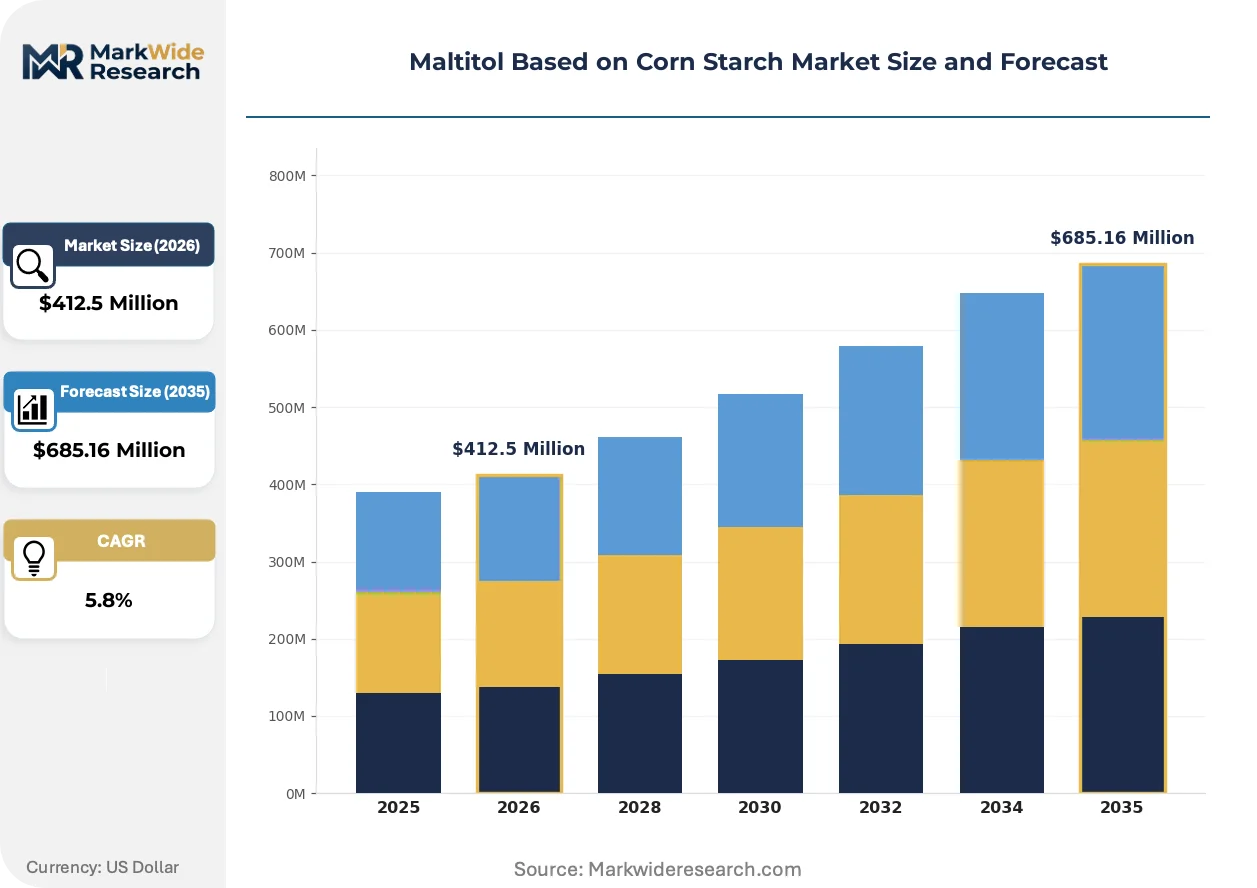
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular Maltitol, Powder Maltitol, Liquid Maltitol, Crystal Maltitol Application: Baked Goods, Confectionery, Beverages, Dairy Products End User: Food Manufacturers, Beverage Companies, Pharmaceutical Firms, Dietary Supplements Packaging Type: Bulk Bags, Sachets, Drums, Retail Packs |
| Companies Covered | Roquette Frères, Cargill Incorporated, Archer Daniels Midland Company, Ingredion Incorporated, Shandong Futaste Co., Tate & Lyle PLC, Zhaoqing Huanfa Biotechnology Co., Gulshan Polyols Ltd., Mitsubishi Corporation Life Sciences Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maltitol Based on Corn Starch Market Trends and Innovations
Continuous processing technologies and regulatory harmonization efforts are compressing production cycles while expanding addressable applications beyond traditional confectionery into pharmaceuticals and functional beverages.
Membrane filtration for maltose purification is fragmenting the traditional centrifugation-dominant process flow. Pharmaceutical-grade maltitol producers in Germany and Switzerland are adopting ceramic membrane cascades to achieve tighter particle size distribution without multiple recrystallization steps. This shift is compressing capital intensity for premium crystal production while raising quality consistency thresholds that batch-oriented competitors struggle to match.
REACH registration requirements for hydrogenation catalysts are tightening supply chain documentation obligations across EU member states. Catalyst suppliers must now submit full substance dossiers covering palladium and nickel-based systems, extending procurement lead times by four to six months. Maltitol refiners with established catalyst recycling partnerships are absorbing these delays better than smaller operators dependent on spot catalyst purchases.
Direct procurement from starch processors is displacing merchant maltose spot markets for integrated refiners. Large confectionery manufacturers in the Netherlands and Belgium are negotiating tolling arrangements with Shandong-based producers, securing volume commitments in exchange for formulation co-development. This channel compression is most visible in chocolate tablet applications where consistent maltitol particle morphology determines coating gloss and snap.
Maltitol Based on Corn Starch Market Segmentation
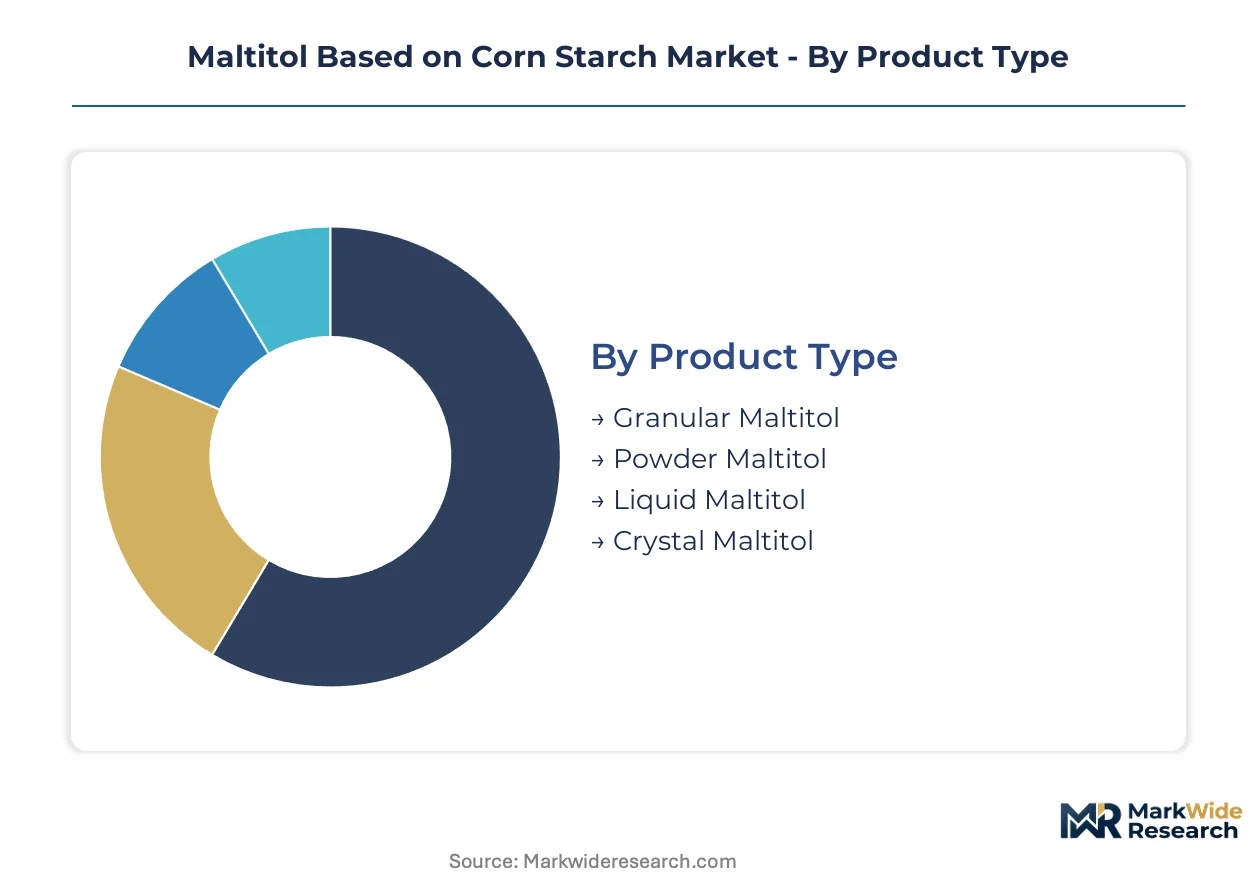
Product form, application intensity, and end-user certification requirements segment maltitol demand into distinct commercial tiers. Each dimension carries unique substitution threats and margin profiles that reshape supplier positioning.
Product Type:
Granular and powder formats face the most intense pressure from erythritol and allulose in high-speed manufacturing, while liquid and crystal grades defend niche positions through functional specificity.
- Powder Maltitol:Spray-dried hydrogenated maltose with controlled particle size distribution enables uniform dispersion in chocolate coatings and compressed tablets. Food manufacturers in the Netherlands and Belgium specify this grade for coating gloss consistency, though erythritol is displacing it in calorie-conscious beverage powders.
- Liquid Maltitol:Aqueous solution at 75% solids content provides viscosity control and humectancy in soft candy centers and bakery fillings. Beverage formulators in Germany favor liquid maltitol for rapid dissolution in functional drinks, but allulose syrup is capturing share in clean-label applications.
- Granular Maltitol:Coarse crystalline form with free-flowing properties suited for dry blending in baking mixes and tabletop sweeteners. Industrial bakeries in France specify granular grades for dough conditioning.
- Crystal Maltitol:High-purity recrystallized product meeting USP-NF and European Pharmacopoeia standards for pharmaceutical excipient use. Swiss and German drug manufacturers demand tight particle size distribution for direct compression tableting.
Powder Maltitol anchors the volume base while Crystal Maltitol gains share at the steepest rate.
Application:
Cost tier stratification separates commodity confectionery from premium functional food applications, with certification requirements driving 40-60% price differentials across use cases.
- Confectionery:Hard candies, chewing gum, and chocolate coatings represent the largest volume outlet, leveraging maltitol's cooling effect and non-cariogenic properties. Manufacturers in China's Shandong Province dominate supply to Asian confectionery exporters, though FDA added-sugar labeling is accelerating reformulation trials in US operations.
- Beverages:Functional drinks and meal replacements utilize liquid maltitol for sweetness and mouthfeel without viscosity spikes. German beverage compounders are testing maltitol-stevia blends for sugar reduction claims, but laxative warning thresholds limit dosage flexibility.
- Baked Goods:Cookies, cakes, and pastries employ granular and powder grades for moisture retention and Maillard browning control. Industrial bakeries in France specify maltitol for extended shelf life in packaged goods.
- Dairy Products:Ice cream and yogurt applications exploit maltitol's freezing point depression and crystallization inhibition. Premium ice cream producers in Switzerland favor crystal grades for smooth texture in reduced-sugar formulations.
Confectionery commands the largest revenue pool while Beverages climb the fastest on functional drink expansion.
End User:
Customer type determines procurement complexity, with pharmaceutical and supplement buyers imposing documentation burdens that exclude commodity-grade suppliers.
- Food Manufacturers:Confectionery and bakery operations purchase bulk powder and granular grades under annual contracts with quality consistency clauses. Large European chocolate manufacturers negotiate tolling arrangements with Shandong-based refiners.
- Pharmaceutical Firms:Excipient applications demand USP-NF or European Pharmacopoeia compliance with full ICH Q3D elemental impurity documentation. German and Swiss generic drug producers specify crystal maltitol for orodispersible tablets.
- Beverage Companies:Functional drink and meal replacement manufacturers source liquid maltitol in tanker quantities with rapid microbiological turnaround. German compounders lead adoption of maltitol-stevia hybrid sweetening systems.
- Dietary Supplements:Protein bars and meal replacement powders utilize granular maltitol for binding and sweetness without cooling aftertaste. US supplement brands are reformulating away from sugar alcohols due to consumer digestive sensitivity concerns.
Food Manufacturers anchor volume demand while Pharmaceutical Firms expand most quickly on excipient certification premiums.
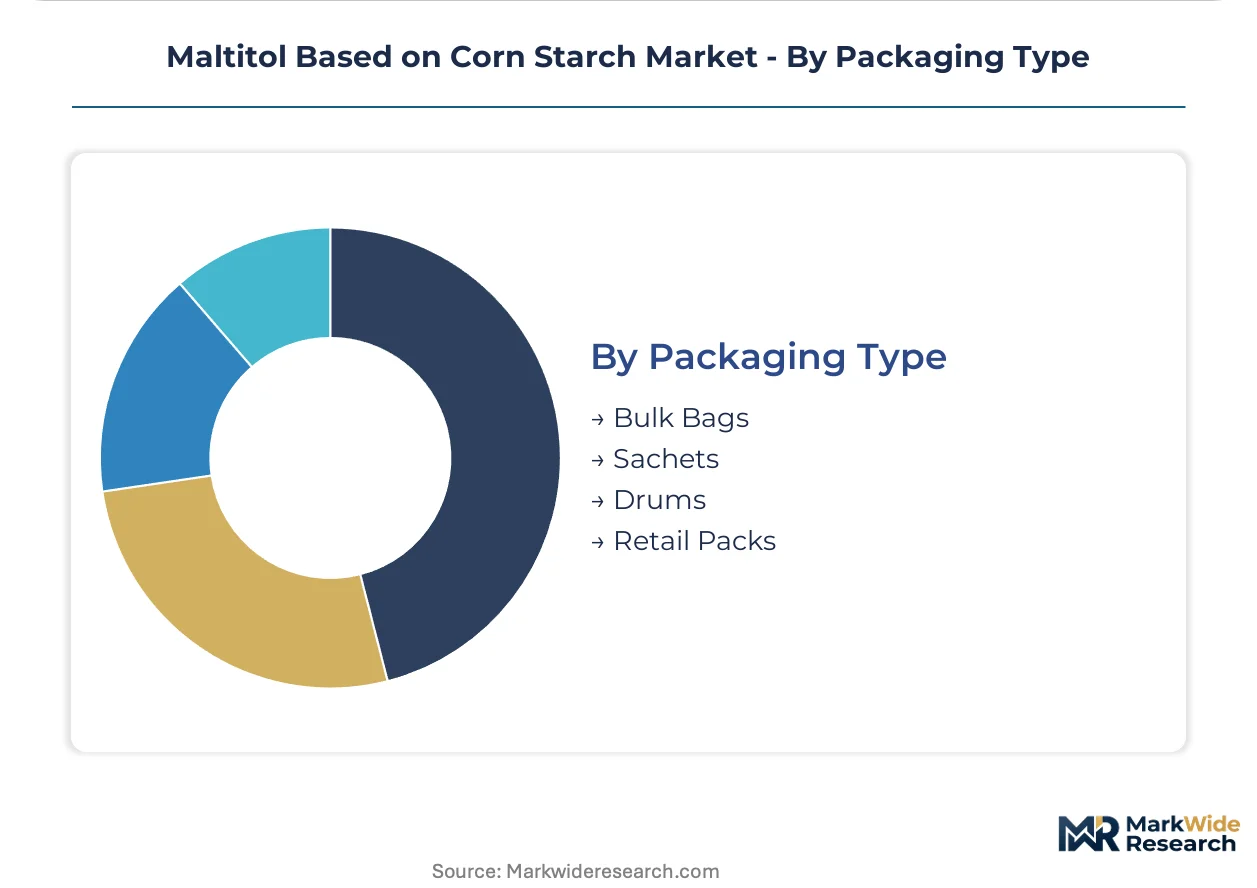
Packaging Type:
Supply concentration in Shandong Province shapes packaging economics, with bulk formats capturing integrated refiners' output and retail packs serving formulation R&D and artisan producers.
- Bulk Bags:One-tonne flexible intermediate bulk containers serve high-volume food manufacturers with dedicated silo systems. Shandong Futaste and similar integrated producers ship predominantly in bulk to European confectionery compounders.
- Drums:200-250 kg steel or plastic drums protect liquid maltitol from moisture ingress during ocean freight. German beverage formulators specify drum packaging for flexible batch sizing.
- Sachets:25-50 kg moisture-barrier bags support mid-scale bakery and supplement operations without bulk handling infrastructure. French industrial bakeries favor sachet formats for recipe flexibility.
- Retail Packs:1-5 kg consumer and small-business packaging serves artisan confectioners and formulation laboratories. Swiss pharmaceutical R&D departments purchase retail crystal grades for excipient compatibility testing.
Bulk Bags dominate tonnage movement while Retail Packs expand fastest on artisan and R&D demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Qingdao port complex in Shandong Province anchors Asia-Pacific maltitol logistics, handling bulk corn starch feedstock imports and refined polyol exports through dedicated liquid bulk terminals.
United States
FDA's added-sugar disclosure rules under 21 CFR 101.9 are compelling confectionery manufacturers in Chicago and Philadelphia to reformulate chocolate coatings with maltitol. The Corn Belt's ethanol production network supplies starch processors in Iowa and Illinois with captive feedstock streams. Cargill's Minneapolis-based operations coordinate North American distribution through river barge terminals on the Mississippi.
China
Shandong Province's enzymatic hydrolysis clusters process over half of domestic corn starch into maltose precursors for hydrogenation. SAMR's GB 1886.245 purity standards enforce tighter heavy metal thresholds than export markets, creating dual compliance tracks for Qingdao port shipments. Shandong Futaste and regional refineries in Weifang and Zibo dominate crystalline maltitol output for pharmaceutical excipient contracts.
Germany
Beverage compounders in Hamburg and Cologne are trialing maltitol-stevia hybrid systems for functional drink lines under EFSA's pending novel food opinions. REACH registration requirements for palladium hydrogenation catalysts have extended procurement cycles by four to six months. The Port of Rotterdam's liquid bulk terminals serve as the import gateway for Shandong-origin liquid maltitol serving Rhineland chocolate manufacturers.
Switzerland
Swissmedic's tightened excipient guidelines under ICH Q3D elemental impurities frameworks favor suppliers with documented USP-NF compliance for orodispersible tablet applications. Basel's pharmaceutical cluster sources crystal maltitol through Swiss distributors with full batch traceability documentation. Geneva-based trading houses coordinate tolling arrangements between European drugmakers and Shandong refiners.
India
FSSAI's front-of-pack labeling rules for sugar content are accelerating maltitol trials in Mumbai and Pune confectionery operations. Gujarat's corn processing belt near Ahmedabad supplies starch to emerging maltitol refineries targeting domestic sugar-free traditional sweet markets. The Jawaharlal Nehru Port Trust handles bulk polyol imports for South Indian beverage manufacturers in Bengaluru.
Maltitol Based on Corn Starch Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, with publicly traded agribusiness conglomerates anchoring volume supply while family-owned refineries capture pharmaceutical-grade premiums. The market structure concentrates around three to five integrated starch-to-polyol operators with captive feedstock access, flanked by merchant refiners dependent on spot maltose procurement. Strategic archetypes include: integrated agribusinesses with corn processing networks, regional starch specialists with hydrogenation capabilities, and pharmaceutical excipient distributors with certification documentation. Dominant competitive moves involve backward integration into corn milling and tolling partnerships with confectionery compounders.
Within the integrated agribusiness tier, Roquette Frères and Cargill Incorporated exemplify players leveraging malting heritage and captive corn networks respectively. Shandong Futaste Co. occupies a position among regional starch specialists with concentrated capacity in China's processing heartland. These three anchors represent distinct geographic and structural approaches to maltitol supply.
| Leading Market Players |
|---|
| Roquette Frères |
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Shandong Futaste Co. |
| Tate & Lyle PLC |
| Zhaoqing Huanfa Biotechnology Co. |
| Gulshan Polyols Ltd. |
| Mitsubishi Corporation Life Sciences Limited |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Shandong refiners and European confectionery compounders lock in both maltitol supply access and eighteen-month price visibility, insulating integrated processors from corn starch spot volatility while exposing merchant buyers to feedstock cost transmission.
Pricing Analysis
Volume-discount tiering separates pharmaceutical-grade crystal maltitol from commodity powder grades, with USP-NF certification commanding forty to sixty percent premiums over food-grade material. Pricing stratifies across premium, standard, and economy tiers based on purity thresholds and particle size distribution precision. Cost compression in standard-grade powder runs through erythritol substitution pressure in beverage applications. Beverage manufacturers exhibit highest price sensitivity due to formulation flexibility requirements, while pharmaceutical firms accept premium pricing for excipient documentation.
Supply Chain Analysis
China and the United States anchor corn starch processing and maltitol hydrogenation capacity, with Germany and Switzerland specializing in pharmaceutical-grade refinement. Feedstock draws from US Midwest corn belts and Shandong Province starch clusters, while palladium catalyst supply rests on South African and Russian mining output. Single-source vulnerability concentrates in Shandong's enzymatic hydrolysis corridor, where port congestion at Qingdao disrupts European confectionery supply. Distribution runs through Rotterdam liquid bulk terminals for Rhineland manufacturers and Mississippi river barge networks for North American food processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Excipient certification services and tolling arrangement management represent the fastest-expanding recurring-revenue layer, outpacing crystalline maltitol hardware margins as pharmaceutical documentation requirements intensify.
For Market Incumbents: Secure backward integration into corn milling capacity in Iowa or Shandong to defend margin buffers against feedstock volatility. Lock in ISO 22000 certification ahead of European retail chain procurement mandates to exclude merchant refiners from premium tier access. Erythritol zero-calorie positioning threatens standard-grade powder volumes, necessitating formulation co-development partnerships with stevia suppliers for hybrid sweetening systems. For New Entrants and Emerging Players: Anchor in India's FSSAI reformulation window for traditional sweet manufacturing, where domestic starch processing infrastructure remains underdeveloped. Target pharmaceutical excipient distribution partnerships in Basel and Geneva, where Swissmedic documentation requirements favor nimble specialists over commodity refiners. Lead with membrane filtration technology adoption to compress crystal maltitol production cycles against batch-oriented incumbents. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among excipient distributors with USP-NF batch traceability capabilities, generating service-attach multiples above commodity refining operations. Long-term viability favors integrated starch-to-polyol operators with captive Qingdao port access and established catalyst recycling partnerships. Watch FDA enforcement patterns on added-sugar labeling claims as inflection indicator for North American reformulation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Milling | Cargill's captive Iowa starch networks demonstrate margin insulation against Midwest harvest volatility. |
| Pharmaceutical Excipient Certification | EMA's ICH Q3D framework favors suppliers with documented USP-NF compliance for orodispersible tablets. |
| Membrane Filtration Technology Adoption | German ceramic membrane cascades compress capital intensity for premium crystal production cycles. |
| Tolling Arrangement Expansion | Shandong-European chocolate compounder partnerships secure volume through formulation co-development. |
| Catalyst Recycling Partnership | Palladium recovery systems extend procurement lead times under REACH registration requirements. |
Research Methodology
The analysis maps hydrogenation reactor capacity, enzymatic hydrolysis yield rates, and excipient certification tiers, each validated through plant managers at starch processing facilities, procurement leads at European confectionery compounders, and regulatory affairs specialists at pharmaceutical excipient distributors. Primary interviews with Shandong refinery operations directors and Rotterdam bulk terminal logistics coordinators combined with secondary validation from FDA 21 CFR filings, EMA European Pharmacopoeia updates, and SAMR GB standard disclosures. Bottom-up capacity modeling and top-down demand estimation triangulate volume figures across the projection horizon.
Consistency checks against customs trade data and SEC agribusiness segment disclosures validated analytical framework outputs. Segmentation dimensions modeled include product form tier, application intensity, end-user certification requirement, and regional production hub clustering. CAGRs derived from feedstock cost trajectory analysis and substitution elasticity estimates for erythritol and allulose in beverage applications. Hydrogenation cycle time compression and membrane filtration adoption curves inform technology-driven supply expansion assumptions.
Material uncertainties — corn price volatility tied to US ethanol policy shifts, REACH catalyst registration delays, and FSSAI enforcement intensity — sit outside the modeled envelope. Forecasts reflect assumptions on regulatory harmonization timelines and enzymatic yield improvement trajectories. Recalibration cycles align with material shifts in FDA added-sugar labeling enforcement and EMA excipient guideline revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global PVC Additives Market
Additives
Marine Fuel Additives Market
Additives
Amino Acids Premixes Market
Additives
Adjustive Agents Market
Additives
Rosin Ester Market
Additives
Wax Additives Market
Additives
Asia-Pacific Concrete Admixtures Market
Additives
Plasticizers Market
Additives
Global Mold Release Agents Market
Additives
Tricalcium Citrate Market
Additives
Metal Modifiers Market
Additives
Sodium Potassium Tartrate Market
Additives
Citrate Ester Market
Additives
Microcrystalline Cellulose (MCC) Market
Additives
South Africa Acidulants Market
Additives
Chelating Agents Market