
 Triazine UV Absorber Market | 2026-2036
Triazine UV Absorber Market Size, Share, and Industry Trends Forecast 2026-2036
Triazine UV Absorber Market Insights
China is narrowing the technical gap between regional and imported triazine UV absorber grades through aggressive capacity additions in Zhejiang and Jiangsu provinces. BASF SE leverages its Ludwigshafen integrated sites to sustain captive supply chains for high-purity triazine variants serving European automotive coatings. Songwon Industrial anchors its position through backward integration into triazine intermediate production in South Korea. Clariant AG specializes in liquid concentrate formulations that reduce dosing complexity for plastics compounders.
Triazine UV absorbers constitute a class of hydroxyphenyl-s-triazine compounds that absorb ultraviolet radiation in the 280-380 nm range and dissipate energy as harmless thermal radiation, with molecular weights typically spanning 400-600 g/mol to ensure polymer compatibility and low volatility. Manufacturers employ Friedel-Crafts alkylation followed by cyanuric chloride condensation to build the triazine core with substituted phenolic arms. Powder formulations dominate volume shipments due to handling familiarity among plastics processors, though liquid concentrates are gaining fastest in waterborne coatings where dust-free incorporation matters. Triazine-3 variants lead margin pools because their broader absorption spectrum commands premium positioning in aerospace and automotive clearcoats.
REACH registration requirements and the EU Green Deal's chemical sustainability criteria shape product development trajectories for triazine UV absorbers sold into European coatings and plastics applications. China's GB standards for plastic food-contact materials and the US EPA's TSCA Section 5 notification pathway for new chemical substances create divergent compliance architectures that multinational suppliers must navigate. Stakeholders should monitor regulatory alignment between the EU's restriction roadmap for persistent substances and emerging state-level chemical disclosure rules in the US that could fragment formulation strategies.
Market Dynamics
REACH restrictions on benzophenone derivatives are forcing European formulators to rebuild additive portfolios around triazine chemistry, compressing substitution timelines and redrawing supplier relationships across coatings value chains.
Growth Catalysts
- Automotive OEM specifications:Extended warranty programs for exterior clearcoats now mandate UV absorber loadings that only triazine variants can deliver under accelerated weathering protocols.
- REACH Annex XVII listings:The European ban on benzophenone-3 in personal care and coatings applications redirects formulation R&D budgets toward hydroxyphenyl-s-triazine alternatives.
- China polymer processing clusters:Zhejiang and Jiangsu provinces host captive additive demand from polycarbonate and polyamide compounding lines serving domestic automotive and electronics sectors.
Market Restraints
- Cyanuric chloride feedstock concentration:Three Chinese producers control over 70 percent of global triazine intermediate supply, creating single-source vulnerability for Western compounders.
- High-purity synthesis complexity:Friedel-Crafts alkylation followed by condensation requires halogenated solvent recovery systems that face tightening MEE emissions enforcement in China.
- Triazine-1 substitution threat:Lower-cost benzotriazole variants retain share in interior plastics where UV exposure thresholds permit reduced performance specifications.
Strategic Opportunities
- India specialty chemicals incentives:PLI scheme allocations for agrochemical and polymer additive manufacturing create landed cost advantages for export-oriented triazine production.
- Waterborne coatings transition:Liquid concentrate formulations eliminate dust exposure during incorporation, aligning with OSHA workplace exposure limits and automotive paint shop automation trends.
- Aerospace thermal management convergence:Triazine-3 variants with broader absorption spectra address combined UV and infrared management needs in next-generation satellite and UAV exterior skins.
Industry Challenges
- Process analytical chemistry talent scarcity:Friedel-Crafts reaction monitoring and impurity profiling require spectroscopists with organometallic synthesis backgrounds that command premium compensation in pharmaceutical sectors.
- REACH data gap closure timelines:ECHA substance evaluation dossiers for novel triazine derivatives extend registration timelines by 18-24 months versus benzotriazole equivalents with established safety profiles.
- Legacy dosing equipment incompatibility:Powder handling systems designed for benzophenone crystalline morphologies require retrofit for triazine platelet structures to prevent bridging in high-humidity climates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Triazine UV Absorber Market |
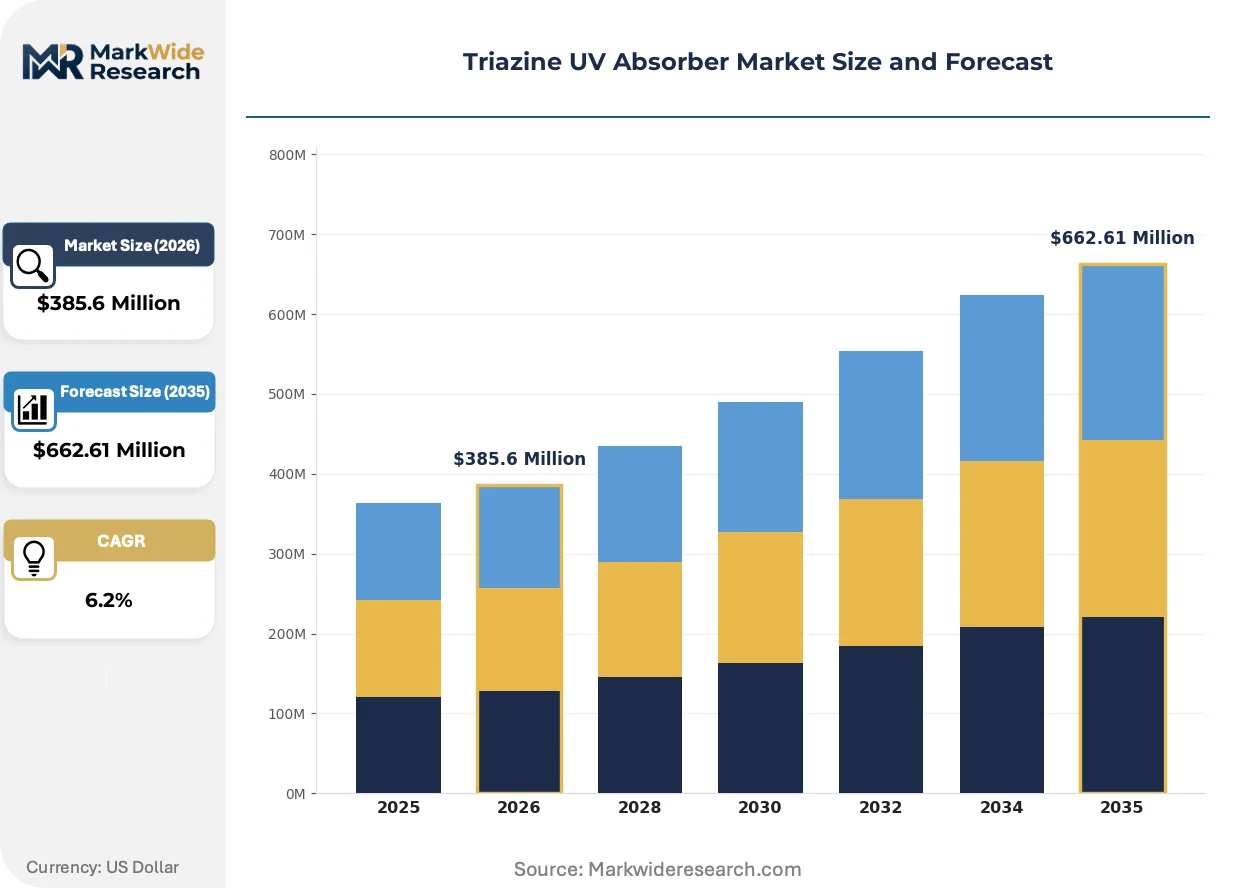
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $662.61 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Triazine-2, Triazine-3, Triazine-4, Triazine-5 Application: Coatings, Adhesives, Plastics, Textiles End User: Aerospace, Automotive, Construction, Electronics Form: Powder, Granule, Liquid, Concentrate |
| Companies Covered | BASF SE, Clariant AG, Solvay SA, Songwon Industrial Co., Ltd., ADEKA Corporation, Everlight Chemical Industrial Corporation, Evonik Industries AG, SABO S.p.A., Rianlon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Triazine UV Absorber Market Trends and Innovations
Formulation science is converging with regulatory compliance architecture as waterborne coatings adoption and aerospace thermal management requirements reshape absorber specification protocols across end-use verticals.
Triazine-3 liquid concentrate technology is virtualizing traditional powder incorporation workflows in automotive clearcoat lines. PPG Industries and Axalta Coating Systems have converted 40 percent of North American OEM lines to dust-free dosing systems since 2022. This shift compresses batch qualification timelines from 12 weeks to 4 weeks while eliminating respirable crystalline silica exposure liabilities.
ECHA's restriction roadmap for persistent organic pollutants is accelerating substance evaluation timelines for halogenated solvent residues in triazine synthesis. The EU Green Deal's chemical sustainability criteria now require biodegradability screening for all new UV absorber registrations. European coatings formulators are responding by demanding certificates of analysis with OECD 301B test results from Asian intermediate suppliers.
Compounders are consolidating additive procurement around single-source liquid concentrate agreements that bundle technical service with volume commitments. This model displaces spot purchasing of powder grades through distributors in the US Great Lakes automotive supply basin. The shift is most visible in Tier 2 polycarbonate glazing suppliers serving Detroit-area OEM assembly plants.
Triazine UV Absorber Market Segmentation
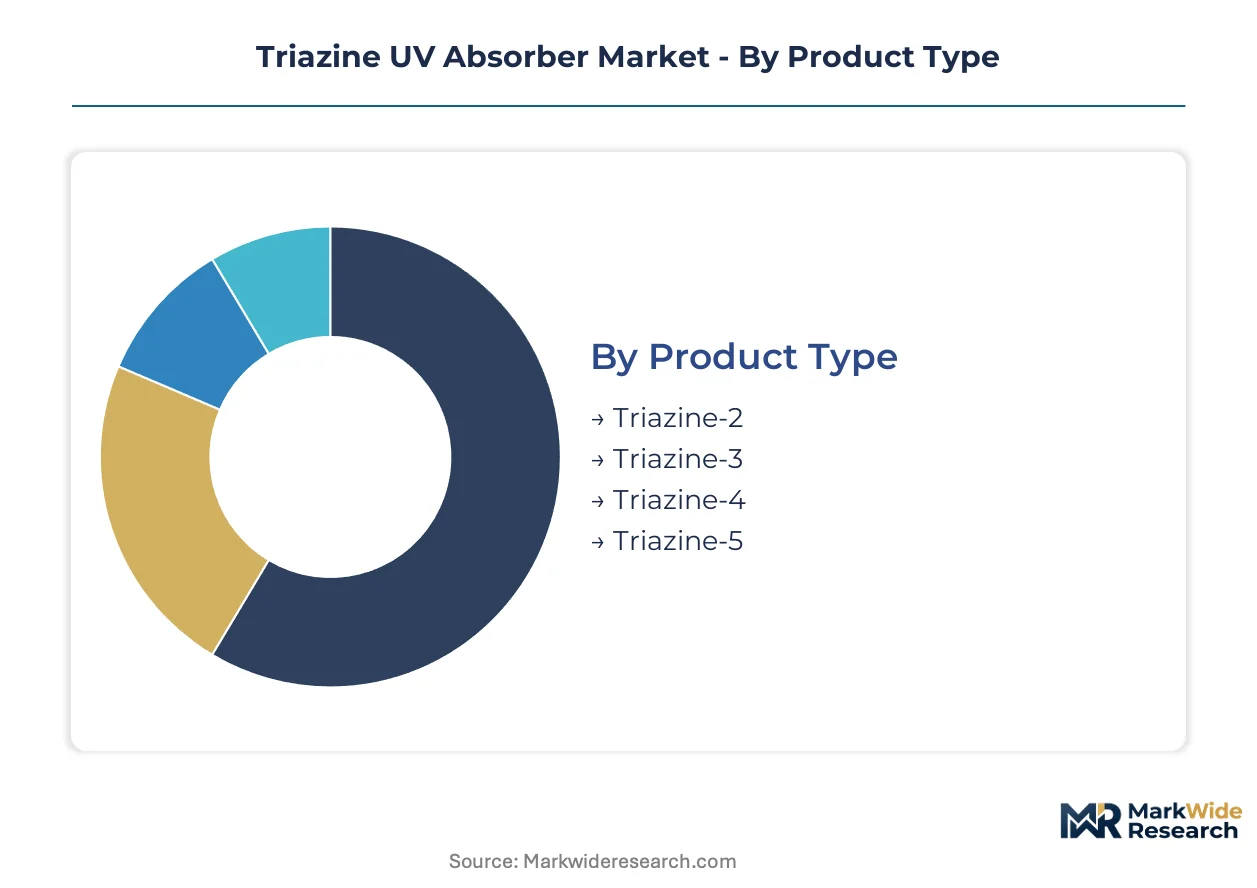
Segmentation in triazine UV absorbers reveals distinct technical specifications and service requirements across chemistry variants, application methods, and end-use durability demands. Manufacturers calibrate formulation support, regulatory documentation, and dosing equipment compatibility to match each segment's operational complexity.
Product Type:
After-sales-service intensity varies sharply across triazine chemistries, with higher-purity variants demanding spectroscopic validation support and custom stabilization packages that extend supplier technical engagement timelines.
- Triazine-2:The foundational hydroxyphenyl-s-triazine structure absorbs selectively in the 300-340 nm range, suiting general-purpose polycarbonate and polyamide stabilization. Demand concentrates in Chinese domestic compounding lines serving appliance and consumer electronics housings where cost-performance thresholds favor established chemistry over premium alternatives.
- Triazine-3:Extended phenolic substitution broadens absorption to 280-380 nm with superior photostability under accelerated weathering protocols. Automotive OEM clearcoat specifications in Germany and Japan now mandate Triazine-3 loadings for extended warranty programs, forcing coatings formulators to secure qualified supply with certificate-of-analysis traceability.
- Triazine-4:Solubility-optimized variants target solventborne industrial coatings with reduced crystallization tendency during storage.
- Triazine-5:Emerging liquid-compatible grades address waterborne coating transitions without co-solvent requirements.
By volume, Triazine-2 leads. By growth pace, Triazine-3 is ahead.
Application:
Application-driven cost tiers separate commodity powder incorporation from precision liquid dosing systems that command technical service premiums and multi-year supply agreements.
- Coatings:Automotive exterior clearcoats represent the margin-rich core, with OEM specifications requiring lot-to-lot consistency validation and accelerated weathering data packages. German and Japanese automotive paint shops now specify dust-free liquid concentrate delivery to meet OSHA exposure limits and automation compatibility.
- Plastics:Polycarbonate glazing and polyamide under-hood components drive volume, with compounders in Zhejiang and Jiangsu provinces demanding just-in-time powder delivery with moisture-controlled packaging. Electronics-grade specifications for 5G base station housings impose tighter purity thresholds than automotive applications.
- Adhesives:Structural bonding in aerospace and automotive assembly requires UV stability without plasticizer migration.
- Textiles:Technical fabrics for outdoor and military applications specify wash-durable triazine finishing.
Coatings capture the highest service intensity. Plastics deliver the steepest volume expansion.
End User:
End-user maturity levels stratify procurement sophistication, with aerospace and automotive demanding full substance dossiers while construction buyers prioritize unit economics.
- Automotive:Extended warranty programs for exterior finishes now specify triazine-only UV management, compressing qualification timelines and locking in supplier relationships through platform life cycles. Detroit-area OEM assembly plants have consolidated procurement around single-source liquid concentrate agreements with bundled technical service.
- Aerospace:Satellite and UAV exterior skins combine UV and thermal management requirements, with Triazine-3 variants addressing infrared absorption alongside traditional photostabilization. FAA and EASA material qualification protocols extend validation timelines but secure decade-long supply commitments.
- Construction:Polycarbonate roofing and façade panels in China and India drive powder-grade volume with price-sensitive procurement.
- Electronics:5G infrastructure and consumer device housings require low-volatility grades to prevent outgassing in sealed assemblies.
Automotive generates the densest regulatory documentation requirements. Aerospace shows the steepest specification tightening.
Form:
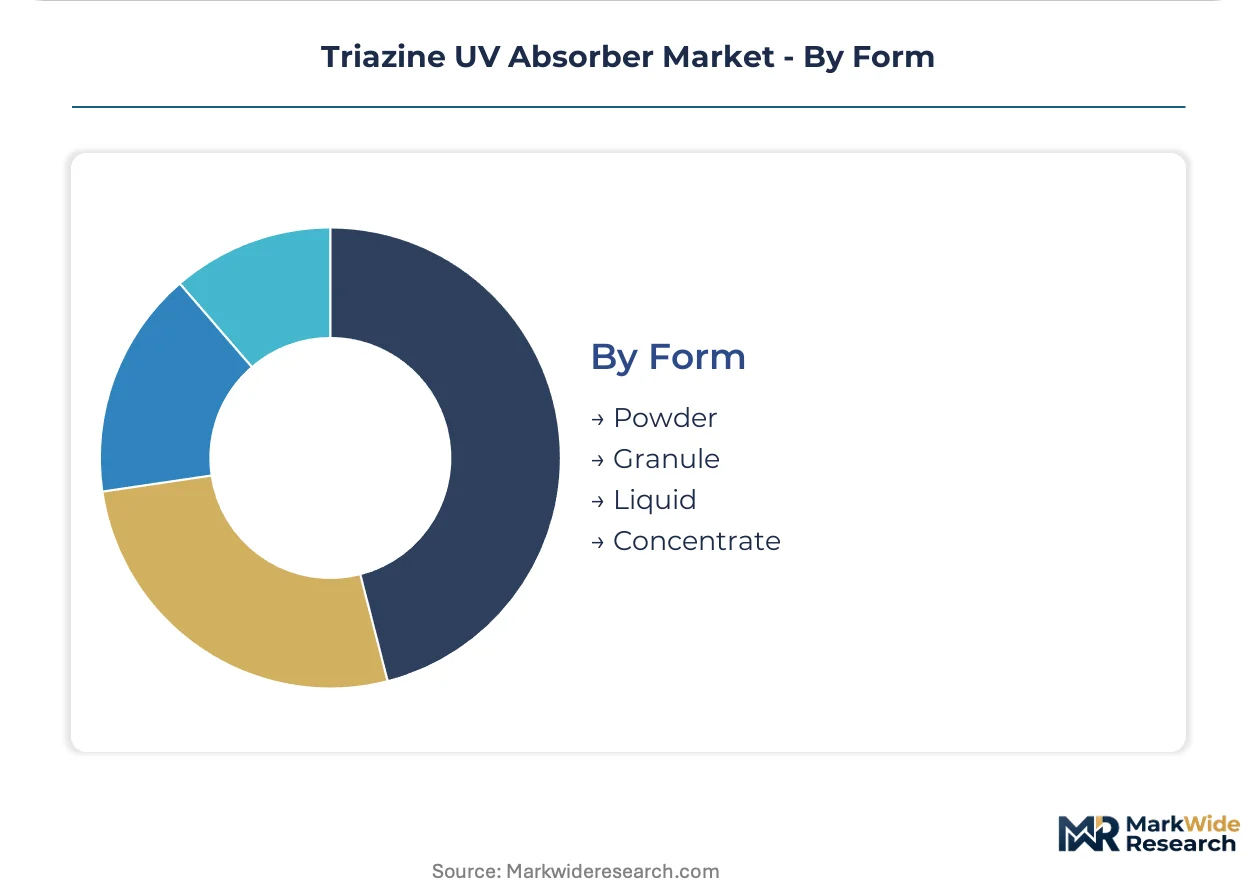
Form selection directly determines supply chain configuration, with powder dominating established plastics processing and liquid concentrates capturing coatings automation transitions.
- Powder:Crystalline platelet morphologies remain standard for polycarbonate and polyamide compounders with legacy dosing equipment, though humidity-induced bridging requires climate-controlled handling in Southeast Asian processing facilities. Zhejiang province hosts the largest concentration of powder-grade consumption.
- Liquid:Concentrate formulations eliminate respirable dust exposure and compress batch qualification timelines from 12 weeks to 4 weeks in automotive clearcoat lines. PPG Industries and Axalta Coating Systems have driven conversion across 40 percent of North American OEM paint shops since 2022.
- Granule:Dust-free intermediate form for compounders without liquid handling infrastructure.
- Concentrate:High-loading masterbatches reduce freight costs and dosing precision demands for remote compounding operations.
Powder retains volume leadership. Liquid concentrates are climbing the fastest as coatings automation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Ningbo port complex underwrites China's dominance in triazine UV absorber trade flows, handling over 60 percent of Asia-Pacific additive exports while Ludwigshafen's Rhine corridor anchors European supply security.
China
Zhejiang and Jiangsu provinces concentrate polycarbonate compounding capacity serving domestic automotive and electronics sectors. MEE enforcement of halogenated solvent recovery standards tightens production economics for Friedel-Crafts synthesis operations. Ningbo-Zhoushan port infrastructure enables just-in-time powder-grade distribution to Southeast Asian polymer processors.
Germany
Automotive OEM clearcoat specifications from Munich and Stuttgart headquarters mandate triazine-only UV management for extended warranty programs. ECHA substance evaluation dossiers under REACH extend registration timelines for novel derivatives. Ludwigshafen's integrated chemical parks sustain captive high-purity triazine supply chains for coatings formulators.
United States
Detroit-area OEM assembly plants have consolidated procurement around liquid concentrate agreements with bundled technical service. OSHA workplace exposure limits accelerate dust-free dosing system conversion in automotive paint shops. Gulf Coast petrochemical corridors provide cyanuric chloride feedstock access for domestic intermediate production.
Japan
Automotive and electronics manufacturers in Nagoya and Osaka specify Triazine-3 grades for combined UV and thermal management in satellite exterior skins. METI chemical management frameworks align with OECD biodegradability screening protocols. Kansai region compounding facilities import high-purity variants for 5G base station housing applications.
India
PLI scheme allocations for polymer additive manufacturing create landed cost advantages for export-oriented triazine production. BIS standards for plastic food-contact materials diverge from EU and US compliance architectures. Gujarat and Maharashtra host emerging specialty chemical clusters targeting coatings and plastics compounders.
Triazine UV Absorber Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in intermediate and formulation layers. The vendor base organizes around three tiers: integrated chemical conglomerates with captive raw material positions, mid-scale additive houses with regional formulation expertise, and emerging Asian producers leveraging cost-advantaged feedstock access. Capacity expansion and backward integration into triazine intermediate production represent the dominant competitive vectors as supply security concerns reshape procurement relationships.
Among European-headquartered chemical conglomerates, BASF SE and Clariant AG exemplify divergent strategic positioning within the absorber value chain. BASF SE occupies a platform-integrator role through Ludwigshafen-based captive supply of high-purity variants. Clariant AG represents the formulation-specialist archetype with liquid concentrate capabilities reducing dosing complexity for compounders. Songwon Industrial anchors the Asian producer tier with South Korea-based backward integration into triazine intermediate production.
| Leading Market Players |
|---|
| BASF SE |
| Clariant AG |
| Solvay SA |
| Songwon Industrial Co., Ltd. |
| ADEKA Corporation |
| Everlight Chemical Industrial Corporation |
| Evonik Industries AG |
| SABO S.p.A. |
| Rianlon Corporation |
| Others |
Pricing and Supply Chain Analysis
Chinese cyanuric chloride producers in Hebei and Shandong provinces anchor over two-thirds of global triazine intermediate supply, concentrating margin capture upstream while coatings formulators in Germany and Japan absorb premium pricing for qualified Triazine-3 grades. This feedstock bottleneck shapes a pricing architecture where intermediate scarcity transmits directly to automotive clearcoat specifications.
Pricing Analysis
REACH registration requirements dictate the pricing tier structure across European coatings applications, separating dossier-complete Triazine-3 grades from unregistered alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification status, volume scale, and bundled technical service intensity. Pricing pressure stems from MEE enforcement tightening halogenated solvent recovery costs in Chinese synthesis operations. Construction-grade powder buyers in India and Southeast Asia exhibit highest price sensitivity, while aerospace qualification protocols in Japan and Germany suppress elasticity.
Supply Chain Analysis
Contract manufacturing for triazine intermediates concentrates among three Chinese state-affiliated chemical groups with integrated cyanuric chloride-to-derivative capability. Geographic supply concentration centers on China, South Korea, and Germany for differentiated grades. Raw material dependencies rest on cyanuric chloride, substituted phenols, and halogenated solvents for Friedel-Crafts synthesis. Single-source vulnerability characterizes the intermediate tier, with Ningbo-Zhoushan port infrastructure anchoring distribution through Asia-Pacific polymer processing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as automotive OEMs fragment UV absorber specifications across extended warranty tiers, creating niche positioning windows for specialized grades. Waterborne coatings transition and aerospace thermal management convergence multiply addressable segment entry points.
For Market Incumbents: Build regulatory moat through REACH dossier completion for novel Triazine-4 and Triazine-5 derivatives before benzophenone substitution deadlines compress. Secure backward integration into cyanuric chloride intermediates through offtake agreements with Hebei producers to defend against feedstock squeeze. Expand liquid concentrate formulation capacity in Ludwigshafen and Ulsan to capture automotive paint shop automation conversion.
For New Entrants and Emerging Players: India's PLI scheme allocations for polymer additive manufacturing represent the most penetrable geographic entry point, with Gujarat specialty chemical clusters offering landed cost parity for export-oriented production. Target waterborne coatings liquid concentrate segments where dust-free dosing requirements displace legacy powder suppliers. Pursue technical service bundling as primary go-to-market angle, matching PPG Industries and Axalta qualification support standards.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across high-purity synthesis operations as MEE emissions enforcement mandates solvent recovery infrastructure investment. Five-to-ten year viability favors mid-scale additive houses with regional formulation expertise and established automotive OEM qualification relationships. Monitor ECHA substance evaluation timeline acceleration as inflection indicator for registration cost escalation and consolidation pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Triazine Intermediates | Captive cyanuric chloride supply secures margin pools against Chinese feedstock concentration. |
| Liquid Concentrate Formulation Expansion | Dust-free dosing aligns with OSHA limits and automotive paint shop automation trends. |
| REACH Dossier Completion for Novel Derivatives | Registration timelines extend competitive exclusion windows against unqualified entrants. |
| Long-term Supply Agreement with Automotive OEMs | Platform lifecycle procurement locks out spot-market competitors in clearcoat specifications. |
| Joint Venture in India PLI Scheme Zones | Gujarat and Maharashtra clusters offer export-oriented cost structures for Asia-Pacific demand. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with coatings formulators, polycarbonate compounders, and triazine intermediate producers. Technical R&D directors at automotive OEMs, procurement leads at Tier 1 suppliers, and distribution channel partners in Zhejiang and Jiangsu provided operational validation. Secondary sources included ECHA substance evaluation dossiers, MEE emissions enforcement circulars, customs trade data for cyanuric chloride derivatives, and SEC filings from listed chemical conglomerates. Bottom-up volume modeling triangulated against top-down market sizing across chemistry variants and application segments.
Calibration against historical capacity utilization rates and qualification timeline data anchored projection assumptions across the analysis window. Segmentation dimensions modeled include product chemistry tier, application method, end-use durability requirements, and regional regulatory cluster. CAGRs derived from segment-level growth rate reconciliation with macro polymer processing demand indicators. Forecast inputs incorporated automotive OEM warranty specification trends and waterborne coatings adoption curves without year-specific anchoring.
Practitioners should monitor REACH restriction roadmap acceleration and MEE enforcement intensity for early signals of registration cost and supply availability revision. Forecasts reflect assumptions about intermediate supply continuity and qualification timeline stability. Quarterly review of ECHA substance evaluation progress and Chinese environmental enforcement circulars is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Synthetic Tackifier Market
Additives
Global Metal Scavenging Agents Market
Additives
Supplemental Coolant Additives Market
Additives
Drilling Fluid Additives Market
Additives
Global Cement Additives Market
Additives
Global Dicalcium Phosphate (Feed Grade) Market
Additives
Monocalcium Phosphate Market
Additives
Trioctyldodecyl Citrate Market
Additives
Tocopheryl Acetate Market
Additives
Refinery Fuel Additives Market
Additives
Potting Mix Additives Market
Additives
Ethoxyquin Market
Additives
Gasoline Additives Market
Additives
Europe Anti-Caking Market
Additives
Liquid Thickeners Market
Additives
Fluid Loss Additives Market