
 Metformin Hydrochloride API Market | 2026-2036
Metformin Hydrochloride API Market Size, Share, and Industry Trends Forecast 2026-2036
Metformin Hydrochloride API Market Foresight
Capital-intensity divergence between large-scale fermentation facilities and smaller synthetic chemistry operations is reorganizing competitive tiers in metformin hydrochloride API supply. Merck KGaA leverages its integrated fermentation infrastructure to anchor European supply security. Dr. Reddy's Laboratories Ltd. sustains cost leadership through backward integration into key starting materials. Wanbury competes aggressively on volume contracts with Indian and African formulation customers.
Metformin hydrochloride API is the hydrochloride salt form of a biguanide antihyperglycemic agent, typically manufactured through a multi-step chemical synthesis starting from dimethylamine and cyanoguanidine, with final purity specifications generally exceeding 99.5% and stringent limits on related substances including melamine and cyanamide derivatives. Its primary commercial purpose is serving as the active pharmaceutical ingredient in oral antidiabetic formulations for type 2 diabetes mellitus. Tablet formulations occupy the largest volume share among product types due to decades of established prescribing patterns and patient familiarity. Extended-release formulations represent the fastest-expanding product category as clinicians prioritize gastrointestinal tolerability and adherence outcomes. Diabetes management applications command the dominant share of API offtake, while polycystic ovary syndrome represents an emerging indication driving incremental demand growth.
The US FDA enforces ICH Q3D elemental impurity guidelines and evolving nitrosamine risk assessment protocols that directly dictate batch release criteria and facility inspection priorities for metformin API producers. India's CDSCO aligns with WHO prequalification standards for export-oriented manufacturers, creating dual compliance burdens that filter out subscale competitors. The EU EMA applies REACH obligations and F-Gas Regulation constraints on certain process solvents, adding environmental compliance layers to manufacturing economics. Stakeholders must monitor how regulatory divergence on impurity thresholds between FDA and EMA specifications reshapes contract manufacturing location decisions and qualification timelines.
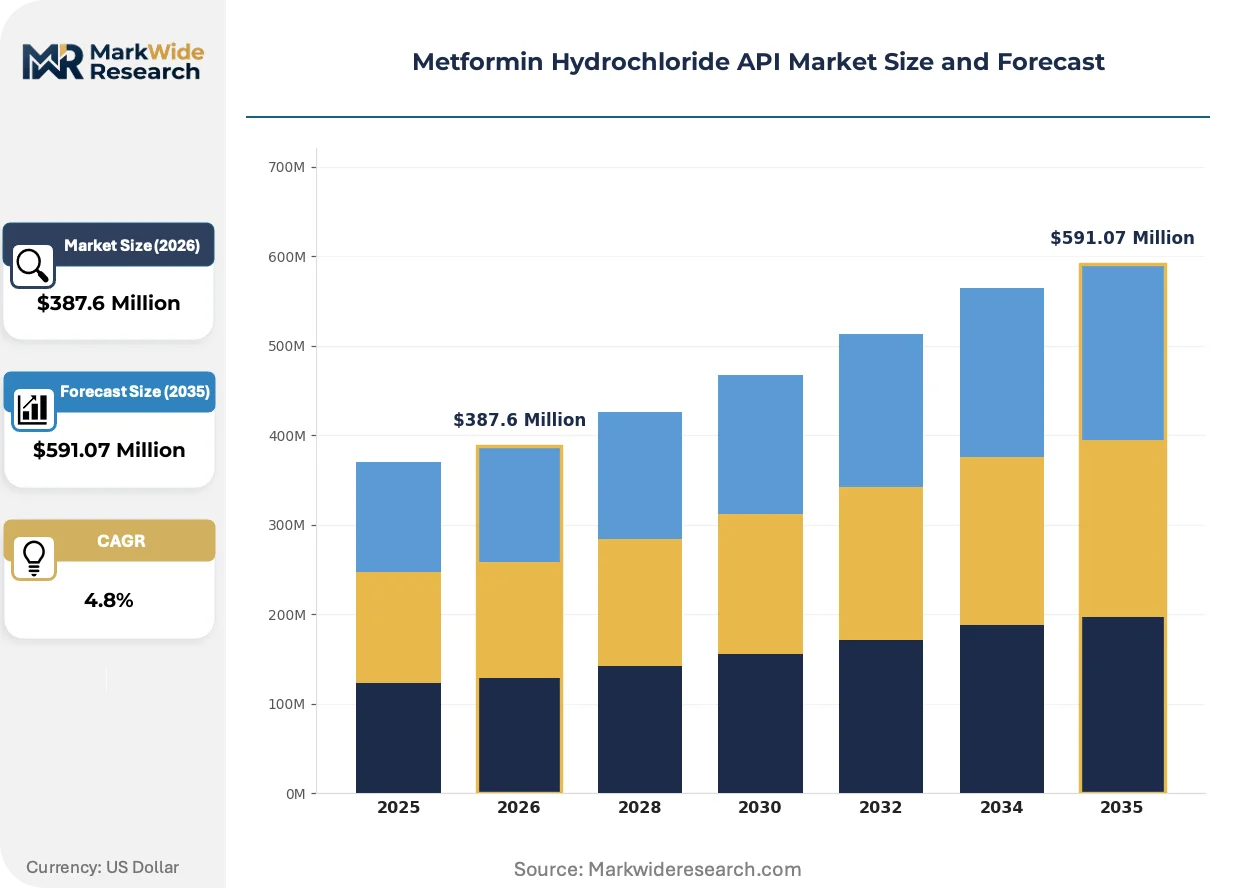
Market Dynamics
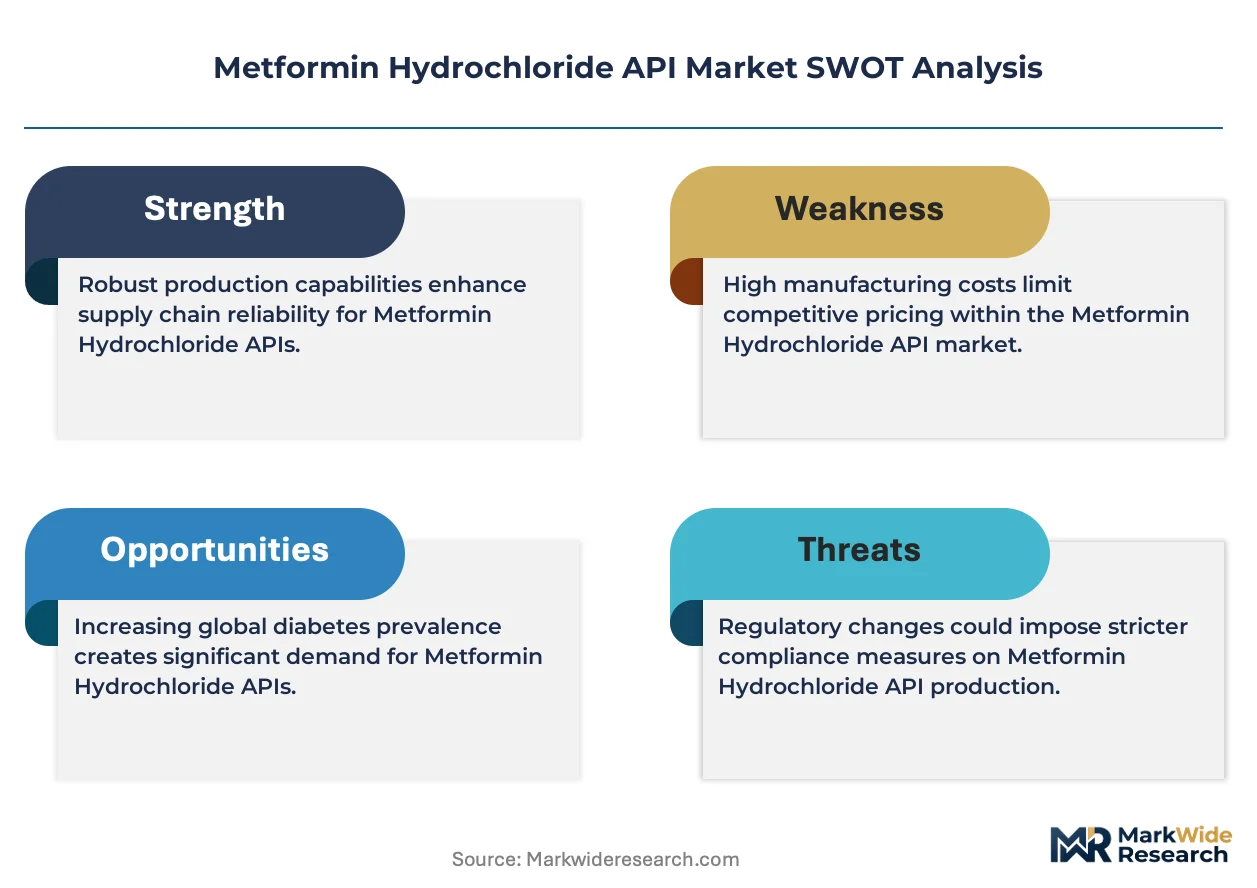
The US FDA's nitrosamine impurity mandates are forcing API manufacturers to retool quality systems and absorb elevated validation costs, compressing margins for non-integrated suppliers while advantaging those with captive analytical capabilities.
Growth Catalysts
- Extended-release tablet protocols:Hospital formularies in the United States are prioritizing once-daily dosing regimens to improve adherence metrics and reduce HbA1c variability in type 2 diabetes populations.
- CDSCO export harmonization:Indian manufacturers achieving WHO prequalification status are securing preferential offtake from African and Southeast Asian tender programs.
- Polycystic ovary syndrome off-label expansion:Endocrinology practices are prescribing metformin for insulin resistance management in reproductive-age women, creating incremental API demand outside diabetes indications.
Market Restraints
- Dimethylamine feedstock volatility:Petrochemical-derived amine pricing fluctuations transmit directly into API cost structures, squeezing contract manufacturers without long-term supply agreements.
- Hyderabad-Ahmedabad supply concentration:Geographic clustering of bulk drug manufacturing exposes procurement continuity to regional logistics disruptions and environmental compliance actions.
- Nitrosamine analytical burden:FDA-mandated risk assessment protocols require mass spectrometry infrastructure investments that filter out subscale producers lacking capital access.
Strategic Opportunities
- Brazilian ANVISA prequalification pathway:Unpenetrated Latin American tender markets offer first-mover advantages for API suppliers establishing local technical dossier presence.
- Continuous flow chemistry adoption:Converging process analytical technology with modular reactor systems enables smaller-batch, higher-purity production for specialty formulation customers.
- EU F-Gas Regulation solvent substitution:Incentive structures for fluorinated solvent reduction create competitive differentiation for manufacturers deploying aqueous or supercritical CO2 process routes.
Industry Challenges
- Analytical chemist scarcity:Nitrosamine method development and validation expertise concentrates in a limited talent pool, extending hiring timelines for quality control expansion.
- Legacy equipment retrofit costs:Stainless steel reactor fleets require corrosion-resistant lining upgrades to meet evolving elemental impurity specifications under ICH Q3D.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metformin Hydrochloride API Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $591.07 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Injections, Extended-release formulations, Oral solutions Application: Diabetes Management, Polycystic Ovary Syndrome, Weight Management, Cardiovascular Health End User: Hospitals, Clinics, Pharmacies, Home Care Distribution Channel: Online Pharmacies, Retail Pharmacies, Wholesalers, Direct Sales |
| Companies Covered | Merck KGaA, Dr. Reddy's Laboratories Ltd., Teva Pharmaceutical Industries Ltd., Wanbury, Shouguang Fukang Pharmaceutical, Aurobindo Pharma Limited, Lupin Limited, Vistin Pharma, Sun Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metformin Hydrochloride API Market Shifts & Advancements
Process intensification and regulatory science advances are converging to redefine manufacturing economics and quality assurance protocols across the metformin API value chain.
Continuous manufacturing platforms are fragmenting traditional batch-based production paradigms. Mid-scale Indian and European suppliers are piloting plug-and-play reactor modules to reduce solvent consumption and accelerate batch release timelines. This technology is fragmenting capital allocation patterns, diverting investment from centralized mega-facilities toward distributed, agile production networks capable of rapid product changeover.
REACH registration obligations for process intermediates are tightening substance documentation requirements for European market access. ECHA's expanded dossier demands are extending qualification timelines by 12-18 months for non-EU manufacturers lacking in-house regulatory affairs capacity. Formulation customers in Germany and France are responding by consolidating supplier panels to pre-qualified incumbents with established EU representation.
Hospital procurement consortia are consolidating API sourcing decisions under centralized pharmacy and therapeutics committees. Group purchasing organizations in the United States are displacing individual hospital contracting, compressing vendor counts and demanding multi-year supply guarantees with fixed-price mechanisms. This concentration is most visible in integrated delivery networks across Texas and Florida, where formulary standardization is reducing qualified supplier pools to three-to-four API sources per network.
Metformin Hydrochloride API Market Segmentation
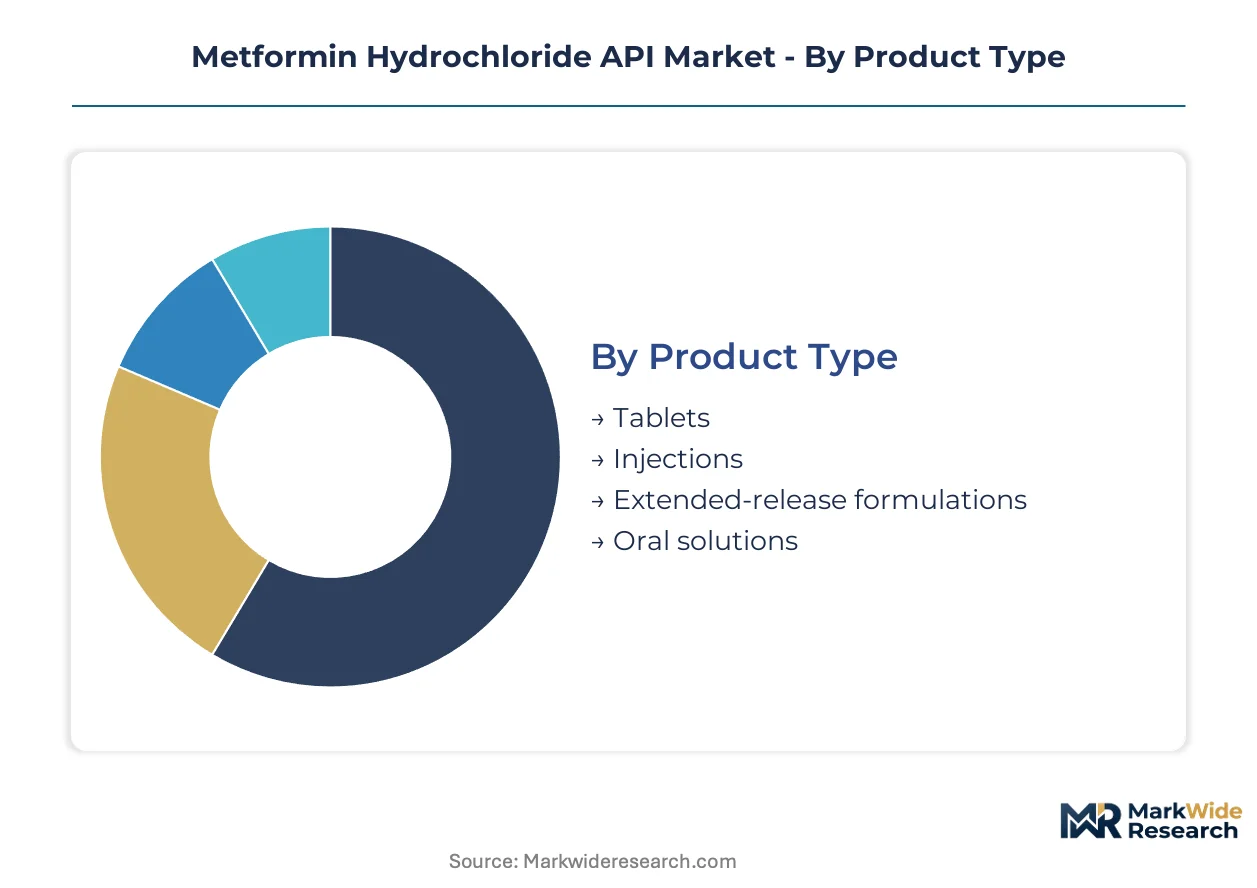
Metformin hydrochloride API demand fragments across formulation technologies, therapeutic indications, and procurement channels. Each segment carries distinct purity specifications, volume scales, and regulatory documentation burdens that reshape supplier economics.
Product Type:
Domestic hospital procurement concentrates in immediate-release tablets, while export-led contract manufacturing tilts toward extended-release technologies for regulated Western markets.
- Tablets:Immediate-release compressed dosage forms dominate hospital formularies and retail pharmacy offtake. Procurement volumes concentrate in Indian bulk drug clusters supplying African and Southeast Asian tender markets, with FDA-compliant specifications commanding price premiums over pharmacopeial-grade alternatives.
- Extended-release formulations:Matrix-based or osmotic pump technologies enable once-daily dosing protocols. Demand accelerates through United States integrated delivery networks prioritizing adherence metrics, with specialized polymer coating requirements filtering out non-integrated API suppliers lacking formulation partnership capabilities.
- Injections:Sterile parenteral preparations require endotoxin-controlled API grades for emergency hyperglycemia protocols.
- Oral solutions:Liquid pediatric and geriatric formulations occupy niche volumes in European compassionate-use programs.
Tablets command the established base. The steepest expansion runs through extended-release formulations.
Application:
Cost tier stratification separates mass-market diabetes APIs from specialty-grade materials for reproductive endocrinology and metabolic syndrome protocols.
- Diabetes Management:Type 2 diabetes mellitus protocols consume the overwhelming majority of API volumes, with hospital procurement consortia demanding multi-year supply guarantees. United States group purchasing organizations consolidate sourcing decisions under centralized pharmacy committees, compressing qualified supplier pools.
- Polycystic Ovary Syndrome:Off-label insulin resistance management in reproductive-age women drives incremental demand outside diabetes indications. Endocrinology practices in Germany and France prescribe metformin for metabolic dysfunction-associated steatotic liver disease, requiring enhanced impurity profiling documentation.
- Weight Management:Adjunct therapy for obesity protocols in combination with GLP-1 agonists creates emerging API demand.
- Cardiovascular Health:Cardioprotective off-label prescribing in prediabetic populations occupies limited volumes in Japanese geriatric care.
Diabetes management anchors volume procurement. Polycystic ovary syndrome applications are climbing the fastest.
End User:
Customer type determines batch size requirements, with hospital systems demanding tonne-scale annual contracts and home care segments fragmenting into kilogram-scale specialty orders.
- Hospitals:Acute care and outpatient clinics within integrated delivery networks procure through centralized formularies. Texas and Florida health systems standardize on three-to-four qualified API sources per network, demanding fixed-price multi-year agreements with nitrosamine risk assessment documentation.
- Clinics:Federally qualified health centers and private endocrinology practices source through wholesale distributors with shorter procurement cycles.
- Pharmacies:Retail chains and independent dispensaries absorb API through finished dosage form procurement rather than direct API purchasing.
- Home Care:Long-term care facilities and patient self-administration programs generate fragmented demand through mail-order pharmacy channels.
Hospitals concentrate procurement volume. Home care segments are expanding most quickly through telehealth-enabled prescription fulfillment.
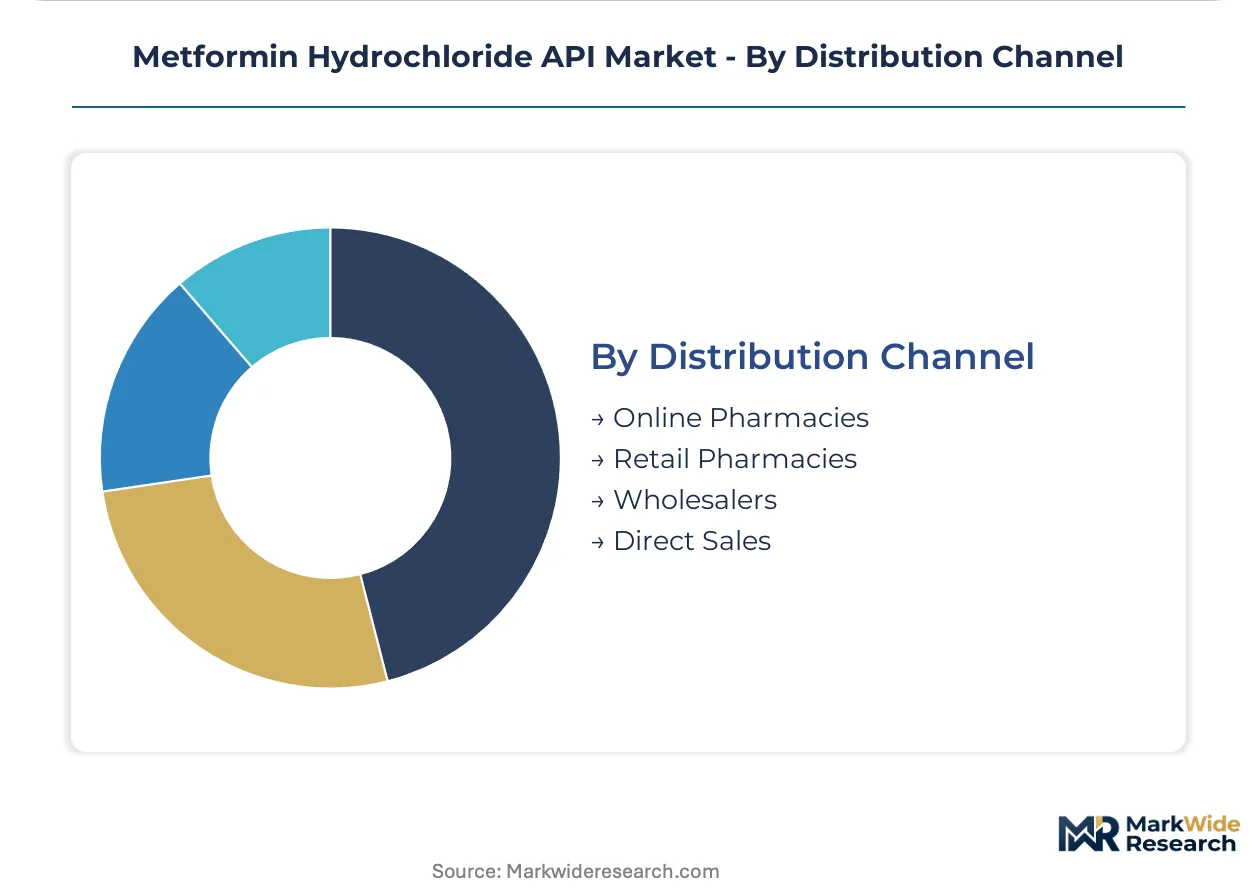
Distribution Channel:
Supply concentration in Hyderabad and Ahmedabad manufacturing clusters dictates logistics configuration, with direct sales dominating high-volume contracts and digital channels penetrating fragmented geographies.
- Wholesalers:Large-volume distributors aggregate API from Indian manufacturing clusters for formulation customers across sub-Saharan Africa and Latin America. ANVISA prequalification pathways in Brazil filter supplier panels to established incumbents with local technical dossier presence.
- Direct Sales:API producers negotiate long-term contracts directly with multinational pharmaceutical manufacturers, bypassing intermediary margins.
- Online Pharmacies:Digital procurement platforms penetrate fragmented Southeast Asian markets lacking established wholesale infrastructure.
- Retail Pharmacies:Finished dosage form dispensing dominates patient-facing channels with minimal direct API exposure.
Wholesalers channel the established volume base. Direct sales are gaining share fastest through consolidated manufacturer-supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement channels. Hospital systems in Germany negotiate on total cost of ownership while Indian tender markets prioritize unit economics above all else.
United States
Integrated delivery networks in Texas and Florida consolidate formulary decisions under centralized pharmacy committees. FDA nitrosamine risk assessment protocols mandate mass spectrometry infrastructure investments that filter subscale suppliers. API procurement concentrates through group purchasing organizations demanding multi-year fixed-price contracts.
India
Bulk drug manufacturing clusters around Hyderabad and Ahmedabad supply African and Southeast Asian tender programs at scale. CDSCO export harmonization with WHO prequalification standards creates dual compliance burdens that advantage established incumbents. Domestic formulation customers absorb the majority of immediate-release API volumes.
Germany
Hospital procurement consortia prioritize extended-release technologies for adherence optimization in type 2 diabetes populations. EMA REACH obligations and F-Gas Regulation constraints add environmental compliance layers to manufacturing economics. Formulation customers consolidate supplier panels to pre-qualified incumbents with established EU representation.
China
Domestic pharmaceutical manufacturers expand metformin API capacity to serve internal formulation needs and export markets. NMPA alignment with ICH Q3D elemental impurity guidelines shapes batch release criteria and facility inspection priorities. Shandong and Jiangsu provinces host concentrated fermentation and synthetic chemistry operations.
Brazil
ANVISA prequalification pathways remain underpenetrated by API suppliers lacking local technical dossier presence. Hospital formularies in São Paulo and Rio de Janeiro standardize on immediate-release tablet protocols for cost containment. Latin American tender markets offer first-mover advantages for manufacturers establishing regulatory footholds.
Metformin Hydrochloride API Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the metformin hydrochloride API supply base. The market structures around a consolidated tier of integrated multinationals and a fragmented layer of regional specialists competing on volume contracts. Fermentation-based manufacturers anchor European supply security while synthetic chemistry operators in India sustain cost leadership through backward integration into key starting materials. Competitive moves concentrate on capacity expansion in Hyderabad-Ahmedabad clusters and strategic partnerships with formulation customers seeking multi-year supply guarantees.
Among European-integrated players, Merck KGaA represents the fermentation infrastructure archetype, leveraging captive bioprocessing capabilities to meet stringent EMA impurity specifications. Dr. Reddy's Laboratories Ltd. and Wanbury exemplify the Indian cost-leadership model, competing aggressively on volume contracts through backward integration into dimethylamine and cyanoguanidine supply chains. These three anchors illustrate the geographic and technological bifurcation shaping procurement decisions across regulated and emerging markets.
| Leading Market Players |
|---|
| Merck KGaA |
| Dr. Reddy's Laboratories Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| Wanbury |
| Shouguang Fukang Pharmaceutical |
| Aurobindo Pharma Limited |
| Lupin Limited |
| Vistin Pharma |
| Sun Pharmaceutical Industries Ltd. |
| Others |
Supply & Pricing Matrix
Dimethylamine substitution for petrochemical-derived alternatives is reshaping procurement geography toward Indian bulk drug clusters while compressing contract manufacturer margins through volatile feedstock pricing. API suppliers without captive amine production face margin erosion as Hyderabad and Ahmedabad manufacturers leverage backward integration into key starting materials to anchor cost leadership.
Pricing Analysis
After-sales analytical service contracts and multi-year validation support packages now drive lifetime value more than unit API sales. Three-tier pricing structure across FDA-certified premium, WHO-prequalified standard, and pharmacopeial-grade economy levels separates integrated multinationals from regional specialists. Pricing pressure stems from nitrosamine testing infrastructure investments that filter subscale producers without mass spectrometry capabilities. Hospital procurement consortia in the United States exhibit lowest price sensitivity due to formulary standardization priorities, while African tender markets prioritize unit economics above certification tier.
Supply Chain Analysis
Inventory buffers and extended lead times for nitrosamine risk assessment documentation have become standard as FDA validation timelines stretch qualification windows. API supply concentrates in India, China, and Germany, with Hyderabad-Ahmedabad clusters feeding African and Southeast Asian formulation customers. Dimethylamine, cyanoguanidine, and specialized polymer coatings for extended-release formulations constitute critical input dependencies. Single-source vulnerability runs through concentrated fermentation capacity in European integrated players. Distribution runs through wholesaler aggregators for emerging markets and direct manufacturer contracts for regulated Western procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against GLP-1 agonist expansion in diabetes protocols, which threatens to displace metformin volume in insulin-resistant patient populations.
For Market Incumbents: Shield market position through captive nitrosamine testing infrastructure investments that filter subscale competitors lacking capital access. Anchor supply security via fermentation capacity expansion or synthetic chemistry partnerships in Indian bulk drug clusters. Defensive consolidation around extended-release formulation partnerships with integrated delivery networks protects against GLP-1 combination therapy displacement.
For New Entrants and Emerging Players: Differentiate on continuous flow chemistry capabilities for smaller-batch, higher-purity production serving specialty formulation customers. Target Brazilian ANVISA prequalification pathways as the most penetrable regulatory geography lacking established API supplier presence. Deploy aqueous or supercritical CO2 process routes as the go-to-market angle for EU F-Gas Regulation compliance differentiation.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed Indian API specialists possessing WHO prequalification status but lacking EU regulatory affairs capacity. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than pure volume scale. Watch FDA nitrosamine enforcement intensity as the inflection signal for margin compression among non-integrated suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Key Starting Materials | Captive dimethylamine supply anchors cost leadership against feedstock volatility for Hyderabad manufacturers. |
| Nitrosamine Testing Infrastructure Investment | Mass spectrometry capabilities filter subscale competitors and secure FDA batch release approvals. |
| Extended-Release Formulation Partnership | Polymer coating expertise opens integrated delivery network procurement in Texas and Florida hospital systems. |
| WHO Prequalification Pathway Completion | CDSCO export harmonization unlocks preferential African and Southeast Asian tender program access. |
| Continuous Flow Chemistry Pilot Adoption | Modular reactor systems reduce solvent consumption and accelerate batch release for specialty customers. |
Research Methodology
Initial hypotheses were tested against primary input from API manufacturing executives, regulatory affairs directors, hospital formulary managers, and group purchasing organization procurement leads and refined through secondary validation against FDA enforcement records, EMA inspection reports, CDSCO export notifications, and WHO prequalification databases. Bottom-up volume estimates from individual manufacturing facility capacities were triangulated against top-down demand projections derived from diabetes prevalence data and metformin prescription analytics.
Variance decomposition across formulation technology, therapeutic indication, procurement channel, and regional regulatory cluster segmentation dimensions shaped the analytical framework. CAGRs were derived from modeled volume trajectories weighted by price tier assumptions across the projection horizon. Forecast inputs incorporated nitrosamine testing adoption curves, GLP-1 agonist substitution elasticities, and extended-release formulation penetration rates in integrated delivery networks.
Forecasts assume regulatory continuity in FDA nitrosamine enforcement, EMA REACH obligations, and CDSCO export harmonization; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Citicoline Market
Pharmaceutical Ingredients
Pharmaceutical Excipients for Taste Masking Market
Pharmaceutical Ingredients
Duloxetine API Market
Pharmaceutical Ingredients
Small-Molecule Injectable Market
Pharmaceutical Ingredients
Scopolamine Market
Pharmaceutical Ingredients
Global Granisetron Market
Pharmaceutical Ingredients
Mitotic Inhibitors Market
Pharmaceutical Ingredients
Quinoline Market
Pharmaceutical Ingredients
Pharmaceutical Propellants Market
Pharmaceutical Ingredients
Pharmaceuticals Grade Sodium Bicarbonate Market
Pharmaceutical Ingredients
Active Pharmaceutical Ingredient for Cancer Market
Pharmaceutical Ingredients
Oral Doxycycline Hyclate Market
Pharmaceutical Ingredients
Albumin (As Excipient) Market
Pharmaceutical Ingredients
Pharmaceutical Grade Magnesium Hydroxide Market
Pharmaceutical Ingredients
Small Molecule Drug Discovery Market
Pharmaceutical Ingredients
Synthetic Small Molecule API Market