

High Performing Matting Agents Market Size, Share, and Industry Trends Forecast 2026-2036
High Performing Matting Agents Market Insights
Direct supply relationships between matting agent producers and automotive coatings formulators is tilting toward technical partnership models with embedded R&D collaboration. Evonik Operations leverages its organosilica expertise to anchor long-term contracts with European automotive paint suppliers. Mitsubishi Chemical competes through backward integration into methacrylate monomers, securing captive feedstock for its polymethyl methacrylate matting grades. PQ Corporation sustains manufacturing scale across multiple silica processing sites, giving it logistics flexibility in North American industrial coatings channels.
High performing matting agents are functional additives that reduce surface gloss in coatings and inks through controlled light scattering, typically achieving gloss units below 10 at 60° measurement angle depending on particle size distribution and refractive index matching with the binder matrix. Their primary commercial purpose is enabling premium aesthetic finishes in automotive topcoats, furniture lacquers, and packaging films where low-sheen appearance signals quality. Silica variants occupy the dominant volume position due to universal compatibility and cost efficiency across waterborne and solventborne systems. Polyurethane matting agents represent the fastest-growing product category as waterborne architectural paint formulators seek alternatives to silica for improved film clarity and scratch resistance. Liquid dispersions command premium positioning in automated dosing systems at large paint manufacturers, while powder forms retain share in smaller batch operations.
EPA oversight of volatile organic compound emissions under the National Emission Standards for Hazardous Air Pollutants constrains solventborne coating formulations, indirectly steering demand toward waterborne-compatible matting technologies. REACH registration requirements and ECHA substance evaluation protocols impose documentation burdens on imported silica and synthetic resin additives entering European paint production facilities. ISO 2813 gloss measurement standards provide the technical baseline for product specification and quality arbitration between matting agent suppliers and coatings buyers. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal's industrial emissions benchmarks reshape raw material sourcing and manufacturing location decisions for matting agent producers serving multinational coatings customers.
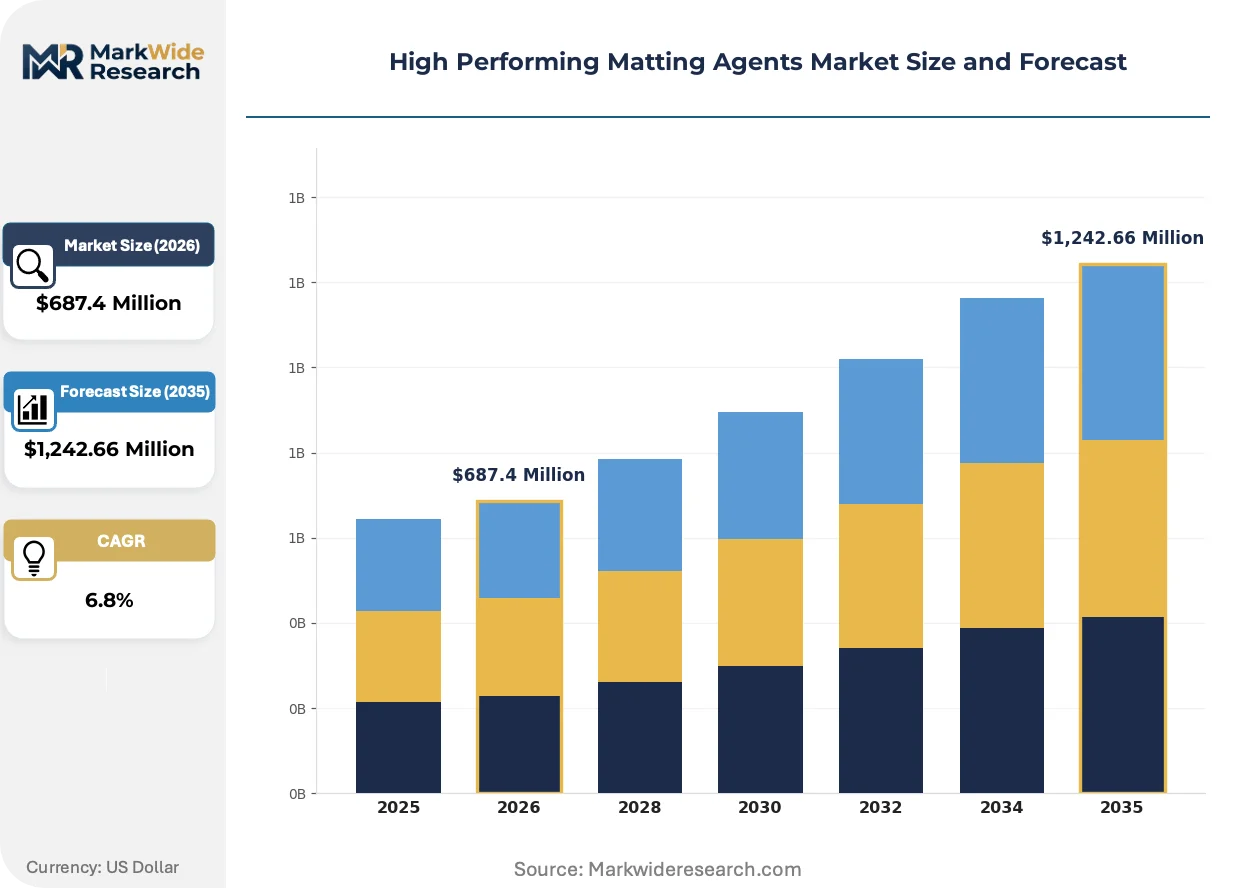
Market Dynamics
Automotive OEMs in Germany and tier-one paint suppliers are consolidating supplier relationships into embedded R&D partnerships, compressing traditional arm's-length procurement and forcing matting agent producers to co-develop formulations rather than sell standardized additives.
Growth Catalysts
- REACH and RoHS compliance:Tightening volatile compound thresholds in European coating formulations are accelerating replacement of legacy high-VOC matting systems with waterborne-compatible silica and polyurethane technologies.
- Automotive premium finishes:German OEMs and their paint suppliers are expanding specification of sub-10 gloss unit topcoats, pulling demand for precisely calibrated particle size distributions in matting agents.
- Waterborne architectural coatings:Formulators across Western Europe are adopting polyurethane matting agents to achieve film clarity and scratch resistance unavailable from conventional silica in interior wall systems.
Market Restraints
- Silica feedstock concentration:High-purity precipitated silica production clusters in Germany and the Netherlands, creating geographic supply vulnerability for coatings manufacturers dependent on just-in-time delivery.
- Energy cost intensity:Synthetic silica calcination and surface treatment processes require sustained thermal input, exposing producers to natural gas price volatility that compresses margin at fixed contract pricing.
- Refractive index matching limitations:Silica matting agents face technical ceiling effects in high-clarity coatings where polyurethane alternatives achieve superior binder matrix compatibility.
Strategic Opportunities
- Liquid dispersion automation:Large paint manufacturers in Italy and Spain are retrofitting dosing systems that favor pumpable matting agent dispersions over powder handling, opening premium positioning for formulated products.
- EU Green Deal industrial benchmarks:Carbon border adjustments and emissions trading scheme expansion are incentivizing coatings producers to source matting agents from producers with verified low-carbon manufacturing processes.
- Furniture and industrial wood coatings:Italian furniture lacquer manufacturers are specifying low-sheen finishes that replicate automotive aesthetic standards, extending matting agent demand beyond traditional transportation coatings.
Industry Challenges
- ISO 2813 gloss arbitration complexity:Disputes between matting agent suppliers and coatings buyers over measurement angle protocols and surface preparation standards are extending qualification timelines and delaying contract execution.
- Dual registration burden:Producers serving both EU and Chinese coatings customers must maintain parallel REACH dossiers and NMPA substance filings, fragmenting regulatory affairs resources and extending product launch cycles.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Performing Matting Agents Market Trends and Innovations
Formulation chemistry and supply chain configuration are converging to reshape how matting agents are specified, purchased, and integrated into coating systems across European industrial channels.
Surface-treated organosilica technologies are collapsing the performance gap between solventborne and waterborne matting efficiency. German automotive paint suppliers are adopting these materials at accelerated qualification pace to maintain gloss control across hybrid coating lines. The structural consequence is collapsing the historical premium commanded by solventborne-grade silica, compressing pricing architecture across product tiers.
REACH registration requirements and ECHA substance evaluation protocols are extending documentation burdens for imported additives entering European paint facilities. Industrial coatings formulators are responding by tightening supplier qualification to pre-registered local producers, reshaping procurement geography. Waterborne architectural segments are most affected, with formulators accelerating substitution toward domestically sourced polyurethane alternatives.
Coatings buyers are consolidating annual matting agent contracts into multi-year technical partnership agreements with embedded joint development clauses. Large automotive paint manufacturers in Germany and France are displacing spot purchasing with dedicated supplier engineering teams co-located at formulation centers. This shift is most visible in premium automotive topcoat programs where surface finish specifications are tightening faster than standard product portfolios can accommodate.
High Performing Matting Agents Market Segmentation
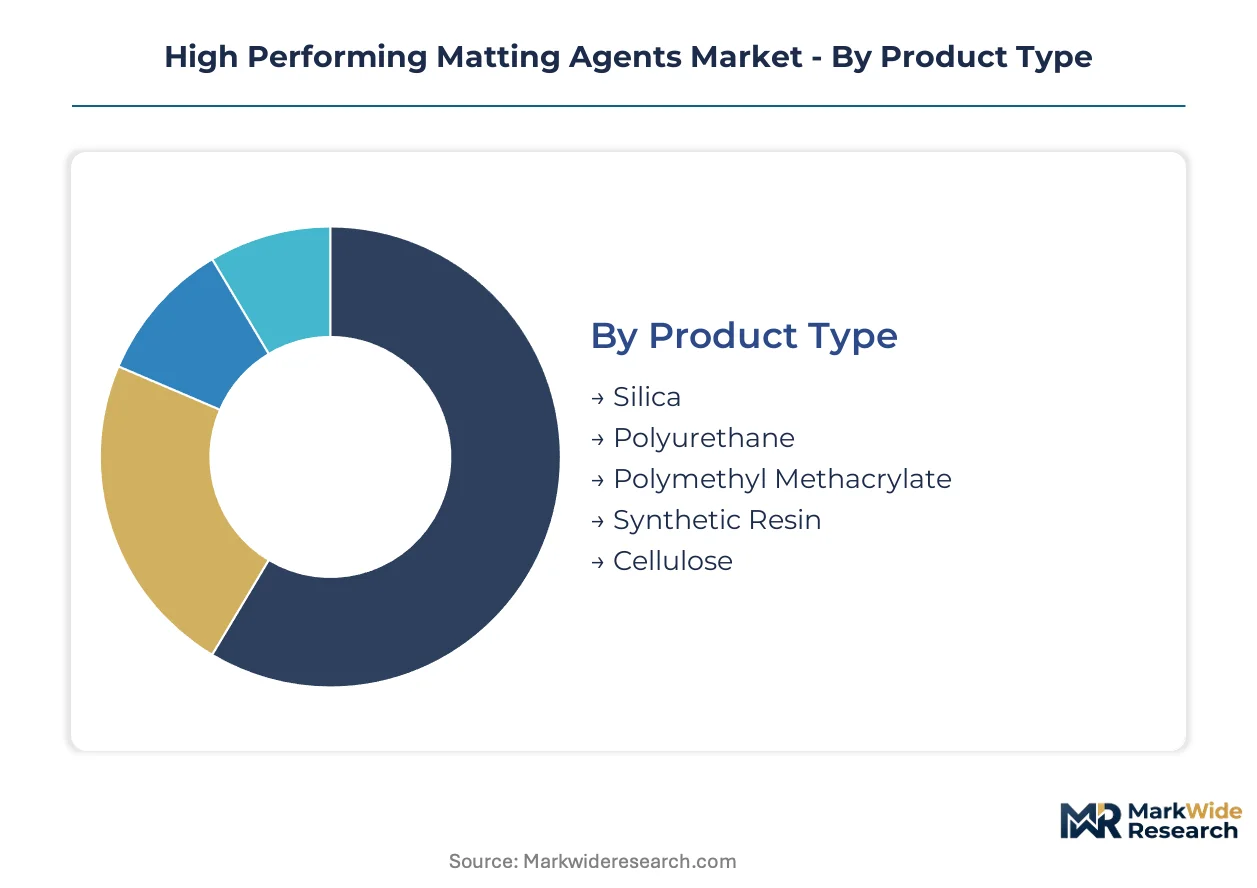
Matting agent procurement patterns diverge sharply across product chemistries and application requirements. Automotive paint suppliers prioritize particle size precision for gloss control, while architectural formulators weigh film clarity against scratch resistance trade-offs.
Product Type:
Mature silica technologies anchor volume procurement, while polyurethane grades emerge as the technology frontier for waterborne systems.
- Silica:Precipitated and fumed silica variants deliver universal compatibility across solventborne and waterborne coating matrices. German automotive OEMs and tier-one paint suppliers in Stuttgart and Munich specify sub-10 gloss unit finishes that demand precisely calibrated particle size distributions from silica suppliers.
- Polyurethane:Thermoplastic polyurethane matting agents achieve superior refractive index matching with acrylic and polyurethane binders, eliminating the haze effects inherent to silica in high-clarity films. Western European architectural paint formulators are adopting these materials for interior wall systems where scratch resistance and film clarity outweigh cost considerations.
- Polymethyl Methacrylate:Crosslinked PMMA microspheres provide controlled light scattering with narrow particle size distribution for premium furniture lacquers.
- Synthetic Resin:Engineered polymer particles offer tailored surface topography for specialized packaging ink applications requiring food-contact compliance.
- Cellulose:Regenerated cellulose derivatives serve niche textile finishing applications where biodegradability specifications constrain synthetic additive selection.
Silica retains volume leadership; polyurethane holds the steepest expansion curve.
Application:
Cost tier differentiation separates specification-intensive automotive programs from price-sensitive architectural volumes.
- Automotive Coatings:Exterior topcoat systems require matting agents capable of maintaining gloss stability across thermal cycling and UV exposure. German OEM paint shops in Ingolstadt and Wolfsburg enforce sub-5 gloss unit specifications for premium matte finishes that drive qualification of surface-treated organosilica grades.
- Architectural Paints:Interior and exterior wall coatings prioritize cost efficiency and application ease over extreme gloss precision. Italian and Spanish formulators specify polyurethane matting agents for high-end residential finishes where film clarity differentiates premium product lines.
- Industrial Coatings:Protective and decorative finishes for machinery and equipment demand chemical resistance and durability under mechanical stress.
- Wood Finishes:Furniture and flooring lacquers in Italy's Brianza district replicate automotive aesthetic standards with low-sheen appearances.
- Packaging Inks:Flexographic and gravure printing applications require finely dispersed matting agents compatible with high-speed coating lines.
Automotive coatings command premium positioning; architectural paints deliver scale volume.
Form:
Customer type divides procurement between automated dosing systems and manual batch operations.
- Liquid:Pumpable dispersions integrate directly into automated manufacturing lines without dust handling complications. Large paint manufacturers in Italy and Spain are retrofitting dosing infrastructure that favors liquid matting agent forms over powder handling.
- Powder:Free-flowing particulate grades retain cost advantages and formulation flexibility for smaller batch producers. German mid-tier coatings manufacturers continue specifying powder silica for intermittent production runs where capital investment in liquid handling systems cannot be justified.
- Dispersion:Pre-stabilized concentrated suspensions reduce milling requirements and shorten production cycle times.
- Granules:Low-dust agglomerated forms improve handling safety in high-volume powder coating operations.
- Paste:High-solids semi-liquid preparations suit specialized ink and adhesive compounding applications.
Liquid forms gain share in automated facilities; powder retains dominance in batch operations.
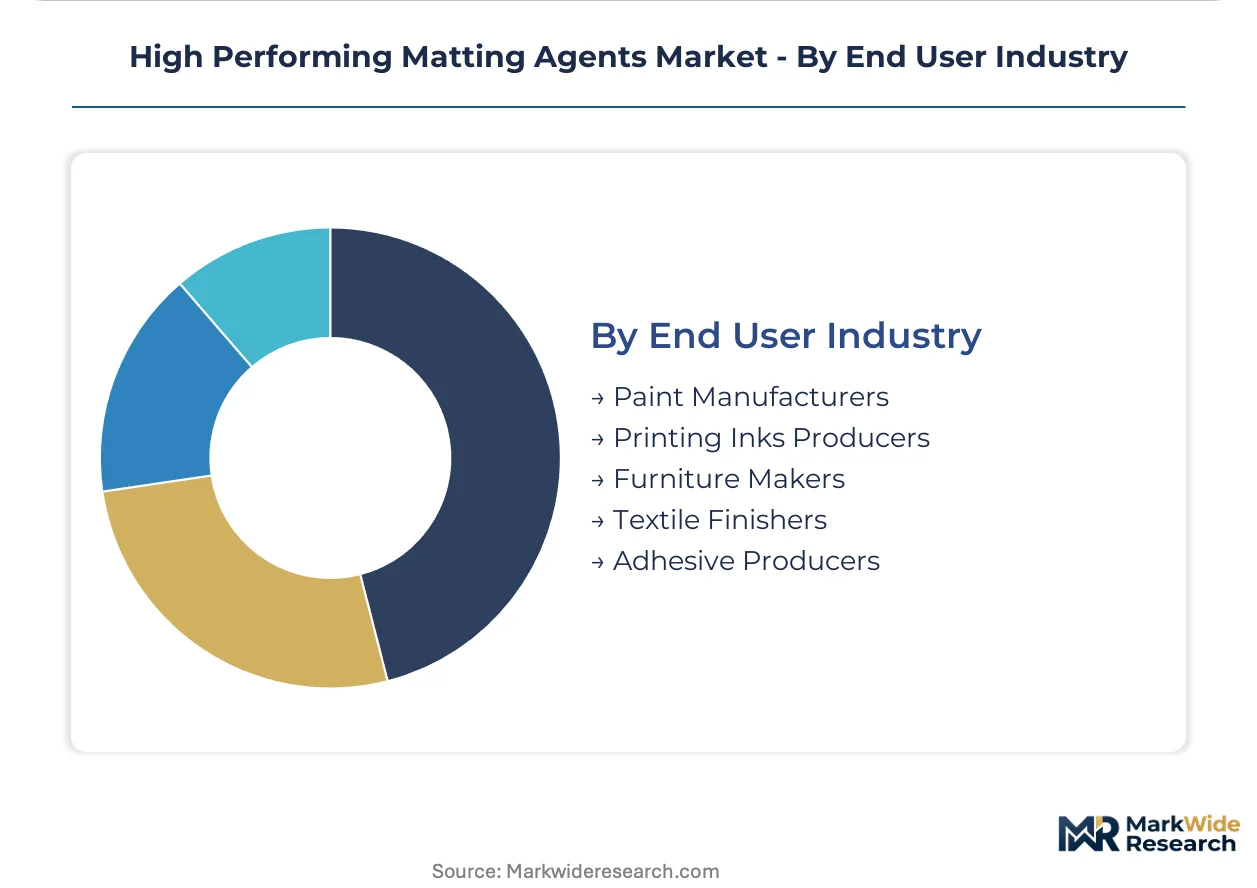
End User Industry:
Supply concentration clusters around paint manufacturing hubs, with adjacent industries adopting adapted specifications.
- Paint Manufacturers:Industrial and decorative coatings producers represent the dominant consumption channel, with procurement decisions centralized at formulation centers. German automotive paint suppliers consolidate annual contracts into multi-year technical partnerships with embedded joint development clauses.
- Printing Inks Producers:Packaging and publication ink formulators require finely milled grades compatible with high-speed printing equipment. French flexographic ink specialists specify low-VOC matting dispersions to meet REACH-compliant formulations for food-contact packaging.
- Furniture Makers:Industrial wood coating operations in Italy specify low-sheen finishes that extend matting agent demand beyond transportation coatings.
- Textile Finishers:Fabric coating and laminating operations employ matting agents for synthetic leather and technical textile surface effects.
- Adhesive Producers:Pressure-sensitive and structural adhesive formulators use controlled matting for aesthetic and functional surface modification.
Paint manufacturers anchor procurement volume; printing inks producers show the fastest uptake of liquid dispersion formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites Europe's dominance in matting agent trade flows, connecting German manufacturing clusters to global coatings supply chains.
Germany
Automotive OEMs in Stuttgart and Wolfsburg enforce sub-5 gloss unit specifications for premium matte finishes. REACH registration requirements tighten documentation burdens on imported additives. The Ingolstadt paint shop corridor anchors qualification programs for surface-treated organosilica grades.
Italy
Furniture lacquer manufacturers in the Brianza district replicate automotive aesthetic standards with low-sheen finishes. EU Green Deal industrial emissions benchmarks reshape sourcing decisions for coatings producers. Milan-based formulators specify polyurethane matting agents for high-end residential interior systems.
France
Flexographic ink specialists demand low-VOC matting dispersions for food-contact packaging compliance. ECHA substance evaluation protocols extend qualification timelines for imported silica additives. The Lyon industrial corridor concentrates printing ink formulation capacity requiring finely milled grades.
Spain
Large paint manufacturers retrofit dosing infrastructure favoring pumpable liquid dispersions over powder handling. RoHS compliance thresholds constrain volatile compound content in coating formulations. Barcelona and Madrid production facilities drive automation investment in automated matting agent integration.
Netherlands
High-purity precipitated silica production clusters around Rotterdam chemical processing sites. Carbon border adjustments incentivize coatings producers to verify low-carbon manufacturing credentials. The Rotterdam-Antwerp pipeline corridor enables just-in-time feedstock delivery to European coatings manufacturers.
High Performing Matting Agents Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the matting agent supply structure. The market exhibits moderate consolidation with multinational chemical conglomerates holding formulation integration advantages while regional specialists retain niche technology positions. Three archetypes dominate: silica processing scale players, organosilica technology specialists, and polyurethane dispersion innovators. Competitive dynamics center on backward integration into methacrylate feedstocks and embedded R&D partnerships with automotive paint suppliers.
Among European chemical conglomerates, Evonik Operations and PQ Corporation exemplify divergent scale-versus-specialization strategies, while Mitsubishi Chemical represents the Asia-Pacific integrated petrochemicals archetype with captive monomer supply positions.
| Leading Market Players |
|---|
| Lamberti S.p.A. |
| Evonik Operations |
| PQ Corporation |
| Mitsubishi Chemical |
| EuroMinerals |
| Honeywell |
| Imerys |
| Ishihara Sangyo Kaisha |
| W. R. Grace |
| Others |
Pricing and Supply Chain Analysis
Rotterdam's chemical processing corridor anchors European silica supply capacity, with calcination and surface treatment operations concentrated around the Port of Rotterdam-Antwerp pipeline. This geographic density grants incumbent producers logistics leverage over coatings formulators seeking just-in-time delivery, compressing margin negotiation space for buyers dependent on premium precipitated silica grades.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement contracts, with premium tiers capturing automotive OEM qualification costs and economy tiers serving commodity architectural volumes. Price differentiation rests on ISO 2813 gloss certification tier and volume scale commitments, with large paint manufacturers extracting double-digit discounts against spot buyers. Cost compression in standard silica grades is intensifying because surface-treated organosilica technologies are collapsing the solventborne premium. Architectural paint formulators in Southern Europe show highest price sensitivity, while German automotive paint suppliers accept premium positioning for sub-5 gloss unit specifications.
Supply Chain Analysis
Contract manufacturing concentration sits with Evonik Operations, PQ Corporation, and Mitsubishi Chemical, which control high-purity precipitated silica and organosilica synthesis capacity. Geographic supply concentration clusters in Germany, the Netherlands, and Japan, with feedstock dependencies on sodium silicate, methacrylate monomers, and natural gas for thermal processing. Single-source vulnerability runs through Rotterdam-Antwerp logistics corridors, where pipeline disruptions would strand just-in-time coatings production. Distribution runs through direct technical partnerships with embedded R&D collaboration, displacing traditional arm's-length procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. REACH registration dossiers and ECHA substance evaluation protocols create documentation barriers that fragment competitor entry timelines and cement incumbent relationships with qualified suppliers.
For Market Incumbents: Entrench position by deepening backward integration into methacrylate feedstocks, mirroring Mitsubishi Chemical's captive monomer supply model against volatile raw material costs. Expand surface-treated organosilica capacity in Germany's Ingolstadt corridor to capture automotive OEM qualification pipelines before polyurethane alternatives achieve technical parity. Prioritize multi-year technical partnership contracts with embedded joint development clauses to lock out emerging dispersion specialists.
For New Entrants and Emerging Players: Spain's underpenetrated automated dosing infrastructure offers white-space positioning for liquid dispersion specialists, with Barcelona and Madrid paint manufacturers retrofitting pumpable systems. Target Italian furniture lacquer manufacturers in the Brianza district replicating automotive aesthetic standards with low-sheen finishes, where polyurethane matting agents command premium positioning unavailable to commodity silica suppliers. Enter through co-development partnerships with regional formulators seeking REACH-compliant alternatives to imported additives.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regulatory documentation burdens and embedded R&D partnership models favor scaled incumbents with existing ECHA dossiers and automotive qualification pipelines. Acquisition target archetype: regional polyurethane dispersion innovators with verified low-carbon manufacturing credentials and existing Milan or Barcelona customer relationships. Monitor EU Green Deal carbon border adjustment implementation as inflection signal for sourcing preference shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methacrylate Feedstocks | Mitsubishi Chemical's captive monomer supply secures margin control against volatile raw material pricing. |
| Surface-Treated Organosilica Capacity Expansion | German automotive paint suppliers in Stuttgart accelerate qualification of waterborne-compatible gloss control technologies. |
| Liquid Dispersion Automation Partnerships | Italian and Spanish paint manufacturers retrofit dosing infrastructure favoring pumpable matting agent forms. |
| REACH-Compliant Low-Carbon Manufacturing Certification | EU Green Deal industrial emissions benchmarks reshape sourcing decisions for verified low-carbon process credentials. |
| Multi-Year Technical Partnership Contracts | German OEM paint shops consolidate procurement into embedded R&D collaboration with co-located supplier engineering teams. |
Research Methodology
Operator-level perspectives from coatings formulators, automotive paint procurement leads, silica plant managers, and ECHA regulatory affairs specialists anchored the qualitative base. Primary interviews combined with secondary validation from REACH registration dossiers, Cefic chemical industry reports, customs trade data, and SEC filings from listed chemical conglomerates. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Scenario-bracketing framed the analytical approach, with growth projections tested against regulatory acceleration and deceleration cases throughout the forecast period. Segmentation dimensions modeled include product chemistry tier, application end-use, form factor, and regional production hub clustering. CAGRs derived from historical trajectory analysis adjusted for documented qualification timeline compressions and partnership model shifts. Industry-specific forecast inputs incorporated automotive OEM gloss specification tightening rates and architectural waterborne transition pacing.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Asian petrochemical conglomerates or accelerated polyurethane substitution in high-clarity coatings would shift outcomes. Quarterly review of ECHA substance evaluation timelines, automotive OEM matte finish specification releases, and EU carbon border adjustment implementation progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.