
 Calcined Petroleum Coke Market | 2026-2036
Calcined Petroleum Coke Market Size, Share, and Industry Trends Forecast 2026-2036
Calcined Petroleum Coke Market Analysis
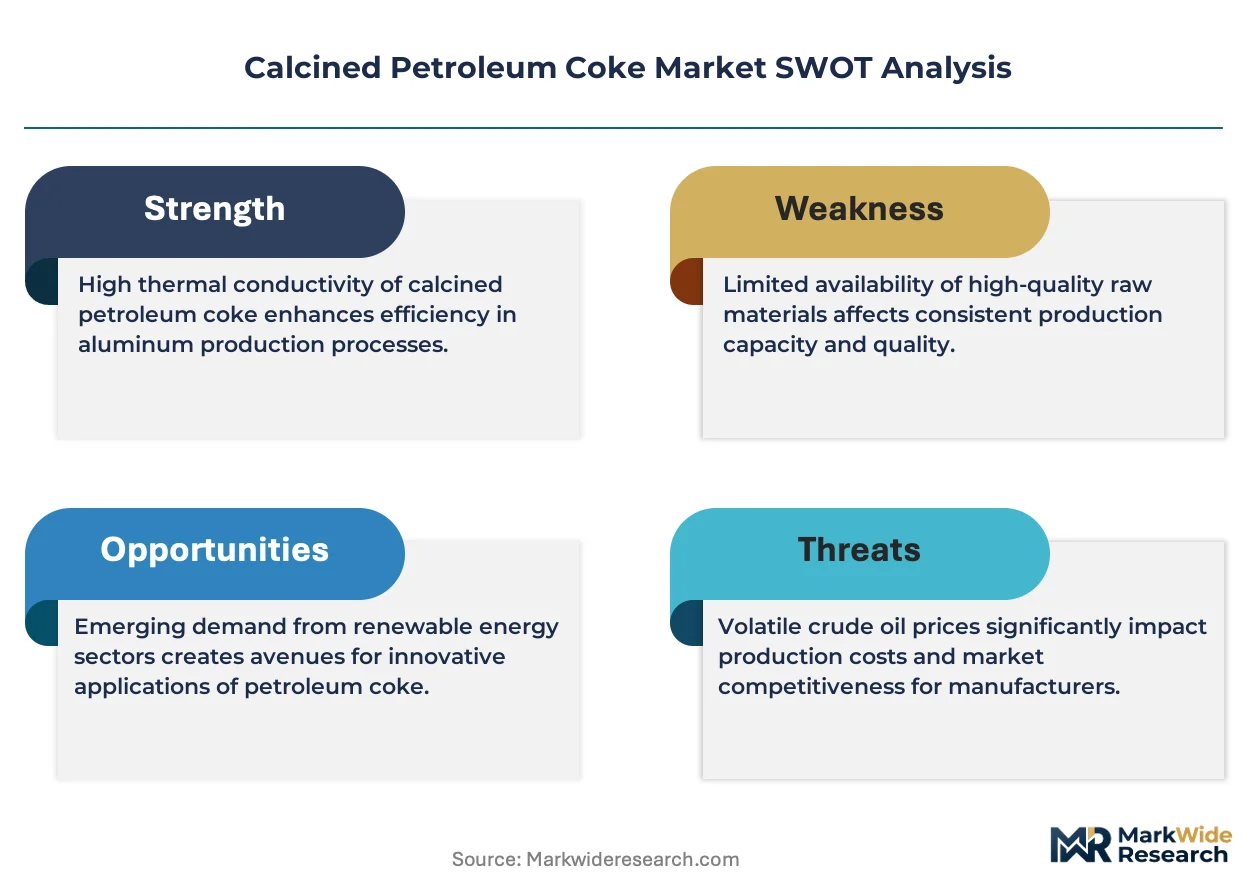
EU REACH compliance is decoupling European calcined petroleum coke supply from legacy import channels. Rain Carbon Inc. leverages integrated calcination capacity across the United States and Europe to sustain anode-grade purity leadership. Oxbow Corporation anchors its competitive stance through extensive green coke sourcing relationships and waterfront terminal control. Phillips 66 Company differentiates via refinery-calciner co-location that trims logistics exposure.
Calcined petroleum coke is a high-temperature thermally treated carbon material derived from green petroleum coke, typically processed at 1200–1400°C to drive off moisture and volatile compounds while increasing fixed carbon content above 98.5 percent; its primary purpose is to serve as the carbon anode material in aluminum electrolysis and as a recarburizer in steelmaking. Low sulfur grades command premium positioning in aerospace and specialty electrode applications where sulfur contamination degrades metallurgical performance. Needle coke represents the fastest-growing product category, driven by lithium-ion battery anode demand and ultra-high power graphite electrode requirements. High sulfur calcined coke occupies mature volume pools tied to cement kiln fuel and lower-tier foundry applications.
EPA emissions rules in the United States and China's MEE air quality standards are elevating calciner capital costs and forcing technology upgrades across the supply base. The EU Carbon Border Adjustment Mechanism will reshape trade flows for carbon-intensive calcined coke imports into European aluminum smelters. Stakeholders must monitor regulatory divergence between jurisdictions to calibrate sourcing strategies and capital deployment timelines.
Market Dynamics
China's dual carbon goals are forcing calciner technology upgrades across the green petroleum coke supply base, tightening emissions standards while aluminum smelter expansion in India and the Middle East pulls anode-grade consumption upward.
Growth Catalysts
- Aluminum smelter expansion:New capacity in India and Saudi Arabia is absorbing anode-grade calcined coke at scale. Smelters require high-purity carbon anodes for electrolytic reduction.
- REACH compliance restructuring:EU importers are decoupling from legacy supply channels and qualifying new calciner sources. This creates entry points for integrated producers with certified purity protocols.
- Needle coke battery demand:Lithium-ion anode material specifications are pulling premium needle coke volumes into electric vehicle supply chains. Battery manufacturers specify ultra-low sulfur and thermal expansion coefficients.
Market Restraints
- Green coke supply concentration:High-sulfur refinery output dominates certain geographies, constraining low-sulfur anode-grade feedstock availability. Refinery coking capacity decisions determine calciner input economics.
- EPA and MEE emissions compliance:United States and Chinese air quality rules are elevating calciner capital intensity. Baghouse upgrades and sulfur recovery systems add fixed cost layers.
- Pitch coke substitution in electrodes:Synthetic graphite and recycled carbon sources are displacing calcined coke in certain ultra-high power electrode applications.
Strategic Opportunities
- EU Carbon Border Adjustment Mechanism:European aluminum smelters face embedded carbon costs on imports. Domestic and near-shore calciners with verified low-carbon process heat gain preference.
- India BIS quality standard harmonization:Domestic calcination capacity expansion aligns with import substitution goals. Local producers can capture anode-grade volume from Middle East smelter projects.
- Refinery-calciner co-location models:Integrated sites eliminate green coke logistics and moisture reabsorption risks. Captive heat integration reduces process energy costs.
Industry Challenges
- Calciner engineering talent scarcity:Rotary kiln optimization and emissions control expertise concentrates with aging specialist workforce. Knowledge transfer gaps threaten operational continuity.
- Multi-jurisdiction certification timelines:REACH, EPA, and BIS registration pathways run on non-aligned schedules. Product qualification delays extend customer conversion cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcined Petroleum Coke Market |
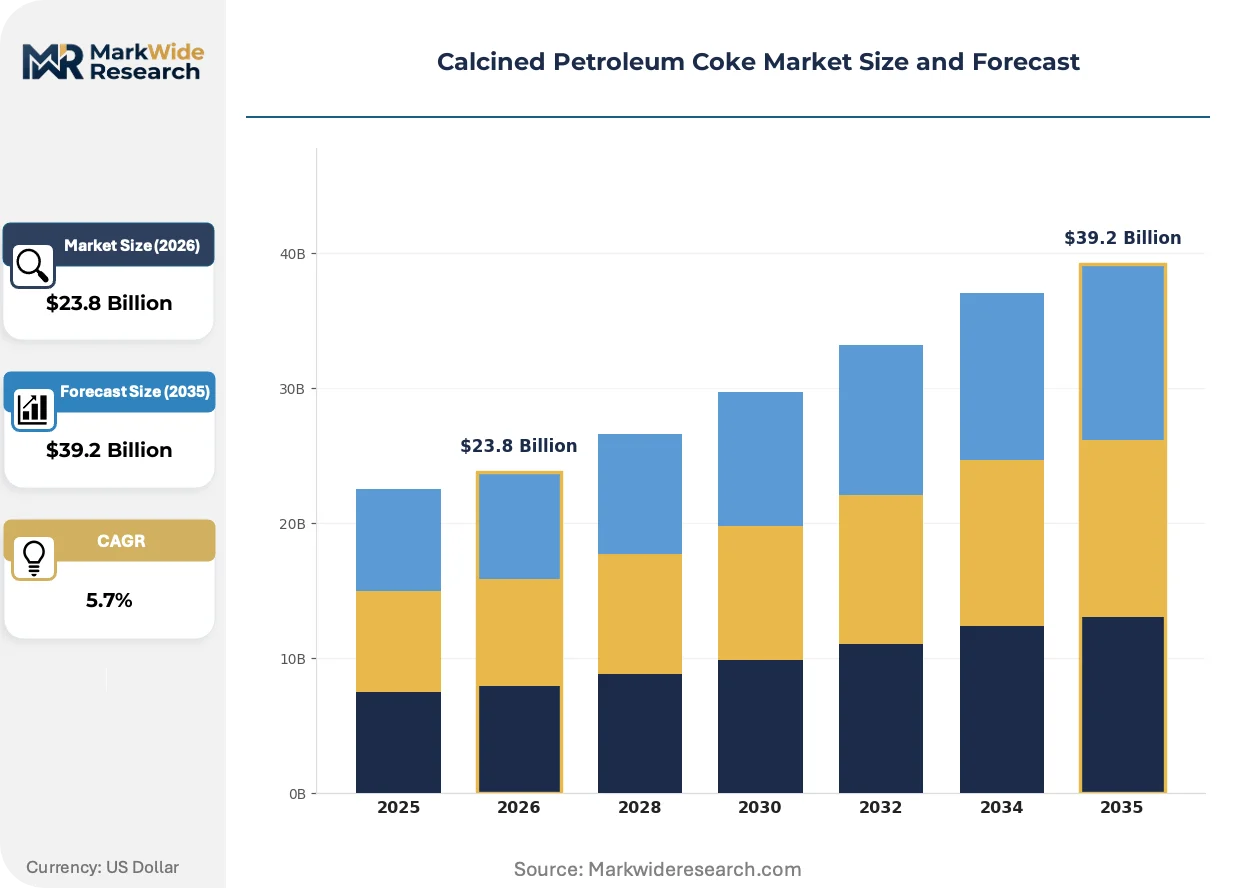
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $39.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Sulfur, Low Sulfur, Needle Coke, Calcined Coke End User: Aluminum Industry, Steel Sector, Titanium Dioxide, Carbon Products Application: Electrode Production, Fuel Cells, Steelmaking, Battery Manufacturing Distribution Channel: Direct Sales, Online Retail, Distributors, Re-sellers |
| Companies Covered | Rain Carbon Inc., Oxbow Corporation, Phillips 66 Company, BP p.l.c, Saudi Aramco, ExxonMobil Corporation, Indian Oil Corporation, HPCL-Mittal Energy Limited, Petrobras, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcined Petroleum Coke Market Emerging Trajectories
Digital process control and emissions monitoring systems are compressing calciner yield variance while regulatory carbon accounting is reshaping trade flow economics.
Advanced kiln control systems is automating temperature profiling and volatile release management across continuous calcination lines. Aluminum smelters in the Middle East are specifying real-time carbon purity verification. This technology is compressing off-specification batches and reducing reprocessing costs.
EU REACH substance registration requirements are extending compliance obligations to downstream aluminum producers. European smelters now demand full supply chain substance data from calciner sources. Anode-grade suppliers with pre-registered dossiers are capturing volume from non-compliant import channels.
Long-term offtake contracting is displacing spot market procurement for battery-grade needle coke. Electric vehicle battery anode manufacturers are locking multi-year supply agreements directly with calciners. This pattern is most visible in South Korean and Japanese cathode material supply chains.
Calcined Petroleum Coke Market Segmentation
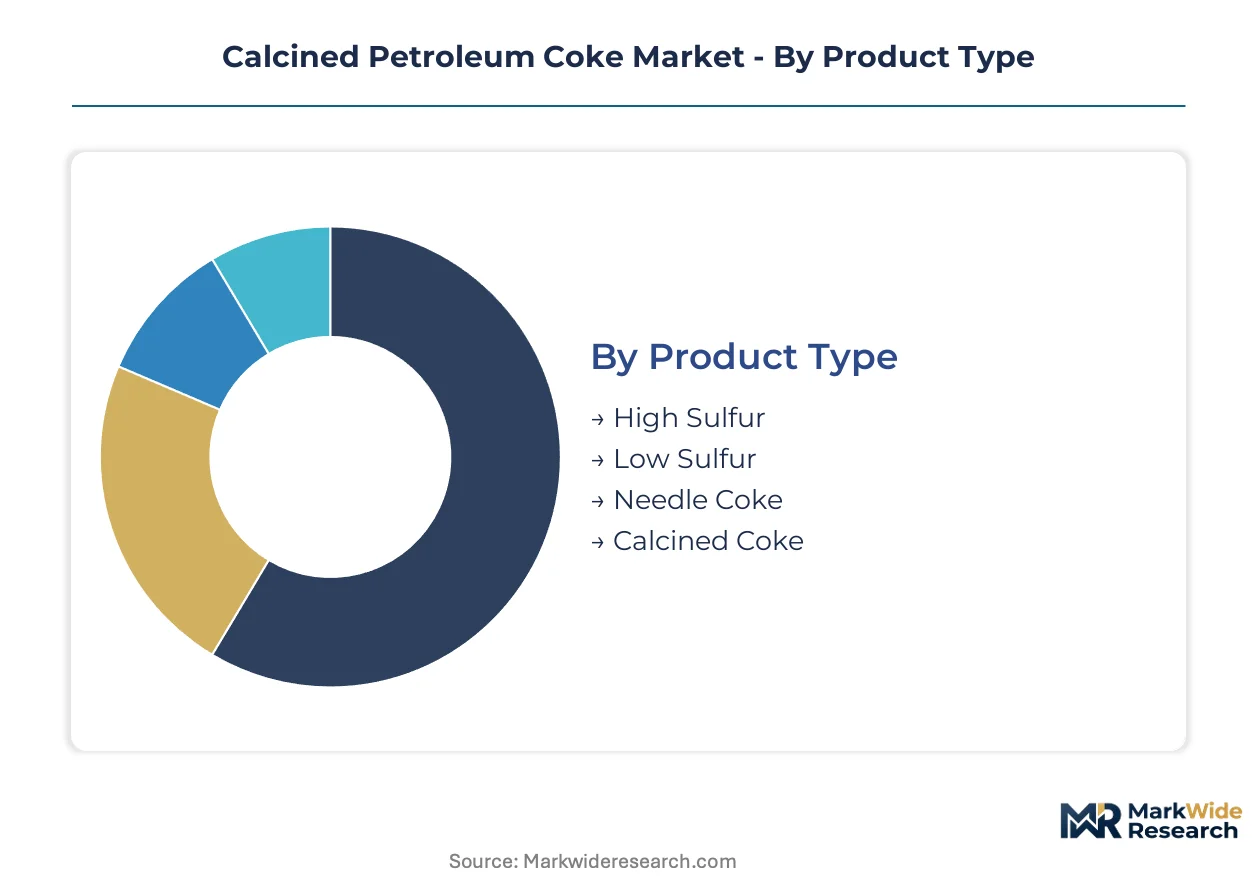
Calcined petroleum coke specifications diverge sharply across end-use requirements, with sulfur content, crystalline structure, and thermal properties determining pricing tiers and supply chain access. Product differentiation separates commodity fuel applications from premium anode and battery-grade supply chains where purity protocols lock in multi-year contracts.
Product Type:
Specification thresholds define commercial positioning across the calcination output spectrum, with sulfur limits and crystalline orientation separating commodity grades from premium battery and aerospace applications.
- Low Sulfur:Contains under 1.5 percent sulfur content with fixed carbon exceeding 99 percent, qualifying for aluminum smelter anodes where sulfur contamination degrades electrolytic efficiency. Primary demand concentrates in Saudi Arabia and UAE smelter expansions where high-purity anodes are specified for new potline capacity.
- Needle Coke:Exhibits distinctive needle-like crystalline structure with ultra-low thermal expansion coefficient below 1.0 ppm/°C, essential for lithium-ion battery anodes and ultra-high power graphite electrodes. South Korean battery manufacturers are locking multi-year offtake agreements directly with calciners to secure supply chain priority.
- High Sulfur:Carries sulfur content above 3 percent, limiting use to cement kiln fuel and lower-tier foundry applications where emissions regulations permit.
- Calcined Coke:General-grade material serving recarburizer demand in steelmaking and basic carbon product manufacturing.
Low sulfur leads on scale; needle coke leads on momentum.
End User:
Customer concentration patterns reflect regional industrial structure, with aluminum smelter location dictating anode-grade logistics economics and steel sector consolidation shaping recarburizer procurement.
- Aluminum Industry:Absorbs the majority of anode-grade low sulfur calcined coke for Hall-Héroult electrolytic reduction cells. Indian smelter expansions at Odisha and Gujarat are pulling dedicated supply chain investments from Middle East calciners.
- Steel Sector:Deploys calcined coke as recarburizer in electric arc furnace and ladle metallurgy operations to adjust carbon content in liquid steel. European steelmakers under EU Carbon Border Adjustment Mechanism are sourcing from verified low-carbon calcination sources.
- Titanium Dioxide:Utilizes high-purity carbon reductant in chloride process pigment manufacturing.
- Carbon Products:Encompasses specialty graphite, carbon black feedstock, and friction material applications.
Aluminum commands volume concentration; battery supply chains are climbing the fastest.
Application:
Use-case specifications create divergent purity and form factor requirements, with electrode production demanding consistent density and battery manufacturing imposing strict particle size distributions.
- Electrode Production:Consumes needle coke and premium low sulfur grades for ultra-high power and regular power graphite electrodes used in electric arc furnace steelmaking. Chinese electrode manufacturers are qualifying new needle coke sources outside traditional supply channels.
- Battery Manufacturing:Requires needle coke with spherical morphology and controlled surface area for synthetic graphite anode precursors. Japanese cathode material producers are integrating backward into calciner partnerships to secure qualified feedstock.
- Steelmaking:Direct recarburizer application in foundries and mini-mills with less stringent sulfur constraints.
- Fuel Cells:Emerging application for high-purity carbon materials in bipolar plate and catalyst support structures.
Electrode production anchors current demand; battery manufacturing shows the steepest expansion trajectory.
Distribution Channel:
Channel selection reflects customer scale and specification complexity, with direct relationships dominating premium grades and intermediaries handling commodity volumes.
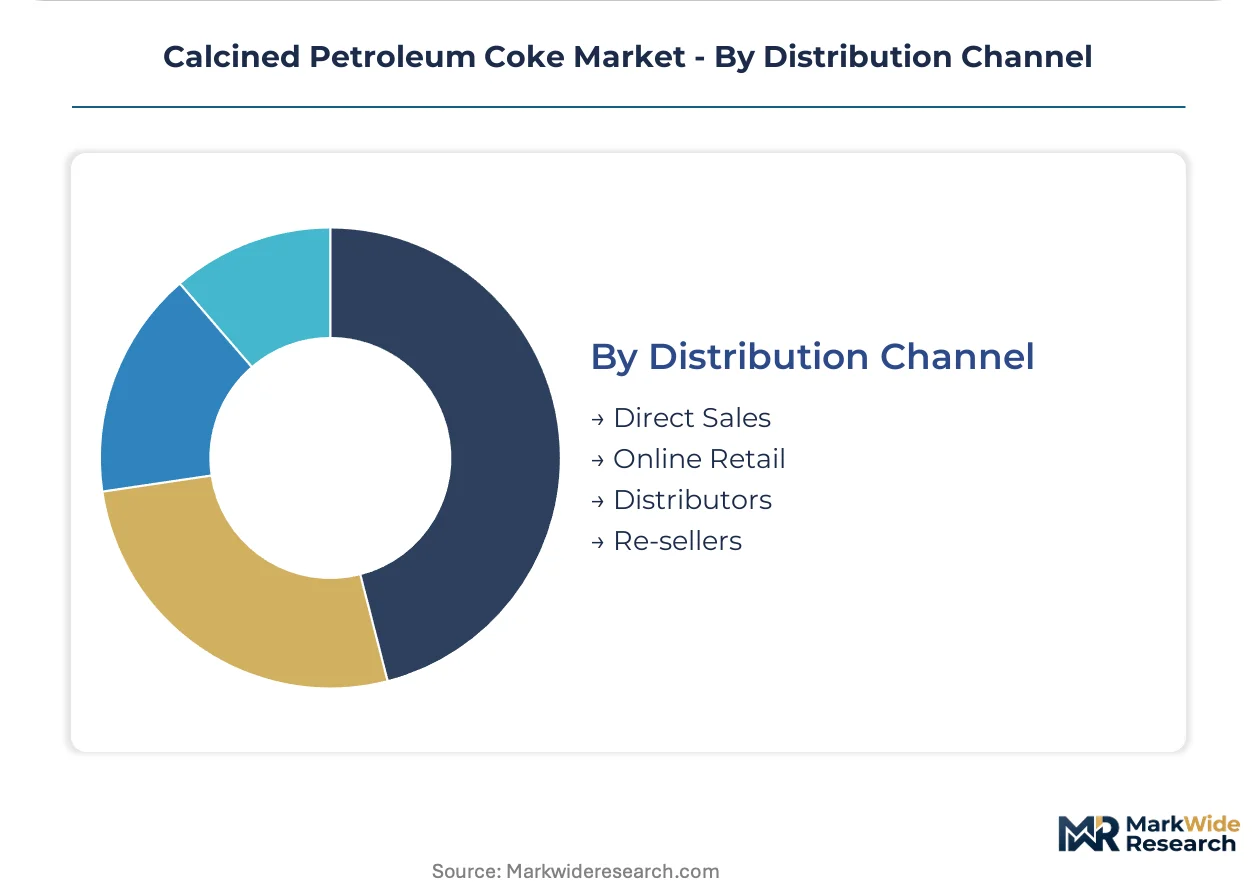
- Direct Sales:Predominates for anode-grade and needle coke where technical qualification, long-term offtake terms, and carbon accounting verification require producer-customer integration. Major aluminum smelters in India and the Middle East negotiate directly with integrated calciner-refinery operators.
- Distributors:Handle standard-grade recarburizer and fuel coke for fragmented steel foundry and cement customer bases where lot sizes and credit terms favor intermediary aggregation.
- Online Retail:Limited to laboratory and small-volume specialty carbon product sampling.
- Re-sellers:Occupy opportunistic arbitrage positions in spot market high sulfur fuel coke.
Direct sales capture premium value; distributor networks retain commodity volume throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized calciner engineering talent concentrates in legacy industrial corridors across the United States, Germany, and China, anchoring operational expertise for rotary kiln optimization and emissions control systems.
United States
Domestic aluminum smelters along the Gulf Coast and Pacific Northwest consume substantial anode-grade volumes. EPA emissions rules are elevating calciner capital intensity for baghouse upgrades and sulfur recovery installations. Rain Carbon Inc. operates integrated calcination capacity across Texas and Louisiana, sustaining purity leadership through refinery-calciner co-location.
China
Dual carbon goals are forcing calciner technology upgrades across the green petroleum coke supply base. MEE air quality standards tighten refinery emissions standards for calcination operations. Shandong Peninsula clusters host concentrated calcination capacity serving both domestic aluminum smelters and battery-grade needle coke producers.
India
Aluminum smelter expansions at Odisha and Gujarat are pulling dedicated anode-grade consumption upward. BIS quality standard harmonization supports domestic calcination capacity expansion aligned with import substitution goals. HPCL-Mittal Energy Limited anchors captive supply relationships serving northwestern smelter complexes.
Saudi Arabia
Middle East smelter projects are absorbing premium low-sulfur calcined coke at scale for new potline capacity. Saudi Aramco leverages integrated refinery-calciner assets to capture regional anode-grade demand. Jubail Industrial City hosts concentrated carbon processing infrastructure serving Gulf aluminum producers.
Germany
EU REACH compliance requirements are decoupling European supply from legacy import channels. The EU Carbon Border Adjustment Mechanism reshapes trade flow economics for carbon-intensive calcined coke imports. Ruhr industrial corridor calciners with verified low-carbon process heat gain preference from European aluminum smelters.
Calcined Petroleum Coke Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Integrated refinery-calciner operators command feedstock security advantages. Standalone calciners compete on technical qualification and purity certification. Capacity expansion and strategic partnerships dominate competitive moves as players secure long-term offtake agreements with battery anode manufacturers.
Among North American integrated operators, Rain Carbon Inc. and Oxbow Corporation exemplify archetypes spanning refinery-calciner co-location and green coke sourcing network control. Phillips 66 Company occupies a position representing downstream oil major participation in calcination value chains. These three entities anchor competitive positioning through distinct supply chain configurations rather than product differentiation alone.
| Leading Market Players |
|---|
| Rain Carbon Inc. |
| Oxbow Corporation |
| Phillips 66 Company |
| BP p.l.c |
| Saudi Aramco |
| ExxonMobil Corporation |
| Indian Oil Corporation |
| HPCL-Mittal Energy Limited |
| Petrobras |
| Others |
Supply Flow & Price Mechanics
Green petroleum coke feedstock costs cascade through calcination economics, with sulfur content and refinery proximity determining tier placement from premium anode-grade to commodity fuel applications. Refinery-calciner co-location in Texas, Louisiana, and Jubail compresses logistics exposure while baghouse upgrade mandates elevate fixed cost layers across independent operators.
Pricing Analysis
Long-term offtake contracting dominates premium needle coke and anode-grade segments, while spot markets handle high-sulfur fuel coke. Price differentiation rests on sulfur certification tiers and REACH dossier completeness, with EU-bound material commanding premiums over unregistered import channels. Pricing pressure stems from EPA and MEE emissions compliance capital requirements, compressing margins for standalone calciners without captive refinery supply. Battery anode manufacturers show least price sensitivity, locking multi-year supply agreements, while cement kiln buyers drive hardest bargain on fuel-grade volumes.
Supply Chain Analysis
Green coke supply rests on refinery coking capacity decisions concentrated in the United States, China, and Saudi Arabia. Input dependencies include crude oil sulfur slate, delayed coker run rates, and calciner rotary kiln availability. Single-source vulnerability concentrates in high-purity needle coke qualified for lithium-ion anode specifications. Distribution runs through direct sales channels for premium grades, with distributor networks handling fragmented foundry and cement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The calcined petroleum coke market functions as a stable compounder, with aluminum smelter capacity expansion in India and the Middle East providing durable demand underpinning.
For Market Incumbents: Lock in captive green coke supply through refinery-calciner co-location or long-term offtake agreements with Middle East producers. Invest in REACH dossier pre-registration and EPA baghouse upgrades ahead of enforcement waves to defend premium positioning against non-compliant import channels. Prioritize needle coke capacity expansion for battery anode qualification programs. For New Entrants and Emerging Players: Domestic Indian aluminum smelters represent the most penetrable buyer archetype, with BIS quality standard harmonization creating entry points alongside HPCL-Mittal's captive relationships. Target high-sulfur fuel coke spot market arbitrage in Southeast Asian cement markets as initial revenue anchor. Pursue toll calcination partnerships with stranded green coke producers to minimize capital intensity. For Investors and Strategic Acquirers: Consolidation pressure builds where standalone calciners face stranded asset risk from emissions compliance capital demands. The five-to-ten year viability window favors integrated refinery-calciner operators with verified low-carbon process heat and battery supply chain qualifications. Watch needle coke qualification timelines with South Korean and Japanese cathode material producers as inflection signal for premium tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Refinery-Calciner Co-location | Captive green coke supply eliminates moisture reabsorption and trims logistics costs for Gulf Coast operators. |
| REACH Dossier Pre-registration | EU substance data compliance unlocks European aluminum smelter procurement channels ahead of CBAM implementation. |
| Needle Coke Capacity Expansion | Battery anode manufacturer offtake agreements provide volume visibility through electric vehicle supply chain ramp. |
| Baghouse Emissions Upgrade | EPA and MEE air quality rule compliance sustains operating permits for rotary kiln calcination assets. |
| Long-term Supply Agreement | Multi-year contracts with Saudi and Indian smelter projects secure anode-grade volume through potline commissioning cycles. |
Methodological Framework
Direct dialogue with rotary kiln operations managers, aluminum smelter procurement leads, petroleum refinery planning officers, and battery anode material R&D directors grounded qualitative findings. Secondary validation drew from EPA emissions filings, ECHA REACH registrations, EIA refinery coking capacity data, and customs trade records. Bottom-up calciner capacity modeling and top-down aluminum production forecasts were triangulated against primary interview intelligence.
Segment-level value outputs across the projection horizon reflect product type, sulfur grade tier, end-use industry, and regional production hub dimensions. CAGRs were derived from historical demand elasticity analysis and forward capacity commissioning schedules. Key inputs included refinery coker run rate projections, aluminum smelter potline expansion timelines, and battery-grade needle coke qualification status with cathode material producers.
Inputs from ECHA substance databases and EPA emissions inventories were available through the study window; gaps in private offtake contract pricing introduce uncertainty bands around premium tier value estimates. Forecasts reflect assumptions on dual carbon policy enforcement intensity and electric vehicle penetration trajectories. A small set of triggers—needle coke qualification accelerations, refinery coking capacity closures, and CBAM carbon border levy implementation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Industrial Personal Computer Market
Others
Enterprise Video Market
Others
Super Computer Market
Others
Cremation Furnace Market
Others
Server Market
Others
Aerospace and Defense Fiber Optic Cables Market
Others
Europe Battery Packaging Market
Others
Europe Travel Retail Market
Others
Commercial Aircraft Angle of Attack Sensors Market
Others
Infant Positioning Aids Market
Others
Connected Homes Market
Others
AI In Government And Public Services Market
Others
Augmented Reality in BFSI Market
Others
China Smart Home Market
Others
Cat Dry Food Market
Others
Football Sportswear Market