
 Cat Dry Food Market | 2026-2036
Cat Dry Food Market Size, Share, and Industry Trends Forecast 2026-2036
Cat Dry Food Market Analytics
Asset-light contract manufacturing and third-party co-packing arrangements is fragmenting competitive dynamics in cat dry food production, lowering capital barriers for new entrants. Nestlé Purina PetCare leverages extensive in-house extrusion capacity across multiple continents. Mars Petcare sustains global supply chain density through vertically integrated ingredient sourcing. Hill's Pet Nutrition differentiates via prescription-grade formulations developed under veterinary oversight.
Cat dry food consists of extruded kibble typically containing 6-10% moisture, formed through high-pressure thermal processing of meals, grains, and functional additives, designed for shelf-stable feline nutrition and dental health benefits. Grain-free formulations command premium positioning as consumers link carbohydrate reduction to obligate carnivore physiology. High-protein segments attract ingredient investments from suppliers of rendered meat meals and novel protein sources. Senior-targeted age groups represent an expanding margin pool as feline longevity extends and geriatric nutritional requirements sharpen.
The United States Food and Drug Administration and the Association of American Feed Control Officials jointly enforce ingredient definitions and nutritional adequacy claims that manufacturers must satisfy for interstate commerce. European feed regulators under the EU Feed Hygiene Regulation impose strict Salmonella controls and additive authorization protocols that shape export compliance costs. Stakeholders must monitor evolving veterinary feeding guidelines and state-level raw material traceability mandates to anticipate reformulation cycles and sourcing realignments.
Market Dynamics
Pet humanization is restructuring competitive positioning in cat dry food as owners treat feline nutrition with clinical precision once reserved for human dietary supplements. This behavioral shift compresses product lifecycles and elevates veterinary endorsement as a purchase determinant.
Growth Catalysts
- AAFCO Nutritional Adequacy Protocols:FDA-aligned labeling standards in the United States create compliance clarity that accelerates new product introductions and reduces interstate commerce friction for reformulated lines.
- Extrusion Technology Advancements:High-pressure thermal processing improvements enable protein denaturation control that preserves amino acid bioavailability while achieving dental abrasion targets.
- Urban Pet Ownership Density:Apartment-dwelling cat populations in Shanghai and Shenzhen concentrate demand for shelf-stable, odor-mitigating dry formulations over raw or wet alternatives.
Market Restraints
- Rendered Protein Meal Volatility:Supply concentration among poultry by-product processors exposes margins to feed-grade commodity price swings and avian influenza disruption cycles.
- EU Salmonella Zero-Tolerance Thresholds:European feed hygiene mandates impose detection limits below 10 CFU per 25g that disqualify conventional thermal processing for export-bound production.
- Carbohydrate Substitution Ceiling:Obligate carnivore physiology limits grain-free formulation flexibility as tapioca and pea starch alternatives face digestibility criticism from veterinary nutritionists.
Strategic Opportunities
- Geriatric Feline Nutrition White Space:Kidney-support phosphorus restriction and joint health glucosamine fortification target the expanding twelve-plus age demographic in Japan and Western Europe.
- Veterinary Channel Direct Distribution:Prescription-grade lines bypass retail markup through clinic-exclusive fulfillment models that capture lifetime value via recurring subscription protocols.
- Novel Protein Source Authorization:Insect meal and cultivated meat regulatory pathways under EFSA novel food consultation create first-mover positioning for sustainability-positioned entrants.
Industry Challenges
- AAFCO Feeding Trial Certification Timelines:Six-month palatability and digestibility studies delay revenue realization for reformulated SKUs targeting seasonal purchasing windows.
- Legacy Extrusion Asset Retrofit Complexity:Cold extrusion and post-extrusion coating upgrades demand capital deployment against uncertain payback periods given SKU proliferation rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cat Dry Food Market |
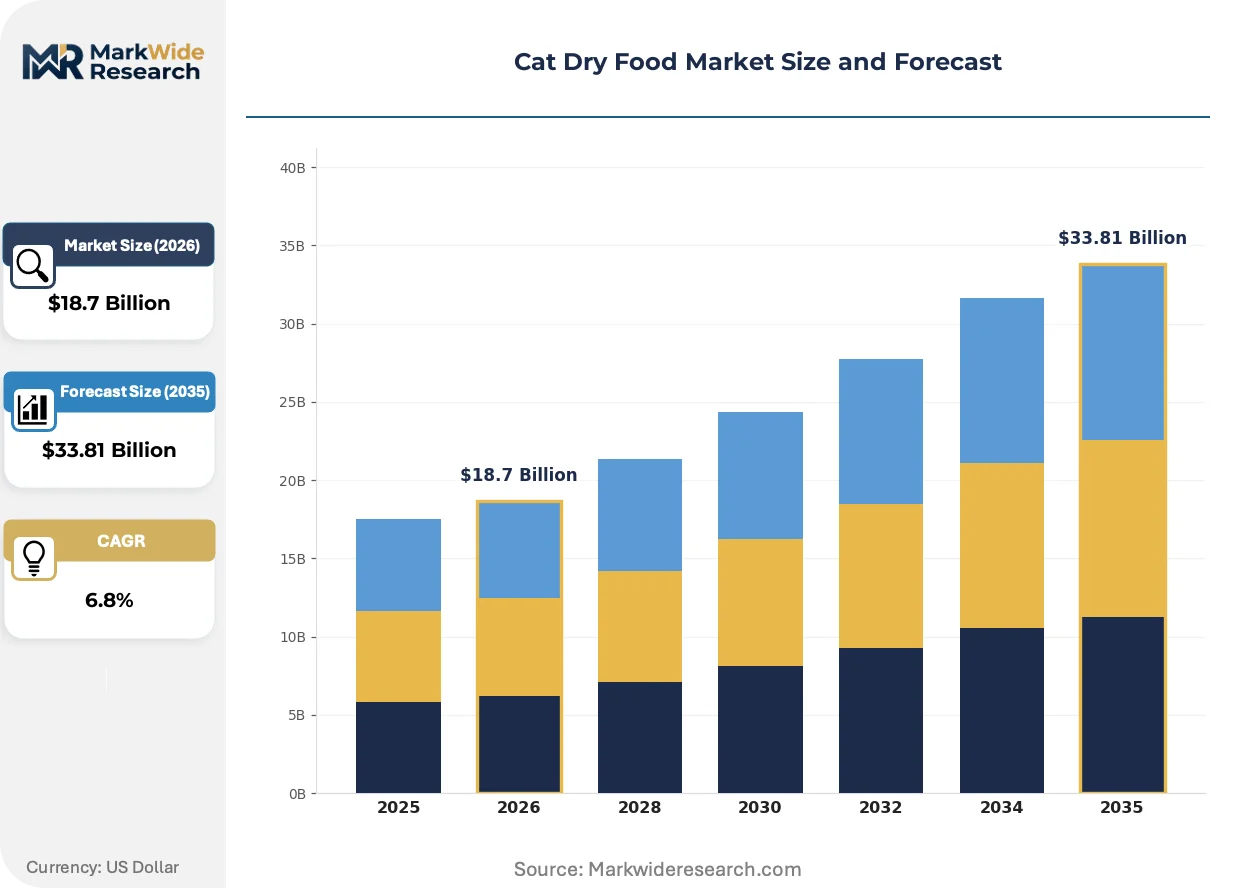
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grain-Free, High Protein, Organic, Natural Flavor: Chicken, Fish, Beef, Salmon Target Age Group: Kitten, Adult, Senior, All Life Stages Packaging Type: Bags, Pouches, Bulk, Tubs |
| Companies Covered | Nestlé Purina PetCare, Mars Petcare, Hill’s Pet Nutrition, General Mills, The J.M. Smucker Company, Diamond Pet Foods, WellPet, Unicharm Corporation, Affinity Petcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cat Dry Food Market Evolving Landscape
Digital traceability infrastructure is compressing supply chain opacity as batch-level ingredient provenance becomes a visible purchase attribute. This transparency imperative intersects with processing innovation and regulatory harmonization to redefine competitive differentiation.
Cold extrusion and post-extrusion coating technologies are virtualizing conventional high-heat processing by enabling heat-sensitive additive incorporation after thermal denaturation. Premium-positioned manufacturers in Germany and the United States deploy these systems to preserve probiotic viability and omega-3 fatty acid integrity. The technology is virtualizing quality tier boundaries as mid-market brands access previously premium-exclusive nutritional claims.
EFSA's novel food authorization framework for insect protein and cultivated meat ingredients is compressing formulation innovation cycles as applicants navigate eighteen-month safety assessment timelines. Pet food manufacturers with pre-submission data packages gain competitive runway while awaiting positive opinions. European export-dependent producers in Thailand and Argentina are restructuring ingredient sourcing to maintain EU market access.
Veterinary endorsement is displacing retail shelf placement as the primary purchase trigger among urban millennial owners. Clinic recommendation protocols and prescription fulfillment platforms capture loyalty through subscription auto-delivery models. This channel shift is most pronounced in the United States and United Kingdom where pet insurance penetration correlates with clinical diet adherence.
Cat Dry Food Market Segmentation
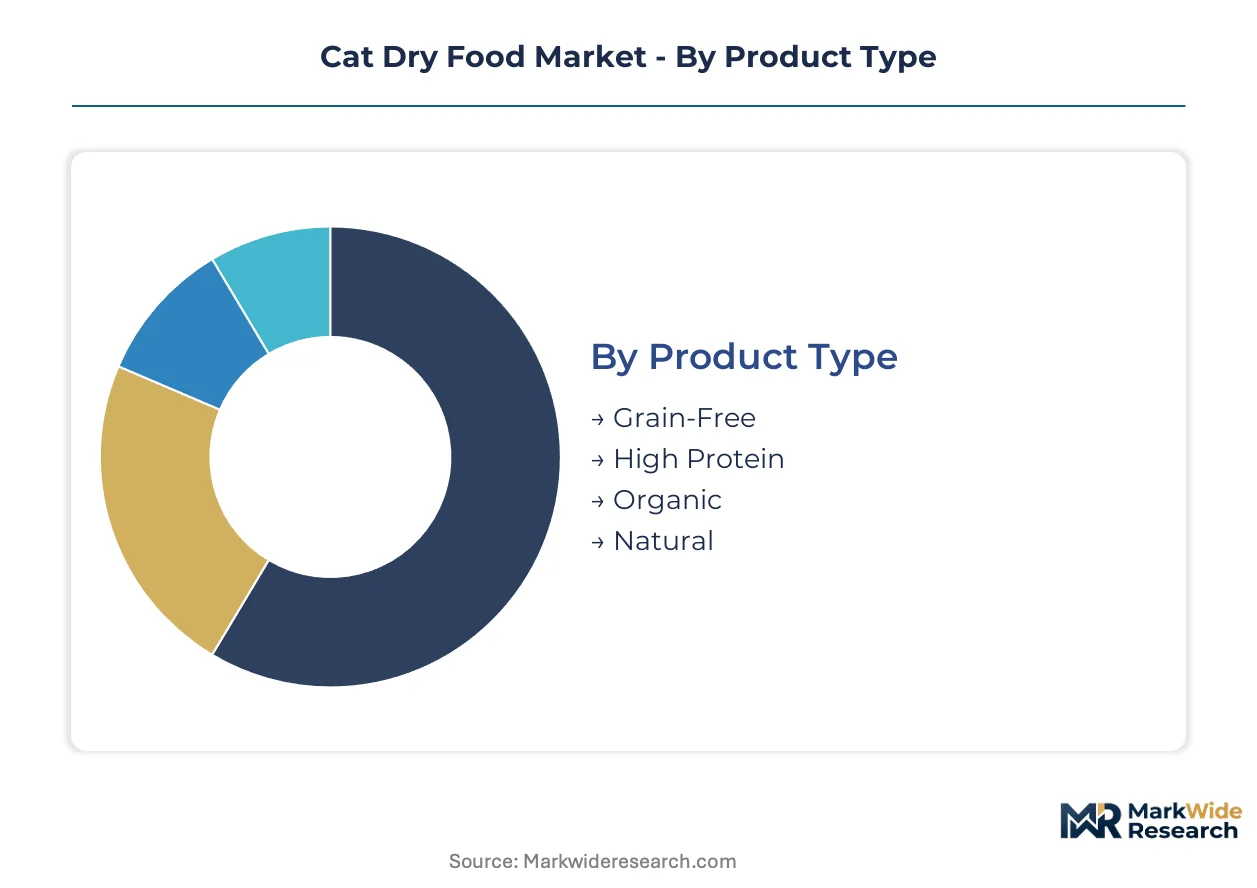
Cat dry food segmentation reflects divergent owner priorities across nutritional philosophy, life-stage biology, and convenience requirements. Manufacturers calibrate formulation density, palatability systems, and packaging formats to capture distinct willingness-to-pay thresholds.
Product Type:
The use-case spectrum spans clinical dietary intervention to lifestyle-aligned feeding choices, with protein architecture and carbohydrate load as the primary technical differentiators.
- Grain-Free:Formulations replace cereal grains with tapioca, pea starch, or legume flours to reduce carbohydrate load for obligate carnivore physiology. Demand concentrates in the United States and Germany where veterinary nutrition discourse has elevated carbohydrate scrutiny among urban owners.
- High Protein:Extruded kibble with elevated rendered meat meal inclusion targets muscle maintenance and satiety signaling. China and Japan drive volume as apartment-dwelling cat populations prioritize calorie density per feeding volume.
- Organic:Certified ingredient chains exclude synthetic pesticides and GMO feed crops from the protein supply base. Premium positioning in France and Switzerland supports price multiples over conventional lines.
- Natural:Minimal processing claims and absence of artificial colors or preservatives attract label-conscious purchasers in mass retail channels.
The dominant share belongs to High Protein, while Grain-Free is closing the gap fastest.
Flavor:
Palatability engineering and raw material procurement economics shape competitive positioning across the taste architecture.
- Chicken:Poultry by-product meal dominates global rendering capacity, delivering consistent amino acid profiles at scale. United States and Brazil supply chains anchor cost-competitive positioning.
- Fish:Marine protein meals from Peruvian anchovy and North Atlantic fisheries command omega-3 positioning premiums. Japan and South Korea concentrate demand for DHA-enriched developmental formulations.
- Beef:Bovine meal inclusion remains constrained by BSE-era regulatory restrictions in the EU and Japan, limiting formulation flexibility.
- Salmon:Farmed Atlantic salmon trim and hydrolysate supply chains support hypoallergenic positioning in veterinary-recommended lines.
Chicken maintains volume leadership, though Salmon is climbing the fastest on premiumization tailwinds.
Target Age Group:
Life-stage nutrition science drives reformulation cycles as physiological requirements shift across growth, maintenance, and degenerative disease management.
- Kitten:Elevated caloric density and DHA fortification support neural development and rapid growth phases. Breeder channels and first-time owner acquisition drive trial volume.
- Adult:Maintenance formulations balance protein turnover with weight management through controlled fat inclusion. Mass retail and subscription channels sustain recurring revenue.
- Senior:Phosphorus restriction and glucosamine fortification address renal function decline and joint degradation in the twelve-plus demographic. Japan and Western Europe concentrate this expanding margin pool.
- All Life Stages:AAFCO-compliant formulations meeting nutritional minima across growth and maintenance phases appeal to multi-cat households seeking feeding simplification.
Adult formulations hold the dominant share, while Senior is gaining share fastest on longevity extension trends.
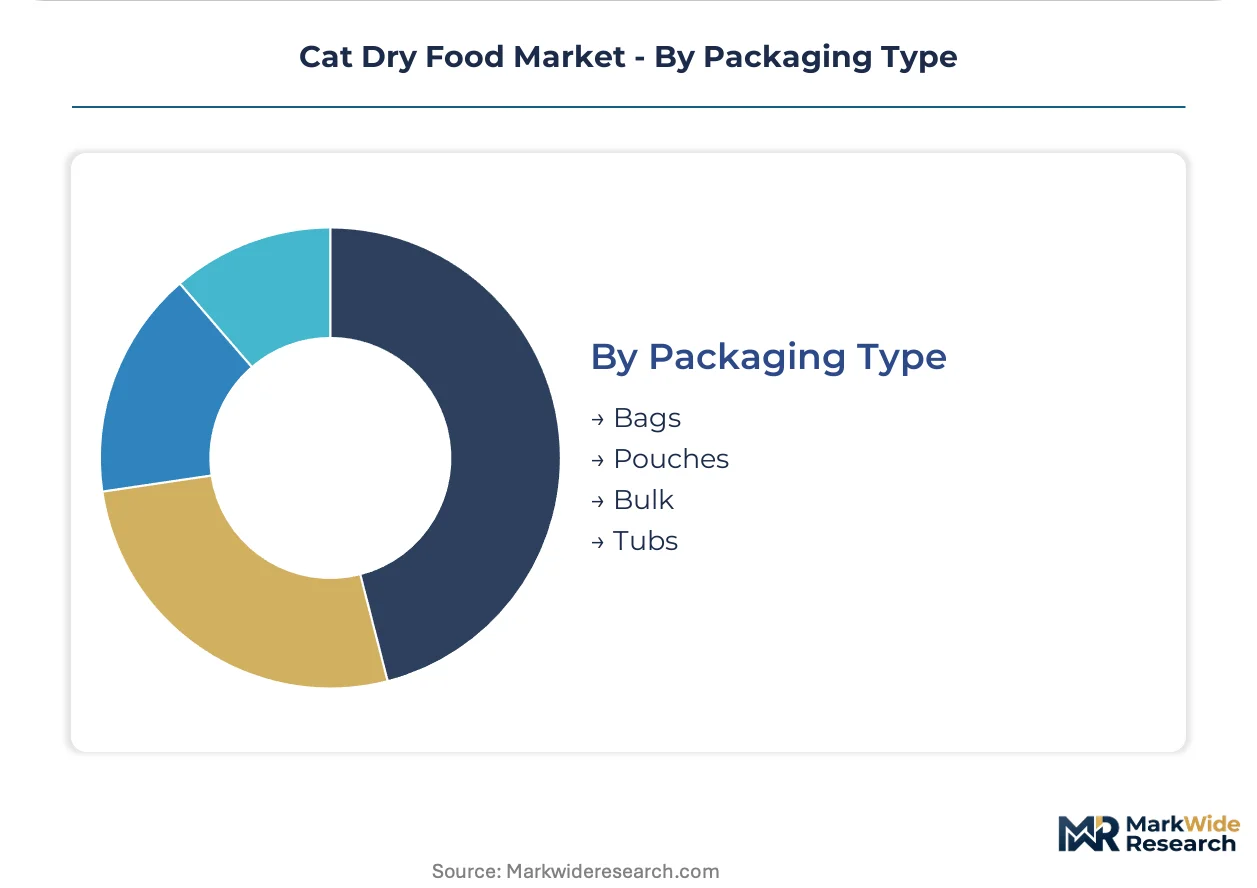
Packaging Type:
Supply chain configuration and consumption velocity determine format selection across retail, veterinary, and direct-to-consumer channels.
- Bags:Multi-layer polymer and paperboard laminates dominate shelf-stable retail distribution with resealability features. United States and China production lines achieve lowest unit economics at volume.
- Pouches:Flexible film formats reduce shipping cube and support single-serve trial sizes in subscription acquisition funnels.
- Bulk:Institutional and breeder channel supply in food-service-grade containers minimizes per-kilogram packaging cost for high-velocity consumption.
- Tubs:Rigid plastic containers with snap lids support premium positioning and moisture-retention claims in specialty retail.
Bags command the dominant share, while Pouches are expanding most quickly on e-commerce penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban millennial pet owners in dense metropolitan clusters drive differentiated demand patterns across major national markets. Veterinary endorsement and e-commerce penetration reshape regional competitive dynamics. Regulatory frameworks in each jurisdiction dictate formulation and labeling compliance costs.
United States
Pet insurance penetration correlates with prescription diet adherence in metropolitan corridors from Boston to Seattle. FDA and AAFCO jointly enforce nutritional adequacy claims that manufacturers must satisfy for interstate commerce. St. Louis and Denver host concentrated extrusion capacity serving mass-market and premium private-label lines.
China
Apartment-dwelling cat populations in Shanghai and Shenzhen concentrate demand for shelf-stable, odor-mitigating formulations over raw alternatives. SAMR and GB standards govern feed safety and ingredient labeling with escalating traceability mandates. Yangtze River Delta manufacturing clusters supply domestic volume and Southeast Asian export markets.
Germany
Grain-free and organic positioning commands premium multiples among label-conscious owners in Munich and Hamburg metropolitan areas. EFSA and EU Feed Hygiene Regulation impose strict Salmonella controls and additive authorization protocols. Bavarian production facilities lead cold extrusion technology deployment for heat-sensitive additive preservation.
Japan
Feline longevity extension sharpens demand for kidney-support phosphorus restriction and joint health fortification in the twelve-plus age demographic. METI and Ministry of Agriculture standards regulate functional claim substantiation and novel ingredient approval. Tokyo-Osaka corridor veterinary clinics drive prescription-grade distribution through subscription auto-delivery models.
United Kingdom
Millennial owner concentration in London and Manchester elevates veterinary channel influence over retail shelf placement decisions. FSA and DEFRA administer feed hygiene and animal by-product processing rules aligned with EU-retained law. Midlands-based co-packing infrastructure supports agile SKU proliferation for direct-to-consumer subscription entrants.
Cat Dry Food Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. Mass-market dominance by diversified consumer goods conglomerates contrasts with veterinary-prescription specialists and agile private-label co-packers. Three archetypes define competitive positioning: vertically integrated multinationals with captive ingredient sourcing, prescription-grade formulators with clinical endorsement protocols, and asset-light contract manufacturers enabling rapid SKU experimentation. Capacity expansion and cold extrusion technology licensing constitute the dominant competitive moves.
Among Swiss and US-based diversified nutrition conglomerates, Nestlé Purina PetCare and Mars Petcare occupy positions exemplifying scale-driven supply chain density and in-house extrusion capacity across multiple continents. Hill's Pet Nutrition represents the prescription-grade archetype with veterinary oversight development protocols. These three anchors illustrate the tension between mass-market volume efficiency and clinical-channel premium capture.
| Leading Market Players |
|---|
| Nestlé Purina PetCare |
| Mars Petcare |
| Hill's Pet Nutrition |
| General Mills |
| The J.M. Smucker Company |
| Diamond Pet Foods |
| WellPet |
| Unicharm Corporation |
| Affinity Petcare |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta manufacturing clusters anchor global extrusion capacity and transmit cost efficiencies downstream to mass-market pricing tiers. Their scale density allows contract manufacturers to undercut vertically integrated multinationals on private-label bids, compressing margins across mid-market positioning.
Pricing Analysis
Certification level creates the primary spread, with AAFCO feeding trial validation and EU Feed Hygiene Regulation compliance commanding 15-25% premiums over baseline formulations. Three-tier pricing structure separates veterinary prescription lines from premium grain-free positioning from economy private-label supply. Pricing pressure stems from rendered protein meal commodity volatility and avian influenza disruption cycles. Mass retail channels exhibit highest price sensitivity, while clinic-exclusive prescription fulfillment captures inelastic demand through subscription lock-in.
Supply Chain Analysis
Rendered poultry by-product meal supply concentrates in United States, Brazil, and Thailand rendering facilities. Extruded kibble production draws from poultry meal, tapioca starch, and marine protein hydrolysate inputs. Single-source vulnerability runs through concentrated poultry by-processor capacity exposed to pathogenic outbreak quarantine protocols. Distribution runs through veterinary clinic networks, mass retail shelf placement, and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary nutrition expertise and cold extrusion technical capacity represent scarce assets that constrain competitive replication. Manufacturers lacking these capabilities face margin compression as premiumization accelerates.
For Market Incumbents: Entrench clinical endorsement relationships through exclusive veterinary clinic distribution partnerships and subscription auto-delivery protocols. Defend against private-label erosion by accelerating cold extrusion capacity expansion in Bavaria and Colorado manufacturing hubs. Certification investment in EFSA novel food pathways for insect protein secures sustainability-positioned product pipelines.
For New Entrants and Emerging Players: Pursue geriatric feline nutrition white space in Japan and Western Europe where phosphorus-restricted formulations face limited specialized competition. Target senior age group segments through kidney-support and joint health positioning. Go-to-market through direct-to-consumer subscription models bypasses retail slotting fee barriers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors contract manufacturers with asset-light co-packing infrastructure enabling rapid SKU experimentation. Long-term viability hinges on regulatory navigation capability across FDA-AAFCO and EFSA frameworks. Acquisition targets should demonstrate pre-submission data packages for novel protein authorization. Watch EFSA positive opinion timelines as inflection signal for sustainability-premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold Extrusion Technology Licensing | Preserves probiotic viability and omega-3 integrity for premium positioning claims. |
| Veterinary Channel Direct Distribution | Bypasses retail markup through clinic-exclusive subscription fulfillment models. |
| Novel Protein Source Authorization | EFSA pre-submission data packages create competitive runway for insect meal positioning. |
| Backward Integration into Rendering | Captive poultry by-product supply insulates margins from avian influenza volatility. |
| Geriatric Formulation R&D Investment | Phosphorus restriction and glucosamine fortification target expanding twelve-plus demographic. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with veterinary nutritionists, extrusion plant managers, retail category buyers, and contract manufacturing executives. Secondary validation drew from FDA enforcement reports, AAFCO official publications, EFSA novel food consultation records, and customs trade flow databases. Bottom-up volume modeling triangulated against top-down value estimates across product type, flavor architecture, target age group, and packaging format dimensions.
Calibration against historical growth patterns and input cost trajectories shaped projection assumptions across the analysis window. Segmentation modeling incorporated protein source tier, life-stage nutritional requirement, distribution channel density, and regional regulatory cluster variables. CAGRs derived from elasticity-adjusted demand curves and capacity expansion pipelines. Forecast inputs included pet ownership demographic shifts and veterinary endorsement influence indices.
Macroeconomic conditions sit as an overlay; deviation in protein meal commodity indices or avian influenza outbreak severity would shift the trajectory. Forecasts reflect documented assumptions about regulatory harmonization timelines and cold extrusion adoption rates. Cross-checking against Nielsen retail audit data and veterinary clinic dispensing records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Semiconductor Gas Filters Market
Others
Android STB and TV Market
Others
US Quantum Computing Market
Others
France Smart Home Market
Others
Radar Speed Signs Market
Others
Industrial Air Purifiers Market
Others
United States Cigarette Market
Others
Smart Home Service Market
Others
Global Essential Oils and Plant Extracts for Livestock Market
Others
Global Cosmetovigilance Market
Others
Middle East and Africa Induced Pluripotent Stem Cells (Ipscs) Market
Others
Magnetic Stripe Readers Market
Others
Japan Indoor LBS Market
Others
Wearable Brain Devices Market
Others
Asia-Pacific Agricultural Enzymes Market
Others
North America Thermoformed Plastics Market