
 Industrial Personal Computer Market | 2026-2036
Industrial Personal Computer Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Personal Computer Market Insights
Software-defined maintenance subscriptions is expanding as a revenue layer that shifts hardware vendors toward recurring relationships. Advantech Co., Ltd. leverages its embedded computing portfolio to anchor long-term service contracts across Asia-Pacific manufacturing clients. Siemens AG competes through vertical integration into automation software stacks that bind IPC hardware to proprietary control ecosystems. Beckhoff Automation differentiates via PC-based control architectures that sustain premium positioning in European precision machinery sectors.
An industrial personal computer is a ruggedized computing platform engineered with extended temperature tolerances, shock-resistant enclosures, and passive or fan-cooled thermal management to sustain continuous operation in factory floors, energy substations, and transportation depots. Panel PC configurations lead volume shipments due to their integration of display and processing in sealed housings for operator interface roles, while edge computing technology represents the fastest-expanding segment as facilities push data processing closer to production lines. Embedded PC architectures occupy mature margin pools in legacy retrofit environments where space constraints and deterministic I/O requirements dominate specification sheets.
The EU Cyber Resilience Act and CE marking directives under ECHA's substance restrictions are reshaping product design cycles for vendors seeking European market access, forcing hardware-level security attestations and material composition disclosures. The US FCC and FDA impose parallel electromagnetic compatibility and safety validation requirements on IPC deployments in medical device manufacturing and critical infrastructure control rooms. Stakeholders must monitor how divergent cybersecurity certification timelines across regulatory jurisdictions will reshape supplier qualification costs and regional competitive barriers.
Market Dynamics
Edge computing architectures are compressing compute latency requirements and forcing IPC vendors to redesign thermal management for cabinet-free deployment directly on production lines.
Growth Catalysts
- EU Cyber Resilience Act:Mandatory hardware-level security attestations for connected industrial devices are compelling facility operators to replace legacy computing platforms with certified IPC systems.
- Semiconductor fabrication expansion:Taiwan and South Korea are scaling process automation investments that require shock-resistant computing for cleanroom environments.
- Smart factory retrofits:Germany's automotive manufacturing corridor is driving specification demand for hardened IPC architectures in brownfield automation upgrades.
Market Restraints
- Component supply concentration:Specialized industrial-grade semiconductors source predominantly from concentrated East Asian foundries, exposing procurement to geopolitical disruption.
- Extended certification timelines:CE marking under ECHA substance restrictions and FCC electromagnetic validation create multi-quarter product launch delays.
- Passive thermal design limitations:Fanless cooling architectures constrain processing density in high-ambient-temperature deployments such as Middle Eastern energy infrastructure.
Strategic Opportunities
- India manufacturing incentives:PLI scheme subsidies for electronics production are attracting IPC assembly investments to serve domestic automation demand.
- Convergence of IPC and AI accelerators:On-device inference chip integration is opening new specification tiers for real-time quality inspection applications.
- Software-defined maintenance:Subscription service contracts are displacing transactional hardware sales and capturing recurring revenue from Asia-Pacific manufacturing clients.
Industry Challenges
- Cybersecurity skill scarcity:Embedded systems security engineering talent concentrates at semiconductor vendors, leaving IPC integrators dependent on external certification consultants.
- Legacy protocol integration:Deterministic fieldbus compatibility requirements in European precision machinery extend sales cycles and inflate non-recurring engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Personal Computer Market |
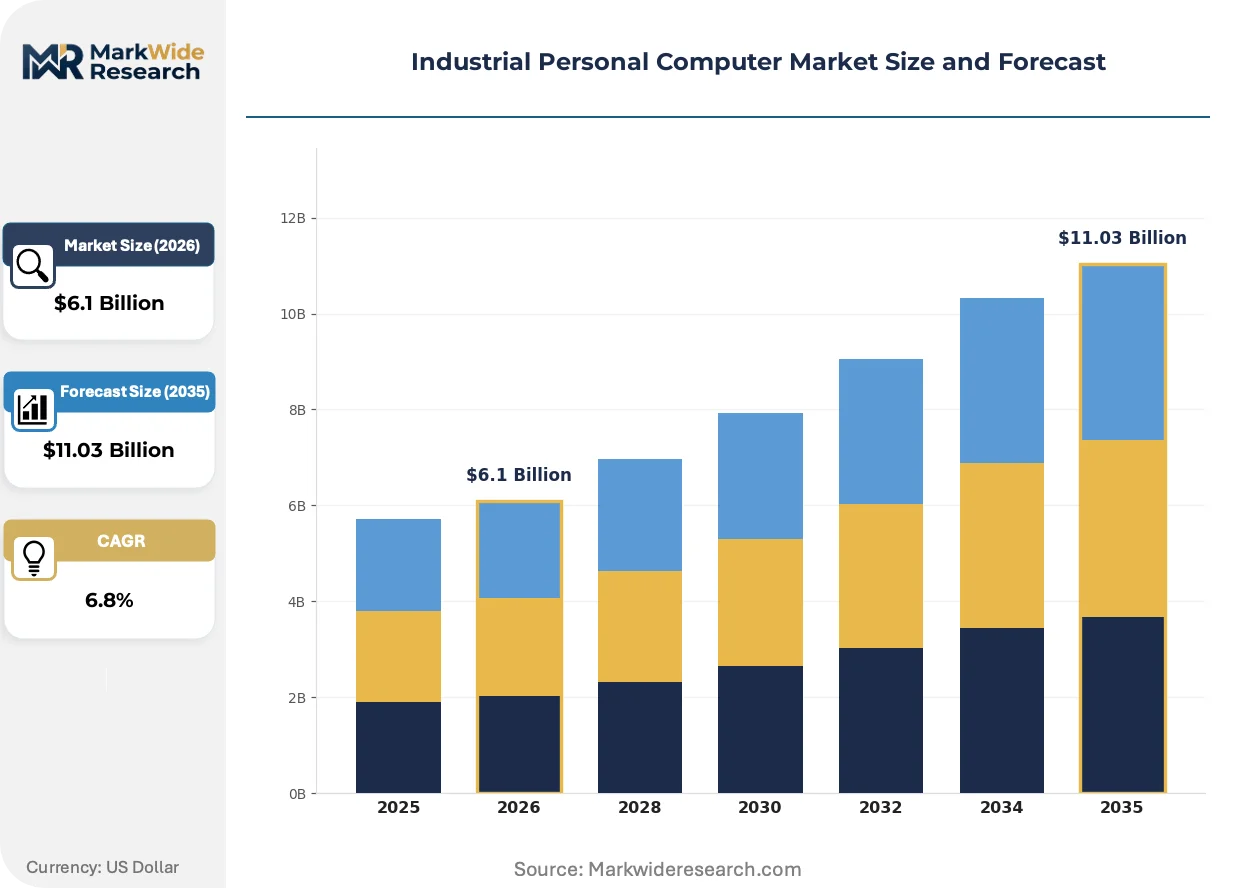
| Market Size in 2026 | $6.1 Billion |
| Market Size in 2035 | $11.03 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rack-Mounted, Panel PC, Embedded PC, Box PC Technology: IoT Connectivity, Edge Computing, Virtualization, AI Processing End User: Manufacturing, Energy, Transportation, Retail Application: Automation, Data Acquisition, HMI, Machine Control |
| Companies Covered | Advantech Co., Ltd., Beckhoff Automation, Siemens AG, Kontron, IEI Integration Corporation, Avalue Technology, DFI, B&R Automation, American Portwell Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Personal Computer Market Trends and Innovations
Compute migration toward production lines is restructuring how industrial data is processed, stored, and secured. Three developments are compressing the traditional hierarchy between enterprise servers and shop-floor controllers.
Edge-native IPC form factors are decentralizing data processing from centralized server rooms to machine-mounted enclosures. Automotive stamping plants in Germany are deploying these systems at line speed to eliminate network latency in defect detection. The shift is compressing infrastructure requirements and enabling closed-loop quality control without cloud dependency.
REACH substance restrictions and RoHS material disclosures are forcing component-level supply chain traceability for European market access. Vendors must now document full material compositions through multi-tier supplier networks. Medical device manufacturers face parallel FDA electromagnetic compatibility validation that extends qualification timelines for North American deployments.
Service contract unbundling is restructuring buyer-vendor relationships across Asia-Pacific manufacturing bases. Long-term maintenance subscriptions are displacing upfront hardware purchases with recurring revenue structures. Japanese precision equipment makers are piloting outcome-based pricing tied to uptime guarantees rather than capital expenditure models.
Industrial Personal Computer Market Segmentation
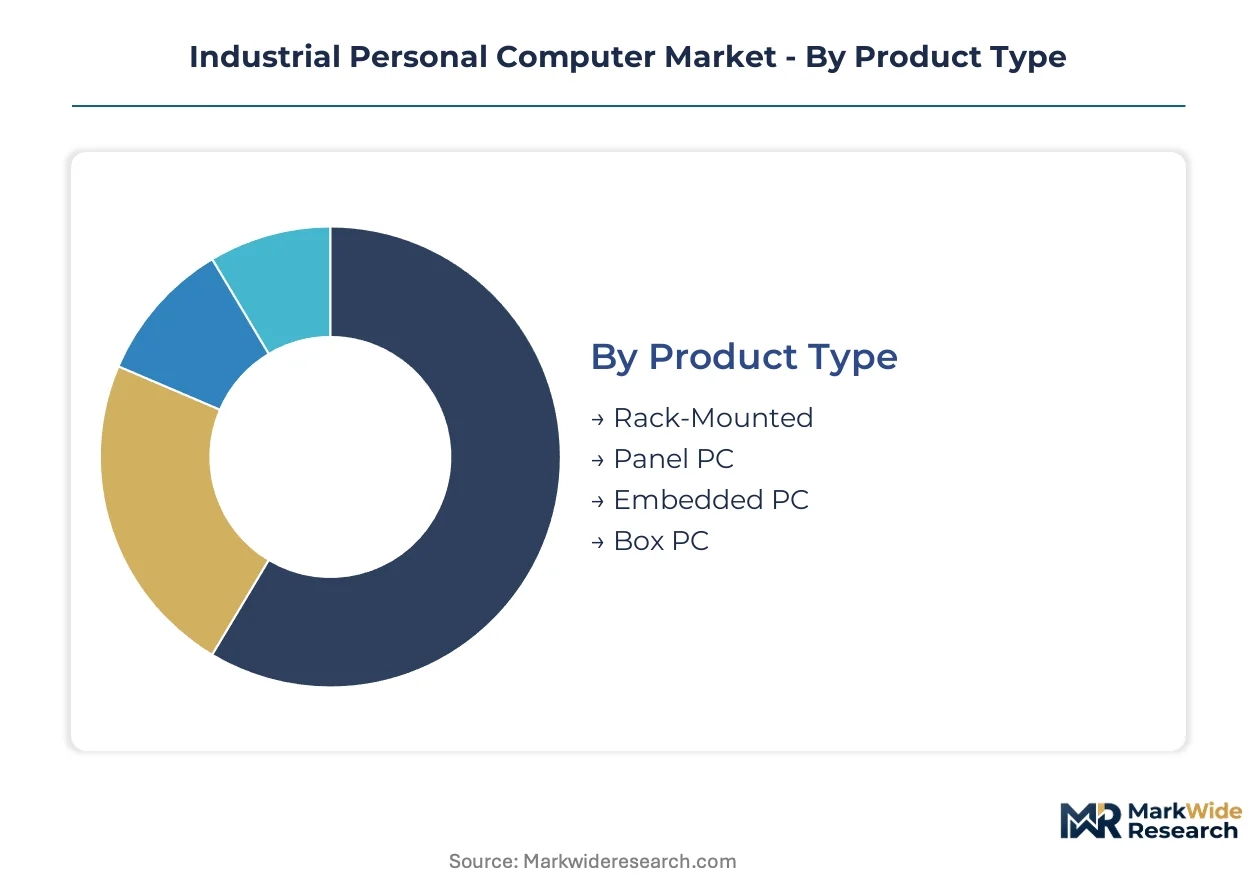
Industrial PC segmentation reveals how ruggedized computing platforms fragment across form factors, processing architectures, and deployment environments. Specification diversity forces vendors to maintain parallel product lines optimized for cabinet-mounted servers, operator-facing interfaces, and machine-integrated controllers.
Product Type:
Form factor specifications dictate thermal envelope, mounting flexibility, and I/O density across factory floor deployments.
- Panel PC:Integrated display-processor units in sealed housings dominate operator interface roles. German automotive stamping plants specify these for HMI stations where washdown resistance and touchscreen durability matter most.
- Embedded PC:Compact deterministic controllers with fixed I/O configurations occupy legacy retrofit environments. Taiwan semiconductor fabs deploy these where space constraints and real-time fieldbus compatibility constrain architecture choices.
- Rack-Mounted:Standardized 19-inch enclosures aggregate compute for centralized control rooms in energy substations.
- Box PC:Flexible mounting options suit machine-mounted edge deployments requiring DIN-rail or wall attachment.
Panel PC leads on scale; Edge Computing leads on momentum.
Technology:
Processing capability tiers separate connectivity-enabled platforms from inference-capable systems commanding specification premiums.
- Edge Computing:Decentralized processing architectures eliminate network latency for closed-loop quality control. South Korean battery gigafactories deploy cabinet-free units directly on production lines to sustain real-time defect detection without cloud dependency.
- AI Processing:On-device inference chip integration enables autonomous visual inspection and predictive maintenance algorithms. Japanese precision equipment makers pilot outcome-based pricing tied to uptime guarantees rather than hardware capital expenditure.
- IoT Connectivity:Wireless and cellular modules extend IPC reach to remote asset monitoring in transportation depots.
- Virtualization:Hypervisor-enabled platforms consolidate multiple control workloads onto shared hardware in brownfield automation upgrades.
Edge Computing leads on scale; AI Processing climbs the fastest.
End User:
Industry verticals impose divergent environmental tolerances, certification requirements, and procurement authority structures.
- Manufacturing:Discrete and process automation consumes the majority of panel PC and embedded controller shipments. Germany's automotive corridor drives hardened IPC specifications for smart factory retrofits requiring CE marking compliance under ECHA substance restrictions.
- Energy:Substations and renewable generation sites demand extended temperature ranges and electromagnetic immunity validation. Middle Eastern infrastructure projects encounter passive thermal design limitations in high-ambient deployments.
- Transportation:Rolling stock and depot applications prioritize shock resistance and wide-input power tolerance.
- Retail:Self-service kiosks and inventory systems require consumer-grade aesthetics with industrial reliability.
Manufacturing leads on scale; Energy leads on specification intensity.
Application:
Functional use cases determine software stack requirements, deterministic response needs, and integration complexity with legacy control systems.
- Automation:PLC replacement and motion control applications demand deterministic cycle times and fieldbus compatibility. European precision machinery sectors extend sales cycles through legacy protocol integration requirements that inflate non-recurring engineering costs.
- HMI:Operator interface deployments prioritize display brightness, glove-enabled touch response, and sealed ingress protection ratings.
- Machine Control:Direct equipment command requires hard real-time operating systems and isolated safety I/O channels.
- Data Acquisition:Sensor aggregation and protocol translation workloads emphasize multi-channel analog input and edge preprocessing capabilities.
Automation leads on scale; HMI leads on deployment velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive manufacturing corridor demands hardened IPC architectures for smart factory retrofits, while Taiwan's semiconductor fabrication expansion drives shock-resistant computing procurement at scale. National regulatory frameworks and industrial cluster concentrations reshape deployment patterns across major manufacturing economies.
United States
Medical device manufacturing and critical infrastructure control rooms sustain demand for FCC-validated electromagnetic compatibility. FDA safety validation requirements extend qualification timelines for North American deployments. Texas energy infrastructure projects encounter passive thermal design limitations in high-ambient deployments requiring cabinet-free edge architectures.
Germany
Automotive stamping plants deploy edge-native IPC form factors at line speed to eliminate network latency in defect detection. CE marking directives under ECHA substance restrictions force material composition disclosures through multi-tier supplier networks. Bavaria's precision machinery sectors extend sales cycles through legacy fieldbus compatibility requirements.
Taiwan
Semiconductor fabrication facilities scale process automation investments requiring shock-resistant computing for cleanroom environments. The country's national industrial regulator mandates hardware-level security attestations for connected devices. Hsinchu Science Park anchors concentrated procurement of embedded PC architectures where space constraints dominate specification sheets.
South Korea
Battery gigafactories deploy cabinet-free edge units directly on production lines for real-time defect detection without cloud dependency. MFDS-aligned safety validation protocols apply to medical-grade IPC deployments. Gyeonggi Province manufacturing clusters specify deterministic I/O configurations for brownfield automation upgrades.
India
PLI scheme subsidies for electronics production attract IPC assembly investments to serve domestic automation demand. BIS certification requirements reshape product design cycles for vendors seeking Indian market access. Maharashtra and Gujarat industrial corridors concentrate specification demand for panel PC configurations in operator interface roles.
Industrial Personal Computer Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertical integration depth determining margin capture in premium tiers. The vendor base clusters around three strategic archetypes: diversified automation conglomerates with captive software ecosystems, embedded computing pure-plays with regional manufacturing footprints, and PC-based control specialists with deterministic real-time expertise. Capacity expansion into India and Vietnam accompanies strategic partnerships for AI accelerator integration. Portfolio diversification toward software-defined maintenance subscriptions displaces transactional hardware sales.
Within the diversified automation tier, Siemens AG exemplifies vertical integration into proprietary control ecosystems. Advantech Co., Ltd. anchors the embedded computing pure-play archetype with Asia-Pacific manufacturing presence. Beckhoff Automation occupies the PC-based control specialist position in European precision machinery sectors. These three represent divergent strategic postures: ecosystem lock-in through software stacks, geographic manufacturing scale, and real-time architecture differentiation respectively.
| Leading Market Players |
|---|
| Advantech Co., Ltd. |
| Beckhoff Automation |
| Siemens AG |
| Kontron |
| IEI Integration Corporation |
| Avalue Technology |
| DFI |
| B&R Automation |
| American Portwell Technology |
| Others |
Pricing and Supply Chain Analysis
Industrial-grade semiconductor wafer costs flow from concentrated East Asian foundries through three pricing tiers downstream, with CE-marked security-certified units commanding premiums over legacy replacements while commodity panel PCs face compression from Indian assembly entrants.
Pricing Analysis
Capacity additions in India under PLI electronics subsidies are reshaping price floors for standard panel PC configurations. Three-tier pricing structure across premium security-certified, standard industrial-grade, and economy commercial-extended tiers separates buyers by validation requirements and after-sales bundling. Price erosion runs through the economy tier as domestic Indian assembly displaces imported units. Automotive OEMs in Germany exhibit lowest price sensitivity due to downtime cost exposure, while Southeast Asian contract manufacturers prioritize unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for industrial-grade x86 processors and FPGA components. Raw material dependencies span high-reliability capacitors from Japan, shock-resistant enclosure alloys from China, and specialized thermal interface materials from Germany. Tariff exposure on Chinese-sourced sheet metal and power supply units is amplifying landed cost variance. Distribution runs through authorized industrial automation distributors with field application engineering support, bypassing commodity electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial PC market reads as a late-cycle quality story where EU Cyber Resilience Act mandates are accelerating replacement demand toward hardware-certified premium tiers over uncertified legacy alternatives.
For Market Incumbents: Deepen captive software ecosystem integration to raise switching costs against modular competitors. Expand embedded security attestation capabilities ahead of divergent national certification timelines. Prioritize backward integration into thermal management subsystems to defend margins against component volatility. For New Entrants and Emerging Players: India's PLI scheme subsidies open a window for domestic assembly plays targeting price-sensitive panel PC demand in Maharashtra and Gujarat industrial corridors. Target brownfield automation retrofits in European precision machinery where legacy fieldbus integration requirements extend incumbent sales cycles. Lead with subscription-based maintenance contracts to bypass capital expenditure procurement friction. For Investors and Strategic Acquirers: Consolidation pressure builds where cybersecurity skill scarcity concentrates at semiconductor vendors rather than IPC integrators. Position for 5-10 year holding periods around vendors with deterministic real-time architecture differentiation. Watch for divergence in national cybersecurity certification timelines as an inflection signal for supplier qualification cost barriers.| Strategic Initiative | Industry Significance |
|---|---|
| AI Accelerator Integration | On-device inference chips enable real-time quality inspection premiums in South Korean battery gigafactories. |
| Software-Defined Maintenance Launch | Subscription contracts displace transactional sales and capture recurring revenue from Asia-Pacific manufacturing clients. |
| CE Marking Pre-Certification Investment | Hardware-level security attestations accelerate EU market access under Cyber Resilience Act mandates. |
| India Manufacturing Footprint Expansion | PLI scheme subsidies attract assembly investments serving domestic automation demand in Gujarat corridors. |
| Legacy Fieldbus Compatibility Development | Deterministic protocol support sustains premium positioning in European precision machinery retrofit cycles. |
Research Methodology
Multiple input streams — plant engineer interviews, OEM procurement surveys, regulatory filing analysis, and distributor channel audits — were reconciled to construct segment-level demand estimates. Primary fieldwork engaged automation system integrators, factory IT directors, and industrial hardware procurement teams across German automotive, Taiwanese semiconductor, and South Korean battery manufacturing clusters. Secondary validation drew from FCC equipment authorization databases, ECHA substance restriction disclosures, BIS certification registries, and customs trade flow records. Bottom-up unit demand modeling was cross-checked against top-down industrial automation capex trajectories.
Data-stream reconciliation across product type, processing technology, end-use vertical, and application function dimensions structured the analytical framework throughout the projection horizon. CAGRs were derived from segment-level growth rate synthesis rather than single-point extrapolation. Forecast inputs incorporated EU Cyber Resilience Act implementation phasing, India PLI scheme subsidy allocation timing, and semiconductor fabrication capacity expansion schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under geopolitical disruption to East Asian component supply and divergent national cybersecurity certification timeline synchronization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Linseed Oil Market
Others
Global Sports and Fitness Wears Market
Others
Global Laser Defense Eyewear Market
Others
Pollen Allergy Market
Others
Augmented Reality (AR) in Manufacturing Market
Others
Shear Testing Equipment Market
Others
Animal Feed Alternative Protein Market
Others
Bitcoin Mining Hardware Market
Others
Latin America 3D Printing Construction Market
Others
Cloud Digital Video Recorder Market
Others
Agitation System Market
Others
Traditional PC Market
Others
Process Spectroscopy Market
Others
Powder Coating Equipment Market
Others
Europe Intercom Devices Market
Others
High-End Servers Market