
 Aerospace and Defense Fiber Optic Cables Market | 2026-2036
Aerospace and Defense Fiber Optic Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace and Defense Fiber Optic Cables Market Insights
Defense project finance through long-term military leasing arrangements is rewriting capital deployment across the supplier base. Corning Incorporated leverages its fused silica core manufacturing scale to anchor US domestic supply security for strategic platforms. TE Connectivity sustains qualification breadth across MIL-DTL-38999 connectorized assemblies, while Amphenol Corporation dominates military-aerospace distribution channels through its integrated interconnect portfolio.
Aerospace and defense fiber optic cables are silica-based waveguides engineered to transmit optical signals across extreme temperature ranges, mechanical stress, and electromagnetic interference environments, typically employing fluoropolymer or polyimide coatings rated for temperatures exceeding 200°C. These assemblies serve as the physical layer for fly-by-light flight controls, tactical data links, and distributed aperture sensor networks in modern weapon systems. Single-mode fiber occupies the highest value tier in satellite and long-haul avionics backbones where attenuation below 0.5 dB/km is mandatory. Multi-mode fiber competes aggressively in cabin and vehicle-area networks where cost-per-channel economics favor larger core diameters. Specialty fiber, including radiation-hardened and hermetic variants, captures concentrated margin pools in nuclear survivable and space-rated applications.
FAA airworthiness directives and DoD MIL-PRF-49291 cable specifications jointly determine qualification pathways for civil-military dual-use suppliers. EASA CS-25 certification requirements for transport aircraft optical interconnects create parallel compliance obligations for European OEM supply chains. NIST traceable measurement standards for optical time-domain reflectometry ensure interoperability across NATO member procurement systems. Stakeholders must monitor shifts in export control classification for specialty fiber technologies as geopolitical alignment reshapes cross-border component flows.
Market Dynamics
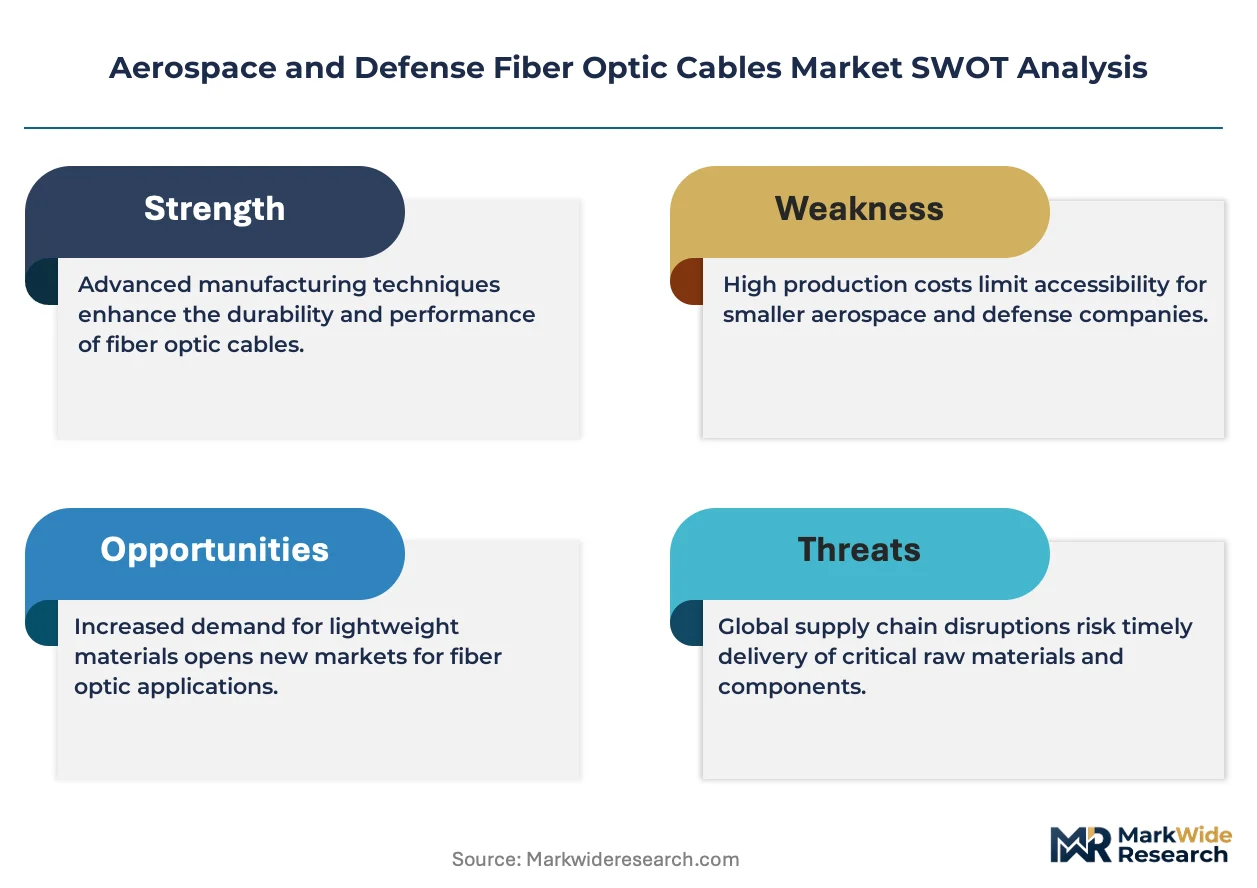
US Department of Defense MIL-STD-810H environmental testing requirements are tightening qualification thresholds for battlefield-deployable cables, compressing supplier margins while accelerating consolidation among qualified manufacturers.
Growth Catalysts
- Avionics Modernization Mandates:Military platforms are replacing copper interconnects with fiber optic backbones to reduce electromagnetic interference and weight. Pentagon sustainment budgets are directing procurement toward fly-by-light flight control architectures.
- MIL-PRF-49291 Cable Specifications:The Department of Defense's performance specification for tactical fiber optic cables is creating standardized demand pools. Dual-use suppliers are qualifying products for both civil and military applications under unified testing protocols.
- Silica Core Manufacturing Scale:Domestic fused silica production capacity in the United States is anchoring supply security for strategic platforms. Advanced drawing towers and preform fabrication are concentrating in defense-critical manufacturing corridors.
Market Restraints
- Fluoropolymer Coating Cost Volatility:Perfluoroalkoxy alkane and ethylene tetrafluoroethylene resin prices fluctuate with petrochemical feedstock markets. Cable manufacturers face margin compression when specialty polymer costs spike without contractual pass-through mechanisms.
- Single-Source Preform Supply:Optical fiber preform production concentrates among a handful of specialized chemical vapor deposition facilities. Geographic concentration of this upstream input creates vulnerability in defense supply chains subject to disruption.
- Radiation-Hardening Technical Limits:Specialty fibers for nuclear-survivable applications require doping profiles that degrade optical performance. The trade-off between radiation resistance and signal attenuation constrains design flexibility for extreme-environment deployments.
Strategic Opportunities
- Space-Rated Hermetic Fiber:Satellite constellation deployments are opening demand for hermetically sealed cables resisting outgassing and thermal cycling. Low-earth orbit commercialization is outpacing legacy geostationary qualification timelines.
- Multi-Mode Fiber in Vehicle-Area Networks:Cost-per-channel economics favor larger core diameters for tactical ground vehicle internal communications. Armored fighting vehicle digitization programs are specifying ruggedized multi-mode assemblies for intra-platform data distribution.
- NATO Interoperability Standards:NIST traceable measurement protocols for optical time-domain reflectometry are harmonizing procurement across allied defense ministries. Standardized testing is reducing qualification duplication for multinational platform programs.
Industry Challenges
- Skilled Fiber Splicing Technician Scarcity:Precision fusion splicing for military-grade assemblies requires certification levels exceeding commercial telecommunications standards. Defense contractors compete with data center builders for experienced optical interconnect technicians.
- MIL-DTL-38999 Connector Qualification Timelines:Environmental and mechanical testing cycles for circular connectorized assemblies extend 18-24 months. Platform development schedules compress as cable qualification bottlenecks accumulate.
- Legacy Copper Infrastructure Integration:Hybrid architectures bridging fiber optic backbones with existing copper sensor networks introduce signal conversion complexity. Interface electronics add failure points and thermal loads that pure-fiber designs eliminate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace and Defense Fiber Optic Cables Market |
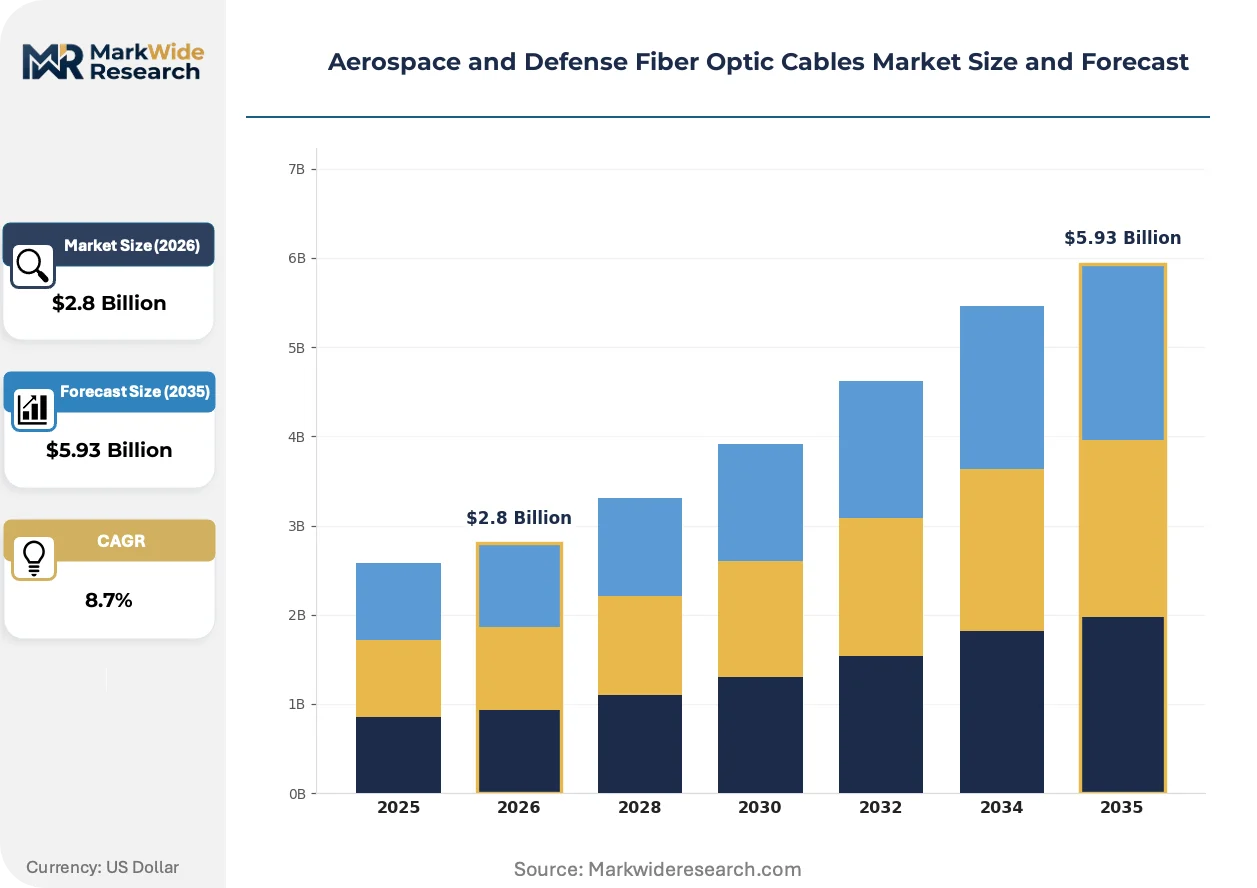
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-mode, Multi-mode, Specialty, Armored Application: Communication Systems, Data Transmission, Sensors, Avionics End User: Defense Contractors, Aerospace OEMs, Military, Research Institutions Installation Type: Fixed Installation, Portable Systems, Underwater, Aerospace |
| Companies Covered | Amphenol Corporation, RTX Corporation, Corning Incorporated, Prysmian Group, TE Connectivity, Carlisle Interconnect Technologies, W.L. Gore & Associates, Inc., Radiall, OFS Fitel, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace and Defense Fiber Optic Cables Market Trends and Innovations
Photonics integration is collapsing discrete component boundaries, while regulatory harmonization and procurement model evolution are reshaping how defense-grade fiber assemblies reach end-use platforms.
Polyimide-coated single-mode fiber is migrating from satellite payload interconnects toward tactical avionics backplanes. Prime contractors are adopting space-qualified coating chemistries for fighter aircraft sensor networks where temperature excursions exceed 300°C. This convergence is compressing the traditional segmentation between orbital and atmospheric fiber specifications.
EASA CS-25 certification requirements for transport aircraft optical interconnects are tightening flame-smoke-toxicity standards for cabin-deployed cables. European OEM supply chains are reformulating jacket compounds to meet combined FAA-EASA dual-qualification thresholds. Civil-military dual-use suppliers are consolidating testing programs to capture both defense and commercial aerospace procurement pools.
Defense agencies are consolidating cable procurement through long-term military leasing arrangements rather than discrete platform-specific buys. Prime contractors are absorbing inventory risk and qualification costs in exchange for multi-year volume commitments. The United States leads this structural shift, with sustainment budgets now favoring availability-based contracting over transactional spare part purchasing.
Aerospace and Defense Fiber Optic Cables Market Segmentation
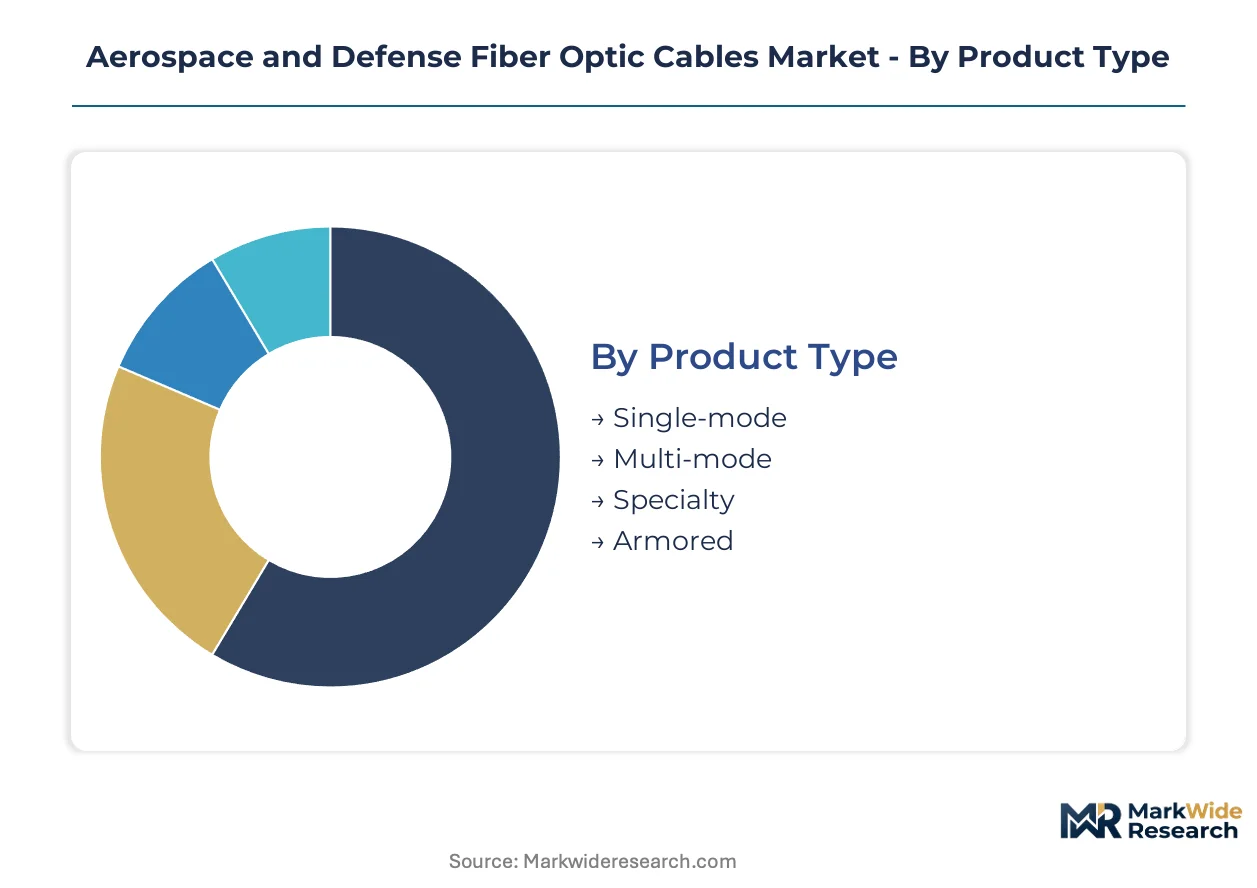
Segmentation in aerospace and defense fiber optic cables reflects divergent technical specifications, qualification burdens, and aftermarket service obligations. Each category carries distinct margin profiles and supplier certification requirements that reshape competitive positioning across the value chain.
Product Type:
After-sales service intensity varies sharply across fiber types, with specialty and armored variants demanding field-level repair protocols and periodic recertification that single-mode and multi-mode products rarely require.
- Single-mode:Silica-based waveguides with core diameters near 9 microns deliver attenuation below 0.5 dB/km for satellite and long-haul avionics backbones. Pentagon next-generation platform development concentrates procurement in the United States where fused silica manufacturing corridors anchor strategic supply security.
- Multi-mode:Larger core diameters of 50-62.5 microns prioritize cost-per-channel economics over distance performance. Tactical ground vehicle digitization programs specify ruggedized multi-mode assemblies for intra-platform data distribution where channel density outweighs spectral efficiency.
- Specialty:Radiation-hardened and hermetic variants serve nuclear-survivable and space-rated applications requiring doping profiles that trade optical performance for environmental resilience.
- Armored:Reinforced cable assemblies with metallic or composite protective layers withstand crush, rodent, and ballistic threats in battlefield-deployed configurations.
By volume, Multi-mode leads. By growth pace, Specialty is ahead.
Application:
Application-driven cost tiers separate high-reliability avionics interconnects from commoditized cabin networking, with qualification depth determining pricing power and supplier stickiness.
- Communication Systems:Tactical data links and secure voice networks employ military-grade fiber for electromagnetic interference immunity in contested spectrum environments. NATO interoperability standards harmonize procurement across allied defense ministries.
- Data Transmission:High-bandwidth backbones for intelligence, surveillance, and reconnaissance platforms demand low-latency optical paths. Fly-by-light flight control architectures in Pentagon sustainment programs accelerate replacement of copper interconnects.
- Sensors:Distributed aperture networks and structural health monitoring systems integrate fiber Bragg gratings and interferometric sensing elements.
- Avionics:Flight-critical computing and navigation interfaces require flame-smoke-toxicity compliance under combined FAA-EASA dual-qualification thresholds.
Avionics commands premium pricing. Data Transmission shows the steepest expansion trajectory.
End User:
Customer type dictates contracting structure, with defense agencies shifting toward availability-based models while aerospace OEMs retain transactional procurement patterns.
- Defense Contractors:Prime systems integrators absorb inventory risk and qualification costs under long-term military leasing arrangements. The United States leads this structural shift with sustainment budgets favoring multi-year volume commitments over discrete platform-specific buys.
- Aerospace OEMs:Commercial and military aircraft manufacturers specify optical interconnects under EASA CS-25 and FAA airworthiness directives. Dual-use suppliers consolidate testing programs to capture both defense and commercial aerospace procurement pools.
- Military:End-user organizations within the Department of Defense enforce MIL-PRF-49291 cable specifications and MIL-STD-810H environmental testing requirements.
- Research Institutions:National laboratories and defense research facilities prototype next-generation photonic systems ahead of operational deployment.
Defense Contractors dominate current revenue. Research Institutions are climbing the fastest as experimental programs transition toward procurement.
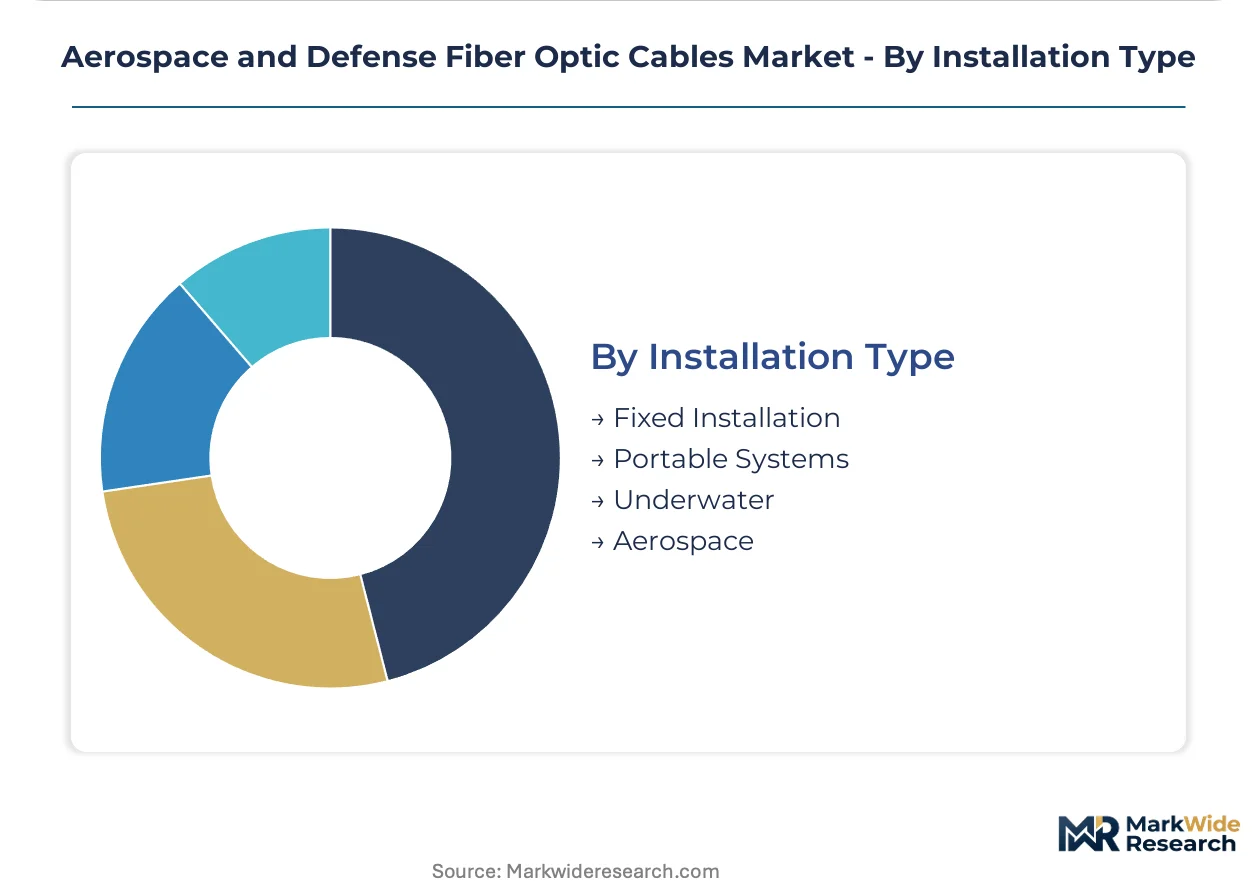
Installation Type:
Installation environment determines supply chain configuration, with underwater and aerospace deployments requiring hermetic sealing and pressure-rated assemblies that fixed installations rarely demand.
- Fixed Installation:Permanent backbone infrastructure within ground stations, command centers, and aircraft carriers employs standard ruggedized assemblies. NIST traceable measurement standards for optical time-domain reflectometry ensure interoperability.
- Portable Systems:Rapidly deployable tactical communications kits require lightweight, coiled cable configurations with quick-disconnect MIL-DTL-38999 connectors.
- Underwater:Submarine and unmanned underwater vehicle applications demand pressure-compensated and hermetically sealed cables resisting seawater ingress.
- Aerospace:Satellite and launch vehicle installations specify polyimide-coated fibers rated for temperature excursions exceeding 300°C and atomic oxygen exposure in low-earth orbit.
Fixed Installation holds the largest installed base. Aerospace is gaining share fastest as satellite constellation deployments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pentagon sustainment budgets and next-generation platform development anchor procurement concentration in the United States, while allied defense ministries accelerate optical interconnect adoption under NATO standardization protocols. Domestic fused silica manufacturing corridors in the US and specialized coating facilities in Western Europe create geographic supply anchors. Satellite constellation deployments and tactical vehicle digitization programs distribute demand across defense-critical industrial clusters.
United States
The Department of Defense drives procurement through MIL-PRF-49291 cable specifications and MIL-STD-810H environmental testing mandates. FAA airworthiness directives for civil-military dual-use suppliers create parallel compliance pathways. Defense-critical manufacturing corridors in Arizona and Massachusetts concentrate advanced drawing towers and preform fabrication for strategic platform supply security.
France
Dassault Aviation and Thales anchor demand for fly-by-light flight control architectures in next-generation combat aircraft programs. EASA CS-25 certification requirements for transport aircraft optical interconnects tighten flame-smoke-toxicity standards. The Île-de-France aerospace cluster around Paris hosts specialized qualification laboratories serving pan-European OEM supply chains.
Germany
Rheinmetall and Krauss-Maffei Wegmann specify ruggedized multi-mode assemblies for armored fighting vehicle digitization programs. The country's national defense procurement office enforces strict electromagnetic interference immunity standards for tactical data links. Bavaria's precision manufacturing corridor concentrates MIL-DTL-38999 connector qualification facilities.
United Kingdom
BAE Systems and Rolls-Royce drive avionics modernization with fiber optic backbone replacements for copper interconnects. The Ministry of Defence's procurement standards align with NATO interoperability protocols for optical time-domain reflectometry. The South West England aerospace cluster around Bristol hosts satellite-rated hermetic fiber development programs.
Israel
Elbit Systems and Rafael Advanced Defense Systems pioneer distributed aperture sensor networks requiring radiation-hardened specialty fibers. The country's national defense research organization funds experimental photonic systems ahead of operational deployment. Tel Aviv's defense technology corridor concentrates rapid prototyping capabilities for battlefield-deployable cable configurations.
Aerospace and Defense Fiber Optic Cables Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered supplier base where qualification breadth determines market access. Three archetypes dominate: fused silica core manufacturers with captive preform supply, connectorized assembly specialists holding MIL-DTL-38999 qualification portfolios, and integrated interconnect distributors capturing prime contractor procurement relationships. Consolidation accelerates through strategic partnerships between cable fabricators and connector houses, while geographic expansion targets defense-critical manufacturing corridors.
Among US-based integrated interconnect specialists, Amphenol Corporation and TE Connectivity occupy positions spanning distribution channel control and qualification breadth. Corning Incorporated anchors the upstream materials tier with fused silica manufacturing scale. These three exemplify the vertical capability stacking required for Pentagon sustainment program participation, where domestic supply security mandates intersect with multi-year availability-based contracting structures.
| Leading Market Players |
|---|
| Amphenol Corporation |
| RTX Corporation |
| Corning Incorporated |
| Prysmian Group |
| TE Connectivity |
| Carlisle Interconnect Technologies |
| W.L. Gore & Associates, Inc. |
| Radiall |
| OFS Fitel, LLC |
| Others |
Pricing and Supply Chain Analysis
Single-source preform dependency in the United States and Japan determines both pricing tier spreads and supply chain shape across the aerospace and defense fiber optic cables market. Fluoropolymer coating volatility and MIL-DTL-38999 connector qualification timelines compress margins at the standard tier while concentrating premium pricing power among qualified manufacturers with captive fused silica supply.
Pricing Analysis
MIL-PRF-49291 certification level creates the primary spread between premium radiation-hardened assemblies and standard multi-mode products. Three-tier pricing structure across space-qualified hermetic, tactical-grade armored, and commercial-off-the-shelf variants reflects qualification depth and field-repair service bundling. Cost compression in standard multi-mode runs through fluoropolymer resin price spikes without contractual pass-through mechanisms. Defense contractors show lowest price sensitivity due to sustainment budget availability, while research institutions exhibit highest sensitivity as experimental programs compete for limited funding.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for specialty coating chemistries and connector subcomponents. Advanced drawing towers and preform fabrication concentrate in the United States, Japan, and Germany, drawing from high-purity silicon tetrachloride and germanium tetrachloride feedstocks. Single-source vulnerability in chemical vapor deposition facilities creates chokepoints for radiation-hardened fiber production. Distribution runs through prime contractor procurement offices and defense-critical manufacturing corridors anchored by Pentagon sustainment programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through MIL-STD-810H and MIL-PRF-49291 qualification timelines creates structural barriers that protect incumbent positions against displacement.
For Market Incumbents: Insulate qualification breadth through backward integration into optical fiber preform production and accelerated MIL-DTL-38999 connector certification cycles. The threat of emerging photonics integration specialists collapsing discrete component boundaries demands defensive patent filing in fly-by-light architectures. Capacity addition in Arizona and Massachusetts defense-critical manufacturing corridors reinforces domestic supply security mandates. For New Entrants and Emerging Players: NATO interoperability standardization programs for optical time-domain reflectometry represent the most penetrable entry point for qualification-light subsystem suppliers. Rapid prototyping capabilities for battlefield-deployable portable systems in allied European defense ministries offer secondary white-space access. A go-to-market angle anchored on NIST-traceable measurement protocol compliance reduces duplication costs for multinational platform participation. For Investors and Strategic Acquirers: EASA CS-25 and FAA dual-qualification harmonization reshapes the acquisition landscape toward civil-military dual-use suppliers with consolidated testing programs. Long-term viability rests on availability-based contracting structures displacing transactional spare part purchasing across Pentagon sustainment budgets. The signal to watch is satellite constellation deployment acceleration outpacing legacy geostationary qualification timelines for hermetic fiber demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| MIL-DTL-38999 Connector Qualification Acceleration | Reduces 18-24 month testing bottlenecks for circular connectorized assemblies in fighter aircraft programs. |
| Backward Integration into Fused Silica Preform Production | Anchors domestic supply security for strategic platforms under Pentagon sustainment budget mandates. |
| Dual-Use Civil-Military Qualification Consolidation | Captures both FAA-EASA commercial aerospace and defense procurement pools through unified testing protocols. |
| Space-Rated Hermetic Fiber Development | Addresses low-earth orbit commercialization outpacing legacy geostationary satellite qualification timelines. |
| NATO Interoperability Standard Adoption | Harmonizes optical time-domain reflectometry procurement across allied defense ministries reducing duplication. |
Research Methodology
A spread of perspectives from prime contractor procurement officers, fiber splicing technician certification bodies, defense research laboratory directors, and fluoropolymer coating compounders converged on the working assumptions. Primary interviews with MIL-DTL-38999 qualification facility managers and secondary validation against FAA airworthiness directive filings, DoD MIL-PRF-49291 specification updates, and NIST measurement standard publications grounded the analysis. Bottom-up channel checks across Arizona and Massachusetts defense-critical manufacturing corridors triangulated with top-down Pentagon sustainment budget allocation patterns.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation by single-mode, multi-mode, specialty, and armored variants alongside application splits in avionics, data transmission, sensors, and communication systems. Installation environment distinctions between fixed, portable, underwater, and aerospace deployments provided a third analytical dimension. CAGRs were derived from platform-specific procurement schedules and satellite constellation deployment trajectories without year-specific anchoring.
Stress conditions across fluoropolymer feedstock price volatility, single-source preform supply disruption, and radiation-hardening technical performance trade-offs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about Pentagon sustainment budget continuity and NATO standardization protocol adoption that geopolitical realignment could revise. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Europe Indoor Air Purification Market
Others
Smart Home Platforms Market
Others
Automatic Barriers and Bollards Market
Others
Global Bio-Based Chemicals Market
Others
5G Tester Market
Others
Workstation Desktops Market
Others
Metal Ore Mining Market
Others
Transportation Lighting Market
Others
Storage Dewars Market
Others
Deflectometer Market
Others
Solar Animal Repellent Market
Others
Insoluble Sulfur Market
Others
Synthetic Leather Market
Others
Workbench Tanks Market
Others
Mobile Retina Services Market
Others
Smart Home Service Market