
 Rotary Union Market | 2026-2036
Rotary Union Market Size, Share, and Industry Trends Forecast 2026-2036
Rotary Union Market Analytics
Single-source to multi-source procurement is repositioning how OEMs contract rotary union suppliers across capital-intensive industries. Moog Inc leverages its aerospace pedigree to dominate flight-critical sealing applications. Deublin Company anchors its position through backward integration into precision machining centers in North America. Kadant Inc competes on pulp and paper process knowledge, sustaining mill service contracts that resist commoditization.
A rotary union is a mechanical device that transfers pressurized fluid or electrical power from a stationary source to a rotating component, typically incorporating carbon-graphite or silicon carbide seal faces rated for pressures exceeding 10,000 psi and rotational speeds above 10,000 rpm. Its primary purpose is to enable continuous operation of rotating machinery without hose wrap or interrupted flow in applications ranging from steel rolling mills to CT scanner gantries. Hydraulic rotary unions command the largest product type share due to their ubiquity in heavy machinery, though dual media configurations are gaining traction as machine builders consolidate fluid and electrical rotary interfaces into single housings. Within applications, industrial machinery absorbs the highest absolute volume, while aerospace represents the fastest-growing margin pool as OEMs qualify lighter titanium-alloy variants for next-generation platforms.
ISO 9001 quality management and REACH chemical compliance shape baseline market access for European suppliers, while the EU F-Gas Regulation directly constrains seal elastomer formulations. In the United States, OSHA machine guarding standards influence rotary union guarding and proximity sensor integration on installed equipment. Stakeholders must monitor how evolving PFAS restrictions on both sides of the Atlantic reshape seal material supply chains and qualification timelines for replacement components.
Market Dynamics
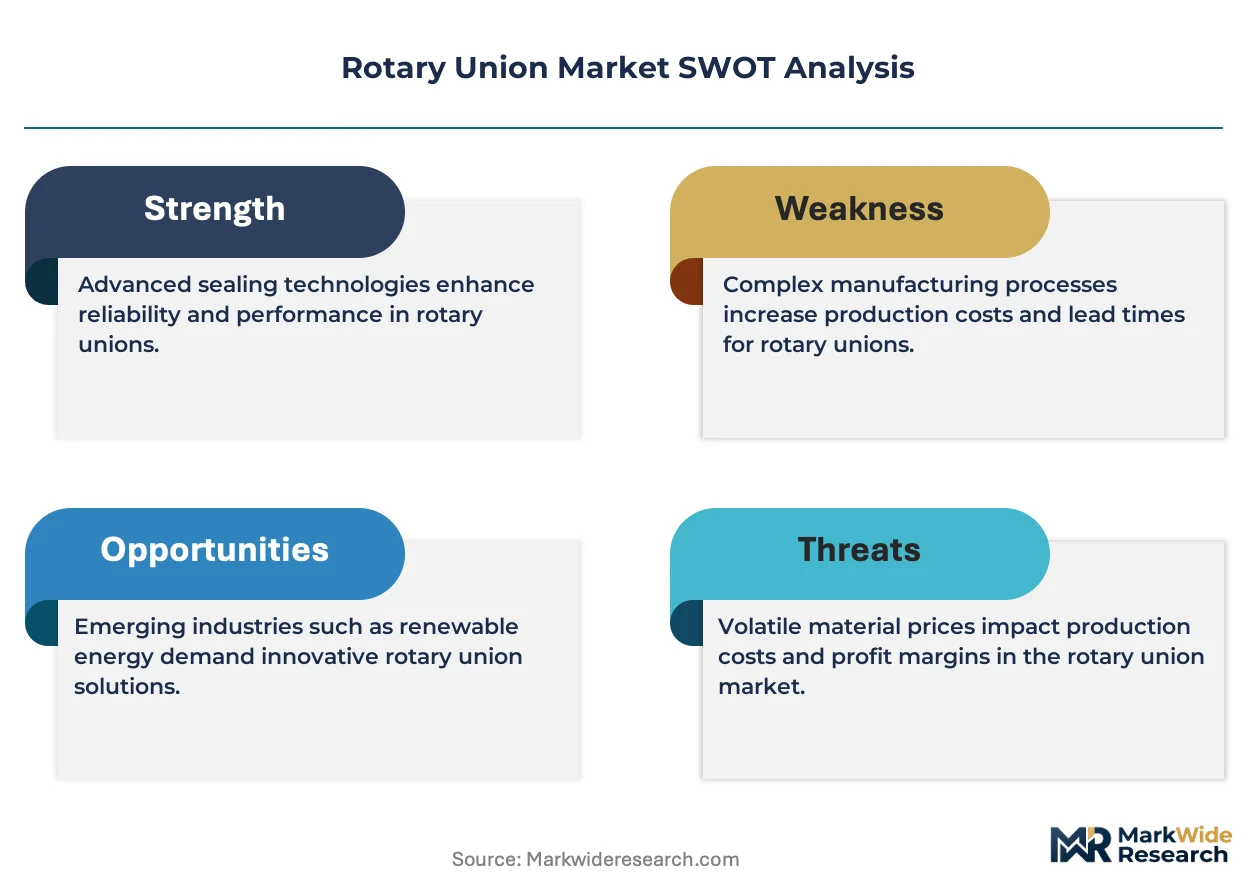
The EU F-Gas Regulation is compressing seal material supply chains, forcing rotary union manufacturers to reformulate elastomers and requalify components under accelerated timelines. This regulatory pressure intersects with automotive electrification, where battery thermal management systems now specify dual-media rotary interfaces that combine coolant and electrical slip rings in single housings.
Growth Catalysts
- EV Battery Manufacturing:Gigafactory expansion across Germany and Hungary is pulling precision rotary unions into thermal management modules for electrode coating and cell formation lines.
- REACH Chemical Compliance:European machinery OEMs now mandate PFAS-free seal documentation, creating competitive differentiation for suppliers with qualified fluoropolymer alternatives.
- Aerospace Lightweighting:Titanium-alloy rotary union variants are displacing steel configurations in next-generation aircraft platforms, opening margin pools in flight-critical sealing.
Market Restraints
- Seal Material Volatility:Fluoropolymer feedstock prices fluctuate with rare earth processing constraints in Chinese supply chains, compressing gross margins for European manufacturers.
- Precision Machining Concentration:Stuttgart and Munich machining clusters control critical housing tolerances, creating geographic single-source risk for non-German OEMs.
- Electrical Slip Ring Substitution:Wireless power transfer systems are encroaching on low-pressure rotary union applications in packaging and printing machinery.
Strategic Opportunities
- India Manufacturing Uptake:PLI scheme incentives for automotive and textile machinery are creating first-mover advantage for rotary union suppliers establishing local assembly.
- Dual-Media Convergence:Integration of hydraulic fluid and fiber-optic signal channels into unified housings is opening specification wins in semiconductor wafer handling equipment.
- OSHA Machine Guarding:Updated proximity sensor mandates in the United States are creating retrofit demand for guarded rotary union configurations on installed metalworking equipment.
Industry Challenges
- PFAS Qualification Timelines:Replacement seal materials require 18-24 month validation cycles under ISO 9001 protocols, delaying revenue recognition on re-engineered product lines.
- Multi-Axis Integration Complexity:Five-axis CNC workholding systems demand rotary unions with simultaneous coolant, air, and electrical feeds, stretching engineering resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotary Union Market |
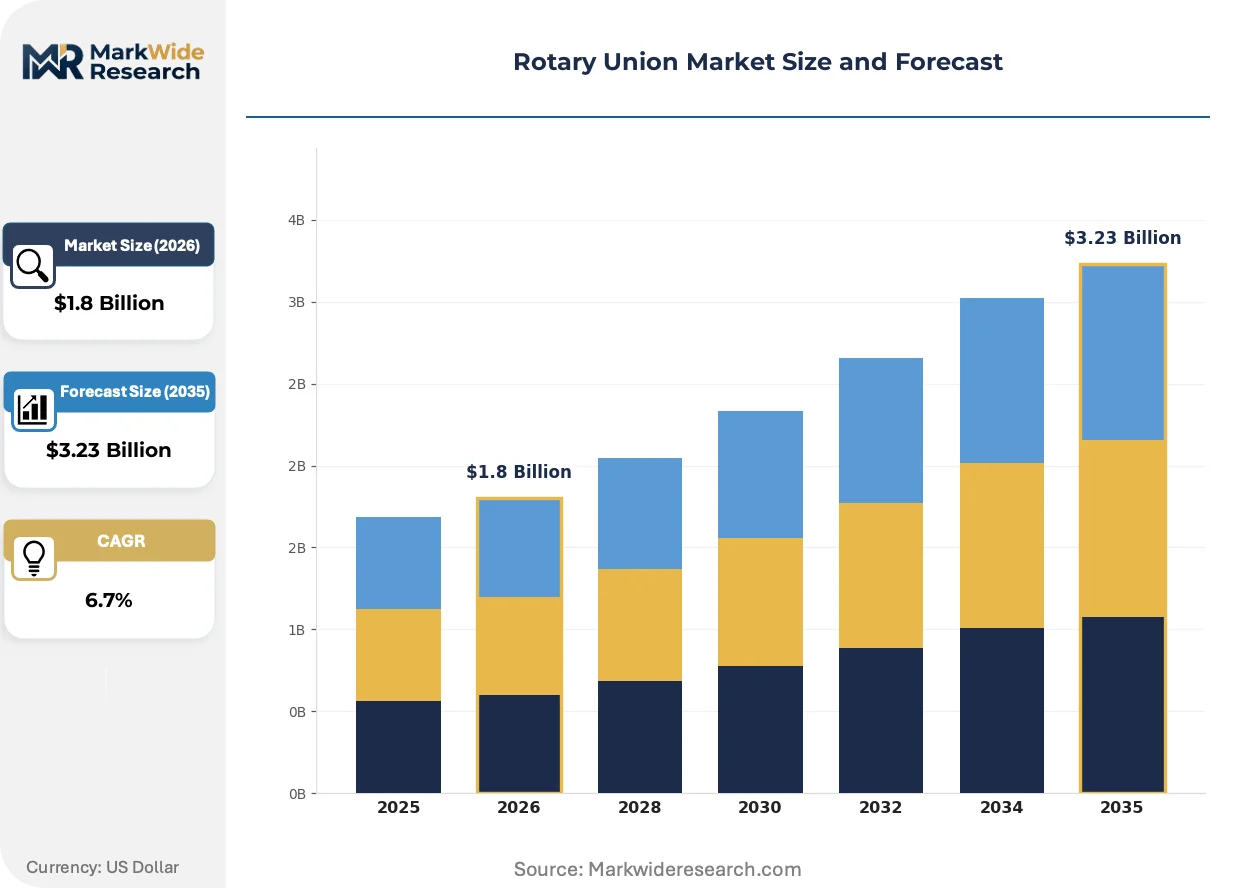
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic, Pneumatic, Electrical, Dual Media Application: Aerospace, Automotive, Industrial Machinery, Marine End User: Manufacturing, Construction, Energy, Transportation Installation Type: Fixed, Mobile, Customizable, Standard |
| Companies Covered | Moog Inc, SPINNER GmbH, Deublin Company, Hammelmann HAAG ZEISSLER, Duff-Norton, Kadant Inc, Dynamic Sealing Technologies, Pascal Moflon Technology, Rotary Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotary Union Market Evolving Landscape
Consolidation of fluid and electrical interfaces is compressing rotary union form factors while expanding functional density. Machine builders now specify single-housing solutions that previously required separate components, altering supplier competitive positioning.
Dual-media rotary unions are consolidating hydraulic coolant and electrical power transfer into unified titanium-alloy housings. Automotive battery manufacturers in Germany and South Korea are specifying these configurations for thermal management modules. This consolidation is eliminating separate slip ring procurement, reducing installation footprint by half in compact gantry systems.
EU F-Gas Regulation amendments are restricting perfluorinated seal elastomers used in high-pressure rotary unions. European suppliers must reformulate compounds and resubmit REACH dossiers for continued market access. Aerospace and industrial machinery segments face the steepest requalification burdens, with some manufacturers stockpiling legacy seals ahead of enforcement deadlines.
Mill service contracts in pulp and paper are fragmenting into component-level procurement, unbundling rotary unions from integrated maintenance agreements. North American paper producers now source seals and bearings separately, compressing supplier margins. This disintermediation is most pronounced in Wisconsin and Maine, where independent rebuild shops compete directly with OEM service networks.
Rotary Union Market Segmentation
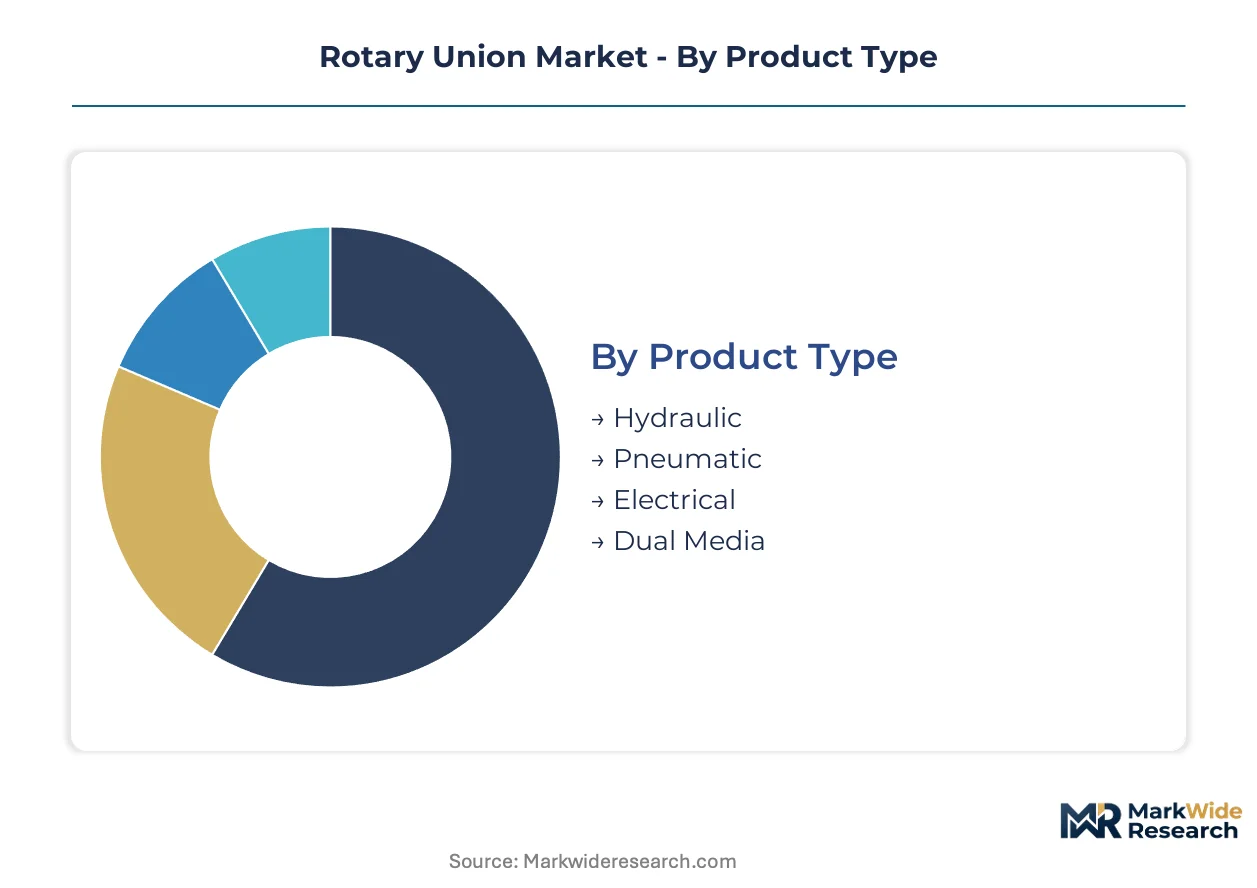
Rotary union specification varies sharply across pressure ratings, media compatibility, and duty cycles. Procurement teams segment purchases by replacement frequency and criticality, with flight-critical aerospace units commanding premium pricing against commodity industrial replacements.
Product Type:
Upgrade cycles diverge dramatically between hydraulic workhorses and emerging dual-media configurations, with the latter forcing premature obsolescence of single-function legacy units.
- Hydraulic:Carbon-graphite or silicon carbide seal faces handle pressures exceeding 10,000 psi in steel rolling mills and heavy machinery. Demand concentrates in German precision engineering clusters serving European machinery builders, where ISO 9001 quality mandates govern replacement scheduling.
- Dual Media:Unified titanium-alloy housings consolidate coolant circulation and electrical slip rings for EV battery thermal management modules. Gigafactory expansion across Germany and Hungary is pulling these configurations into electrode coating lines, displacing separate component procurement.
- Pneumatic:Lower-pressure rotary seals for automated packaging and material handling systems.
- Electrical:Slip ring assemblies for power and signal transfer in CT scanner gantries and radar platforms.
Hydraulic units sit at the top of the volume ranking, with dual media climbing the fastest.
Application:
Cost tier stratification separates flight-critical aerospace qualification from price-sensitive industrial machinery procurement, with margin pools inversely correlated to unit volume.
- Industrial Machinery:Highest absolute volume absorption across metalworking, plastics processing, and textile equipment. Mill service contracts in Wisconsin and Maine are fragmenting into component-level sourcing, compressing supplier margins as independent rebuild shops compete with OEM networks.
- Aerospace:Titanium-alloy variants displace steel configurations in next-generation aircraft platforms. FAA qualification protocols and REACH chemical compliance create steep barriers, opening premium margin pools for qualified suppliers.
- Automotive:Battery manufacturing lines specify precision rotary unions for cell formation and thermal management.
- Marine:Corrosion-resistant configurations for offshore drilling and subsea equipment.
Industrial machinery commands the widest installed base, while aerospace delivers the steepest expansion trajectory.
End User:
Customer type determines specification authority, with energy sector procurement teams centralizing technical standards against fragmented manufacturing plant-level purchasing.
- Manufacturing:Dominant demand source spanning automotive, electronics, and consumer goods production. OSHA machine guarding standards in the United States drive retrofit demand for proximity-sensor-integrated rotary unions on installed metalworking equipment.
- Energy:Wind turbine blade pitch systems and oilfield drilling equipment require high-reliability sealing. EU F-Gas Regulation amendments are restricting perfluorinated seal elastomers, forcing reformulation and requalification.
- Construction:Mobile equipment and concrete pumping machinery.
- Transportation:Rail and marine propulsion systems.
Manufacturing anchors volume demand, with energy gaining share fastest on renewable infrastructure buildout.
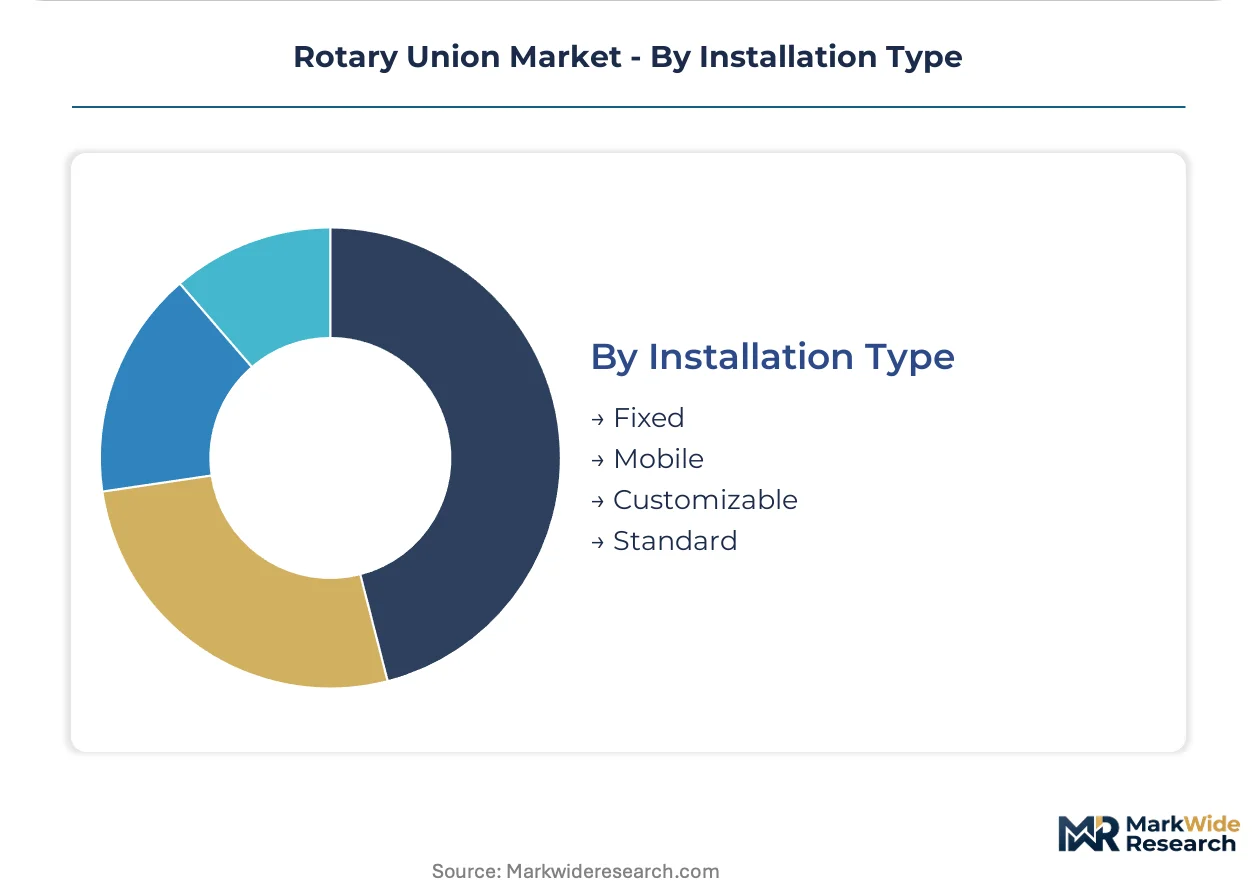
Installation Type:
Supply concentration in Stuttgart and Munich machining clusters favors standardized housing tolerances, while mobile and customizable variants face elongated lead times.
- Fixed:Permanent mounting in steel mills, paper machines, and machine tool spindles. Precision machining concentration in German engineering clusters controls critical housing tolerances, creating geographic single-source risk for non-German OEMs.
- Customizable:Five-axis CNC workholding systems demand simultaneous coolant, air, and electrical feeds, stretching engineering resource allocation across specialized suppliers.
- Mobile:Construction equipment and portable industrial machinery.
- Standard:Catalog configurations for replacement markets.
Fixed installations dominate replacement revenue, with customizable variants expanding most quickly on multi-axis machine tool complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing rotary union manufacturing capacity as compliance costs diverge across jurisdictions. Suppliers are relocating precision machining operations toward jurisdictions with stable chemical regulations and established industrial clusters.
Germany
Stuttgart and Munich engineering clusters anchor European precision machining for rotary union housings. The EU F-Gas Regulation is forcing seal reformulation across Baden-Württemberg suppliers ahead of enforcement deadlines. Bavaria-based fabricators are stockpiling legacy fluoropolymer seals while accelerating fluoropolymer alternative qualification under REACH protocols.
United States
OSHA machine guarding standards are driving retrofit demand for proximity-sensor-integrated rotary unions on installed metalworking equipment. The EPA's evolving PFAS restrictions are compressing seal material supply chains for domestic manufacturers. Wisconsin and Maine pulp and paper producers are fragmenting mill service contracts into component-level procurement, intensifying price competition.
China
Rare earth processing constraints are elevating fluoropolymer feedstock costs for seal manufacturers serving export markets. MIIT industrial upgrading programs are channeling investment toward precision component fabrication in Yangtze River Delta clusters. Zhejiang and Jiangsu province machining centers are expanding capacity for hydraulic rotary union exports to Southeast Asian machinery builders.
India
PLI scheme incentives for automotive and textile machinery are attracting first-mover rotary union suppliers to establish local assembly operations. BIS quality certification requirements are creating compliance barriers for unqualified imports. Maharashtra and Gujarat industrial corridors are concentrating demand from battery manufacturing investments and plastics processing equipment.
South Korea
Gigafactory expansion around Seoul and Busan is pulling dual-media rotary unions into electrode coating and cell formation lines. MFDS chemical safety protocols are aligning with REACH-equivalent standards for seal material documentation. Gyeonggi-do precision engineering suppliers are qualifying titanium-alloy variants for aerospace tier-one contracts.
Rotary Union Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue dual-media convergence and PFAS-compliant seal technologies. The vendor base stratifies across aerospace-qualified specialists, pulp-and-paper service incumbents, and precision machining generalists. Three archetypes dominate: flight-critical sealing specialists leveraging FAA qualification protocols; process-industry incumbents defending mill service relationships; and precision engineering houses exploiting geographic clustering. Competitive moves concentrate on backward integration into captive machining capacity and accelerated seal material requalification under tightening chemical regulations.
Within the flight-critical tier, Moog Inc and SPINNER GmbH exemplify aerospace-qualified positioning. Deublin Company anchors the process-industry service archetype through North American machining integration. Kadant Inc occupies the pulp-and-paper specialist position where mill knowledge resists commoditization. These three represent distinct competitive vectors: aerospace pedigree, geographic machining control, and vertical application expertise.
| Leading Market Players |
|---|
| Moog Inc |
| SPINNER GmbH |
| Deublin Company |
| Hammelmann HAAG ZEISSLER |
| Duff-Norton |
| Kadant Inc |
| Dynamic Sealing Technologies |
| Pascal Moflon Technology |
| Rotary Systems |
| Others |
Value Network & Pricing Analysis
Fluoropolymer feedstock costs cascade from Chinese rare earth processing through European seal manufacturers into tiered component pricing for automotive and aerospace buyers. Stuttgart machining clusters capture premium housing tolerances while Asian fabricators compete on standardized hydraulic units, creating geographic price stratification that rewards precision engineering proximity.
Pricing Analysis
Input-cost pass-through from fluoropolymer compounds and titanium-alloy bar stock dominates pricing dynamics across product tiers. Three-tier pricing structure across premium, standard, and economy levels separates FAA-qualified aerospace configurations from ISO 9001 industrial replacements and catalog commodity units. Pricing pressure stems from PFAS restriction compliance costs and seal material requalification investments, compressing margins on legacy product lines. Automotive battery manufacturers exhibit highest price sensitivity due to gigafactory volume procurement, while aerospace OEMs accept premium positioning for flight-critical qualification documentation.
Supply Chain Analysis
Direct-to-OEM channels handle flight-critical aerospace demand while distributor networks serve aftermarket replacement markets. Supply concentrates in Germany, China, and the United States for precision housings, with secondary machining capacity emerging in India and South Korea. Raw material dependencies rest on fluoropolymer elastomers, titanium-alloy forgings, and silicon carbide seal blanks. Single-source vulnerability concentrates around Stuttgart and Munich tolerance-controlled machining clusters. Distribution runs through authorized service networks for mill maintenance contracts and direct mill procurement for new equipment builds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as EV battery thermal management and aerospace lightweighting shift procurement toward dual-media titanium-alloy specifications that command sustained premium positioning.
For Market Incumbents: Deploy backward integration into captive machining capacity to defend margin position against geographic supply concentration risks. Accelerate PFAS-compliant seal qualification under REACH protocols to preempt regulatory displacement. Moog Inc's aerospace pedigree and Deublin Company's North American machining control exemplify defensible positioning against emerging precision engineering entrants. For New Entrants and Emerging Players: Dual-media convergence technology offers entry wedge into semiconductor wafer handling and battery manufacturing equipment specifications underserved by legacy single-function suppliers. Target India's PLI scheme corridors for automotive and textile machinery assembly to capture first-mover localization advantages. Lead with fluoropolymer alternative documentation to differentiate against incumbents burdened by legacy seal requalification timelines. For Investors and Strategic Acquirers: Consolidation pressure builds where mill service contract fragmentation and component-level procurement unbundle integrated maintenance relationships. Long-term viability favors precision machining generalists with geographic diversification and certified alternative material pipelines. Watch FAA qualification protocol adoption rates as inflection signal for titanium-alloy variant penetration in next-generation aircraft platforms.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Compliant Seal Qualification | REACH dossier resubmission secures continued EU market access for high-pressure configurations. |
| Dual-Media Product Development | Unified coolant-electrical housings capture EV battery thermal management specification wins. |
| Precision Machining Expansion | Captive tolerance control reduces geographic single-source risk for non-German OEMs. |
| India Manufacturing Localization | PLI scheme alignment captures automotive and textile machinery demand growth. |
| Mill Service Contract Restructuring | Component-level procurement adaptation responds to Wisconsin and Maine paper producer sourcing shifts. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with rotary union procurement managers, aerospace tier-one supplier engineers, pulp and paper mill maintenance directors, and precision machining facility operators with secondary validation. Bottom-up and top-down triangulation drew from SEC 10-K filings, EU F-Gas Regulation enforcement documentation, customs trade data for fluoropolymer imports, and machinery builder capex disclosures.
Segment-weighting across product type, application, end user, and installation type dimensions anchored volume and value outputs throughout the forecast period. CAGRs derived from regression analysis against industrial machinery production indices, aerospace delivery schedules, and automotive battery manufacturing capacity announcements. Modeling incorporated REACH chemical compliance timeline assumptions and OSHA machine guarding retrofit penetration rates as industry-specific forecast inputs.
The model holds under stable regulatory enforcement timelines and continued rare earth processing capacity; deviation in PFAS restriction acceleration or Chinese export controls would shift seal material cost assumptions. Forecasts reflect documented base-case assumptions regarding gigafactory buildout schedules and aerospace platform qualification windows. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Agitator Bead Mill Market
Others
Nutricosmetics Market
Others
Cloud Broadcasting Solutions Market
Others
Hookah Tobacco Market
Others
Global Radar Systems Market
Others
India Foundry Market
Others
Mexico Retail Market
Others
Japan Coal Market
Others
France Automotive LED Lighting Market
Others
Allogeneic Human Chondrocyte Market
Others
Workbench Tanks Market
Others
Linear Shaft Market
Others
Language Translation Device Market
Others
Nuclear Power Cables Market
Others
Fresh Durian Market
Others
Dental Ceramics Market