
 Pyrophyllite Market | 2026-2036
Pyrophyllite Market Size, Share, and Industry Trends Forecast 2026-2036
Pyrophyllite Market Intelligence
Refractory manufacturers is reorganizing procurement priorities away from legacy alumina-silica blends toward pyrophyllite-rich formulations that tolerate higher thermal shock. IMI Fabi S.p.A. leverages vertical integration across Italian mining and milling assets to secure consistent feedstock quality. Minerals Technologies Inc. anchors North American supply through controlled calcination capacity. Ashapura Minechem Limited dominates Indian exports with captive port infrastructure.
Pyrophyllite is a hydrous aluminum silicate mineral with a Mohs hardness of 1-2 and a chemical composition of Al₂Si₄O₁₀(OH)₂, formed through hydrothermal alteration of feldspathic rocks and prized for its low thermal expansion and chemical inertness in high-temperature industrial processes. Calcined pyrophyllite commands premium positioning among product types due to its dimensional stability in precision ceramics, while crude pyrophyllite sustains volume leadership in bulk refractory filler applications. Powdered pyrophyllite captures expanding share in plastics compounding as a functional filler that reduces resin load without degrading mechanical performance.
REACH registration requirements in Europe and EPA mining discharge rules in the United States constrain market access for unprocessed ore with elevated heavy metal content, forcing beneficiation investments at extraction points. China's GB standards for ceramic raw materials and India's BIS certification for refractory minerals add parallel compliance layers that shape product specifications across export channels. Stakeholders must monitor how dual carbon goals in China and evolving EU carbon border adjustments recast the cost structure of calcination-intensive processing routes.
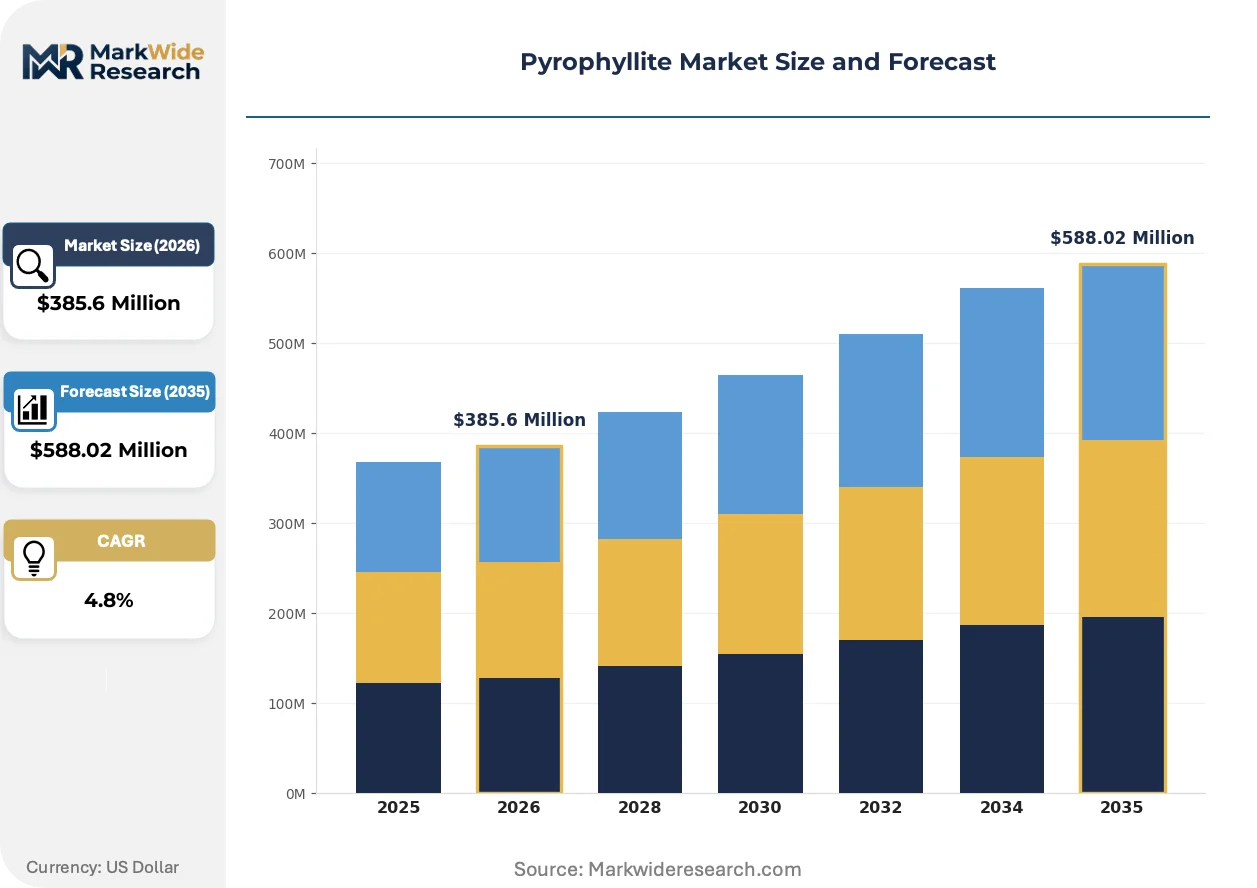
Market Dynamics
Refractory kiln operators are consolidating feedstock specifications around thermally stable aluminum silicates, compressing supplier margins while elevating purity premiums across calcination-dependent processing tiers.
Growth Catalysts
- REACH chemical safety mandates:ECHA registration requirements for industrial minerals are filtering out unprocessed ore with heavy metal contamination, directing volume toward certified beneficiation facilities in Europe.
- Ceramic tile cluster expansion:Jiangxi and Zhejiang provinces in China are absorbing processed pyrophyllite grades at accelerating rates for high-volume tile production.
- Calcination technology advancement:Controlled thermal processing is unlocking dimensional stability specifications that crude grades cannot match, opening precision ceramics applications.
Market Restraints
- Energy cost volatility:Natural gas and electricity inputs for calcination operations are compressing margins at thermal processing facilities.
- Deposit concentration risk:Economically viable pyrophyllite reserves cluster in specific geological formations, limiting geographic diversification of primary supply.
- Alumina-silica substitute competition:Synthetic refractory blends and alternative hydrous aluminum silicates are capturing price-sensitive refractory filler segments.
Strategic Opportunities
- Plastics compounding penetration:Powdered pyrophyllite as a functional filler is gaining formulation trials in polymer systems seeking resin reduction without mechanical degradation.
- EU carbon border adjustment alignment:CBAM implementation is creating first-mover advantages for calciners with verified low-carbon thermal processing.
- India refractory export growth:BIS-certified mineral grades from Indian processing hubs are accessing Middle Eastern and Southeast Asian steel refractory markets.
Industry Challenges
- Beneficiation capex requirements:Heavy metal removal and particle size classification infrastructure demands capital deployment at extraction points before market access.
- Multi-jurisdiction certification timelines:Parallel REACH, EPA, GB standard, and BIS compliance processes are extending product qualification cycles for export-oriented processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pyrophyllite Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $588.02 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crude Pyrophyllite, Calcined Pyrophyllite, Fiber-Reinforced Pyrophyllite, Powdered Pyrophyllite Form: Granules, Powder, Blocks, Slabs Application: Ceramics, Refractories, Paints, Plastics End User: Construction, Automotive, Electronics, Pharmaceuticals |
| Companies Covered | IMI Fabi S.p.A., Minerals Technologies Inc., Ashapura Minechem Limited, R.T. Vanderbilt Company, Inc., Pyrophyllite Company Inc., Sibelco Group, LKAB Minerals AB, Xinyang Mineral Group, Golcha Minerals Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pyrophyllite Market Strategic Shifts & Innovations
Digital process control and emissions tracking are reconfiguring how pyrophyllite processors compete, separating capitalized operators from legacy miners unable to meet documentation requirements.
Advanced calcination with real-time temperature profiling is fragmenting the traditional split between crude and processed grades. Precision ceramics manufacturers are adopting these thermally stable inputs for kiln furniture and electronic substrates. The technology is fragmenting established supply relationships as buyers bypass traders to contract directly with controlled-calcination facilities.
EPA mining discharge rules are tightening effluent standards for heavy metal runoff at extraction sites. Operators must install water treatment infrastructure or face permit revocation. United States-based miners are responding by integrating beneficiation circuits earlier in the value chain to ensure compliance before ore leaves the property.
Direct mill-to-plant contracting is displacing spot-market purchasing among large refractory manufacturers. Volume buyers are securing multi-year offtake agreements with specified purity bands and carbon intensity disclosures. This pattern is most visible in European ceramics clusters where REACH documentation requirements make trader intermediation cost-prohibitive.
Pyrophyllite Market Segmentation
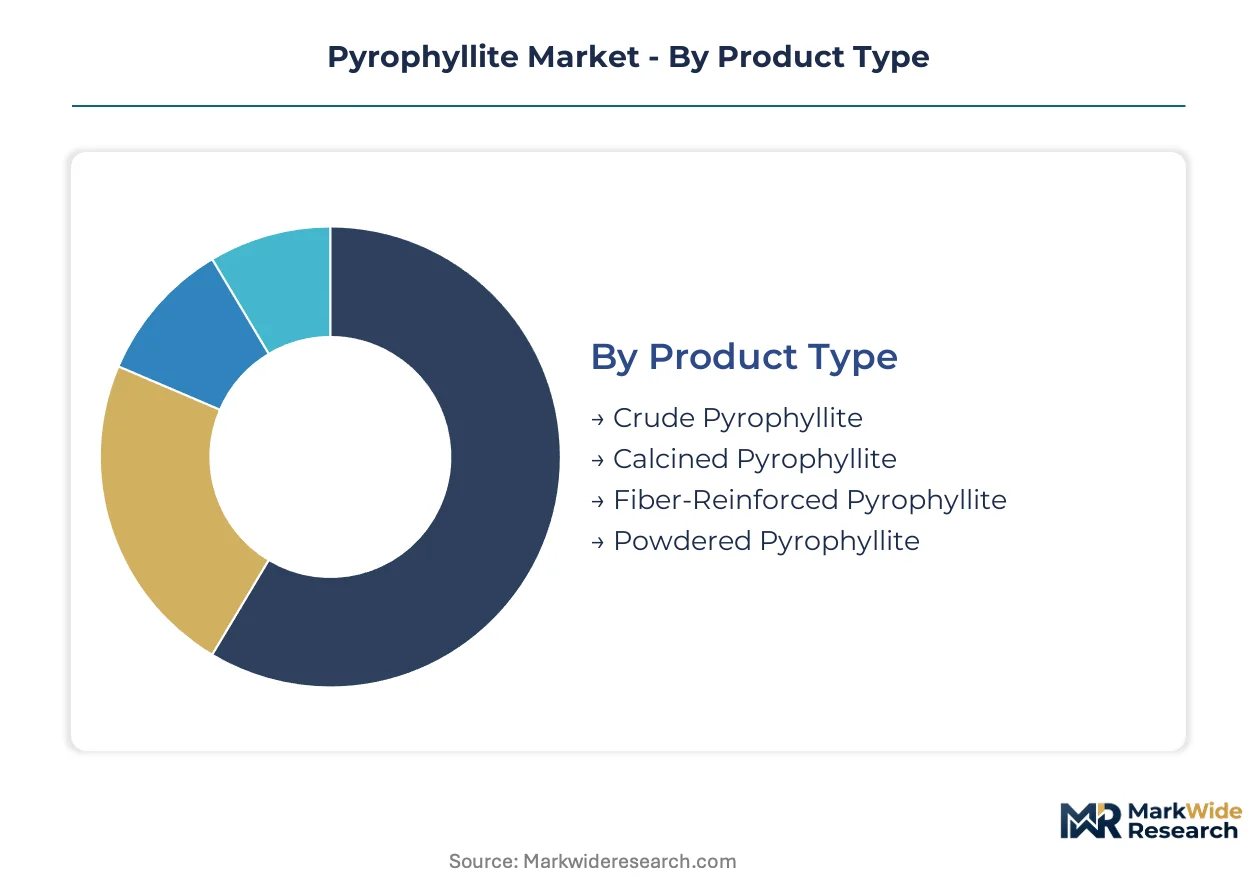
Pyrophyllite's industrial utility fragments across mineral processing tiers, physical forms, and end-use specifications that dictate channel strategy. Buyers route crude grades through bulk commodity distributors while precision ceramics manufacturers contract directly with calcination facilities for certified thermal stability.
Product Type:
Channel economics separate unprocessed ore moving through trader networks from value-added grades commanding direct mill-to-plant procurement relationships.
- Crude Pyrophyllite:Raw hydrous aluminum silicate ore with minimal beneficiation serves as bulk refractory filler where thermal shock tolerance matters less than cost containment. Refractory manufacturers in India's BIS-certified processing hubs absorb substantial volumes for steel industry kiln linings, though heavy metal content restrictions under EPA mining discharge rules constrain unprocessed export flows from United States extraction sites.
- Calcined Pyrophyllite:Controlled thermal processing drives off hydroxyl groups to achieve dimensional stability specifications essential for precision ceramics. Jiangxi province ceramic tile clusters source these processed grades aggressively, with REACH-registered European buyers requiring documented carbon intensity disclosures under evolving EU carbon border adjustment mechanisms.
- Fiber-Reinforced Pyrophyllite:Composite formulations blending mineral matrix with ceramic or glass fibers target structural applications demanding mechanical reinforcement.
- Powdered Pyrophyllite:Finely milled grades with controlled particle size distribution penetrate plastics compounding as functional fillers reducing resin load.
Crude pyrophyllite dominates installed base. Calcined pyrophyllite is where expansion concentrates.
Form:
Physical configuration determines logistics cost structure and processing equipment compatibility at downstream integration points.
- Granules:Intermediate sizing between crude ore and fine powders suits refractory gunning mixes and ramming compounds where controlled permeability supports binder penetration. Steel producers in China's Zhejiang manufacturing corridors specify narrow granulometric bands for consistent packing density in monolithic linings.
- Powder:Sub-45 micron classifications enable homogeneous dispersion in ceramic body formulations and polymer matrices. Plastics compounders trial these grades for resin extension without tensile strength degradation, particularly in automotive underhood components facing thermal cycling demands.
- Blocks:Dimensioned raw material for carving specialized refractory shapes or artistic applications.
- Slabs:Large-format pieces serving sculptural and select architectural surfacing markets.
Powder commands the broadest addressable market. Granules retain the deepest refractory penetration.
Application:
End-use performance requirements stratify procurement specifications across thermal, chemical, and mechanical stress envelopes.
- Ceramics:Wall and floor tile manufacturers leverage pyrophyllite's low thermal expansion to minimize firing defects in high-speed roller hearth kilns. China's GB standards for ceramic raw materials mandate specific alumina-silica ratios that processed pyrophyllite grades satisfy more consistently than alternative fluxes.
- Refractories:High-temperature kiln furniture, steel ladles, and glass tank linings demand thermally stable aluminum silicates tolerating repeated thermal shock. Indian exporters with captive port infrastructure capture Middle Eastern steel refractory demand through BIS-certified mineral grades.
- Paints:Functional extender pigments exploiting platy particle morphology for barrier properties and sheen control.
- Plastics:Engineering resin systems incorporate powdered grades for cost reduction and dimensional stability in injection-molded components.
Refractories anchor volume consumption. Plastics compounding is gaining share fastest.
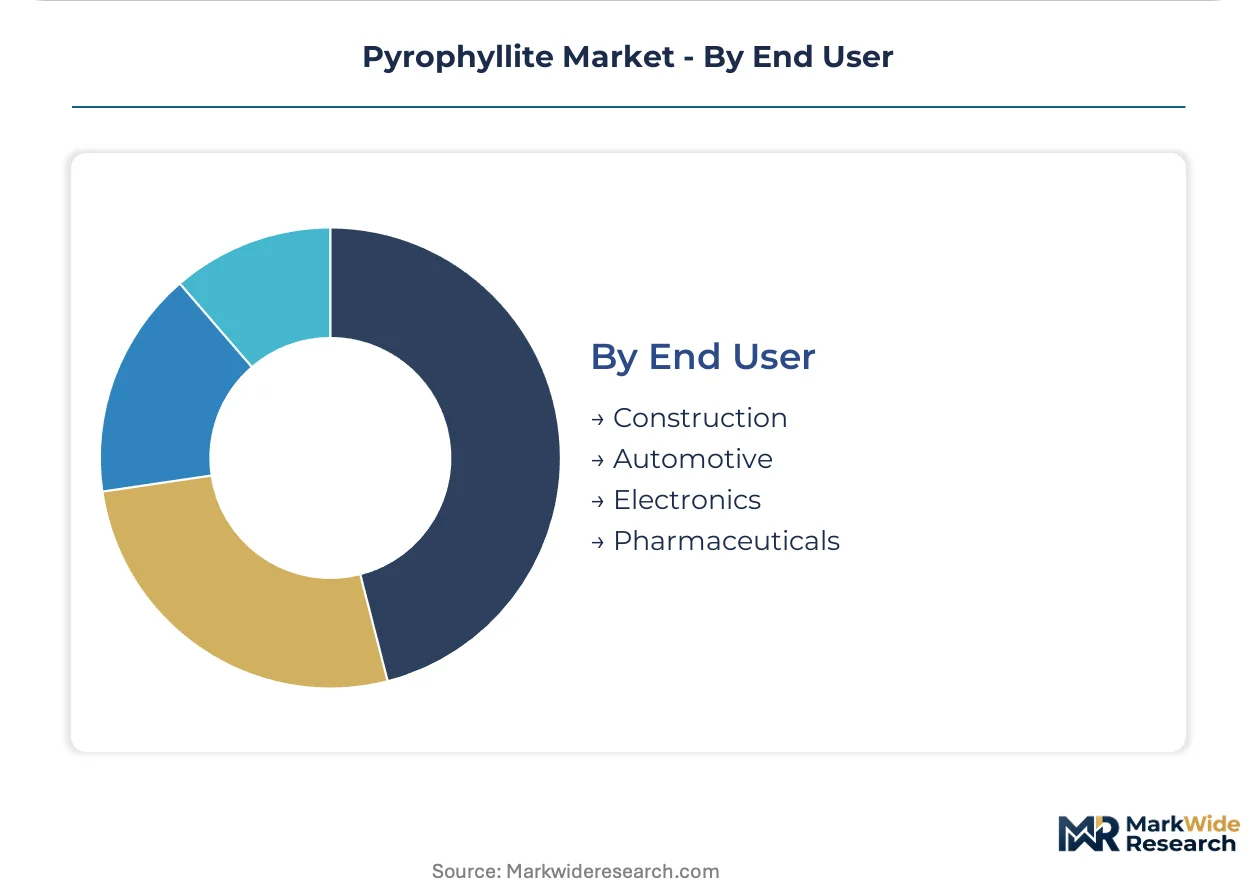
End User:
Customer scale and technical sophistication determine whether procurement flows through distributors or direct supply agreements with carbon disclosure requirements.
- Construction:Ceramic tile producers and refractory installers constitute the foundational demand base, with specification engineers prioritizing consistent firing behavior over commodity pricing. European ceramics clusters now require REACH documentation that trader intermediation cannot economically provide.
- Automotive:Underhood plastics and brake friction formulations utilize pyrophyllite's thermal stability and abrasive properties. Tier suppliers face OEM mandates for supply chain carbon transparency that favor calciners with verified low-carbon thermal processing.
- Electronics:Precision ceramics for substrates and insulators demand ultra-low alkali calcined grades.
- Pharmaceuticals:Limited specialty applications in tablet excipients and processing equipment linings where chemical inertness is paramount.
Construction commands absolute tonnage. Automotive is where qualification complexity is accelerating.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Geologically viable pyrophyllite reserves cluster in hydrothermal formations across East Asia, South Asia, and select European Alpine regions, with calcination capacity and ceramic cluster proximity determining competitive positioning.
China
Jiangxi and Zhejiang provinces absorb processed pyrophyllite grades aggressively for ceramic tile production. GB standards for ceramic raw materials mandate specific alumina-silica ratios that shape import specifications. Yangtze River Delta ceramic clusters source calcined grades directly from controlled-thermal-processing facilities.
United States
Refractory manufacturers reorganize procurement priorities toward pyrophyllite-rich formulations for high-temperature kiln linings. EPA mining discharge rules tighten effluent standards for heavy metal runoff at extraction sites. Appalachian and Southeastern mining operations integrate beneficiation circuits to ensure compliance before ore leaves property.
India
BIS-certified mineral grades from Indian processing hubs access Middle Eastern and Southeast Asian steel refractory markets. Captive port infrastructure at western and eastern seaboards dominates export logistics. Maharashtra and Gujarat refractory processing corridors concentrate beneficiation investments to meet multi-jurisdiction certification timelines.
Italy
REACH chemical safety mandates filter unprocessed ore with heavy metal contamination toward certified beneficiation facilities. ECHA registration requirements shape procurement documentation for European ceramics clusters. Alpine region mining and milling assets secure consistent feedstock quality for precision ceramics applications.
Japan
Precision ceramics manufacturers adopt thermally stable pyrophyllite inputs for kiln furniture and electronic substrates. METI industrial standards govern mineral purity specifications for high-technology applications. Kansai and Chubu manufacturing corridors contract directly with calcination facilities for ultra-low alkali grades.
Pyrophyllite Market Key Industry Players
Concentration sits with vertically integrated miners controlling both extraction assets and thermal processing capacity. The supplier base fragments between integrated majors with captive calcination infrastructure and regional traders dependent on third-party processing. Three archetypes dominate: Italian and Nordic miners with backward integration into Alpine deposits, Indian exporters leveraging captive port infrastructure, and Chinese state-affiliated mineral groups with cluster-proximity advantages. Competitive moves center on multi-year offtake agreements with carbon intensity disclosures and direct mill-to-plant contracting that displaces spot-market purchasing.
Within the integrated-miner tier, IMI Fabi S.p.A. and LKAB Minerals AB exemplify European operators with upstream control over extraction and milling assets. Ashapura Minechem Limited occupies a position among Indian exporters with coastal infrastructure advantages. These anchors illustrate how geographic proximity to ceramic clusters and refractory demand centers shapes competitive positioning across the value chain.
| Leading Market Players |
|---|
| IMI Fabi S.p.A. |
| Minerals Technologies Inc. |
| Ashapura Minechem Limited |
| R.T. Vanderbilt Company, Inc. |
| Pyrophyllite Company Inc. |
| Sibelco Group |
| LKAB Minerals AB |
| Xinyang Mineral Group |
| Golcha Minerals Pvt. Ltd. |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day inventory cycles at European refractory manufacturers concentrate pricing power with calcination facilities holding REACH-registered beneficiation capacity, while spot-market crude ore traders face margin compression from multi-jurisdiction certification timelines.
Pricing Analysis
REACH registration requirements dictate the pricing tier structure across European ceramic clusters, separating premium calcined grades with documented carbon intensity disclosures from standard beneficiated ore and economy crude shipments lacking ECHA certification. Price differentiation rests on heavy metal purity thresholds and thermal stability specifications, with precision ceramics buyers showing least price sensitivity for ultra-low alkali grades while bulk refractory fillers face acute cost compression from alumina-silica substitutes.
Supply Chain Analysis
Strait of Malacca transit underwrites much of Indian export flows to Southeast Asian steel refractory markets, with supply concentrating in China's Jiangxi province, India's Maharashtra-Gujarat corridor, and Italy's Alpine mining districts. Raw material extraction draws from hydrothermally altered feldspathic formations requiring diesel fuel, electricity, and water treatment chemicals. Distribution runs through captive port infrastructure at Indian seaboards and direct mill-to-plant contracting displacing spot-market purchasing among large European ceramics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
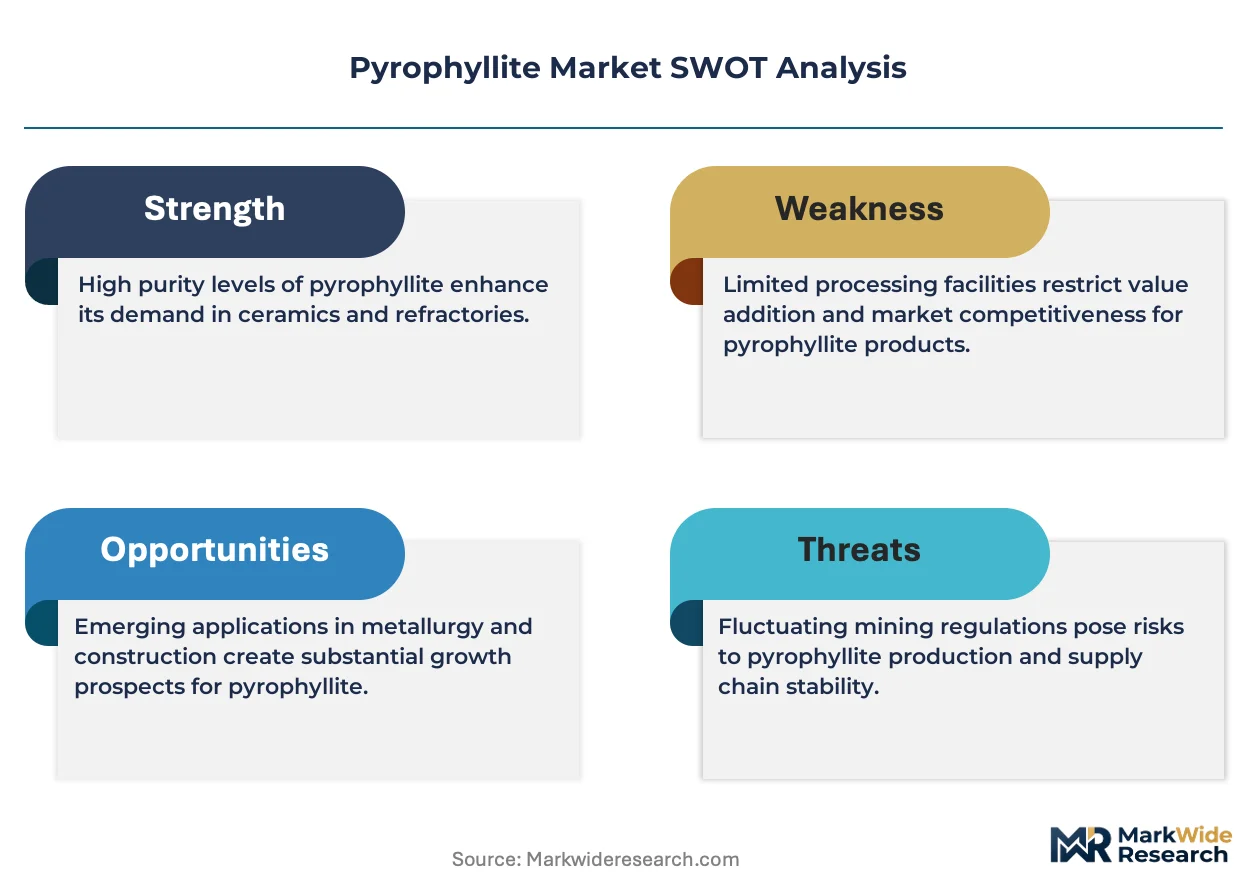
Fragmentation opportunity emerges as precision ceramics specifications proliferate beyond standardized refractory grades, with plastics compounding trials and carbon border adjustment documentation creating definable niche positions for specialized processors.
For Market Incumbents: Compound defensibility through backward integration into captive calcination capacity and multi-year offtake agreements with carbon intensity disclosure requirements. Synthetic refractory blend competition threatens price-sensitive filler segments; counter through BIS-certified export positioning at Indian coastal hubs. For New Entrants and Emerging Players: Lead with plastics compounding penetration in automotive underhood resin systems, where resin reduction without mechanical degradation commands formulation trials. Target Middle Eastern steel refractory procurement through Indian processing partnerships; differentiate via documented low-carbon thermal processing aligned with EU carbon border adjustment mechanisms. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified mining conglomerates with neglected pyrophyllite assets lacking calcination infrastructure. Long-term viability hinges on ceramic cluster proximity and regulatory certification depth; watch for carbon border adjustment implementation intensity as inflection indicator for calciner valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Beneficiation Assets | Captive heavy metal removal capacity secures REACH market access ahead of trader-dependent competitors. |
| Long-term Supply Agreement | Direct mill-to-plant contracting with Jiangxi ceramic clusters displaces spot-market intermediation. |
| Green Manufacturing Transition | Verified low-carbon calcination unlocks EU carbon border adjustment alignment for European buyers. |
| Joint Venture | Indian port infrastructure partnerships with Middle Eastern steel refractory distributors accelerate BIS-certified export growth. |
| Capacity Expansion | Controlled thermal processing additions in Zhejiang province capture precision ceramics specification upgrades. |
Research Approach
Cross-validation between primary interviews with refractory procurement managers, calcination facility technical directors, and ceramic tile specification engineers and secondary validation through customs trade data, SEC 10-K filings from listed mineral processors, and BIS certification registries anchors the qualitative findings. Bottom-up volume estimates from individual beneficiation facilities triangulate against top-down demand modeling from end-use consumption patterns.
Sensitivity analysis around energy cost assumptions and carbon border adjustment implementation timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use application, physical form specification, and regional production hub. CAGRs derive from fitted growth curves applied to verified baseline volumes, with calcination capacity utilization rates and ceramic cluster expansion pipelines serving as industry-specific forecast inputs.
Forecasts assume regulatory continuity in REACH, EPA mining discharge, and BIS certification regimes; material policy shifts would require re-modeling. Revision becomes warranted when carbon border adjustment coverage expansion or synthetic refractory substitute cost reductions cross thresholds altering calcined grade demand elasticity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Feldspathic Minerals Market
Industrial Minerals
Global Feed Minerals Market
Industrial Minerals
Olivine Sand Market
Industrial Minerals
Chelated Minerals Market
Industrial Minerals
Global Commercial Perlite Market
Industrial Minerals
Mineral Adsorbent Market
Industrial Minerals
Unexpanded Perlite Market
Industrial Minerals
Slate Market
Industrial Minerals
Pyrites Market
Industrial Minerals
Gluconate Mineral Market
Industrial Minerals
Anhydrite Market
Industrial Minerals
North America Silica Sand Market
Industrial Minerals
Feldspar Mining Market
Industrial Minerals
Perlite Market
Industrial Minerals
Limestone Market
Industrial Minerals
Limestone Mill Market