
 Organic Frozen Bakery Market | 2026-2036
Organic Frozen Bakery Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Frozen Bakery Market Outlook
USDA Organic certification is bifurcating the competitive landscape into qualified suppliers and excluded commodity producers. Amy's Kitchen leverages its vertically integrated supply chain to maintain ingredient traceability from farm to freezer. Schär specializes in gluten-free organic formulations, occupying a defensible niche across European retail channels. Conagra Brands extends its frozen portfolio through broad distribution agreements with North American supermarket chains.
Organic frozen bakery comprises dough-based products manufactured without synthetic pesticides, artificial preservatives, or genetically modified organisms, then flash-frozen at minus eighteen degrees Celsius to arrest starch retrogradation and preserve volatile aromatic compounds. The primary commercial purpose is to deliver extended-shelf-life baked goods to retail and foodservice operators requiring batch flexibility without on-premise mixing infrastructure. Bread and pastries lead volume contribution, though gluten-free ingredient types command premium positioning in allergen-sensitive segments. Foodservice end users represent the fastest-growing demand pool as institutional buyers substitute frozen organic SKUs for scratch production.
USDA Organic standards govern crop sourcing and processing claims in the United States, while EFSA and EU Green Deal frameworks regulate carbon accounting and clean-label thresholds across European supply chains. These certification requirements raise capital barriers for new entrants and force incumbent reformulation investments. Stakeholders must monitor evolving refrigerant regulations and organic integrity enforcement to protect market access and margin structures.
Market Dynamics
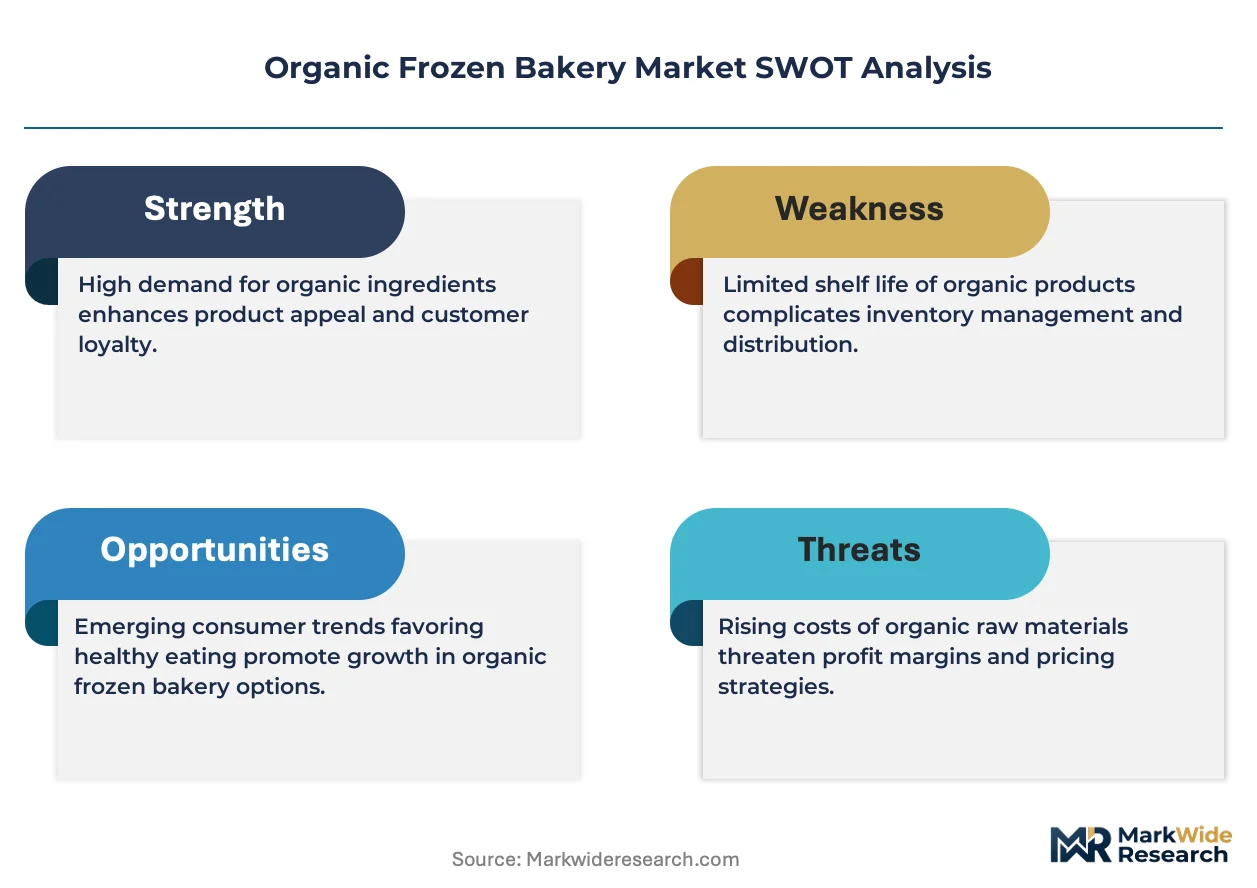
The EU F-Gas Regulation and USDA Organic certification requirements are forcing simultaneous reformulation of refrigerant systems and ingredient sourcing protocols, compressing margins while erecting capital barriers that favor scaled operators with captive supply chains.
Growth Catalysts
- EU Green Deal carbon accounting mandates:Foodservice operators across Germany and France now require verified Scope 3 emissions documentation, pulling organic frozen SKUs into institutional procurement frameworks.
- Boutique hotel breakfast programs:Independent hospitality chains in Berlin and Munich substitute flash-frozen organic pastries for scratch production to reduce labor variance and waste.
- Flash-freezing at minus eighteen degrees Celsius:This process arrests starch retrogradation in dough-based products, preserving volatile aromatic compounds that differentiate premium positioning from commodity alternatives.
Market Restraints
- Organic wheat and butter input volatility:Contract pricing for certified organic grains fluctuates with weather-induced yield compression in Black Sea and North American growing regions.
- Cold-chain infrastructure concentration:Third-party logistics providers with F-Gas-compliant refrigerant systems cluster in northern Italy and the Netherlands, creating distribution bottlenecks for southern European markets.
- Scratch production substitution threat:Artisan bakeries in Vienna and Copenhagen market "fresh-baked" provenance that undercuts frozen organic claims among experience-driven consumers.
Strategic Opportunities
- Underpenetrated Spanish foodservice:Barcelona and Madrid institutional buyers show lagging adoption versus German benchmarks, presenting first-mover expansion potential for certified suppliers.
- Convergence of modified-atmosphere packaging with blockchain traceability:Combined technologies enable real-time organic integrity verification from farm to freezer, justifying premium pricing in skeptical retail channels.
- Direct-to-hotel distribution platforms:Digital procurement networks bypass traditional wholesale intermediaries, capturing margin previously allocated to frozen food distributors.
Industry Challenges
- USDA Organic certification timeline compression:Three-year transition periods for conventional farmland conversion strain supplier onboarding velocity.
- Refrigerant reengineering capex intensity:Retrofitting production facilities for hydrofluoroolefin alternatives demands capital allocation that squeezes mid-tier producers.
- Cross-border organic integrity enforcement:Divergent EU member state interpretations of EFSA clean-label thresholds create compliance fragmentation for pan-European brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Frozen Bakery Market |
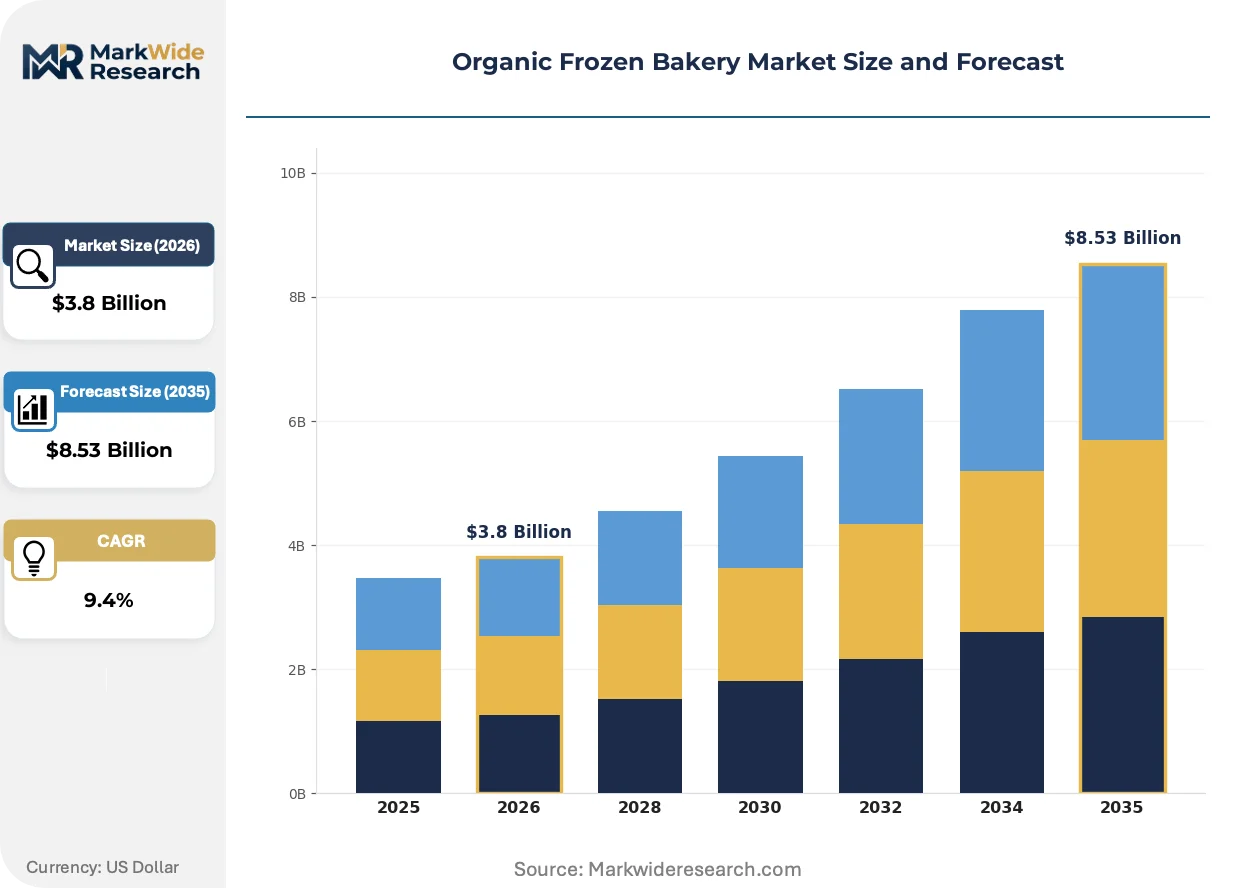
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
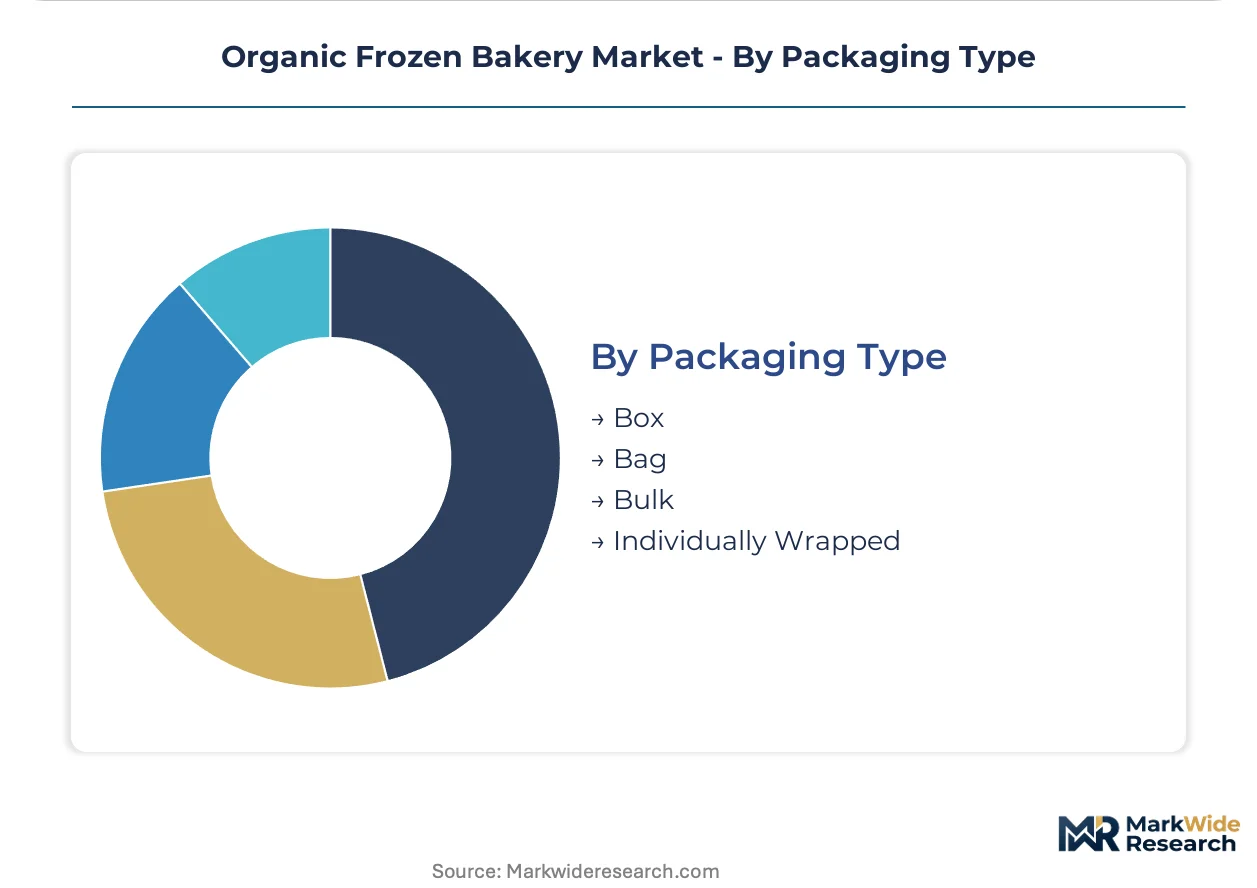
| Segmentation | Product Type: Pastries, Bread, Cookies, Muffins Ingredient Type: Whole Grain, Gluten-Free, Non-GMO, Natural Sweeteners End User: Retail, Foodservice, Bakeries, Online Consumers Packaging Type: Box, Bag, Bulk, Individually Wrapped |
| Companies Covered | Amy's Kitchen, Nature's Bakery, Dawn Foods, Earth Balance, Schär, Whole Foods Market, Pillsbury, Baker's Delight, Conagra Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Frozen Bakery Market Strategic Shifts
Flash-freezing technology and refrigerant chemistry are converging with digital traceability platforms to redefine competitive advantage, while procurement patterns among foodservice buyers shift toward emission-documented supply chains.
Modified-atmosphere packaging systems that extend shelf life without synthetic preservatives are bifurcating the competitive landscape between certified organic suppliers and conventional frozen bakery producers. Boutique hotel chains and specialty coffee operators in Munich and Berlin adopt these systems aggressively, compressing demand for commodity alternatives that rely on chemical stabilizers.
The EU F-Gas Regulation mandates phasedown of hydrofluorocarbon refrigerants across cold-chain infrastructure, forcing manufacturers to retrofit production facilities with hydrofluoroolefin or natural refrigerant alternatives. This regulatory pressure concentrates investment capacity among scaled operators, while smaller producers face facility obsolescence or third-party logistics dependency. German and Dutch manufacturing clusters lead compliance velocity, creating geographic advantage in export competitiveness.
Foodservice procurement departments now require batch-level carbon footprint documentation as a standard vendor qualification criterion, displacing price-primary sourcing models. Institutional buyers in Copenhagen and Vienna substitute emission-verified organic frozen pastries for unverified alternatives, channeling volume toward suppliers with integrated farm-to-freezer traceability systems. This behavioral shift is most visible in Nordic and Germanic markets where public sector procurement guidelines embed climate performance thresholds.
Organic Frozen Bakery Market Segmentation
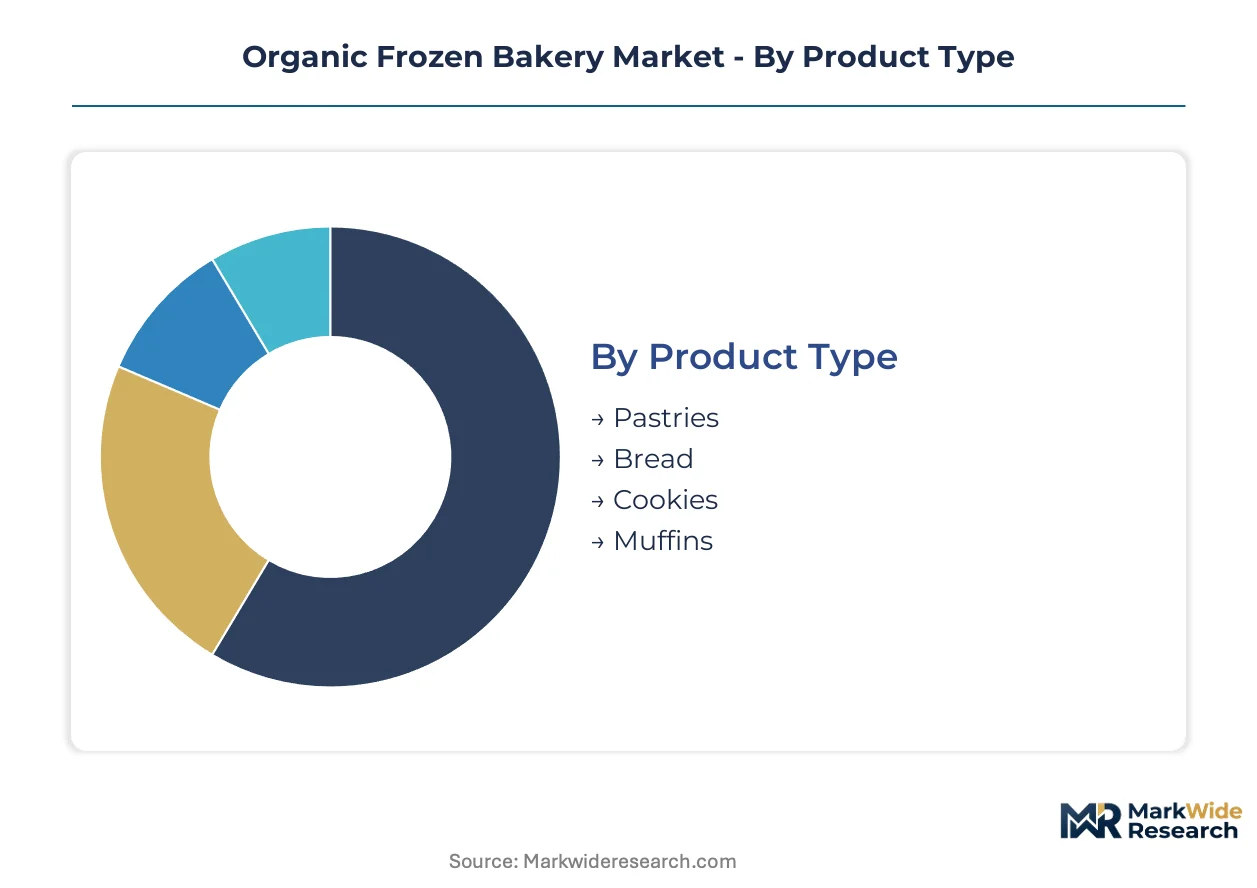
Segmentation in organic frozen bakery reveals how certification tiers, packaging formats, and channel economics allocate margin pools across supply chains. Manufacturers optimize formulation and logistics investments by matching product architecture to specific buyer procurement criteria.
Product Type:
Premium margin capture concentrates in ambient-stable formats that withstand extended cold-chain transit without quality degradation.
- Pastries:Laminated dough products with butterfat content exceeding 20 percent deliver the highest unit economics. Boutique hotel breakfast programs in Berlin and Munich pull volume for flash-frozen croissants and Danish variants, driven by labor cost reduction mandates.
- Bread:Artisan loaves with extended fermentation profiles dominate retail freezer cases. German organic retail networks anchor volume, though foodservice substitution for scratch production is accelerating most quickly in Copenhagen institutional kitchens.
- Cookies:Portion-controlled formats suit K-12 and university cafeteria specifications.
- Muffins:Single-serve wrapped variants align with grab-and-go convenience retailing.
The dominant share belongs to Bread, while Pastries is closing the gap fastest.
Ingredient Type:
Input cost structures bifurcate sharply between commodity organic grains and specialty allergen-free formulations.
- Gluten-Free:Rice and tapioca starch blends command 40-60 percent input cost premiums over wheat-based alternatives. European retail channels in Vienna and Amsterdam stock these SKUs as standard, driven by celiac diagnosis rates and clean-label preference convergence.
- Whole Grain:Sprouted wheat and ancient grain varieties (spelt, einkorn, emmer) satisfy EFSA clean-label thresholds. German consumers prioritize these formulations, creating geographic demand concentration that rewards suppliers with captive organic grain contracts.
- Non-GMO:Identity-preserved corn and soy derivatives support USDA Organic compliance for US-bound production.
- Natural Sweeteners:Coconut sugar and date paste formulations replace refined sucrose in premium positioning.
Whole Grain holds volume leadership, though Gluten-Free exhibits the steepest expansion trajectory as allergen-sensitive segments deepen.
End User:
Procurement sophistication varies dramatically across channel types, dictating traceability and documentation requirements.
- Foodservice:Institutional buyers now mandate batch-level carbon footprint documentation as standard vendor qualification. Nordic public sector procurement guidelines embed climate performance thresholds that channel volume toward suppliers with integrated farm-to-freezer systems.
- Retail:Supermarket chains negotiate slotting fees and promotional calendars that compress margins for branded suppliers. German organic retail networks anchor volume concentration.
- Bakeries:Artisan operators source frozen organic dough for labor flexibility during peak demand windows.
- Online Consumers:Direct-to-door subscription models bypass wholesale intermediaries, capturing margin previously allocated to frozen food distributors.
Retail maintains the largest share position, while Foodservice is gaining share fastest as institutional buyers substitute frozen organic SKUs for scratch production.
Packaging Type:
Packaging technology investments determine shelf-life extension and waste reduction metrics that buyers now weight in vendor scorecards.
- Modified-Atmosphere Box:Rigid containers with nitrogen flush systems extend shelf life without synthetic preservatives. Boutique hotel chains adopt these aggressively, compressing demand for commodity alternatives relying on chemical stabilizers.
- Individually Wrapped:Portion-control formats reduce food waste in institutional settings. School and healthcare foodservice specifications increasingly require this format for inventory management and hygiene compliance.
- Bag:Flexible packaging suits high-velocity retail SKUs with rapid turnover.
- Bulk:Foodservice tote formats minimize per-unit packaging cost for high-volume operators.
Bag formats dominate current volume, while Modified-Atmosphere Box is climbing the fastest as emission-documented supply chains prioritize waste reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German foodservice procurement guidelines under the EU Green Deal mandate verified Scope 3 emissions documentation, pulling organic frozen bakery SKUs into institutional frameworks across multiple jurisdictions.
Germany
Boutique hotel chains in Berlin and Munich substitute flash-frozen organic pastries for scratch production to reduce labor variance. The EU F-Gas Regulation pressures manufacturers to retrofit cold-chain infrastructure with hydrofluoroolefin alternatives. Bavaria anchors manufacturing compliance velocity, creating geographic export competitiveness for regional suppliers.
United States
USDA Organic certification bifurcates the competitive landscape into qualified suppliers and excluded commodity producers. The EPA and FDA govern clean-label thresholds alongside USDA standards. Amy's Kitchen leverages vertically integrated supply chains to maintain ingredient traceability from farm to freezer across North American retail networks.
France
Institutional buyers in Paris now require batch-level carbon footprint documentation as standard vendor qualification. EFSA frameworks regulate organic integrity enforcement across pan-European supply chains. Lyon and Marseille foodservice operators channel volume toward suppliers with integrated farm-to-freezer traceability systems.
Italy
Third-party logistics providers with F-Gas-compliant refrigerant systems cluster in northern Italy, creating distribution advantages for organic frozen bakery producers. The EU Green Deal carbon accounting mandates pull SKUs into procurement frameworks. Milan anchors cold-chain infrastructure concentration that bottlenecks southern European market access.
Netherlands
Amsterdam retail channels stock gluten-free organic formulations as standard, driven by celiac diagnosis rates and clean-label preference convergence. EFSA clean-label thresholds create compliance requirements for pan-European brands. Rotterdam logistics hubs facilitate emission-documented supply chains for Nordic and Germanic market distribution.
Organic Frozen Bakery Market Competitive Environment
Player mix skews toward mid-cap specialists with captive organic supply chains and diversified food conglomerates extending frozen portfolios through distribution agreements. Market structure concentrates investment capacity among scaled operators, while smaller producers face facility obsolescence or third-party logistics dependency. Strategic archetypes include vertically integrated organic specialists, gluten-free formulation experts, and broad-line frozen food conglomerates. Dominant competitive moves encompass backward integration into certified organic grain sourcing and geographic expansion into underpenetrated foodservice markets.
Within the vertically integrated tier, Amy's Kitchen and Conagra Brands exemplify contrasting scale profiles. Schär occupies a defensible niche position as a gluten-free formulation specialist across European retail channels. These three anchors demonstrate how certification compliance and supply chain configuration allocate competitive position in emission-documented procurement environments.
| Leading Market Players |
|---|
| Amy's Kitchen |
| Nature's Bakery |
| Dawn Foods |
| Earth Balance |
| Schär |
| Whole Foods Market |
| Pillsbury |
| Baker's Delight |
| Conagra Brands |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts for certified organic wheat and butter lock in supply access for German and Dutch manufacturers while anchoring price visibility against Black Sea weather volatility. These arrangements concentrate procurement power among scaled operators with captive grain contracts, compressing spot-market alternatives into marginal supply roles.
Pricing Analysis
Certification level (USDA Organic versus conventional frozen) creates the primary spread in unit economics across retail and foodservice channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by ingredient traceability depth and carbon documentation completeness. Cost compression in the mid-tier is intensifying because F-Gas retrofit capex demands force smaller producers to outsource cold-chain logistics. Foodservice institutional buyers show lowest price sensitivity due to labor substitution value, while convenience retail channels exhibit highest sensitivity to slotting fee negotiations.
Supply Chain Analysis
Cold-chain infrastructure bottlenecks in northern Italy and the Netherlands constrain southern European market access for organic frozen bakery distribution. Manufacturing draws from certified organic grain sources in Germany, France, and Austria, with butterfat inputs resting on pasture-based dairy contracts in Bavaria and Normandy. Single-source vulnerability concentrates in third-party logistics providers with F-Gas-compliant refrigerant systems. Distribution runs through frozen food distributors to foodservice operators, with direct-to-hotel digital platforms emerging as margin-capturing alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from cyclical input cost compression as organic grain yields stabilize and F-Gas compliance investments mature into operational efficiency gains.
For Market Incumbents: Secure captive organic grain contracts in Black Sea-adjacent growing regions to buffer against weather-induced price spikes. Retrofit remaining production facilities for hydrofluoroolefin refrigerants before regulatory phase-down deadlines harden competitive disadvantage for laggards. For New Entrants and Emerging Players: USDA Organic certification fast-track programs offer accelerated market entry for suppliers willing to absorb three-year farmland conversion timelines. Target Spanish foodservice markets in Barcelona and Madrid where institutional adoption lags German benchmarks, deploying direct-to-hotel digital procurement platforms as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated mid-cap specialists with established farm-to-freezer traceability systems and existing F-Gas compliance. Long-term viability hinges on carbon-accounting infrastructure that satisfies EU Green Deal procurement mandates. Watch Nordic public sector tender announcements as the signal for demand inflection toward emission-documented supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Organic Grain Sourcing | Amy's Kitchen and Schär demonstrate how captive supply contracts insulate margin from Black Sea weather volatility. |
| F-Gas Refrigerant Retrofit Completion | Bavaria-based manufacturers gain export competitiveness as EU regulatory phase-down accelerates facility obsolescence elsewhere. |
| Direct-to-Hotel Digital Platform Launch | Boutique hotel chains in Berlin and Munich bypass frozen food distributors to capture procurement margin directly. |
| Blockchain-Enabled Traceability Integration | Combined modified-atmosphere packaging with farm-to-freezer verification justifies premium positioning in skeptical retail channels. |
| Gluten-Free Formulation Capacity Expansion | Vienna and Amsterdam retail channels stock these SKUs as standard due to celiac diagnosis rates and clean-label convergence. |
Study Parameters
Desk research of trade customs data, EU regulatory filings, and organic certification databases preceded structured interviews with frozen food procurement directors, cold-chain logistics operators, boutique hotel F&B managers, and organic grain contract specialists. Primary fieldwork across German, Dutch, and Italian manufacturing clusters was cross-validated against secondary sources including USDA Organic integrity databases, EFSA clean-label guidance documents, and EU F-Gas Regulation implementation reports. Bottom-up volume modeling by product type and ingredient category was triangulated against top-down market sizing from channel-level revenue aggregation.
Variance decomposition across product type, ingredient certification tier, packaging technology, and end-user channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market trajectory. Forecast inputs incorporated organic grain yield projections, F-Gas retrofit capex schedules, and foodservice substitution elasticity estimates for scratch-to-frozen conversion.
Decision-makers should treat outputs as directional under assumptions of stable EU Green Deal enforcement and no Black Sea supply disruption; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as refrigerant chemistry regulations and organic integrity enforcement protocols evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Bakery Premixes Market
Bakery Products
Par-Baked Bread Market
Bakery Products
Bakery Contract Manufacturing Market
Bakery Products
Fondant Market
Bakery Products
Low Fat Baked Goods Market
Bakery Products
Frozen Bakery Additives Market
Bakery Products
Packaged Bread Market
Bakery Products
Low Fat Bread Market
Bakery Products
South America Ice Cream Market
Bakery Products
Dough Whitener Market
Bakery Products
Latin America Frozen Bakery Market
Bakery Products
Bakery Cases Market
Bakery Products
Low Calorie Muffins Market
Bakery Products
Premix Bread Flour Market
Bakery Products
Global Cake Mix Market
Bakery Products
Sourdough Market