
 Global Bottled Water Market | 2026-2036
Global Bottled Water Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bottled Water Market Analysis
Multi-pack bundling is rebalancing buyer choice in the Global Bottled Water Market as households shift toward bulk purchasing for cost efficiency and pantry loading. Nestlé leverages its deep European spring network to sustain premium positioning in glass and PET formats. The Coca-Cola Company anchors North American volume through Dasani and Smartwater distribution muscle across big-box retail. PepsiCo competes with Aquafina and LIFEWTR through enhanced portfolio breadth across still and flavored lines.
Bottled water comprises potable water sealed in food-grade containers, typically treated through reverse osmosis, UV sterilization, or ozonation to meet microbiological and chemical safety thresholds for direct consumption. Still water dominates volume globally while sparkling and mineral categories command higher per-unit margins due to source provenance claims and carbonation infrastructure requirements. Plastic bottles occupy the mass-market tier though carton and glass alternatives are capturing sustainability-premium segments in European and North American retail. Flavored water differentiates through zero-calorie positioning against carbonated soft drinks, with sports and institutional end-users driving bulk procurement of functional variants.
The FDA enforces bottled water quality standards under 21 CFR 165.110 in the United States while the EU Green Deal and REACH framework constrain polymer sourcing and recyclability mandates across European supply chains. China's SAMR and GB standards govern domestic production and import compliance, with NMPA-aligned testing protocols for mineral source registration. Stakeholders must monitor evolving extended producer responsibility laws and deposit-return scheme expansions that will reshape packaging cost structures and regional competitive advantage.
Market Dynamics
Packaging material transitions under EU Green Deal directives are compressing legacy PET supply chains while redirecting capital toward recycled-content infrastructure and alternative substrates.
Growth Catalysts
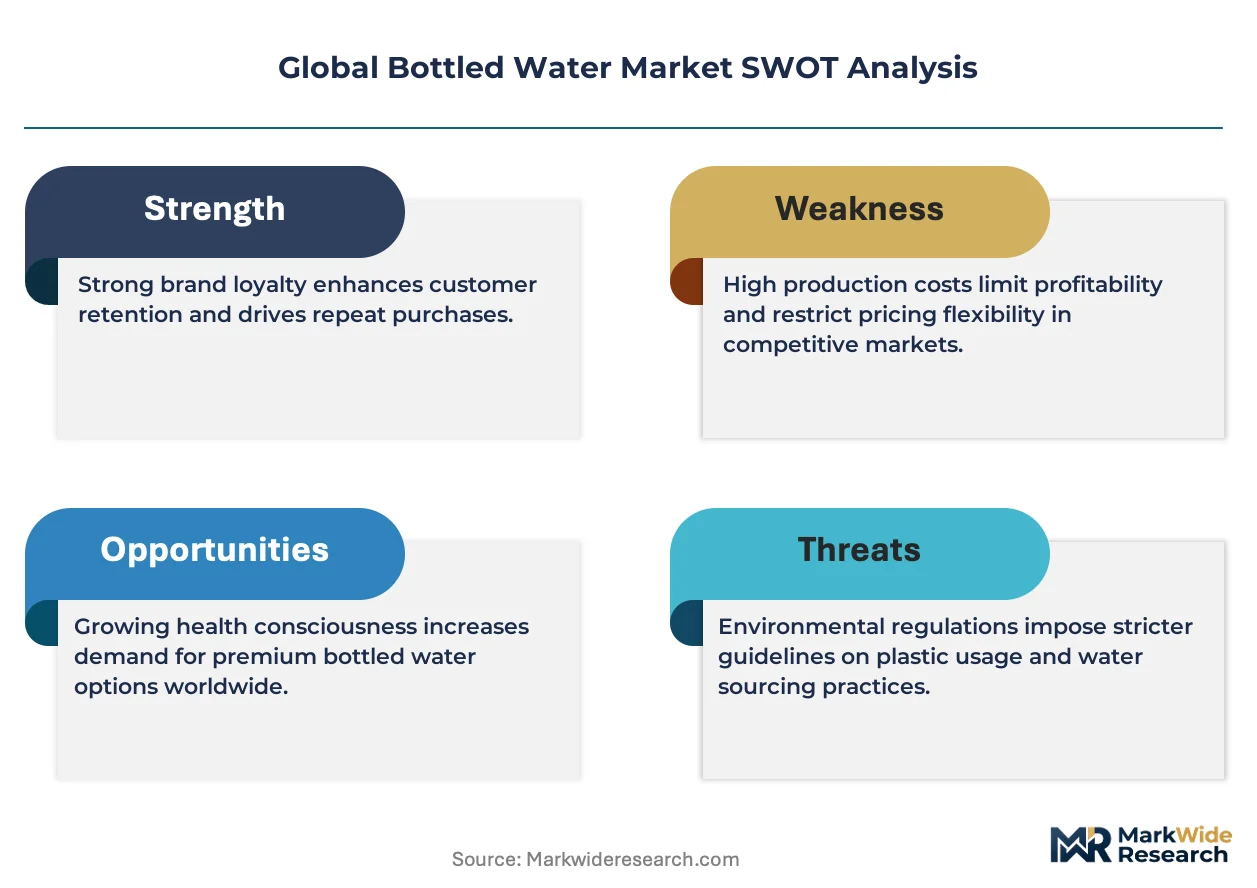
- EU Green Deal packaging mandates:The EU's binding recycled-content quotas and extended producer responsibility frameworks are forcing material substitution investments that favor compliant producers with pre-positioned recycling partnerships.
- Fitness culture proliferation:Sports end-users in North America and Western Europe are driving functional water procurement through institutional channels and direct-to-consumer subscription models.
- Reverse osmosis cost compression:Membrane efficiency gains are enabling source-flexible production in water-stressed regions previously dependent on fixed spring assets.
Market Restraints
- rPET feedstock scarcity:Food-grade recycled polymer supply concentrates in Germany, Italy, and France, creating input cost volatility for producers outside established collection infrastructure zones.
- Spring source registration timelines:China's SAMR mineral source certification protocols impose multi-year approval windows that lock out new entrants from premium positioning.
- Tap water quality improvements:Municipal infrastructure investments in Germany, Japan, and Switzerland are narrowing the perceived quality gap for basic hydration needs.
Strategic Opportunities
- India's underpenetrated premium tier:Urban household income growth in Mumbai, Delhi, and Bangalore is creating first-time demand for certified mineral and sparkling categories previously absent from retail.
- Carton-based ambient distribution:SIG and Tetra Pak formats are penetrating European convenience retail through shelf-stable logistics that bypass cold-chain constraints.
- US IRA clean manufacturing credits:Domestic recycled-content production incentives are offsetting capital costs for integrated bottling and rPET processing facilities.
Industry Challenges
- Food-grade rPET purification expertise:Bottle-to-bottle recycling requires specialized decontamination engineering talent concentrated in German and Dutch technical institutes.
- Legacy asset stranding:Single-use PET blow-molding capacity in Eastern Europe faces accelerated obsolescence under tightening EPR fee structures.
- Blockchain provenance integration:Mineral source traceability systems must interface with incompatible retailer data protocols across Carrefour, Tesco, and Walmart networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bottled Water Market |
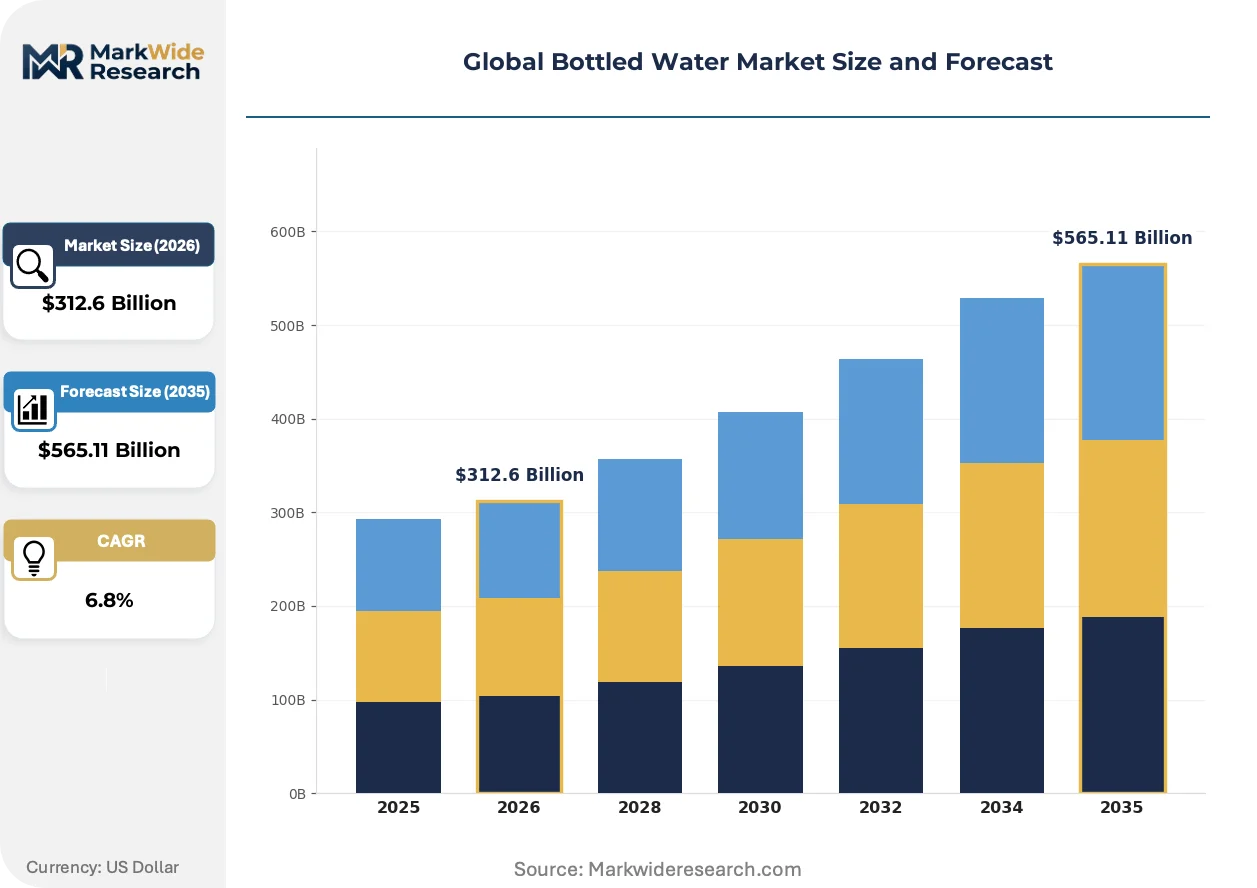
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
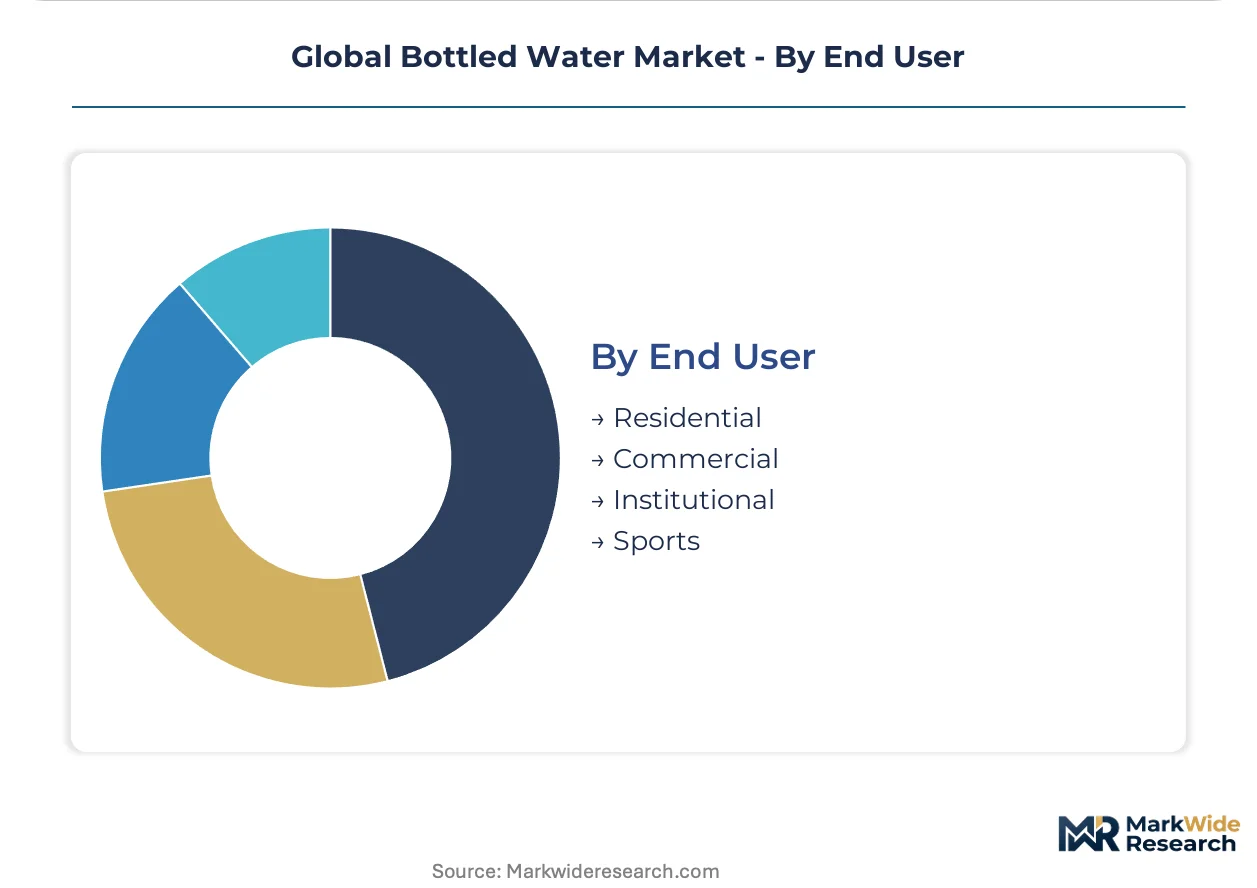
| Segmentation | Product Type: Sparkling, Still, Flavored, Mineral Packaging Type: Plastic Bottles, Glass Bottles, Cartons, Pouches Distribution Channel: Supermarkets, Convenience Stores, Online, Vending Machines End User: Residential, Commercial, Institutional, Sports |
| Companies Covered | Nestlé, The Coca-Cola Company, PepsiCo, Danone, Nongfu Spring, Primo Water Corporation, Gerolsteiner Brunnen, Tata Consumer Products Limited, National Beverage Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bottled Water Market Emerging Trajectories
Material science breakthroughs and regulatory compliance architectures are converging to redefine production economics and consumer value propositions across still, sparkling, and functional water categories.
Advanced barrier coating technologies for paper-based bottles are unifying structural integrity with fiber recyclability. Premium retail buyers in France and the Netherlands are piloting these formats at 15-20% price premiums. The technology is unifying sustainability messaging with supply chain flexibility, allowing regional producers to bypass PET import dependencies.
REACH polymer registration expansions are tightening additive disclosure requirements for European bottlers. Compliance costs are diverting R&D budgets toward pre-approved material libraries. Still water producers with direct spring access face lighter testing burdens than purified water operators using municipal source inputs.
Bulk pantry loading behaviors have compressed purchase cycles toward multi-case e-commerce fulfillment. Amazon and dedicated beverage subscription platforms are displacing traditional wholesale club channels for household replenishment. This pattern is most visible in US suburban markets where delivery density optimizes per-unit logistics costs.
Global Bottled Water Market Segmentation

Segmentation in bottled water tracks how hydration occasions fragment across consumption contexts, packaging preferences, and channel access points. Understanding these divisions reveals where margin pools concentrate and where volume expansion meets infrastructure constraints.
Product Type:
Upgrade cycles in bottled water follow shifting health positioning and carbonation technology accessibility, with consumers trading up from basic hydration to functional or experiential formats.
- Still:Non-carbonated purified or spring water dominates bulk procurement through reverse osmosis or natural filtration. Residential pantry loading in the United States and Germany drives multi-case e-commerce fulfillment, though municipal tap quality improvements in Switzerland and Japan compress premium pricing power for basic variants.
- Sparkling:Carbonated natural mineral water or CO2-injected purified water commands higher per-unit margins due to pressurized bottling infrastructure and source provenance requirements. Demand concentrates in France, Italy, and Germany where dining culture integrates sparkling service, with German retailers expanding private-label offerings to capture price-sensitive trial.
- Flavored:Zero-calorie essence-infused waters differentiate against carbonated soft drinks through natural flavor positioning. Sports end-users in North America drive institutional procurement of functional variants with electrolyte or vitamin fortification.
- Mineral:Naturally sourced water with certified mineral content requires spring registration and geological surveying compliance. China's SAMR mineral source certification protocols impose multi-year approval windows that protect incumbent positions.
Still sits at the top of the volume ranking, with Flavored climbing the fastest.
Packaging Type:
Cost tier stratification in bottled water packaging separates mass-market convenience from sustainability-premium positioning, with material transitions accelerating under regulatory pressure.
- Plastic Bottles:PET blow-molded containers occupy the mass-market tier through lightweight logistics and cold-chain compatibility. EU Green Deal recycled-content quotas are forcing rPET feedstock investments that favor producers with German, Italian, or French collection infrastructure access.
- Glass Bottles:Returnable and single-use glass formats sustain premium positioning in European foodservice and retail through source provenance signaling. French and Dutch retailers pilot advanced barrier-coated paper alternatives at 15-20% price premiums, pressuring glass share in sustainability-conscious segments.
- Cartons:SIG and Tetra Pak formats penetrate European convenience retail through shelf-stable ambient distribution that bypasses refrigeration requirements. Carton-based logistics enable regional producers to bypass PET import dependencies in water-stressed markets.
- Pouches:Flexible film packaging serves institutional and sports bulk dispensing with reduced shipping weight. Pouch formats face limited retail penetration due to shelf presentation constraints and consumer handling preferences.
Plastic Bottles maintains dominant volume share, though Glass Bottles gains share fastest in premium European channels.
Distribution Channel:
Application-based channel selection in bottled water matches purchase urgency with fulfillment economics, from immediate consumption to planned replenishment.
- Supermarkets:Multi-brand shelf sets and promotional bundling drive household stock-up behavior. German and French hypermarkets anchor volume through private-label spring water and imported mineral varieties.
- Convenience Stores:Immediate consumption occasions and impulse hydration needs concentrate in urban transit corridors and fuel retail. Japanese convenience chains integrate seasonal limited editions to sustain traffic.
- Online:Subscription replenishment and bulk pantry loading compress purchase cycles toward multi-case fulfillment. Amazon and dedicated beverage platforms displace wholesale club channels in US suburban markets where delivery density optimizes logistics.
- Vending Machines:Cold bottled water access in offices, transit hubs, and recreational facilities serves unplanned demand. Vending operators in Italy and Spain face margin pressure from rising electricity costs for refrigeration.
Supermarkets leads channel volume, with Online expanding most quickly through subscription mechanics.
End User:
Customer type segmentation in bottled water reveals how hydration needs diverge across private consumption, commercial service, and institutional provisioning contexts.
- Residential:Household pantry loading and daily hydration routines drive multi-format procurement from bulk still to premium sparkling. US and German households shift toward e-commerce subscription for core replenishment.
- Commercial:Foodservice, hospitality, and workplace provisioning require reliable supply contracts with format flexibility. French restaurant culture sustains glass-bottle mineral water placement despite cost premiums.
- Institutional:Healthcare, education, and government facilities prioritize cost control and safety certification over brand differentiation. Institutional buyers in India source bulk purified water through tender-based procurement.
- Sports:Fitness culture proliferation drives functional water demand through gyms, events, and direct-to-consumer athletic positioning. North American sports end-users procure enhanced electrolyte variants through institutional channels and subscription models.
Residential commands the largest volume base, with Sports showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The bottled water industry traces its modern mass-market origins to 19th-century European mineral springs, with France and Germany establishing the first commercial bottling operations that defined premium source-provenance marketing still used today.
United States
Suburban pantry loading and fitness culture proliferation drive multi-case e-commerce fulfillment through Amazon and dedicated beverage platforms. The FDA enforces quality standards under 21 CFR 165.110 while IRA clean manufacturing credits offset recycled-content production costs. Texas and California host integrated bottling and rPET processing clusters expanding under domestic incentive programs.
China
Urban household income growth in Beijing, Shanghai, and Guangzhou creates first-time demand for certified mineral categories. SAMR mineral source certification protocols impose multi-year approval windows protecting incumbent positions. The Yangtze River Delta concentrates volume production leveraging membrane efficiency gains for source-flexible operations.
Germany
Sparkling water dining culture and municipal tap quality improvements create bifurcated demand for premium mineral versus basic variants. EU Green Deal recycled-content quotas and EPR frameworks force material substitution investments. The Rhineland and Bavaria anchor food-grade rPET purification expertise concentrated in regional technical institutes.
India
Mumbai, Delhi, and Bangalore generate underpenetrated premium tier demand as certified mineral and sparkling categories enter retail for the first time. FSSAI governs packaged drinking water standards while BIS certification requirements shape quality compliance costs. Institutional buyers in Maharashtra and Karnataka source bulk purified water through tender-based procurement systems.
France
Restaurant culture sustains glass-bottle mineral water placement despite cost premiums, while advanced barrier-coated paper alternatives pilot at 15-20% price premiums in Paris and Lyon retail. REACH polymer registration expansions tighten additive disclosure requirements for bottlers. The Auvergne-Rhône-Alpes region hosts spring network infrastructure supporting premium positioning.
Global Bottled Water Market Vendor Landscape
Premium-margin players sit above commodity-margin players across source-provenance and packaging material dimensions, with the market consolidating around scale-driven multinationals and regional spring specialists. Tiered competition separates global beverage conglomerates with distribution muscle from mineral-source incumbents leveraging geological exclusivity. Three archetypes dominate: multinational diversified beverage groups, European spring-network specialists, and Asian source-integrated regional champions. Competitive moves concentrate on recycled-content packaging partnerships and direct-to-consumer subscription platform buildouts.
Among diversified beverage conglomerates, Nestlé and The Coca-Cola Company exemplify scale-driven archetypes spanning multiple hydration formats and geographies. PepsiCo occupies a complementary position with portfolio breadth across still and flavored lines. These three entities represent the dominant competitive anchors structuring tiered market access and retail shelf allocation dynamics.
| Leading Market Players |
|---|
| Nestlé |
| The Coca-Cola Company |
| PepsiCo |
| Danone |
| Nongfu Spring |
| Primo Water Corporation |
| Gerolsteiner Brunnen |
| Tata Consumer Products Limited |
| National Beverage Corp |
| Others |
Supply Flow & Price Mechanics
The EU Green Deal's recycled-content quotas and extended producer responsibility frameworks gate both qualified supply and premium-tier pricing access. Producers with pre-positioned German, Italian, or French collection infrastructure capture margin premiums while outsiders face feedstock cost volatility that compresses pricing power in standard tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the market by source provenance and packaging material. Price differentiation rests on mineral certification grade and rPET content percentage, with glass and carton formats commanding 15-20% premiums in European retail. Pricing pressure stems from municipal tap quality improvements in Germany, Japan, and Switzerland that erode basic still water margins. Institutional buyers in India and sports end-users in North America exhibit highest price sensitivity, while French restaurant channels show lowest sensitivity due to cultural placement requirements.
Supply Chain Analysis
Dual-sourcing mandates from major retailers require producers to qualify multiple rPET suppliers across Germany, Italy, and France to mitigate feedstock disruption risk. Raw material dependencies center on food-grade recycled polymer, virgin PET resin, and advanced barrier coatings for paper-based alternatives. Single-source vulnerability concentrates in German and Dutch technical institutes holding bottle-to-bottle decontamination expertise. Distribution runs through integrated bottling and recycling clusters in Texas, California, and China's Yangtze River Delta, with ambient carton logistics bypassing cold-chain constraints in European convenience retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers geographic-arbitrage returns through rPET processing cost differentials between US IRA credit zones and EU EPR fee structures. Producers can capture 15-25% capital cost advantages by siting integrated facilities in domestic incentive corridors versus European compliance-heavy environments.
For Market Incumbents: Anchor premium positioning through exclusive spring network control in France's Auvergne-Rhône-Alpes and Germany's Rhineland. Defend against private-label encroachment by accelerating backward integration into rPET purification capacity. Lock in multi-year supply contracts with Carrefour, Tesco, and Walmart before deposit-return scheme expansions reshape packaging economics. Prioritize blockchain provenance systems that interface with incompatible retailer data protocols to create switching costs. For New Entrants and Emerging Players: Urban households in Mumbai, Delhi, and Bangalore represent the most penetrable buyer archetype for first-time certified mineral and sparkling categories. Exploit underpenetrated premium tiers through direct-to-consumer subscription platforms that bypass established wholesale club channels. Target sports end-users with functional electrolyte variants via institutional procurement relationships and gym placement partnerships. Launch with SIG or Tetra Pak formats to bypass PET import dependencies and cold-chain infrastructure gaps. For Investors and Strategic Acquirers: Roll-up economics work for regional spring specialists with SAMR-registered mineral sources because China's multi-year certification protocols protect incumbent positions from new supply. Acquire assets with pre-qualified European rPET partnerships to capture compliance premiums under tightening EPR frameworks. Monitor US IRA credit permanence and EU Green Deal enforcement timelines as inflection indicators for capital allocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| rPET Processing Capacity Expansion | Captures EU Green Deal compliance premiums and IRA credit offsets in Texas and California clusters. |
| Direct-to-Consumer Subscription Launch | Displaces Amazon and wholesale club channels through delivery density optimization in US suburban markets. |
| Mineral Source Certification Investment | Locks out competitors through SAMR multi-year approval windows protecting China's premium tier. |
| Carton-Based Ambient Distribution | Bypasses PET import dependencies and refrigeration costs via SIG and Tetra Pak European convenience penetration. |
| Blockchain Provenance Integration | Interfaces with Carrefour, Tesco, and Walmart data protocols to secure premium retail placement. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged bottling plant managers, retail category buyers at Carrefour and Walmart, rPET procurement leads, and FSSAI regulatory affairs officers. Secondary validation drew from FDA 21 CFR filings, EU ECHA REACH registrations, SAMR mineral source databases, and Nielsen retail audit data. Bottom-up volume builds across product type, packaging material, distribution channel, and end-user segments triangulated against top-down macroeconomic anchors.
Historical reference periods spanning the pre-pandemic baseline through post-regulatory implementation phases anchored the forecast window. The analytical framework modeled still, sparkling, flavored, and mineral categories across plastic, glass, carton, and pouch formats, with supermarket, convenience, online, and vending channel splits. CAGRs derived from segment-level growth drivers including fitness culture proliferation, EU packaging mandates, and membrane efficiency gains in water-stressed regions. Regional forecasts incorporated country-specific EPR fee trajectories and IRA credit availability.
Underlying measurement precision varies by segment; established PET and still water categories carry tighter precision than emerging paper-bottle and functional water variants. Forecasts assume continued EU Green Deal enforcement, stable rPET collection infrastructure expansion, and no abrupt relaxation of China's mineral source certification protocols. Deviation in IRA credit permanence or SAMR approval timeline acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
GCC Bottled Water Market
Beverages
North America Dairy Beverages Market
Beverages
China Soy Beverages Market
Beverages
Middle East and Africa Fruits and Vegetable Juice Market
Beverages
Peanut Oil Market
Beverages
Recovery Drinks Market
Beverages
Soft Serve Premix Market
Beverages
Probiotic Beverage Market
Beverages
Global Soft Drinks Concentrate Market
Beverages
Europe Juices Market
Beverages
Beverage Dispenser Market
Beverages
Powdered Soft Drinks Market
Beverages
Hydrogen Water Dispenser Market
Beverages
Latin America Sports and Energy Drinks Market
Beverages
Global Electrolyte Drinks Market
Beverages
Sparkling Water Market