
 Global Cloud Based Collaboration Software Market | 2026-2036
Global Cloud Based Collaboration Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cloud Based Collaboration Software Market Intelligence
Demand from small and medium-sized businesses for integrated collaboration suites is rotating market focus away from siloed, enterprise-only solutions. Microsoft leverages its dominant Office suite to bundle Teams and expand its user base. Atlassian specializes in project management and developer-centric tools like Jira and Confluence. Salesforce positions its Slack platform as a central hub for customer-centric business communication.
Cloud based collaboration software refers to applications delivered via a software-as-a-service model, enabling real-time interaction and file sharing across distributed teams. These platforms utilize cloud infrastructure for data storage and synchronization, accessible through standard web browsers. Within the solution segment, integrated suites that combine project management and workflow automation are becoming standard over standalone video conferencing tools. The information technology end-user industry constitutes the largest user base, while adoption within government agencies is accelerating due to digital transformation initiatives.
Data governance regulations like Europe's GDPR and the US's HIPAA mandate strict controls on how personal and sensitive information is handled and stored on these platforms. Compliance with data residency requirements in jurisdictions such as China and India shapes platform architecture and deployment options for providers. Vendor success will increasingly depend on the ability to embed generative AI capabilities securely within collaborative workflows to enhance productivity.
Market Dynamics
The central tension shaping the market is the conflict between demands for frictionless, open-ended collaboration and the stringent requirements of data governance. This forces platform providers to engineer solutions that are both highly accessible and compliant with complex, fragmented regulations.
Growth Catalysts
- Digital Transformation Initiatives:Government and public sector adoption is accelerating, driven by mandates for improved efficiency and citizen service delivery, creating new, large-scale deployment opportunities.
- Expansion of Remote Work:The structural shift to hybrid and fully remote work models across industries like information technology and financial services necessitates investment in robust, scalable collaboration infrastructure.
- Integrated Suite Demand:Small and medium-sized businesses are increasingly seeking all-in-one platforms that combine communication, project management, and workflow automation, lowering the total cost of ownership.
Market Restraints
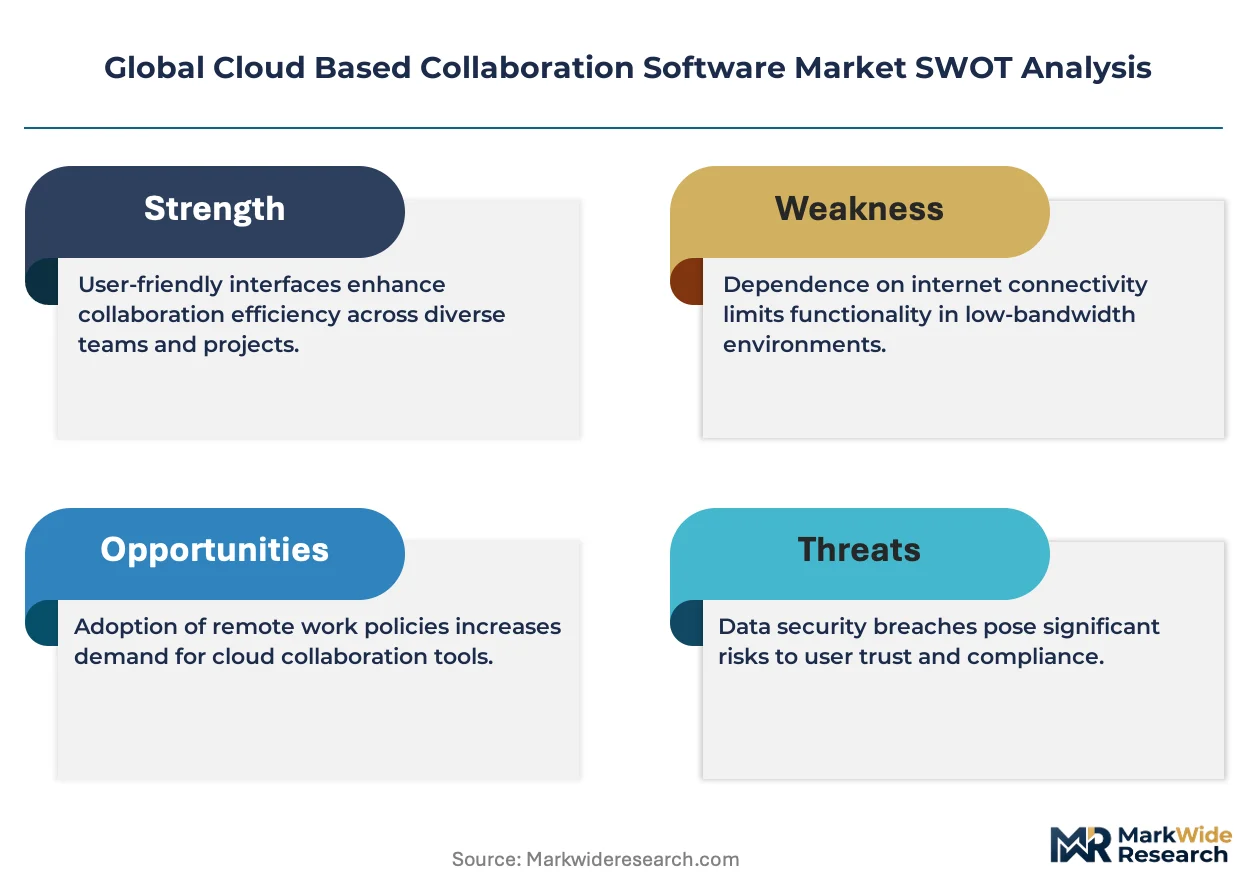
- Data Residency Laws:Strict data localization mandates in jurisdictions like China and India, alongside Europe's GDPR, impose significant architectural and operational costs on global platform providers.
- Vendor Lock-In:High switching costs associated with migrating data, retraining users, and re-establishing integrations between deeply embedded collaboration suites and other enterprise systems deter customers from changing providers.
- Security Vulnerabilities:The centralization of sensitive corporate data on cloud platforms makes them high-value targets for cyberattacks, raising security concerns among enterprises in regulated industries.
Strategic Opportunities
- Vertical-Specific Solutions:Developing tailored collaboration platforms for industries with unique compliance and workflow needs, such as healthcare with HIPAA requirements or legal services, presents a significant growth vector.
- Generative AI Integration:Embedding secure generative AI capabilities to automate meeting summaries, generate project plans, and assist in content creation offers a path to significant productivity gains and feature differentiation.
- Emerging Market Penetration:Targeting technology and business process outsourcing hubs in countries like India and the Philippines provides access to a large, concentrated base of new users.
Industry Challenges
- Interoperability Complexity:Ensuring seamless functionality between a primary collaboration suite and a multitude of third-party, best-of-breed applications remains a persistent technical and user experience challenge for enterprise IT departments.
- Cybersecurity Talent Gap:A shortage of skilled security professionals capable of managing and defending complex, multi-cloud collaboration environments against sophisticated threats constrains secure adoption for many organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cloud Based Collaboration Software Market |
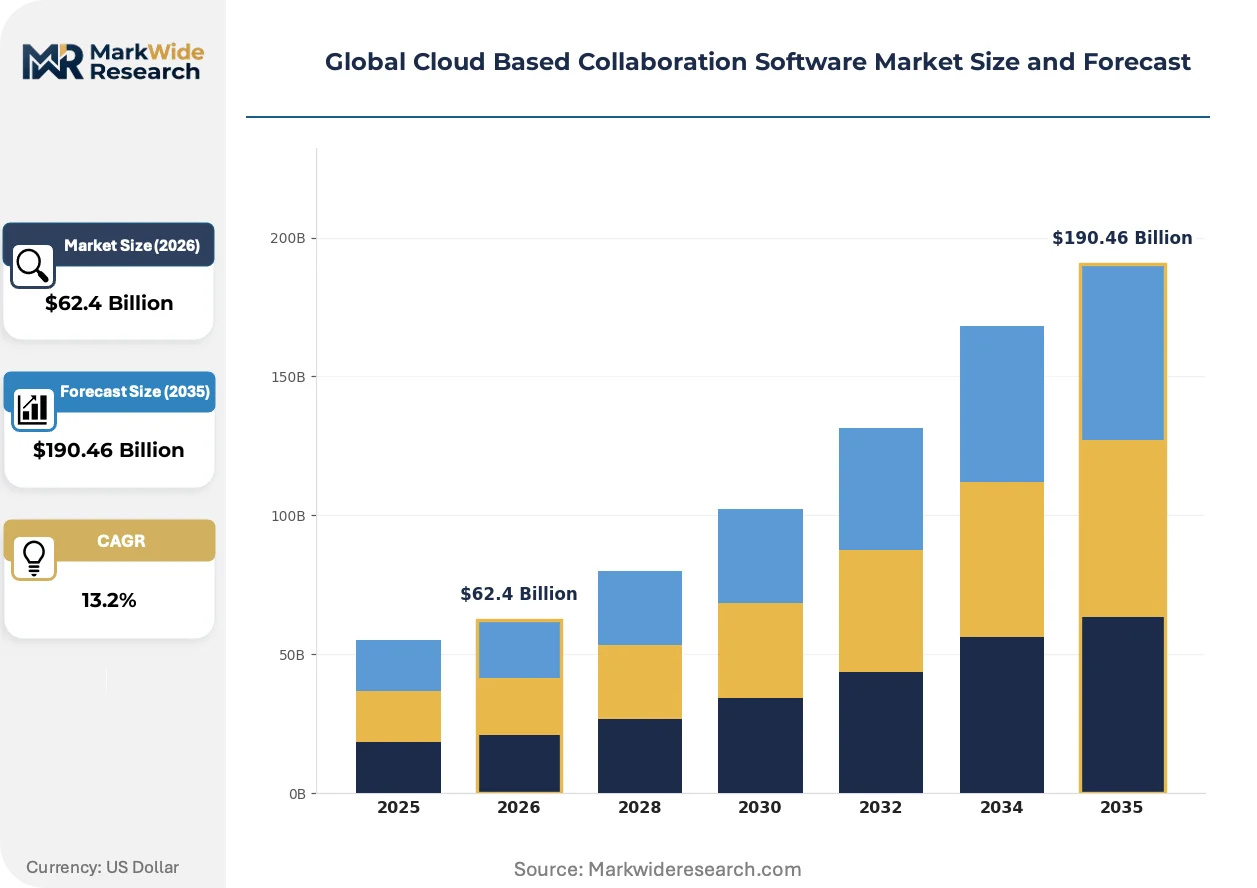
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $190.46 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Solution: Project Management, Video Conferencing, Document Sharing, Team Messaging, Workflow Automation Application: Remote Workforce Enablement, Virtual Training, Cross-Team Communication, Content Co-creation, Task Coordination End User Industry: Information Technology, Media Agencies, Financial Services, Education Institutions, Government Agencies |
| Companies Covered | Microsoft Corporation, Google LLC, Cisco Systems, Inc., Zoom Video Communications, Inc., Salesforce, Inc., Atlassian Corporation Plc, IBM Corporation, Oracle Corporation, Box, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cloud Based Collaboration Software Market Strategic Shifts & Innovations
The evolution of collaboration platforms is defined by the infusion of intelligence and a deeper focus on security. Functionality is shifting from simple real-time communication toward predictive, automated work environments that are compliant by design, fundamentally altering user workflows and productivity expectations.
Generative AI serves as the core enabling technology for next-generation features. The financial services and technology sectors are rapidly adopting tools that automate routine tasks like summarizing meetings and drafting communications. This trend is miniaturizing the role of the user as a manual data processor, elevating their function to strategic oversight and exception handling.
Europe's AI Act introduces a risk-based framework for artificial intelligence systems, directly impacting collaboration software vendors. This regulation forces providers to build auditable, transparent, and explainable AI features to comply with new legal obligations. The enterprise software segment, particularly vendors selling into the EU, is proactively developing governance tools and "responsible AI" frameworks in response.
A notable shift in purchasing behavior involves the move from centralized, IT-led procurement to decentralized, departmental-level adoption. This pattern disrupts the traditional enterprise-wide licensing model in favor of more agile, needs-based tool selection by individual teams. This trend is most prominent within the marketing and software development verticals in North America, where specialized tools are valued over monolithic platforms.
Global Cloud Based Collaboration Software Market Segmentation
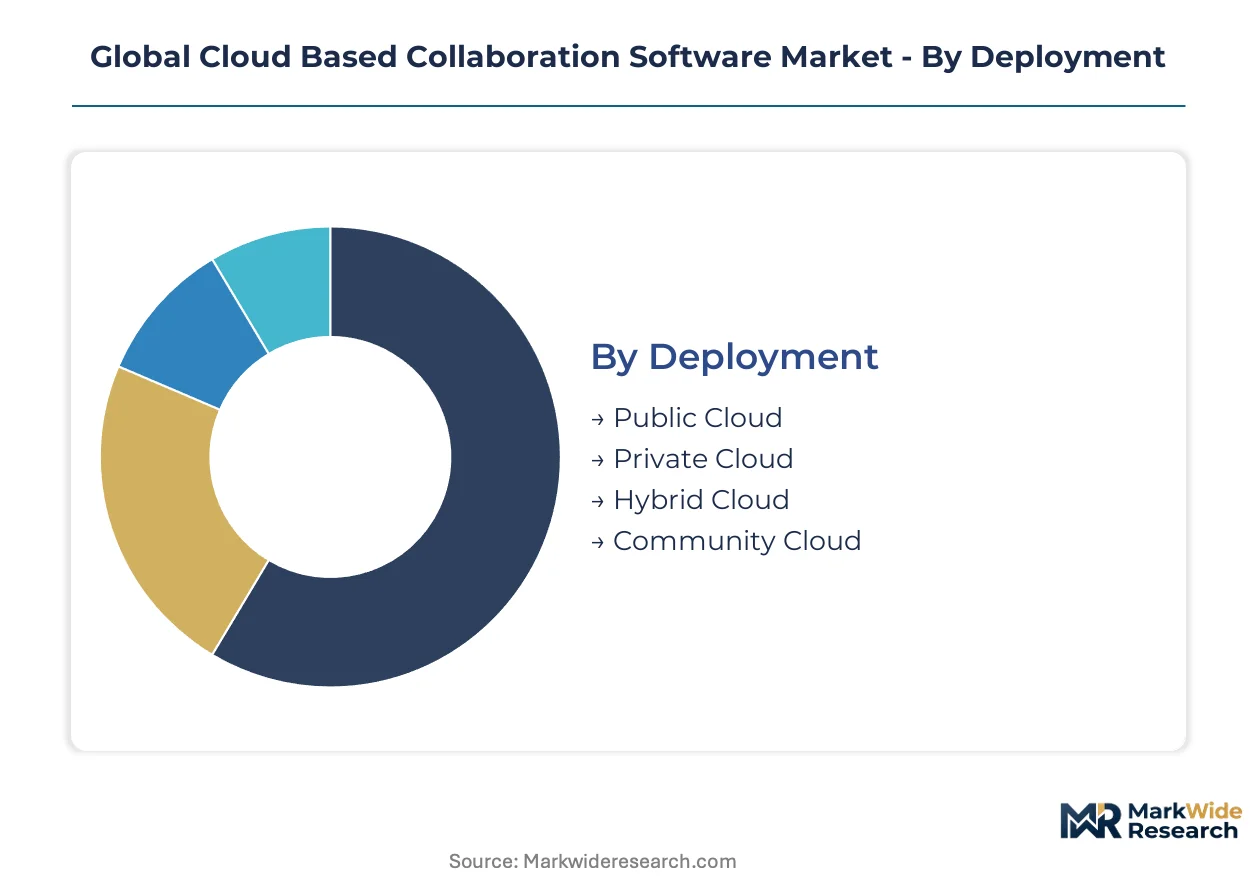
The segmentation analysis for the global cloud based collaboration software market reveals distinct demand patterns and compliance requirements across various deployment models, solution types, applications, and end-user industries. Understanding these granular divisions helps providers tailor offerings and navigate the complex regulatory landscape. This detailed breakdown highlights areas of concentrated value creation.
Deployment:
Margin pools within the deployment category sit highest in specialized, secure environments that cater to stringent regulatory needs.
- Public Cloud:Services delivered over the open internet, shared across multiple customers with multi-tenant architecture. Demand concentrates in small and medium-sized businesses across India and other emerging markets due to lower operational costs and rapid scalability.
- Private Cloud:Dedicated infrastructure exclusively for a single organization, managed internally or by a third party for enhanced control. Financial services and government agencies in the US and Europe drive demand for enhanced security and compliance with data governance regulations like HIPAA and GDPR.
- Hybrid Cloud:Combines public and private cloud environments, allowing data and applications to move seamlessly between them.
- Community Cloud:Shared infrastructure among organizations with common concerns, such as specific security or compliance requirements, fostering industry-specific collaboration.
Public Cloud holds installed capacity. Hybrid Cloud is rotating up the share rankings.
Solution:
Demand for integrated functionalities shapes the solution landscape, driving consolidation across various tools.
- Project Management:Tools facilitating planning, execution, and tracking of tasks within a project lifecycle, often incorporating agile methodologies. Demand is strong in the technology sector, particularly for software development teams that necessitate structured collaboration and version control.
- Workflow Automation:Platforms that streamline and automate repetitive business processes and tasks through predefined rules and integrations. Financial services organizations utilize these solutions to ensure compliance and increase operational efficiency across global teams, reducing manual errors.
- Video Conferencing:Real-time visual and audio communication platforms supporting virtual meetings and presentations for distributed teams.
- Document Sharing:Systems enabling secure storage, access, and collaborative editing of files among distributed teams.
- Team Messaging:Instant communication applications designed for group discussions and quick information exchange within organizations.
Integrated suites are expanding most quickly. Standalone video conferencing tools face displacement.
Application:
Customer type and operational criticality define application segment value within diverse organizational contexts.
- Remote Workforce Enablement:Supports employees working outside traditional office settings with necessary communication, file sharing, and productivity tools. Demand is high across industries like information technology, driven by the structural shift to hybrid work models and the need for seamless connectivity.
- Cross-Team Communication:Facilitates seamless interaction and information flow between different departments or project groups within an organization, breaking down silos. Adoption is critical for large enterprises managing complex, multi-disciplinary initiatives requiring unified messaging.
- Virtual Training:Platforms used for delivering educational content and interactive sessions to remote participants across various sectors.
- Content Co-creation:Tools allowing multiple users to simultaneously contribute to and edit shared documents or media files.
- Task Coordination:Software designed to assign, track, and manage individual or team tasks to ensure project milestones are met efficiently.
Remote Workforce Enablement sees the steepest expansion trajectory. Virtual Training maintains steady demand.
End User Industry:
Regulatory intensity and digital maturity distinguish end-user industry segments, influencing platform requirements.
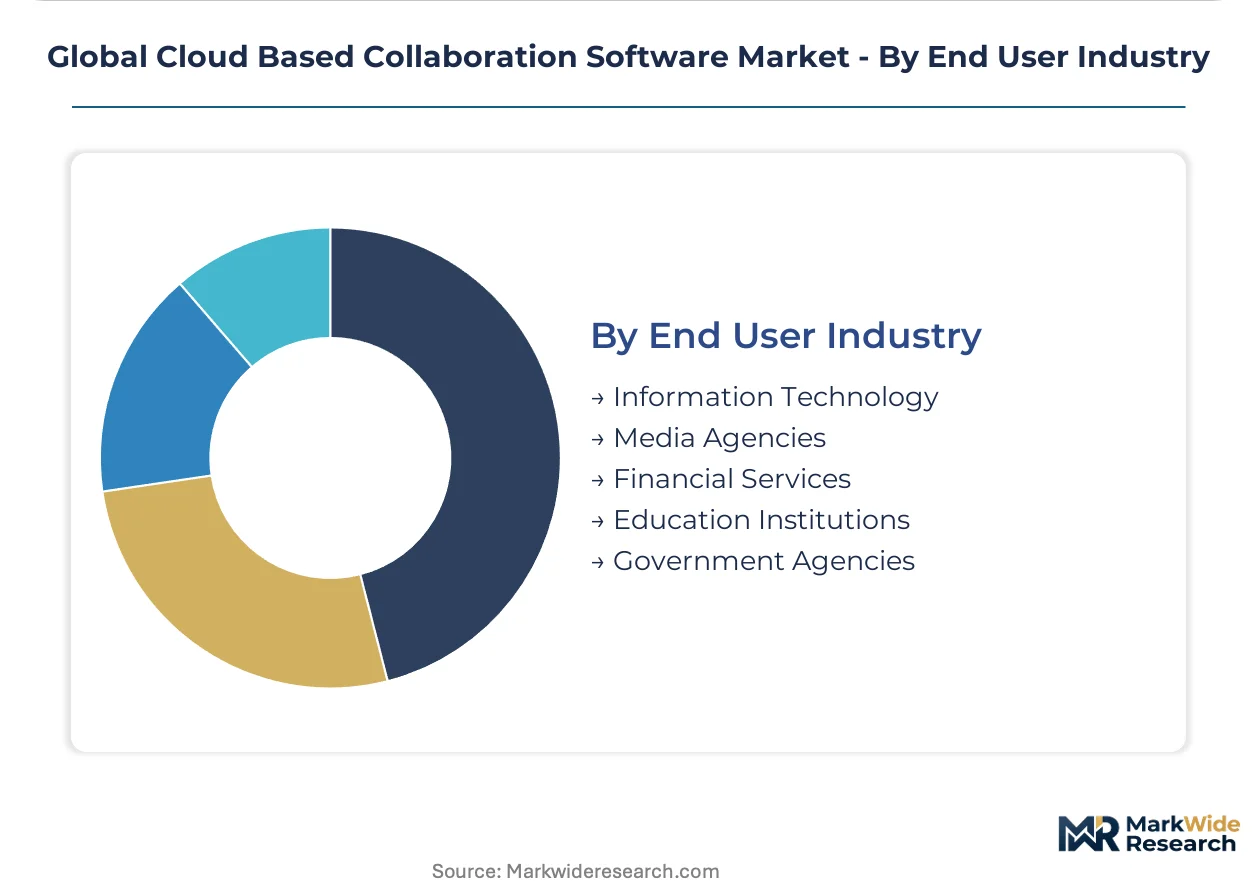
- Information Technology:The largest end-user segment, comprising software development, IT services, and hardware companies globally. These firms require advanced collaboration tools to manage geographically dispersed teams and complex development cycles efficiently.
- Financial Services:Includes banking, insurance, and investment firms that demand highly secure and compliant cloud collaboration platforms. Expansion is pronounced due to stringent data governance regulations like GDPR and HIPAA, necessitating robust data handling.
- Media Agencies:Organizations involved in advertising, publishing, and digital content creation, requiring tools for creative collaboration.
- Education Institutions:Schools, colleges, and universities leveraging cloud platforms for remote learning and administrative coordination.
- Government Agencies:Public sector entities adopting collaboration software for digital transformation and improved citizen service delivery.
Information Technology anchors enterprise spending. Government Agencies are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for cloud-based collaboration software flows significantly from technology and outsourcing hubs in countries like India, while major providers and adopters are concentrated in the United States and Europe. This global market expansion is driven by diverse regulatory landscapes and varying digital maturity levels. Countries with strong financial services sectors exhibit pronounced needs for secure, compliant platforms.
United States
Digital transformation initiatives in financial services and the structural shift to remote work models drive significant demand for collaboration software. HIPAA mandates strict data handling protocols, pushing providers to offer enhanced security features. Technology clusters in Silicon Valley and New York City continue to lead innovation and adoption for advanced collaboration tools.
Germany
Enterprise adoption for workflow automation and integrated suites supports market expansion across German industries. Europe's GDPR dictates stringent data protection and privacy standards for all cloud-based platforms operating within the country. Major industrial centers like Munich and Berlin are investing in secure, compliant solutions for distributed teams.
India
The expansion of India's technology and outsourcing industries fuels robust demand for scalable, cost-effective collaboration solutions. Strict data residency requirements influence platform architecture and deployment options for global vendors. Bengaluru and Hyderabad, as major tech hubs, represent concentrated user bases for these services.
China
Data residency laws and government digital transformation initiatives shape the competitive landscape for cloud collaboration software within China. Local providers often dominate due to specific regulatory compliance and cultural preferences. Major urban centers such as Shanghai and Beijing are rapidly adopting cloud-based tools for public sector and enterprise use.
United Kingdom
Financial services and hybrid work models generate substantial demand for secure and integrated collaboration platforms across the United Kingdom. Data governance regulations, influenced by GDPR, require providers to ensure robust data protection and residency options. London's financial district and technology firms in Manchester are key adopters of advanced collaborative technologies.
Global Cloud Based Collaboration Software Market Key Industry Players
Player mix skews toward established software giants and specialized platform providers, creating a tiered market structure. The competitive environment includes large technology conglomerates offering broad integrated suites, alongside agile niche players focused on specific functionalities like project management or developer tools. Dominant competitive moves involve embedding generative AI capabilities and forming strategic partnerships to expand ecosystem integration.
Specialists in integrated collaboration suites include Microsoft Corporation, which leverages its extensive Office ecosystem to bundle communication and productivity tools. Atlassian Corporation Plc occupies a position as a provider of project management and developer-centric solutions like Jira and Confluence. Salesforce, Inc. exemplifies a customer-centric approach, positioning its Slack platform as a central communication hub for business operations.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Google LLC |
| Cisco Systems, Inc. |
| Zoom Video Communications, Inc. |
| Salesforce, Inc. |
| Atlassian Corporation Plc |
| IBM Corporation |
| Oracle Corporation |
| Box, Inc. |
| Others |
Cost & Logistics Intelligence
The 90-day implementation lead time for compliant cloud collaboration suites directly influences platform pricing power, especially in highly regulated sectors where specialized infrastructure is required.
Pricing Analysis
The current-generation pricing for integrated collaboration suites reflects a SaaS-tiered model, often based on user count and feature sets. Price differentiation stems from the level of customization offered and the robustness of embedded security features. Pricing softness reflects intense competition from bundled offerings by large technology conglomerates. Financial services and government agencies exhibit the least price sensitivity, prioritizing compliance and security, while small and medium-sized businesses remain highly price-sensitive.
Supply Chain Analysis
The critical chokepoint of global data center capacity, heavily concentrated in the United States and Ireland, underpins the delivery of cloud collaboration software. The supply chain draws from cloud infrastructure providers and a global pool of developer talent, particularly in India. Data residency compliance poses a significant structural risk for platform providers operating across multiple jurisdictions. Downstream distribution runs predominantly through direct SaaS subscriptions and channel partnerships, often leveraging hyperscaler marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global cloud-based collaboration software market stands as an early-cycle expansion story, buoyed by the sustained tailwind of digital transformation initiatives across industries.
For Market Incumbents:Consolidate core platform capabilities by integrating advanced generative AI features directly into workflow automation tools. This move counters the threat from agile niche AI startups and reinforces competitive positioning. Invest heavily in data governance frameworks and compliance certifications, leveraging existing enterprise client relationships. Deepen vertical integration into secure cloud infrastructure to control data residency options.
For New Entrants and Emerging Players:Differentiate on hyper-specialized compliance features for highly regulated verticals like healthcare or legal services. Target underpenetrated small and medium-sized businesses in emerging markets such as India with compliance-by-design solutions. An API-first go-to-market angle allows seamless integration with existing enterprise systems, reducing switching costs for potential customers. Focus on delivering tangible productivity gains through purpose-built AI tools.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting in an upward direction across specialized private cloud infrastructure providers supporting stringent data residency requirements. Long-term viability for collaboration platforms hinges on their ability to securely embed generative AI and navigate complex regulatory landscapes over the next decade. Acquisition targets should include AI-specialized startups with strong intellectual property in natural language processing and compliance technology firms. The signal to watch is the adoption rate of Europe's AI Act among enterprise software vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate Generative AI for Workflow Automation | Enhances user productivity and provides significant feature differentiation against competitors. |
| Develop Vertical-Specific Compliance Solutions | Captures market share in highly regulated sectors like financial services and healthcare. |
| Expand Private Cloud Deployment Options | Addresses stringent data residency and security requirements for government agencies. |
| Form Strategic Partnerships with Hyperscalers | Extends market reach and leverages established cloud infrastructure for scalability. |
| Invest in Cybersecurity Talent and Tools | Mitigates growing threats and reinforces trust among enterprise clients handling sensitive data. |
Research Approach
A standing panel of CTOs, IT procurement officers, compliance leads, and platform engineers provided ongoing calibration for market sizing and trend validation. The research methodology combined extensive primary interviews with rigorous secondary data analysis. This approach ensured a balanced perspective, triangulating insights from both market participants and published sources.
Consistency checks against external benchmarks, including government digital transformation spend reports and industry association surveys, validated the projected market trajectories over the projection horizon. The analytical framework modeled segmentation dimensions such as deployment model, solution type, end-user industry, and regional regulatory intensity. Compound annual growth rates were derived from historical data and forward-looking inputs, including AI integration rates and remote work adoption indices.
Decision-makers should treat outputs as directional under current macroeconomic stability and regulatory frameworks; material deviation would warrant model refresh and re-evaluation. Forecasts reflect assumptions regarding technological advancements and market adoption curves. Practitioners should keep alternative scenarios live as geopolitical shifts and new data privacy mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Driving School Software Market
Software & Services
Audio and Video Editing Software Market
Software & Services
Global Janitorial Software Market
Software & Services
Global Help Desk Software Market
Software & Services
Discount Management Software Market
Software & Services
Lease Accounting and Management Software Market
Software & Services
Global Development Tools Software Market
Software & Services
Global Business Software Market
Software & Services
Optical Design Software Market
Software & Services
User Feedback Software Market
Software & Services
Audit Management Software Market
Software & Services
Digital Painting Software Market
Software & Services
Workflow Management Software (WMS) Market
Software & Services
UK Point of Sale Software Market
Software & Services
Service Scheduling Software Market
Software & Services
Global Customer Experience Software Market