
 3D CAD Market | 2026-2036
3D CAD Market Size, Share, and Industry Trends Forecast 2026-2036
3D CAD Market Analysis
Shortage of simulation-trained mechanical engineers is collapsing project timelines for complex product development cycles. Autodesk Inc. leverages extensive educational partnerships to build pipeline capacity for parametric design competency. Siemens AG anchors industrial demand through tight integration between CAD, PLM, and manufacturing execution systems. Dassault Systèmes SE dominates high-complexity aerospace and automotive accounts with its CATIA ecosystem.
Three-dimensional computer-aided design software enables precise geometric modeling, surface definition, and assembly constraint management through NURBS-based kernels and parametric feature trees. Its primary commercial purpose is to compress product development cycles while enabling digital validation before physical prototyping. Cloud-based and SaaS deployment models represent the fastest-expanding segment as engineering organizations shed on-premises maintenance overhead. Software licensing for product design and simulation applications captures the deepest margin pools, while plugins and add-ons extend platform stickiness through specialized workflow automation.
FDA medical device design controls, EU MDR technical documentation requirements, and ISO 9001 quality management standards collectively mandate traceable design histories that elevate CAD platform selection criteria. REACH substance restrictions and RoHS compliance obligations further embed material data management within design environments. Stakeholders must monitor how AI-assisted generative design capabilities reshape workforce composition and platform switching costs.
Market Dynamics
Cloud-native architectures are compressing deployment cycles and redistributing competitive advantage toward platforms with elastic compute infrastructure. Engineering organizations now prioritize subscription economics over perpetual licenses, forcing established vendors to restructure pricing and partner ecosystems.
Growth Catalysts
- EU MDR technical documentation mandates:Medical device manufacturers in Germany and France require traceable design histories that elevate CAD platform selection criteria toward validated systems.
- Generative design algorithms:Topology optimization and AI-assisted form-finding are accelerating iteration velocity for automotive lightweighting programs in Stuttgart and Detroit.
- China dual carbon goals:MIIT efficiency standards for industrial machinery are compelling domestic OEMs to adopt simulation-integrated CAD for energy-optimized designs.
Market Restraints
- GPU compute cost volatility:Cloud rendering and real-time raytracing dependencies expose engineering teams to fluctuating infrastructure spend during peak project phases.
- NURBS kernel supplier concentration:Critical geometry engines originate from a narrow base of German and Japanese mathematical software specialists, creating single-source vulnerability.
- REACH substance data integration:Material compliance databases require continuous updating, adding friction to design workflows without direct productivity return.
Strategic Opportunities
- India PLI scheme for manufacturing:Production-linked incentives for industrial machinery and automotive components are expanding design software procurement budgets among Pune and Chennai engineering centers.
- Digital twin convergence with IoT:Real-time sensor feedback loops are opening new service revenue streams for CAD vendors in predictive maintenance applications.
- US IRA clean energy manufacturing:Tax credits for domestic battery and turbine production are accelerating greenfield facility design activity requiring advanced modeling capabilities.
Industry Challenges
- Parametric modeling expertise scarcity:Mechanical engineering programs graduate insufficient simulation-trained practitioners, extending hiring timelines for complex product development roles.
- Legacy PLM integration friction:Decades-old data architectures resist API connectivity, forcing expensive middleware development for hybrid cloud deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D CAD Market |
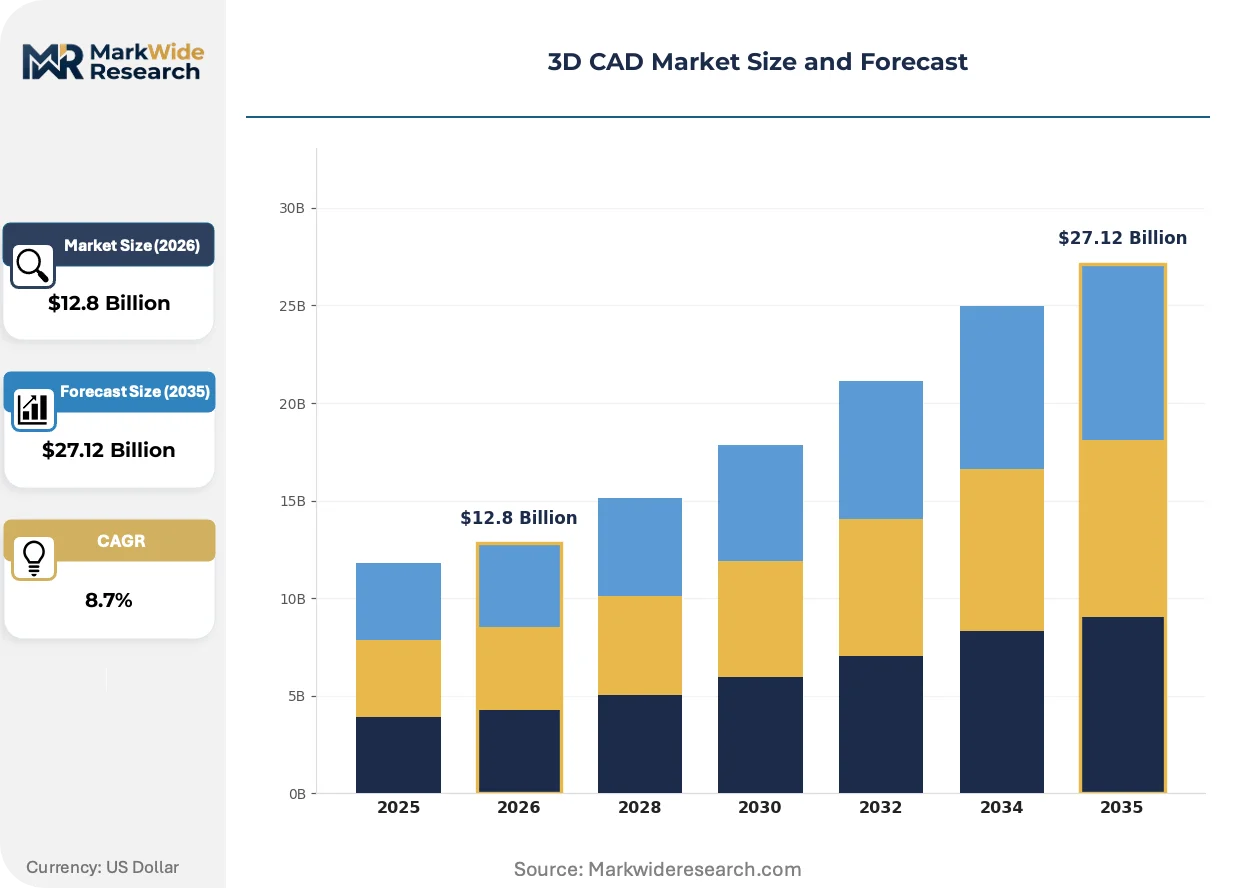
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Licensing, Plugins, Add-ons End User: Aerospace, Automotive, Architecture, Engineering Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS Application: Product Design, Prototyping, Simulation, Manufacturing |
| Companies Covered | Autodesk Inc., Dassault Systèmes SE, PTC Inc., Siemens AG, Bentley Systems Inc., Hexagon AB, Bricsys NV, ZWSOFT Co. Ltd., Trimble Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D CAD Market Emerging Trajectories
Real-time collaboration infrastructure is displacing file-based workflows across distributed engineering teams. Three converging developments are restructuring how geometric data moves between designers, analysts, and manufacturing planners.
Browser-native CAD kernels are fragmenting the traditional desktop software monopoly. Automotive suppliers in Bavaria now deploy lightweight modeling clients for supplier design reviews without full license overhead. This accessibility is compressing vendor switching costs and enabling multi-platform experimentation.
EU AI Act risk classification requirements are reshaping algorithmic design tool deployment. Generative features in high-risk medical device and aerospace applications now require documented training data provenance and human oversight protocols. German automotive OEMs are establishing internal AI governance boards ahead of enforcement timelines.
Subscription fatigue is altering enterprise negotiation posture. Procurement teams in US industrial machinery conglomerates are demanding consumption-based pricing tied to active user hours rather than seat counts. This metric shift favors platforms with granular usage telemetry and penalizes vendors with coarse licensing granularity.
3D CAD Market Segmentation
Segmentation in 3D CAD software reveals how purchasing power concentrates across license models, deployment architectures, and vertical workflows. Understanding these divisions exposes where vendors can defend pricing power versus where commoditization pressures intensify.
Product Type:
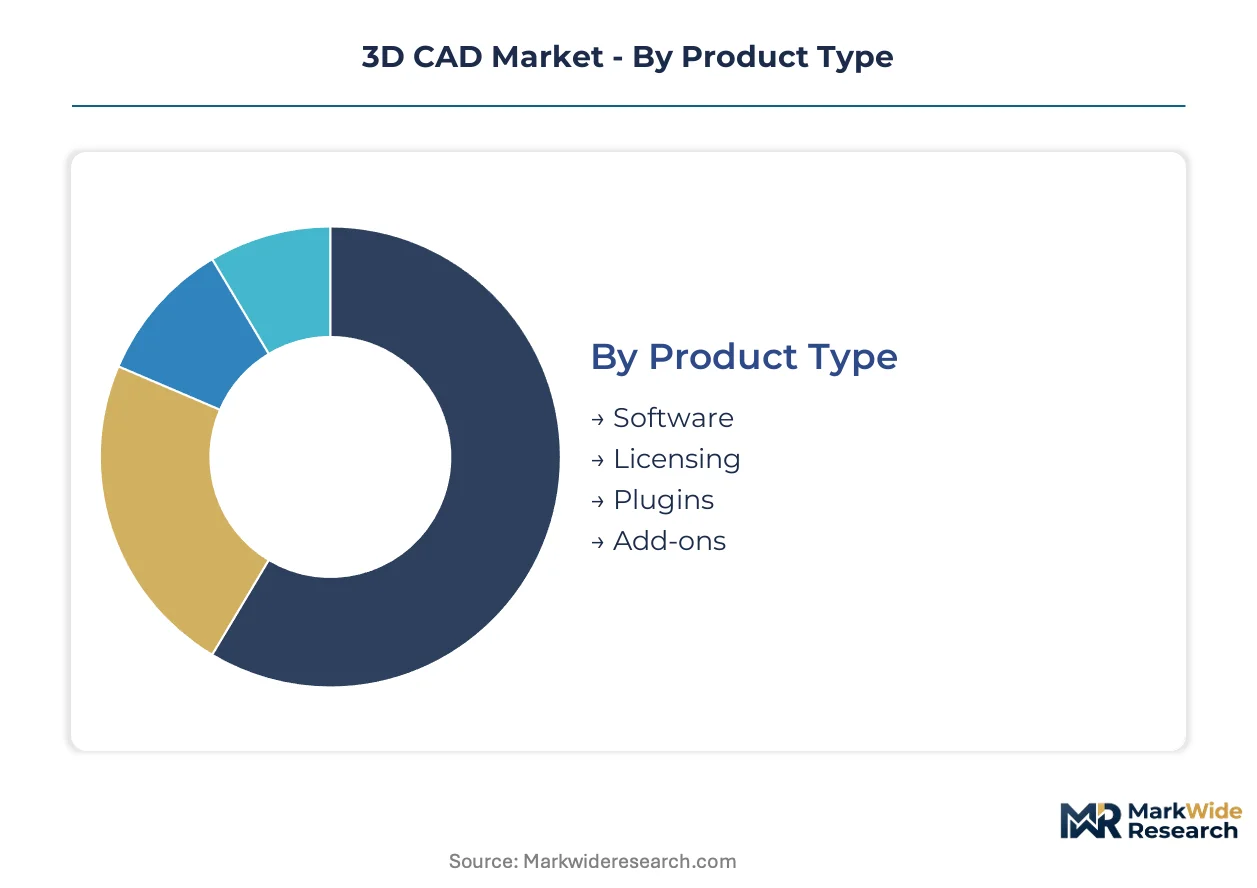
Margin pools concentrate in recurring license revenue and high-value specialized modules rather than base software seats.
- Software:Core geometric modeling engines with NURBS-based kernels and parametric feature trees form the foundation of design environments. Aerospace manufacturers in Toulouse and Seattle anchor demand through multi-year enterprise agreements that bundle simulation capabilities.
- Licensing:Subscription and perpetual models dictate customer lifetime value calculations and sales compensation structures. German automotive OEMs in Stuttgart negotiate consumption-based pricing tied to active project hours rather than fixed seat counts.
- Plugins:Specialized workflow automation tools extend platform functionality for niche manufacturing processes.
- Add-ons:Material databases and compliance modules address REACH and RoHS documentation requirements without core platform replacement.
The dominant share belongs to Software, while Licensing is closing the gap fastest as vendors force subscription transitions.
End User:
Application complexity and regulatory burden determine willingness to pay premium pricing tiers.
- Aerospace:Digital twin integration and FAA certification documentation requirements demand validated systems with traceable design histories. Boeing and Airbus supply chains in Wichita and Hamburg drive procurement of CATIA-integrated environments.
- Automotive:Lightweighting programs and generative design adoption compress iteration cycles for EV platform development. Detroit and Munich engineering centers prioritize topology optimization capabilities for battery enclosure design.
- Architecture:Building information modeling convergence pressures traditional CAD vendors to expand structural analysis partnerships.
- Engineering:Industrial machinery producers in China's Yangtze River Delta adopt simulation-integrated CAD under MIIT efficiency mandates.
Aerospace commands the deepest margin pool, though Automotive offers the steepest expansion trajectory as electrification reshapes design workloads.
Deployment Model:
Customer infrastructure preferences are redistributing competitive advantage toward elastic compute providers.
- On-Premises:Legacy installations persist where IT security policies restrict external data transmission. Defense contractors and classified program participants in the US and France maintain air-gapped environments.
- Cloud-Based:Remote collaboration requirements accelerated adoption among distributed engineering teams. Bavarian automotive suppliers deploy lightweight browser clients for supplier design reviews without full license overhead.
- Hybrid:Sensitive IP remains on-premises while rendering and collaboration shift to cloud infrastructure.
- SaaS:Subscription economics eliminate capital expenditure approval cycles for mid-market engineering firms.
On-Premises retains installed base dominance, yet Cloud-Based deployment is gaining share fastest as procurement teams prioritize operational flexibility.
Application:
Workflow integration depth separates commodity modeling from high-value platform stickiness.
- Product Design:Parametric feature trees and assembly constraint management enable precise geometric control. Medical device manufacturers in Massachusetts and Minnesota require FDA-validated design histories under 21 CFR Part 820.
- Prototyping:Digital validation before physical fabrication compresses development cycles and reduces tooling costs.
- Simulation:FEA and CFD integration demands GPU compute infrastructure that exposes teams to fluctuating cloud spend during peak project phases.
- Manufacturing:CAM toolpath generation and additive manufacturing preparation extend design data into production environments.
Product Design holds the largest revenue share, while Simulation is expanding most quickly as AI-assisted generative capabilities reshape engineering workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA certification requirements anchor United States demand, while MIIT efficiency mandates and EU MDR technical documentation obligations reshape procurement patterns across industrial clusters in China and Germany.
United States
Defense contractors and aerospace OEMs sustain air-gapped on-premises installations for classified programs. FAA design approval processes mandate traceable digital histories that elevate validated system selection criteria. Wichita and Seattle engineering centers drive multi-year enterprise agreements bundling simulation capabilities for commercial aviation supply chains.
Germany
Automotive lightweighting programs and industrial machinery efficiency standards compress design iteration cycles. EU MDR documentation requirements compel medical device manufacturers toward audit-ready CAD environments. Stuttgart and Munich engineering centers negotiate consumption-based pricing tied to active project hours rather than fixed licensing structures.
China
MIIT efficiency mandates for industrial machinery and dual carbon goals accelerate simulation-integrated CAD procurement. Domestic OEMs in the Yangtze River Delta adopt energy-optimized design workflows under national efficiency standards. Shanghai and Suzhou engineering centers expand cloud-based deployment for supplier collaboration networks.
Japan
METI manufacturing competitiveness programs and JIS standards compliance sustain precision machinery design software demand. Automotive and electronics OEMs prioritize NURBS-based kernel reliability for high-tolerance component development. Nagoya and Osaka industrial clusters maintain hybrid deployment models balancing IP security with rendering flexibility.
India
PLI scheme incentives for automotive components and industrial machinery expand design software procurement budgets. Engineering services outsourcing from Pune and Chennai drives browser-native CAD adoption for distributed collaboration. CDSCO medical device regulations increasingly influence platform selection for domestic manufacturers.
3D CAD Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the 3D CAD market structure. The upper tier commands enterprise accounts through bundled simulation and manufacturing execution integration. Mid-market specialists compete on deployment flexibility and industry-specific workflow automation. Dominant competitive moves include cloud infrastructure partnerships and consumption-based pricing restructuring.
Within the integrated platform tier, Autodesk Inc., Dassault Systèmes SE, and Siemens AG exemplify contrasting geographic anchoring and vertical integration depth. Autodesk represents the subscription-transition archetype with extensive educational partnership networks. Dassault Systèmes occupies a position emphasizing high-complexity aerospace and automotive ecosystem lock-in. Siemens exemplifies the industrial automation convergence model through manufacturing execution system integration.
| Leading Market Players |
|---|
| Autodesk Inc. |
| Dassault Systèmes SE |
| PTC Inc. |
| Siemens AG |
| Bentley Systems Inc. |
| Hexagon AB |
| Bricsys NV |
| ZWSOFT Co. Ltd. |
| Trimble Inc. |
| Others |
Supply Flow & Price Mechanics
FAA certification requirements gate both supplier qualification and price differentiation simultaneously, as validated CAD systems command substantial premiums over unvalidated alternatives while defense contractors absorb higher costs to maintain air-gapped compliance infrastructure. Medical device manufacturers face parallel gating through FDA design controls that elevate audit-ready platforms above commodity alternatives.
Pricing Analysis
Long-term enterprise agreements dominate aerospace and automotive procurement, with multi-year contracts bundling simulation capabilities and manufacturing execution integration. Three-tier pricing structure across premium, standard, and economy levels separates validated systems for FDA-regulated medical devices from browser-native collaboration tools for supplier design reviews. Cost compression in mid-market SaaS tiers is intensifying because procurement teams demand consumption-based pricing tied to active project hours rather than fixed seat counts. Engineering services outsourcing firms in India exhibit highest price sensitivity, while defense contractors in the United States show lowest sensitivity due to security-mandated infrastructure requirements.
Supply Chain Analysis
Just-in-time deployment cycles prevail among cloud-native engineering teams, though strategic stockpiling of NURBS kernel licenses persists where German and Japanese mathematical software specialists create single-source vulnerability. Critical geometry engines originate from concentrated bases in Germany and Japan, while cloud rendering infrastructure draws from hyperscaler data centers across the United States, Ireland, and Singapore. Supply chain risk centers on GPU compute cost volatility during peak project phases for real-time raytracing and simulation workloads. Distribution runs through direct enterprise sales for aerospace OEMs and value-added resellers serving mid-market industrial machinery producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue streams including simulation credits, compliance module subscriptions, and digital twin hosting layers are expanding faster than perpetual license hardware, transforming vendor economics toward recurring relationship models.
For Market Incumbents: Fortify platform stickiness through deeper manufacturing execution system integration and captive NURBS kernel development to reduce dependency on German and Japanese mathematical software specialists. Invest in consumption-based pricing telemetry to defend against procurement teams demanding granular usage-based contracts rather than coarse seat licensing.
For New Entrants and Emerging Players: Differentiate on browser-native accessibility for distributed supplier collaboration networks, targeting mid-market automotive component manufacturers in India's PLI scheme corridors as the most penetrable geography. Pursue white-space in AI-assisted generative design tools requiring documented training data provenance for EU AI Act compliance.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native CAD deployment as hyperscaler infrastructure replaces on-premises data center investment. Target acquisition candidates with established educational partnership pipelines and parametric design competency training networks. Watch GPU compute cost volatility as the signal indicating when hybrid deployment models will accelerate versus full cloud migration.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Infrastructure Partnership | Elastic compute access reduces capital expenditure barriers for mid-market engineering firms in Pune and Chennai. |
| Educational Pipeline Investment | University partnerships address parametric modeling expertise scarcity collapsing project timelines for complex product development. |
| Compliance Module Development | FDA-validated design history tools capture medical device manufacturers in Massachusetts and Minnesota under 21 CFR Part 820. |
| Generative Design Acquisition | AI-assisted topology optimization capabilities accelerate automotive lightweighting programs in Stuttgart and Detroit. |
| Digital Twin Service Launch | Real-time sensor feedback loops open predictive maintenance revenue streams from industrial machinery OEMs in the Yangtze River Delta. |
Methodological Framework
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings. Conversations with CTOs at aerospace OEMs, IT procurement officers at automotive conglomerates, platform engineers at cloud-native entrants, and integration specialists at industrial machinery producers combined with FDA 510(k) databases, EMA technical documentation registries, MIIT efficiency standard filings, and hyperscaler capex disclosures. Bottom-up segmentation modeling and top-down macroeconomic triangulation reconcile volume estimates across deployment models and vertical workflows.
Sensitivity analysis around GPU compute cost assumptions and subscription transition velocity shapes the analytical framework across the analysis window. Segmentation dimensions include deployment architecture, organization size, vertical industry, integration complexity with PLM systems, and regional regulatory cluster. CAGRs derive from fitted adoption curves weighted by procurement budget surveys and vendor revenue disclosures. Cloud rendering infrastructure expansion and AI-assisted design tool penetration serve as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained hyperscaler infrastructure investment and stable regulatory enforcement timelines would require recalibration. Forecasts reflect documented assumptions about engineering workforce composition and enterprise software procurement cycles. Revision becomes warranted when GPU compute cost volatility crosses thresholds disrupting simulation-integrated design adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Technology
APAC 3D Telepresence Market
3D Technology
3D Rendering Software Market
3D Technology
3D Point Cloud Processing Software Market
3D Technology
LAMEA Smartphone 3D Camera Market
3D Technology
UK 3D Rendering Services Market
3D Technology
Global 3D 4D Technology Market
3D Technology
Latin America 3D 4D Technology Market
3D Technology
3D Reconstruction Technology Market
3D Technology
Spatial Computing Market
3D Technology
3D Simulation Software Market
3D Technology
Contactless 3D Laser Scanner Market
3D Technology
Generative Design Market
3D Technology
Global 3D Virtual Platform Market
3D Technology
3D Printing CAD Software Market
3D Technology
Molecular Modeling Market
3D Technology
Digital Holography Market