
 POS Software Market | 2026-2036
POS Software Market Size, Share, and Industry Trends Forecast 2026-2036
POS Software Market Intelligence
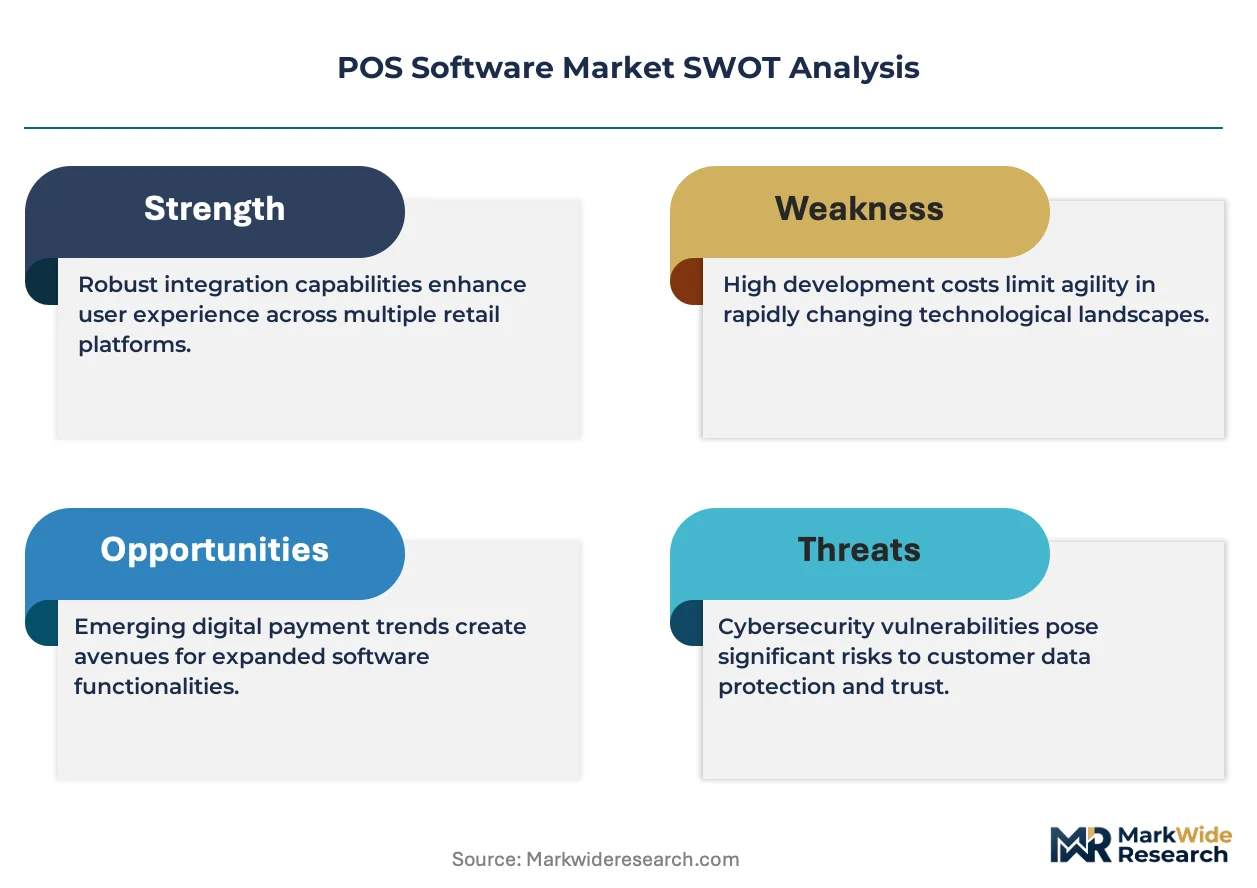
A capital-intensity divergence between legacy hardware-anchored vendors and lightweight cloud-native entrants is redrawing competitive boundaries in POS software. Oracle Corporation leverages its database and enterprise ERP installed base to sustain high-margin, full-stack contracts with Tier 1 retailers. Toast, Inc. anchors its position through restaurant-specialized hardware-software bundles and integrated payment monetization. Shopify Inc. competes by extending commerce tools from online storefronts into physical retail, blurring traditional POS boundaries.
POS software encompasses transaction-processing applications that interface with peripherals—receipt printers, barcode scanners, card readers, and cash drawers—to capture sales data, manage inventory, and execute payment authorization in real time. Cloud-based deployment leads segment expansion as vendors shift from perpetual licenses to recurring SaaS revenue, while on-premises installations retain dominance in regulated environments with strict data residency requirements. Within end users, hospitality and retail capture the deepest feature penetration, though healthcare is emerging as a specialized vertical where HIPAA-compliant payment integration creates distinct margin pools.
PCI-DSS standards, enforced by card networks and audited by qualified security assessors, dictate encryption and tokenization requirements that elevate engineering costs for new entrants. The Federal Trade Commission and state-level data breach notification laws in the United States impose liability frameworks that favor vendors with dedicated compliance infrastructure. Stakeholders must monitor how open-banking APIs and real-time payment rails reshape integration architectures before committing to multi-year platform contracts.
Market Dynamics
Cloud infrastructure migration is compressing replacement cycles as restaurant chains and retailers abandon perpetual-license hardware for subscription-based tablet systems with integrated payment processing.
Growth Catalysts
- PCI-DSS compliance mandates:Card network enforcement of encryption and tokenization standards forces legacy terminal upgrades, creating pull-through demand for certified software stacks across North American hospitality operators.
- Tablet-based hardware bundles:Restaurant-specialized systems with integrated payment monetization are displacing siloed terminals, driving attach rates for recurring SaaS revenue models.
- Omnichannel retail investments:United States-based SMBs are consolidating online and physical commerce onto unified platforms, erasing boundaries between e-commerce storefronts and in-store transaction processing.
Market Restraints
- Engineering cost elevation:PCI-DSS audit requirements and qualified security assessor oversight inflate development budgets for new entrants seeking certification.
- Data residency friction:On-premises installations retain dominance in regulated environments with strict local storage mandates, limiting cloud-native vendor addressable market.
- Legacy terminal installed base:Decade-old hardware-anchored systems in Tier 1 retailers create switching costs that elongate replacement timelines despite functional obsolescence.
Strategic Opportunities
- Healthcare vertical specialization:HIPAA-compliant payment integration creates distinct margin pools in ambulatory clinics and hospital outpatient services currently underserved by generic retail-hospitality platforms.
- Open-banking API convergence:Real-time payment rails and account-to-account transfer protocols are reshaping integration architectures, enabling new entrants to bypass traditional card network infrastructure.
- State-level breach notification laws:United States liability frameworks favor vendors with dedicated compliance infrastructure, creating acquisition opportunities for well-capitalized platforms.
Industry Challenges
- Embedded systems engineering scarcity:Firmware development expertise for peripheral integration—receipt printers, barcode scanners, card readers—commands premium compensation and elongates product timelines.
- Multi-year contract lock-in:Platform switching costs and data migration complexity suppress competitive churn, forcing vendors to front-load customer acquisition investment.
- Federal Trade Commission enforcement exposure:Data breach liability frameworks impose operational overhead for security infrastructure and incident response capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | POS Software Market |
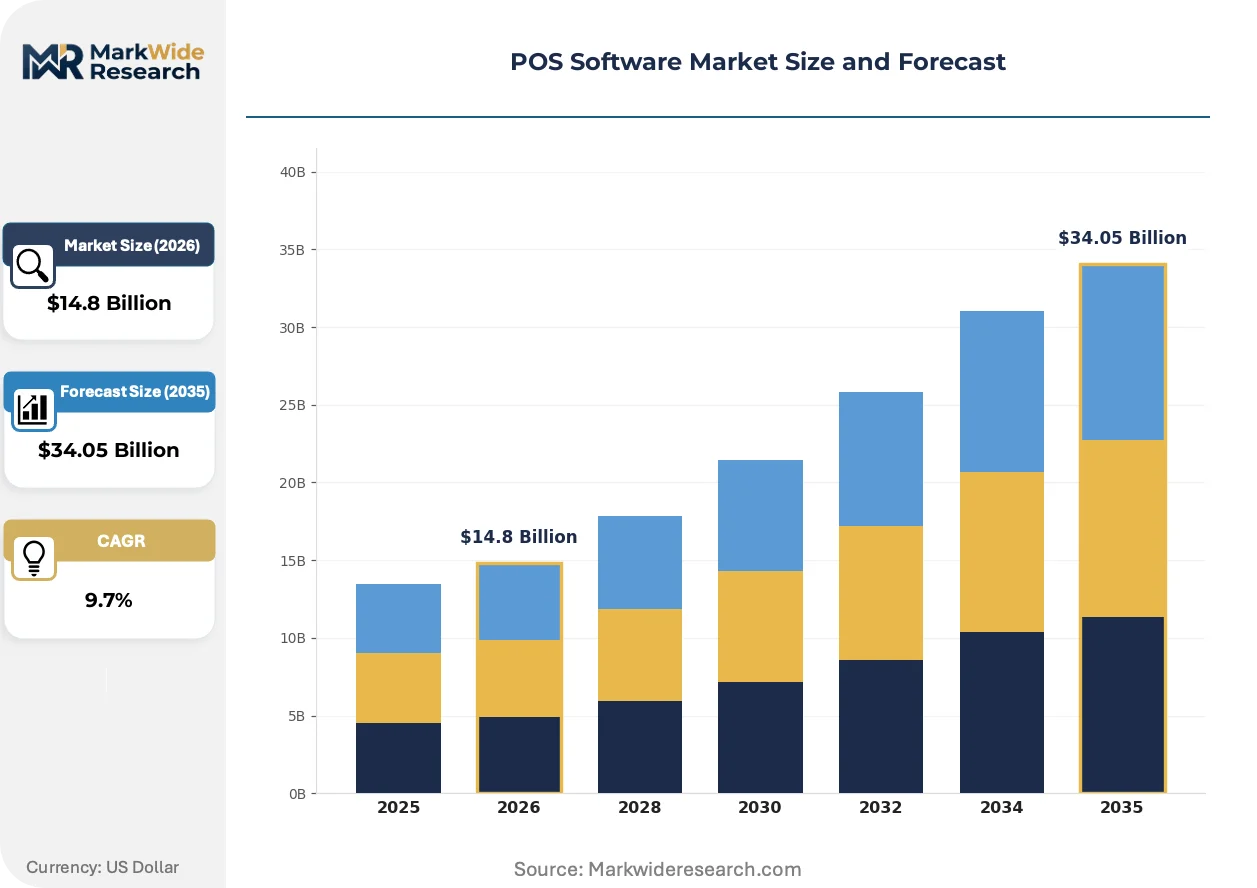
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $34.05 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-premises, Cloud-based, Hybrid, Mobile End User: Retail, Hospitality, Healthcare, Entertainment Features: Inventory Management, Customer Analytics, Payment Processing, Employee Management Service Type: Implementation, Training, Maintenance, Support |
| Companies Covered | GK Software, NCR Voyix, Toshiba Global Commerce Solutions, Flooid, Oracle Corporation, Block, Inc., Toast, Inc., Shopify Inc., Lightspeed Commerce Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
POS Software Market Strategic Shifts & Innovations
Software architecture is fragmenting from monolithic stacks into modular API-first components, enabling buyers to assemble best-of-breed solutions rather than accepting vendor-locked ecosystems.
Headless POS architecture is decomposing transaction processing from presentation layers, allowing hospitality operators to deploy branded guest-facing interfaces on consumer tablets while routing payments through certified back-end infrastructure. Mid-market restaurant chains are piloting these configurations fastest, compressing hardware refresh cycles from seven years to under thirty-six months as software updates decouple from terminal replacement.
The FTC's data breach notification requirements and state-level privacy statutes are elevating security architecture to a primary procurement criterion. Vendors must now document encryption protocols and incident response procedures during RFP stages, with non-compliant platforms excluded from shortlists regardless of functional capability. Healthcare and financial services verticals are responding by demanding SOC 2 Type II attestation as table stakes.
Buyer preference is gravitating toward usage-based pricing models that align software costs with transaction volume rather than fixed per-location fees. SMB retailers in the United States are leading this shift, pressuring vendors to unbundle hardware, software, and payment processing into separately negotiable components. This disaggregation favors cloud-native entrants with modular cost structures over legacy providers dependent on bundled margin pools.
POS Software Market Segmentation
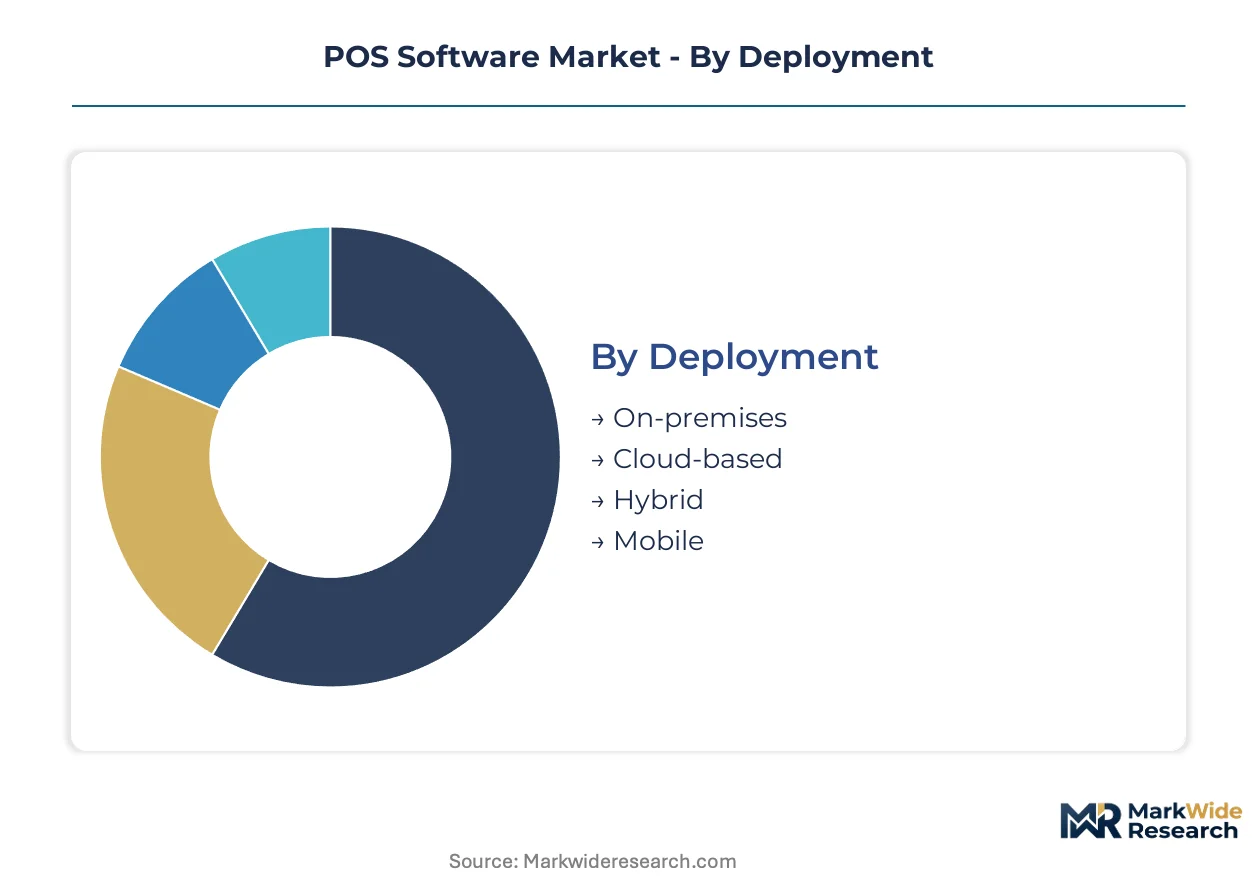
POS software segmentation reveals how procurement patterns fragment across operational complexity, regulatory exposure, and integration depth. Buyers select deployment modes and feature bundles based on transaction volume, compliance mandates, and existing infrastructure investments.
Deployment:
Cloud-native vendors reach mid-market buyers through direct sales and channel partners, while on-premises specialists rely on systems integrators for complex enterprise rollouts.
- On-premises:Perpetual-license software installed on local servers with dedicated hardware terminals. Tier 1 retailers in the United States with strict data residency requirements maintain this architecture despite higher capital expenditure.
- Cloud-based:Subscription SaaS delivered via browser or native applications with automatic updates. Restaurant chains across North America are migrating fastest as PCI-DSS compliance burdens shift to vendors.
- Hybrid:Core transaction processing remains local while analytics and reporting sync to cloud infrastructure. Healthcare clinics favor this model to isolate protected health information from public networks.
- Mobile:Smartphone and tablet applications enabling untethered checkout and line-busting. Food trucks and pop-up retail in dense urban corridors drive adoption for flexibility over feature depth.
On-premises deployments dominate installed base. Cloud-based configurations are where expansion concentrates.
End User:
Margin structures vary sharply by vertical, with hospitality tolerating higher per-transaction fees in exchange for integrated payment monetization.
- Retail:Inventory synchronization across channels demands real-time stock visibility and omnichannel return capabilities. United States-based SMBs consolidating online and physical operations generate replacement demand.
- Hospitality:Tableside ordering, kitchen display integration, and tip distribution workflows require specialized modules. Full-service restaurant chains prioritize hardware-software bundles over standalone software licensing.
- Healthcare:HIPAA-compliant payment integration and insurance eligibility verification create distinct procurement criteria. Ambulatory clinics and hospital outpatient services remain underserved by generic platforms.
- Entertainment:Venue-specific requirements span season ticket management, concession routing, and dynamic pricing for events. Stadiums and performing arts centers demand high-availability architectures during peak transaction windows.
Retail captures the deepest feature penetration. Healthcare is climbing the fastest as compliance requirements reshape vendor qualification.
Features:
Feature bundling determines pricing tiers, with payment processing anchoring margin pools and analytics modules commanding premium subscriptions.
- Inventory Management:Real-time stock tracking with automated reorder triggers and supplier integration. Multi-location retailers require this capability to prevent stockouts across distributed footprints.
- Customer Analytics:Purchase history aggregation, loyalty program management, and predictive segmentation. Hospitality operators leverage this data for personalized marketing and visit frequency optimization.
- Payment Processing:Card authorization, tokenization, and settlement routing with integrated hardware. PCI-DSS certification requirements elevate engineering costs and create vendor consolidation pressure.
- Employee Management:Time-clock integration, permission hierarchies, and tip pooling calculations. Restaurant chains with high turnover prioritize streamlined onboarding and role-based access controls.
Payment Processing anchors revenue concentration. Customer Analytics is gaining share fastest as merchants seek to monetize transaction data.
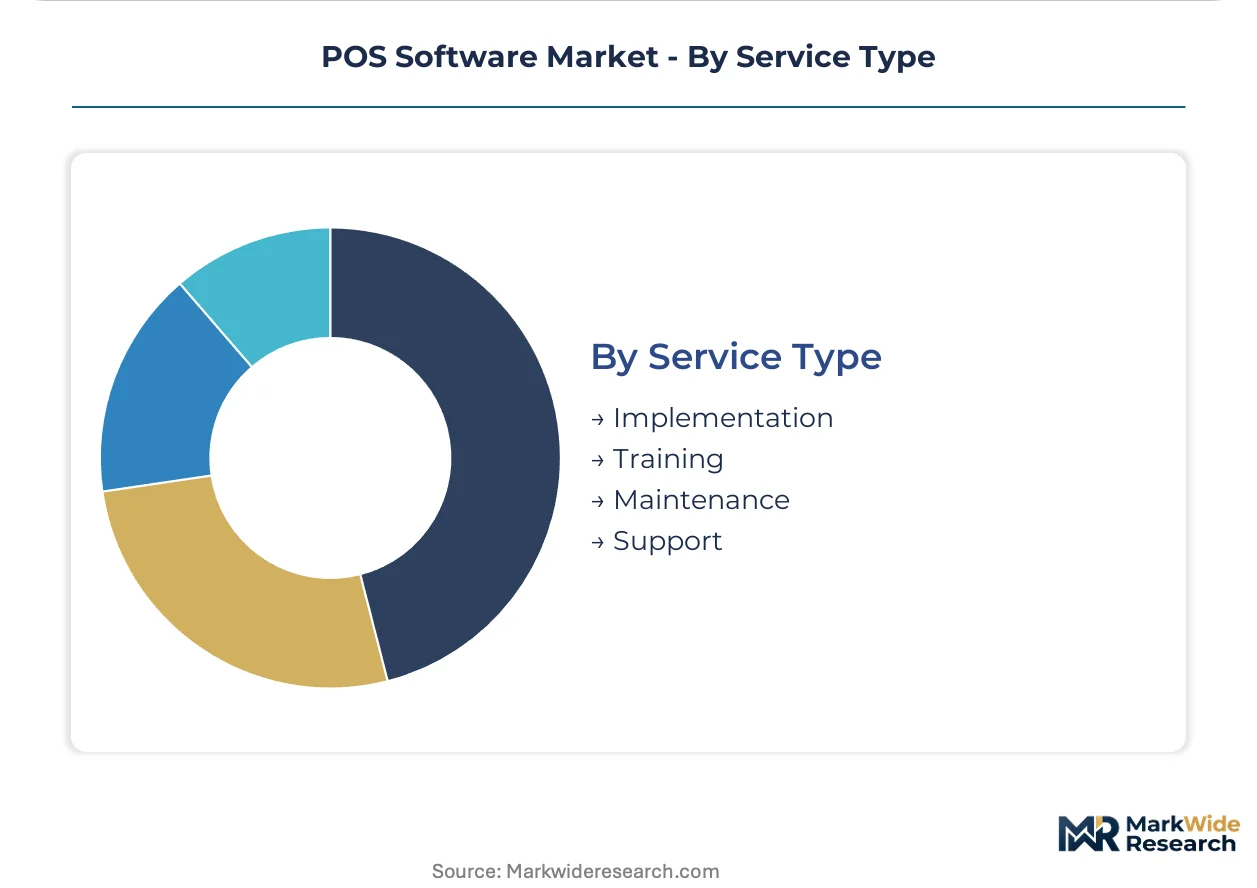
Service Type:
Professional services attach rates correlate with deployment complexity and buyer technical sophistication.
- Implementation:System configuration, data migration, and peripheral integration. Enterprise retailers with legacy ERP investments require extensive customization and testing protocols.
- Training:Role-based instruction for cashiers, managers, and back-office staff. Quick-service restaurant chains with seasonal hiring cycles prioritize scalable digital training modules.
- Maintenance:Patch management, security updates, and hardware replacement programs. On-premises deployments demand more intensive maintenance than cloud-native alternatives.
- Support:Helpdesk access, incident escalation, and dedicated account management. Tier 1 hospitality operators negotiate 24/7 coverage with guaranteed response time commitments.
Implementation services dominate professional services revenue. Support contracts are expanding most quickly as buyers seek operational continuity guarantees.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where PCI-DSS enforcement and SMB digitization accelerate replacement cycles, while European markets face margin compression from GDPR compliance costs and fragmented national payment schemes.
United States
Restaurant chains and independent retailers drive demand as legacy terminal replacement accelerates. The FTC enforces data breach notification laws that elevate security architecture to primary procurement criteria. California and New York Metro host dense clusters of cloud-native POS vendors competing for hospitality contracts.
Germany
Retail consolidation and fiscal cash register compliance mandates reshape vendor qualification requirements. The GoBD guidelines on digital record-keeping impose strict audit trail specifications. Berlin-Brandenburg and Bavaria concentrate mid-market retailers migrating from perpetual licenses to SaaS models.
United Kingdom
Omnichannel commerce investments and contactless payment penetration push hardware refresh demand. The Financial Conduct Authority oversees payment service authorization requirements for integrated processing modules. London anchors fintech-POS convergence as open-banking APIs reshape integration architectures.
Japan
QR code payment standardization and tourism recovery stimulate hospitality operator upgrades. METI promotes cashless transaction targets that pressure small merchants toward digitized systems. Tokyo and Osaka metropolitan areas concentrate deployment of tablet-based systems with integrated loyalty programs.
India
UPI real-time payment rails and GST compliance requirements drive formalization of retail transactions. RBI regulations on payment aggregators impose capital and technology standards that filter vendor eligibility. Maharashtra and Karnataka host emerging clusters of domestic POS software developers serving Tier 2 and Tier 3 cities.
POS Software Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with enterprise database vendors sustaining high-margin full-stack contracts while cloud-native entrants capture mid-market share through modular SaaS pricing. The market structure reflects a tiered concentration where three distinct strategic archetypes coexist: legacy hardware-anchored platforms, restaurant-specialized bundles, and commerce-software extenders. Dominant competitive moves include vertical integration into payment processing monetization and strategic partnerships with peripheral hardware manufacturers.
Within the enterprise tier, Oracle Corporation occupies a position representing database-anchored full-stack vendors. Toast, Inc. and Shopify Inc. exemplify contrasting specialization strategies—one restaurant-native with hardware-software bundling, the other extending from e-commerce into physical retail. These three entities collectively illustrate how competitive boundaries redraw around payment monetization capabilities rather than software features alone.
| Leading Market Players |
|---|
| GK Software |
| NCR Voyix |
| Toshiba Global Commerce Solutions |
| Flooid |
| Oracle Corporation |
| Block, Inc. |
| Toast, Inc. |
| Shopify Inc. |
| Lightspeed Commerce Inc. |
| Others |
Cost & Logistics Intelligence
Subscription-based SaaS contracts with embedded payment processing lock in multi-year revenue visibility while shifting PCI-DSS compliance burdens from restaurant operators to vendors. United States-based SMBs negotiate these agreements to flatten capital expenditure curves and secure predictable per-transaction costs across tablet-based hardware refreshes.
Pricing Analysis
The customization-premium spread separates configured-to-order enterprise deployments from standard SaaS tiers. Three-tier pricing structure across premium, standard, and economy levels anchors the market, with PCI-DSS certification grade and integration complexity serving as primary differentiation drivers. Cost compression in the standard tier intensifies because cloud-native entrants compete on modular unbundling. Quick-service restaurant chains with seasonal hiring cycles exhibit highest price sensitivity, while Tier 1 retailers with legacy ERP investments tolerate premium configuration fees.
Supply Chain Analysis
Inbound logistics costs through Shenzhen and Hong Kong port corridors affect hardware bundle economics for tablet-based terminal manufacturers. Semiconductor fabrication concentrates in Taiwan, South Korea, and China, while precision metalwork and display panel assembly anchor in Vietnam and Mexico. Firmware development expertise for peripheral integration commands premium compensation, creating single-source vulnerability for specialized engineering talent. Distribution runs through direct sales teams for enterprise accounts and value-added resellers serving mid-market hospitality operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PCI-DSS compliance mandates and real-time payment rail integration are compressing replacement cycles across North American hospitality, creating high-growth disruption as legacy terminal installed bases depreciate faster than historical seven-year norms.
For Market Incumbents: Consolidate payment processing capabilities through backward integration into tokenization infrastructure and acquire specialized healthcare compliance vendors to defend against cloud-native entrants targeting HIPAA-compliant verticals. Channel control through exclusive peripheral hardware partnerships represents a critical defensive lever against modular API-first competitors. For New Entrants and Emerging Players: Differentiate on healthcare vertical specialization where ambulatory clinics and hospital outpatient services remain underserved by generic retail-hospitality platforms. The most penetrable segment lies in mid-market restaurant chains piloting headless POS architectures, with open-banking API convergence offering a distinct go-to-market angle bypassing traditional card network infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward cloud-native platforms with modular cost structures capable of capturing SMB digitization tailwinds across the analysis window. Acquisition targets should demonstrate SOC 2 Type II attestation and established PCI-DSS certification infrastructure. The signal to watch is state-level breach notification law expansion, which will favor well-capitalized compliance-heavy platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Headless POS architecture decomposes transaction processing from presentation layers for branded guest interfaces. |
| Acquisition of Specialist Firm | Healthcare compliance vendors with HIPAA-certified payment modules unlock ambulatory clinic market access. |
| Strategic Partnership | Open-banking API alliances enable real-time account-to-account transfers bypassing card network fees. |
| Product Launch | Tablet-based hardware bundles with integrated payment monetization displace siloed legacy terminals. |
| Geographic Expansion | California and New York Metro clusters concentrate cloud-native vendor competition for hospitality contracts. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with restaurant chain CTOs, IT procurement officers at Tier 1 retailers, platform integration specialists, and channel partners distributing hardware-software bundles. Secondary validation drew from SEC filings, hyperscaler capex disclosures, PCI-DSS certification registries, and state-level data breach notification law databases. Bottom-up deployment modeling and top-down market sizing triangulated volume estimates.
Across the projection horizon, analytical frameworks segmented by deployment model, organization size, vertical specialization, and regional adoption pattern generated consistent growth trajectories. CAGRs derived from replacement cycle compression analysis and SMB digitization penetration curves. Forecast inputs incorporated PCI-DSS enforcement intensity indices and real-time payment rail adoption rates by metropolitan statistical area.
Material uncertainties — regulatory enforcement variance, open-banking API standardization delays, and healthcare vertical procurement cycle elongation — sit outside the modeled envelope. Forecasts reflect assumptions about compliance burden shifting and cloud migration velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Payroll and HR Software Market
Software & Services
Global Back Testing Software Market
Software & Services
Global Photogrammetry Software Market
Software & Services
Africa HR Payroll Software Market
Software & Services
Virtual Fitting Software Market
Software & Services
Global Lead Capture Software Market
Software & Services
Workflow Automation and Optimization Software Market
Software & Services
Oracle Services Market
Software & Services
Productivity Management Software Market
Software & Services
Business Spend Management (BSM) Software Market
Software & Services
Poultry Farm Management Software Market
Software & Services
Vending Software Market
Software & Services
BIM Objects Software Market
Software & Services
Instant Messaging Software Market
Software & Services
Global Cinema Software Market
Software & Services
Global Business Management Software Market