
 Lead Management Software Market | 2026-2036
Lead Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Lead Management Software Market Analysis
Silicon Valley SaaS infrastructure is decoupling from traditional CRM monoliths as specialized lead orchestration layers gain traction. Salesforce sustains dominance through its AppExchange ecosystem and native data cloud architecture. HubSpot Sales Hub differentiates via inbound methodology tooling and freemium-to-paid conversion mechanics. Pipedrive occupies the mid-market with visual pipeline management and aggressive European channel expansion.
Lead management software comprises cloud-native applications that capture, score, route, and nurture prospect interactions through automated workflows and predictive algorithms, typically operating via REST APIs and real-time event streaming to synchronize engagement data across sales and marketing stacks. The primary commercial purpose centers on reducing customer acquisition cost by accelerating qualified lead velocity and eliminating manual handoff friction between demand generation and revenue operations. Cloud-Based deployment leads absolute revenue contribution as enterprises abandon server maintenance overhead, while CRM Integration solutions command premium pricing by eliminating data silos between marketing automation and sales execution platforms. SMEs represent the fastest-expanding customer type as self-service onboarding and per-seat pricing democratize access previously gated to enterprise procurement cycles.
FCC guidelines on telemarketing consent and TCPA compliance obligations shape how lead capture forms structure opt-in workflows and telephone outreach cadences in the United States. GDPR data-processing requirements in Europe enforce granular consent logging and right-to-erasure capabilities that vendors must embed at the database schema level. California's CCPA amplifies these demands for US-based buyers serving California residents. Stakeholders must monitor evolving state-level privacy legislation and API interoperability standards as determinants of platform switching costs and competitive moat durability.
Market Dynamics
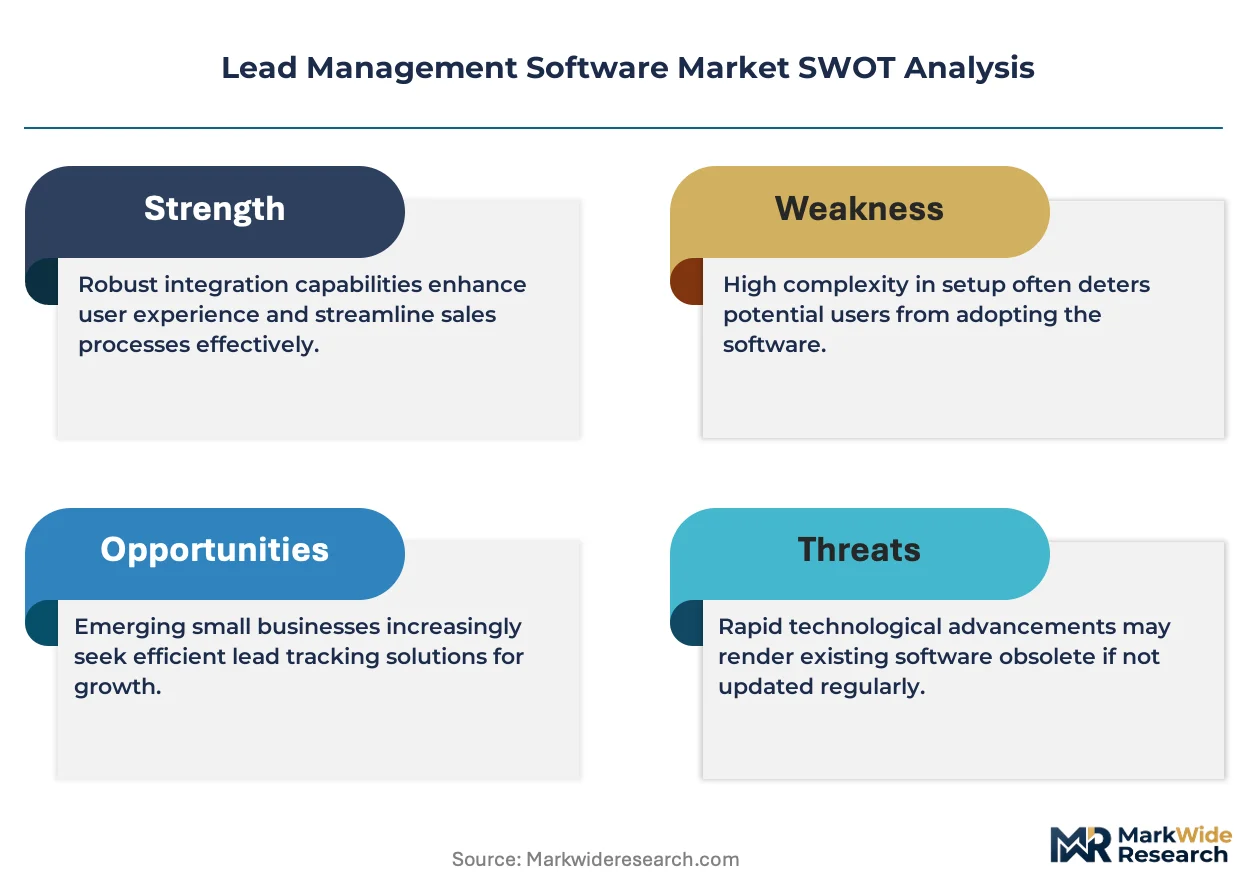
API-first architectures are fragmenting the lead management stack as enterprises dismantle monolithic CRM deployments in favor of composable, best-of-breed orchestration layers. This structural decoupling accelerates vendor switching and compresses integration timelines.
Growth Catalysts
- GDPR consent automation:European demand generation teams require granular audit trails for lead capture workflows. Vendors embedding right-to-erasure capabilities at the schema level capture replacement cycles from legacy systems.
- Real-time event streaming:Kafka and WebSocket protocols enable sub-second lead routing between marketing automation and sales execution. Mid-market SaaS buyers prioritize platforms with native event-driven architectures.
- Revenue operations specialization:Dedicated RevOps functions at B2B technology firms now own lead velocity metrics. This organizational shift creates procurement authority for standalone orchestration tools outside traditional IT budgets.
Market Restraints
- TCPA compliance friction:FCC telemarketing consent rules impose strict opt-in documentation and outreach cadence limits. Telephone-based lead qualification faces structural headwinds in United States markets.
- Cloud concentration risk:AWS, Azure, and Google Cloud host the majority of lead management infrastructure. Single-region outages or egress pricing changes directly impact vendor operating margins.
- Data residency mandates:Saudi Arabia's SFDA and China's NMPA impose local storage requirements for customer interaction records. Global vendors must replicate infrastructure across sovereign jurisdictions.
Strategic Opportunities
- India PLI scheme alignment:Production-linked incentives for software exports create cost advantages for vendors establishing development centers. Indian SaaS buyers represent underpenetrated mid-market demand.
- Conversational AI convergence:Large language models integrated with lead scoring engines enable dynamic qualification scripts. Early deployments show compression of sales development representative touch cycles.
- Embedded finance partnerships:Banking-as-a-service APIs allow lead management platforms to offer payment-integrated quoting. This channel innovation targets professional services verticals with complex pricing workflows.
Industry Challenges
- Identity resolution complexity:Cross-device tracking degradation and cookie deprecation fragment prospect profiles. Engineering teams must rebuild attribution models around first-party data graphs.
- RevOps talent scarcity:Functional expertise spanning marketing operations, sales analytics, and data engineering commands premium compensation. Vendors face elongated implementation timelines due to customer-side capability gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lead Management Software Market |
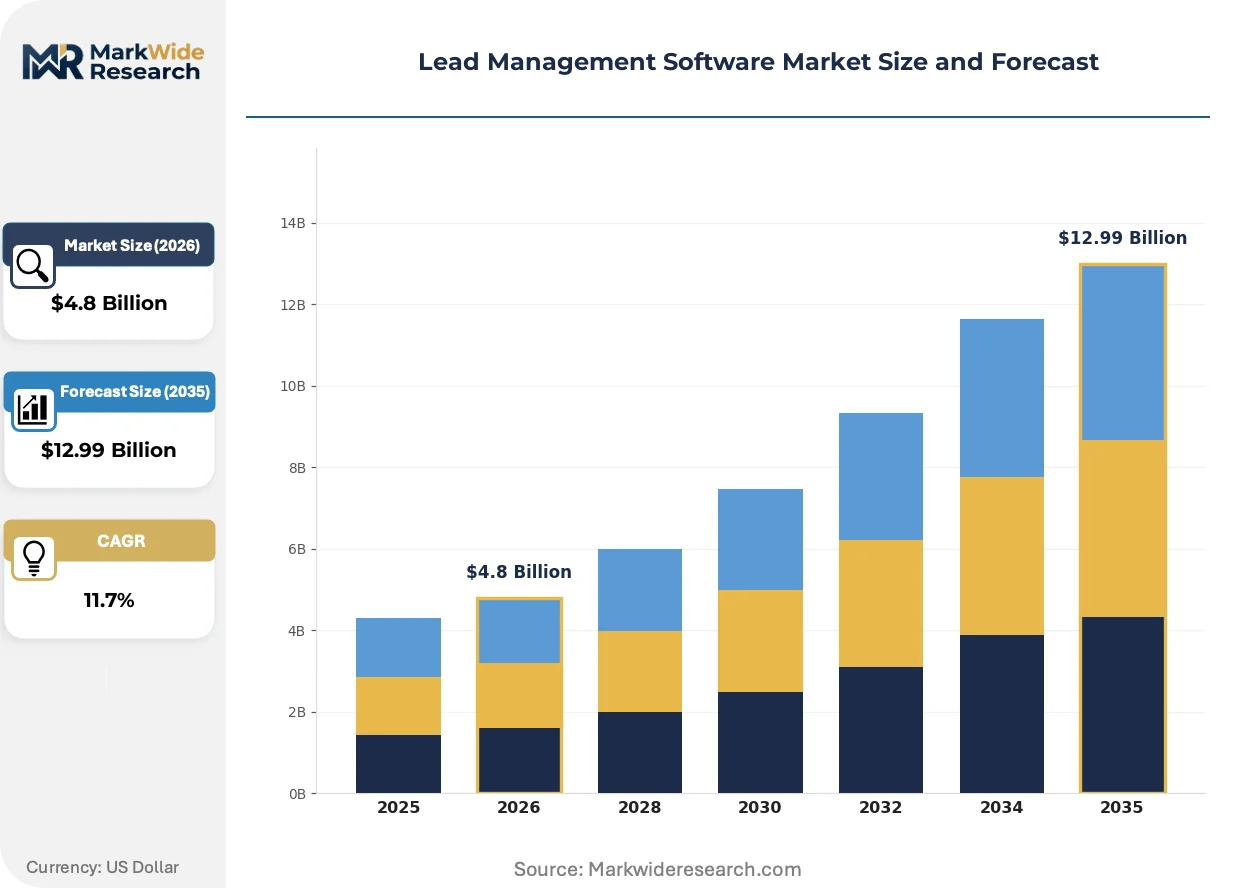
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Mobile Customer Type: SMEs, Enterprises, Agencies, Freelancers Solution: Automated, Manual, CRM Integration, Analytics Industry Vertical: Real Estate, Finance, Retail, Education |
| Companies Covered | Zoho CRM, Freshworks CRM, Salesflare, Kartra, Zendesk Sell, HubSpot Sales Hub, Salesforce, Keap, Pipedrive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lead Management Software Market Emerging Trajectories
Generative AI and real-time data infrastructure are compressing the interval between lead capture and sales engagement. Vendors race to embed predictive capabilities that anticipate buyer intent signals before explicit form submissions.
Event-driven architectures is electrifying lead routing infrastructure. Apache Kafka and Redis Streams enable millisecond-scale handoffs between demand generation and sales development functions. Enterprise buyers with dedicated revenue operations teams now mandate event streaming as a core procurement criterion. This technology is electrifying competitive positioning by collapsing the latency advantage previously held by native CRM ecosystems.
GDPR Article 17 enforcement is tightening data retention obligations across European deployments. Controllers must demonstrate automated erasure capabilities for prospect records across all downstream systems. Mid-market vendors without native compliance automation face elevated churn risk in Germany, France, and Netherlands markets. Legal and engineering teams now co-own product roadmap prioritization for privacy-by-design features.
Self-service onboarding is displacing traditional sales-assisted implementation for sub-100-seat deployments. Product-led growth mechanics including freemium tiers and in-app usage analytics now drive expansion revenue. This pattern concentrates among venture-backed SaaS firms with technical founders and existing marketing automation investments. North American and United Kingdom markets show the highest concentration of product-led procurement committees.
Lead Management Software Market Segmentation
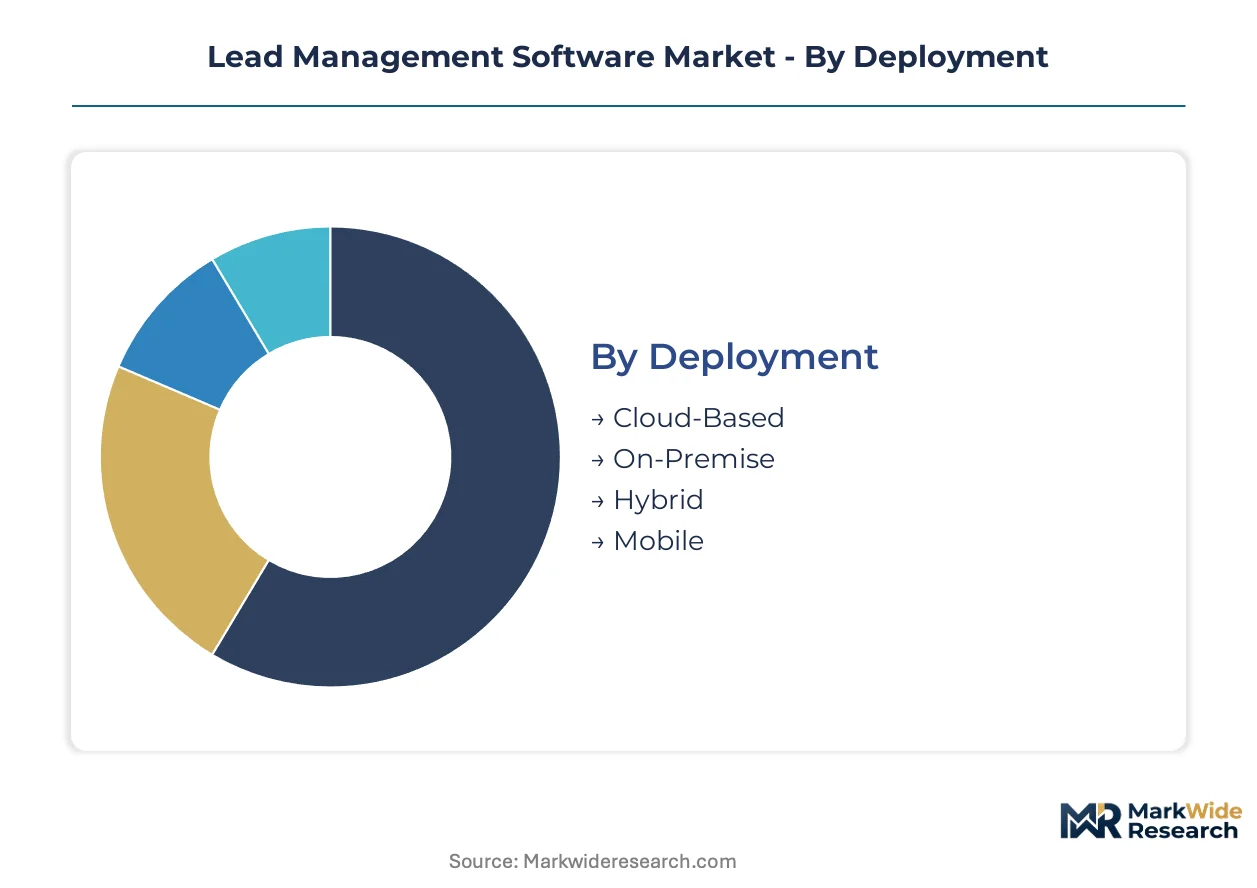
Lead management software vendors architect pricing and packaging around deployment flexibility, organizational scale, and integration depth. Segmentation decisions determine API strategy, compliance automation requirements, and channel economics across revenue operations buyers.
Deployment:
Customization intensity varies sharply across deployment modes, with self-managed infrastructure demanding the most engineering resources while fully managed options trade control for speed-to-value.
- Cloud-Based:Multi-tenant SaaS architectures with REST API gateways and serverless compute backends. United States mid-market buyers prioritize these platforms for real-time pipeline analytics and zero infrastructure overhead. GDPR Article 17 automated erasure capabilities now factor into European procurement scorecards.
- On-Premise:Single-tenant installations on customer-managed hardware with direct database access. Financial services firms in Germany and Switzerland mandate these deployments for data residency compliance with national banking regulators. Maintenance burden and upgrade friction create replacement cycle opportunities.
- Hybrid:Split architectures with sensitive data on-premise and compute workloads in cloud environments. Appeals to healthcare and government verticals with mixed classification requirements.
- Mobile:Native iOS and Android applications with offline synchronization and push notification routing. Field sales teams in real estate and logistics drive adoption for territory-based lead assignment.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in Hybrid configurations as regulated industries seek architectural compromise.
Customer Type:
Account size dictates sales motion complexity, with product-led growth mechanics viable only below specific seat thresholds where procurement authority decentralizes.
- SMEs:Organizations with under 200 employees purchasing through self-service portals with per-seat pricing. Freemium-to-paid conversion mechanics and in-app usage analytics dominate acquisition strategy. United Kingdom and United States show highest product-led procurement committee concentration.
- Enterprises:Multi-divisional organizations with dedicated revenue operations functions and custom integration requirements. Security reviews, SLA negotiations, and professional services attachments extend sales cycles. Procurement authority increasingly sits with RevOps leaders outside traditional IT budgets.
- Agencies:Marketing services firms managing lead flows across multiple client tenants. White-label capabilities and sub-account isolation determine platform selection.
- Freelancers:Individual practitioners with basic contact management and simple automation needs. Price sensitivity drives preference for free tiers with usage-based upgrade triggers.
Revenue concentrates in Enterprise accounts despite longer sales cycles. Seat growth is climbing fastest in Agencies as marketing services firms consolidate client technology stacks.
Solution:
Functional depth separates commodity contact databases from platforms commanding premium pricing through workflow automation and predictive intelligence.
- Automated:Event-driven architectures with Kafka-based lead routing, predictive scoring algorithms, and multi-channel nurture sequences. Mid-market SaaS buyers in the United States mandate sub-second handoff latency between marketing automation and sales development.
- Manual:Basic list management with spreadsheet-style interfaces and minimal workflow logic. Declining share as self-service onboarding democratizes access to automation capabilities.
- CRM Integration:Native connectors eliminating data silos between lead capture forms and opportunity records. Salesforce and HubSpot API ecosystems command pricing premiums through bidirectional synchronization.
- Analytics:Attribution modeling, cohort analysis, and pipeline velocity dashboards. Revenue operations specialization creates procurement authority for standalone analytics layers.
Automated solutions carry the highest average contract values. Analytics modules are expanding most quickly as RevOps teams seek visibility into lead-to-revenue conversion mechanics.
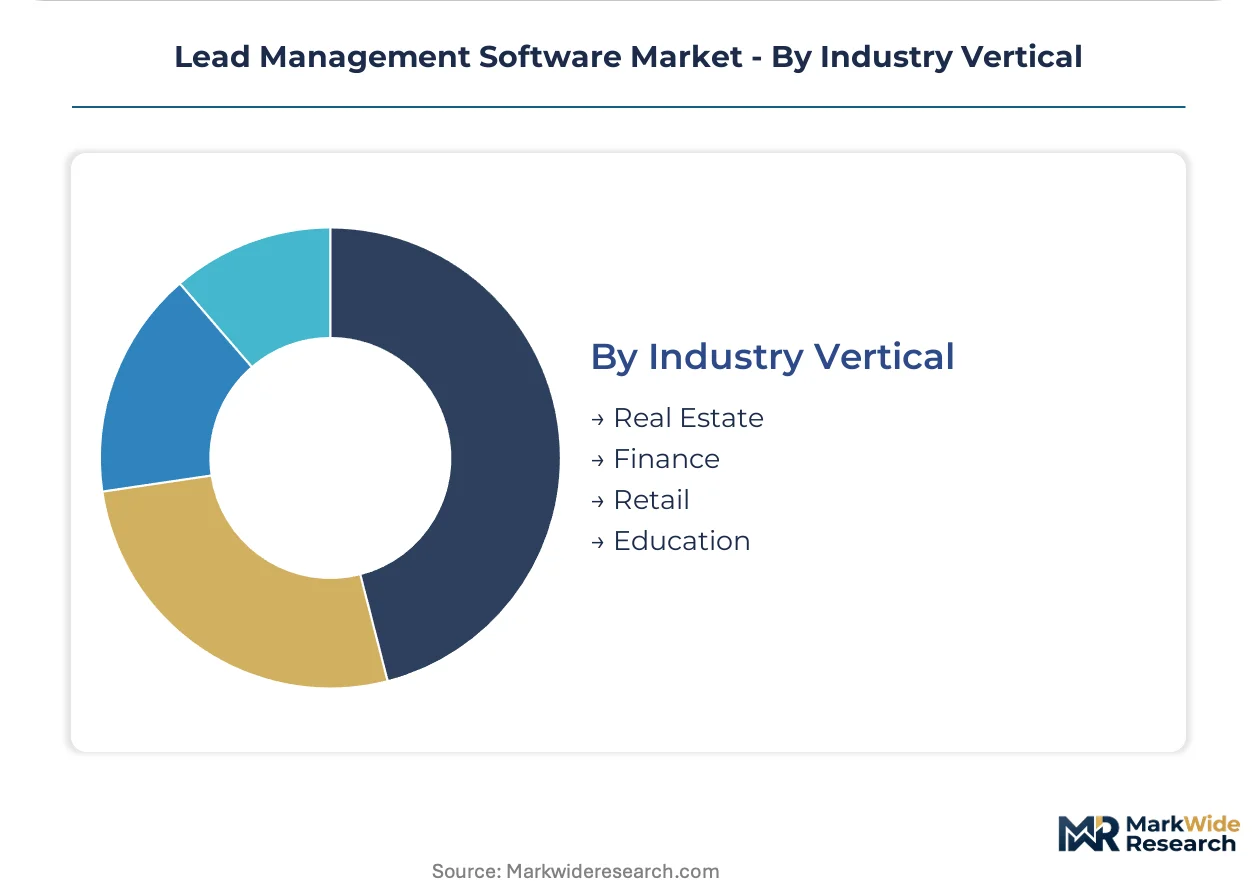
Industry Vertical:
Vertical-specific compliance requirements and sales process complexity shape feature prioritization across go-to-market investments.
- Real Estate:Territory-based routing, MLS integration, and commission split tracking. Brokerages in California and Texas drive demand for mobile-first field sales capabilities.
- Finance:TCPA consent logging, SEC communication archiving, and suitability documentation workflows. Banks and wealth managers face FCC telemarketing rule constraints on outreach cadences.
- Retail:E-commerce cart abandonment triggers, loyalty program integration, and high-volume seasonal scaling. Omnichannel attribution complexity favors platforms with first-party data graph capabilities.
- Education:Inquiry-to-enrollment tracking, financial aid workflow integration, and multi-campus lead distribution. Universities prioritize right-to-erasure automation for prospective student records.
Finance verticals generate the highest per-seat pricing. Education institutions are gaining share fastest as enrollment pressure intensifies post-pandemic demographic shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost-of-compliance gaps are redistributing lead management software deployment strategies across jurisdictions. Vendors optimize data residency architectures to exploit differences between strict GDPR enforcement zones and more permissive regulatory environments.
United States
Enterprise sales teams in the United States drive demand for real-time pipeline analytics and automated lead routing. FCC TCPA guidelines on telemarketing consent shape opt-in workflow designs and telephone outreach cadences. Silicon Valley SaaS infrastructure clusters in San Francisco and Seattle are decoupling from legacy CRM monoliths as specialized lead orchestration layers gain procurement traction.
Germany
German demand generation teams require granular audit trails for lead capture workflows under GDPR Article 17 enforcement. The country's national data protection regulator mandates automated right-to-erasure capabilities embedded at the database schema level. Frankfurt and Munich host the densest concentration of financial services firms mandating on-premise deployments for data residency compliance.
United Kingdom
Mid-market SaaS buyers in the United Kingdom show the highest concentration of product-led procurement committees. Domestic privacy regulations derived from GDPR enforce granular consent logging requirements. London fintech clusters are expanding adoption of cloud-based lead management platforms with native event streaming architectures.
India
Indian SaaS buyers represent underpenetrated mid-market demand as production-linked incentives for software exports create cost advantages. The country's central bank and data protection authority impose evolving data localization requirements. Bengaluru and Hyderabad development centers are attracting vendors establishing engineering hubs for APAC market expansion.
Japan
Japanese enterprises prioritize CRM integration solutions that eliminate data silos between marketing automation and sales execution platforms. METI guidelines on digital transformation shape procurement criteria for revenue operations tooling. Tokyo-based B2B technology firms are creating dedicated RevOps functions that own standalone orchestration tool budgets outside traditional IT.
Lead Management Software Market Vendor Landscape
United States producers anchor the premium tier through native data cloud architectures and AppExchange ecosystems; European specialists hold the compliance-automation segment through GDPR-native schema designs. Market structure tilts toward consolidated platform dominance at the enterprise level while fragmenting across mid-market vertical specialists. Three archetypes define competitive positioning: full-suite CRM incumbents extending into lead orchestration, standalone best-of-breed routing platforms, and vertical-specific solutions for regulated industries. Dominant competitive moves include API-first architecture investments that compress integration timelines and strategic partnerships with banking-as-a-service providers.
Within the full-suite tier, Salesforce and HubSpot Sales Hub exemplify platform consolidation strategies that bundle lead management with broader revenue operations infrastructure. Pipedrive occupies a distinct position among European-originated vendors emphasizing visual pipeline management and aggressive channel expansion. Zoho CRM represents the emerging-market efficiency archetype with cost-optimized self-service onboarding mechanics targeting SME procurement patterns.
| Leading Market Players |
|---|
| Zoho CRM |
| Freshworks CRM |
| Salesflare |
| Kartra |
| Zendesk Sell |
| HubSpot Sales Hub |
| Salesforce |
| Keap |
| Pipedrive |
| Others |
Supply Flow & Price Mechanics
GDPR Article 17 compliance mandates gate both qualified supply and premium-tier pricing access, as vendors embedding automated right-to-erasure capabilities at the database schema level capture replacement cycles from legacy systems while commanding subscription premiums in Germany, France, and Netherlands markets.
Pricing Analysis
Direct-to-enterprise discounts compress channel margins for cloud-native deployments, while partner reseller markups sustain 15-25 point spreads on implementation services. SaaS-tiered subscription models dominate, with price differentiation hinging on API call volume entitlements and native event streaming architecture. Pricing pressure stems from self-service onboarding mechanics democratizing access previously gated to enterprise procurement cycles. SMEs exhibit highest price sensitivity, while enterprises with dedicated RevOps functions prioritize latency performance over per-seat cost.
Supply Chain Analysis
Cross-border data transfer costs and sovereign cloud egress fees are reshaping vendor infrastructure economics as compliance architectures fragment across jurisdictions. Engineering talent concentrates in India, Poland, and Portugal, while compute infrastructure rests on AWS, Azure, and Google Cloud hyperscaler networks. Single-region outage vulnerability creates operational risk for real-time lead routing platforms. Distribution runs through direct sales teams for enterprise accounts and self-service portals for sub-100-seat deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as revenue operations specialization creates durable procurement authority for standalone orchestration tools outside traditional IT budgets.
For Market Incumbents: Deepen API-first architecture investments to compress integration timelines and defend against best-of-breed routing platforms. Extend native data cloud capabilities to neutralize the latency advantage held by Salesforce's AppExchange ecosystem. Prioritize GDPR-native schema designs to capture replacement cycles from legacy systems in European enforcement zones.
For New Entrants and Emerging Players: Capture underpenetrated Indian mid-market demand as production-linked incentives for software exports create cost advantages for development center establishment. Target professional services verticals with complex pricing workflows through embedded finance partnerships. Lead with conversational AI convergence to compress sales development representative touch cycles.
For Investors and Strategic Acquirers: Roll-up economics work for vertical-specific compliance-automation specialists because data residency mandates fragment infrastructure requirements across sovereign jurisdictions. Five-to-ten year viability favors vendors with event-driven architectures and RevOps-native go-to-market motions. Monitor API interoperability standard adoption as the inflection signal for platform switching cost durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native Kafka-based event streaming eliminates data silos between marketing automation and Salesforce opportunity records. |
| Acquisition of Specialist Firm | GDPR-native schema designs from European vendors accelerate right-to-erasure automation for German financial services clients. |
| Strategic Partnership | Banking-as-a-service APIs enable payment-integrated quoting for professional services verticals with complex workflows. |
| Geographic Expansion | Bengaluru development centers exploit PLI scheme cost advantages for APAC market penetration. |
| Product Launch | Large language model integration with lead scoring engines compresses SDR touch cycles for mid-market SaaS buyers. |
Methodological Framework
Direct dialogue with revenue operations leaders, SaaS procurement officers, integration specialists, and channel partners grounded qualitative findings, combined with secondary validation from SEC filings, hyperscaler capex disclosures, App Annie platform analytics, and GDPR enforcement tracker databases. Bottom-up deployment estimates across cloud, on-premise, hybrid, and mobile architectures triangulated against top-down SaaS spend projections from IT budget surveys.
Segment-level value outputs calibrated to organization size, deployment model, solution depth, and vertical compliance intensity across the projection horizon. CAGRs derived from historical adoption velocity in United States mid-market SaaS clusters and European GDPR replacement cycles. Forecast inputs incorporated API interoperability standard maturation timelines and RevOps function proliferation rates at B2B technology firms.
Underlying measurement precision varies by segment; cloud-based deployments carry tighter precision than on-premise installations due to disclosed hyperscaler revenue attribution. Forecasts reflect assumptions around regulatory enforcement consistency and talent scarcity duration. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Pet Tracking Software Market
Software & Services
Automotive Digital Retailing Software Market
Software & Services
Global Time and Attendance Management Software Market
Software & Services
India Sports Management Software Market
Software & Services
Association Management Software Market
Software & Services
Compensation Software Market
Software & Services
Salesforce Services Market
Software & Services
Petcare Software Market
Software & Services
Global Roofing Software Market
Software & Services
Sports Production Software Market
Software & Services
Cloud Testing and ASQ Software Market
Software & Services
Global Jewelry Store Management Software Market
Software & Services
Online Project Management Software Market
Software & Services
Managed Information Services Market
Software & Services
Retail Core Banking Solution Market
Software & Services
Global Testing Software Market