
 Global Policy Management Software Market | 2026-2036
Global Policy Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Policy Management Software Market Foresight
ISO 27001 certification is redrawing competitive boundaries in policy management software. Oracle Corporation leverages its database infrastructure to anchor enterprise deployments across regulated industries. SAP SE sustains deep ERP integration that locks in large corporations with complex multi-jurisdictional compliance obligations. MetricStream specializes in GRC workflows that differentiate its offering for financial services and healthcare buyers seeking pre-configured regulatory templates.
Policy management software encompasses systems that automate the creation, distribution, enforcement, and audit of organizational policies through workflow engines, version control, and attestation tracking. These platforms integrate role-based access controls with document lifecycle management to ensure employees acknowledge current standards before accessing sensitive operations. Cloud-based deployment leads adoption as mid-sized companies abandon on-premises maintenance burdens, while compliance management solutions capture the largest margin pools due to recurring regulatory update subscriptions. Incident management represents the fastest-expanding solution type as boards demand real-time escalation pathways for cybersecurity and operational risk events.
The Federal Risk and Authorization Management Program in the United States and the EU AI Act create mandatory audit trails that directly expand software procurement budgets. HIPAA, SEC disclosure rules, and the EU Green Deal's CSRD reporting layers compound requirements for centralized policy repositories with immutable version histories. Stakeholders must evaluate whether their current platforms can absorb emerging algorithmic accountability mandates without parallel system investments.
Market Dynamics
Regulatory fragmentation across jurisdictions is forcing enterprises to abandon fragmented compliance tools in favor of unified policy platforms that can absorb multi-standard mandates without parallel infrastructure investments.
Growth Catalysts
- EU AI Act:Mandatory algorithmic accountability requirements in Europe are compelling financial institutions and healthcare providers to deploy automated policy attestation systems with immutable audit trails.
- Cloud migration:Mid-sized enterprises are abandoning on-premises policy servers for SaaS platforms that eliminate maintenance overhead and accelerate deployment cycles.
- FedRAMP:United States federal contractors face escalating authorization requirements that directly expand procurement budgets for compliant policy management infrastructure.
Market Restraints
- Implementation complexity:ERP integration timelines frequently exceed eighteen months, delaying realized value and extending sales cycles for vendors serving large manufacturers.
- Specialist talent scarcity:Organizations struggle to hire compliance technologists capable of configuring multi-jurisdictional policy frameworks across GDPR, HIPAA, and SEC jurisdictions simultaneously.
- Subscription fatigue:Recurring regulatory update fees compound total cost of ownership, prompting finance departments to scrutinize overlapping GRC tool investments.
Strategic Opportunities
- India:RBI and SEBI are tightening governance mandates for banks and securities firms, creating first-mover advantage for platforms pre-configured with Indian regulatory templates.
- Incident management convergence:Real-time escalation pathways for cybersecurity events represent underexploited white space as boards demand faster breach notification workflows.
- API-first architecture:Open integration standards enable embedded policy controls within existing productivity suites, reducing switching friction for reluctant enterprise buyers.
Industry Challenges
- Legacy system entanglement:Mainframe-dependent insurers and government agencies face prohibitive data migration costs when modernizing decades-old policy repositories.
- Version control sprawl:Organizations operating across fifty-plus jurisdictions struggle to maintain synchronized policy updates without creating conflicting employee attestations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Policy Management Software Market |
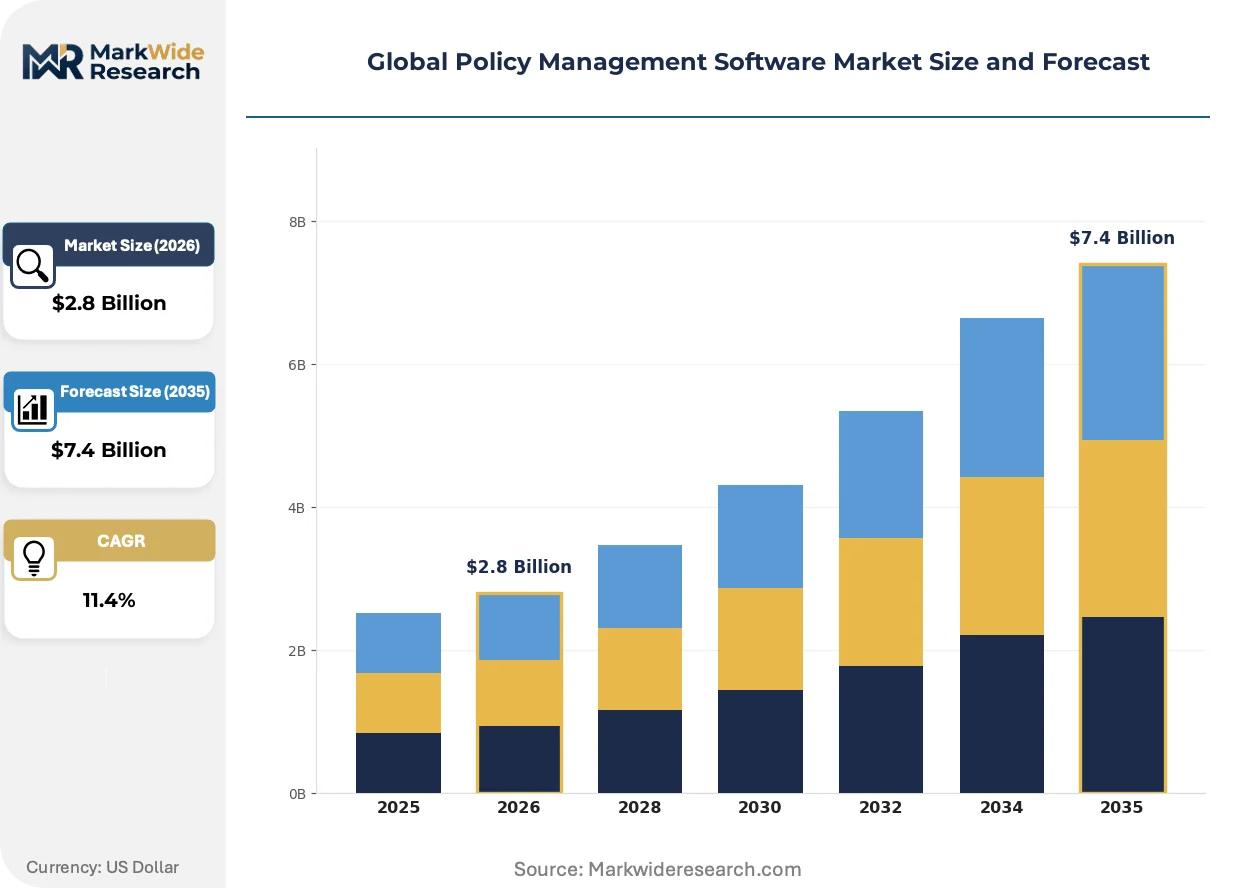
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Managed Services Solution Type: Compliance Management, Risk Management, Document Management, Audit Management, Incident Management Application: Financial Services, Information Technology, Education Sector, Manufacturing Firms, Telecommunications Customer Type: Small Enterprises, Mid-Sized Companies, Large Corporations, Government Agencies |
| Companies Covered | Guidewire Software, Duck Creek Technologies, Sapiens International Corporation, Oracle Corporation, SAP SE, Cognizant Technology Solutions, IBM, NAVEX Global, MetricStream, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Policy Management Software Market Shifts & Advancements
Artificial intelligence is restructuring how policy content gets generated, interpreted, and enforced, compressing the gap between regulatory publication and enterprise implementation from months to days.
Natural language processing engines are decomposing traditional document-centric policy management into modular, machine-readable rule sets. Financial services firms in the United States and Germany are deploying these tools to auto-extract obligations from SEC and BaFin publications. This capability is decomposing the market for manual compliance translation services and reconstituting vendor value around real-time regulatory intelligence.
The EU AI Act's risk classification framework is mandating documented governance procedures for high-risk automated decision systems. Deployers of credit scoring and recruitment algorithms must maintain technical documentation and human oversight protocols. Healthcare and financial services verticals in France and the Netherlands are responding by embedding policy checkpoints directly into model development pipelines.
Subscription-based procurement is displacing perpetual licensing as the dominant commercial model for mid-market buyers. Vendors are unbundling implementation services from software fees, creating transparent cost structures that appeal to procurement departments under margin pressure. This shift is most visible among United Kingdom professional services firms and Scandinavian manufacturing exporters seeking predictable operational expenditures.
Global Policy Management Software Market Segmentation
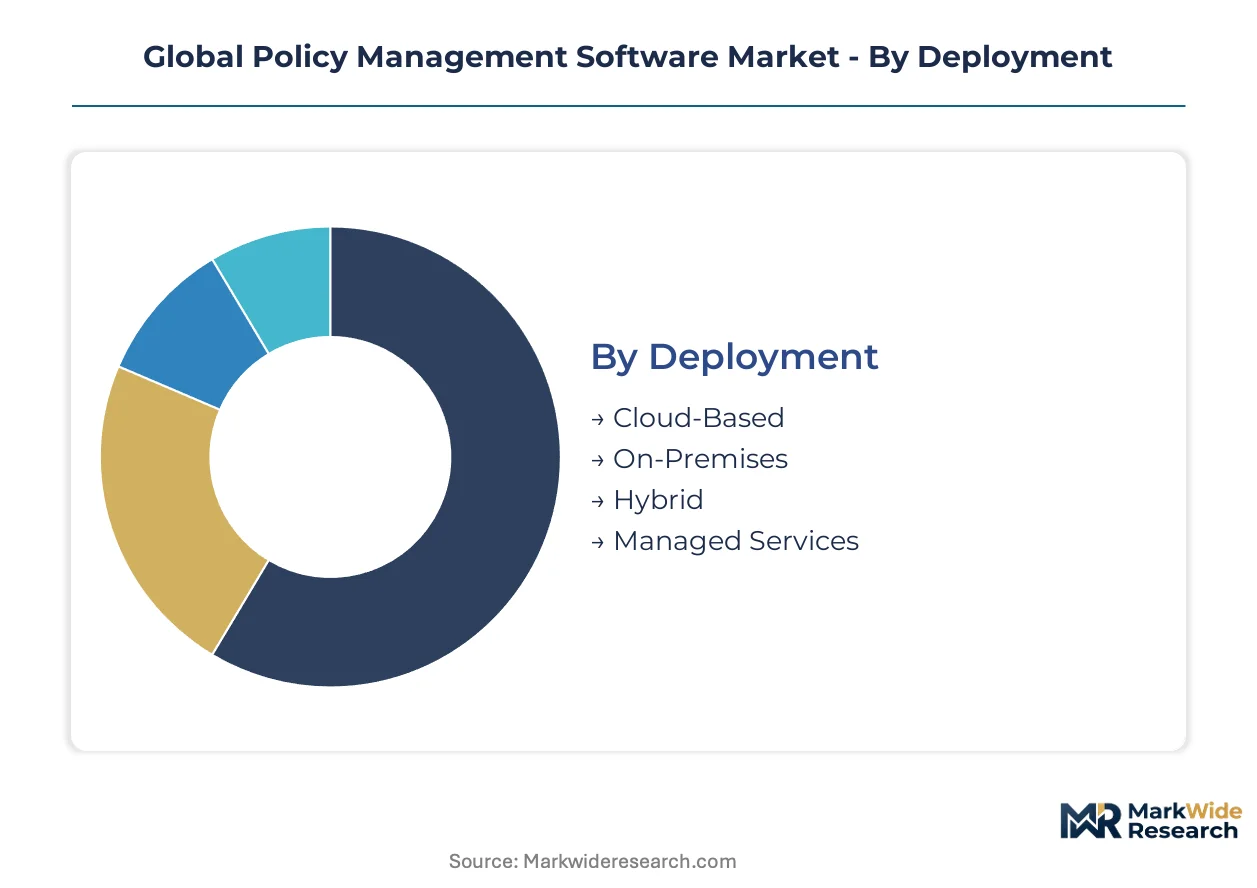
Segmentation in policy management software reveals how regulatory intensity and IT maturity shape procurement decisions. Buyers select deployment modes and solution bundles based on audit frequency, data sovereignty requirements, and the complexity of multi-jurisdictional compliance obligations they must maintain.
Deployment:
GDPR's data residency clauses and FedRAMP's authorization tiers create divergent infrastructure requirements that segment the deployment landscape across regulated industries.
- Cloud-Based:Multi-tenant SaaS architectures eliminate server maintenance overhead while delivering automatic regulatory template updates. Financial services firms in Germany and the United States favor this model for GDPR and SEC compliance workflows where patch velocity matters more than physical data control.
- On-Premises:Air-gapped installations within client data centers satisfy national security mandates and pharmaceutical manufacturing requirements under FDA 21 CFR Part 11. Defense contractors and classified government facilities in the United States maintain this deployment exclusively.
- Hybrid:Sensitive policy repositories remain on-premises while employee attestation workflows route through cloud gateways. Healthcare networks in France and Canada deploy this architecture to balance HIPAA and provincial privacy law requirements.
- Managed Services:Third-party operators assume full infrastructure responsibility including backup, disaster recovery, and compliance monitoring. Mid-sized manufacturers in Japan and South Korea outsource policy infrastructure to focus capital on production equipment.
Established volume favors Cloud-Based; emerging adoption favors Managed Services.
Solution Type:
Solution bundling correlates directly with board-level risk oversight intensity and the frequency of external audit cycles.
- Compliance Management:Centralized repositories with version control and employee attestation tracking form the core revenue engine. Banks in India under RBI guidelines and securities firms facing SEBI mandates purchase these solutions as foundational infrastructure.
- Risk Management:Quantitative scoring engines aggregate operational, credit, and market risk indicators into unified dashboards. Insurance carriers in Switzerland and asset managers in the United Kingdom deploy these for Solvency II and FCA stress testing requirements.
- Document Management:Policy lifecycle workflows from drafting through obsolescence with full audit trails. Professional services firms in Australia maintain these systems for TGA documentation and client confidentiality protocols.
- Audit Management:Automated evidence collection and finding remediation tracking for internal and external examination cycles. Energy utilities in the United States facing FERC reliability standards utilize these platforms.
- Incident Management:Real-time escalation pathways with automated regulatory notification timers for cybersecurity and operational breaches. This segment is expanding most quickly as EU AI Act and SEC disclosure rules compress response windows.
Compliance Management commands the largest installed base; Incident Management is climbing the fastest.
Application:
Industry-specific regulatory architectures determine solution configuration complexity and integration depth requirements.
- Financial Services:Multi-layered mandates spanning Basel III, MiFID II, and anti-money laundering protocols demand the most sophisticated policy orchestration. Investment banks in Singapore and retail banks in Brazil under Central Bank of Brazil regulations drive premium solution adoption.
- Information Technology:FedRAMP authorization and ISO 27001 certification requirements dominate procurement criteria. Cloud service providers and SaaS vendors in the United States and Ireland prioritize automated evidence collection for continuous monitoring.
- Education Sector:FERPA compliance and research data governance policies shape smaller-scale deployments. Universities in Canada and Australia manage student privacy and grant-funded research protocols through streamlined platforms.
- Manufacturing Firms:Environmental permits, quality management under ISO 9001, and supply chain codes of conduct create distributed policy requirements. Automotive suppliers in Germany and Mexico coordinate multi-facility compliance through centralized repositories.
- Telecommunications:Net neutrality obligations, lawful intercept procedures, and data retention mandates vary by national regulator. Mobile operators in Nigeria and Indonesia navigate fragmented requirements through modular policy engines.
Financial Services absorbs the highest per-seat pricing; Information Technology shows the steepest expansion trajectory.
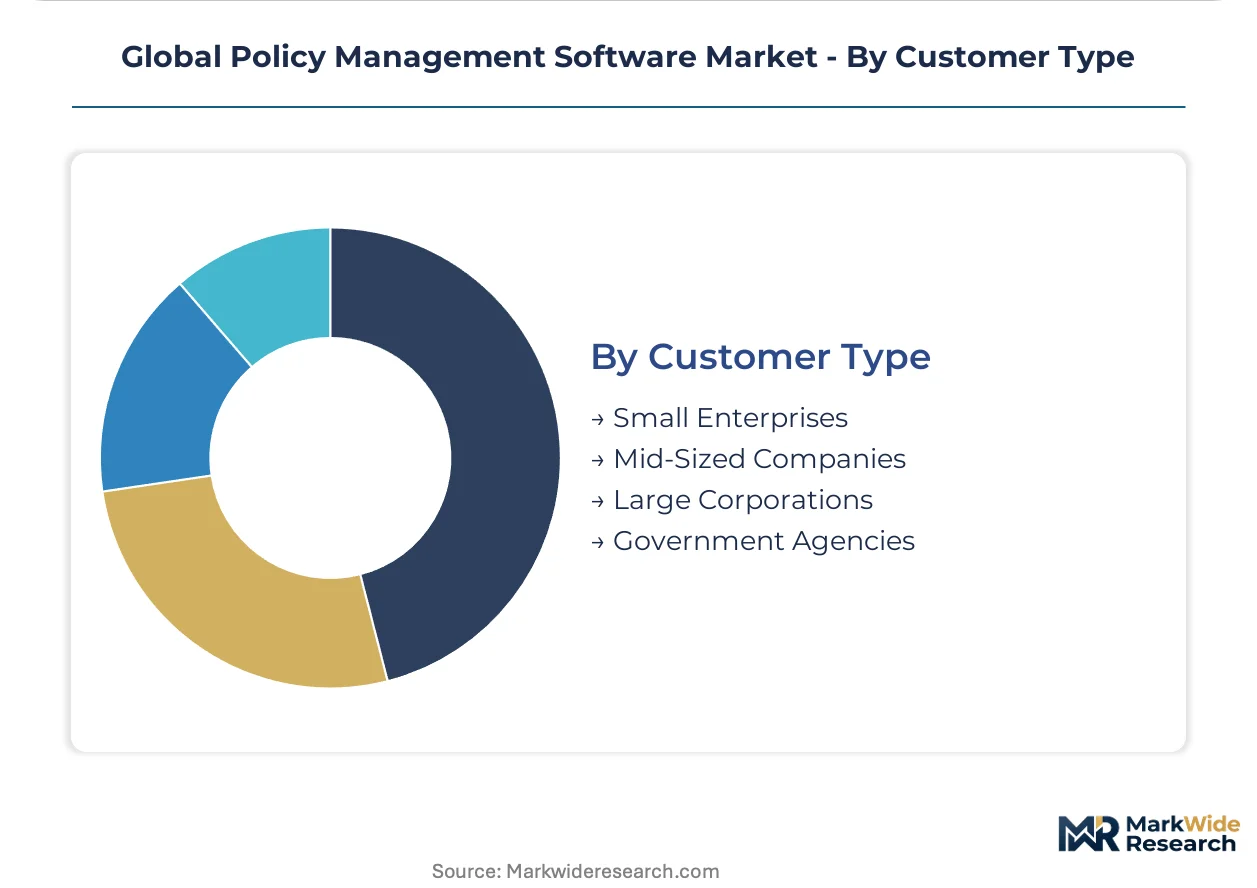
Customer Type:
Organizational scale dictates integration complexity, customization tolerance, and procurement approval hierarchy length.
- Small Enterprises:Out-of-the-box configurations with minimal IT staff requirements dominate selection criteria. Professional services boutiques in the United Kingdom and Denmark purchase lightweight SaaS tiers for GDPR documentation.
- Mid-Sized Companies:Balanced need for customization without enterprise implementation timelines. Regional healthcare providers in Spain and logistics operators in the Netherlands represent the fastest-expanding customer category.
- Large Corporations:ERP integration mandates and multi-jurisdictional template libraries justify extended deployment cycles. Multinational manufacturers with operations across Italy, Poland, and Vietnam require synchronized policy distribution.
- Government Agencies:FedRAMP authorization, classified data handling, and public procurement transparency rules create specialized vendor requirements. Federal departments in the United States and ministry IT units in Saudi Arabia operate dedicated acquisition channels.
Large Corporations generate the deepest recurring revenue; Mid-Sized Companies are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FedRAMP authorization requirements and EU AI Act mandates are redirecting procurement budgets toward compliant policy infrastructure across major economies. Financial institutions in Germany and the United States lead enterprise deployments. Cloud migration accelerates fastest among mid-sized companies in India and the United Kingdom.
United States
Defense contractors and federal agencies drive demand for FedRAMP-authorized platforms with immutable audit trails. CMMC requirements for Department of Defense suppliers compound procurement urgency. Silicon Valley cloud providers and Washington DC-area government integrators anchor the vendor ecosystem.
Germany
BaFin's regulatory intensity pushes banks and insurers toward automated policy attestation systems. GDPR enforcement creates data residency requirements favoring hybrid deployment architectures. Frankfurt's financial services cluster and Munich's industrial technology corridor concentrate procurement decisions.
India
RBI guidelines for bank governance and SEBI mandates for securities firms expand addressable market for pre-configured regulatory templates. Mid-sized enterprises abandon spreadsheet-based compliance for SaaS platforms. Mumbai's financial district and Bengaluru's technology corridor generate disproportionate demand.
United Kingdom
FCA disclosure rules and post-Brexit regulatory divergence force firms to maintain dual-track compliance frameworks. Professional services firms prioritize subscription-based procurement for predictable operational expenditures. London's legal and consulting clusters drive template customization requirements.
France
CNIL enforcement actions and EU AI Act risk classifications mandate documented governance for algorithmic decision systems. Healthcare providers embed policy checkpoints into model development pipelines. Parisian banking headquarters and Lyon-based pharmaceutical operations concentrate deployment activity.
Global Policy Management Software Market Competitive Landscape
Player mix skews toward enterprise software conglomerates with adjacent GRC portfolios. Market structure concentrates around vendors with pre-existing database or ERP relationships that reduce switching friction. Three archetypes dominate: infrastructure-anchored platforms, vertical-specialist suites, and cloud-native challengers. Competitive moves center on API-first architecture investments and regulatory template library expansion.
Within the infrastructure-anchored tier, Oracle Corporation and SAP SE occupy positions shaped by their database and ERP installed bases. MetricStream exemplifies the vertical-specialist archetype through its concentrated focus on financial services and healthcare compliance workflows. These three entities represent distinct competitive vectors—enterprise lock-in through system integration, versus modular specialization for regulated industries.
| Leading Market Players |
|---|
| Guidewire Software |
| Duck Creek Technologies |
| Sapiens International Corporation |
| Oracle Corporation |
| SAP SE |
| Cognizant Technology Solutions |
| IBM |
| NAVEX Global |
| MetricStream |
| Others |
Supply & Pricing Matrix
Subscription-based capacity reservations lock in multi-year SaaS commitments for FedRAMP-authorized platforms, binding United States federal contractors to predictable expenditure schedules while securing vendor revenue visibility against regulatory update cycles.
Pricing Analysis
Certification level creates the primary spread between deployment tiers, with FedRAMP High and ISO 27001-certified platforms commanding substantial premiums over standard SaaS offerings. Three-tier pricing structure across premium, standard, and economy levels segments buyers by audit frequency and data sovereignty requirements. Cost compression in the mid-market tier intensifies as Indian and United Kingdom SaaS vendors compete on implementation speed. Small enterprises exhibit highest price sensitivity, while government agencies prioritize compliance assurance over unit economics.
Supply Chain Analysis
Just-in-time regulatory template delivery dominates vendor operations, with cloud infrastructure provisioning scaling elastically to match policy update velocity. Software development concentrates in the United States, India, and Ireland, drawing from specialized compliance technologist talent pools. Intellectual property licensing for embedded NLP engines and API frameworks rests on partnerships with academic research institutions. Single-source vulnerability emerges around proprietary algorithmic accountability modules required for EU AI Act compliance. Distribution runs through direct enterprise sales teams supplemented by systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of compliance technologists capable of configuring multi-jurisdictional frameworks simultaneously constrains vendor scaling and inflates implementation timelines across the industry.
For Market Incumbents: Compound defensive positioning by deepening ERP integration moats and acquiring niche regulatory template libraries before cloud-native challengers can replicate coverage. Cloud migration acceleration among mid-sized companies threatens traditional enterprise lock-in. Vertical integration into specialized compliance consulting services preserves margin capture during elongated sales cycles. For New Entrants and Emerging Players: Lead with API-first architectures targeting mid-sized healthcare providers in Spain and logistics operators in the Netherlands, the fastest-expanding customer category. India's tightening RBI and SEBI governance mandates present first-mover white space for pre-configured regional templates. Partner with regional systems integrators to bypass direct enterprise sales infrastructure requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertical-specialist suites with embedded regulatory intelligence capabilities. Long-term viability hinges on template library breadth spanning GDPR, HIPAA, SEC, and emerging algorithmic accountability mandates. Acquisition targets should demonstrate sustained renewal rates above industry benchmarks. Watch for EU AI Act enforcement actions as inflection indicators accelerating procurement urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Template Library Expansion | Pre-configured GDPR and SEC workflows differentiate offerings for financial services buyers in Germany and the United States. |
| API-First Architecture Investment | Open integration standards reduce switching friction for reluctant enterprise buyers wedded to existing productivity suites. |
| Vertical Compliance Consulting Integration | In-house policy configuration services capture margin pools eroding from pure software subscriptions. |
| Geographic Expansion into India | RBI and SEBI mandate acceleration creates addressable market for localized deployment expertise. |
| Strategic Partnership with Systems Integrators | Channel leverage bypasses direct sales cost structures while accelerating federal contractor acquisition. |
Research Methodology
Initial hypotheses were tested against primary input from chief compliance officers, IT procurement officers, platform integration specialists, and regulatory affairs leads and refined through secondary validation against SEC filings, FedRAMP authorization databases, EU regulatory publication archives, and hyperscaler partnership disclosures. Bottom-up deployment estimates triangulated against top-down market sizing across cloud-based, on-premises, hybrid, and managed services deployment modes.
Variance decomposition across deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern shaped the analytical framework. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion trajectories. Model inputs incorporated regulatory mandate publication timelines, cloud migration velocity indicators, and compliance technologist labor market constraints.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement intensity or accelerated cloud migration adoption would require recalibration. Forecasts reflect assumptions regarding template update frequency and implementation timeline compression. Revision becomes warranted when EU AI Act enforcement thresholds or FedRAMP authorization backlogs cross critical capacity constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Mobile Application Development Market
Software & Services
Executive Search (Headhunting) Software Market
Software & Services
Global Integration Software Market
Software & Services
Global Cloud Testing Market
Software & Services
Europe Digital Signage Software Market
Software & Services
Global Photogrammetry Software Market
Software & Services
Global Sweepstakes Software Market
Software & Services
Global Inside Sales Software Market
Software & Services
Business Spend Management (BSM) Software Market
Software & Services
Global Franchise Management Software Market
Software & Services
Global Digital Adoption Platform Software Market
Software & Services
Tech Support Services Market
Software & Services
Automation Test Software Market
Software & Services
Global Auto Dealer Software Market
Software & Services
Global Continuous Integration Tools Market
Software & Services
Plant Design Software Market