
 Global Automotive Elastomers Market | 2026-2036
Global Automotive Elastomers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Elastomers Market Foresight
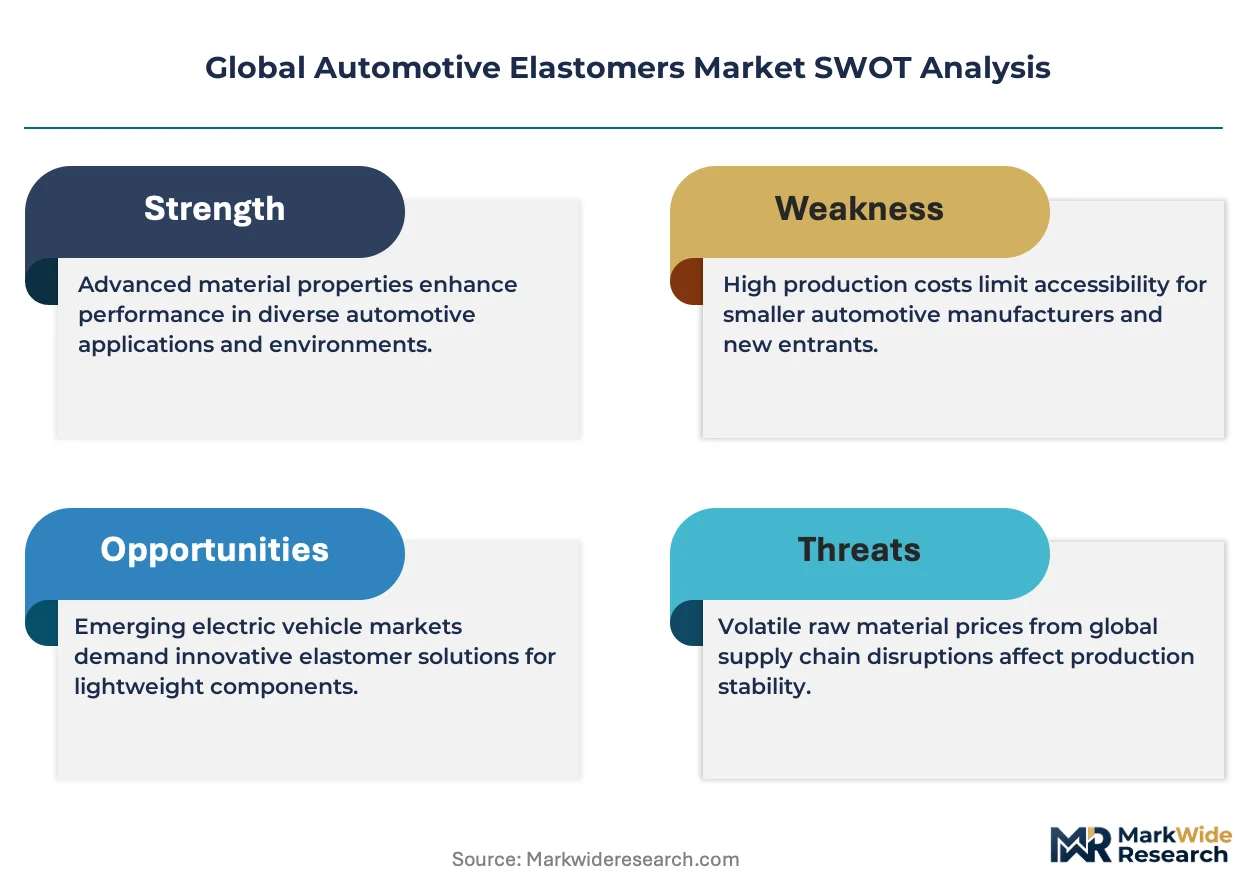
The capability gap between integrated polymer producers and compounders is collapsing as raw material volatility forces backward integration strategies. Dow leverages captive ethylene-propylene supply chains to sustain margin stability across EPDM tire and sealing grades. LANXESS anchors its position through advanced hydrogenated nitrile rubber technology for high-temperature powertrain applications. Mitsui Chemicals differentiates via proprietary metallocene catalyst platforms that dominate precision injection molding segments for Asian OEM supply chains.
Automotive elastomers are synthetic or natural polymers with elastic recovery exceeding 200% strain, formulated with sulfur, peroxide, or metal oxide crosslinking systems to deliver temperature resistance from minus 60°C to 300°C depending on base polymer chemistry. These materials function primarily as dynamic seals, vibration dampers, and flexible barriers that maintain sealing force across thermal cycles and fluid exposure in vehicle assemblies. Silicone and fluoroelastomer categories command premium positioning as electrification raises thermal management and chemical resistance requirements for battery cooling and e-motor encapsulation. EPDM sustains volume leadership in weatherstrip and coolant hose applications where cost-performance balance favors ethylene-propylene-diene monomer formulations. SBR competes aggressively in tire tread compounds as rolling resistance regulations tighten across multiple jurisdictions.
EPA tailpipe standards, REACH substance restrictions, and China's GB automotive emission regulations collectively mandate reduced volatile organic compound release from interior trim and fuel system elastomer components. EMA and FDA frameworks additionally govern medical-grade silicone crossover applications that increasingly supply automotive sensor encapsulation. Stakeholders must monitor regulatory divergence between European chemical hazard classifications and Asian material approval pathways when allocating formulation development resources.
Market Dynamics
Electrification is fragmenting elastomer demand into thermal management and high-voltage sealing specializations that diverge sharply from legacy internal combustion formulations. Battery pack architectures now specify silicone and fluoroelastomer grades that tolerate 180°C continuous exposure, forcing compounders to abandon commodity EPDM positions in powertrain-adjacent segments.
Growth Catalysts
- EPA tailpipe standards:Tightening volatile organic compound limits for fuel system components mandate fluorocarbon and hydrogenated nitrile rubber upgrades across US vehicle production.
- Battery thermal management:Liquid cooling circuits in electric vehicle platforms specify platinum-cured silicone grades for hose and gasket applications that resist glycol degradation.
- Germany:The KBA enforces ECE R118 fire safety protocols that accelerate halogen-free flame retardant elastomer adoption in commercial vehicle interior applications.
Market Restraints
- Propylene feedstock volatility:EPDM margins compress when naphtha-cracker output fluctuates, exposing non-integrated compounders to raw material cost spikes without captive ethylene supply.
- Fluoropolymer supply concentration:Perfluoroelastomer precursor manufacturing clusters in Japan and China, creating single-source vulnerability for aerospace-grade automotive crossover specifications.
- REACH substance restrictions:ECHA candidate list updates on medium-chain chlorinated paraffins force reformulation of conveyor belt and under-hood hose compounds with unproven plasticizer alternatives.
Strategic Opportunities
- India:PLI scheme incentives for electric vehicle component localization create first-mover advantage for domestic silicone compounding capacity serving Maruti Suzuki and Tata Motors supply chains.
- Sensor encapsulation:Medical-grade silicone crossover applications for lidar and camera housing seals command 40-60% price premiums over standard automotive grades with FDA-compliant contamination protocols.
- Closed-loop recycling:Pyrolysis-derived carbon black from end-of-life tires integrates into new EPDM formulations, aligning with EU Green Deal circular economy mandates for 25% recycled content targets.
Industry Challenges
- Metallocene catalyst expertise:Precision polymerization for narrow molecular weight distribution grades requires polymer scientists with organometallic chemistry backgrounds that automotive compounders rarely retain in-house.
- Homologation timeline compression:OEM platform cycles now demand 18-month material qualification windows versus 36-month historical baselines, stretching testing laboratory capacity at TÜV and SGS facilities.
- Legacy equipment retrofit:Existing EPDM extrusion lines lack temperature control precision for high-consistency silicone processing, forcing capital allocation decisions between greenfield investment and equipment replacement.
Report Scope
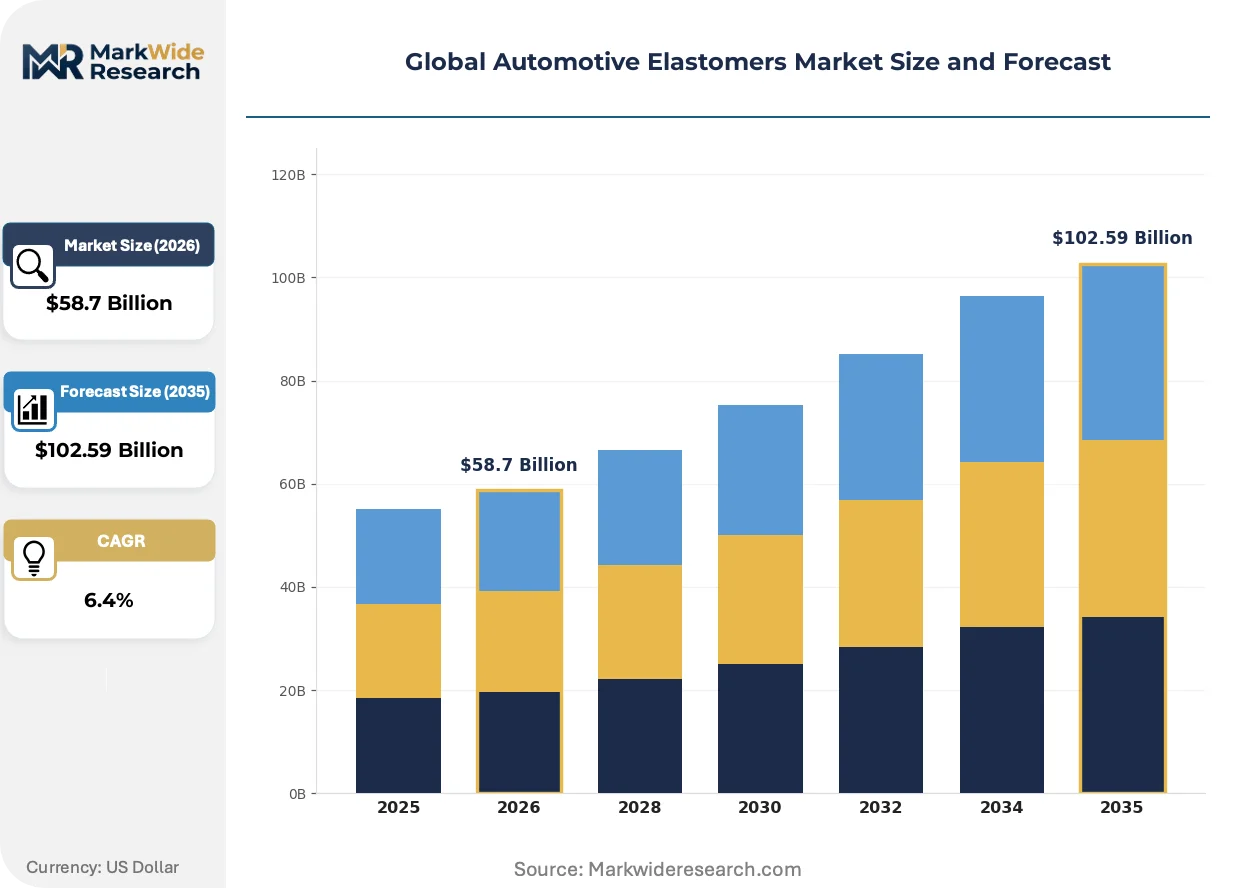
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Elastomers Market |
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $102.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SBR, NBR, EPDM, Silicone, Fluoroelastomers Application: Tire Components, Sealing Systems, Vibration Isolation, Fuel System Parts, Interior Trim End User: OEM Manufacturers, Aftermarket Suppliers, Tier-1 Suppliers, Vehicle Refurbishment Services Manufacturing Process: Injection Molding, Compression Molding, Extrusion, Calendering, Transfer Molding |
| Companies Covered | Dow, LANXESS, DuPont, ExxonMobil Corporation, BASF SE, SABIC, Huntsman International LLC, Mitsui Chemicals, Inc., Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Elastomers Market Shifts & Advancements
Material science convergence with electrification requirements is collapsing the traditional segmentation between commodity and specialty elastomer grades. Formulation capabilities now determine competitive position more than scale economies.
Self-healing silicone formulations incorporating reversible Diels-Alder crosslinks are decomposing the historical trade-off between processability and service temperature in gasket applications. BMW and Hyundai procurement teams specify these grades for battery module compression pads that must maintain seal integrity across 15-year vehicle lifespans. The technology is decomposing incumbent two-part silicone systems that required secondary curing operations, compressing supplier margins on standard liquid injection molding compounds.
REACH authorization requirements for diisocyanates in polyurethane casting operations are accelerating water-based adhesive substitutions in interior trim lamination. German Tier 1 suppliers now qualify hot-melt reactive polyurethane alternatives that eliminate solvent-based processing hazards. Interior headliner and door panel manufacturers in Stuttgart and Wolfsburg clusters absorb compliance costs through automated dispensing equipment retrofits.
Automotive OEMs now consolidate elastomer procurement through platform-level material councils rather than component-specific purchasing functions. Volkswagen Group's unified specification database forces compounders to compete across multiple vehicle lines simultaneously rather than defending single-component relationships. This concentration is most visible in China, where BYD and NIO centralize silicone and fluoroelastomer sourcing decisions at headquarters level, eliminating regional supplier fragmentation that characterized joint-venture era purchasing structures.
Global Automotive Elastomers Market Segmentation
Automotive elastomer procurement now fragments across incompatible performance tiers. OEM material councils consolidate specifications while electrification forces chemistry-specific qualifications that resist supplier interchangeability.
Product Type:
REACH substance restrictions and EPA emissions standards diverge sharply in chemical hazard classification, forcing compounders to maintain parallel formulation portfolios for European and North American vehicle programs.
- EPDM:Ethylene-propylene-diene monomer formulations dominate weatherstrip and coolant hose applications through cost-performance balance. Germany's KBA enforces ECE R118 fire safety protocols that accelerate halogen-free flame retardant grades in commercial vehicle interiors.
- Silicone:Platinum-cured grades tolerate 180°C continuous exposure in battery thermal management circuits. Liquid cooling architectures in BYD and NIO platforms specify these formulations for glycol-resistant hose and gasket applications.
- SBR:Styrene-butadiene rubber competes aggressively in tire tread compounds as rolling resistance regulations tighten across multiple jurisdictions.
- NBR:Nitrile butadiene rubber seals fuel system components under EPA volatile organic compound limits.
- Fluoroelastomers:Perfluorinated grades command premium positioning for high-temperature powertrain sealing in hydrogenated internal combustion applications.
EPDM handles the majority of throughput; silicone is the fastest mover on share.
Application:
Cost tier differentiation separates commodity sealing from sensor-grade encapsulation specifications.
- Tire Components:Tread compounds integrate pyrolysis-derived carbon black from end-of-life tires, aligning with EU Green Deal circular economy mandates for recycled content thresholds.
- Sealing Systems:Battery pack architectures specify fluoroelastomer and silicone grades for high-voltage isolation, displacing commodity EPDM from powertrain-adjacent positions.
- Vibration Isolation:Engine mount and suspension bushing formulations balance dynamic stiffness across thermal cycles.
- Fuel System Parts:Hydrogenated nitrile rubber upgrades satisfy EPA tailpipe standards for volatile organic compound containment.
- Interior Trim:Water-based adhesive substitutions accelerate as REACH authorization requirements for diisocyanates force polyurethane casting reformulation.
Sealing systems absorb the steepest investment in qualification capacity; tire components retain the largest absolute volume position.
End User:
Procurement concentration varies dramatically by vehicle program maturity and regional supply chain structure.
- OEM Manufacturers:Volkswagen Group's unified specification database forces compounders to compete across multiple vehicle lines simultaneously rather than defending single-component relationships.
- Tier-1 Suppliers:Stuttgart and Wolfsburg clusters absorb compliance costs through automated dispensing equipment retrofits for hot-melt reactive polyurethane alternatives.
- Aftermarket Suppliers:Distribution networks serve replacement demand for legacy internal combustion sealing systems.
- Vehicle Refurbishment Services:End-of-life vehicle directives in the European Union create secondary material recovery channels.
Tier-1 suppliers manage the densest qualification workload; OEM direct procurement is expanding most quickly as platform consolidation accelerates.
Manufacturing Process:
Existing asset bases constrain chemistry migration as electrification raises thermal management requirements.
- Injection Molding:Precision metallocene-catalyzed EPDM grades dominate Asian OEM supply chains through narrow molecular weight distribution. Mitsui Chemicals leverages proprietary catalyst platforms for this segment.
- Extrusion:Legacy EPDM extrusion lines lack temperature control precision for high-consistency silicone processing, forcing capital allocation decisions between greenfield investment and equipment replacement.
- Compression Molding:Gasket and seal production accommodates lower volume specialty grades.
- Calendering:Sheet goods manufacturing serves conveyor belt and under-hood hose applications.
- Transfer Molding:Complex geometry components require precise cavity filling control.
Injection molding commands the highest technical barrier; extrusion carries the largest installed base requiring retrofit investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in automotive elastomers track vehicle production density and regulatory stringency. Germany and China maintain trade surpluses in specialty grades, while the United States absorbs significant fluoroelastomer imports for powertrain applications.
United States
Domestic battery plant construction drives silicone thermal management demand across Michigan, Tennessee, and South Carolina facilities. EPA tailpipe standards enforce volatile organic compound limits that upgrade hydrogenated nitrile rubber specifications for fuel system sealing. Detroit-Windsor corridor compounders invest in platinum-cured silicone capacity to serve General Motors and Ford electric platform launches.
Germany
KBA enforcement of ECE R118 fire safety protocols accelerates halogen-free flame retardant elastomer adoption in commercial vehicle interiors. Stuttgart and Wolfsburg clusters absorb REACH compliance costs through automated dispensing equipment retrofits for water-based adhesive substitutions. LANXESS anchors hydrogenated nitrile rubber production for high-temperature powertrain applications serving Volkswagen Group consolidated procurement.
China
GB automotive emission regulations tighten specifications for fuel system and under-hood elastomer components across BYD and NIO centralized sourcing structures. MIIT dual carbon goals pressure compounders toward pyrolysis-derived carbon black integration in tire tread formulations. Yangtze River Delta silicone producers expand metallocene-catalyzed capacity for precision battery cooling circuit specifications.
Japan
METI industrial policy supports fluoroelastomer precursor manufacturing concentration that supplies aerospace-grade automotive crossover specifications. Nagoya and Osaka chemical complexes maintain perfluoroelastomer output for thermal management applications in Toyota and Honda electrification programs. Domestic compounders face feedstock vulnerability from naphtha-cracker output fluctuations.
India
PLI scheme incentives for electric vehicle component localization create first-mover positioning for domestic silicone compounding capacity. Maruti Suzuki and Tata Motors supply chains absorb reformulation costs as BIS standards converge with REACH substance restrictions. Gujarat and Maharashtra polymer hubs attract backward integration investments from ethylene-propylene producers.
Global Automotive Elastomers Market Competitive Landscape
Concentration sits with integrated polymer producers that control captive ethylene supply chains. Three to five multinational chemical conglomerates anchor volume positions in EPDM and silicone categories. The competitive terrain separates into commodity compounders serving tire and weatherstrip applications versus specialty formulators targeting battery thermal management. Strategic moves emphasize backward integration into propylene feedstocks and metallocene catalyst licensing agreements.
Within the integrated producer tier, Dow and ExxonMobil Corporation represent scale-driven positions anchored in North American ethylene infrastructure. LANXESS and BASF SE exemplify European specialty orientation toward hydrogenated nitrile and advanced fluoroelastomer grades. Mitsui Chemicals, Inc. occupies the Asian precision molding segment through proprietary catalyst platforms. DuPont, Arkema, and Huntsman International LLC sit within diversified material science portfolios that span automotive crossover applications.
| Leading Market Players |
|---|
| Dow |
| LANXESS |
| DuPont |
| ExxonMobil Corporation |
| BASF SE |
| SABIC |
| Huntsman International LLC |
| Mitsui Chemicals, Inc. |
| Arkema |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between integrated polymer producers and OEM material councils lock in ethylene-propylene supply access while constraining price visibility for non-integrated compounders exposed to naphtha-cracker volatility. These contracts tether EPDM and silicone pricing to feedstock indices, amplifying margin compression when propylene spot markets fluctuate.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across premium fluoroelastomer, standard silicone, and economy EPDM tiers. Price differentiation hinges on REACH certification grade and volume scale commitments, with battery-grade silicone commanding substantial premiums over weatherstrip formulations. Cost compression in commodity EPDM segments is intensifying because backward-integrated producers leverage captive ethylene supply. Tier-1 suppliers exhibit highest price sensitivity due to consolidated procurement mandates, while sensor encapsulation specialists absorb premium pricing with minimal negotiation leverage.
Supply Chain Analysis
Naphtha feedstock transit through Rotterdam-Rhine corridor terminals underwrites European EPDM production economics. Manufacturing concentrates in Germany, China, and the United States, with perfluoroelastomer precursor output clustering in Japan. Raw material dependencies encompass ethylene-propylene monomers, metallocene catalyst systems, and platinum-curing agents. Single-source vulnerability pervades aerospace-grade fluoroelastomer supply. Distribution runs through platform-level material councils that consolidate multi-vehicle line specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as electric vehicle thermal management requirements penetrate beyond premium segments into mass-market battery platforms. Electrification adoption curves justify capacity positioning ahead of qualification timeline compression.
For Market Incumbents: Consolidate metallocene catalyst licensing agreements to defend precision molding positions against Asian compounders with proprietary organometallic platforms. Add platinum-cured silicone capacity in Michigan-Tennessee corridor to capture General Motors and Ford electric platform demand. Lock in long-term propylene supply contracts before naphtha-cracker volatility intensifies.
For New Entrants and Emerging Players: Differentiate on sensor-grade silicone encapsulation protocols that command FDA-compliant contamination premiums for lidar and camera housing applications. Target India's PLI scheme incentives for domestic compounding capacity serving Maruti Suzuki and Tata Motors supply chains. Pursue joint development agreements with Yangtze River Delta battery producers to bypass entrenched qualification barriers.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier compounders with backward integration pathways into ethylene-propylene feedstocks and existing OEM qualification relationships. Five-to-ten year viability hinges on electrification content-per-vehicle trajectories. Monitor pyrolysis-derived carbon black integration rates as circular economy mandate compliance signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene-Propylene Feedstocks | Dow and LANXESS anchor margin stability through captive naphtha-cracker output. |
| Metallocene Catalyst Licensing Agreements | Mitsui Chemicals leverages proprietary platforms to dominate Asian precision molding segments. |
| Platinum-Cured Silicone Capacity Expansion | Detroit-Windsor corridor investments serve General Motors Ultium battery thermal management specifications. |
| Pyrolysis-Derived Carbon Black Integration | EU Green Deal circular economy mandates drive 25% recycled content targets in tire tread formulations. |
| Sensor-Grade Silicone Qualification Pathways | FDA-compliant encapsulation protocols unlock 40-60% price premiums for lidar and camera housing seals. |
Research Methodology
Operator-level perspectives from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and compounder technical R&D directors anchored the qualitative base. Primary interviews combined with secondary validation from SEC 10-K filings, customs and trade data, ACC and Cefic industry reports, and vehicle production databases. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers to ensure cross-verification.
Sensitivity analysis tested forecast robustness across propylene price volatility scenarios, electrification penetration rates, and REACH substance restriction timelines. The analytical framework segmented by product chemistry, application thermal requirements, vehicle propulsion architecture, and regional regulatory stringency across the analysis window. CAGRs derived from elasticity-adjusted demand curves incorporating battery pack architecture evolution and content-per-vehicle trajectories.
Material uncertainties — feedstock price spikes, regulatory divergence between ECHA and EPA hazard classifications, and metallocene catalyst supply concentration — sit outside the modeled envelope. Forecasts reflect assumptions about qualification timeline compression and OEM platform consolidation trajectories. Practitioners should keep alternative scenarios live as hydrogenated internal combustion applications and solid-state battery thermal management specifications evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Global Rubber Coated Fabrics Market
Rubber
Polyisoprene Market
Rubber
Rubber Splicing Tape Market
Rubber
Polybutadiene Market
Rubber
Neoprene Rubber Market
Rubber
Silica for S-SBR Market
Rubber
Nitrile Butadiene Rubber Market
Rubber
Europe Neoprene Market
Rubber
Rubber Foam Materials Market
Rubber
Specialty Nitrile Butadiene Rubber (NBR) Market
Rubber
Europe Rubber Derived Unrefined Pyrolysis Oil Market
Rubber
EPDM Market
Rubber
Rubber Molding Market
Rubber
Global Rubber Processing Chemicals Market
Rubber
Styrene Butadiene (SB) Latex Market
Rubber
Rubber Tapes Market