
 Asia Pacific Medical Rubber and Balloon Product Market | 2026-2036
Asia Pacific Medical Rubber and Balloon Product Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Medical Rubber and Balloon Product Market Outlook
Aftermarket service revenue for balloon catheter refurbishment is reconfiguring margin distribution between original equipment and third-party reprocessors. Hartalega Holdings Berhad leverages its integrated glove-to-device manufacturing footprint across Malaysia to sustain cost advantages in latex component supply. Terumo Corporation anchors its position through captive polymer compounding operations in Japan, while Boston Scientific Corporation differentiates via proprietary balloon molding technology for coronary interventions.
Asia Pacific medical rubber and balloon products encompass elastomer-based components and inflatable devices manufactured through dip molding, extrusion, or blow-forming processes, with wall thickness tolerances typically ranging from 0.02 mm to 0.15 mm depending on pressure-rated applications. These products serve critical functions in fluid management, vessel occlusion, and minimally invasive access across interventional medicine. Catheters command the largest product type share due to procedural volume in cardiology and urology, while balloons represent the fastest-expanding segment driven by drug-eluting and scoring balloon adoption in percutaneous coronary intervention. Silicone material demand is outpacing natural rubber growth as PMDA and CDSCO biocompatibility standards harden against latex protein allergenicity.
Japan's PMDA, India's CDSCO, and Australia's TGA enforce divergent biocompatibility and sterilization validation requirements that fragment product registration pathways across the region. Malaysia's MDA and Thailand's FDA are harmonizing with ASEAN Medical Device Directive frameworks, though substantive convergence remains incomplete. Stakeholders must monitor regulatory divergence costs against the scale advantages of centralized manufacturing hubs in Penang and Shenzhen.
Market Dynamics
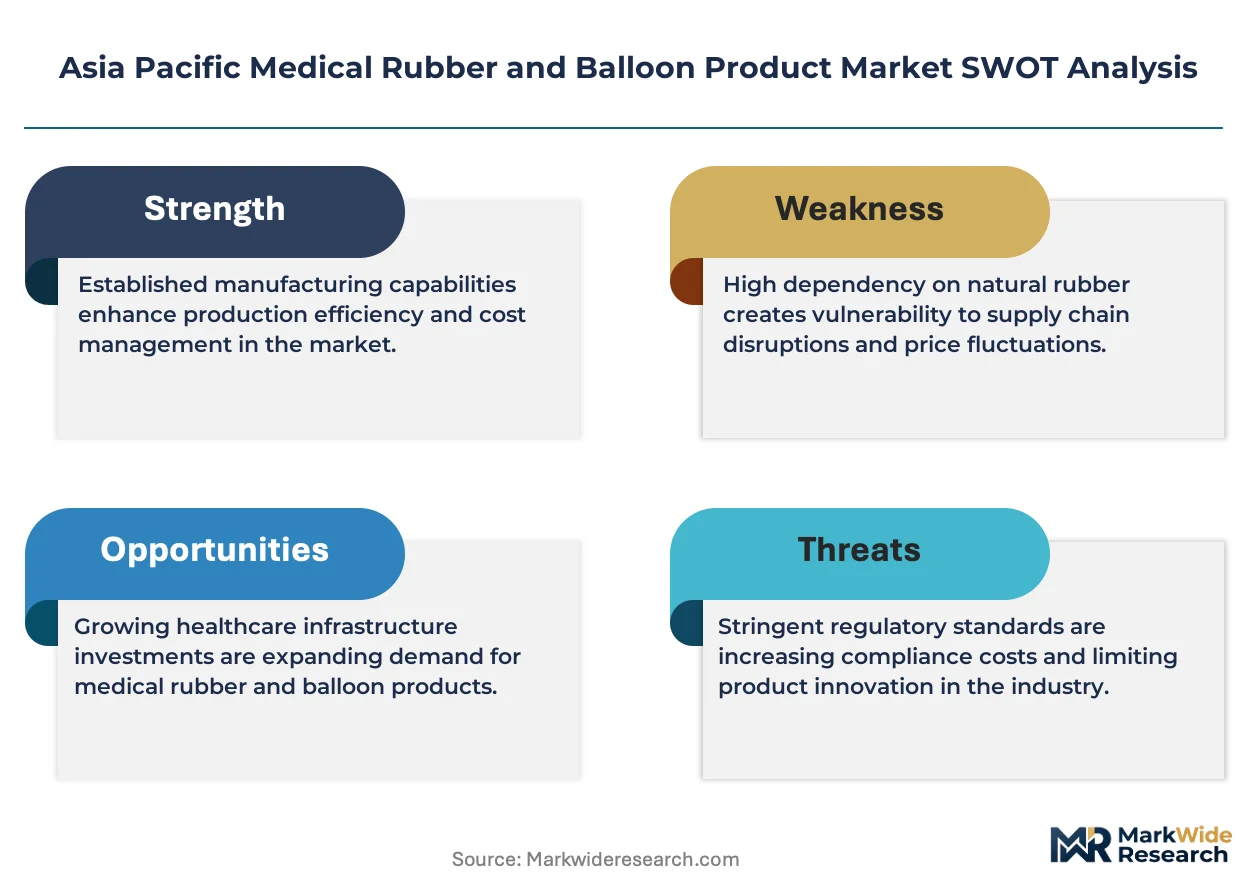
Japan's PMDA biocompatibility tightening is accelerating silicone substitution across catheter and balloon manufacturing, compressing natural rubber supply chains while elevating compound purity requirements for interventional device producers.
Growth Catalysts
- ASEAN MDD Harmonization:Malaysia's MDA and Thailand's FDA are aligning registration frameworks, reducing duplicate testing costs for multi-country product launches.
- India's PLI Scheme for Medical Devices:Domestic catheter production incentives are expanding capacity for government cardiac care procurement.
- Drug-Eluting Balloon Adoption:Cardiology departments in Southeast Asian hospitals are prioritizing scoring balloon procurement for percutaneous coronary intervention volume growth.
Market Restraints
- Natural Rubber Price Volatility:Malaysian latex supply concentration exposes manufacturers to climate-driven input cost swings and currency fluctuation.
- Silicone Feedstock Bottleneck:Japan and South Korea dominate high-purity silicone monomer production, creating geographic supply risk for regional device makers.
- PMDA Allergenicity Testing Burden:Extended protein quantification protocols for latex-containing devices are elongating registration timelines without parallel revenue offset.
Strategic Opportunities
- Vietnam's Underpenetrated Interventional Cardiology:Public hospital infrastructure expansion creates first-mover positioning for balloon catheter suppliers.
- Indonesia's Urology Device Gap:Domestic production scarcity for urinary catheter systems invites localized manufacturing partnerships.
- Digital Procurement Platforms:Hospital group purchasing organizations in Australia are consolidating supplier access through centralized e-procurement portals.
Industry Challenges
- Polymer Compounding Talent Scarcity:Specialized elastomer formulation expertise concentrates in Japan and Malaysia, constraining regional expansion.
- Multi-Regulatory Certification Burden:Divergent sterilization validation requirements across PMDA, CDSCO, and TGA force redundant testing expenditure.
- Legacy Late-to-Silicone Conversion:Existing dip-molding equipment retrofit costs are compressing margins for mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Medical Rubber and Balloon Product Market |
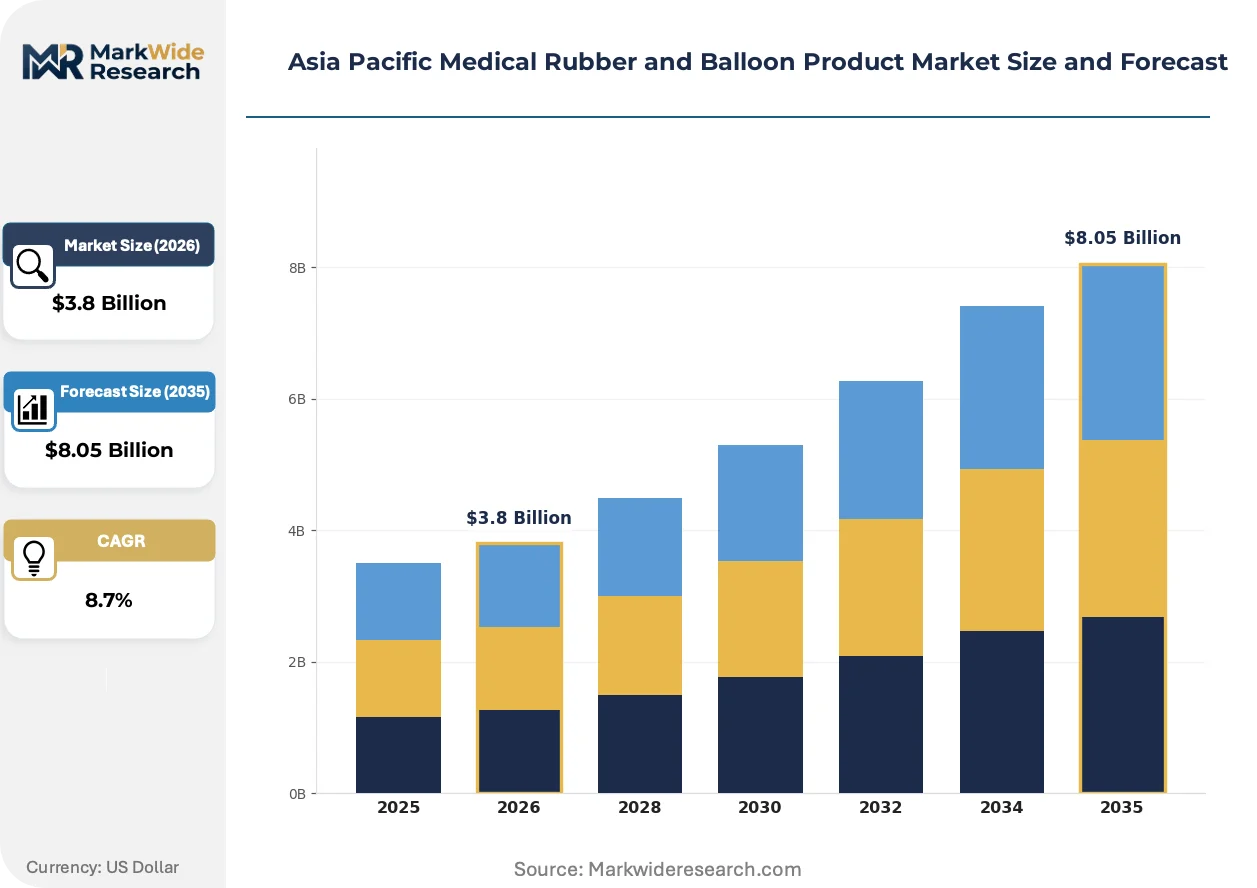
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Syringe Components, Catheters, Balloons, Seals Application: Cardiology, Urology, Surgical, Diagnostic Material: Natural Rubber, Synthetic Rubber, Silicone, Latex End User: Hospitals, Clinics, Laboratories, Home Care |
| Companies Covered | Hartalega Holdings Berhad, Terumo Corporation, Boston Scientific Corporation, AngioDynamics, B. Braun Melsungen, Adventa Berhad, Rubberex, Cook Medical, Supermax Corporation Berhad, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Medical Rubber and Balloon Product Market Strategic Shifts
Material science advancement and regulatory stringency are converging to reshape manufacturing processes and procurement criteria across Asia Pacific interventional device supply chains.
Silicone elastomer formulations are displacing natural rubber in pressure-rated balloon applications due to superior biocompatibility profiles and reduced protein allergenicity risk. Japanese and Australian hospital procurement committees are mandating latex-free device specifications in tender documentation. The technology is migrating from coronary intervention into peripheral vascular and urological applications, expanding addressable procedure volumes.
PMDA's 2023 biocompatibility guidance revision imposed quantitative protein limit thresholds for latex-containing medical devices. Device manufacturers are reformulating compounds and resubmitting registration dossiers to maintain market access. Cardiology catheter segments face the steepest compliance cost escalation, with some producers accelerating full silicone conversion to bypass testing overhead.
Hospital group purchasing organizations in Australia and Singapore are consolidating supplier relationships through multi-year framework agreements. Traditional distributor networks face margin compression as procurement authority centralizes at health system level. This concentration is most pronounced in cardiac care programs where volume commitments secure preferential balloon catheter pricing tiers.
Asia Pacific Medical Rubber and Balloon Product Market Segmentation
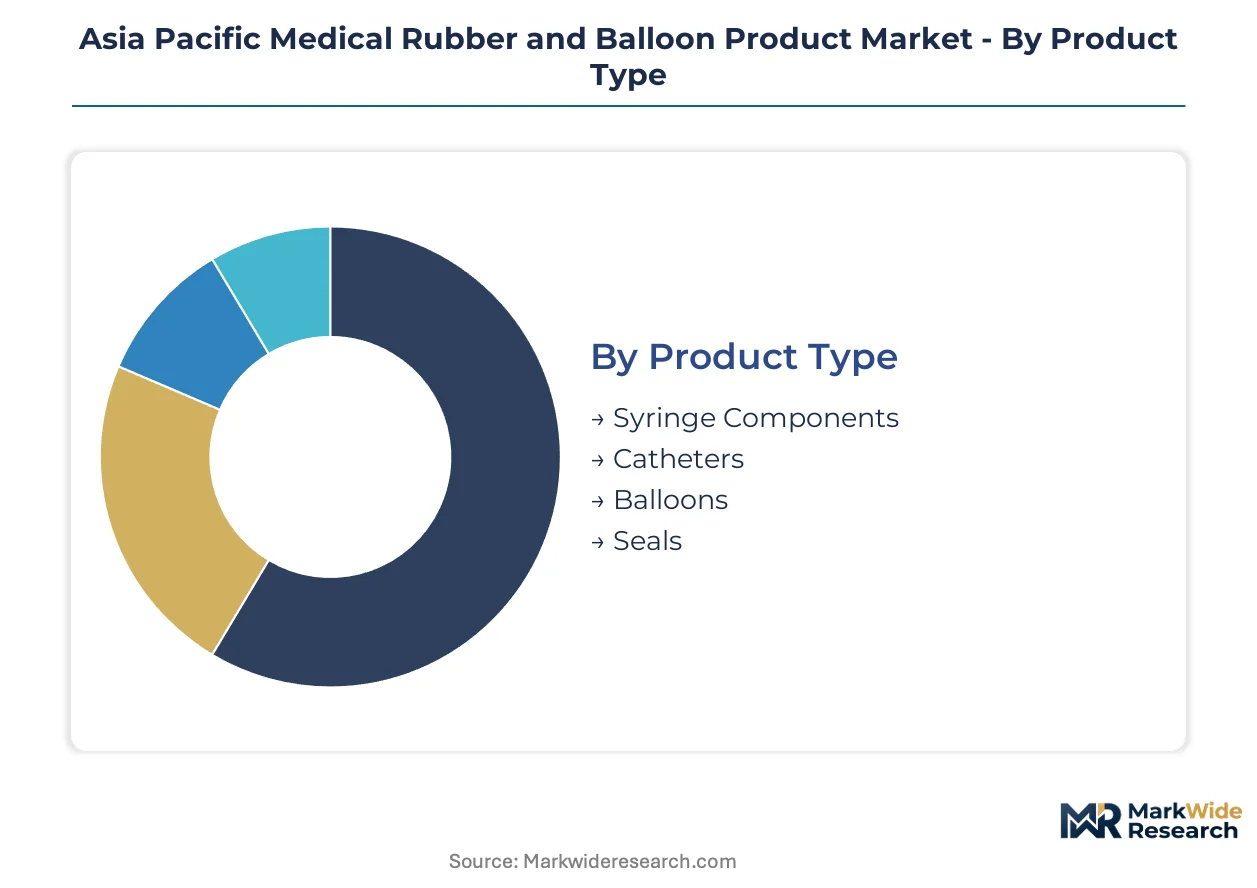
Segmentation in Asia Pacific medical rubber and balloon products reveals how material substitution pressures and procedural specialization are fragmenting procurement requirements across interventional medicine supply chains. Manufacturers must align compound formulations and molding capabilities against distinct performance thresholds for pressure-rated balloons versus static seals.
Product Type:
Device architecture spans fluid delivery, vessel access, occlusion, and containment functions with divergent wall thickness and elastomer purity specifications.
- Catheters:Multi-lumen extrusions and tip-forming configurations dominate procedural volume in cardiac catheterization laboratories across India and Southeast Asia. Government-funded cardiac care programs in India are expanding procurement of coronary guiding catheters while Japan's PMDA biocompatibility tightening elevates silicone purity requirements for neurovascular access devices.
- Balloons:Blow-formed elastomer membranes with calibrated compliance curves enable vessel dilation and drug delivery in percutaneous coronary intervention. Drug-eluting balloon adoption in South Korean and Australian cardiology departments is accelerating demand for thin-walled, high-pressure-rated formulations with sub-0.05 mm thickness tolerance.
- Syringe Components:Piston seals and plunger tips require compression set resistance across sterilization cycles.
- Seals:Static and dynamic gasket applications in diagnostic equipment housings.
Established volume favors catheters; emerging adoption favors balloons.
Application:
Clinical specialization dictates performance validation protocols and reimbursement pathways across interventional disciplines.
- Cardiology:Coronary and peripheral vascular interventions demand burst-pressure-rated balloons and torque-responsive catheter shafts with hydrophilic coating compatibility. Southeast Asian hospital procurement committees are consolidating supplier frameworks for scoring balloon systems as percutaneous coronary intervention volumes climb in Vietnam and Indonesia.
- Urology:Drainage and access catheters require kink resistance and biostability in prolonged indwelling applications. India's domestic manufacturing incentives under the PLI scheme are expanding capacity for Foley catheter production to serve public hospital procurement.
- Surgical:Trocar seals and insufflation components for minimally invasive procedures.
- Diagnostic:Blood collection system septa and instrument interface gaskets.
Cardiology commands premium pricing tiers; urology offers volume scale through standardized specifications.
Material:
Regulatory allergenicity thresholds and pressure performance requirements are driving compound reformulation across manufacturing footprints.
- Silicone:Platinum-cured elastomers deliver superior biocompatibility profiles and thermal stability for high-pressure balloon applications. PMDA's quantitative protein limit thresholds are accelerating silicone substitution in Japan while CDSCO alignment pressures mount for India-registered devices.
- Synthetic Rubber:Nitrile and isoprene formulations balance cost and performance in non-implant, short-duration applications. Malaysian compounders are expanding nitrile capacity for glove-to-device manufacturing integration.
- Natural Rubber:Hevea brasiliensis latex retains cost advantage in low-pressure seals despite protein allergenicity constraints.
- Latex:Prevailing in legacy device registrations facing extended PMDA protein quantification protocols.
Silicone gains share fastest in pressure-rated segments; synthetic rubber defends position in cost-sensitive disposables.
End User:
Procurement authority concentration and sterilization infrastructure availability segment demand across care settings.
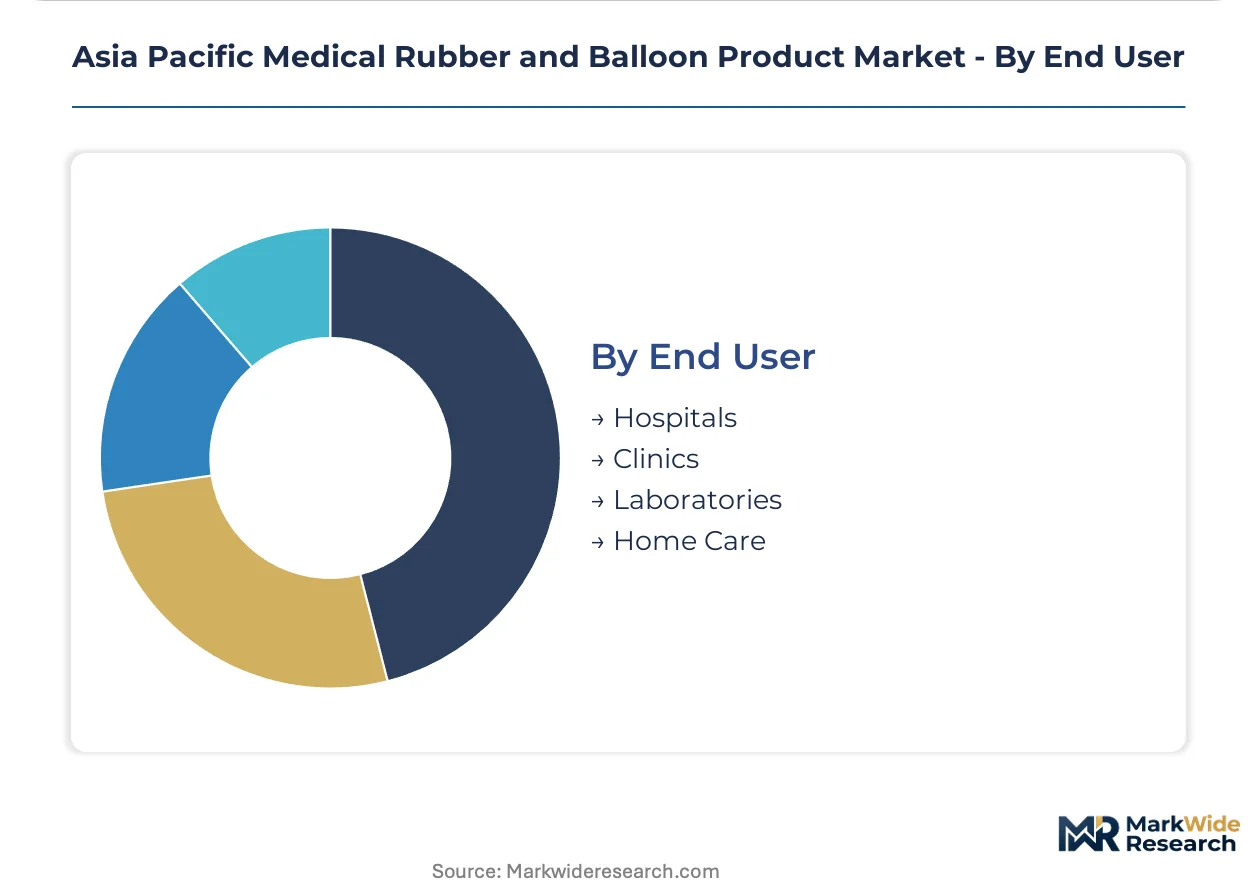
- Hospitals:Tertiary cardiac centers and interventional suites in Australia and Singapore drive consolidated purchasing through group purchasing organization frameworks. Multi-year balloon catheter agreements are compressing distributor margins while securing volume commitments for manufacturers.
- Clinics:Ambulatory surgical centers in Thailand and Malaysia prioritize single-use catheter bundles with simplified inventory management.
- Laboratories:Diagnostic reagent containment and automated analyzer interface components.
- Home Care:Intermittent urinary catheter systems for patient self-administration.
Hospital procurement centralization favors integrated suppliers; clinic fragmentation sustains distributor networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across the region. Japan and Australia prioritize silicone-based, high-purity devices for interventional cardiology. India and Southeast Asian markets emphasize cost-optimized catheters for high-volume public health programs.
Japan
PMDA's quantitative protein limit thresholds for latex-containing devices are accelerating full silicone conversion among domestic manufacturers. Tokyo and Osaka cardiac centers drive premium balloon catheter procurement through consolidated purchasing frameworks. The Kanto region hosts captive polymer compounding operations that supply regional device makers with high-purity elastomer feedstock.
India
CDSCO alignment pressures are mounting for latex protein testing as domestic catheter production scales under the PLI scheme for medical devices. Government-funded cardiac care programs in Maharashtra and Karnataka are expanding procurement of coronary guiding catheters. The Delhi-NCR corridor is emerging as a manufacturing hub for Foley catheter systems serving public hospital networks.
Australia
TGA sterilization validation requirements are elevating compliance costs for imported balloon devices while hospital group purchasing organizations consolidate supplier access. Sydney and Melbourne cardiac centers are mandating latex-free specifications in tender documentation. The Southeast Queensland corridor is attracting regional distribution centers for Asia-sourced silicone components.
Malaysia
MDA harmonization with ASEAN Medical Device Directive frameworks is reducing duplicate testing costs for multi-country product launches. Penang's integrated glove-to-device manufacturing clusters are sustaining cost advantages in latex component supply. Domestic compounders are expanding nitrile capacity to serve regional demand for non-implant, short-duration applications.
Vietnam
Public hospital infrastructure expansion in Ho Chi Minh City and Hanoi is creating first-mover positioning for balloon catheter suppliers targeting underpenetrated interventional cardiology. The country's national pharmaceutical regulator is aligning biocompatibility standards with ASEAN frameworks. The Red River Delta is attracting manufacturing partnerships for urinary catheter systems addressing domestic production scarcity.
Asia Pacific Medical Rubber and Balloon Product Market Competitive Environment
Capability concentration sits with integrated polymer compounders; scale advantage sits with high-volume disposable manufacturers. The vendor base separates into three tiers: captive compounders with backward integration into raw material supply, specialized balloon molders with proprietary process technology, and contract manufacturers serving procurement consolidation trends. Dominant competitive moves include capacity expansion in ASEAN manufacturing corridors and strategic partnerships to secure silicone monomer feedstock.
Within the integrated manufacturing tier, Hartalega Holdings Berhad exemplifies the glove-to-device production model across Malaysian facilities. Terumo Corporation occupies a position among Japan-based compounders with captive elastomer operations. Boston Scientific Corporation represents the specialized device technology archetype with differentiated process capabilities for interventional applications.
| Leading Market Players |
|---|
| Hartalega Holdings Berhad |
| Terumo Corporation |
| Boston Scientific Corporation |
| AngioDynamics |
| B. Braun Melsungen |
| Adventa Berhad |
| Rubberex |
| Cook Medical |
| Supermax Corporation Berhad |
| Others |
Value Chain & Pricing Dynamics
Malaysian latex supply concentration and Japanese silicone monomer production dominance anchor margin distribution across Asia Pacific interventional device supply chains. Compound purity requirements from PMDA and CDSCO are elevating feedstock qualification costs while hospital procurement centralization compresses distributor tiers.
Pricing Analysis
Long-term framework agreements between hospital group purchasing organizations and balloon catheter manufacturers dominate procurement structures across Australia and Singapore. Price differentiation rests on silicone purity grades and PMDA biocompatibility certification tiers, with premium formulations commanding substantial markups over standard latex alternatives. Pricing pressure stems from India's PLI scheme expanding domestic catheter production capacity and pressuring import-dependent suppliers. Public hospital procurement committees in Southeast Asia exhibit highest price sensitivity, while Japanese tertiary cardiac centers prioritize performance specifications over unit cost.
Supply Chain Analysis
Contract manufacturing capacity concentrates with Malaysian glove-to-device integrated producers and Japanese captive compounders serving regional device makers. Raw material flows draw from Thai and Indonesian latex plantations alongside South Korean and Japanese high-purity silicone monomer facilities. Single-source vulnerability runs through Japan's dominant position in medical-grade silicone feedstock, where limited qualified alternative suppliers create geographic concentration risk. Distribution runs through hospital group purchasing organization portals in Australia and Singapore, with traditional distributor networks persisting in fragmented clinic segments across Thailand and Vietnam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicone substitution acceleration and PMDA biocompatibility tightening constitute a dual inflection reshaping competitive positioning across Asia Pacific interventional device supply chains. Manufacturers face compressed timelines for compound reformulation and registration dossier resubmission.
For Market Incumbents: Pre-empt margin erosion by accelerating captive silicone compounding capacity in Penang or Kanto corridor facilities before CDSCO alignment pressures harden across India. Secure multi-year offtake agreements with South Korean monomer suppliers to lock feedstock access against supply bottleneck escalation. Reinforce hospital GPO relationships through bundled catheter-balloon offerings that exploit existing tender frameworks.
For New Entrants and Emerging Players: Establish a beachhead in Vietnam's underpenetrated interventional cardiology segment where public hospital infrastructure expansion outpaces established supplier coverage. Target Indonesia's urology device gap through localized manufacturing partnerships for urinary catheter systems. Pursue digital procurement platform integration with Australian hospital GPOs as primary go-to-market channel.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Malaysian glove manufacturers seeking device verticalization to escape commoditization. Long-term viability hinges on silicone conversion completion and ASEAN regulatory harmonization capture. Watch PMDA registration timeline acceleration as signal for incumbent restructuring pressure and distressed acquisition opportunity.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicone Conversion Program | Full compound reformulation bypasses PMDA protein quantification burden for latex-containing devices. |
| ASEAN MDD Harmonization Alignment | Unified registration dossiers reduce duplicate testing costs across Malaysia, Thailand, and Vietnam launches. |
| Hospital GPO Partnership | Multi-year framework agreements with Australian cardiac centers secure volume commitments against price erosion. |
| Captive Polymer Compounding | In-house elastomer formulation insulates margin from Japanese and South Korean monomer supply bottlenecks. |
| India PLI Scheme Participation | Domestic catheter production incentives expand capacity for government-funded cardiac care procurement. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with hospital procurement managers, biomedical engineers in cardiac catheterization laboratories, GPO contracts administrators, and polymer compounding technical directors. Secondary validation drew from PMDA registration filings, CDSCO device approval databases, ASEAN Medical Device Directive implementation reports, and hospital tender documentation. Bottom-up procedure volume modeling and top-down elastomer consumption estimates were triangulated to anchor market sizing.
Calibration against historical silicone substitution rates and regulatory timeline elasticity informed projection dynamics across the analysis window. Segmentation dimensions spanned product architecture, clinical application, material compound, and procurement channel concentration. CAGRs were derived from weighted procedure growth assumptions and average selling price trajectory modeling. Forecast inputs incorporated PMDA biocompatibility compliance cost escalation and India's PLI scheme capacity addition schedules.
Stress conditions across natural rubber price volatility bands, silicone monomer supply disruption scenarios, and ASEAN regulatory harmonization delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding procedure volume elasticity and material substitution rates. Quarterly review of PMDA registration backlog indicators and Indian domestic production capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Evacuated Drainage Bottles Market
Medical Supplies
Biodegradable Hemostat Market
Medical Supplies
US N95 Mask Market
Medical Supplies
Retractable Needle Safety Syringes Market
Medical Supplies
Glass Pasteur Pipettes Market
Medical Supplies
Germany Hospital Supplies Market
Medical Supplies
Global Enema Based Products Market
Medical Supplies
Ostomy Drainage Bags Market
Medical Supplies
Surgical Collagen Powders Market
Medical Supplies
Europe Medical Gloves Market
Medical Supplies
Surgical Amniotics Market
Medical Supplies
Disposable Oxygen Masks Market
Medical Supplies
Ostomy Care and Accessories Market
Medical Supplies
Europe Insulin Syringe Market
Medical Supplies
Single Use Safety Lancet Market
Medical Supplies
Push-In Plug Vials Market