
 Low-Calorie Margarine Market | 2026-2036
Low-Calorie Margarine Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Calorie Margarine Market Analytics
Multi-source oil procurement is rebalancing supply relationships across the low-calorie margarine value chain. Unilever Plc anchors its European production through dedicated sunflower and rapeseed processing partnerships in the Netherlands and Germany. Bunge Limited leverages its oilseed crushing infrastructure across North and South America to secure cost-advantaged feedstock flows. Cargill, Incorporated competes through integrated supply contracts that link Brazilian soybean origins directly to European formulation facilities.
Low-calorie margarine denotes a water-in-fat emulsion containing reduced lipid content, typically achieved through elevated water phase incorporation and structured emulsifier systems such as distilled monoglycerides or lecithin blends, yielding spreads with caloric density below standard butter or full-fat margarine alternatives. Spreadable formats dominate retail shelf space due to consumer convenience expectations, while plant-based formulations capture the fastest expansion as vegan label claims penetrate mainstream supermarkets. Tub packaging sustains margin pools through higher unit economics and brand differentiation opportunities compared to commodity stick formats.
FDA nutrition labeling requirements and WHO trans-fat elimination frameworks compel reformulation investments, while EFSA health claim assessments shape permissible marketing language across European markets. The EU F-Gas Regulation indirectly pressures cold-chain packaging specifications for temperature-sensitive spreads. Stakeholders must monitor evolving emulsifier approval pathways and origin-certification demands as clean-label expectations harden procurement criteria.
Market Dynamics
Reformulation mandates from the FDA and WHO are compressing product development cycles across the low-calorie margarine sector, forcing manufacturers to rebuild emulsifier systems and oil sourcing strategies simultaneously.
Growth Catalysts
- WHO Trans-Fat Elimination Framework:Governments across 40+ countries have enacted trans-fat limits, accelerating demand for reformulated spreads that rely on structured emulsifier systems rather than partially hydrogenated oils.
- Bakery Channel Expansion:Artisan and industrial bakeries in Germany and France are specifying reduced-fat spreads for laminated dough applications, creating volume pull through professional ingredient procurement.
- Plant-Based Oil Blending:Advances in high-oleic sunflower and enzymatically interesterified rapeseed processing enable stable water-in-fat emulsions without trans-fat content, unlocking clean-label positioning.
Market Restraints
- Input Cost Volatility:Sunflower oil prices swing with Black Sea supply disruptions, compressing margins for producers dependent on single-origin feedstock procurement.
- Supply Concentration Risk:European emulsifier production clusters in the Netherlands and Belgium, creating vulnerability to F-Gas Regulation compliance costs for cold-chain dependent facilities.
- Technical Limitation:Water-phase incorporation above 60% compromises spreadability and shelf stability, capping caloric reduction potential without texture trade-offs.
Strategic Opportunities
- Underpenetrated Poland and Czech Republic:Retail discounters in Central Europe are expanding private-label reduced-fat spreads, offering first-mover positioning before branded players establish shelf dominance.
- Regulatory Tailwind from EU Green Deal:Farm-to-fork sustainability metrics favor plant-based spreads over dairy butter in public procurement and institutional foodservice contracts.
- Direct-to-Bakery Distribution:Bypassing traditional wholesale intermediaries through refrigerated logistics partnerships lets manufacturers capture margin and formulation collaboration access.
Industry Challenges
- Emulsifier Chemistry Expertise Gap:Distilled monoglyceride formulation and water-phase structuring require specialized food science talent that competes with pharmaceutical and cosmetic sectors.
- EFSA Health Claim Certification Timeline:Substantiating cholesterol-reduction or cardiovascular-benefit claims demands 18-24 month clinical validation, delaying marketing differentiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Calorie Margarine Market |
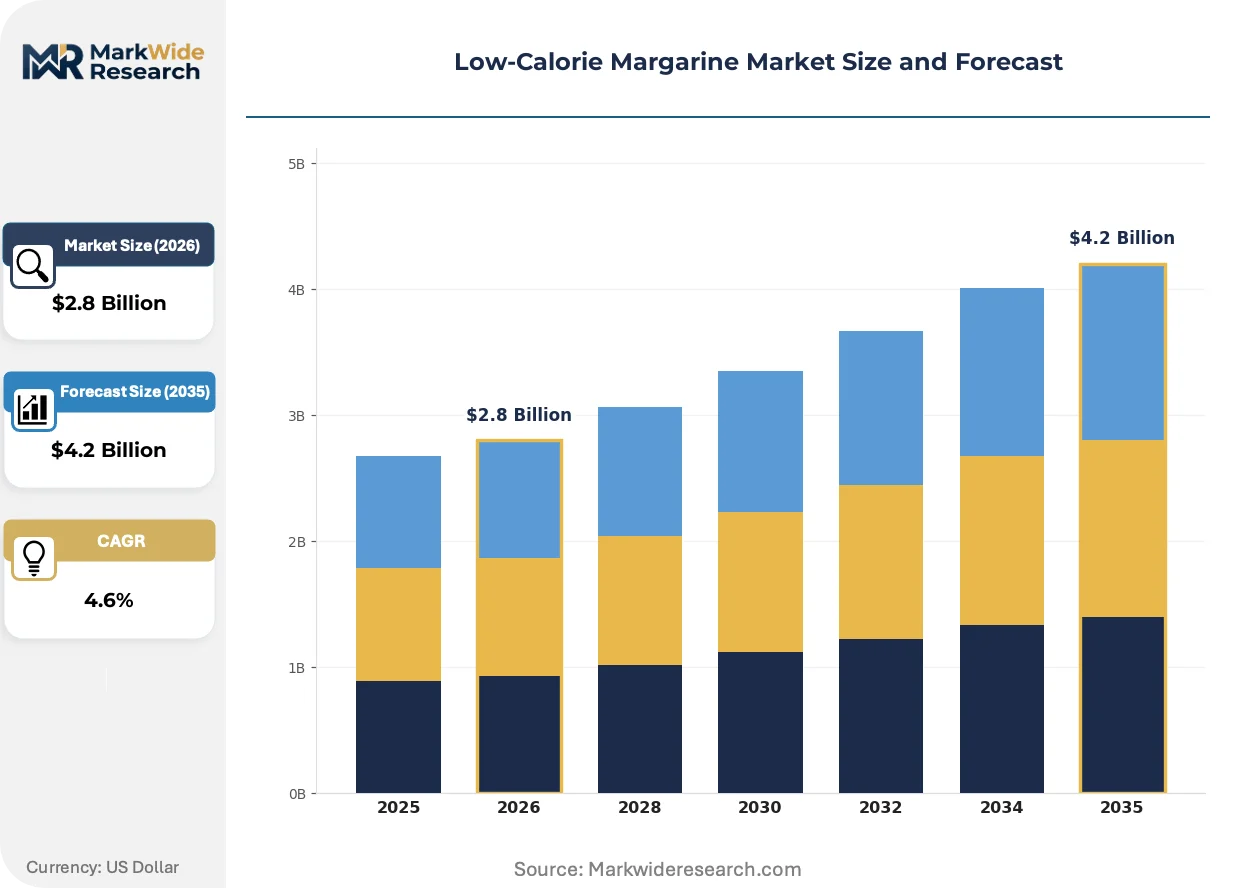
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spreadable, Soft, Liquid, Whipped Formulation: Vegan, Dairy-based, Plant-based, Blended Packaging Type: Tub, Stick, Bottle, Single Serve Distribution Channel: Supermarkets, Online, Convenience Stores, Specialty Stores |
| Companies Covered | Conagra Brands, Inc., Bunge Limited, Unilever Plc, Upfield BV, Wilmar International Ltd., Vandemoortele, BRF SA, NMGK Group, Cargill, Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Calorie Margarine Market Evolving Landscape
Ingredient science and packaging engineering are converging to solve the shelf-stability paradox that has historically constrained water-in-fat emulsion performance in ambient retail conditions.
Enzymatic interesterification is converging with high-pressure homogenization to produce stable reduced-fat spreads without trans-fat content. Industrial bakeries in Northern Europe are piloting these reformulated bases for croissant and puff pastry applications. The technology is converging with clean-label positioning to displace traditional hydrogenation across premium private-label contracts.
EU F-Gas Regulation phase-down schedules are forcing cold-chain packaging redesigns for temperature-sensitive tub formats. Manufacturers must adopt alternative insulation materials or absorb higher refrigerant compliance costs. German retailers are responding by consolidating SKUs into fewer, higher-volume formats to amortize packaging investments.
Bakery procurement teams are consolidating supplier relationships around integrated oil-plus-emulsifier contracts rather than sourcing components separately. This compresses the vendor base for mid-sized margarine producers while rewarding integrated crushers with formulation partnerships. The shift is most visible in France, where industrial bakers prioritize single-source accountability for lipid functionality.
Low-Calorie Margarine Market Segmentation
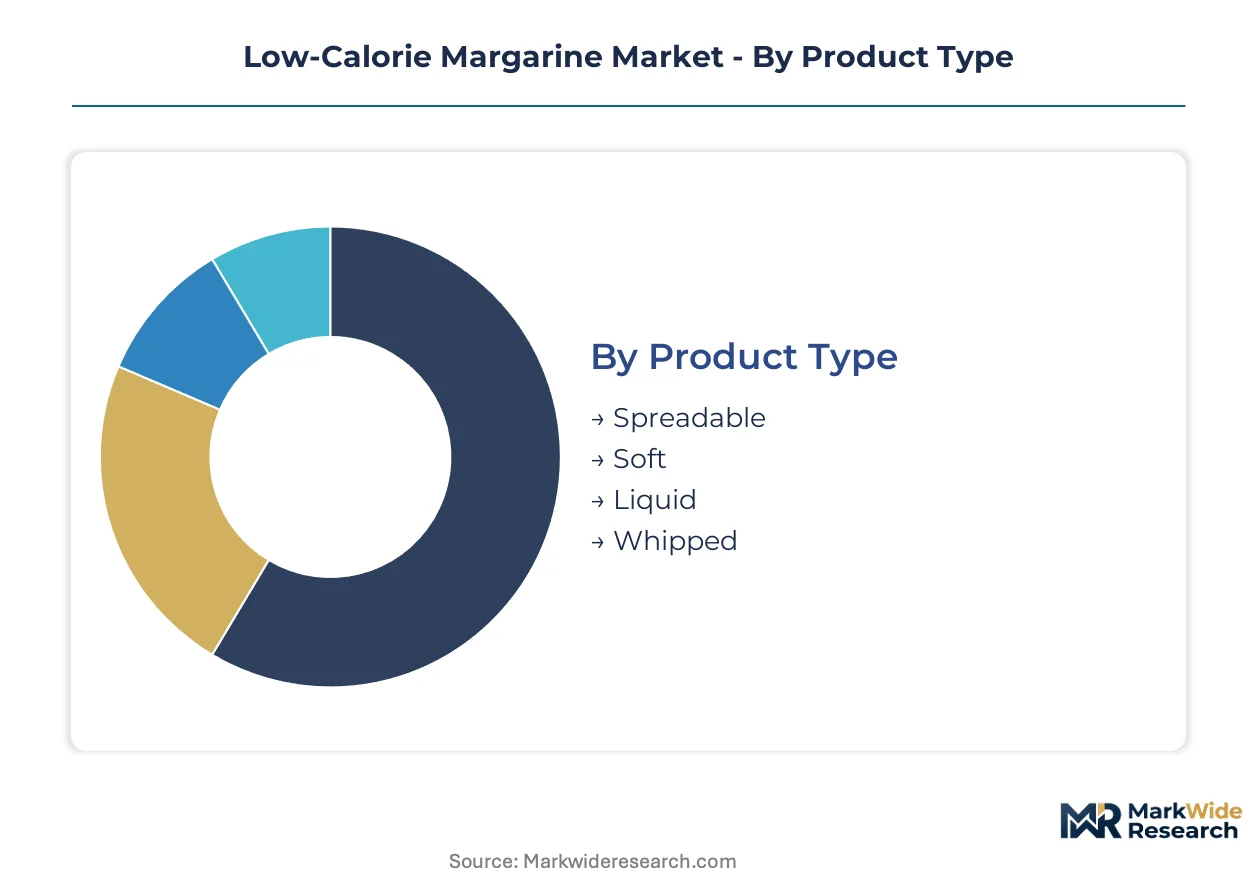
Segmentation in low-calorie margarine determines both procurement economics and shelf positioning. Product texture dictates emulsifier chemistry requirements, while packaging format governs cold-chain investment and margin capture.
Product Type:
Supply concentration among European emulsifier specialists favors formats requiring standardized water-phase structuring.
- Spreadable:Water-in-fat emulsions with 40-60% lipid content achieve spoonable consistency through distilled monoglyceride stabilization. German retail discounters and French hypermarkets drive volume procurement for this format, though texture degradation above 60% water incorporation limits further caloric reduction.
- Soft:Higher water-phase margarines (50-55% fat) rely on lecithin-blend emulsifiers for spreadability at refrigerated temperatures. Artisan bakeries in Northern Europe specify soft variants for laminated dough applications where plasticity under mechanical stress matters.
- Liquid:Pourable emulsions with reduced crystalline fat content suit commercial foodservice dispensing systems.
- Whipped:Aerated structures incorporate nitrogen to increase volume per unit fat, appealing to calorie-conscious household segments.
Spreadable formats absorb the bulk of installed capacity; whipped variants are expanding most quickly as aeration technology improves.
Formulation:
Cost tier differentiation separates premium-positioned claims from commodity private-label supply.
- Vegan:Fully plant-based spreads exclude all animal-derived ingredients, requiring dedicated processing lines to prevent cross-contamination. Clean-label positioning in Dutch and Belgian supermarkets supports price premiums, though EFSA health claim substantiation demands 18-24 month validation timelines.
- Dairy-based:Blends incorporating butterfat or buttermilk deliver familiar flavor profiles for consumers transitioning from conventional butter. German dairy cooperatives leverage existing chilled distribution infrastructure to compete in this segment.
- Plant-based:High-oleic sunflower and enzymatically interesterified rapeseed formulations achieve trans-fat elimination without hydrogenation.
- Blended:Hybrid formulations combine dairy and vegetable fats to balance taste, functionality, and cost.
Plant-based formulations dominate new product development pipelines; vegan certification commands steepest price premiums.
Packaging Type:
Margin structure varies sharply with cold-chain dependency and unit economics.
- Tub:Refrigerated containers with resealable lids support brand differentiation through label design and sustainability claims. EU F-Gas Regulation compliance costs for insulated packaging favor larger format tubs that amortize fixed investment across higher volumes.
- Stick:Wrapped rectangular formats suit baking applications requiring precise measurement and extended ambient stability. Lower unit economics constrain brand marketing investment, relegating sticks to commodity positioning.
- Bottle:Squeeze dispensers target foodservice and institutional channels with high-throughput usage patterns.
- Single Serve:Portion-controlled packets serve hospitality and airline catering contracts with strict inventory control requirements.
Tub packaging captures highest margin pools; single-serve formats are gaining share fastest in contract foodservice.
Distribution Channel:
Customer type determines formulation collaboration depth and pricing architecture.
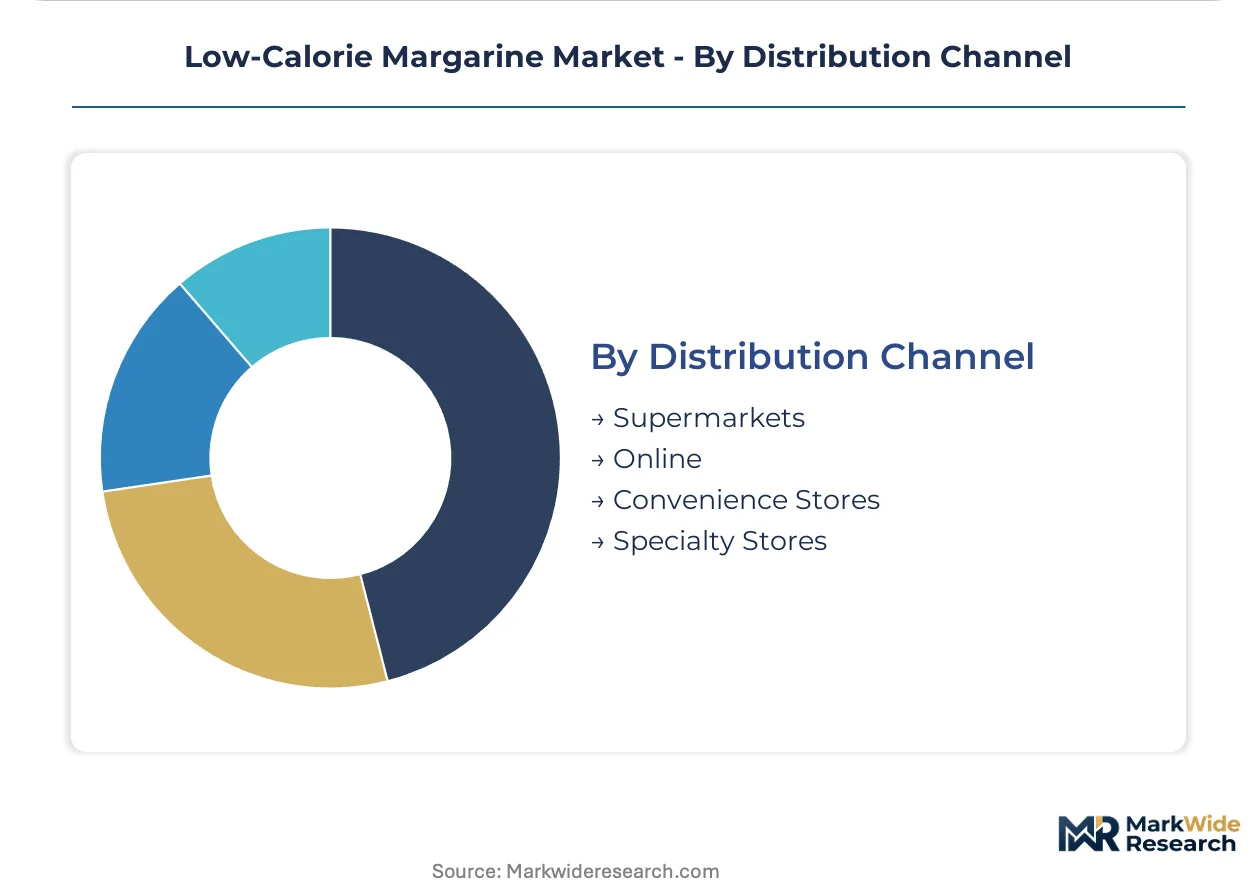
- Supermarkets:Multi-banner retail chains in Germany and France negotiate annual listings with dedicated shelf-space guarantees. Private-label penetration here forces branded players to defend position through innovation cadence and promotional frequency.
- Online:Direct-to-consumer and third-party marketplace sales enable subscription models and bulk purchasing. Cold-chain logistics partnerships with specialized last-mile providers remain the critical capability gap.
- Convenience Stores:Limited assortment formats favor impulse-sized tubs and recognized brand names with minimal explanatory packaging.
- Specialty Stores:Health food and organic retailers stock premium-positioned variants with certified sustainable palm or regenerative agriculture claims.
Supermarkets anchor volume throughput; online channels are climbing the fastest as refrigerated fulfillment infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retail discounters and artisan bakeries in Germany generate disproportionate pull for reduced-fat spreads, concentrating formulation innovation and procurement volume in Western European markets.
Germany
Artisan bakeries in Berlin and Munich specify reduced-fat spreads for laminated dough applications, while retail discounters Aldi and Lidl drive private-label volume. The EU F-Gas Regulation pressures cold-chain packaging redesigns for temperature-sensitive tub formats. Industrial margarine production clusters in North Rhine-Westphalia leverage proximity to Dutch emulsifier suppliers.
France
Industrial bakers in the Île-de-France region prioritize single-source accountability for lipid functionality, consolidating supplier relationships around integrated oil-plus-emulsifier contracts. EFSA health claim assessments shape permissible marketing language for cholesterol-reduction positioning. Lyon-based formulation facilities pilot enzymatically interesterified rapeseed processing for clean-label croissant bases.
Netherlands
Dutch supermarkets support premium pricing for vegan-certified spreads with dedicated processing lines to prevent cross-contamination. The EU Green Deal farm-to-fork sustainability metrics favor plant-based spreads over dairy butter in public procurement. Rotterdam and Amsterdam serve as emulsifier production hubs, concentrating supply relationships for European margarine manufacturers.
United States
FDA nutrition labeling requirements compel reformulation investments for trans-fat elimination, accelerating demand for structured emulsifier systems. Chicago and Minneapolis house major margarine production facilities serving North American retail and foodservice channels. Midwest soybean crushing infrastructure feeds cost-advantaged feedstock flows to formulation plants.
Brazil
BRF SA anchors domestic production through integrated oilseed processing and distribution networks. ANVISA regulatory frameworks govern food additive approvals for emulsifier systems in reduced-fat spreads. São Paulo-based industrial bakeries drive professional ingredient procurement for laminated dough applications.
Low-Calorie Margarine Market Competitive Landscape
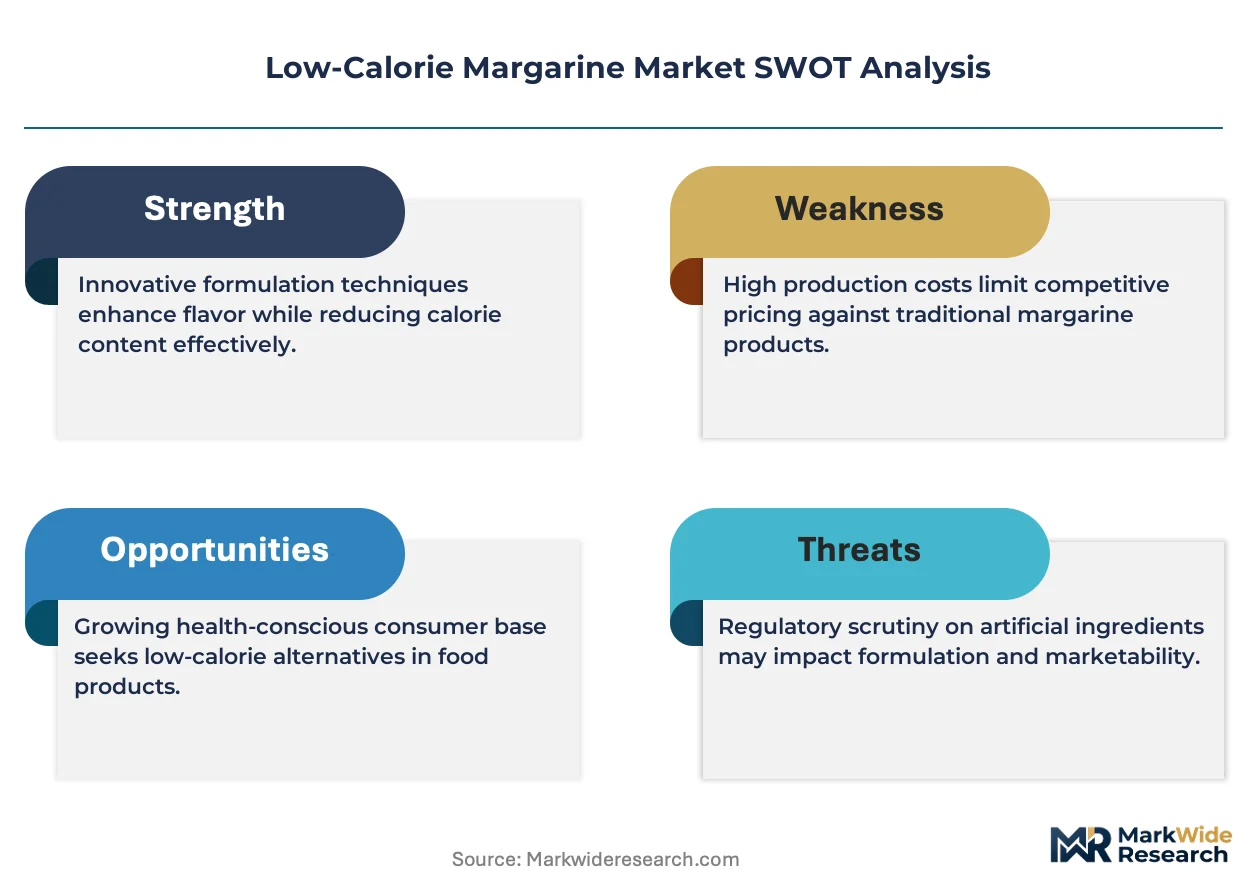
Reformulation partnerships dominate the current landscape as manufacturers rebuild emulsifier systems and oil sourcing strategies simultaneously. The vendor base organizes around three tiers: integrated agribusiness conglomerates with captive oilseed crushing, specialized margarine producers with bakery channel relationships, and private-label specialists serving retail discounters. Strategic archetypes include upstream-integrated feedstock controllers, formulation-technology licensors, and regional bakery-service distributors. Competitive moves center on enzymatic interesterification licensing agreements and direct-to-bakery distribution bypassing wholesale intermediaries.
Among integrated agribusiness players, Bunge Limited and Cargill, Incorporated exemplify the upstream-integrated archetype through oilseed crushing infrastructure that secures cost-advantaged feedstock flows. Unilever Plc occupies a position representing the branded-consumer-goods tier with dedicated sunflower and rapeseed processing partnerships anchoring European production. These three companies illustrate how supply-chain control and formulation collaboration access separate market positions in a sector where procurement economics and technical capability jointly determine competitive standing.
| Leading Market Players |
|---|
| Conagra Brands, Inc. |
| Bunge Limited |
| Unilever Plc |
| Upfield BV |
| Wilmar International Ltd. |
| Vandemoortele |
| BRF SA |
| NMGK Group |
| Cargill, Incorporated |
| Others |
Value Network & Pricing Analysis
Enzymatic interesterification technology is compressing formulation cost differentials between premium and commodity tiers while concentrating procurement leverage among integrated oilseed crushers with captive processing assets. This production-method transition simultaneously enables trans-fat elimination compliance and reshapes margin pools across tub and stick formats as manufacturers absorb cold-chain packaging investments driven by EU F-Gas Regulation phase-down schedules.
Pricing Analysis
Service bundling separates formulation collaboration from commodity supply, with integrated oil-plus-emulsifier contracts commanding premiums over component sourcing. Three-tier pricing structure across premium, standard, and economy levels tracks certification status and bakery channel integration depth. Cost compression in private-label tiers is intensifying because retail discounters consolidate SKU counts to amortize refrigerated packaging redesign costs. Artisan bakeries exhibit lowest price sensitivity due to functionality requirements for laminated dough applications.
Supply Chain Analysis
Direct-to-bakery distribution partnerships bypass traditional wholesale intermediaries, capturing margin and formulation collaboration access for integrated producers. Feedstock supply concentrates in the Netherlands, Germany, and Belgium, where emulsifier production clusters draw from Black Sea sunflower and domestic rapeseed origins. Raw material dependencies rest on high-oleic sunflower oil, enzymatically processed rapeseed, and distilled monoglyceride stabilizers. Single-source vulnerability in European emulsifier capacity creates exposure to F-Gas Regulation compliance cost shocks. Distribution runs through refrigerated logistics networks serving retail discounters and industrial bakeries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The low-calorie margarine market functions as a cost-of-compliance arena where FDA and WHO trans-fat elimination frameworks erect regulatory moats favoring incumbents with reformulation capital and integrated supply chains.
For Market Incumbents: Hedge margin erosion from input cost volatility through multi-origin oil procurement contracts spanning South American soybean and European rapeseed sources. Deepen bakery channel lock-in via direct-to-bakery refrigerated logistics partnerships that bypass wholesale intermediaries and secure formulation collaboration access. Prioritize enzymatic interesterification licensing agreements to monetize technical capabilities before process patents expire. For New Entrants and Emerging Players: E-commerce subscription models for premium vegan-certified spreads offer lower barrier entry than contested supermarket shelf space. Target Poland and Czech Republic retail discounters where private-label reduced-fat spreads remain underpenetrated and first-mover positioning is achievable. Pursue single-serve format contracts with airline and hospitality catering channels where portion-control specifications limit incumbent adaptation speed. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated agribusiness conglomerates seeking bakery channel formulation capabilities. Long-term viability favors targets with enzymatic processing assets and established direct-to-bakery distribution infrastructure. Monitor EFSA health claim certification timelines as inflection indicators for premium pricing power realization.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Interesterification Licensing | Technology transfer agreements enable trans-fat elimination without hydrogenation, unlocking clean-label positioning for bakery channel contracts. |
| Direct-to-Bakery Distribution Buildout | Refrigerated logistics partnerships with Berlin and Munich artisan bakeries capture margin and formulation collaboration access. |
| Multi-Origin Oil Procurement | Diversified feedstock sourcing from Brazilian soybean and Black Sea sunflower mitigates price volatility exposure. |
| Vegan Certification Investment | Dedicated processing lines prevent cross-contamination, supporting premium positioning in Dutch and Belgian supermarket channels. |
| Cold-Chain Packaging Redesign | EU F-Gas Regulation compliance for tub formats favors larger SKUs that amortize insulation material investments. |
Research Methodology
Document review covered trade customs data, EFSA health claim registers, and SEC filings from integrated agribusiness conglomerates, complemented by interviews with plant managers at European margarine production facilities, procurement leads at German retail discounters, bakery channel sales heads, and R&D directors specializing in emulsifier chemistry. Secondary validation drew from WHO trans-fat policy frameworks, FDA nutrition labeling guidance, and EU F-Gas Regulation implementation schedules. Bottom-up volume modeling triangulated against top-down market sizing from oilseed crushing capacity and bakery ingredient procurement patterns.
Cross-referencing historical price series for sunflower and rapeseed oils against expert panel input on reformulation cost trajectories anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product texture tier, formulation certification status, packaging cold-chain dependency, and distribution channel type. CAGRs were derived from elasticity-adjusted volume projections and value-per-unit assumptions reflecting premium tier expansion. Industry-specific inputs incorporated enzymatic processing adoption curves and EFSA health claim approval timelines.
The model holds under stable regulatory enforcement of trans-fat limits and sustained bakery channel demand; deviation in Black Sea supply disruptions or F-Gas Regulation compliance cost spikes would shift volume and value trajectories. Forecasts reflect documented assumptions regarding oilseed yield patterns and emulsifier capacity expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Coffee Creamer Market
Processed Foods
Accompanying Marinated Product Market
Processed Foods
Casual Marinated Products Market
Processed Foods
Europe Soup Market
Processed Foods
United States Fresh Noodles Market
Processed Foods
Processed Superfruits Market
Processed Foods
Ready to Cook Market
Processed Foods
Asia-Pacific Soup Market
Processed Foods
Instant Curry Market
Processed Foods
Sugar-Free Ice Cream Market
Processed Foods
Shelf-Stable Soup Market
Processed Foods
Processed Egg Market
Processed Foods
China Freeze-Dried Food Market
Processed Foods
Mashed Potatoes Market
Processed Foods
South America Soup Market
Processed Foods
Asia-Pacific Food Spread Market